
 Dermatophytic Onychomycosis Treatment Market | 2026-2036
Dermatophytic Onychomycosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Dermatophytic Onychomycosis Treatment Market Intelligence
EU MDR requirements for dermatological device-drug combinations is hardening compliance thresholds across European supply chains. Pfizer Inc. leverages its oral antifungal legacy portfolio to sustain formulary positions in hospital networks. Galderma anchors its competitive stance through topical specialization in nail lacquer formulations. Kaken Pharmaceuticals Co., Ltd. dominates transungual delivery innovation with proprietary penetration technologies developed for East Asian markets.
Dermatophytic onychomycosis treatment encompasses pharmaceutical and device interventions targeting Trichophyton rubrum and other dermatophyte species infecting the nail unit, with topical formulations typically requiring 40-54% urea pretreatment or novel permeation enhancers to achieve therapeutic concentrations in the nail plate. The primary commercial purpose centers on clearing infection, restoring nail anatomy, and preventing recurrence in a condition affecting roughly one in ten adults globally. Oral antifungals still occupy the largest value share due to superior cure rates in distal lateral subungual cases, though topical antifungals are gaining fastest among patients with comorbidities contraindicating systemic therapy. Combination therapy represents the concentrated margin pool as physicians seek to reduce relapse rates that challenge monotherapy economics.
FDA bioequivalence standards for generic oral terbinafine shape substitution patterns in US retail pharmacy, while EMA's MDR classification of laser-device combination kits creates divergent approval costs across Atlantic markets. Japan's PMDA maintains distinct clinical endpoint requirements for transungual products that filter entrants into its reimbursed formulary. Stakeholders must monitor how decentralized diagnostic tools—portable dermatoscopes and PCR-based point-of-care tests—reshape referral pathways between primary care and dermatology clinics.
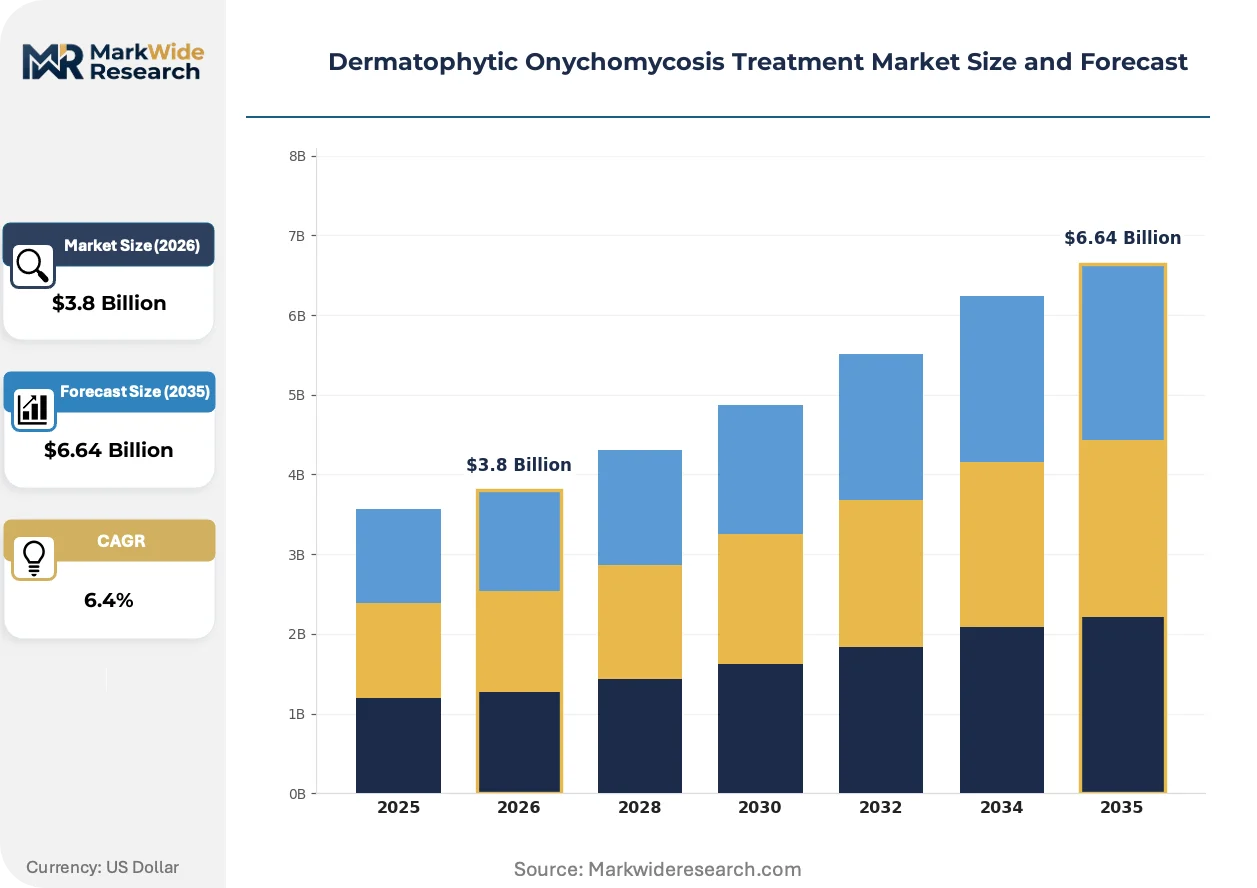
Market Dynamics
FDA's streamlined bioequivalence pathways for topical antifungals are compressing commercialization timelines, while dermatology clinics pivot toward combination protocols that reduce relapse rates and defend margin pools against generic oral substitution.
Growth Catalysts
- Medicare reimbursement expansion:Broader coverage for onychomycosis diagnostics in the United States is pulling patient volume into reimbursed care pathways. Primary care networks now route cases to dermatology clinics with pre-authorized testing.
- Transungual penetration technologies:Novel permeation enhancers and urea-based pretreatment protocols are achieving therapeutic nail-plate concentrations previously exclusive to oral agents. Device-drug combinations accelerate this shift.
- Point-of-care PCR diagnostics:Portable molecular testing at dermatology clinics compresses time-to-treatment initiation. Speciation accuracy improves targeting of Trichophyton rubrum versus non-dermatophyte molds.
Market Restraints
- Oral antifungal safety profiling:Systemic therapy carries hepatotoxicity monitoring requirements that constrain prescribing in patients with polypharmacy. Liver function testing adds cost and compliance friction.
- Generic terbinafine substitution:FDA bioequivalence standards enable automatic pharmacy-level switching that erodes branded oral margins. Retail chains prioritize lowest-acquisition-cost formulary placement.
- EU MDR compliance burden:Device-drug combination kits face hardened technical documentation and notified body review timelines. European supply chains absorb certification costs that filter smaller entrants.
Strategic Opportunities
- Pediatric and geriatric topical segments:Patients with hepatic comorbidities or contraindications to systemic therapy represent underserved demand. Formulation tolerability drives preference for nail lacquer alternatives.
- Laser-device combination protocols:Photodynamic and thermal adjuncts paired with topical agents create premium reimbursement tiers. Aesthetic dermatology channels cross-sell these services.
- East Asian transungual innovation:Japan's PMDA maintains distinct clinical endpoints that reward proprietary penetration technologies. Kaken Pharmaceuticals' regional formulary dominance demonstrates pathway viability.
Industry Challenges
- Nail-plate pharmacokinetic modeling:Standardized ex vivo testing methods remain elusive across regulatory jurisdictions. Sponsors face duplicated validation work for FDA, EMA, and PMDA submissions.
- Combination therapy evidence generation:Clinical trials must demonstrate superiority over monotherapy for formulary access. Sample sizes and durations multiply development costs versus single-agent programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermatophytic Onychomycosis Treatment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Antifungals, Oral Antifungals, Combination Therapy, Natural Remedies Route of Administration: Oral, Topical, Intralesional, Transungual, Nail Lacquer Indication: Proximal Subungual, Distal Lateral Subungual, White Superficial, Total Dystrophic, Mixed Infection End User: Dermatology Clinics, Specialty Pharmacies, Outpatient Care Centers, Cosmetic Centers |
| Companies Covered | Bausch Health Companies Inc., Pfizer Inc., Galderma, Novartis AG, GlaxoSmithKline plc, Janssen Pharmaceuticals, Inc., Cipla Inc., Kaken Pharmaceuticals Co., Ltd., Moberg Pharma AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermatophytic Onychomycosis Treatment Market Strategic Shifts & Innovations
Photodynamic and laser adjunct technologies are penetrating dermatology clinics as physicians seek to differentiate services and reduce reliance on oral antifungal prescribing. Three developments are compressing traditional treatment economics.
Photodynamic therapy systems paired with topical photosensitizers are integrating into combination protocols for recalcitrant distal lateral subungual cases. Dermatology clinics in Germany and South Korea deploy these as premium cash-pay services outside pharmaceutical reimbursement. The structural consequence is a parallel revenue stream that competes with pharmaceutical margins.
EMA's Medical Device Regulation reclassification of laser-device kits as Class IIa or higher is lengthening European approval timelines and concentrating supply among notified-body-approved manufacturers. Dermatology device distributors are consolidating vendor relationships to manage documentation burden. France and Italy show earliest adaptation to MDR-compliant procurement.
Direct-to-consumer diagnostic sampling is fragmenting traditional referral pathways between primary care and dermatology. Patients in the United States initiate therapy through telehealth platforms with photographic triage, bypassing in-person dermatoscope examination. Retail pharmacy chains capture prescription fulfillment from these virtual encounters, compressing clinic visit volume.
Dermatophytic Onychomycosis Treatment Market Segmentation
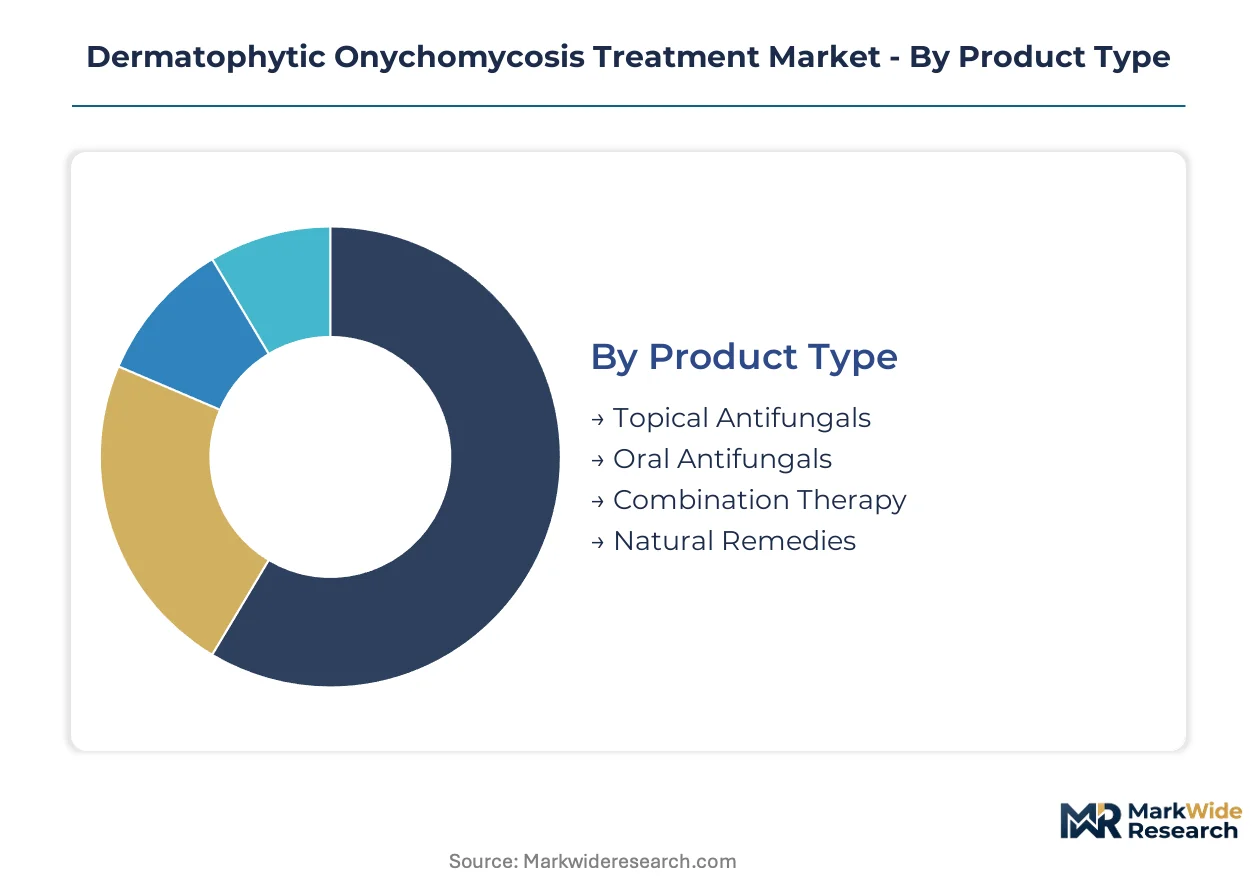
Dermatophytic onychomycosis treatment segments fragment across pharmacological mechanisms, delivery technologies, and care settings. Supply concentration varies sharply by category, with oral antifungals consolidating around generic manufacturers while topical innovation disperses across specialty formulation houses.
Product Type:
Supply concentration clusters around oral antifungal manufacturing capacity, where API sourcing from Indian and Chinese contract manufacturers dominates cost structures.
- Topical Antifungals:Formulations incorporating terbinafine hydrochloride, ciclopirox, or efinaconazole require permeation enhancers to breach the nail plate. Demand concentrates in Germany and South Korea where photodynamic combination protocols create premium positioning. Regulatory divergence between FDA and EMA bioequivalence standards fragments formulation strategies.
- Oral Antifungals:Systemic terbinafine and itraconazole tablets achieve superior mycological cure rates through nail bed vascularization. United States retail pharmacy chains drive volume through automatic generic substitution enabled by FDA bioequivalence pathways. Hepatotoxicity monitoring requirements constrain prescribing in polypharmacy patients.
- Combination Therapy:Sequential or concurrent oral-topical protocols target relapse reduction in recalcitrant cases. Dermatology clinics in France and Italy adopt these as first-line for severe presentations.
- Natural Remedies:Tea tree oil, oregano extract, and undecylenic acid formulations occupy direct-to-consumer channels with limited clinical validation. Wellness retailers in California and Melbourne capture this demand.
Oral antifungals absorb the bulk of installed capacity; combination therapy is expanding most quickly.
Route of Administration:
Cost tier differentiation separates hospital-administered intralesional injections from self-applied nail lacquer systems.
- Oral:First-pass hepatic metabolism governs dosing schedules and drug-drug interaction profiles. United States Medicare reimbursement anchors volume in managed care networks.
- Topical:Creams and solutions require 40-54% urea pretreatment to achieve therapeutic nail-plate concentrations. European dermatology clinics favor these for pediatric and geriatric populations.
- Intralesional:Direct injection into the nail matrix or bed delivers high local concentrations for total dystrophic cases. Japanese and South Korean specialists pioneer these techniques.
- Transungual:Proprietary penetration technologies from Kaken Pharmaceuticals enable drug carriage across the nail plate without chemical pretreatment. PMDA clinical endpoint requirements filter entrants to Japan's reimbursed formulary.
- Nail Lacquer:Film-forming formulations provide sustained release with cosmetic acceptability. Galderma's amorolfine lacquer dominates European pharmacy dispensing.
Oral administration retains the largest prescription volume; transungual delivery is gaining share fastest.
Indication:
Application severity determines whether monotherapy suffices or combination protocols become economically justified.
- Distal Lateral Subungual:The most common presentation originating from the hyponychium and spreading proximally. Oral terbinafine remains standard of care in United States hospital networks.
- Proximal Subungual:Infection beginning at the proximal nail fold indicates immunocompromise or HIV association. Aggressive systemic therapy dominates treatment selection.
- White Superficial:Surface invasion by Trichophyton mentagrophytes responds to topical monotherapy alone. French and Italian pharmacies dispense ciclopirox lacquer as first-line.
- Total Dystrophic:Complete nail destruction requires prolonged combination therapy or surgical avulsion. German dermatology clinics deploy laser adjuncts for these recalcitrant cases.
- Mixed Infection:Concurrent dermatophyte and non-dermatophyte mold involvement complicates speciation-directed therapy. PCR diagnostics at South Korean clinics improve targeting accuracy.
Distal lateral subungual cases absorb the bulk of treatment volume; total dystrophic presentations command the highest per-patient expenditure.
End User:
Customer type segmentation reflects referral pathway fragmentation between traditional dermatology and emerging direct-to-consumer channels.
- Dermatology Clinics:Specialist settings deploy combination protocols and device adjuncts with premium reimbursement. EMA MDR compliance costs are concentrating European supply among notified-body-approved vendors.
- Specialty Pharmacies:Compounding capabilities enable customized topical formulations for patients with contraindications to systemic therapy. United States independent pharmacies capture this niche.
- Outpatient Care Centers:Primary care networks route cases with pre-authorized PCR diagnostics to dermatology referrals. Medicare reimbursement expansion is pulling volume into reimbursed pathways.
- Cosmetic Centers:Aesthetic dermatology channels cross-sell laser-device combinations as cash-pay services. South Korean and German clinics lead photodynamic protocol adoption.
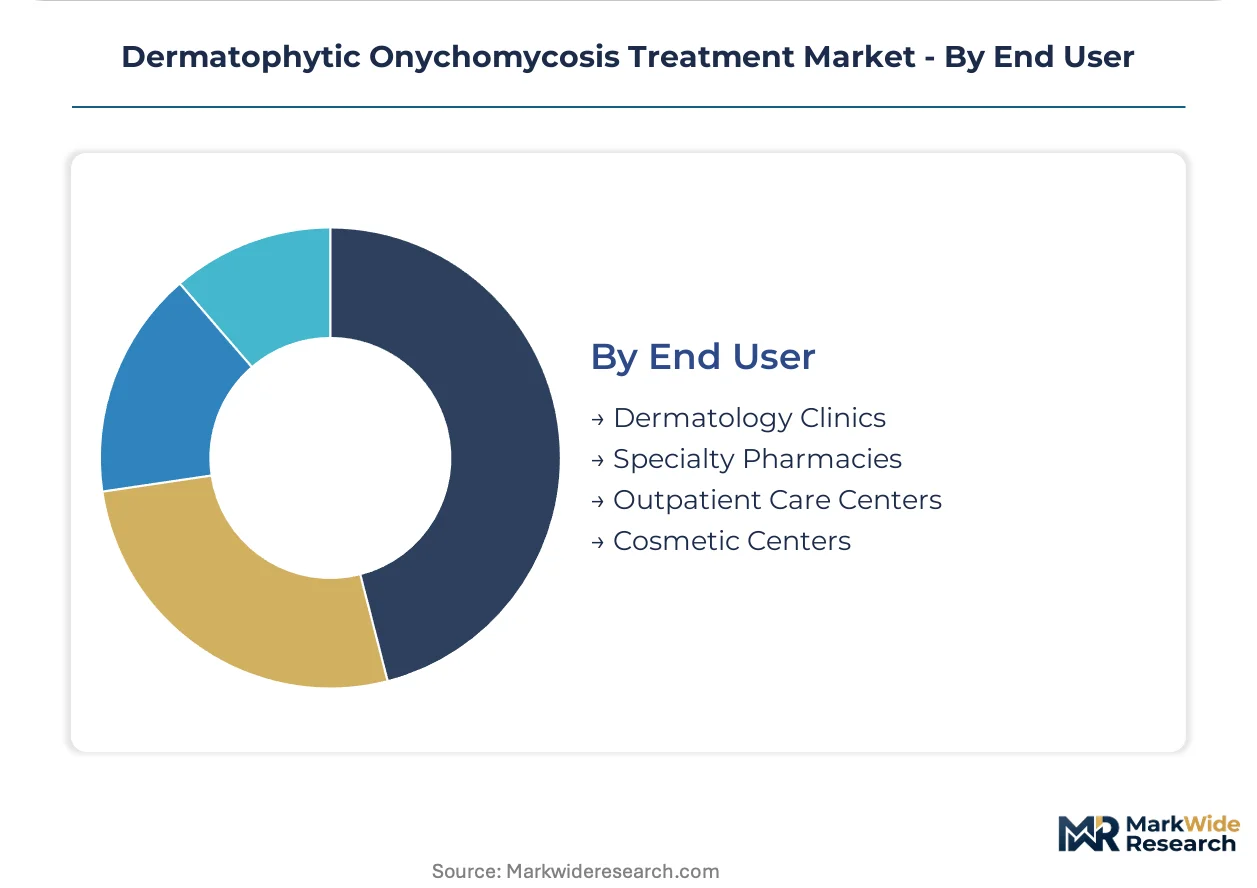
Dermatology clinics absorb the bulk of high-margin combination therapy; cosmetic centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Philadelphia anchors North American pharmaceutical R&D concentration for dermatophytic onychomycosis therapies, with the Delaware Valley corridor hosting FDA-aligned clinical trial infrastructure. Regulatory harmonization pressures are reshaping how sponsors navigate divergent approval pathways across major markets.
United States
Medicare reimbursement expansion for onychomycosis diagnostics is routing patient volume through pre-authorized testing pathways. FDA's streamlined bioequivalence standards for topical antifungals compress commercialization timelines versus historical benchmarks. Boston and San Francisco Bay Area dermatology networks pioneer combination protocol adoption.
Germany
EMA MDR compliance costs for device-drug combination kits are concentrating European supply among notified-body-approved manufacturers. Photodynamic therapy protocols in Munich and Hamburg clinics establish premium cash-pay service tiers. German dermatology associations advocate for standardized nail-plate pharmacokinetic testing methods.
Japan
PMDA maintains distinct clinical endpoint requirements for transungual penetration technologies that filter entrants to reimbursed formularies. Tokyo and Osaka dermatology clinics drive adoption of proprietary nail lacquer formulations. Kaken Pharmaceuticals' regional dominance demonstrates pathway viability for transungual innovation.
South Korea
Point-of-care PCR diagnostics at Seoul and Busan clinics compress time-to-treatment initiation with improved Trichophyton rubrum speciation accuracy. MFDS regulatory frameworks for laser-device combinations create approval efficiency versus European MDR timelines. Domestic manufacturers specialize in photodynamic adjunct systems.
France
ANSM oversight of dermatological device-drug combinations aligns with broader EMA MDR implementation timelines. Paris and Lyon dermatology clinics adopt combination therapies as first-line protocols for severe presentations. French pharmacy dispensing of ciclopirox lacquer dominates white superficial onychomycosis cases.
Dermatophytic Onychomycosis Treatment Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulation sophistication and proprietary delivery technology. Oral antifungal manufacturing consolidates around generic API sourcing from Indian and Chinese contract manufacturers, while topical innovation disperses across specialty formulation houses. Three archetypes dominate: legacy pharmaceutical conglomerates with oral antifungal portfolios, dermatology-focused specialists in topical delivery, and device-drug combination developers. Competitive moves center on M&A for transungual penetration technologies and strategic partnerships between laser device manufacturers and topical formulation houses.
Within the legacy pharmaceutical tier, Pfizer Inc. and Novartis AG occupy positions sustained by hospital network formulary relationships and oral antifungal manufacturing scale. Galderma exemplifies the dermatology-specialist archetype through topical formulation concentration, while Kaken Pharmaceuticals Co., Ltd. anchors the transungual innovation segment with proprietary penetration technologies developed for East Asian regulatory pathways.
| Leading Market Players |
|---|
| Bausch Health Companies Inc. |
| Pfizer Inc. |
| Galderma |
| Novartis AG |
| GlaxoSmithKline plc |
| Janssen Pharmaceuticals, Inc. |
| Cipla Inc. |
| Kaken Pharmaceuticals Co., Ltd. |
| Moberg Pharma AB |
| Others |
Cost & Logistics Intelligence
Backward integration into API manufacturing anchors pricing power for oral antifungal producers while fragmenting margin capture across topical formulation specialists. Indian and Chinese contract manufacturers supply terbinafine and itraconazole active pharmaceutical ingredients to branded and generic tablet producers, concentrating cost leverage upstream. Dermatology-focused houses in Switzerland and Japan retain premium positioning through proprietary transungual penetration technologies that command reimbursement premiums.
Pricing Analysis
Outcome-based pricing anchors reimbursement for combination therapy protocols that demonstrate superior mycological cure rates over monotherapy. Three-tier pricing structure across premium, standard, and economy levels separates device-drug combination kits from generic oral tablets and direct-to-consumer natural remedies. Price differentiation hinges on FDA bioequivalence certification tier and hepatotoxicity monitoring bundling. Cost compression in generic oral terbinafine is intensifying because retail pharmacy chains prioritize lowest-acquisition-cost formulary placement. Hospital networks show lowest price sensitivity; cash-pay cosmetic channels exhibit highest.
Supply Chain Analysis
Terbinafine hydrochloride API supply rests on Indian specialty chemical producers in Hyderabad and Mumbai, with secondary sourcing from Chinese manufacturers in Zhejiang and Jiangsu provinces. Nail lacquer formulations draw from European excipient suppliers for film-forming polymers and East Asian manufacturers for permeation enhancers. Single-source vulnerability concentrates in urea pretreatment chemical supply for topical protocols. Distribution runs through hospital procurement networks for oral antifungals and specialty pharmacy channels for compounded topical alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA MDR compliance costs for device-drug combination kits erect a barrier-to-entry moat that rewards notified-body-approved manufacturers with durable formulary positioning. This cost-of-compliance story concentrates European supply among capitalized players capable of absorbing technical documentation and clinical validation burdens.
For Market Incumbents: Anchor formulary positions through backward integration into transungual penetration technology and captive supply of permeation enhancers. Generic terbinafine substitution threatens branded oral margins; defend through hospital network GPO contracts and hepatotoxicity monitoring service bundling. CE marking investment under EMA MDR filters smaller device competitors.
For New Entrants and Emerging Players: Begin with pediatric and geriatric topical segments where systemic therapy contraindications create underserved demand pockets. White superficial onychomycosis presentations in French and Italian pharmacy channels offer lowest competitive density. Telehealth platform partnerships enable direct-to-consumer diagnostic sampling bypassing traditional dermatology referral pathways.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by dermatology-focused specialists seeking transungual delivery capabilities. Long-term viability favors proprietary penetration technology holders over commodity API manufacturers. Watch FDA bioequivalence pathway expansion for topical antifungals as inflection signal for generic topical entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Certification Pathway | Notified-body approval unlocks premium reimbursement tiers in German and French dermatology clinics. |
| Transungual Technology Licensing | Proprietary penetration patents from Japanese specialists enable PMDA-aligned market entry. |
| Point-of-Care Diagnostic Partnership | PCR platform integration with dermatology networks compresses time-to-treatment initiation. |
| Combination Protocol Clinical Trial | Superiority evidence over monotherapy secures hospital formulary access and defensible pricing. |
| Generic API Manufacturing Scale-Up | Indian contract manufacturing capacity anchors cost position in oral antifungal supply. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with dermatology clinic directors, hospital formulary managers, regulatory affairs specialists at topical formulation houses, and GPO procurement officers combined with FDA 510(k) submissions, EMA MDR technical documentation, PMDA approval summaries, and ClinicalTrials.gov records. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulated value estimates.
Reconciliation of manufacturer-reported shipment data with pharmacy dispensing records and reimbursement claims databases validated volume assumptions across the projection horizon. Segmentation dimensions modeled include pharmacological mechanism, delivery technology, indication severity, and care setting. CAGRs derived from fitted growth curves applied to base-year estimates. Forecast inputs incorporated Medicare reimbursement expansion trajectories and EMA MDR implementation timelines.
Underlying measurement precision varies by segment; oral antifungal prescription data carry tighter precision than direct-to-consumer natural remedy estimates. Forecasts reflect assumptions about regulatory pathway efficiency and reimbursement policy continuity. Patent expiry schedules and generic entry timing present revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Global Dermatology Cro Market
Dermatology
Japan Scar Treatment Market
Dermatology
Global Hirsutism Market
Dermatology
Lentigo Maligna Melanoma Therapeutic Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Radiation Dermatitis Market
Dermatology
Androgenetic Alopecia Market
Dermatology
Psoriasis Treatment Market
Dermatology
Australia Skin Treatment Market
Dermatology
Global Dermatological OTC Drugs Market
Dermatology
Hyperpigmentation Disorder Treatment Market
Dermatology
Prescription Dermatology Therapeutics Market
Dermatology
Dermatology Drugs Market
Dermatology
Global Online Dermatology Consultation Market
Dermatology
US and Canada Skin Cancer Dermatology Market
Dermatology
Global Dermatology Lasers Market