
 Dystrophic Epidermolysis Bullosa Treatment Market | 2026-2036
Dystrophic Epidermolysis Bullosa Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Dystrophic Epidermolysis Bullosa Treatment Market Analysis
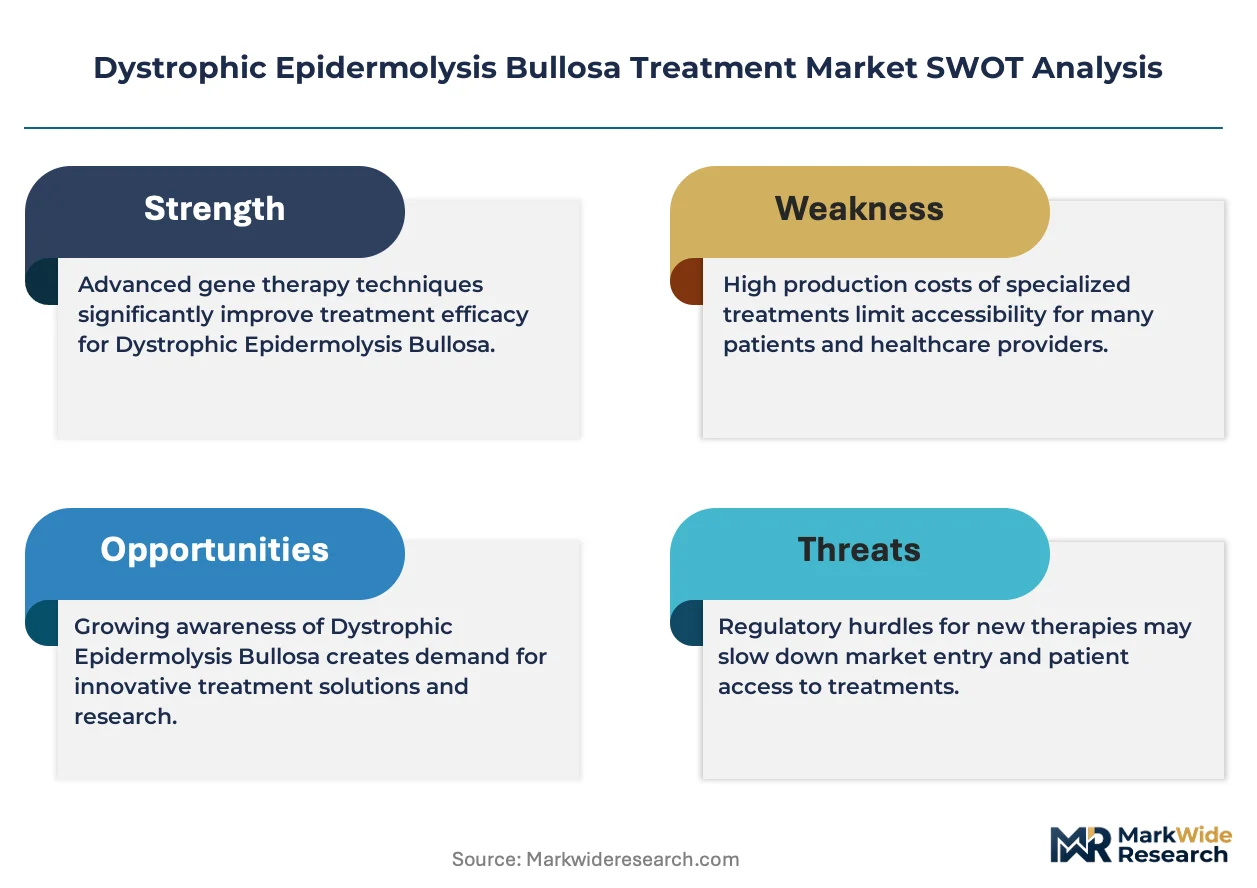
Modular therapy bundling is rebalancing procurement decisions across hospital and homecare channels. Krystal Biotech leverages its gene therapy platform to anchor premium positioning in the treatment landscape. Castle Creek Biosciences specializes in autologous cell-based approaches that differentiate its portfolio from systemic alternatives. Amryt Pharma dominates commercial distribution for approved topical and systemic options across European and North American markets.
Dystrophic epidermolysis bullosa treatment encompasses therapeutic interventions targeting type VII collagen defects arising from COL7A1 mutations, with gene therapy vectors and protein replacement biologics designed to restore dermal-epidermal adhesion in patients suffering recurrent blistering and chronic wounds. Gene therapy represents the fastest-expanding segment as investigational programs advance through late-stage clinical validation, while wound care products retain the largest current revenue pool due to persistent need for symptomatic management across all patient severities. Systemic therapies command differentiated pricing tied to orphan drug designation status and limited manufacturing scale.
FDA orphan drug incentives and EMA accelerated assessment pathways compress development timelines for novel modalities, while the EU AI Act and HIPAA privacy frameworks shape real-world evidence collection strategies that sponsors must navigate for label expansion. The central regulatory tension involves reconciling accelerated approval mechanisms with long-term safety monitoring requirements for gene and cell therapies. Stakeholders must monitor payer negotiation precedents for one-time curative interventions versus chronic management paradigms.
Market Dynamics
Gene therapy vectors for COL7A1 mutation correction are compressing development timelines and forcing incumbents to reposition chronic wound care portfolios against one-time curative interventions.
Growth Catalysts
- Orphan drug incentives:FDA's seven-year market exclusivity and tax credits accelerate investigational program advancement. EMA's PRIME designation provides enhanced scientific advice for priority medicines.
- Specialized wound care centers:Academic medical centers in the United States, Germany, and Japan cluster multidisciplinary expertise. These hubs concentrate patient recruitment and real-world evidence generation.
- Modular therapy bundling:Hospital procurement teams negotiate integrated contracts spanning biologics, dressings, and nursing protocols. This procurement pattern favors vendors with full-spectrum portfolios.
Market Restraints
- Viral vector manufacturing scarcity:AAV production capacity constraints limit gene therapy supply scaling. Contract manufacturers command premium pricing for GMP-grade material.
- Reimbursement uncertainty:Payer committees struggle to value one-time curative interventions against lifetime chronic management costs. Germany's G-BA assessment timelines create launch delays.
- Patient population fragmentation:Ultra-rare disease status complicates trial enrollment and commercial forecasting. Geographic dispersion across tertiary care centers fragments addressable markets.
Strategic Opportunities
- Homecare channel expansion:Wound care protocols migrate from hospital outpatient to home nursing services. Durable medical equipment distributors capture recurring revenue streams.
- Real-world evidence platforms:HIPAA-compliant patient registries enable post-market safety monitoring for gene therapies. Sponsors leverage these data for label expansion negotiations.
- Emerging market access:Brazil's ANVISA orphan drug pathway and Saudi Arabia's SFDA priority review create early-mover advantages. Local partnership requirements favor licensing structures over direct investment.
Industry Challenges
- Gene therapy manufacturing expertise:Viral vector production, fill-finish operations, and cold chain logistics require specialized talent. Competition with oncology programs strains available workforce.
- Long-term follow-up infrastructure:FDA mandates fifteen-year post-treatment monitoring for integrating vectors. Patient retention and data integrity across decentralized sites demand substantial operational investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dystrophic Epidermolysis Bullosa Treatment Market |
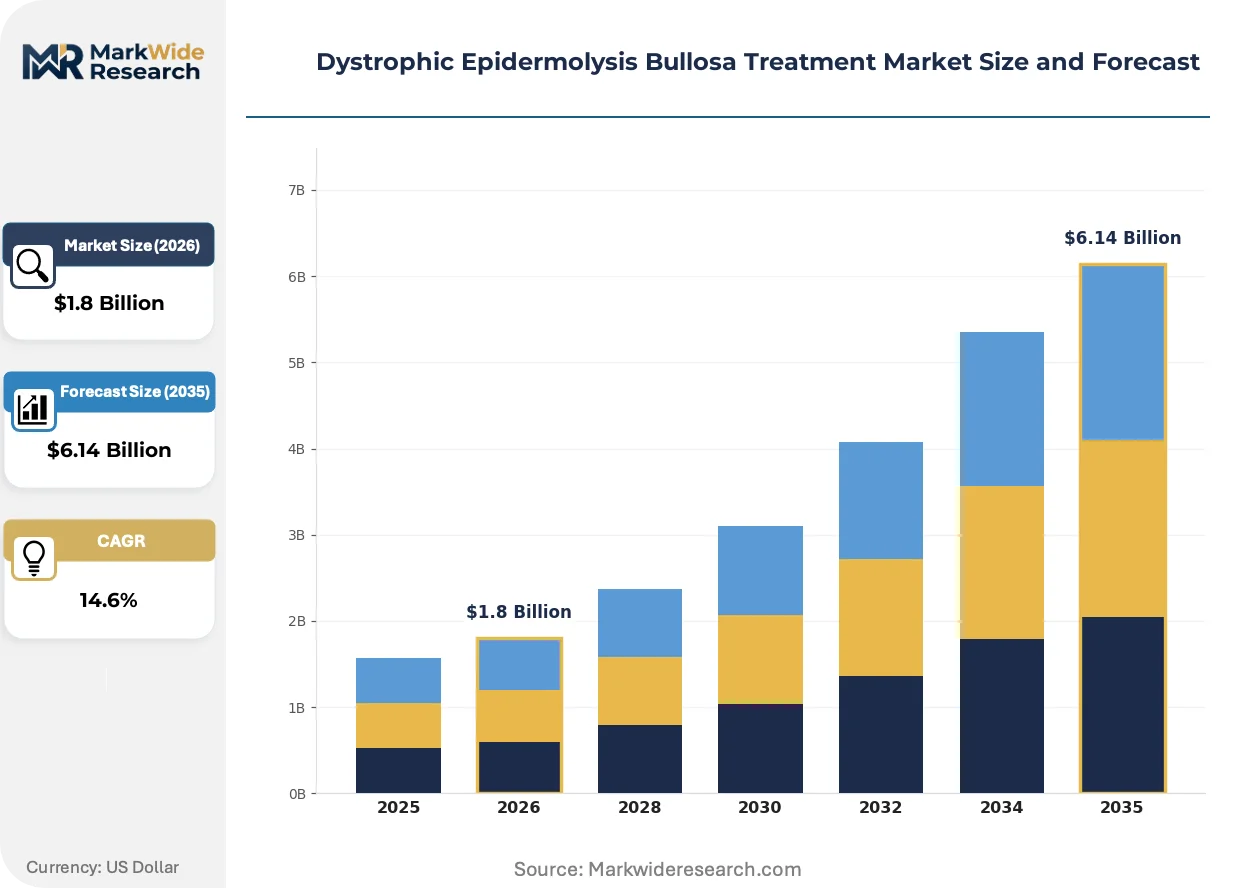
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Systemic Therapies, Wound Care Products, Gene Therapy Delivery Mode: Intravenous, Subcutaneous, Oral, Transdermal End User: Hospitals, Specialty Clinics, Homecare Settings, Research Institutions Therapy Area: Dermatology, Genetics, Pain Management, Surgical Interventions |
| Companies Covered | Amryt Pharma, Phoenix Tissue Repair, Krystal Biotech, RegeneRx, InMed Pharmaceuticals, Castle Creek Biosciences, Wings Therapeutics, Holostem Terapie Avanzate, Abeona Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dystrophic Epidermolysis Bullosa Treatment Market Emerging Trajectories
Vector engineering advances and regulatory science evolution are compressing the gap between preclinical proof-of-concept and pivotal trial initiation. These forces reshape competitive positioning across gene therapy, cell therapy, and symptomatic management segments.
Redosable non-viral gene delivery platforms are decentralizing treatment access by eliminating the cold chain and specialized infusion center requirements that constrain AAV-based approaches. Community dermatology practices in the United States and Germany are piloting these modalities for moderate-severity patients. The structural consequence is compressing the addressable market for chronic wound care products among patients eligible for curative intervention.
EMA's accelerated assessment pathway and FDA's regenerative medicine advanced therapy designation are compressing review timelines for dystrophic epidermolysis bullosa programs. These frameworks require sponsors to commit to confirmatory trial designs at submission rather than post-approval. Gene therapy developers are responding by embedding natural history studies into phase II protocols to satisfy evidentiary requirements.
Patient advocacy organizations are consolidating purchasing influence through dedicated pharmacy benefit structures. The Dystrophic Epidermolysis Bullosa Research Association of America negotiates directly with manufacturers for access programs and compassionate use protocols. This concentration of buyer power is most visible in the United States, where foundation-managed registries control referral flows to specialized treatment centers.
Dystrophic Epidermolysis Bullosa Treatment Market Segmentation
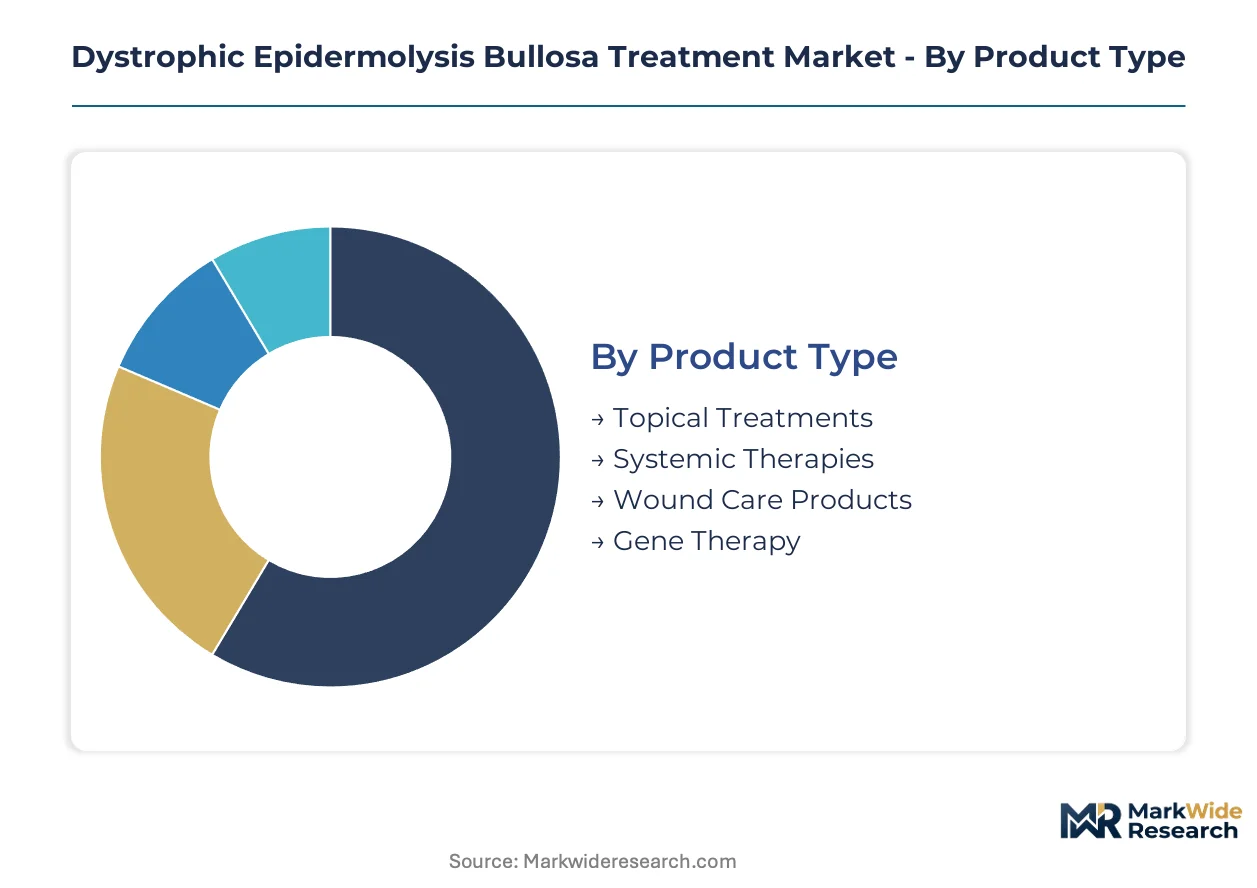
Therapeutic modality selection in dystrophic epidermolysis bullosa hinges on mutation severity, wound burden, and curative intent. Segmentation reveals how gene therapy vectors are compressing the addressable market for chronic symptomatic management while expanding total treatable population through earlier intervention.
Product Type:
Technology platform sophistication determines reimbursement tier and manufacturing complexity across the therapeutic spectrum.
- Gene Therapy:AAV and non-viral vectors deliver functional COL7A1 transgenes to restore type VII collagen production at the dermal-epidermal junction. Demand concentrates in the United States and Germany where specialized infusion centers and accelerated regulatory pathways cluster. Manufacturing scarcity and fifteen-year follow-up mandates constrain supply scaling.
- Wound Care Products:Advanced dressings, antimicrobial barriers, and negative pressure systems manage chronic blistering and prevent secondary infection. Procurement concentrates in hospital outpatient departments and homecare channels across Japan and the United States. Symptomatic management retains the largest current revenue pool due to universal applicability across severity grades.
- Topical Treatments:Corticosteroid formulations, antibiotic ointments, and moisture-retentive emollients address localized lesions.
- Systemic Therapies:Immunomodulators and anti-inflammatory biologics target disease-modifying endpoints through circulating administration.
Mature deployment sits with Wound Care Products. Newer deployment is concentrated in Gene Therapy.
Delivery Mode:
Route selection balances bioavailability requirements against patient compliance and care setting constraints.
- Intravenous:Enables systemic distribution of biologics and gene therapy vectors requiring direct vascular access. Administration concentrates in academic medical centers with infusion pharmacy capabilities. Cold chain logistics and specialized nursing protocols limit site expansion.
- Transdermal:Emerging microneedle and electroporation platforms enable localized gene delivery without viral vectors. Pilot programs in community dermatology practices across Germany and the United States are validating redosable protocols. Elimination of infusion center dependency expands addressable geography.
- Subcutaneous:Facilitates self-administration or home nursing for select biologic formulations.
- Oral:Supports chronic symptomatic management with conventional small-molecule agents.
Established infrastructure dominates Intravenous administration. Transdermal innovation is climbing the fastest among emerging modalities.
End User:
Care setting migration reflects reimbursement pressure and patient preference for decentralized management.
- Specialty Clinics:Academic dermatology and genetics centers concentrate multidisciplinary expertise for complex case management. Patient recruitment for clinical trials and real-world evidence generation clusters in the United States, Germany, and Japan. Foundation-managed registries in these markets control referral flows to gene therapy programs.
- Homecare Settings:Wound care protocols and subcutaneous biologic administration shift to durable medical equipment distributors and visiting nurse services. Recurring revenue streams attract private equity investment in home infusion platforms across the United States.
- Hospitals:Retain gene therapy administration and surgical intervention for severe complications.
- Research Institutions:Drive natural history studies and early-phase clinical validation.
Commercial volume concentrates in Specialty Clinics. Homecare Settings are gaining share fastest as procurement patterns favor decentralized chronic management.
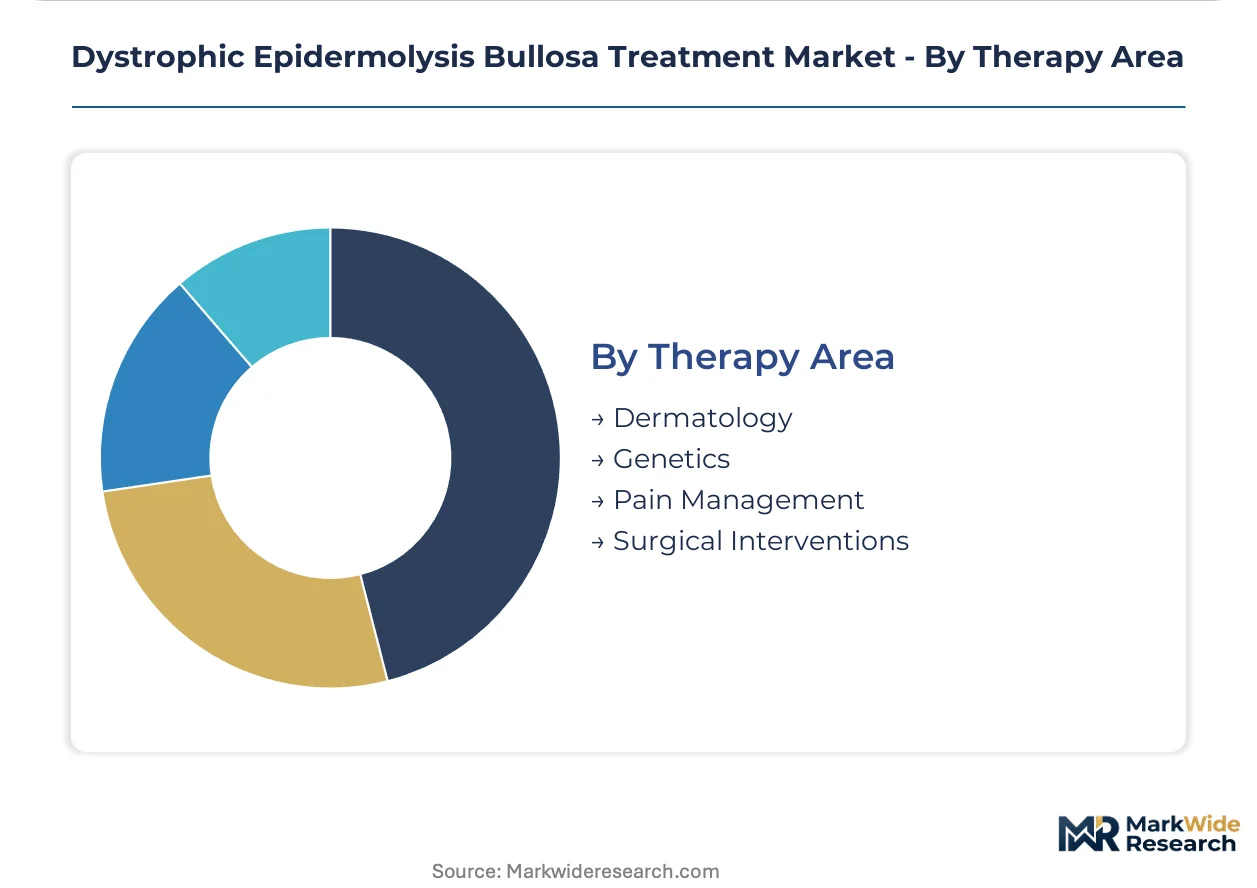
Therapy Area:
Clinical specialization determines prescriber access and payer categorization for reimbursement negotiations.
- Dermatology:Primary specialty managing wound care, infection prevention, and symptomatic relief across all severity grades. Prescriber concentration in tertiary care centers creates geographic access disparities. Modular therapy bundling negotiations favor vendors with integrated dressing and biologic portfolios.
- Genetics:Emerging specialty coordinating gene therapy candidacy assessment, vector selection, and long-term monitoring. Centers in the United States and Germany leverage FDA regenerative medicine advanced therapy and EMA PRIME designations to compress trial timelines.
- Pain Management:Addresses neuropathic and procedural pain associated with chronic wound care.
- Surgical Interventions:Encompasses escharotomy, contracture release, and digit preservation procedures.
Revenue concentration remains with Dermatology. Genetics is expanding most quickly as curative modalities advance through regulatory validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy manufacturing concentrates in the United States and Germany while patient recruitment and commercial deployment cluster in Japan alongside tertiary care networks. Consumption geography diverges from production capacity as regulatory acceleration and specialized infusion infrastructure determine access patterns.
United States
FDA orphan drug incentives and regenerative medicine advanced therapy designations compress clinical trial timelines for COL7A1-targeting programs. The Dystrophic Epidermolysis Bullosa Research Association of America negotiates directly with manufacturers for access protocols and registry-managed referrals. Academic medical centers in Boston, Philadelphia, and Stanford anchor gene therapy administration and fifteen-year post-treatment monitoring infrastructure.
Germany
EMA PRIME designation and accelerated assessment pathways attract sponsor investment for priority medicine status. G-BA reimbursement negotiations create launch delays for one-time curative interventions against chronic management benchmarks. Specialized dermatology centers in Munich, Heidelberg, and Berlin concentrate multidisciplinary expertise and real-world evidence generation for label expansion.
Japan
PMDA orphan drug designation and priority review vouchers accelerate regulatory timelines for ultra-rare disease programs. METI funding for regenerative medicine infrastructure expands GMP-grade viral vector manufacturing capacity. Tokyo, Osaka, and Nagoya host the Asia-Pacific's densest clustering of specialized wound care centers and gene therapy candidacy assessment programs.
United Kingdom
NICE technology appraisals struggle to value gene therapy cost-effectiveness against lifetime symptomatic management expenditure. MHRA post-Brexit regulatory autonomy enables accelerated access pathways for innovative medicinal products. London, Cambridge, and Manchester concentrate clinical trial recruitment and natural history study coordination for European programs.
Switzerland
Swissmedic expedited review procedures and HTA alignment with German precedents attract sponsor submissions for premium-priced biologics. Federal funding for rare disease research infrastructure supports patient registry interoperability across cantonal hospital networks. Basel, Zurich, and Geneva anchor pharmaceutical manufacturing partnerships and specialized pediatric dermatology referral pathways.
Dystrophic Epidermolysis Bullosa Treatment Market Vendor Landscape
The competitive structure tilts toward platform-specialized developers rather than diversified pharmaceutical conglomerates. Gene therapy vector engineering and autologous cell-based manufacturing require capabilities that incumbent wound care vendors cannot readily replicate. Three archetypes dominate: viral vector gene therapy platforms, redosable non-viral delivery systems, and integrated chronic wound care portfolios. Capacity expansion through contract manufacturing partnerships and strategic licensing for emerging market access represent the dominant competitive moves as sponsors navigate manufacturing scarcity.
Within the gene therapy platform tier, Krystal Biotech and Castle Creek Biosciences occupy differentiated positions based on vector selection and manufacturing approach. Amryt Pharma anchors the commercial distribution archetype across European and North American markets for approved symptomatic options. Abeona Therapeutics and Abeona's platform specialization exemplify the autologous cell-based development model that competes with systemic alternatives for prescriber attention and payer reimbursement slots.
| Leading Market Players |
|---|
| Amryt Pharma |
| Phoenix Tissue Repair |
| Krystal Biotech |
| RegeneRx |
| InMed Pharmaceuticals |
| Castle Creek Biosciences |
| Wings Therapeutics |
| Holostem Terapie Avanzate |
| Abeona Therapeutics |
| Others |
Supply Flow & Price Mechanics
Redosable non-viral gene delivery platforms are compressing cost economics for moderate-severity patients while simultaneously fragmenting supply concentration away from AAV contract manufacturers clustered in the United States and Germany. This dual shift rebalances pricing power toward developers with in-house vector engineering capabilities and cold-chain-free distribution networks.
Pricing Analysis
Margin tightening in gene therapy tiers reflects AAV manufacturing scarcity and fifteen-year post-treatment monitoring mandates that inflate total cost of care. Pricing stratifies across one-time curative interventions, chronic biologic infusions, and symptomatic wound care bundles. Cost-down pressure on viral vector production accelerates as sponsors negotiate GMP-grade material contracts. Hospital procurement committees exhibit highest price sensitivity for chronic management protocols, while specialty clinics absorb premium pricing for curative candidates.
Supply Chain Analysis
Viral vector production rests on contract manufacturing organizations concentrated in the United States, Germany, and Japan. Plasmid DNA, HEK293 cell lines, and GMP-grade reagents constitute critical input dependencies. Single-source vulnerability pervades AAV serotype-specific production suites with limited cross-platform flexibility. Distribution runs through specialized infusion centers with cold chain logistics and certified nursing protocols for gene therapy administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over vector manufacturing capacity and long-term patient monitoring infrastructure determines sustainable margin capture.
For Market Incumbents:Extend manufacturing partnerships into captive AAV production capacity to secure supply priority against oncology program competition. Deepen registry-controlled referral relationships with the Dystrophic Epidermolysis Bullosa Research Association of America and European patient advocacy networks to defend channel access against emerging redosable platform developers.
For New Entrants and Emerging Players:Capture homecare channel wound care contracts that incumbent gene therapy developers neglect due to monitoring infrastructure requirements. Target Brazil's ANVISA orphan drug pathway and Saudi Arabia's SFDA priority review for early-mover positioning before G-BA and NICE reimbursement negotiations mature.
For Investors and Strategic Acquirers:Exit pathways concentrate in platform-specialized developers with validated COL7A1-targeting vector engineering rather than diversified wound care portfolios. Long-term viability hinges on manufacturing scale-up execution and confirmatory trial design commitments to FDA and EMA. Watch for EMA PRIME designation awards and FDA regenerative medicine advanced therapy approvals as inflection signals for valuation step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive AAV production capacity insulates against contract manufacturer queue delays and premium pricing. |
| Regulatory Approval Pathway | EMA PRIME and FDA regenerative medicine advanced therapy designations compress development timelines and enhance valuation. |
| Licensing Agreement | Local partnerships in Brazil and Saudi Arabia satisfy ANVISA and SFDA domestic requirements without direct investment. |
| Pipeline Diversification | Redosable non-viral platforms expand addressable geography beyond infusion center-dependent AAV approaches. |
| Reimbursement Strategy | Foundation-managed registry relationships anchor patient referral flows and payer negotiation leverage. |
Methodological Framework
Independent corroboration across gene therapy development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists underwrites the qualitative findings. Secondary validation draws from FDA orphan drug designations, EMA PRIME submissions, ClinicalTrials.gov protocols, and formulary databases across the United States, Germany, and Japan. Bottom-up patient population modeling and top-down revenue triangulation reconcile volume and value estimates.
Rate-of-change decomposition across therapeutic modality, delivery mode, end user, and therapy area segments structures the analytical framework. CAGRs derive from segment-level growth trajectories weighted by addressable patient populations and pricing tier evolution. Gene therapy manufacturing capacity expansion schedules and regulatory pathway acceleration events constitute key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to viral vector production bottlenecks, G-BA reimbursement precedent outcomes, and redosable platform clinical validation timelines. A small set of regulatory designation awards and manufacturing partnership announcements warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Phelan-Mcdermid Syndrome Market
Rare Diseases
Glanzmann Thrombasthenia Market
Rare Diseases
Behcets Disease Market
Rare Diseases
Middle East and Africa Down Syndrome Market
Rare Diseases
Global Guillain-Barre Syndrome Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Rare Inflammatory Disease Treatment Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Gastrointestinal Rare Diseases Treatment Market
Rare Diseases
Menkes Syndrome Market
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Rare Neurodegenerative Disease Treatment Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Down Syndrome Market
Rare Diseases
Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market
Rare Diseases
Gaucher Disease Drugs Market