
 Global Dermatological OTC Drugs Market | 2026-2036
Global Dermatological OTC Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dermatological OTC Drugs Market Foresight
Pharmaceutical-grade formulation standards is rotating the Global Dermatological OTC Drugs Market toward higher-margin, clinically validated SKUs. Johnson & Johnson leverages its consumer health division to sustain shelf dominance across North American retail pharmacies. Bayer AG anchors European distribution through pharmacist-endorsed hydrocortisone and clotrimazole lines. Galderma specializes in dermocosmetic positioning that commands premium pricing in clinic-adjacent channels.
Dermatological OTC drugs comprise non-prescription topical and oral preparations containing active pharmaceutical ingredients at concentrations approved for self-administration without physician supervision, typically formulated with corticosteroids, antifungal agents, or keratolytic compounds in cream, gel, or ointment vehicles designed for skin barrier modulation and inflammatory control. Antifungal and anti-acne product types capture disproportionate margin pools due to high recurrence rates and brand loyalty among chronic sufferers. E-commerce platforms represent the fastest-expanding distribution channel as algorithm-driven replenishment and telehealth referrals redirect traffic from brick-and-mortar pharmacies.
FDA OTC monograph reform and EU MDR compliance obligations are elevating documentation burdens for ingredient safety and label claims, effectively filtering out subscale private-label competitors. The country's national pharmaceutical regulators in Japan and South Korea are tightening import inspection protocols for topical steroids and antiseptics. Stakeholders must monitor evolving monograph status for emerging actives and calibrate R&D pipelines against regional divergence in permissible concentrations and combination rules.
Market Dynamics
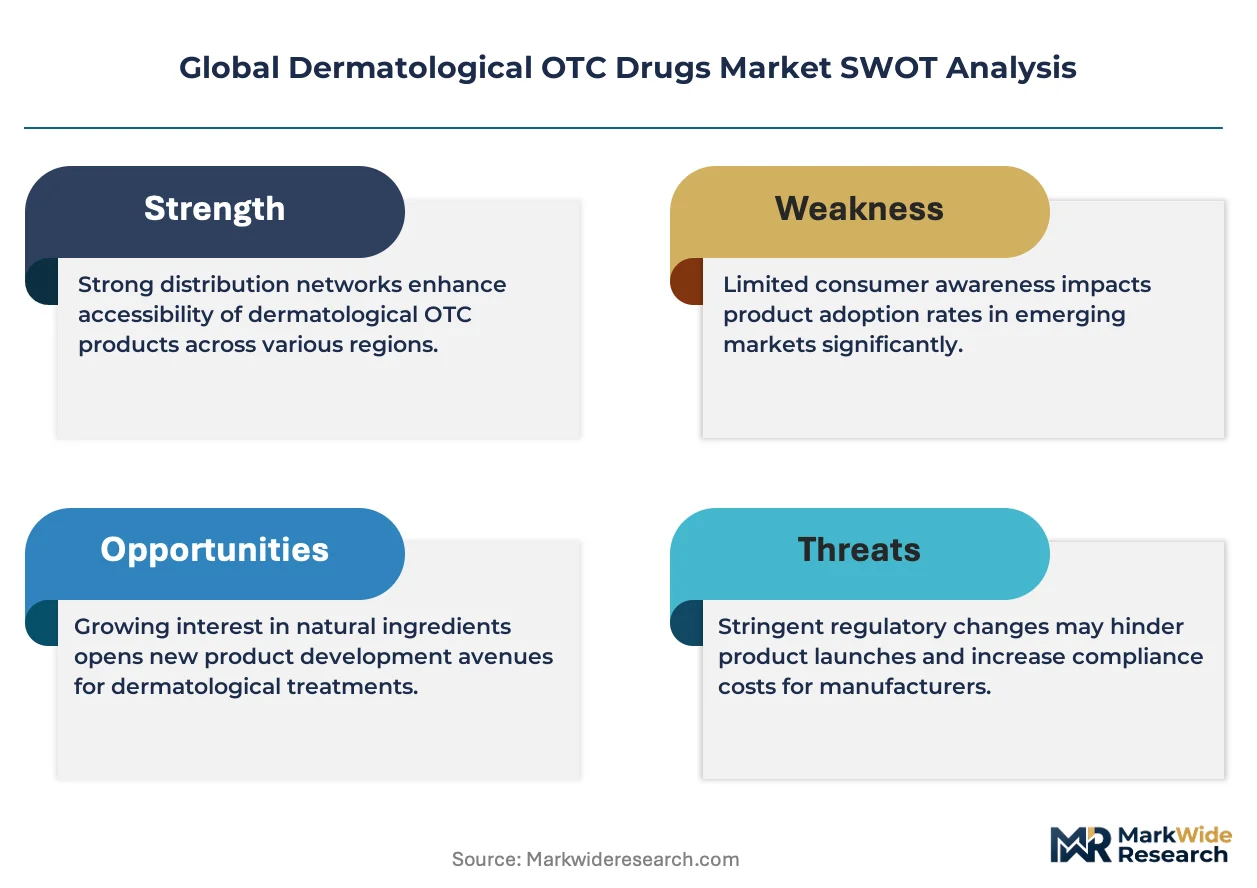
Pharmaceutical-grade formulation standards are compressing margin structures across the dermatological OTC drugs sector, forcing manufacturers to absorb elevated compliance costs while defending shelf position against clinically validated private-label alternatives.
Growth Catalysts
- Aging demographics in developed economies:Self-medication rates among consumers over 65 in the United States, Germany, and Japan sustain recurring demand for topical antifungal and anti-acne maintenance regimens.
- EU MDR compliance timelines:The Medical Device Regulation's ingredient disclosure mandates are filtering out subscale competitors and consolidating shelf space for documented formulations in European pharmacy channels.
- E-commerce algorithmic replenishment:Telehealth platforms and subscription-based auto-delivery models are capturing chronic-condition sufferers who prioritize convenience over pharmacy counter consultation.
Market Restraints
- Active pharmaceutical ingredient concentration caps:FDA OTC monograph reforms and Japan's PMDA import inspection protocols restrict permissible steroid and antiseptic potencies, forcing reformulation of legacy SKUs.
- Documentation burden escalation:Efficacy substantiation requirements under EU MDR and state-level pharmacy board audits in the United States are extending product development cycles and elevating fixed compliance costs.
- Substitution by dermocosmetic positioning:Clinic-adjacent channels are diverting premium-seeking consumers toward cosmeceutical alternatives that bypass pharmaceutical regulatory scrutiny entirely.
Strategic Opportunities
- Underpenetrated South Korean retail pharmacy modernization:MFDS regulatory alignment with international standards is opening import pathways for documented European and North American brands.
- Combination active convergence:Keratolytic-antifungal and corticosteroid-antimicrobial hybrid formulations are creating differentiated positioning in recurrence-prone chronic conditions.
- Pharmacist-endorsed channel expansion:Professional recommendation programs in German and Swiss pharmacy cooperatives are commanding price premiums over mass retail alternatives.
Industry Challenges
- Cross-regulatory divergence in combination rules:Permissible active pairings vary between FDA monographs, EU MDR annexes, and Japan's PMDA guidance, complicating global SKU rationalization.
- Legacy distribution integration friction:Brick-and-mortar pharmacy networks in the United States and Germany are resisting margin compression from direct-to-consumer platform encroachment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dermatological OTC Drugs Market |
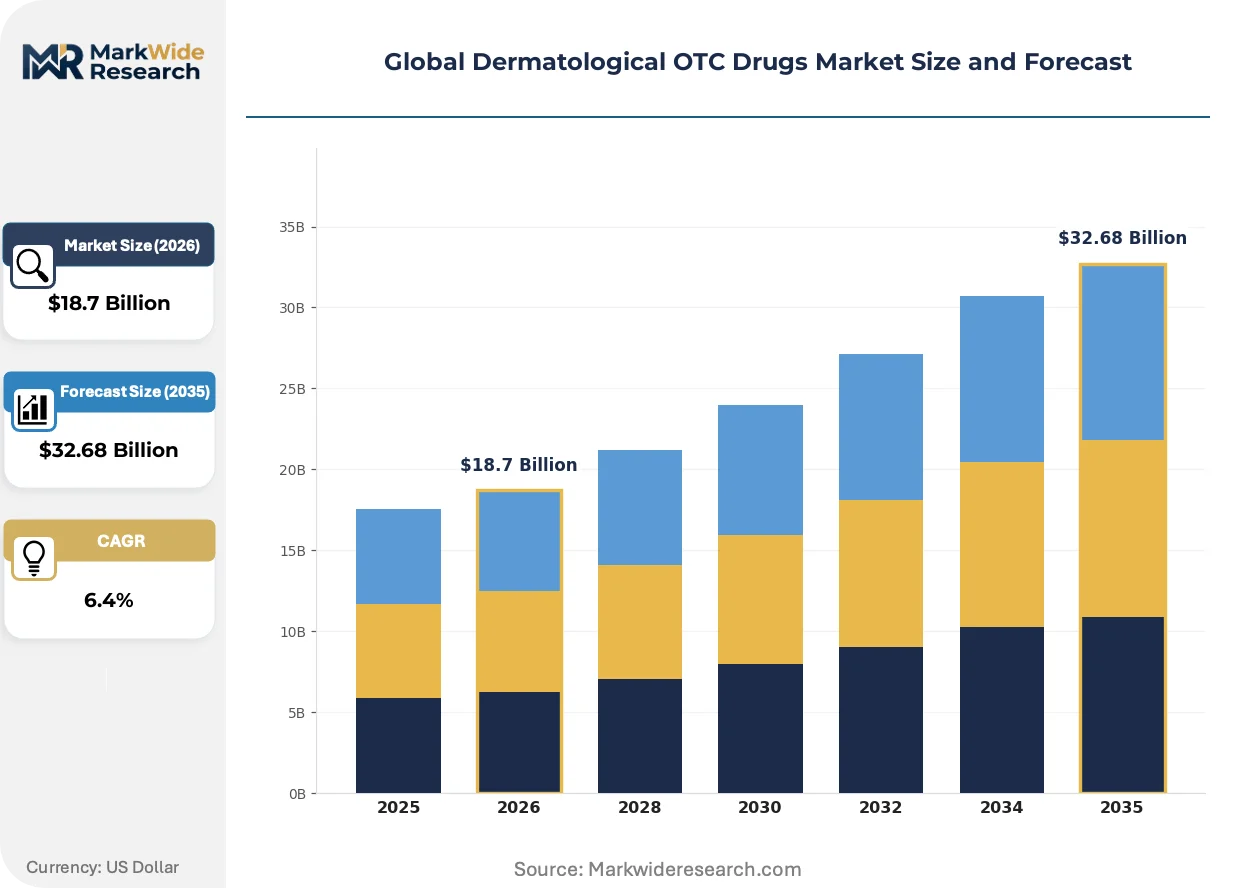
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiseptics, Emollients, Anti-Acne, Antifungal, Corticosteroids, Keratolytics Application: Psoriasis, Eczema, Fungal Infections, Acne Treatment, Wound Care, Sun Protection End User: Pharmacies, Drugstores, Dermatology Clinics, Cosmetic Retailers, Online Stores Distribution Channel: Direct Sales, Retail Pharmacies, E-Commerce Platforms, Hospital Pharmacies, Specialized Outlets |
| Companies Covered | Perrigo Company plc, Bausch Health Companies Inc., Johnson & Johnson, Bayer AG, Galderma, GlaxoSmithKline plc, Viatris Inc, Teva Pharmaceutical Industries Ltd., Dr. Reddy's Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dermatological OTC Drugs Market Shifts & Advancements
Formulation science and channel architecture are diverging simultaneously across the dermatological OTC drugs sector, with clinical validation requirements tightening while consumer access pathways multiply beyond traditional pharmacy counters.
Microbiome-targeted topical delivery systems are fragmenting the anti-acne category's historical reliance on benzoyl peroxide and salicylic acid monotherapies. Dermocosmetic brands and pharmaceutical manufacturers are both investing in prebiotic and postbiotic actives that modulate skin flora rather than stripping sebaceous barriers. The structural consequence is fragmenting market share concentration among legacy keratolytic leaders as clinically substantiated microbiome claims capture premium positioning.
EU MDR Article 10 post-market surveillance obligations are elevating pharmacovigilance documentation requirements for all topical OTC drugs distributed in European Economic Area member states. Manufacturers must now maintain systematic safety data collection and periodic safety update reports that parallel prescription drug standards. Smaller private-label suppliers without dedicated regulatory affairs infrastructure are exiting the market, concentrating shelf presence among scaled pharmaceutical divisions.
Algorithm-driven replenishment models are displacing episodic pharmacy counter purchases for chronic dermatological conditions. Subscription platforms in the United States and United Kingdom are capturing anti-fungal and eczema maintenance users through predictive refill timing and telehealth prescriber integration. This behavioral shift is most visible among millennial and Generation X consumers managing recurrence-prone conditions who prioritize uninterrupted therapy adherence over professional consultation.
Global Dermatological OTC Drugs Market Segmentation
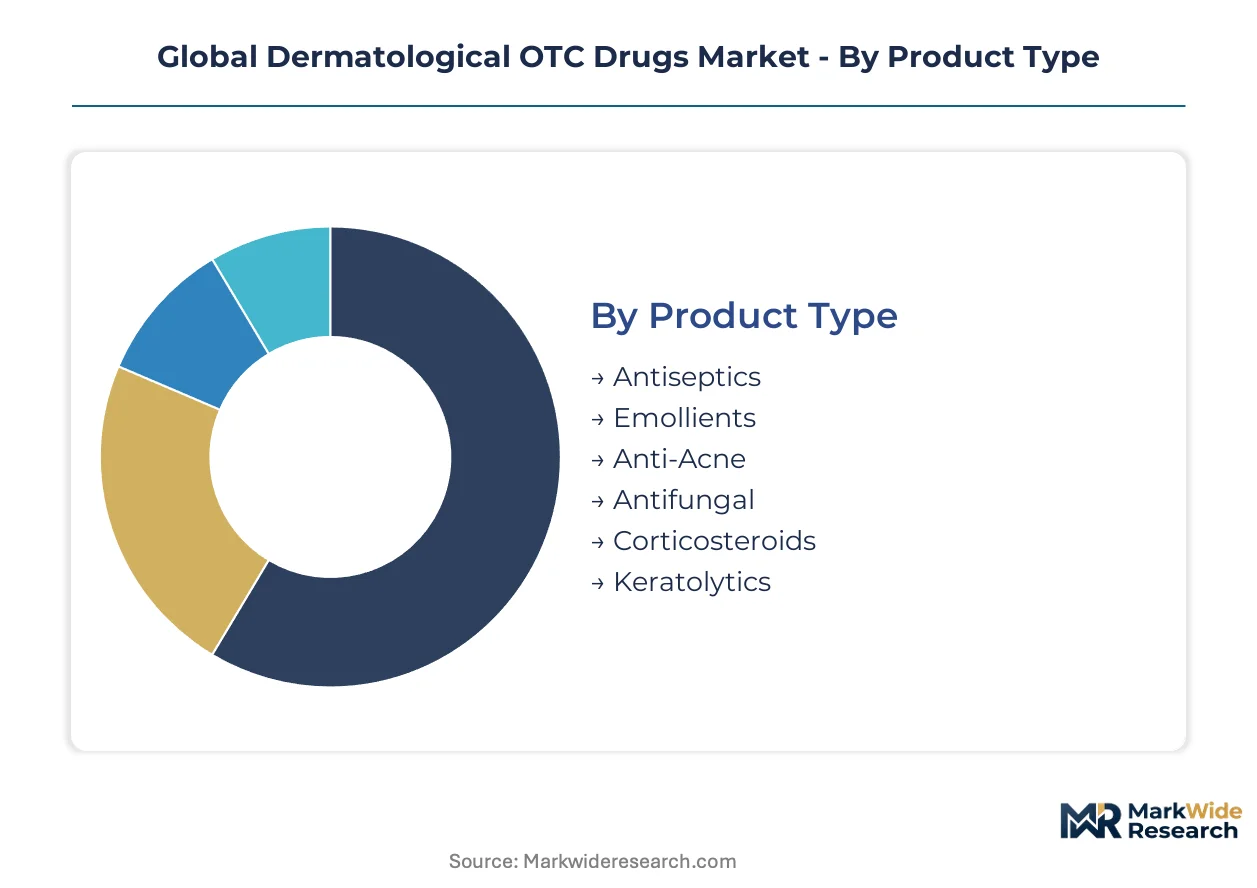
Margin concentration across dermatological OTC drugs varies sharply by therapeutic category and channel control. Manufacturers calibrate portfolio mix against recurrence rates, regulatory documentation burdens, and pharmacist endorsement premiums that differ fundamentally across segment boundaries.
Product Type:
Antifungal and anti-acne formulations command the widest margin spreads due to chronic-condition recurrence and brand loyalty stickiness.
- Antifungal:Topical azole and allylamine preparations target dermatophyte colonization of skin, hair, and nail surfaces. Recurrence-driven replenishment in the United States and Germany sustains premium pricing for pharmacist-recommended brands despite private-label encroachment.
- Anti-Acne:Keratolytic and antimicrobial combinations modulate sebum production and Cutibacterium acnes proliferation. Millennial and Generation X self-medication in Japan and South Korea favors dermocosmetic-positioned lines that command clinic-adjacent premiums over mass retail equivalents.
- Corticosteroids:Hydrocortisone formulations provide inflammatory control for eczema and dermatitis flares.
- Keratolytics:Salicylic acid and urea preparations address hyperkeratotic conditions including psoriasis plaques and callus formation.
- Emollients:Barrier-repair formulations target atopic dermatitis maintenance regimens.
- Antiseptics:Povidone-iodine and chlorhexidine preparations address minor wound disinfection.
Antifungal holds the dominant share, while anti-acne is climbing the fastest on dermocosmetic premiumization and telehealth channel expansion.
Application:
Chronic inflammatory conditions generate recurring revenue streams that dwarf episodic acute treatment categories.
- Fungal Infections:Tinea pedis, corporis, and cruris presentations drive the highest per-patient lifetime value through recurrence-prone maintenance protocols. Japanese pharmacy chains and German cooperative networks capture disproportionate margin through pharmacist-guided brand selection.
- Eczema:Atopic and contact dermatitis management requires sustained emollient and intermittent corticosteroid use. Pediatric and aging demographics in the United States sustain volume concentration despite EU MDR documentation burdens elevating compliance costs.
- Acne Treatment:Adolescent and adult persistent presentations favor combination therapy approaches.
- Psoriasis:Plaque and scalp variants require keratolytic-corticosteroid combination regimens.
- Wound Care:Minor abrasion and post-procedural healing applications favor antiseptic-first protocols.
- Sun Protection:Photodamage prevention positioning increasingly overlaps with dermocosmetic skincare.
Eczema captures the largest patient population base, though fungal infections deliver superior per-user economics through replenishment frequency.
End User:
Channel control determines pricing power, with professional endorsement commanding substantial premiums over self-selection formats.
- Pharmacies:German and Swiss cooperative networks leverage pharmacist consultation to sustain price premiums for documented formulations. EU MDR compliance filters shelf presence toward scaled manufacturers with dedicated regulatory infrastructure.
- Online Stores:Algorithmic replenishment and telehealth integration capture chronic-condition sufferers prioritizing convenience. United States and United Kingdom subscription platforms displace episodic pharmacy purchases for antifungal and eczema maintenance users.
- Drugstores:Mass retail self-selection favors private-label and value-tier alternatives.
- Dermatology Clinics:Clinic-adjacent positioning enables dermocosmetic premiumization beyond pharmaceutical regulatory boundaries.
- Cosmetic Retailers:Sephora and equivalent channels blur pharmaceutical-cosmeceutical boundaries for acne and sun protection categories.
Pharmacies retain the dominant volume position, while online stores are expanding most quickly on millennial preference for subscription adherence.
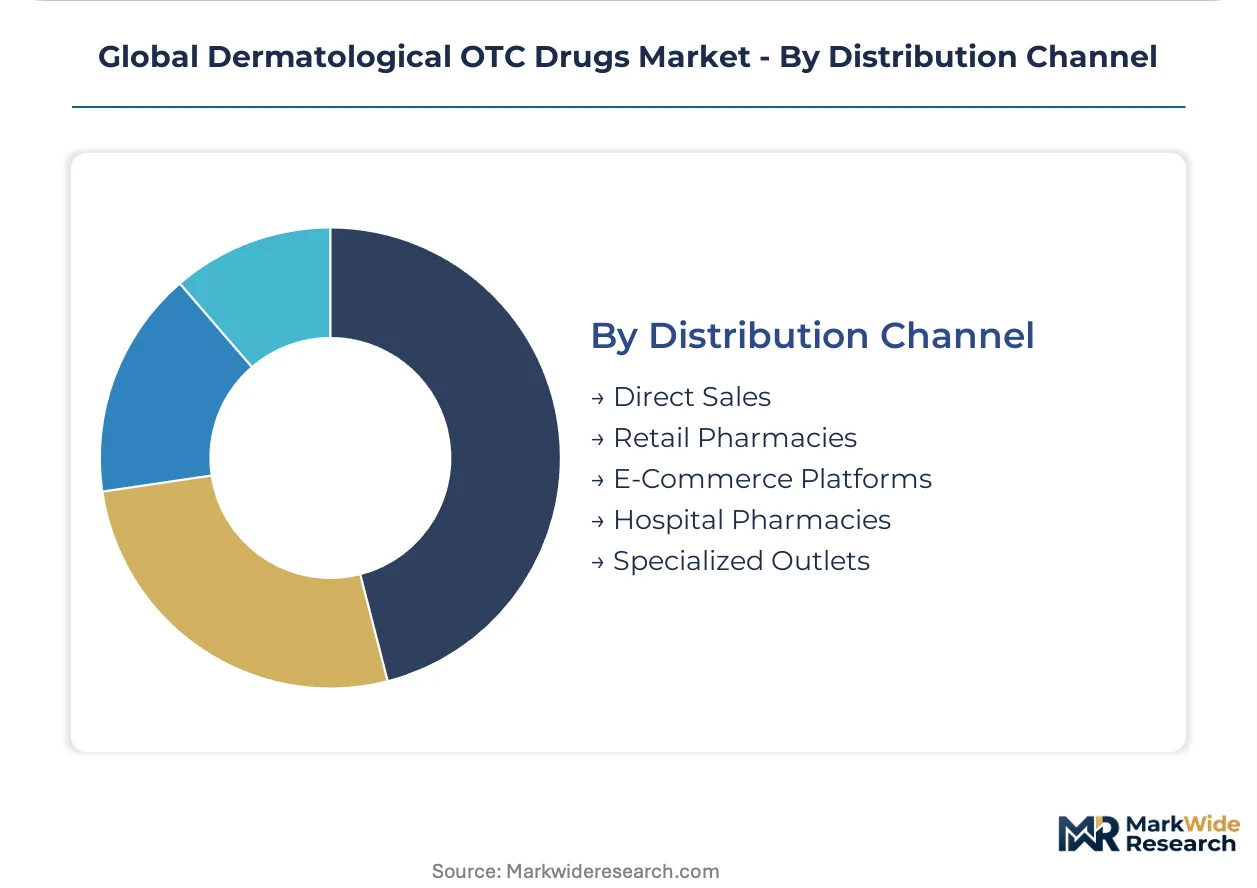
Distribution Channel:
Direct-to-consumer platform encroachment is fragmenting historical pharmacy channel concentration.
- E-Commerce Platforms:Predictive refill timing and telehealth prescriber integration capture recurrence-prone chronic sufferers. Amazon and specialized dermatology platforms in the United States and United Kingdom redirect traffic from brick-and-mortar counters through algorithm-driven replenishment.
- Retail Pharmacies:CVS, Walgreens, and equivalent chains defend position through loyalty programs and pharmacist consultation services. German Apotheken and Japanese drugstores sustain premium capture through professional endorsement protocols.
- Direct Sales:Manufacturer-controlled subscription models bypass intermediary margin extraction.
- Hospital Pharmacies:Post-discharge continuity protocols favor documented formulation selection.
- Specialized Outlets:Dermatology clinic retail and dermocosmetic boutiques command premium positioning.
Retail pharmacies maintain category leadership, though e-commerce platforms are gaining share fastest on convenience-oriented demographic shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates among manufacturers with dedicated regulatory infrastructure in the United States, Germany, and Japan, where pharmacy-led distribution and high consumer health literacy sustain premium product uptake. FDA OTC monograph reforms and EU MDR compliance timelines are filtering shelf presence toward scaled pharmaceutical divisions with documented formulation capabilities.
United States
Aging demographics over 65 sustain recurring demand for topical antifungal and anti-acne maintenance regimens through CVS and Walgreens pharmacy networks. FDA OTC monograph reforms are elevating documentation burdens for ingredient safety and label claims, filtering out subscale private-label competitors. Algorithm-driven replenishment platforms in California and New York redirect traffic from brick-and-mortar counters through subscription-based auto-delivery models.
Germany
Pharmacist-endorsed hydrocortisone and clotrimazole lines anchor European distribution through cooperative Apotheken networks that command price premiums over mass retail alternatives. EU MDR Article 10 post-market surveillance obligations require systematic safety data collection that parallels prescription drug standards. Industrial concentration in North Rhine-Westphalia and Bavaria hosts scaled pharmaceutical divisions with dedicated regulatory affairs infrastructure.
Japan
High consumer health literacy and pharmacy-led distribution sustain premium positioning for dermocosmetic-positioned anti-acne lines among millennial and Generation X self-medication segments. PMDA import inspection protocols for topical steroids and antiseptics are tightening permissible potencies, forcing reformulation of legacy SKUs. Tokyo and Osaka metropolitan areas concentrate clinic-adjacent channel expansion for premium SKUs.
South Korea
MFDS regulatory alignment with international standards is opening import pathways for documented European and North American brands through retail pharmacy modernization. National pharmaceutical regulators are tightening inspection protocols for topical actives, elevating compliance barriers for undocumented suppliers. Seoul Capital Area and Busan-Ulsan clusters concentrate e-commerce platform development for algorithmic replenishment models.
United Kingdom
Telehealth platforms and subscription-based auto-delivery models capture chronic-condition sufferers who prioritize convenience over pharmacy counter consultation. MHRA post-Brexit regulatory divergence from EU MDR creates documentation complexity for cross-border formulation approvals. London and Southeast England host specialized dermatology platform development for predictive refill timing integration.
Global Dermatological OTC Drugs Market Competitive Landscape
Concentration sits with diversified pharmaceutical conglomerates and specialized dermocosmetic divisions that leverage dedicated regulatory infrastructure to defend shelf position against clinically validated private-label alternatives. The vendor base stratifies across three tiers: scaled consumer health divisions with global distribution networks, mid-cap specialists with regional pharmacy channel dominance, and private-label suppliers exiting under documentation burden escalation. Dominant competitive moves include portfolio diversification into microbiome-targeted actives and strategic partnerships with telehealth platforms for algorithmic replenishment integration.
Within the diversified pharmaceutical tier, Johnson & Johnson and Bayer AG exemplify archetypes that sustain shelf dominance through consumer health division scale and pharmacist-endorsed channel relationships. Galderma occupies a specialist position representing dermocosmetic premiumization strategies that command clinic-adjacent pricing beyond pharmaceutical regulatory boundaries. These three anchors demonstrate how regulatory documentation capabilities and channel control determine competitive positioning across pharmacy, e-commerce, and clinic-adjacent distribution vectors.
| Leading Market Players |
|---|
| Perrigo Company plc |
| Bausch Health Companies Inc. |
| Johnson & Johnson |
| Bayer AG |
| Galderma |
| GlaxoSmithKline plc |
| Viatris Inc |
| Teva Pharmaceutical Industries Ltd. |
| Dr. Reddy's Laboratories |
| Others |
Supply & Pricing Matrix
FDA OTC monograph reform gates both supply qualification and price differentiation simultaneously, filtering shelf presence toward documented formulations while compressing margin structures for subscale competitors. EU MDR compliance timelines and Japan's PMDA import inspection protocols create parallel regulatory barriers that sustain premium capture for manufacturers with dedicated pharmacovigilance infrastructure.
Pricing Analysis
FDA OTC monograph reform dictates the pricing tier structure across dermatological OTC drugs, stratifying formulations across pharmacist-endorsed premium SKUs, mass retail documented brands, and private-label economy alternatives. Certification grade under EU MDR Article 10 and brand premium from clinic-adjacent dermocosmetic positioning drive price differentiation, while cost compression in economy tiers intensifies due to documentation burden escalation. Private-label suppliers exhibit highest price sensitivity as compliance costs force exit, whereas dermocosmetic-positioned lines in Japanese and German pharmacy channels demonstrate lowest sensitivity.
Supply Chain Analysis
API synthesis concentration in India and China anchors raw material supply for topical corticosteroids and antifungal actives, with formulation finishing concentrating in the United States, Germany, and Japan. Active pharmaceutical ingredients draw from specialized chemical manufacturers in Gujarat and Zhejiang provinces, while packaging components rest on polymer suppliers in North Rhine-Westphalia and Osaka industrial clusters. Single-source vulnerability runs through legacy azole intermediate suppliers, and distribution runs through pharmacy cooperative networks in Germany and direct-to-consumer platforms in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dermocosmetic alternatives bypassing pharmaceutical regulatory scrutiny threaten substitution of premium OTC positioning, compelling incumbents to defend clinical validation moats while entrants exploit white-space in underpenetrated channels.
For Market Incumbents: Secure pharmacist endorsement premiums through EU MDR documentation investment and backward integration into API supply to offset margin compression from algorithmic replenishment platforms. Threat from private-label encroachment demands channel control reinforcement in German Apotheken cooperatives and Japanese drugstore networks. For New Entrants and Emerging Players: MFDS regulatory alignment fast-track opens South Korean retail pharmacy modernization for documented European and North American brands with combination active convergence in keratolytic-antifungal hybrids. Target underpenetrated Seoul Capital Area e-commerce platforms with telehealth-integrated subscription models capturing millennial eczema maintenance users. For Investors and Strategic Acquirers: EU MDR Article 10 post-market surveillance obligations reshape the acquisition landscape toward scaled pharmaceutical divisions with dedicated regulatory affairs infrastructure. Long-term viability centers on manufacturers with pharmacovigilance capabilities spanning prescription-paralleling documentation standards. Signal to monitor: divergence in FDA-EU-Japan combination active rules forcing SKU rationalization costs.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Investment | Systematic safety data collection parallels prescription drug standards, filtering subscale competitors. |
| Microbiome-Targeted R&D Pipeline | Prebiotic and postbiotic actives fragment anti-acne category share from legacy benzoyl peroxide leaders. |
| Telehealth Platform Partnership | Algorithmic replenishment captures chronic-condition sufferers prioritizing convenience over pharmacy consultation. |
| Pharmacist-Endorsed Channel Expansion | German and Swiss cooperative networks command price premiums over mass retail alternatives. |
| Combination Active Convergence | Keratolytic-antifungal hybrids create differentiated positioning in recurrence-prone chronic conditions. |
Research Methodology
A spread of perspectives from regulatory affairs directors at pharmaceutical manufacturers, pharmacy cooperative procurement managers in Germany, telehealth platform operators, and formulary specialists at Japanese drugstore chains converged on the working assumptions. Secondary validation drew from FDA OTC monograph filings, EMA MDR submission databases, MFDS import inspection protocols, and pharmacy retail audit data. Bottom-up patient population modeling and top-down pharmaceutical division revenue triangulation anchored volume and value estimates.
Segmentation dimensions modeled span product type, application, end user channel, and regional regulatory cluster across the projection horizon. CAGRs derive from patient population growth trajectories, recurrence-rate-driven replenishment frequency, and channel shift elasticity coefficients. Forecast inputs include EU MDR compliance timeline adherence rates and e-commerce penetration curves for chronic dermatological conditions.
Decision-makers should treat outputs as directional under stable regulatory enforcement intensity and chronic-condition prevalence assumptions; material deviation in FDA monograph reform implementation pace would warrant model refresh. Practitioners should keep alternative scenarios live as PMDA import inspection stringency and telehealth reimbursement policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Homecare Dermatology Energy-Based Devices Market
Dermatology
Scar Treatment Market
Dermatology
Dermal Facial Fillers Market
Dermatology
Global Online Dermatology Consultation Market
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Keratoacanthoma Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Derma Rollers Market
Dermatology
Acne Vulgaris Treatment Market
Dermatology
Dermatophytic Onychomycosis Treatment Market
Dermatology
Japan Scar Treatment Market
Dermatology
Scleroderma Treatment Market
Dermatology
Acne Vulgaris Market
Dermatology
Androgenetic Alopecia Market
Dermatology
Cutaneous Squamous Cell Carcinoma Market
Dermatology
Global Ozone Therapy in Dermatology Market