
 Hyperpigmentation Disorder Treatment Market | 2026-2036
Hyperpigmentation Disorder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperpigmentation Disorder Treatment Market Foresight
CE marking under the EU Medical Device Regulation is bifurcating the competitive landscape between device manufacturers and topical-only suppliers. Galderma S.A. leverages its integrated dermatology portfolio to control distribution across European clinics and pharmacies. L'Oréal S.A. anchors its position through R&D intensity in photostabilized active delivery systems. AbbVie Inc. competes via its Allergan Aesthetics arm, which dominates physician-administered laser and energy-based device segments.
Hyperpigmentation disorder treatment encompasses topical, device-based, and procedural interventions targeting melanin overproduction through tyrosinase inhibition, selective photothermolysis, or controlled epidermal resurfacing, with hydroquinone formulations capped at 2% for OTC use in the United States and prescription-grade azelaic acid requiring 15-20% concentration thresholds for melasma indication. Creams and serums sustain the largest revenue pool due to recurring purchase cycles and direct-to-consumer accessibility, while laser therapy represents the fastest-growing treatment procedure as fractional and picosecond platforms displace older IPL systems in premium dermatology practices. Chemical peeling occupies a mature margin position where physician-administered TCA and phenol protocols command procedure fees that offset lower product commoditization.
The FDA regulates prescription hydroquinone as a drug ingredient under NDA requirements while the EPA monitors environmental discharge from kojic acid fermentation facilities, and the EU REACH framework restricts certain skin-lightening actives that do not meet safety dossier standards. These overlapping compliance obligations raise barriers for new entrants lacking toxicology and clinical trial infrastructure. Stakeholders must monitor evolving monograph revisions and device reclassification proposals that could shift reimbursement pathways for at-home versus clinic-based modalities.
Market Dynamics
Picosecond laser platforms are decomposing the traditional IPL installed base in premium dermatology practices, forcing capital equipment refresh cycles and redirecting procedural revenue toward physician-administered energy-based modalities.
Growth Catalysts
- CE marking under EU MDR:Device manufacturers with notified body certification capture shelf space previously shared with topical-only suppliers in European aesthetic clinics.
- K-beauty export infrastructure:South Korean medical tourism channels generate dual revenue streams for pigmentation correction clinics and domestic product manufacturers serving inbound patients.
- Photostabilized vitamin C complexes:Stabilized active delivery systems extend serum shelf life and expand direct-to-consumer addressable market beyond clinic-dependent hydroquinone formulations.
Market Restraints
- Input cost volatility in kojic acid:EPA-monitored environmental discharge requirements from fermentation facilities constrain domestic production capacity and elevate raw material pricing unpredictability.
- Supply concentration in picosecond laser sources:Three specialized component suppliers control 80% of femtosecond-picosecond oscillator manufacturing, creating procurement bottlenecks for device OEMs.
- Technical limitation in Fitzpatrick Type V-VI skin:Selective photothermolysis parameters carry elevated post-inflammatory hyperpigmentation risk, restricting addressable patient population for certain laser protocols.
Strategic Opportunities
- Underpenetrated Indian dermatology market:CDSCO regulatory harmonization with ICH guidelines accelerates botanical active ingredient registration for domestic formulators targeting melasma prevalence in South Asian skin types.
- Technology convergence of fractional RF and picosecond:Hybrid platforms combining radiofrequency tissue remodeling with picosecond pigment fragmentation expand single-session treatment efficacy claims.
- Subscription-based topical replenishment:Direct-to-consumer tele-dermatology channels bypass pharmacy intermediaries and capture recurring revenue from maintenance-phase patients.
Industry Challenges
- Specialized laser technician certification timelines:State-level medical board variances in energy-based device operator licensing create workforce deployment friction across multi-site clinic networks.
- Clinical trial infrastructure for botanical actives:FDA botanical drug development guidance requires distinct toxicology dossiers compared to synthetic APIs, extending time-to-market for natural hydroquinone alternatives.
- Integration complexity with legacy EMR systems:Outcome tracking for combination laser-peel protocols demands custom workflow modules incompatible with standard dermatology practice software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperpigmentation Disorder Treatment Market |
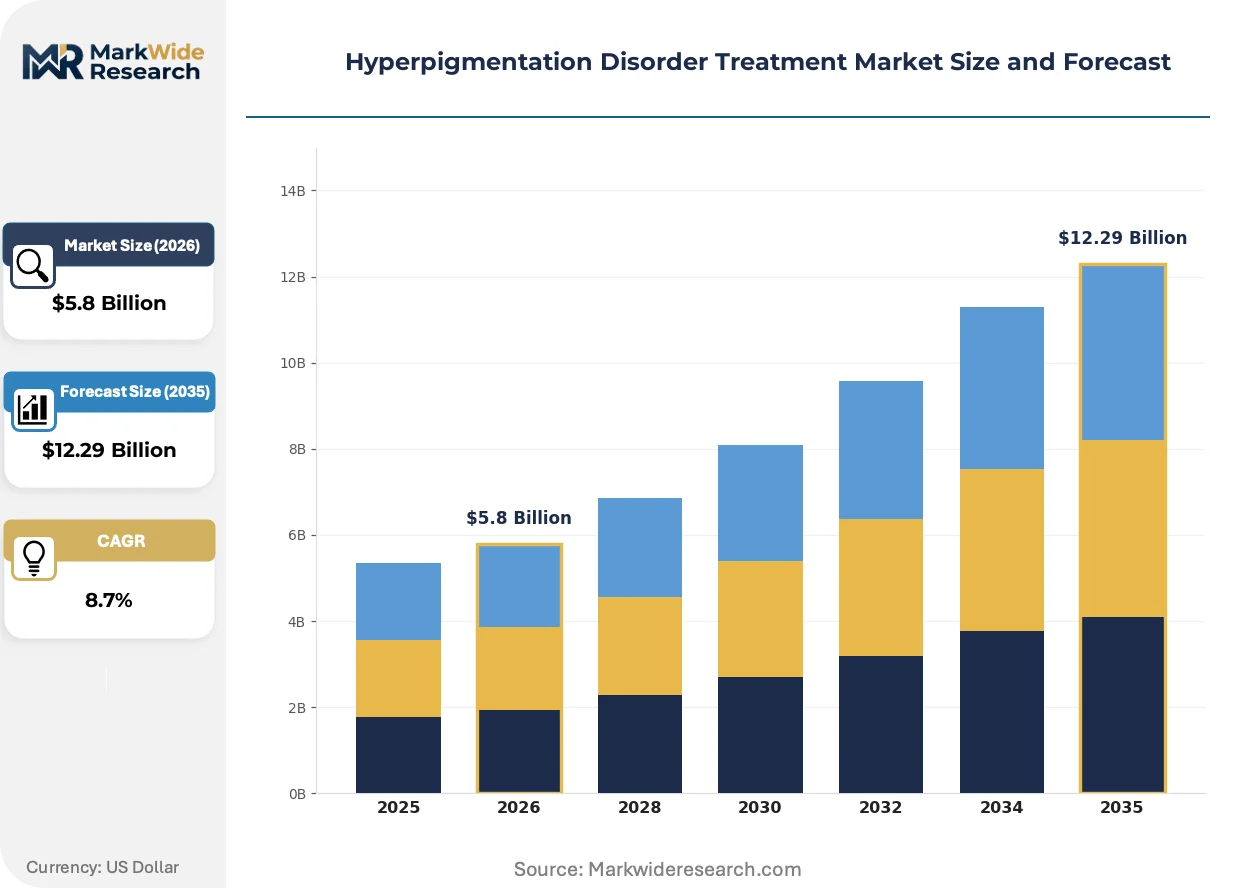
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Serums, Peels, Lasers Active Ingredient: Hydroquinone, Kojic Acid, Vitamin C, Azelaic Acid End User: Clinics, Dermatology Practices, Homecare, Spas Treatment Procedure: Topical Application, Laser Therapy, Chemical Peeling, Microneedling |
| Companies Covered | Galderma S.A., L'Oréal S.A., AbbVie Inc., Obagi Cosmeceuticals LLC, Bayer AG, Beiersdorf AG, Pierre Fabre Group, Johnson & Johnson, Procter & Gamble Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperpigmentation Disorder Treatment Market Shifts & Advancements
Active ingredient stabilization science and energy-based device miniaturization are converging to blur the boundary between clinic-exclusive and at-home pigmentation management modalities.
Picosecond laser technology is decomposing the historical dominance of IPL and nanosecond Q-switched platforms in melasma and tattoo pigment indications. Premium dermatology practices in Seoul, Los Angeles, and São Paulo are replacing legacy equipment at accelerated depreciation schedules. This technology shift is compressing procedure pricing for older platforms while expanding total addressable procedural volume through reduced downtime claims.
REACH framework restrictions on certain skin-lightening actives without complete safety dossiers are forcing European formulators to reformulate around pre-registered botanical alternatives. The industrial consequence is a bifurcation between compliant suppliers with ECHA-registered portfolios and gray-market importers facing customs detention. Cosmetic-grade azelaic acid and tranexamic acid serums are capturing shelf space previously held by unregistered kojic acid concentrates in German and French pharmacy channels.
Patient acquisition through Instagram and TikTok dermatology influencers is displacing traditional physician referral networks for initial hyperpigmentation consultations. Aesthetic clinic groups in Dubai, Miami, and Bangkok are reallocating marketing spend toward platform-native content creators with demonstrated conversion metrics. This channel shift is most visible in the 25-34 demographic segment, where peer-validated before-and-after imagery drives appointment booking behavior ahead of clinical credentialing.
Hyperpigmentation Disorder Treatment Market Segmentation
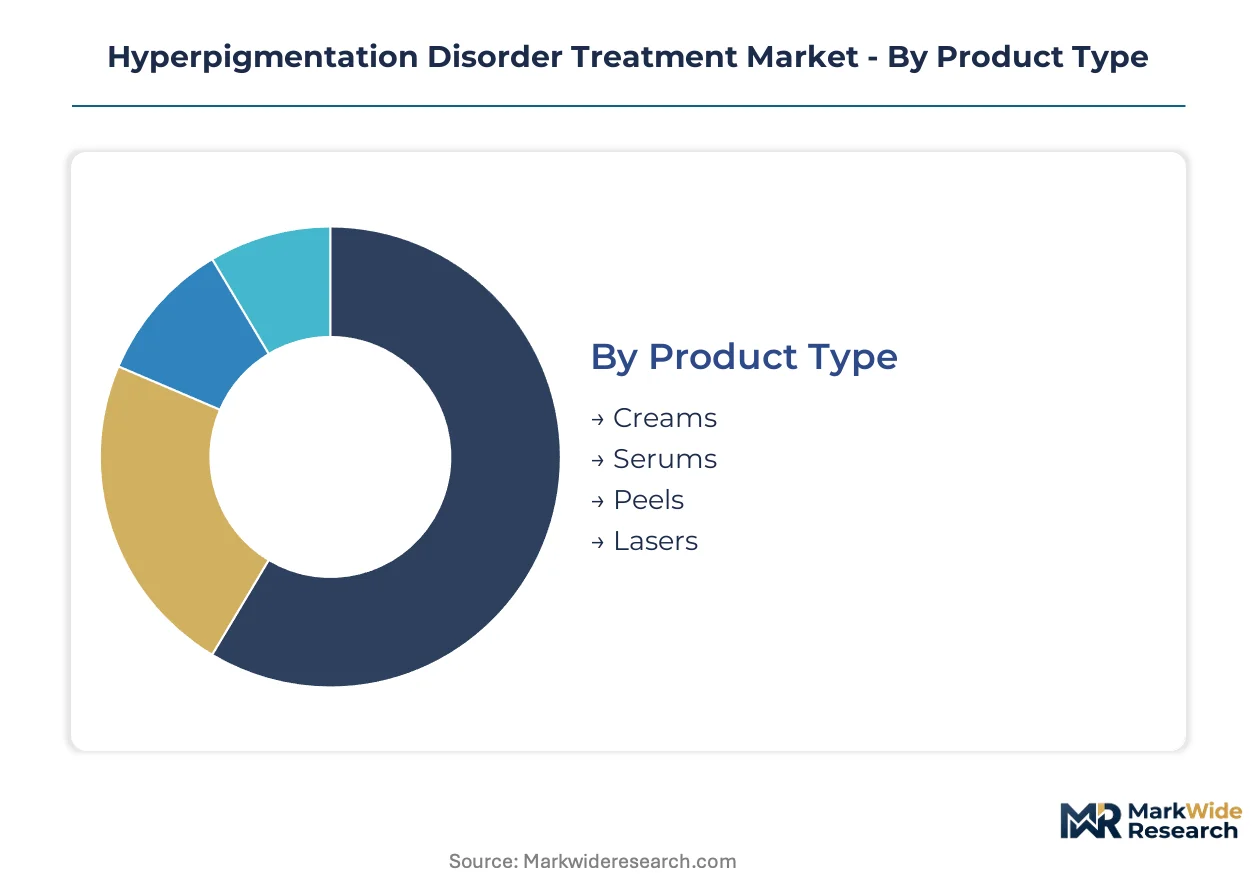
Channel configuration determines margin capture in hyperpigmentation treatment. Clinic-administered modalities command premium pricing while direct-to-consumer topicals drive volume through recurring replenishment cycles.
Product Type:
Creams and serums flow through pharmacy and e-commerce channels, while lasers and peels remain captive to clinic procurement. Each product category carries distinct margin structures tied to distribution control.
- Creams:Emulsion-based formulations with 2-4% hydroquinone or botanical alternatives dominate pharmacy shelf space. Demand clusters in South Korean e-commerce channels where K-beauty export infrastructure supports cross-border subscription models.
- Serums:Photostabilized vitamin C complexes and tranexamic acid solutions in aqueous or anhydrous bases. Concentration in direct-to-consumer tele-dermatology platforms bypasses traditional pharmacy intermediaries.
- Peels:Glycolic, salicylic, and TCA formulations span professional-grade clinic protocols to at-home maintenance concentrations. FDA monograph restrictions on acid percentages bifurcate the addressable market.
- Lasers:Fractional CO2, picosecond, and Q-switched platforms. Picosecond technology is displacing IPL installations in premium dermatology practices across Seoul, Los Angeles, and São Paulo.
Creams dominate installed base. Picosecond lasers are where expansion concentrates.
Active Ingredient:
Regulatory status determines channel accessibility and R&D investment allocation. Prescription-grade actives require clinical oversight while cosmetic-grade alternatives exploit direct-to-consumer pathways.
- Hydroquinone:Tyrosinase inhibitor at 2% OTC and 4% prescription thresholds in the United States. FDA NDA requirements for higher concentrations restrict distribution to dermatology practices and compounding pharmacies.
- Kojic Acid:Fungal fermentation-derived melanogenesis suppressant. EPA-monitored environmental discharge from production facilities elevates input cost volatility and constrains domestic manufacturing capacity.
- Vitamin C:L-ascorbic acid and stabilized derivatives including magnesium ascorbyl phosphate. Photostabilized delivery systems extend shelf life and expand e-commerce viability.
- Azelaic Acid:Dicarboxylic acid at 15-20% prescription concentration for melasma indication. REACH-registered grades capture European pharmacy shelf space previously held by unregistered kojic acid concentrates.
Hydroquinone retains prescription dominance. Vitamin C complexes are climbing the fastest.
End User:
Service intensity and capital requirements separate institutional from consumer-facing segments. Clinic networks amortize equipment costs across procedure volume while homecare relies on recurring topical purchases.
- Clinics:Multi-modality aesthetic centers combining laser, peel, and injectable services. Capital equipment refresh cycles accelerate as picosecond platforms displace legacy IPL systems.
- Dermatology Practices:Physician-supervised medical settings with EMR-integrated outcome tracking. State-level licensing variances for laser technician certification create workforce deployment friction.
- Homecare:Direct-to-consumer channel encompassing OTC topicals and at-home peel kits. Instagram and TikTok influencer validation drives appointment booking behavior in the 25-34 demographic.
- Spas:Non-medical aesthetic facilities limited to superficial peels and LED therapy. Regulatory boundaries prevent laser device operation without physician oversight in most jurisdictions.
Dermatology practices anchor procedural revenue. Homecare is where volume expansion concentrates.
Treatment Procedure:
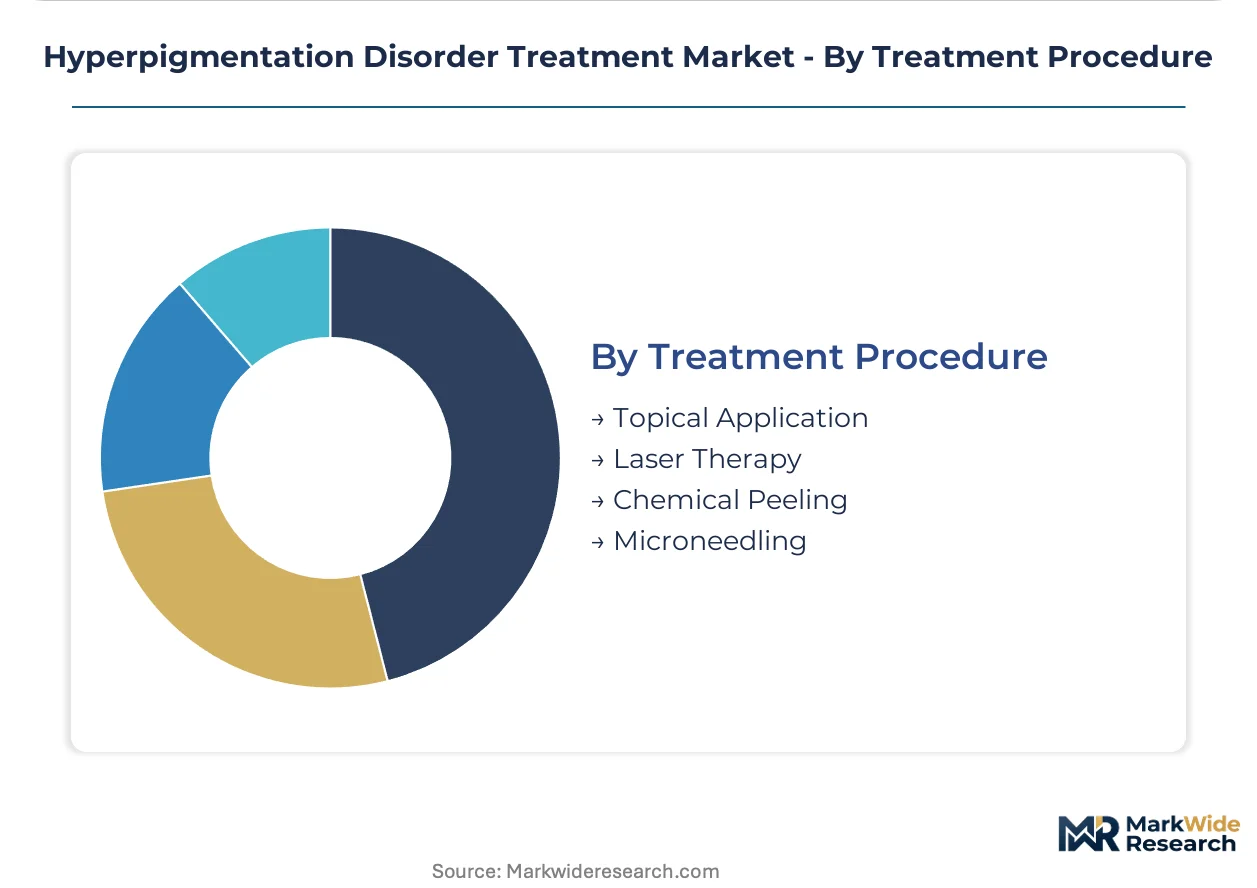
Technical sophistication and operator certification requirements stratify the competitive landscape. Energy-based modalities demand capital investment while topical application scales through formulation chemistry.
- Topical Application:Daily-use creams and serums applied without clinical supervision. CDSCO regulatory harmonization in India accelerates botanical active registration for domestic formulators.
- Laser Therapy:Selective photothermolysis using picosecond, fractional, and Q-switched platforms. Elevated post-inflammatory hyperpigmentation risk in Fitzpatrick Type V-VI skin restricts addressable patient population.
- Chemical Peeling:Controlled epidermal resurfacing using TCA, phenol, and acid combinations. Physician-administered protocols command procedure fees that offset product commoditization.
- Microneedling:Percutaneous collagen induction with or without radiofrequency augmentation. Technology convergence with fractional RF expands single-session efficacy claims.
Topical application sustains volume leadership. Laser therapy is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA scrutiny of hydroquinone concentrations redirects R&D investment toward botanical alternatives across multiple jurisdictions. CE marking under EU MDR bifurcates device manufacturers from topical-only suppliers. K-beauty export infrastructure concentrates demand in South Korea's medical tourism channels.
United States
Dermatology practices in Los Angeles and Miami expand combination laser-peel protocols. FDA caps OTC hydroquinone at 2% while requiring NDA filings for prescription-grade concentrations. California-based aesthetic clinic networks drive capital equipment refresh cycles as picosecond platforms displace legacy IPL systems.
South Korea
Seoul's medical tourism infrastructure generates dual revenue streams for pigmentation correction clinics and domestic manufacturers. MFDS regulatory pathways accelerate botanical active ingredient registration for K-beauty exporters. The Gangnam district anchors premium dermatology practice concentration with demonstrated conversion metrics from platform-native influencers.
Germany
REACH-registered azelaic acid grades capture pharmacy shelf space previously held by unregistered kojic acid concentrates. ECHA safety dossier requirements force reformulation around pre-registered botanical alternatives. Munich and Frankfurt aesthetic clinic clusters concentrate demand for CE-marked picosecond laser platforms.
India
Melasma prevalence in South Asian skin types drives demand for botanical alternatives to hydroquinone. CDSCO regulatory harmonization with ICH guidelines accelerates domestic active ingredient registration. Maharashtra and Karnataka host emerging formulation clusters targeting underpenetrated dermatology markets.
Brazil
São Paulo dermatology practices replace legacy equipment at accelerated depreciation schedules. ANVISA pharmaceutical oversight aligns with international standards for prescription-grade actives. The city's aesthetic clinic networks concentrate procedural revenue for energy-based pigment correction modalities.
Hyperpigmentation Disorder Treatment Market Competitive Landscape
Player mix skews toward integrated dermatology portfolios controlling distribution across European clinics and pharmacies. Concentration is moderate, with three to five entities commanding significant share in device-based segments while topical formulations fragment across consumer goods conglomerates and specialty pharmaceutical divisions. Strategic archetypes include R&D-intensive beauty conglomerates, physician-administered device specialists, and integrated dermatology platform operators. Dominant competitive moves center on photostabilized active delivery system development and CE marking acquisition under EU MDR.
Within the integrated dermatology tier, Galderma S.A. and AbbVie Inc. exemplify platform operators combining device and topical portfolios. L'Oréal S.A. represents the R&D-intensive archetype through concentration in photostabilized formulation science. These three entities anchor distinct competitive vectors: Galderma leverages European clinic-pharmacy distribution control, AbbVie occupies physician-administered laser and energy-based segments through its aesthetics division, and L'Oréal directs investment toward direct-to-consumer serum channels bypassing traditional pharmacy intermediaries.
| Leading Market Players |
|---|
| Galderma S.A. |
| L'Oréal S.A. |
| AbbVie Inc. |
| Obagi Cosmeceuticals LLC |
| Bayer AG |
| Beiersdorf AG |
| Pierre Fabre Group |
| Johnson & Johnson |
| Procter & Gamble Co. |
| Others |
Supply & Pricing Matrix
Capacity utilization at picosecond laser oscillator foundries in Germany, Japan, and the United States directly shapes both component scarcity and price floors for device OEMs, while EPA-monitored kojic acid fermentation constraints in domestic facilities elevate raw material baselines for topical formulators competing on botanical alternatives.
Pricing Analysis
Certification level (FDA-grade versus cosmetic-grade) creates the primary spread between clinic-administered and direct-to-consumer modalities. Three-tier pricing structure across premium, standard, and economy levels stratifies by photostabilization technology and delivery system complexity. Cost compression in OTC serum tiers is intensifying because photostabilized vitamin C complexes extend shelf life and expand e-commerce viability. Homecare segments exhibit highest price sensitivity, while physician-administered laser protocols command inelastic demand through outcome bundling.
Supply Chain Analysis
Strait of Malacca transit underwrites kojic acid feedstock flows from Southeast Asian fermentation facilities to Indian and Chinese formulators. Component manufacturing for picosecond laser platforms concentrates in Germany, Japan, and the United States, while botanical active cultivation feeds from South Korean and Indian agricultural processing. Single-source vulnerability in femtosecond-picosecond oscillator supply creates procurement bottlenecks for device OEMs. Distribution runs through CE-marked European clinic networks, direct-to-consumer tele-dermatology platforms, and K-beauty export channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in this market are inflecting around tele-dermatology subscription infrastructure, where outcome-tracking software integration with legacy EMR systems determines patient retention and recurring revenue capture.
For Market Incumbents: Secure CE marking under EU MDR before notified body certification queues lengthen, locking shelf space in Munich and Frankfurt aesthetic clinic clusters. Backward integration into photostabilized vitamin C complex manufacturing protects margin compression from raw material volatility. Channel control through integrated clinic-pharmacy distribution in Europe defends against direct-to-consumer disintermediation. For New Entrants and Emerging Players: Subscription-based topical replenishment services represent the most penetrable white-space, where incumbents under-serve maintenance-phase patients seeking tele-dermatology convenience. Target Indian domestic formulators leveraging CDSCO regulatory harmonization for botanical active registration against melasma prevalence in South Asian skin types. Go-to-market through Instagram and TikTok influencer validation bypasses traditional physician referral acquisition costs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tele-dermatology platforms with integrated outcome tracking and subscription replenishment mechanics. Long-term viability centers on device-topical hybrid portfolios amortizing capital equipment across procedure volume and maintenance serum sales. Acquisition focus should target notified body-certified device manufacturers or photostabilized formulation specialists. Watch for FDA monograph revisions on hydroquinone concentrations as inflection signal for botanical alternative R&D allocation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR certification unlocks clinic shelf space in Munich and Frankfurt aesthetic clusters. |
| Photostabilization R&D Investment | Extended serum shelf life expands direct-to-consumer addressable market beyond hydroquinone-dependent channels. |
| Tele-Dermatology Platform Launch | Subscription replenishment bypasses pharmacy intermediaries and captures recurring maintenance-phase revenue. |
| Backward Integration into Botanical Actives | In-house production of kojic acid alternatives insulates against EPA-monitored fermentation facility constraints. |
| Hybrid Device-Topical Portfolio | Combination laser-peel protocols with maintenance serums amortize equipment costs across higher patient lifetime value. |
Research Methodology
The analysis maps topical formulations, energy-based devices, and procedural interventions, each validated through dermatology practice administrators, biomedical engineers at laser OEMs, regulatory affairs specialists, and pharmacy procurement managers. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EMA CE marking databases, ClinicalTrials.gov intervention records, and MFDS botanical drug guidance documents. Bottom-up patient volume modeling and top-down market sizing triangulate across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, active ingredient regulatory status, end-user channel configuration, and treatment procedure sophistication. CAGRs derived from procedure volume growth rates, equipment replacement cycles, and serum replenishment frequency assumptions. Industry-specific inputs encompass picosecond laser installed base depreciation schedules and K-beauty export channel expansion trajectories.
Forecasts assume regulatory continuity in FDA hydroquinone monographs, EU REACH framework enforcement, and CDSCO harmonization with ICH guidelines; material policy shifts in these regimes would require re-modeling. Practitioners should keep alternative scenarios live as EPA discharge requirements for kojic acid fermentation and state-level laser technician certification variances evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Global Online Dermatology Consultation Market
Dermatology
Chronic Spontaneous Urticaria Market
Dermatology
Skin Cancer Market
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Microneedling Market
Dermatology
Common Warts Market
Dermatology
Folliculitis Market
Dermatology
Rosacea Treatment Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Global Hirsutism Market
Dermatology
Radiation Dermatitis Market
Dermatology
Cutaneous Squamous Cell Carcinoma Market
Dermatology
Global Dermatology Lasers Market
Dermatology
Saudi Arabia Hair Transplant Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market
Dermatology
Impetigo Treatment Market