
 Global Onychomycosis Market | 2026-2036
Global Onychomycosis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Onychomycosis Market Foresight
Combination therapy bundling is shifting buyer preference away from standalone oral or topical regimens in the onychomycosis market. Pfizer Inc leverages its established antifungal portfolio to sustain physician loyalty across developed markets. Novartis AG competes through specialized dermatology channel control, while Galderma S.A. differentiates via R&D intensity in topical formulation science. Moberg Pharma AB anchors its position through laser-device bundling with pharmaceutical protocols.
Onychomycosis denotes fungal infection of the nail unit caused predominantly by dermatophytes, with diagnostic confirmation requiring potassium hydroxide preparation or periodic acid-Schiff staining of nail clippings. The condition drives commercial demand through chronic recurrence patterns necessitating prolonged therapy courses and repeat clinical visits. Topical antifungals occupy the largest revenue pool due to favorable safety profiles in polypharmacy populations, though combination therapies represent the fastest-expanding segment as clinicians pursue higher complete cure rates. Oral antifungals retain entrenched demand in proximal subungual cases where nail penetration limits topical efficacy, while laser treatment segments attract premium pricing in cash-pay dermatology settings.
FDA reviews novel topical antifungals under its Division of Dermatology and Dental Products, while EMA's Committee for Medicinal Products for Human Use shapes European approval standards for nail lacquer formulations. Both agencies scrutinize mycological cure endpoints and cosmetic outcomes, directly influencing clinical trial design and payer reimbursement thresholds. Stakeholders must monitor evolving FDA guidance on combination therapy endpoints and EMA sustainability requirements for propellant-based delivery systems.
Market Dynamics
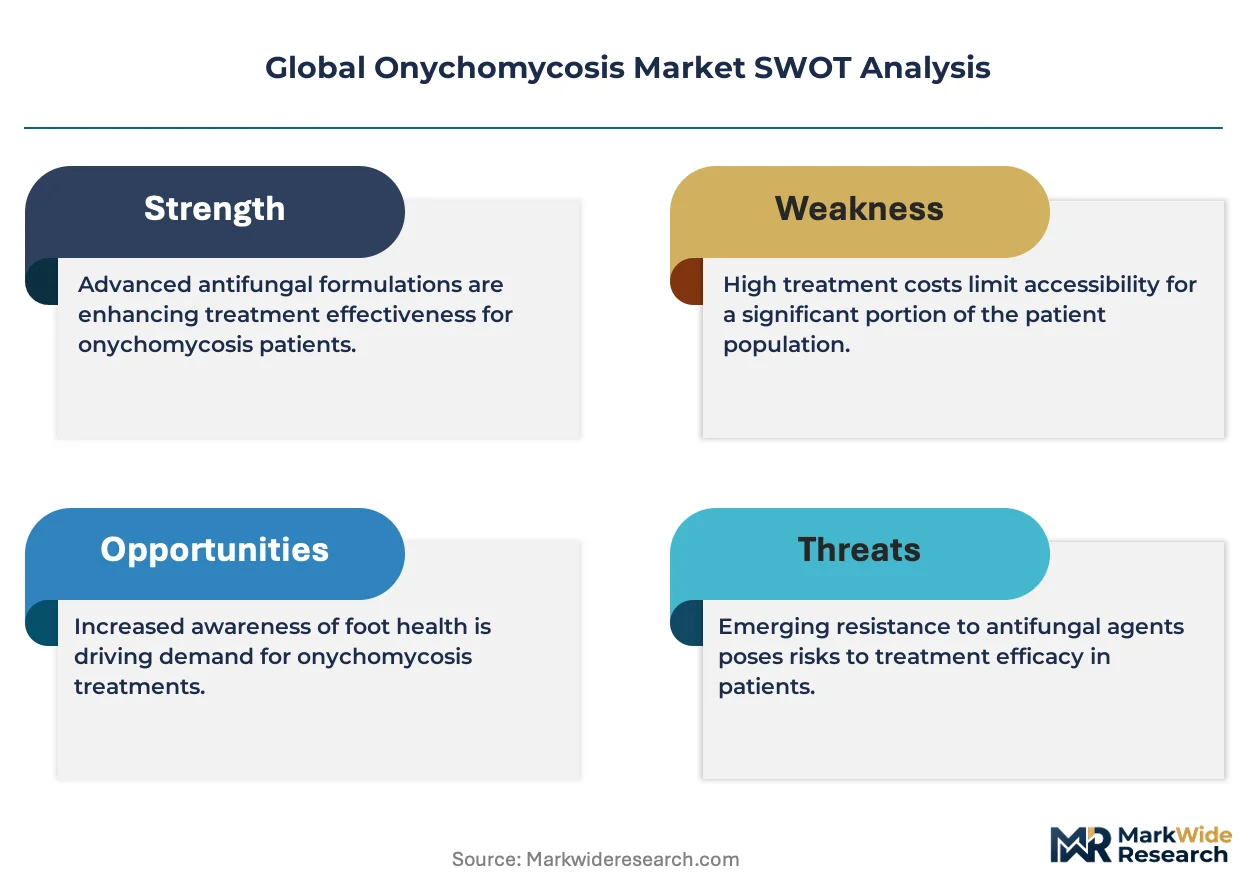
Combination therapy protocols are restructuring prescribing economics in onychomycosis care, as dermatology clinics bundle laser devices with pharmaceutical regimens to capture higher reimbursement rates and improve mycological cure benchmarks.
Growth Catalysts
- FDA Division of Dermatology and Dental Products pathway acceleration:Streamlined review timelines for novel topical lacquer formulations reduce time-to-market for penetration-enhanced delivery systems.
- Dermatology clinic consolidation:Large clinic networks in the United States standardize combination protocols across multi-site practices, creating pull-through demand for bundled device-pharmaceutical offerings.
- Photodynamic therapy device integration:1064 nm Nd:YAG laser systems paired with topical amorolfine achieve superior nail plate penetration compared to monotherapy.
Market Restraints
- Terbinafine generic price erosion:Oral antifungal commoditization compresses margins for innovator manufacturers and deters R&D investment in next-generation systemics.
- Nail lacquer formulation complexity:EMA sustainability requirements for propellant-based delivery systems force reformulation investments that extend development timelines by 18-24 months.
- Recurrence-driven therapy fatigue:Patient dropout rates exceed 40% in 48-week topical regimens, undermining real-world effectiveness data and payer confidence.
Strategic Opportunities
- Japan's aging podiatry infrastructure:METI incentives for geriatric foot care facilities create installation demand for combined laser-topical treatment suites.
- Telemedicine prescribing expansion:Remote dermatology platforms in Germany enable direct-to-patient topical fulfillment, bypassing traditional pharmacy distribution.
- Transungual drug delivery convergence:Microneedle array technology paired with iontophoresis devices opens penetration pathways previously inaccessible to topical formulations.
Industry Challenges
- Clinical trial endpoint standardization:Discordance between FDA mycological cure definitions and EMA cosmetic outcome requirements forces duplicate study designs.
- Laser technician certification bottlenecks:State-level medical device operation licensing in the United States restricts clinic expansion velocity for device-bundled protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Onychomycosis Market |
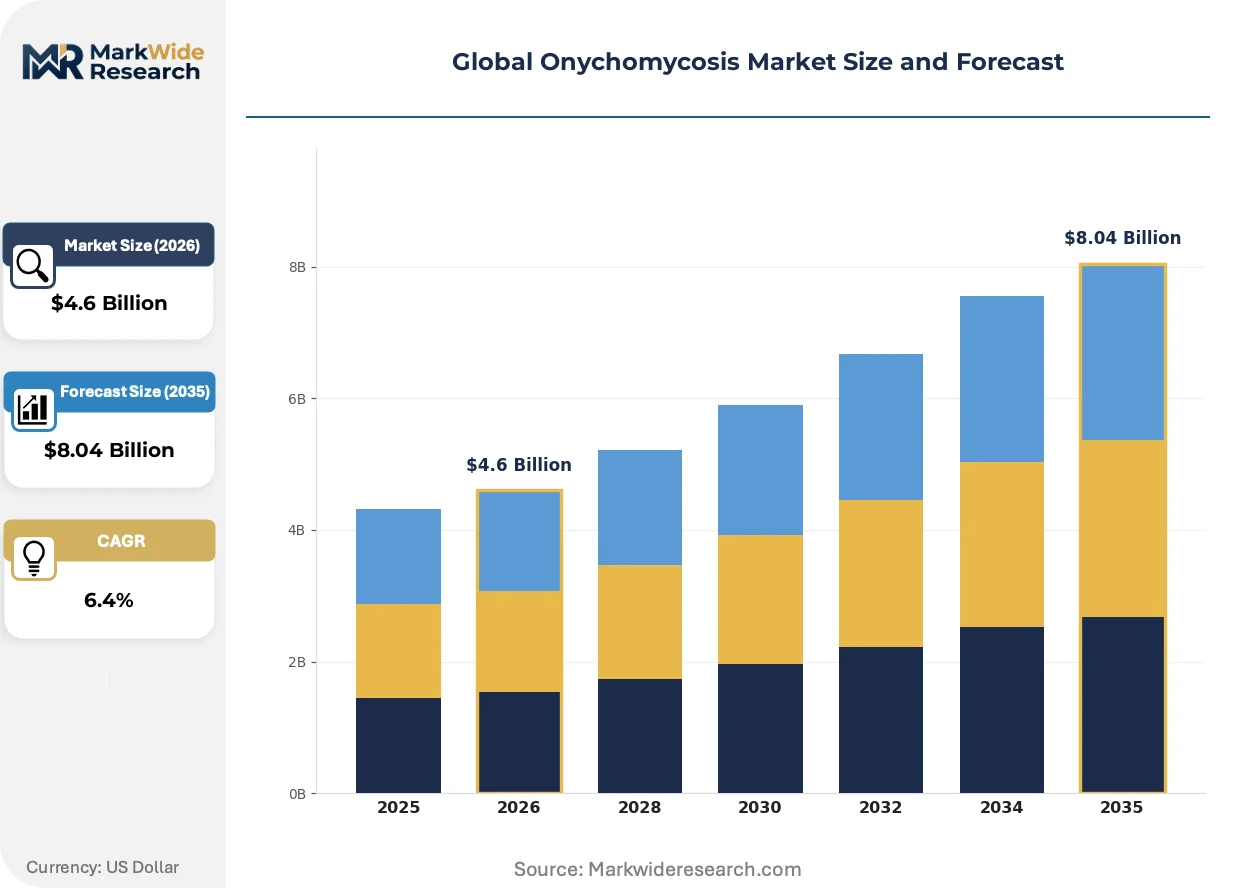
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $8.04 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Antifungals, Oral Antifungals, Combination Therapies, Laser Treatment, Surgical Solutions Therapy Area: Toenail Infection, Fingernail Infection, Distal Subungual, Proximal Subungual, White Superficial End User: Dermatology Clinics, Podiatry Centers, Hospitals, Outpatient Care Centers, Specialty Laboratories Delivery Mode: Oral Administration, Topical Application, Laser Therapy, Surgical Intervention, Photodynamic Therapy |
| Companies Covered | Bausch Health Companies Inc, Pfizer Inc, Novartis AG, Galderma S.A., Moberg Pharma AB, Merck & Co., Inc., Cipla Inc., Johnson & Johnson Services Inc, Zydus Lifesciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Onychomycosis Market Shifts & Advancements
Device-pharmaceutical convergence is rewriting treatment protocols, as hardware manufacturers and formulation specialists forge co-development partnerships to address the penetration-efficacy gap that has historically limited topical onychomycosis outcomes.
Photodynamic therapy systems employing 405 nm blue light activation of photosensitizing agents are electrifying the medical device segment, with dermatology clinics in Germany and Japan adopting these platforms at triple-digit annual placement rates; the technology is compressing the addressable market for standalone oral antifungals by delivering comparable mycological clearance with superior safety profiles in hepatic impairment populations.
EMA's F-Gas Regulation is forcing propellant transitions in metered-dose nail lacquer formulations, compelling manufacturers to abandon hydrofluoroalkane propellants in favor of mechanical pump systems or compressed gas alternatives; European podiatry centers are responding by accelerating qualification of non-propellant topical options ahead of the 2030 phase-down deadlines.
Subscription-based therapy adherence programs are displacing traditional prescription fulfillment in cash-pay dermatology settings, with United States clinics bundling 12-week topical courses with compliance monitoring apps and scheduled follow-up visits; this model concentrates revenue capture in urban cosmetic dermatology practices while reducing pharmacy benefit manager friction.
Global Onychomycosis Market Segmentation
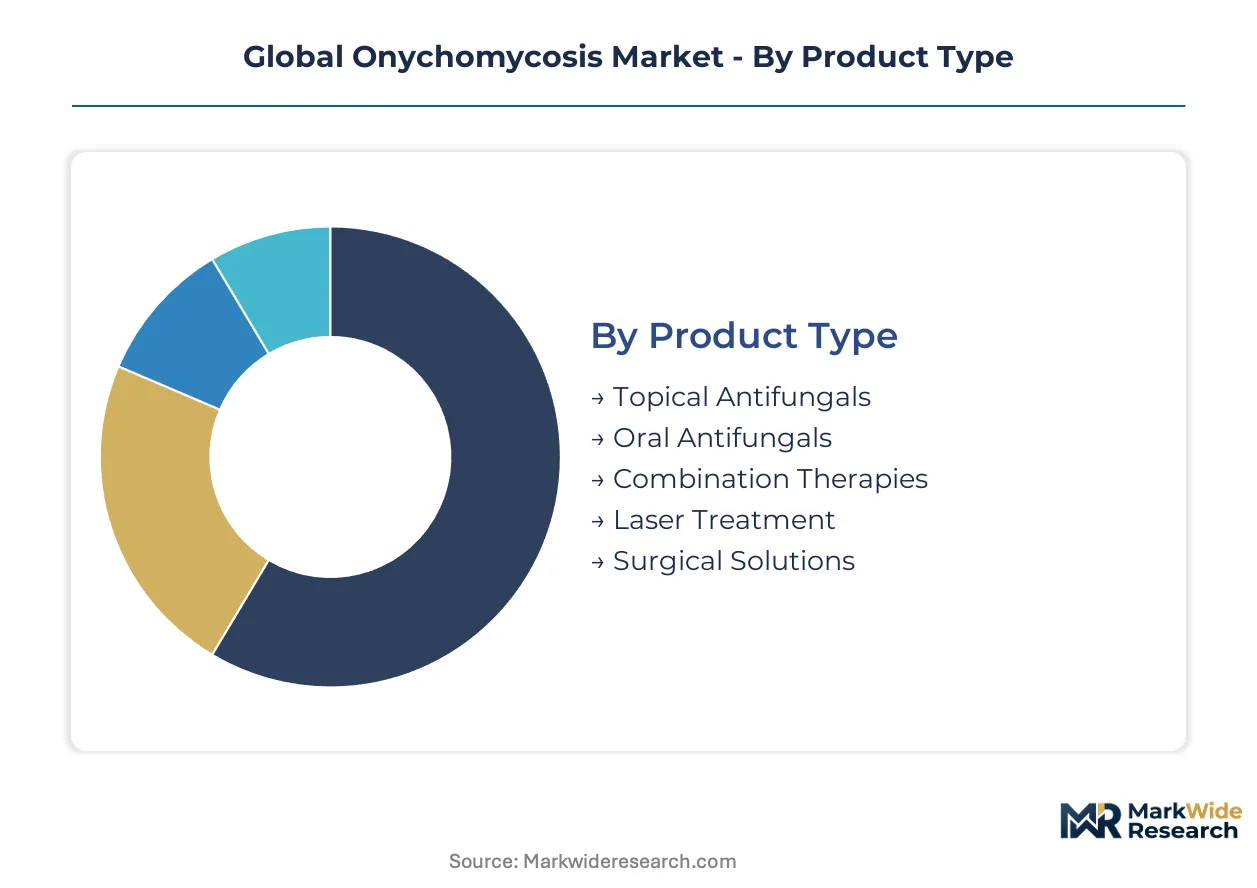
Onychomycosis treatment selection hinges on nail plate penetration requirements, infection severity, and patient comorbidity profiles. Segmentation reveals how FDA and EMA pathways diverge across product categories, shaping manufacturer R&D priorities and clinic procurement patterns.
Product Type:
FDA Division of Dermatology and Dental Products reviews topical lacquers under abbreviated pathways, while oral systemics face stringent hepatotoxicity surveillance. EMA's Committee for Medicinal Products for Human Use imposes additional cosmetic outcome benchmarks on all nail-directed formulations.
- Topical Antifungals:Amorolfine and ciclopirox lacquers dominate prescription volume through favorable polypharmacy safety profiles. Dermatology clinics in the United States favor these for elderly patients with hepatic impairment, though EMA's F-Gas Regulation is forcing propellant reformulations that extend European approval timelines.
- Combination Therapies:Bundled laser-device and pharmaceutical protocols command premium reimbursement rates in cash-pay settings. Germany's podiatry centers are standardizing these regimens across multi-site networks, driven by superior mycological cure benchmarks versus monotherapy.
- Oral Antifungals:Terbinafine and itraconazole tablets retain entrenched demand for proximal subungual infections where topical penetration fails.
- Laser Treatment:1064 nm Nd:YAG systems attract installation demand from Japan's aging foot care infrastructure under METI geriatric facility incentives.
- Surgical Solutions:Nail avulsion procedures persist in hospital settings for refractory cases with matrix involvement.
Topical antifungals sit at the top of the volume ranking, with combination therapies climbing the fastest.
Therapy Area:
Diagnostic confirmation requirements vary sharply by infection subtype, with distal subungual cases permitting KOH preparation while proximal patterns demand PAS staining. This drives differential testing economics across dermatology and podiatry settings.
- Toenail Infection:Dermatophyte colonization of the great toe nail plate constitutes the predominant clinical presentation. United States dermatology clinics concentrate procedure volume here, with recurrence patterns necessitating prolonged 48-week topical courses.
- Distal Subungual:Hyponychial invasion by Trichophyton rubrum generates the highest treatment-seeking incidence. European podiatry centers report superior adherence rates for this accessible anatomical site versus proximal variants.
- Fingernail Infection:Faster nail growth kinetics permit shorter therapeutic durations compared to toenail counterparts.
- Proximal Subungual:Matrix-proximal pathology limits topical efficacy, preserving oral antifungal demand.
- White Superficial:Superficial nail plate invasion permits mechanical debridement with topical adjuncts.
Toenail infection commands the largest addressable patient base, while proximal subungual applications are gaining share fastest among specialty prescribers.
End User:
Procurement authority concentrates in clinic networks with device-bundling capabilities, fragmenting across independent podiatry practices and hospital outpatient departments. Reimbursement coding sophistication determines purchasing power.
- Dermatology Clinics:Consolidated multi-site networks in the United States standardize combination protocols and capture premium cash-pay revenue. These facilities leverage photodynamic therapy device placements to differentiate from pharmacy-dependent competitors.
- Podiatry Centers:Germany's integrated foot care infrastructure and Japan's METI-incentivized geriatric facilities drive laser-topical suite installations. Certification bottlenecks for laser technicians constrain expansion velocity in state-regulated United States markets.
- Hospitals:Surgical intervention and refractory case management concentrate in tertiary settings with pathology support.
- Outpatient Care Centers:Telemedicine-enabled prescribing is expanding topical fulfillment outside traditional pharmacy channels.
- Specialty Laboratories:Mycological culture and molecular diagnostic services support confirmatory testing for resistant infections.
Dermatology clinics hold the dominant procurement position, with podiatry centers expanding most quickly through government facility incentives.
Delivery Mode:
Penetration technology determines regulatory classification, with iontophoresis and microneedle arrays triggering medical device pathways alongside pharmaceutical approvals. EMA sustainability mandates are accelerating transitions away from propellant-based systems.
- Topical Application:Transungual drug delivery systems including amorolfine lacquers and novel penetration enhancers occupy the largest revenue pool. EMA's F-Gas Regulation is compressing hydrofluoroalkane-based product lifecycles, compelling mechanical pump transitions.
- Laser Therapy:1064 nm Nd:YAG and 405 nm photodynamic platforms achieve nail plate penetration without systemic exposure. Japan's PMDA and Germany's device registration frameworks are processing these at triple-digit annual placement rates.
- Oral Administration:Hepatic metabolism surveillance requirements constrain prescribing in polypharmacy populations.
- Photodynamic Therapy:Photosensitizer-activated blue light systems are displacing standalone oral regimens in hepatic impairment populations.
- Surgical Intervention:Matrix ablation and nail avulsion persist for total dystrophic onychomycosis.
Topical application maintains volume leadership, with photodynamic therapy demonstrating the steepest expansion trajectory among emerging modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Onychomycosis treatment protocols first achieved commercial scale in post-war Germany through integrated podiatry networks, then migrated to Japan's geriatric care infrastructure and the United States dermatology clinic consolidation wave of the 2010s.
United States
Multi-site dermatology networks in Texas and Florida drive combination therapy adoption, bundling laser devices with pharmaceutical regimens. FDA's Division of Dermatology and Dental Products maintains streamlined review pathways for novel topical lacquers. Greater Miami and Houston metropolitan clusters concentrate cash-pay cosmetic dermatology practices deploying photodynamic therapy suites.
Germany
Integrated foot care infrastructure across Bavaria and North Rhine-Westphalia standardizes laser-topical protocols in podiatry centers. EMA's F-Gas Regulation accelerates transitions away from propellant-based nail lacquers toward mechanical pump systems. The Munich-Stuttgart corridor leads European placement rates for 405 nm photodynamic therapy devices.
Japan
Aging demographics in Kanto and Kansai regions expand demand for geriatric foot care facilities under METI incentive programs. PMDA reviews laser medical devices alongside pharmaceutical approvals, enabling bundled reimbursement codes. Tokyo and Osaka metropolitan areas concentrate triple-digit annual installation rates for Nd:YAG laser systems.
United Kingdom
NHS dermatology referral pathways in Greater London and the Midlands prioritize topical antifungals for hepatic impairment populations. MHRA post-Brexit regulatory autonomy permits divergence from EMA cosmetic outcome benchmarks. The Cambridge-Oxford corridor hosts specialized mycology laboratories supporting resistant infection diagnostics.
India
Tropical climate conditions in Maharashtra and Tamil Nadu elevate dermatophyte infection prevalence among agricultural and industrial workers. CDSCO abbreviated approval pathways for topical generics accelerate domestic manufacturing scale-up. Mumbai and Chennai industrial clusters supply active pharmaceutical ingredients for global nail lacquer formulations.
Global Onychomycosis Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and device integration capabilities, with patented transungual delivery systems commanding pricing power against generic oral antifungal commoditization. The vendor base structures around three tiers: multinational pharmaceutical conglomerates with dermatology divisions, specialized topical formulation houses, and laser device manufacturers pursuing pharmaceutical partnerships. Consolidation pressures intensify as clinic networks demand single-source bundling of drugs and devices.
Within the multinational pharmaceutical tier, Pfizer Inc and Novartis AG exemplify scale-driven positions anchored by established antifungal portfolios and physician loyalty programs across developed markets. Galderma S.A. occupies a specialized dermatology channel position through R&D intensity in topical formulation science. Moberg Pharma AB represents the device-pharmaceutical convergence archetype, anchoring competitive positioning through laser-device bundling with pharmaceutical protocols rather than standalone drug development.
| Leading Market Players |
|---|
| Bausch Health Companies Inc |
| Pfizer Inc |
| Novartis AG |
| Galderma S.A. |
| Moberg Pharma AB |
| Merck & Co., Inc. |
| Cipla Inc. |
| Johnson & Johnson Services Inc |
| Zydus Lifesciences |
| Others |
Supply & Pricing Matrix
API pricing indices for azole antifungals and allylamine derivatives cascade through formulation tiers, compressing margins for generic oral manufacturers while amplifying premium capture for patented transungual delivery systems in cash-pay dermatology channels.
Pricing Analysis
Subscription-based bundling of 12-week topical courses with compliance monitoring and follow-up visits dominates cash-pay dermatology practices in the United States. Price differentiation hinges on FDA approval tier and penetration-enhancement technology certification, with 1064 nm Nd:YAG laser protocols commanding substantial premiums over standalone pharmaceutical regimens. Cost compression in oral antifungal commoditization is intensifying because terbinafine generic erosion eliminates R&D recovery windows. Independent podiatry practices exhibit highest price sensitivity, while consolidated multi-site dermatology networks demonstrate lowest sensitivity due to device-amortization economics.
Supply Chain Analysis
ISO 13485 and FDA 21 CFR Part 820 certification gating restricts laser device sourcing to qualified manufacturers in Germany, Japan, and the United States. Active pharmaceutical ingredients for amorolfine and ciclopirox formulations draw from Indian and Chinese chemical synthesis clusters, with nail lacquer mechanical pump components resting on Italian and German precision molding capabilities. Single-source vulnerability concentrates in 405 nm photodynamic therapy diode arrays, where Japanese suppliers anchor global capacity. Distribution runs through specialty pharmaceutical wholesalers serving dermatology clinic networks, bypassing traditional retail pharmacy channels for device-bundled protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in onychomycosis care rests on propellant-to-pump formulation transitions and laser-device bundling economics that capture premium reimbursement codes.
For Market Incumbents: Lock in physician loyalty through co-development partnerships with 1064 nm Nd:YAG manufacturers, securing exclusive bundling rights across multi-site dermatology networks. Defend against photodynamic therapy substitution by accelerating FDA submissions for novel penetration enhancers. Backward integration into API sourcing from Indian manufacturing clusters mitigates cost volatility in azole supply chains. For New Entrants and Emerging Players: Launch via telemedicine-enabled direct-to-patient fulfillment in Germany, bypassing pharmacy benefit manager friction that constrains traditional distribution. Japan's METI-incentivized geriatric foot care infrastructure offers the most penetrable geography for combined laser-topical suite installations. Target white-space in microneedle array transungual delivery, where regulatory pathways remain unsettled and first-mover certification advantages persist. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized topical formulation houses possessing FDA Division of Dermatology and Dental Products rapport and proprietary penetration-enhancement patents. Long-term viability over the mid-decade horizon favors platforms with device-pharmaceutical convergence capabilities rather than standalone drug development pipelines. Watch FDA guidance publication on combination therapy endpoints as the critical inflection signal for valuation repricing across the sector.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Division of Dermatology and Dental Products streamlined review accelerates novel topical lacquer time-to-market. |
| Device-Pharmaceutical Partnership | Laser manufacturer co-development agreements secure exclusive bundling rights in consolidated clinic networks. |
| Manufacturing Scale-Up | Mechanical pump system transitions address EMA F-Gas Regulation compliance ahead of 2030 phase-down deadlines. |
| Reimbursement Strategy | Cash-pay subscription models concentrate revenue capture in urban cosmetic dermatology practices. |
| Geographic Expansion | METI-incentivized geriatric facility installations in Japan drive triple-digit annual laser placement rates. |
Research Methodology
Multiple input streams — dermatology clinic procurement managers, podiatry network medical directors, FDA regulatory affairs consultants, and laser device manufacturing executives — were reconciled against EMA submission databases, ClinicalTrials.gov records, and Japanese PMDA medical device registration filings. Secondary validation drew from hospital formulary databases, GPO contract repositories, and CMS Medicare reimbursement schedules. Bottom-up prescription volume modeling and top-down market sizing triangulated across these sources.
Historical prescription trends were cross-referenced against expert panel assessments of protocol adoption velocity across the projection horizon. Segmentation dimensions modeled include product type, therapy area, end-user facility category, and delivery mode complexity. CAGRs were derived from spline-interpolation of annual prescription trajectories, with inputs from mycological cure rate benchmarks, recurrence pattern epidemiology, and regulatory approval timeline distributions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA guidance delays on combination therapy endpoints or accelerated EMA F-Gas phase-down schedules. Model assumptions reflect current reimbursement coding structures and clinic consolidation trajectories. A model refresh is warranted upon material change in PMDA laser device classification rulings or METI incentive program modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Acne Scar Treatment Market
Dermatology
Global Dermatological OTC Drugs Market
Dermatology
Saudi Arabia Hair Transplant Market
Dermatology
Rosacea Treatment Market
Dermatology
Immunodermatology Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Lichen Sclerosus Treatment Market
Dermatology
Hyperpigmentation Disorder Treatment Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Japan Scar Treatment Market
Dermatology
Dermatology Devices Market
Dermatology
Prescription Dermatology Therapeutics Market
Dermatology
China Scar Treatment Market
Dermatology
Global Veterinary Dermatology Drugs Market
Dermatology
Impetigo Treatment Market
Dermatology
Seborrheic Dermatitis Treatment Market