
 Lentigo Maligna Melanoma Therapeutic Market | 2026-2036
Lentigo Maligna Melanoma Therapeutic Market Size, Share, and Industry Trends Forecast 2026-2036
Lentigo Maligna Melanoma Therapeutic Market Insights
Project finance for late-stage immuno-oncology trials is narrowing the field of viable competitors to those with balance-sheet depth or partnership networks. Merck & Co., Inc. leverages its checkpoint inhibitor infrastructure to sustain clinical leadership in melanoma combinations. Bristol-Myers Squibb Company anchors its position through broad PD-1 franchise economics that compete across multiple skin cancer indications. F. Hoffmann-La Roche AG differentiates via diagnostic-therapeutic bundling that controls patient identification and treatment sequencing.
Lentigo maligna melanoma therapeutics encompass interventions targeting the radial growth phase of melanoma in situ on sun-damaged skin, typically requiring histologic confirmation of atypical melanocyte proliferation beyond the dermoepidermal junction. These therapies aim to eradicate malignant clones while preserving cosmetic and functional outcomes in facial and head-neck presentations where surgical margins challenge tissue conservation. Immunotherapy leads the therapy area segment as checkpoint inhibitors displace extensive surgical excision in medically complex patients. Targeted therapies within the product type category concentrate margin pools where BRAF-mutant subpopulations permit precision pricing. Diagnostic tools represent the fastest-growing segment as reflectance confocal microscopy and gene expression profiling reduce unnecessary biopsies.
FDA breakthrough therapy designation and EMA PRIME eligibility compress regulatory timelines for novel melanoma agents, while the IRA's Medicare price negotiation provisions reshape US commercialization assumptions for established therapies. The EU MDR elevates clinical evidence requirements for diagnostic tools used in melanoma staging, redirecting R&D budgets toward prospective validation studies. Stakeholders must monitor how CMS coverage determinations for topical immunomodulators interact with dermatology practice economics to decide whether to prioritize office-based administration or hospital outpatient models.
Market Dynamics
Checkpoint inhibitor infrastructure is concentrating clinical investment around combination regimens that displace surgical excision for facial and head-neck lentigo maligna presentations where tissue conservation drives patient selection.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Accelerated approval pathways compress development timelines for novel melanoma biologics, enabling earlier commercial access for patients with medically complex lesions.
- Reflectance Confocal Microscopy:Non-invasive diagnostic imaging reduces unnecessary biopsies in dermatology clinics, expanding addressable patient pools for therapeutic intervention.
- Sun-damaged skin demographics:Aging populations in coastal United States and Mediterranean Europe sustain higher incidence screening rates that feed diagnostic and treatment pipelines.
Market Restraints
- Specialized dermatopathology capacity:Histologic confirmation requirements for atypical melanocyte proliferation strain trained diagnostician availability in community practice settings.
- Medicare price negotiation provisions:The IRA's established therapy provisions reshape US commercialization assumptions and compress margin pools for mature checkpoint inhibitors.
- Surgical margin standards:Conservative excision protocols for facial preservation limit addressable lesion size and complexity eligible for pharmacologic monotherapy.
Strategic Opportunities
- Diagnostic-therapeutic bundling:Gene expression profiling integration with treatment sequencing controls patient identification and captures margin pools across the care pathway.
- Topical immunomodulator administration models:CMS coverage determinations for office-based delivery create channel differentiation opportunities against hospital outpatient settings.
- EU MDR clinical evidence requirements:Elevated validation standards for melanoma staging tools redirect competitor R&D budgets toward prospective studies that advantage prepared entrants.
Industry Challenges
- Immuno-oncology trial design complexity:Late-stage combination studies require balance-sheet depth or partnership networks that narrow viable sponsor pools.
- Cosmetic outcome documentation:Functional preservation metrics in facial presentations demand specialized endpoint validation that prolongs regulatory submission preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lentigo Maligna Melanoma Therapeutic Market |
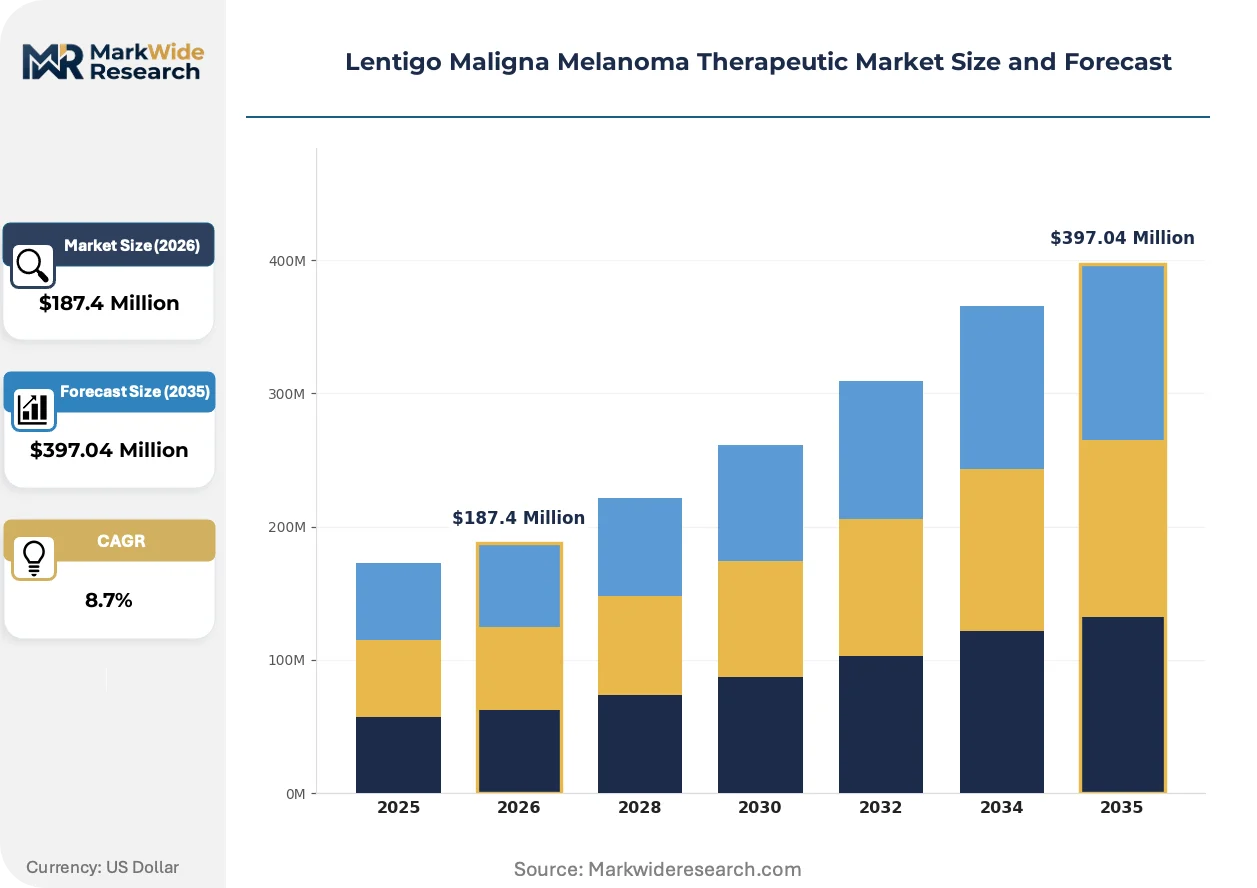
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Surgery, Immunotherapy, Radiation Therapy, Chemotherapy Product Type: Topical Agents, Targeted Therapies, Diagnostic Tools, Biologics End User: Oncologists, Dermatologists, Hospitals, Research Institutions Administration Route: Topical, Intravenous, Subcutaneous, Oral |
| Companies Covered | Merck & Co., Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche AG, Novartis AG, Pfizer Inc., AstraZeneca plc, Amgen Inc., Eisai Co., Ltd., Regeneron Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lentigo Maligna Melanoma Therapeutic Market Trends and Innovations
Non-surgical intervention modalities are reshaping patient selection criteria and reimbursement frameworks across early-stage melanoma management, with technology convergence compressing traditional diagnostic-to-treatment timelines.
Reflectance confocal microscopy is migrating from academic referral centers into community dermatology practice as hardware costs decline and image interpretation training expands. Mid-sized clinic networks in Florida and California are adopting the technology at accelerating pace to reduce biopsy referral volumes. The diagnostic modality is migrating from specialized academic settings into routine community practice, compressing time-to-diagnosis intervals and expanding eligible patient capture for therapeutic intervention.
The EU Medical Device Regulation elevates clinical evidence requirements for melanoma staging and monitoring tools, forcing manufacturers to redirect R&D budgets toward prospective validation studies. Diagnostic companies face compressed timelines for technical documentation renewal that advantage larger players with established quality management systems. In vitro diagnostic segments serving the lentigo maligna pathway are most affected, with several firms accelerating PMCF study recruitment to maintain CE marking validity.
Patients with sun-damaged skin on facial and head-neck areas are prioritizing tissue-sparing outcomes over traditional excision protocols, shifting provider selection toward dermatology clinics advertising cosmetic preservation metrics. This preference rotation favors practices investing in non-invasive diagnostic confirmation and topical immunomodulator administration capabilities. The behavioral shift is most visible in United States coastal markets and German urban centers where patient information access and aesthetic concern concentration intersect.
Lentigo Maligna Melanoma Therapeutic Market Segmentation
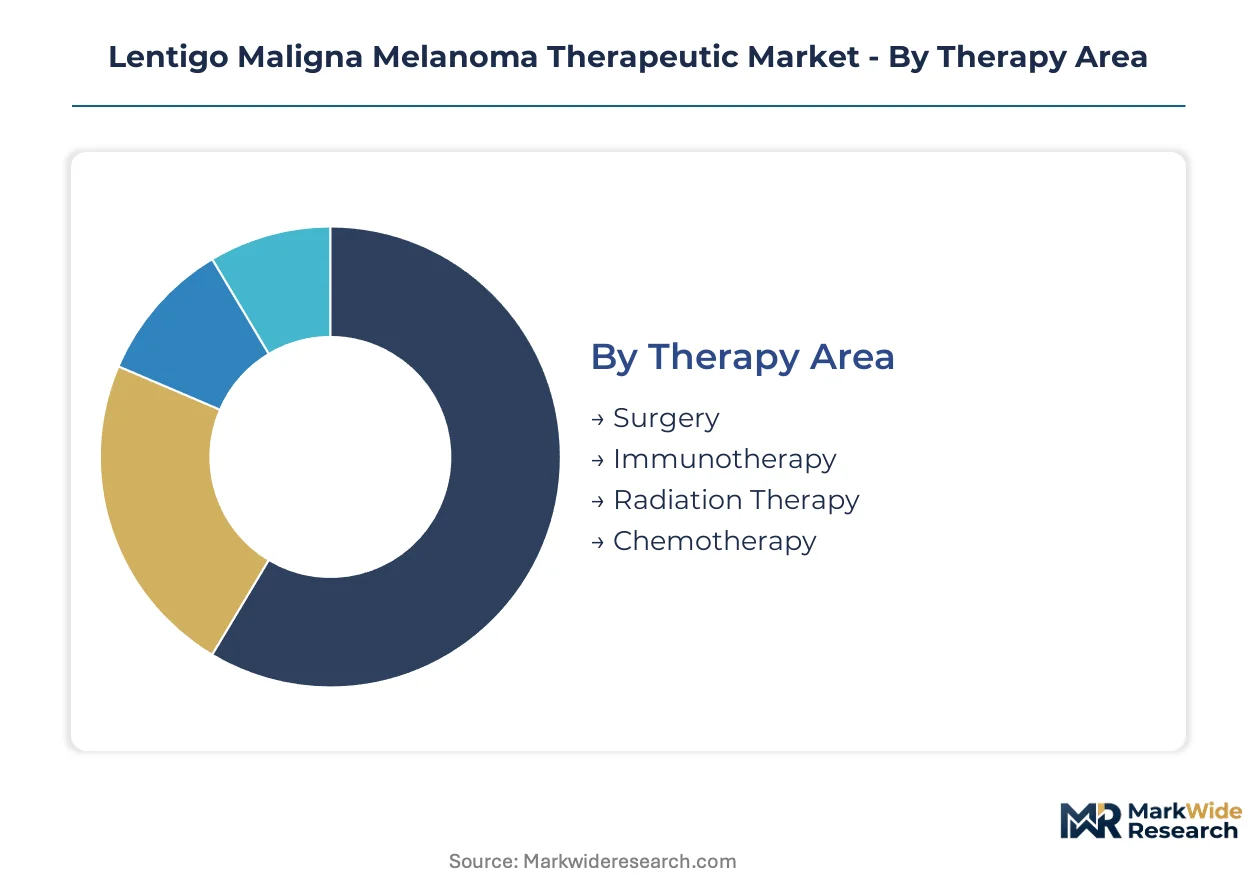
Therapeutic segmentation in lentigo maligna melanoma reveals distinct margin profiles and patient selection criteria across intervention modalities. Cycle times vary dramatically: diagnostic tools refresh every 18-24 months with hardware upgrades, while surgical protocols stabilize over 5-7 years.
Therapy Area:
Cycle times diverge sharply — immunotherapy protocols iterate quarterly with biomarker refinements, whereas radiation equipment depreciates over decade-long horizons.
- Surgery:Wide local excision with staged margin control remains the histologic gold standard for lesions with confirmed dermal invasion. Demand concentrates in German academic medical centers where Mohs micrographic surgery preserves facial tissue in head-neck presentations, constrained by specialized dermatopathologist availability.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 axes demonstrate complete histologic clearance in select in-situ presentations. United States coastal dermatology clinics are expanding intralesional administration for medically complex patients, driven by Medicare coverage determinations for office-based delivery.
- Radiation Therapy:Superficial orthovoltage and electronic brachytherapy serve as salvage modalities for surgical contraindications.
- Chemotherapy:Systemic cytotoxic regimens retain niche utility in metastatic progression scenarios.
Surgery dominates installed base. Immunotherapy is where expansion concentrates.
Product Type:
Cost tiers stratify sharply — biologics command premium pricing against commoditized topical formulations.
- Topical Agents:Imiquimod and 5-fluorouracil formulations target superficial malignant clones with cytokine-mediated immune activation. Florida dermatology networks prioritize these for elderly patients with multiple actinic lesions, balancing clearance rates against extended treatment durations.
- Biologics:Monoclonal antibodies and checkpoint inhibitors require cold-chain logistics and infusion infrastructure. German hospital outpatient departments capture margin pools through bundled reimbursement for combination regimens in advanced presentations.
- Targeted Therapies:BRAF/MEK inhibitor combinations address mutant subpopulations with precision dosing protocols.
- Diagnostic Tools:Reflectance confocal microscopy and gene expression profiling reduce unnecessary biopsies.
Biologics anchor revenue concentration. Diagnostic tools are climbing the fastest.
End User:
Customer types fragment across referral intensity and reimbursement capture models.
- Dermatologists:Office-based practitioners control patient identification and initial therapeutic selection for early-stage lesions. California clinic networks are integrating confocal microscopy to retain biopsy revenue, shaped by commercial payer preferences for site-of-care optimization.
- Hospitals:Academic centers manage complex presentations requiring multidisciplinary coordination. These institutions capture margin pools through infusion center economics and clinical trial enrollment in the United States.
- Oncologists:Medical oncologists assume care coordination for metastatic progression or combination protocols.
- Research Institutions:Academic sites drive biomarker discovery and novel agent validation.
Dermatologists dominate patient volume. Hospitals concentrate where case complexity escalates.
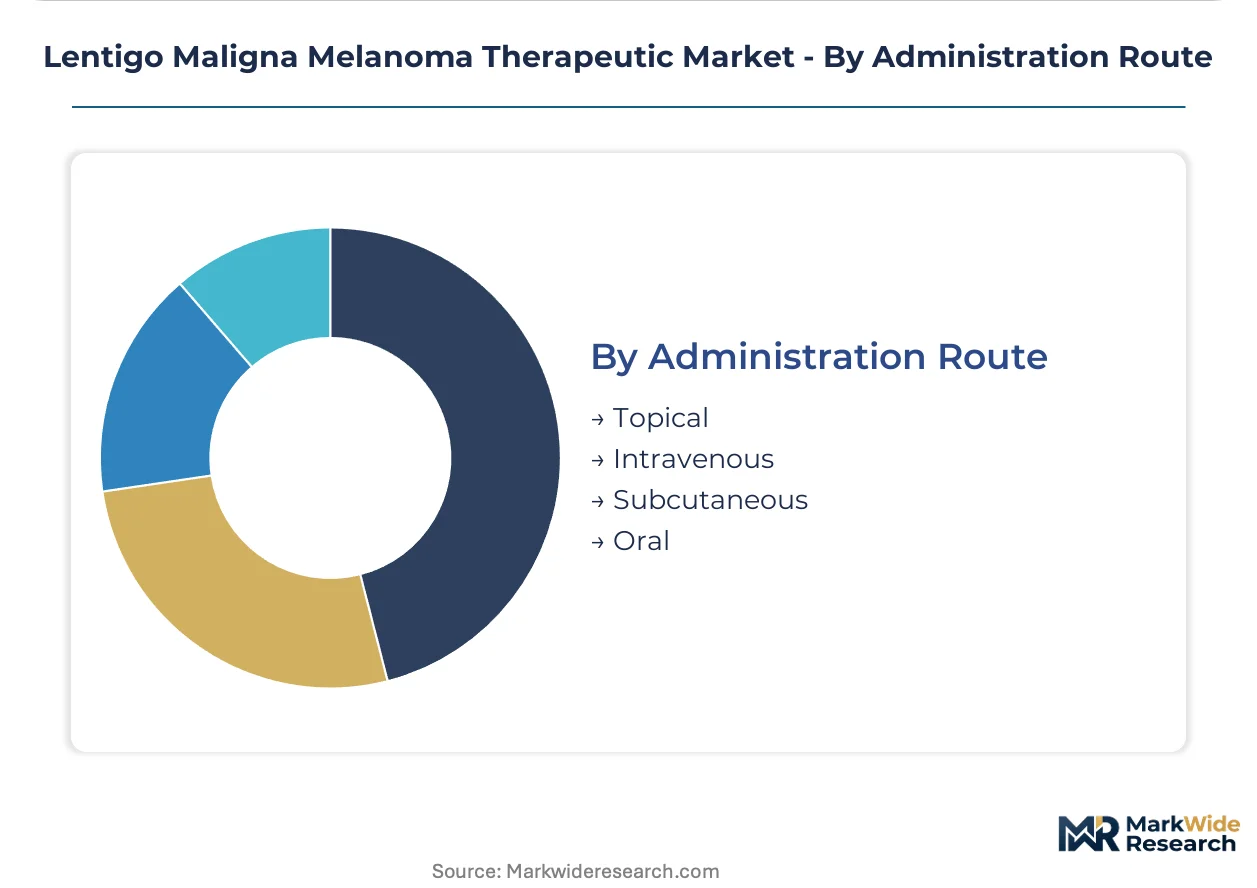
Administration Route:
Supply concentration varies by delivery infrastructure requirements.
- Intravenous:Infusion-dependent biologics require hospital outpatient or ambulatory surgery center certification. United States payers are tightening site-of-care policies that favor hospital-based administration for high-cost agents.
- Topical:Patient-administered formulations eliminate facility fees and expand addressable geography to community practice. German statutory health insurance reimburses these preferentially for elderly populations with transportation barriers.
- Subcutaneous:Self-injection protocols are emerging for maintenance regimens.
- Oral:Targeted therapy tablets enable home-based administration with monitoring requirements.
Intravenous anchors biologic delivery. Topical administration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where Medicare reimbursement for intralesional immunotherapy exceeds German statutory health insurance rates by substantial margins. Coastal dermatology networks in Florida and California capture premium economics through office-based administration models. European markets compress margins through reference pricing mechanisms while sustaining volume through broader screening protocols.
United States
FDA breakthrough therapy designation accelerates checkpoint inhibitor approvals for facial lentigo maligna presentations where tissue conservation drives patient preference. The IRA's Medicare price negotiation provisions reshape commercialization assumptions for mature PD-1 inhibitors. Miami and Los Angeles clinic networks integrate reflectance confocal microscopy to reduce biopsy referrals and retain diagnostic revenue.
Germany
Mohs micrographic surgery demand concentrates in academic medical centers where specialized dermatopathologists preserve facial tissue in head-neck lesions. EMA PRIME eligibility compresses regulatory timelines for novel melanoma biologics entering European markets. Bavarian university hospitals anchor combination regimen development through clinical trial infrastructure and statutory insurance reimbursement pathways.
United Kingdom
NHS England's specialized commissioning frameworks concentrate complex melanoma cases in designated tertiary centers with multidisciplinary coordination capabilities. NICE technology appraisals establish cost-effectiveness thresholds that filter market access for premium biologics. London teaching hospitals drive gene expression profiling adoption through integrated diagnostic-therapeutic pathways.
Japan
PMDA's sakigake designation system accelerates melanoma biologic approvals for elderly populations with sun-damaged facial skin. METI's healthcare export initiatives promote diagnostic imaging technology developed for domestic dermatology networks. Osaka and Tokyo academic centers lead reflectance confocal microscopy validation studies for regulatory submission packages.
Australia
TGA's priority review pathway compresses timelines for melanoma agents addressing high ultraviolet exposure populations. Medicare Benefits Schedule revisions for topical immunomodulators reshape dermatology practice economics toward office-based administration. Sydney and Melbourne melanoma institutes anchor translational research linking diagnostic imaging to therapeutic selection protocols.
Lentigo Maligna Melanoma Therapeutic Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream where diagnostic-therapeutic bundling creates margin capture opportunities. Consolidation pressures intensify as late-stage immuno-oncology trials require balance-sheet depth that narrows viable sponsor pools to established pharmaceutical groups. Two strategic archetypes dominate: checkpoint inhibitor franchise holders leveraging clinical infrastructure across skin cancer indications, and diagnostic-therapeutic bundlers controlling patient identification and treatment sequencing. Competitive moves concentrate on diagnostic imaging partnerships and site-of-care administration models that secure reimbursement capture.
Among checkpoint inhibitor specialists, Merck & Co., Inc., Bristol-Myers Squibb Company, and F. Hoffmann-La Roche AG occupy positions reflecting distinct strategic orientations toward melanoma combination development. Merck exemplifies the PD-1 infrastructure archetype with clinical leadership sustained through biomarker-refined protocols. Bristol-Myers Squibb represents broad immuno-oncology franchise economics competing across multiple skin cancer indications. Roche anchors diagnostic-therapeutic integration through control of patient identification technologies and treatment sequencing decisions. Novartis AG and Pfizer Inc. sit within the targeted therapy tier where BRAF-mutant subpopulations permit precision pricing and narrower addressable populations.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche AG |
| Novartis AG |
| Pfizer Inc. |
| AstraZeneca plc |
| Amgen Inc. |
| Eisai Co., Ltd. |
| Regeneron Pharmaceuticals, Inc. |
| Others |
Pricing and Supply Chain Analysis
Air freight corridors linking Swiss biologics manufacturing hubs to United States coastal dermatology networks impose cost premiums that concentrate pricing power among checkpoint inhibitor franchise holders while compressing margins for topical formulation distributors serving community clinics.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate biologic procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA breakthrough therapy designation status and cold-chain certification tier. Cost compression in the topical agent tier intensifies because German statutory health insurance reimbursement rates undercut United States Medicare margins. Hospital outpatient departments exhibit lowest price sensitivity due to bundled reimbursement capture, while community dermatology clinics face acute sensitivity to facility fee differentials.
Supply Chain Analysis
Tariff exposure between Switzerland and the United States dominates supply chain risk assessment for monoclonal antibody distribution. Manufacturing concentrates in Switzerland, Massachusetts, and Singapore, drawing from recombinant protein production platforms, single-use bioreactor systems, and temperature-controlled packaging materials. Single-source vulnerability in fill-finish capacity feeds from three CDMO networks serving melanoma biologics. Distribution runs through specialty pharmacy channels with hub-and-spoke cold-chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward United States coastal dermatology networks as clinic consolidation in Florida and California concentrates procurement volume among fewer decision-makers.
For Market Incumbents: Build diagnostic-therapeutic bundling moats that lock in patient identification and treatment sequencing decisions. Incorporate reflectance confocal microscopy partnerships to defend against emerging diagnostic-agnostic specialists. Expand intralesional administration capacity in Medicare Advantage-heavy geographies to preempt site-of-care policy shifts. For New Entrants and Emerging Players: Pursue topical immunomodulator white-space in Australian and Japanese markets where TGA and PMDA pathways compress approval timelines. Target elderly patient segments with transportation barriers in German statutory insurance regions. Deploy direct-to-dermatology sales models bypassing hospital outpatient gatekeepers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diagnostic imaging platform specialists with EU MDR-compliant quality management systems. Long-term viability hinges on gene expression profiling integration with therapeutic selection protocols. Acquisition targets should demonstrate prospective validation study completion and CE marking renewal momentum. Watch FDA coverage determinations for office-based immunotherapy administration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Bundling | Roche's control of patient identification technologies secures margin capture across the care pathway. |
| Office-Based Administration Expansion | CMS coverage determinations for intralesional delivery reshape dermatology practice economics toward clinic retention. |
| EU MDR Compliance Investment | Prospective validation studies for melanoma staging tools advantage prepared diagnostic entrants against delayed competitors. |
| Checkpoint Infrastrucure Leverage | Merck's PD-1 platform economics sustain clinical leadership through biomarker-refined protocol iterations. |
| Regional Manufacturing Footprint | Bavarian university hospital partnerships anchor German combination regimen development through statutory reimbursement pathways. |
Research Methodology
A spread of perspectives from dermatology clinic operators, hospital formulary directors, payer access specialists, and diagnostic platform engineers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA breakthrough therapy designations, EMA PRIME eligibility records, ClinicalTrials.gov melanoma protocol registrations, and CMS Medicare coverage determinations. Bottom-up patient flow modeling and top-down therapeutic class sizing were triangulated to anchor volume estimates.
Demand-supply balance dynamics across the analysis window were assessed through therapy area segmentation, product type tiering, end-user channel economics, and administration route infrastructure requirements. CAGRs were derived from patient incidence projections, screening rate assumptions, and reimbursement pathway evolution. Forecast inputs incorporated IRA Medicare price negotiation provisions, EU MDR technical documentation timelines, and reflectance confocal microscopy hardware cost curves.
Sensitivities concentrate around FDA coverage determination timing for topical immunomodulators and EMA PRIME eligibility compression for novel melanoma biologics. Forecasts reflect documented assumptions about patient preference shifts toward tissue-sparing outcomes and diagnostic-therapeutic bundling adoption rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Microdermabrasion Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Skin Cancer Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Dermabrasion Market
Dermatology
Saudi Arabia Hair Transplant Market
Dermatology
Europe Scar Treatment Market
Dermatology
Acne Vulgaris Market
Dermatology
Australia Skin Laser Market
Dermatology
Dermatology Devices Market
Dermatology
Folliculitis Market
Dermatology
Scleroderma Treatment Market
Dermatology
Erythema Treatment Market
Dermatology
Seborrheic Keratosis Market
Dermatology
Acne Vulgaris Treatment Market
Dermatology
Global Hirsutism Market