
 Psoriasis Treatment Market | 2026-2036
Psoriasis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Psoriasis Treatment Market Intelligence
The specialized expertise of immunologists and dermatologists in biologic drug administration is bifurcating the provider landscape. This creates a division between general practitioners and specialty clinics. AbbVie leverages its extensive portfolio in immunology to maintain a significant market presence. Novartis competes through its development pipeline of novel kinase inhibitors and biologics, targeting specific patient subpopulations.
Psoriasis treatment involves therapeutic interventions designed to manage a chronic autoimmune inflammatory skin disease by targeting specific immune pathways, such as TNF-alpha or interleukins. Its primary purpose is to reduce inflammation, clear skin lesions, and improve patient quality of life. Biologics represent the highest value product type, driven by their efficacy in severe cases. Within therapy areas, plaque psoriasis treatment commands the largest share, while topical therapies serve as a foundational approach for milder forms of the condition.
Regulatory frameworks from the FDA in the United States and the EMA in Europe dictate stringent clinical trial requirements for new drug approvals. These agencies, along with Japan's PMDA, influence market access and post-market surveillance protocols. Payers and providers are increasingly scrutinizing the cost-effectiveness of these therapies. Stakeholders must now focus on demonstrating long-term safety and comparative effectiveness to secure favorable reimbursement policies.
Market Dynamics
The expansion of biologic therapies targeting specific immune pathways like interleukins is the central force shaping the psoriasis treatment market. This technological shift is creating a division between specialty clinics and general practitioners while escalating cost-containment pressures from payers.
Growth Catalysts
- Advanced Biologic Efficacy:High efficacy of interleukin inhibitors for severe plaque psoriasis expands the patient population treatable beyond traditional topical therapies.
- Biosimilar Approval Pathways:Regulatory frameworks from the FDA and EMA for biosimilars improve access and introduce competition against high-cost originator biologics.
- Patient Advocacy Impact:Advocacy in the United States and Germany highlights quality-of-life impacts, encouraging earlier diagnosis and treatment by physicians.
Market Restraints
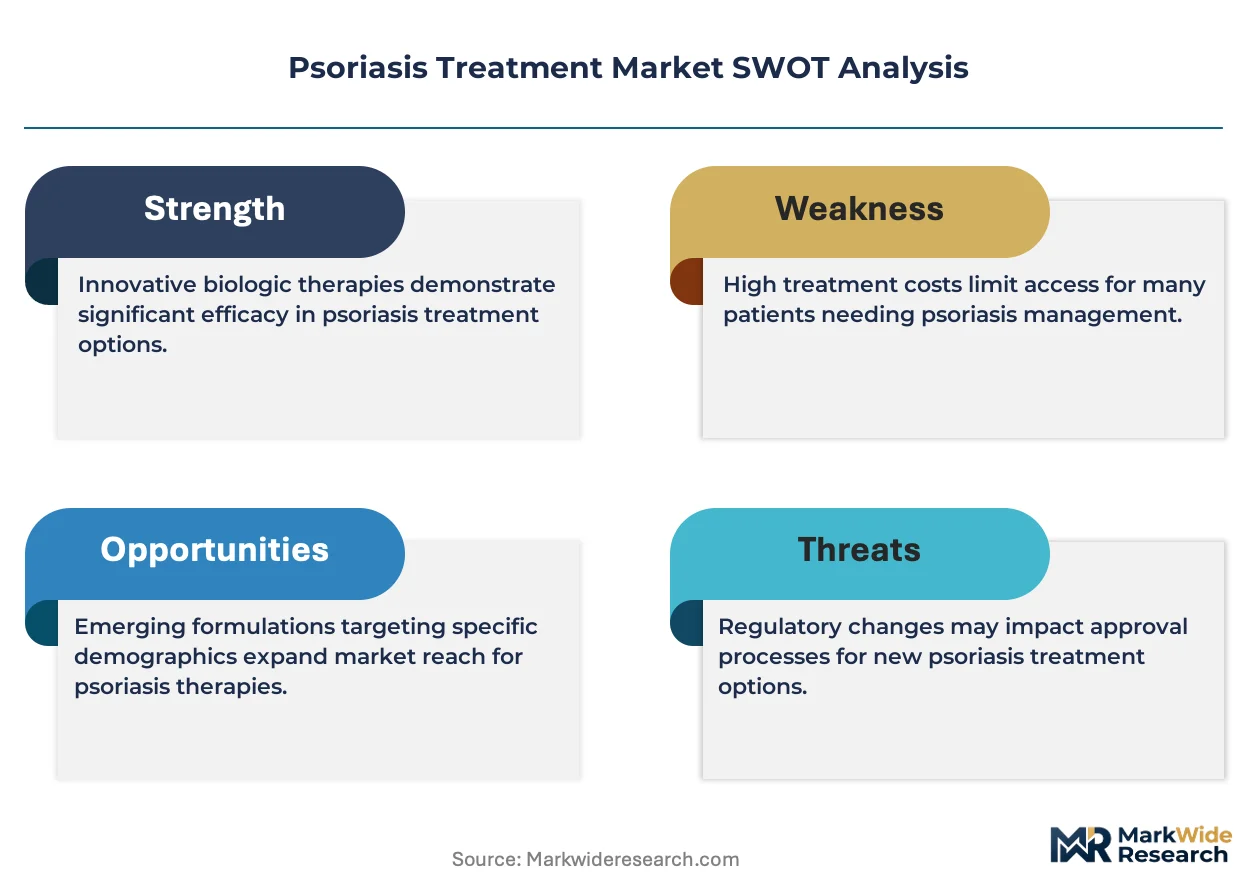
- High Treatment Cost:The expense of biologic drugs limits patient access and invites intense reimbursement scrutiny from public and private healthcare payers.
- Biologic Safety Profiles:Potential long-term side effects of TNF-alpha inhibitors, including infection risk, create prescribing hesitation for certain patient cohorts.
- Complex Drug Administration:The injection or infusion requirement for most biologics presents logistical hurdles for patients compared to simpler oral treatments.
Strategic Opportunities
- Untreated Asian Populations:Expanding access to affordable treatments, including biosimilars, in underpenetrated markets like India and China presents a significant volume opportunity.
- Oral Therapies:Developing effective oral treatments like TYK2 inhibitors offers a convenience advantage over injectables, appealing to a large patient segment.
- Personalized Medicine:Using genetic markers to predict treatment response can optimize therapeutic selection and justify high-cost drug expenditures to payers.
Industry Challenges
- Cost-Effectiveness Hurdles:Demonstrating superior long-term value and comparative effectiveness against cheaper alternatives is a critical challenge for securing favorable reimbursement from payers.
- Clinical Trial Complexity:Enrolling patients for trials targeting less common forms of psoriasis, such as pustular or erythrodermic psoriasis, is difficult and costly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Psoriasis Treatment Market |
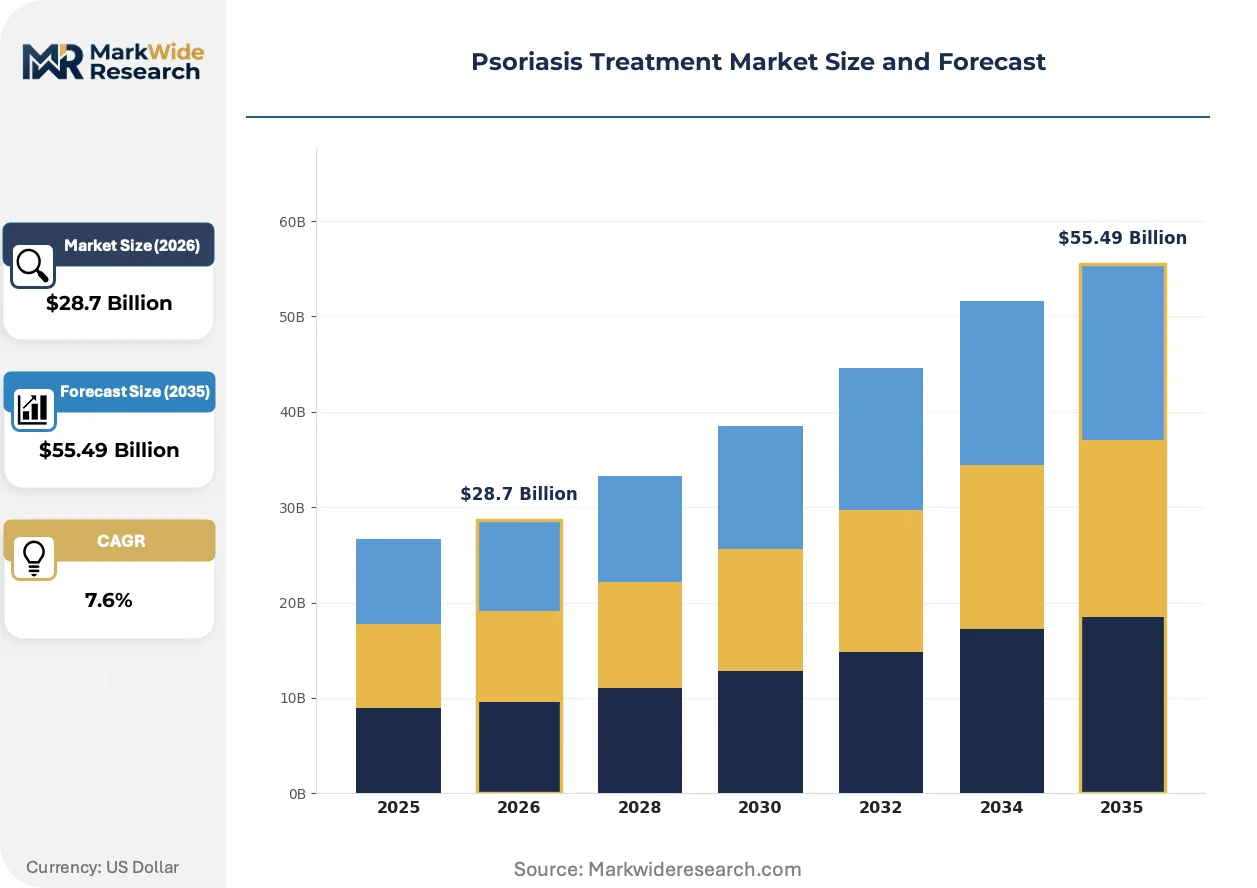
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $55.49 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Therapies, Biologics, Systemic Medications, Phototherapy, Combination Treatments Therapy Area: Plaque Psoriasis, Guttate Psoriasis, Pustular Psoriasis, Erythrodermic Psoriasis, Inverse Psoriasis End User: Dermatology Clinics, Research Institutes, Specialty Hospitals, Outpatient Centers, Pharmacy Chains Delivery Mode: Oral, Injectable, Topical, Phototherapeutic, Intravenous |
| Companies Covered | Amgen, LEO Pharma, AbbVie, UCB, Eli Lilly and Company, Novartis, Pfizer, Sun Pharmaceutical, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Psoriasis Treatment Market Strategic Shifts & Innovations
A pronounced shift toward patient-centric care models and precision medicine is redefining therapeutic strategies. This evolution prioritizes not just lesion clearance but also long-term safety, convenience, and quality of life, influencing both drug development and delivery.
Oral small molecules, such as TYK2 inhibitors, provide a new therapeutic mechanism by targeting intracellular signaling pathways. Patients and physicians seeking to avoid injectable biologics are driving adoption of these convenient, at-home treatments. The availability of a potent oral option is fragmenting the severe psoriasis treatment market, which was previously consolidated around injectable TNF-alpha and interleukin inhibitors.
Regulatory initiatives like the European Medicines Agency's PRIME scheme are accelerating the development of innovative psoriasis therapies. This framework provides enhanced scientific and regulatory support for medicines targeting high unmet needs. Consequently, developers of novel biologics for rare psoriatic conditions gain a faster route to market access in Europe, influencing clinical trial strategies.
Patient preference is decisively moving toward self-administered subcutaneous injections and oral medications, away from clinic-based intravenous infusions. This shift impacts the service model of dermatology clinics and standalone infusion centers, reducing their role in routine drug administration. This trend is most prominent in the United States and Canada, where patient convenience and healthcare system costs are major considerations.
Psoriasis Treatment Market Segmentation
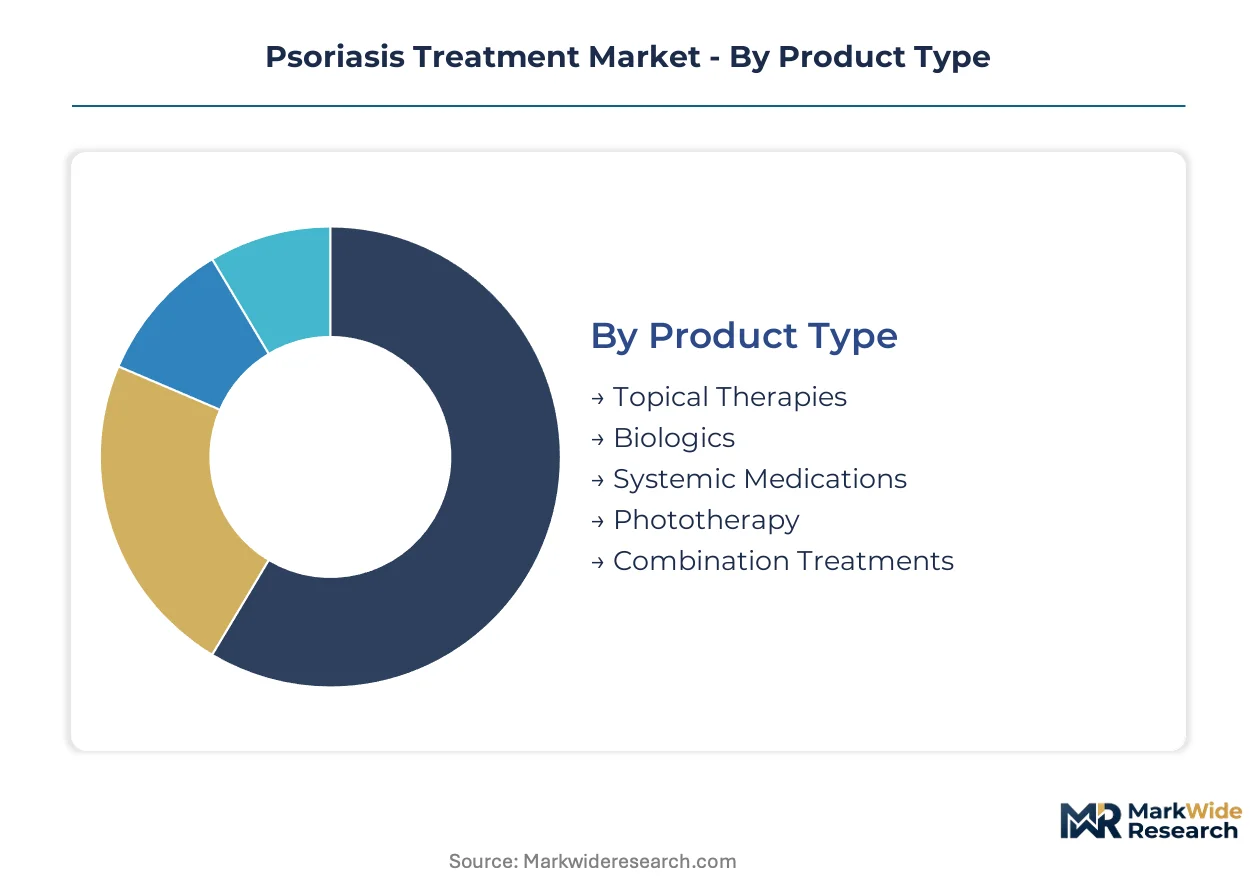
Understanding the varied segments within the psoriasis treatment market is essential for identifying specific growth vectors and patient needs. Each category represents distinct approaches to managing this chronic condition, influencing product development and market access strategies.
Product Type:
The distribution of psoriasis treatments varies significantly across different patient access points, reflecting product characteristics and administration requirements.
- Topical Therapies:These formulations, including corticosteroids and vitamin D analogs, are applied directly to the skin to reduce inflammation and slow skin cell growth. They serve as a foundational approach for milder forms of psoriasis, often prescribed by general practitioners.
- Biologics:These advanced protein-based drugs target specific immune pathways, such as TNF-alpha or interleukins, to suppress inflammation. Biologics represent the highest value product type, primarily administered in dermatology clinics or specialty hospitals for severe cases due to their efficacy and administration complexity.
- Systemic Medications:Oral drugs like methotrexate and cyclosporine work throughout the body to control psoriasis symptoms. These are typically prescribed for moderate to severe cases when topical treatments are insufficient.
- Phototherapy:This treatment involves exposing the skin to ultraviolet light under medical supervision. Phototherapy is administered in specialized clinics or hospital settings, often as a standalone therapy or in combination with other treatments.
- Combination Treatments:This approach involves using two or more different types of therapies simultaneously or sequentially to achieve better disease control. These regimens are tailored to individual patient needs, often overseen by dermatologists.
By volume, Topical Therapies lead the market. By growth pace, Biologics are expanding most quickly.
Therapy Area:
The range of therapeutic targets addresses distinct clinical presentations and disease severities, guiding specialized treatment protocols.
- Plaque Psoriasis:Characterized by raised, red patches covered with silvery scales, this is the most common form of psoriasis, accounting for the largest share of treatment demand. Treatment strategies often involve a step-wise approach from topical to systemic and biologic therapies.
- Guttate Psoriasis:This form presents as small, drop-like lesions, often triggered by a bacterial infection. Guttate psoriasis typically responds well to phototherapy and topical treatments, with systemic options reserved for persistent cases.
- Pustular Psoriasis:A severe and rare form, characterized by pus-filled blisters, often requiring hospitalization and systemic medications. Clinical trials for this less common form face significant enrollment challenges.
- Erythrodermic Psoriasis:This aggressive and potentially life-threatening form involves widespread redness and peeling over large body areas. Erythrodermic psoriasis necessitates intensive medical intervention, often in a hospital setting.
- Inverse Psoriasis:Manifesting in skin folds like the armpits or groin, this type presents as smooth, red lesions without scales. Topical treatments are the primary approach, with careful consideration of irritation in sensitive areas.
Plaque psoriasis accounts for the largest patient cohort, while rare forms like erythrodermic psoriasis require highly specialized interventions.
End User:
The diverse range of healthcare providers dictates where patients receive diagnosis, treatment initiation, and ongoing management for psoriasis.
- Dermatology Clinics:These specialized outpatient facilities serve as the primary centers for diagnosis, treatment planning, and administration of advanced therapies like biologics. Growth is pronounced in these settings due to their expertise in complex skin conditions.
- Research Institutes:These entities focus on advancing the understanding of psoriasis pathogenesis and developing novel therapeutic agents. Research institutes conduct clinical trials for new drugs and contribute to evidence-based treatment guidelines.
- Specialty Hospitals:Equipped to handle severe and complicated cases, these hospitals provide comprehensive care, including inpatient management for conditions like erythrodermic psoriasis. They often administer intravenous biologic therapies.
- Outpatient Centers:These facilities offer a range of services from routine check-ups to minor procedures and prescription fulfillment. Outpatient centers play a role in managing milder cases and providing follow-up care.
- Pharmacy Chains:These retail outlets dispense prescribed medications, including both oral and topical psoriasis treatments. Pharmacy chains also provide patient counseling on medication use and adherence.
Dermatology clinics remain central for routine care, with specialty hospitals managing complex or severe cases.
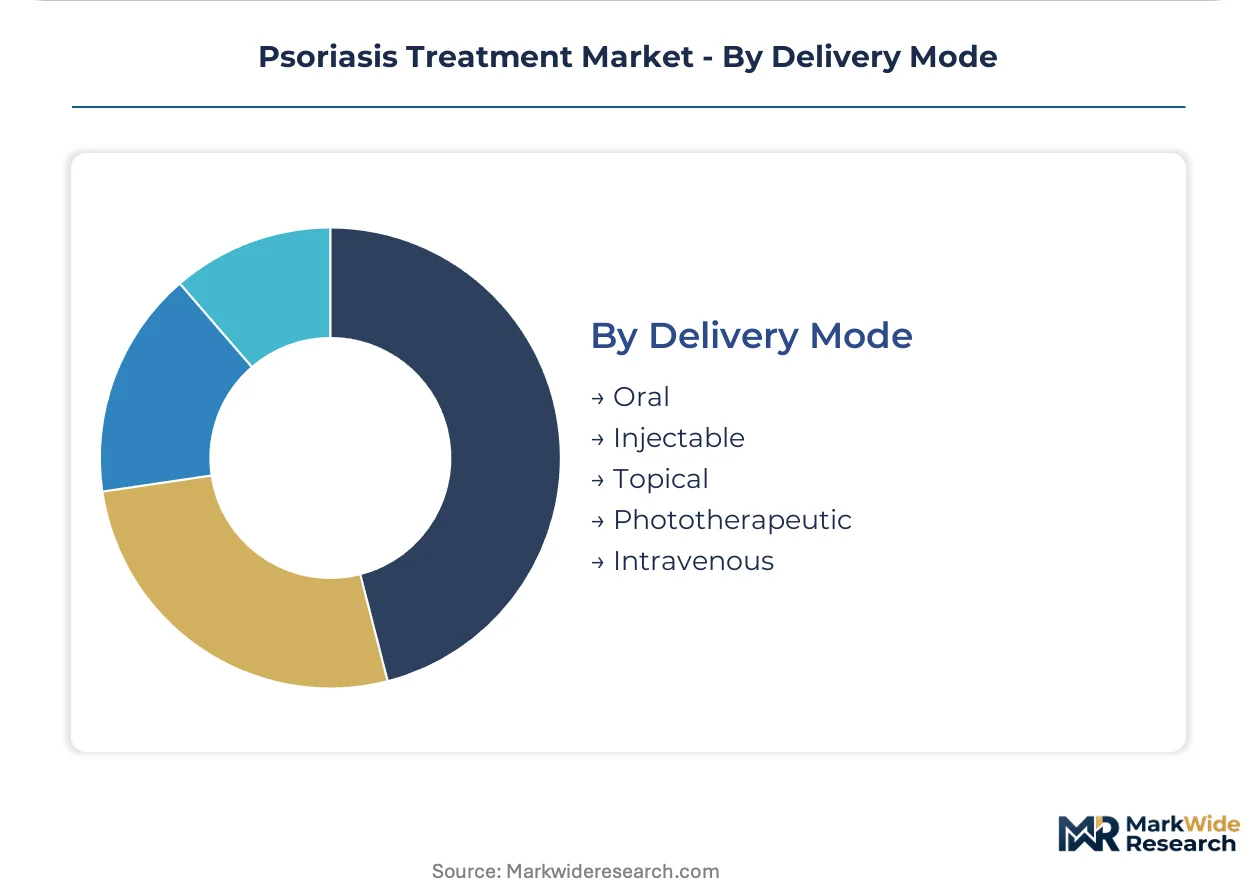
Delivery Mode:
The evolution of drug delivery methods reflects both technological advancement and a pronounced shift toward patient convenience and self-administration.
- Oral:Medications taken by mouth offer significant convenience for patients, eliminating the need for injections or topical application. The development of effective oral treatments like TYK2 inhibitors presents a strategic opportunity for market expansion.
- Injectable:This mode involves subcutaneous injections, commonly used for many biologic therapies, allowing for self-administration by patients at home. Injectable delivery impacts the service model of dermatology clinics by reducing the need for in-clinic administration.
- Topical:Applied directly to the skin, topical treatments are a localized delivery method for milder forms of psoriasis. These include creams, ointments, and gels that address skin lesions directly.
- Phototherapeutic:This method involves exposure to specific wavelengths of ultraviolet light, administered in a clinical setting using specialized equipment. Phototherapeutic delivery requires regular clinic visits for treatment sessions.
- Intravenous:Administered directly into a vein, intravenous delivery is typically reserved for severe cases of psoriasis or for specific biologics requiring hospital-based infusion. This mode presents logistical hurdles for patients compared to other options.
Oral options are gaining traction for their ease of use, while injectable biologics remain critical for systemic efficacy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The psoriasis treatment market exhibits significant regional pricing-power asymmetry. High healthcare expenditure in the United States supports premium biologic therapies, while countries like India emphasize affordable treatment access. This dynamic shapes market entry strategies and reimbursement negotiations across diverse healthcare systems.
United States
The United States experiences strong demand for advanced biologic therapies, driven by high healthcare expenditure and rapid treatment adoption. FDA regulations dictate stringent approval pathways for new psoriasis drugs, influencing market access. Pharmaceutical research hubs in New Jersey and Massachusetts actively develop next-generation oral and injectable treatments.
Germany
German demand for psoriasis treatments benefits from robust patient advocacy and a focus on improving quality of life. The European Medicines Agency (EMA) provides regulatory oversight, including enhanced support through its PRIME scheme. Biotech clusters in Munich and Berlin contribute significantly to the development of novel immunologic drugs.
Japan
Japanese demand for psoriasis treatments is shaped by an aging demographic and a preference for advanced medical solutions. The Pharmaceuticals and Medical Devices Agency (PMDA) sets rigorous standards for drug approval and post-market surveillance. Research institutes in Tokyo and Osaka concentrate on genetic markers for personalized therapeutic selection.
China
Chinese demand presents a significant volume opportunity due to large untreated patient populations and expanding healthcare access. The National Medical Products Administration (NMPA) streamlines approval processes for innovative and biosimilar psoriasis treatments. Pharmaceutical manufacturing centers in Shanghai and Guangdong actively scale up production of affordable biologics.
India
Indian demand for psoriasis treatments is driven by a need for affordable options and rising disease awareness. The Central Drugs Standard Control Organization (CDSCO) supports market entry for biosimilars to enhance patient access. Pharmaceutical clusters in Hyderabad and Ahmedabad are pivotal for the research and manufacturing of generic and biosimilar drugs.
Psoriasis Treatment Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the psoriasis treatment market. The landscape is bifurcated, with established pharmaceutical giants dominating the high-value biologic segment and numerous smaller firms focusing on generic or topical therapies. Strategic archetypes include innovation-driven specialists, diversified healthcare conglomerates, and regional generic manufacturers. Companies primarily engage in strategic partnerships to expand therapeutic pipelines and pursue geographic expansion into underpenetrated markets.
Specialists in immunology, such as AbbVie and Novartis, anchor the market's high-value biologic segment, leveraging extensive R&D capabilities. AbbVie exemplifies a diversified portfolio approach, maintaining a significant market presence across various autoimmune conditions. Novartis, a Swiss-based pharmaceutical company, competes through its development pipeline of novel kinase inhibitors and biologics, targeting specific patient subpopulations. Indian pharmaceutical firm Sun Pharmaceutical represents the growing segment of companies focused on expanding access to affordable therapies, including biosimilars, in emerging markets. These firms collectively shape the market's innovation trajectory and accessibility.
| Leading Market Players |
|---|
| Amgen |
| LEO Pharma |
| AbbVie |
| UCB |
| Eli Lilly and Company |
| Novartis |
| Pfizer |
| Sun Pharmaceutical |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Oral small molecules substituting injectable biologics reshape the psoriasis treatment market's supply geography and pricing economics simultaneously. This shift moves manufacturing from complex biologic facilities towards chemical synthesis plants, impacting cost structures and patient access.
Pricing Analysis
Customization for patient subpopulations and premium pricing for novel biologics define the market's pricing structure. Value-based pricing models are prevalent for advanced therapies, while per-unit transactional models apply to generics and topical treatments. Price differentiation is driven by demonstrated efficacy in severe cases and extensive reimbursement coverage. Cost compression in the biologic segment intensifies due to biosimilar competition and payer scrutiny on cost-effectiveness. Public and private healthcare payers exhibit high price sensitivity, contrasting with patients seeking convenience for self-administered options.
Supply Chain Analysis
The United States anchors high-value biologic research and manufacturing, while India and China concentrate on generic and biosimilar active pharmaceutical ingredient production. Biologic manufacturing relies heavily on specialized cell culture media and advanced purification resins. Single-source vulnerability for these complex raw materials presents a significant supply chain risk. Distribution runs through direct-to-pharmacy channels for oral and topical medications, with specialty distributors handling cold-chain biologics for clinic-based administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The psoriasis treatment market is undergoing a platform-economics inflection as patient-centric care models demand interoperability across diagnostic, therapeutic, and monitoring solutions. This requires integrated digital health ecosystems.
For Market Incumbents:Fortify core biologic franchises by investing in next-generation interleukin inhibitors and expanding into adjacent autoimmune conditions. Acquire specialized oral therapy developers to counter the threat from emerging TYK2 inhibitors. Enhance patient support programs and digital health platforms to improve adherence and outcomes, justifying premium pricing. Expand manufacturing capacity in strategic regions like Ireland to mitigate supply chain risks and optimize global distribution.
For New Entrants and Emerging Players:Regulatory fast-track schemes, such as EMA's PRIME, offer a pathway for novel therapies targeting rare psoriatic conditions like pustular or erythrodermic psoriasis. Focus on developing effective oral treatments for convenience-seeking patients, particularly in underpenetrated markets. Target affordable biosimilars in high-volume regions like India and China, leveraging streamlined approval processes. Penetrate the market by emphasizing patient convenience and cost-effectiveness for milder to moderate cases.
For Investors and Strategic Acquirers:Increased FDA approvals for novel oral small molecules reshapes the acquisition landscape for psoriasis treatments. The market remains viable long-term due to the chronic nature of the disease and ongoing unmet needs in specific patient cohorts. Target companies with late-stage oral TYK2 inhibitor pipelines or innovative personalized medicine diagnostics. A signal to watch is the expansion of favorable reimbursement policies for non-injectable systemic therapies.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Expands treatment options and addresses specific patient subpopulations with high unmet needs. |
| Regulatory Approval Pathway | Accelerates market access for innovative therapies, particularly for rare disease forms. |
| Manufacturing Scale-Up | Ensures consistent supply of biologics and biosimilars to meet growing global demand. |
| Pipeline Diversification | Reduces reliance on single drug classes and broadens therapeutic reach across disease severities. |
| Patient Support Program Enhancement | Improves medication adherence and patient outcomes, supporting long-term therapy effectiveness. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during the data collection phase, combining primary interviews with extensive secondary validation. Stakeholders included dermatologists, immunologists, pharmaceutical R&D executives, payer representatives, and patient advocacy groups. Secondary data sources encompassed FDA filings, EMA submissions, ClinicalTrials.gov, and pharmaceutical company annual reports, triangulating findings through both bottom-up and top-down approaches.
The forecasting boundary extends across the analysis window, utilizing quantitative models and qualitative insights to project market evolution. Segmentation dimensions modeled include product type, therapy area, end user, delivery mode, and regional regulatory frameworks. Compound annual growth rates were derived from historical growth trends and projected market expansion factors. Key forecast inputs included new drug launch timelines and biosimilar market penetration rates.
Decision-makers should treat outputs as directional under base assumptions regarding regulatory policy stability and expected clinical trial outcomes; material deviation would warrant model refresh. Key risk factors include unexpected efficacy of novel oral therapies or significant changes in reimbursement structures. Recalibration cycles align with material shifts in drug approval timelines or payer coverage.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Skin Excision Market
Dermatology
Global Dermatology Lasers Market
Dermatology
Cutaneous Squamous Cell Carcinoma Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Dermatological Products Market
Dermatology
US and Canada Skin Cancer Dermatology Market
Dermatology
Dermabrasion Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Erythema Treatment Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Global Dermatitis Herpetiformis Market
Dermatology
Global Veterinary Dermatology Drugs Market
Dermatology
Folliculitis Treatment Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market
Dermatology
Scar Treatment Market
Dermatology
Global Dermatology Cro Market