
 Global Online Dermatology Consultation Market | 2026-2036
Global Online Dermatology Consultation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Dermatology Consultation Market Foresight
North American telehealth infrastructure is consolidating around platforms that integrate electronic health records with dermatology-specific workflows. Teladoc Health leverages its enterprise channel relationships to anchor large health system deployments. First Derm specializes in asynchronous image-based triage, competing on speed and cost against video-first alternatives. MDLIVE sustains broad primary care connectivity that extends into dermatology referrals through payer partnerships.
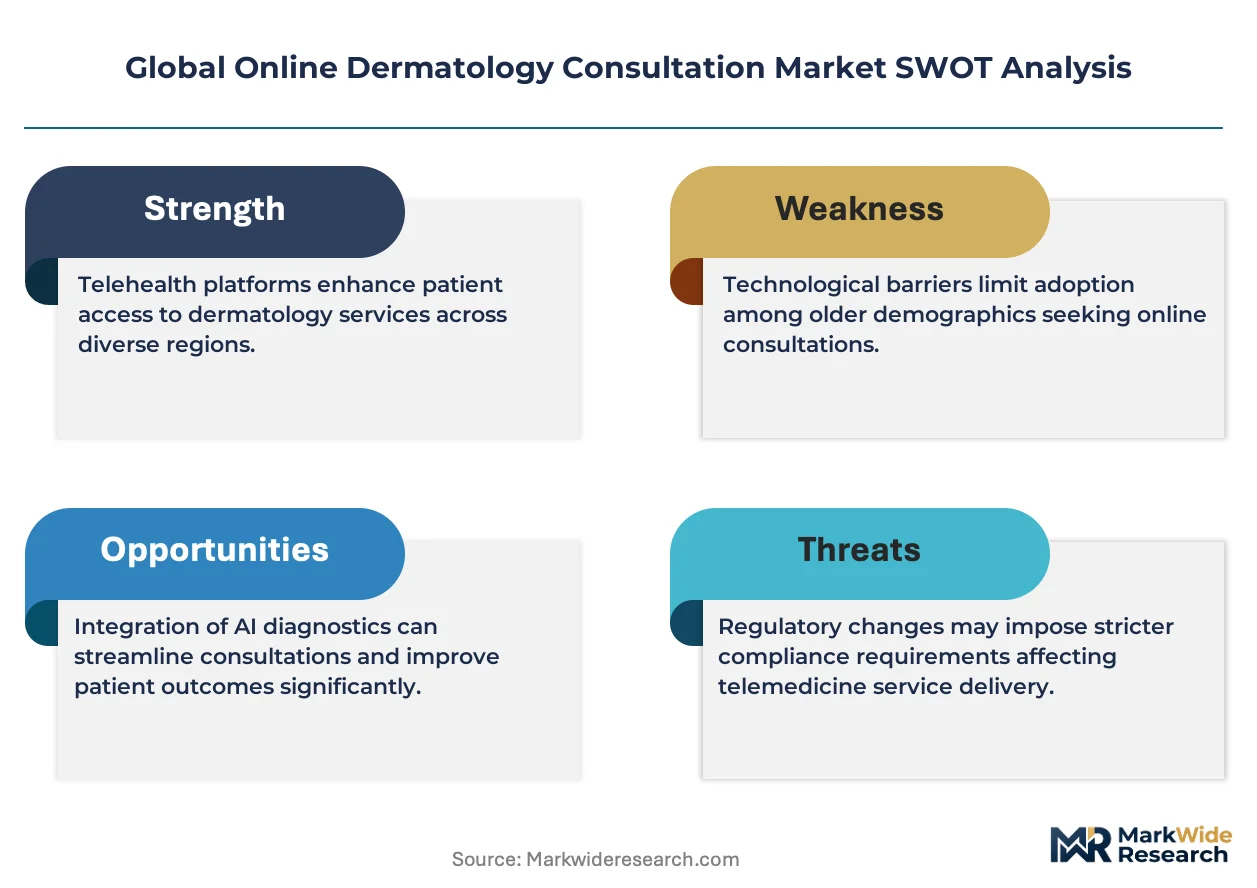
Online dermatology consultation encompasses remote clinical assessment, diagnosis, and treatment planning for skin conditions through digital channels, typically requiring high-resolution image capture with standardized lighting protocols and secure transmission to board-certified specialists. Its primary commercial purpose is reducing geographic and temporal barriers to dermatologic care while enabling scalable specialist utilization. Live video consultation occupies the premium reimbursement tier due to real-time interaction requirements, whereas store-and-forward asynchronous models capture the fastest volume expansion by eliminating scheduling friction. AI-assisted diagnosis segments concentrate venture funding and regulatory scrutiny as algorithms train on expanding dermoscopic image libraries.
FDA oversees software-as-medical-device classifications for diagnostic algorithms in the United States, while GDPR and the EU AI Act impose data residency and risk-tiering obligations on European platform operators. HIPAA security rule compliance shapes hosting architecture decisions for US-facing services, with business associate agreements required for any cloud infrastructure processing protected health information. Stakeholders must monitor evolving reimbursement parity legislation across state and national jurisdictions to calibrate service mix investments between synchronous and asynchronous modalities.
Market Dynamics
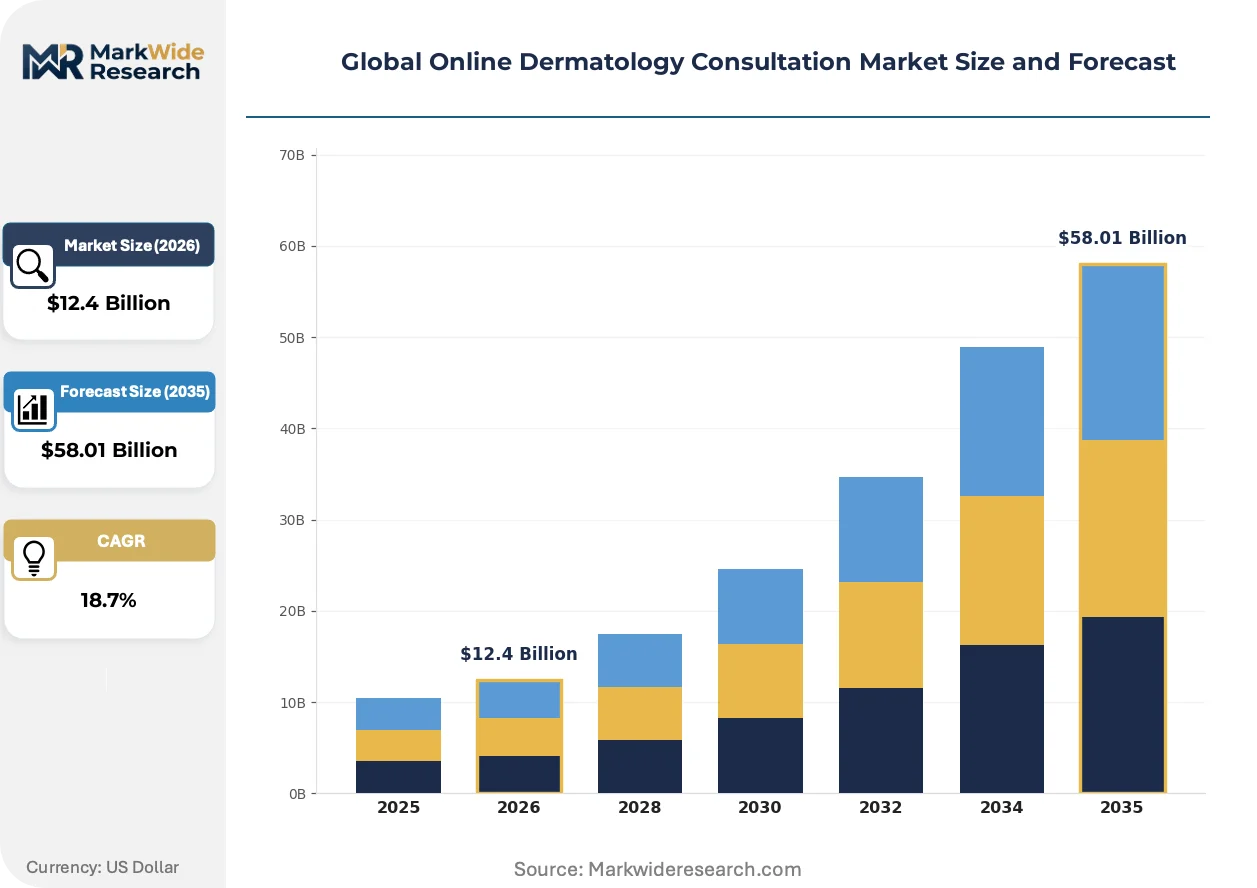
Reimbursement parity legislation is compressing the commercial gap between synchronous video consultations and asynchronous store-and-forward models, forcing platform operators to reconfigure service architectures around hybrid delivery systems.
Growth Catalysts
- Asynchronous Triage Protocols:Store-and-forward dermatology eliminates scheduling friction for primary care providers in the United States, Germany, and India. Platform operators capture volume expansion by removing real-time specialist availability constraints.
- HIPAA Security Rule:Compliance requirements are reshaping cloud hosting architecture decisions for US-facing services, with business associate agreements now mandatory for any infrastructure processing protected health information.
- Dermoscopic Image Libraries:Expanding training datasets for AI-assisted diagnosis algorithms are attracting venture funding and regulatory scrutiny from FDA and EMA simultaneously.
Market Restraints
- GDPR Data Residency:European platform operators face mandatory localization requirements for patient imaging data, increasing infrastructure redundancy costs across multiple jurisdictions.
- Specialist Supply Concentration:Board-certified dermatologist availability clusters in urban medical centers, creating access bottlenecks for rural and semi-urban patient populations.
- Reimbursement Fragmentation:Inconsistent state-level Medicaid coverage for teledermatology services creates revenue uncertainty for multi-state platform deployments.
Strategic Opportunities
- Brazil and Mexico:Underpenetrated Latin American markets present first-mover advantages for asynchronous platforms before national reimbursement frameworks mature.
- EU AI Act Risk-Tiering:Regulatory clarity on software-as-medical-device classifications creates compliance roadmaps for diagnostic algorithm developers seeking European market entry.
- Primary Care Integration:Embedded dermatology modules within electronic health record systems are opening new channel partnerships for triage-as-a-service models.
Industry Challenges
- Image Quality Standardization:Patient-captured photography without standardized lighting protocols generates diagnostic uncertainty and liability exposure for remote specialists.
- Interoperability Friction:Legacy hospital information systems resist seamless API integration with cloud-native teledermatology platforms, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Dermatology Consultation Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Live Video, Store & Forward, Hybrid, AI-Assisted Diagnosis, Remote Monitoring End User: Primary Care Providers, Telehealth Platforms, Independent Dermatologists, Corporate Wellness Programs Consultation Mode: Mobile App, Web Portal, Telephone Support, Email Consultation, Chatbot Interaction Subscription Model: Pay Per Session, Monthly Plan, Annual Plan, Freemium Access, Corporate Packages |
| Companies Covered | Teladoc Health, Doctolib, First Derm, Doctor On Demand, Amwell, MDLIVE, DermatologistOnCall, Miiskin, DirectDerm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Dermatology Consultation Market Shifts & Advancements
Artificial intelligence is penetrating diagnostic workflows at the point of image capture, compressing the traditional specialist review timeline and enabling new triage economics for high-volume primary care settings.
Convolutional neural networks trained on annotated dermoscopic datasets are decentralizing diagnostic capability from academic medical centers to distributed primary care clinics. Rural health systems in the United States and district hospitals in India are adopting AI-assisted pre-screening tools to prioritize specialist referrals. This technology diffusion is compressing the traditional hub-and-spoke dermatology delivery model.
EMA's forthcoming guidance on machine-learning-enabled medical devices is forcing European platform operators to establish quality management systems for algorithm lifecycle monitoring. Manufacturers must now document training data provenance and performance drift metrics across deployed environments. German and French health technology assessment bodies are incorporating these documentation requirements into reimbursement evaluation criteria.
Patients are gravitating toward subscription-based dermatology access models that bundle asynchronous consultation with medication management and follow-up tracking. This preference shift is displacing per-encounter fee structures in direct-to-consumer channels. Subscription penetration is most advanced in United States metropolitan markets where high-deductible health plans amplify out-of-pocket cost sensitivity.
Global Online Dermatology Consultation Market Segmentation
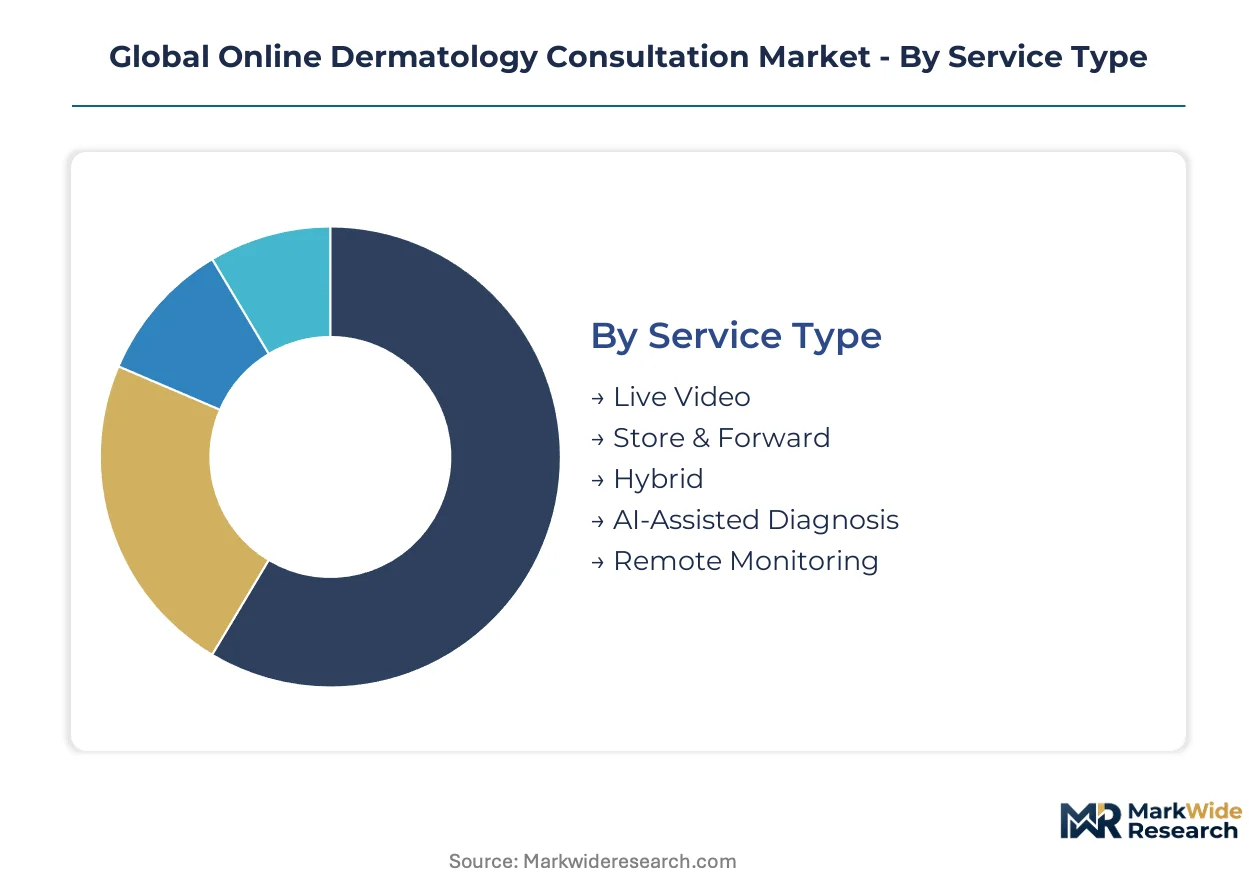
Service architecture decisions in teledermatology determine capital deployment across cloud infrastructure, specialist networks, and regulatory compliance layers. Segmentation reveals where platform operators concentrate R&D spend versus where they optimize for unit economics.
Service Type:
Capital intensity peaks with real-time video infrastructure requiring low-latency global networks and synchronous specialist staffing pools.
- Live Video:Demands redundant server clusters and guaranteed bandwidth for high-definition dermoscopic streaming. Demand clusters in United States metropolitan corridors where reimbursement parity mandates real-time interaction for premium tier coverage.
- Store & Forward:Eliminates specialist scheduling constraints through asynchronous image queues. Primary care providers in Germany and India are scaling deployments fastest where workforce shortages make synchronous models economically unviable.
- Hybrid:Combines triage routing with escalation protocols to live consultation. Requires dual-stack infrastructure investment.
- AI-Assisted Diagnosis:Consumes capital in algorithm training pipelines and FDA 510(k) clearance pathways. Venture funding concentrates here.
- Remote Monitoring:Depends on patient-owned device ecosystems and longitudinal data storage architectures. Chronic condition management drives adoption.
Most installed capacity flows through Store & Forward. Expansion is steepest in AI-Assisted Diagnosis.
End User:
Customer type shapes go-to-market economics from enterprise sales cycles to direct-to-consumer acquisition costs.
- Primary Care Providers:Embedded triage modules within Epic and Cerner workflows. United States health systems demand HIPAA-compliant API integration with existing EHR investments.
- Telehealth Platforms:Aggregate demand across specialties and monetize through payer contracts. Require multi-tenant architecture scaling.
- Independent Dermatologists:Solo practitioners adopting white-label asynchronous tools to extend geographic reach without physical expansion.
- Corporate Wellness Programs:Employers in India and Germany bundle dermatology access with occupational health benefits. Procurement evaluates per-employee-per-month economics.
Revenue concentration sits with Telehealth Platforms. Volume expansion is climbing the fastest among Primary Care Providers.
Consultation Mode:
Interface selection determines patient demographic reach and image quality standardization challenges.
- Mobile App:Dominates patient-initiated demand with built-in camera calibration tools. Younger demographics in Brazil and Mexico favor this channel for privacy and convenience.
- Web Portal:Preferred by enterprise purchasers for desktop integration with clinical workflows. Higher completion rates for complex intake forms.
- Telephone Support:Legacy channel for elderly populations and follow-up scheduling. Declining share but persistent in rural United States markets.
- Email Consultation:Lowest-cost entry point with highest latency. Used for non-urgent second opinions.
- Chatbot Interaction:AI-powered symptom checkers filtering traffic before specialist handoff. Reduces per-consultation labor cost.
Patient volume flows predominantly through Mobile App. Steepest adoption gains are occurring in Chatbot Interaction.
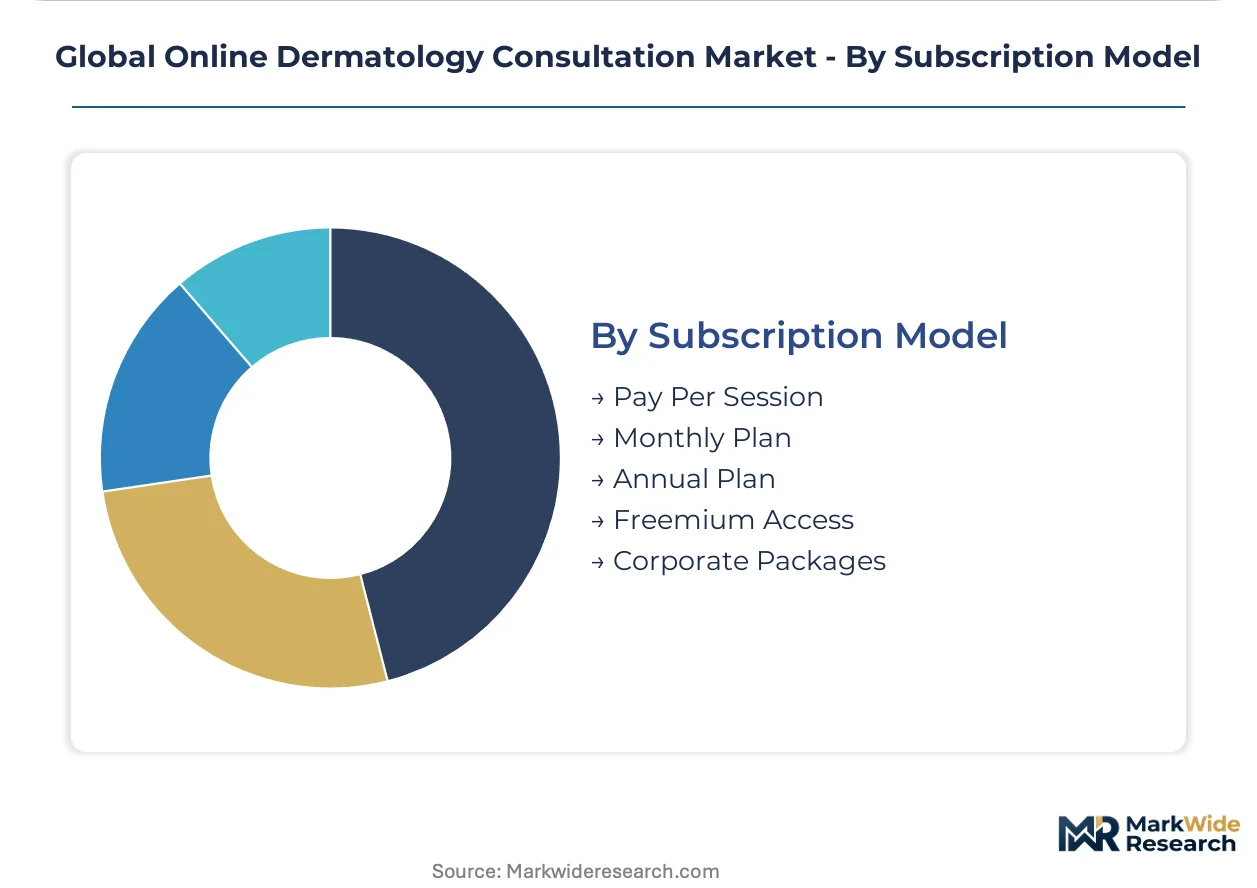
Subscription Model:
Billing structure determines customer lifetime value calculations and churn risk profiles across patient segments.
- Pay Per Session:Transactional model attracting price-sensitive episodic demand. High acquisition cost relative to retention.
- Monthly Plan:Recurring revenue foundation for direct-to-consumer platforms in United States high-deductible plan environments.
- Annual Plan:Locks in commitment and improves cash flow predictability. Corporate purchasers favor this structure.
- Freemium Access:Basic AI screening with paid specialist escalation. Viral acquisition engine with conversion optimization challenges.
- Corporate Packages:B2B contracts with utilization guarantees. Procurement in Germany evaluates against statutory health insurance alternatives.
Recurring revenue concentrates in Monthly Plan. Fastest share gains are emerging in Corporate Packages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing platform development investments toward jurisdictions with clearer software-as-medical-device pathways and reimbursement parity statutes, compressing cost-of-compliance gaps between established and emerging markets.
United States
Enterprise health systems in the United States are consolidating vendor relationships around HIPAA-compliant platforms with Epic and Cerner integration. FDA's evolving 510(k) guidance for diagnostic algorithms is channeling venture capital toward pre-submission pathways. The Boston-Cambridge corridor anchors AI-assisted diagnosis development clusters.
Germany
Germany's statutory health insurance funds are expanding asynchronous teledermatology reimbursement under selective contracting provisions. The EU AI Act's risk-tiering framework is forcing platform operators to establish quality management systems for algorithm lifecycle documentation. Berlin and Munich concentrate health technology assessment expertise influencing European market entry decisions.
India
Primary care providers in India are scaling store-and-forward deployments to address dermatologist density gaps in tier-2 and tier-3 cities. CDSCO's software-as-medical-device regulations are formalizing compliance requirements for AI-assisted diagnostic tools. Bengaluru and Hyderabad host platform development centers serving domestic and export markets simultaneously.
Brazil
Brazil's private health insurance sector is piloting teledermatology coverage before national reimbursement framework maturation. ANVISA's medical device software regulations are creating compliance benchmarks for diagnostic algorithm market entry. São Paulo anchors specialist network concentration and platform commercialization infrastructure.
United Kingdom
NHS England's teledermatology referral pathways are standardizing asynchronous image-based triage for suspected skin cancer cases. MHRA's software-as-medical-device guidance is aligning with FDA and EMA frameworks to reduce regulatory fragmentation. London's digital health clusters concentrate platform engineering and clinical validation partnerships.
Global Online Dermatology Consultation Market Competitive Landscape
United States platforms anchor the enterprise health system tier; European specialists hold positions in direct-to-consumer asynchronous models. Market structure exhibits moderate consolidation around telehealth incumbents with cross-specialty scale, with independent dermatology-focused operators occupying niche positions. Three strategic archetypes predominate: integrated telehealth conglomerates, pure-play dermatology platforms, and AI-assisted diagnostic developers. Dominant competitive moves include payer contract expansion and EHR integration partnerships.
Among integrated telehealth conglomerates, Teladoc Health and Amwell occupy positions representing enterprise channel scale and multi-specialty platform architecture. Within pure-play dermatology specialists, First Derm exemplifies the asynchronous image-based triage archetype competing on speed and cost efficiency against video-first alternatives. These named entities anchor industry-level commentary on service model differentiation and customer acquisition channel strategies without implying specific strategic actions or financial performance.
| Leading Market Players |
|---|
| Teladoc Health |
| Doctolib |
| First Derm |
| Doctor On Demand |
| Amwell |
| MDLIVE |
| DermatologistOnCall |
| Miiskin |
| DirectDerm |
| Others |
Supply & Pricing Matrix
Cloud compute pricing indices from Amazon Web Services and Microsoft Azure cascade through teledermatology platform operating costs into subscription tiers, with HIPAA-compliant hosting premiums compressing margins at the standard service level while AI-assisted diagnostic modules command premium positioning.
Pricing Analysis
Platform operator margins absorb the steepest pressure from enterprise health system procurement teams negotiating volume-based SaaS contracts. Pricing stratifies across premium, standard, and economy tiers according to AI feature depth and EHR integration complexity. Cost compression in the asynchronous base tier intensifies because primary care providers in Germany and India demand per-consultation economics below video-first alternatives. Corporate wellness purchasers in India exhibit highest price sensitivity; United States metropolitan direct-to-consumer subscribers show lowest sensitivity due to high-deductible plan out-of-pocket exposure.
Supply Chain Analysis
Dual-sourcing requirements from United States health systems mandate qualified cloud infrastructure providers in at least two domestic availability zones plus one European jurisdiction for GDPR-covered data. Platform development concentrates in the United States, Germany, and India. Specialist network capacity rests on board-certified dermatologist supply concentrated in urban medical centers. Single-source vulnerability runs through dermoscopic imaging device manufacturers facing FDA 510(k) clearance backlogs. Distribution feeds from cloud-native platform providers through health system IT procurement channels and direct-to-consumer app stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications in teledermatology are hardening toward FDA-cleared AI diagnostic modules and HIPAA-compliant API architectures, shifting procurement criteria away from basic video connectivity toward validated clinical workflow integration.
For Market Incumbents: Lock in enterprise health system relationships through Epic and Cerner embedded module deployments before reimbursement parity legislation commoditizes asynchronous triage. Consolidate specialist network density in United States metropolitan corridors where synchronous video retains premium reimbursement tiers. Counter emerging pure-play dermatology platforms with AI-assisted diagnosis capability investments that extend beyond primary care triage into longitudinal monitoring. For New Entrants and Emerging Players: Payer channel partnerships in Brazil and Mexico offer first-mover positioning before national reimbursement frameworks mature. White-label asynchronous platforms for independent dermatologists in Germany represent the most penetrable segment given statutory health insurance selective contracting expansion. Pursue CDSCO software-as-medical-device registration in India to access tier-2 and tier-3 city primary care networks underserved by incumbent telehealth conglomerates. For Investors and Strategic Acquirers: Consolidation pressure builds where AI-assisted diagnostic developers lack FDA 510(k) clearance pathways and health system distribution relationships. Long-term viability in this market hinges on regulatory validation depth and EHR integration breadth rather than consumer brand awareness. Acquisition target archetypes include pure-play dermatology platforms with established German reimbursement contracts and AI training data libraries exceeding annotated dermoscopic images. Watch FDA pre-submission meeting outcomes for diagnostic algorithm developers as inflection indicators for venture funding velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Pre-market clearance for AI diagnostic algorithms unlocks Medicare reimbursement codes in United States health systems. |
| Epic EHR Integration Partnership | Embedded dermatology modules within Cerner and Epic workflows capture primary care provider triage volume at point of care. |
| German Statutory Insurance Contracting | Selective contracting provisions under EU AI Act compliance frameworks secure recurring revenue from statutory health funds. |
| CDSCO Software Registration | Domestic regulatory clearance in India enables platform deployment across tier-2 and tier-3 city hospital networks. |
| AI Training Data Acquisition | Annotated dermoscopic image libraries accelerate FDA pre-submission pathways and algorithm performance validation. |
Research Methodology
Multiple input streams — structured interviews with dermatology platform executives, health system IT procurement directors, and regulatory affairs specialists at FDA and EMA — were reconciled against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, and EU AI Act implementation guidance. Bottom-up and top-down triangulation cross-checked platform deployment metrics with statutory health insurance contracting data from Germany and private health insurance pilot programs in Brazil.
Data-stream reconciliation across service type, end user, consultation mode, and subscription model segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed capacity trajectories and reimbursement parity legislative tracking. Forecast inputs incorporated cloud infrastructure cost indices, specialist network density ratios, and AI algorithm regulatory clearance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA software-as-medical-device classification shifts and EU AI Act risk-tiering enforcement patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Europe Scar Treatment Market
Dermatology
Global Dermatology Lasers Market
Dermatology
Australia Skin Treatment Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Derma Rollers Market
Dermatology
Atopic Dermatitis Therapeutics Market
Dermatology
Psoriasis Treatment Market
Dermatology
Global Dermatitis Herpetiformis Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
Radiation Dermatitis Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Erythema Treatment Market
Dermatology
Global Dermatological OTC Drugs Market
Dermatology
Acne Scar Treatment Market