
 Prescription Dermatology Therapeutics Market | 2026-2036
Prescription Dermatology Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Prescription Dermatology Therapeutics Market Outlook
Multi-source procurement of active pharmaceutical ingredients is recalibrating how dermatology drug makers secure their supply chains. Galderma S.A. leverages its vertically integrated manufacturing network across Europe to control quality from API synthesis through finished dose. Pfizer Inc. anchors its dermatology portfolio through strategic partnerships with specialty biotech firms, while AbbVie Inc. dominates the biologics segment with deep R&D investment in IL-23 and IL-17 pathway inhibitors.
Prescription dermatology therapeutics comprise regulated pharmaceutical formulations designed for topical, oral, or parenteral administration to treat inflammatory, autoimmune, and neoplastic skin conditions, with biologics typically requiring cold-chain distribution at two to eight degrees Celsius to maintain protein stability. These products serve dermatologists, hospitals, and specialty clinics managing chronic diseases where standard over-the-counter remedies prove insufficient. Biologics command the highest margin pools within the product type landscape due to manufacturing complexity and patent protection, while topical corticosteroids remain the volume backbone in eczema and psoriasis first-line therapy. Injectable delivery modes are gaining fastest among biologic-treated patients, though topical formulations sustain the majority of prescriptions across acne and rosacea indications.
The FDA governs dermatology drug approvals through its Center for Drug Evaluation and Research, with the EMA's Committee for Medicinal Products for Human Use applying parallel standards across European member states, while China's NMPA has tightened bioequivalence requirements for generic topical formulations. These regulatory frameworks shape clinical trial design, label claims, and market access timelines, creating divergent launch sequences across major markets. Stakeholders must monitor evolving biosimilar entry strategies and payer contracting dynamics as biologic patents expire, since formulary positioning will determine which manufacturers capture the next wave of dermatology spending.
Market Dynamics
Biologic cold-chain infrastructure expansion is compressing distribution timelines for temperature-sensitive dermatology therapies, forcing manufacturers to rebuild logistics networks around two-to-eight-degree Celsius compliance rather than ambient distribution economics.
Growth Catalysts
- IL-23 pathway inhibitors:These biologics are capturing specialist preference in moderate-to-severe psoriasis by delivering durable skin clearance with quarterly dosing intervals, reducing patient injection burden.
- FDA accelerated approval:The pathway has compressed Phase II-to-launch timelines for dermatology biologics, enabling earlier patient access and faster manufacturer revenue recognition.
- Atopic dermatitis biologic penetration:Pediatric and adult populations previously managed with topical corticosteroids alone are now transitioning to systemic biologics as first-line failure rates accumulate.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient synthesis for monoclonal antibodies clusters among contract manufacturers in Switzerland and Singapore, creating single-source vulnerability.
- Cold-chain cost inflation:Specialized refrigerated transport and storage infrastructure adds fifteen to twenty-five percent to landed product cost versus ambient pharmaceuticals.
- Biosimilar substitution pressure:Patent cliffs on originator biologics are triggering automatic substitution protocols at US pharmacy benefit managers, eroding branded pricing power.
Strategic Opportunities
- China's NMPA priority review:The expanded fast-track designation for innovative dermatology therapies is opening accelerated market access for biologics with domestic clinical data.
- Telemedicine prescribing:Remote dermatology consultations are expanding biologic-eligible patient pools beyond major metropolitan hospital systems into secondary cities.
- Topical JAK inhibitor convergence:Small-molecule Janus kinase inhibitors delivered through enhanced transdermal formulations are bridging the efficacy gap between biologics and conventional topicals.
Industry Challenges
- Biologics manufacturing talent scarcity:Cell culture and purification expertise concentrates among a limited cohort of specialists, constraining capacity expansion timelines.
- EMA variation procedure complexity:Post-approval manufacturing changes require coordinated regulatory submissions across European member states, delaying supply network optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prescription Dermatology Therapeutics Market |
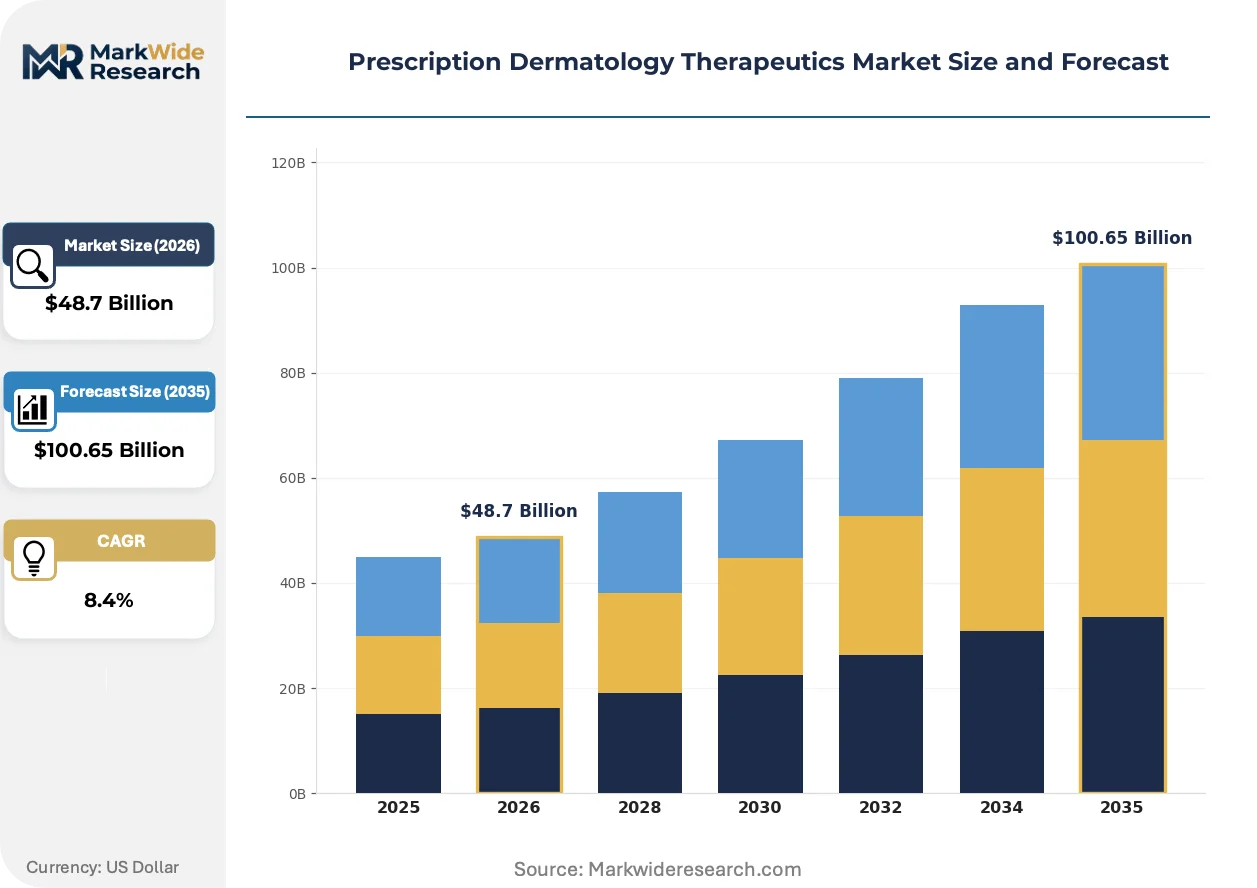
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Retinoids, Calcineurin Inhibitors, Biologics Application: Psoriasis, Eczema, Acne, Rosacea Delivery Mode: Topical, Oral, Injectable, Transdermal End User: Hospitals, Dermatology Clinics, Pharmacies, Home Care |
| Companies Covered | Galderma S.A., Amgen Inc., Pfizer Inc., Johnson & Johnson, Eli Lilly and Company, AbbVie Inc., Bausch Health Companies Inc., Sun Pharmaceutical Industries Ltd., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prescription Dermatology Therapeutics Market Strategic Shifts
Prescription dermatology is absorbing platform innovations from adjacent therapeutic areas, with gene-silencing technologies and microbiome modulation crossing over from oncology and gastroenterology into inflammatory skin disease management.
RNA interference therapeutics are absorbing development investment from large-cap pharmaceutical portfolios previously focused on small-molecule dermatology assets. These siRNA platforms target specific inflammatory cytokine production at the transcriptional level, offering dermatologists mechanism-of-action differentiation from existing biologics. Early-phase programs in hidradenitis suppurativa and alopecia areata are absorbing patient recruitment priority at investigative sites.
REACH authorization requirements for novel chemical entities are absorbing reformulation resources at topical dermatology manufacturers across the European Union. The regulation's extended data requirements for skin-sensitization and environmental fate are absorbing additional twelve-to-eighteen-month registration timelines for new molecular entities. Generic topical manufacturers are absorbing compliance costs through portfolio pruning rather than full dossier resubmission.
Specialty pharmacy channel consolidation is absorbing patient onboarding and adherence monitoring functions previously managed by prescriber offices. These distributors are absorbing biologic shipment coordination, injection training, and prior authorization navigation for dermatology practices. The shift is absorbing administrative burden most visibly in United States commercial insurance networks where step-therapy protocols require documented topical failure before biologic approval.
Prescription Dermatology Therapeutics Market Segmentation
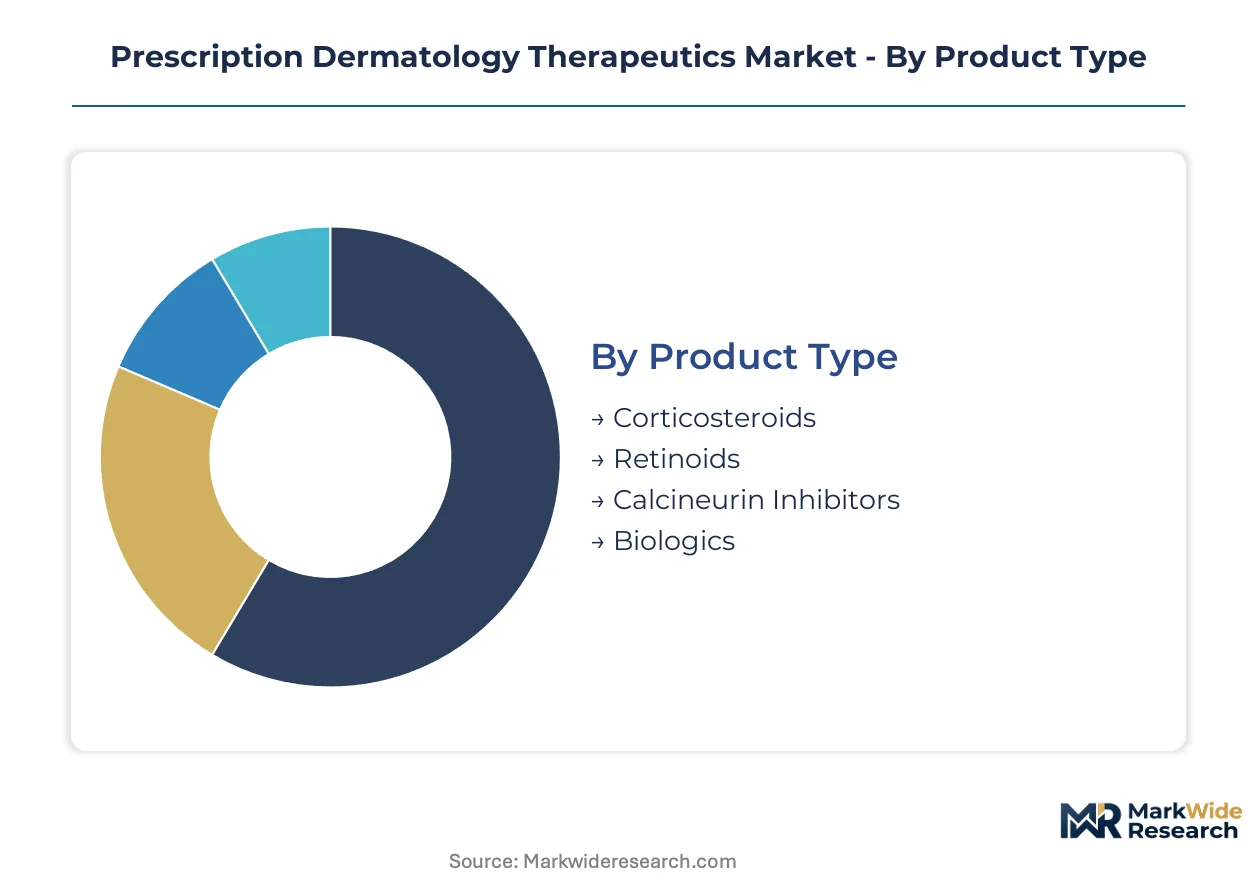
Prescription dermatology therapeutics fragment across four distinct dimensions, each carrying divergent margin profiles and regulatory pathways. Product type and delivery mode classifications determine cold-chain requirements and manufacturing complexity, while application and end-user segments shape reimbursement dynamics and prescribing authority.
Product Type:
Standardization dominates corticosteroid and retinoid production, whereas biologics demand bespoke cell-line development and batch-specific release testing.
- Corticosteroids:Synthetic glucocorticoid formulations ranging from low-potency hydrocortisone to super-high-potency clobetasol propionate. Demand concentrates in United States Medicaid formularies and German statutory health insurance where first-line eczema protocols mandate step-therapy initiation with these agents before biologic escalation.
- Biologics:Recombinant monoclonal antibodies and fusion proteins targeting IL-17, IL-23, and IL-4/13 cytokine pathways. United States specialty pharmacy networks and Japanese hospital outpatient clinics absorb the majority of volume as dermatologists shift moderate-to-severe psoriasis management toward quarterly injectable regimens.
- Retinoids:Vitamin A derivatives including isotretinoin, tretinoin, and adapalene for acne and photoaging indications.
- Calcineurin Inhibitors:Tacrolimus and pimecrolimus macrolactams for steroid-sparing atopic dermatitis therapy, particularly in pediatric populations.
Leading the category by volume: Corticosteroids. Growing fastest: Biologics.
Application:
Cost tier stratification separates chronic autoimmune conditions requiring lifetime biologic therapy from episodic infectious or inflammatory presentations managed with short-course topicals.
- Psoriasis:Chronic plaque-type and psoriatic arthritis variants driving systemic therapy decisions. United States Medicare Part D plans and United Kingdom NHS specialist commissioning groups concentrate reimbursement authorization for biologic-eligible patients with PASI scores above threshold criteria.
- Eczema:Atopic dermatitis spanning infant, pediatric, and adult phenotypes with heterogeneous severity distributions. German dermatology practices and French hospital centers absorb elevated biologic penetration as dupilumab and tralokinumab displace cyclosporine for refractory cases.
- Acne:Androgen-driven pilosebaceous inflammation managed primarily with retinoids, antibiotics, and hormonal modulators.
- Rosacea:Chronic facial erythema and inflammatory lesions addressed through topical metronidazole, ivermectin, and oral tetracycline derivatives.
Psoriasis commands premium pricing per treated patient. Eczema is expanding most quickly as pediatric biologic indications broaden.
Delivery Mode:
Volume scale inversely correlates with technical sophistication, as topical formulations sustain prescription counts while injectable biologics concentrate revenue.
- Injectable:Prefilled syringes and autoinjector devices for subcutaneous biologic administration. Cold-chain infrastructure investments across United States specialty pharmacy distributors and Japanese hospital outpatient pharmacies enable two-to-eight-degree Celsius compliance for protein stability maintenance.
- Topical:Creams, ointments, gels, and foams for direct cutaneous application. United States retail pharmacy chains and German community pharmacies handle the majority of dispensed volume for corticosteroid and retinoid prescriptions.
- Oral:Systemic small-molecule therapies including methotrexate, acitretin, and apremilast.
- Transdermal:Patch-based and microneedle-enhanced delivery systems for sustained drug release.
Topical formulations dominate prescription counts. Injectable biologics are gaining share fastest among newly diagnosed moderate-to-severe patients.
End User:
Customer type determines formulary leverage and patient onboarding complexity, with institutional purchasers extracting deeper discounts than retail channels.
- Hospitals:Inpatient and outpatient departments managing severe drug reactions, autoimmune blistering diseases, and biologic initiation protocols. United States academic medical centers and Japanese national university hospitals concentrate biologic infusion capacity and prior authorization navigation resources.
- Dermatology Clinics:Specialist practices with direct prescribing authority and in-office dispensing privileges. German dermatologist-operated practices and French liberal profession clinics capture the majority of biologic-eligible patient evaluations through referral networks.
- Pharmacies:Retail and specialty dispensing channels handling prescription fulfillment and insurance adjudication.
- Home Care:Self-administration settings for stable patients on maintenance biologic regimens.
Dermatology clinics lead by patient encounter volume. Home care is climbing the fastest as autoinjector training programs expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient synthesis clusters in Basel, Switzerland, and Singapore's Tuas Biomedical Park anchor global supply networks for monoclonal antibody production. These localities feed formulation plants across four demand centers where reimbursement policy and specialist density determine biologic penetration rates.
United States
Medicare Part D plans and commercial pharmacy benefit managers drive biologic volume through prior authorization protocols that mandate topical corticosteroid failure documentation. FDA's accelerated approval pathway compresses launch timelines for IL-23 and IL-17 inhibitors targeting moderate-to-severe psoriasis. The Northeast corridor from Boston to Philadelphia concentrates dermatology clinical trial sites and specialty pharmacy distribution hubs managing cold-chain logistics.
Germany
Statutory health insurance funds and dermatologist-operated practices sustain elevated biologic penetration rates for atopic dermatitis and psoriasis relative to European peers. EMA's Committee for Medicinal Products for Human Use coordinates centralized marketing authorization procedures that enable simultaneous multi-country launches. The Rhine-Main region around Frankfurt anchors logistics infrastructure for temperature-controlled distribution across Central Europe.
Japan
National university hospitals and prefectural medical centers absorb the majority of biologic-eligible patient evaluations under universal health coverage reimbursement. PMDA's sakigake designation accelerates review timelines for innovative dermatology therapies with domestic clinical data. The Kanto region surrounding Tokyo concentrates dermatology specialist practices and hospital outpatient pharmacies equipped for protein stability maintenance.
China
Priority review expansion at NMPA and domestic clinical trial requirements are reshaping market access timelines for multinational biologic portfolios. Tier-one hospital dermatology departments in Beijing, Shanghai, and Guangzhou drive specialist-prescribed systemic therapy adoption for psoriasis and atopic dermatitis. The Yangtze River Delta pharmaceutical manufacturing corridor is absorbing capacity investments for monoclonal antibody production.
Switzerland
Contract manufacturing organizations in Basel and the greater Zurich area supply cell culture and purification services for originator and biosimilar monoclonal antibodies. Swissmedic maintains alignment with EMA standards while offering streamlined procedures for manufacturing site variations. The country's pharmaceutical cluster benefits from proximity to German and French hospital procurement networks.
Prescription Dermatology Therapeutics Market Competitive Environment
Strategic partnerships dominate the current landscape as large-cap pharmaceutical anchors access biologic development capabilities through specialty biotechnology alliances. The market structure concentrates revenue among a handful of vertically integrated dermatology specialists and diversified pharmaceutical conglomerates with deep biologics pipelines. Three archetypes define competitive positioning: originator biologic developers with IL-pathway expertise, mid-cap topical formulation specialists, and emerging biosimilar manufacturers. Capacity expansion in cold-chain distribution and M&A activity targeting transdermal delivery platforms represent the dominant competitive moves reshaping participant rankings.
Among originator biologic developers, AbbVie Inc., Eli Lilly and Company, and Novartis AG exemplify the R&D-intensive archetype commanding premium positioning in psoriasis and atopic dermatitis segments. These entities occupy positions defined by cytokine pathway specialization and quarterly-dosing regimen development. Galderma S.A. and Bausch Health Companies Inc. represent the dermatology-focused mid-cap tier, with portfolios spanning topical corticosteroids through biologic co-development arrangements. Sun Pharmaceutical Industries Ltd. anchors the emerging market and generic topical segment, leveraging formulation expertise across cost-sensitive healthcare systems.
| Leading Market Players |
|---|
| Galderma S.A. |
| Amgen Inc. |
| Pfizer Inc. |
| Johnson & Johnson |
| Eli Lilly and Company |
| AbbVie Inc. |
| Bausch Health Companies Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialty pharmacy distributors anchor cold-chain logistics infrastructure across the United States, compressing margins for originator biologics while extracting service-bundling premiums from manufacturers seeking formulary access. This ownership pattern concentrates pricing power among consolidated intermediaries that bundle injection training, prior authorization navigation, and temperature-controlled delivery into per-dose fees.
Pricing Analysis
Service-bundling separates biologic pricing into unbundled drug acquisition costs versus wrapped patient-support fees that specialty pharmacies capture separately. Three-tier pricing structure across originator biologics, authorized biosimilars, and unbranded generics stratifies reimbursement tiers, with FDA biosimilar interchangeability designation serving as the primary quality-grade differentiator. Pricing pressure stems from automatic substitution protocols at US pharmacy benefit managers as adalimumab and ustekinumab patents expire. Medicaid formularies exhibit highest price sensitivity, while Medicare Part D specialty tiers demonstrate lowest sensitivity due to manufacturer patient-assistance programs.
Supply Chain Analysis
Direct-to-hospital channels handle biologic volume for academic medical centers with in-house infusion capacity, while specialty pharmacy networks manage self-administered subcutaneous therapies for community dermatology practices. Active pharmaceutical ingredient synthesis concentrates in Switzerland, Singapore, and the United States, with monoclonal antibody cell culture and purification anchored in Basel and Tuas Biomedical Park. Supply chains draw from Chinese contract manufacturers for fill-finish services and German packaging specialists for autoinjector assembly. Single-source vulnerability in Swiss CMO capacity represents the dominant structural risk. Distribution runs through temperature-controlled lanes maintained at two-to-eight degrees Celsius from manufacturing site to patient doorstep.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The prescription dermatology therapeutics sector sits in a technology-transition phase as RNA interference platforms displace legacy small-molecule assets in inflammatory skin disease pipelines. siRNA mechanisms targeting cytokine transcription offer dermatologists mechanism-of-action differentiation from existing IL-pathway biologics.
For Market Incumbents: Hedge against biosimilar erosion by accelerating investment in next-generation IL-23 and IL-17 pathway inhibitors with extended dosing intervals that complicate automatic substitution protocols. Secure backward integration into cell culture capacity through partnerships with Swiss and Singaporean CMOs to mitigate single-source API vulnerability. Prioritize pediatric label expansions for atopic dermatitis biologics ahead of generic topical JAK inhibitor entry.
For New Entrants and Emerging Players: Launch via telemedicine-enabled specialty pharmacy partnerships to access biologic-eligible patients in secondary US cities and German dermatology practices outside major metropolitan hospital systems. Target the topical JAK inhibitor convergence segment where efficacy gaps between biologics and conventional topicals create white-space opportunity for enhanced transdermal formulations. Prioritize China NMPA domestic clinical trial investment to capture priority review benefits for innovative dermatology therapies.
For Investors and Strategic Acquirers: FDA accelerated approval pathway utilization rates for dermatology biologics are the leading indicator that development-stage asset valuations will compress as Phase II-to-launch timelines shorten. Position portfolios for five-to-ten year horizon viability by targeting acquisition of mid-cap topical formulation specialists with transdermal delivery platform capabilities. Monitor EMA variation procedure approval velocity as a signal of European supply network optimization potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Specialty pharmacy networks in the United States and Japan are building two-to-eight-degree Celsius compliance capacity to support biologic volume growth. |
| Regulatory Approval Pathway Optimization | FDA accelerated approval and China NMPA priority review are compressing market access timelines for IL-pathway inhibitors. |
| Manufacturing Scale-Up | Swiss and Singaporean CMOs are expanding cell culture capacity to meet monoclonal antibody demand from dermatology portfolios. |
| Pipeline Diversification | RNA interference platforms targeting hidradenitis suppurativa and alopecia areata are absorbing R&D investment from large-cap pharmaceutical portfolios. |
| Strategic Partnership | Telemedicine prescribing platforms are partnering with specialty pharmacies to expand biologic-eligible patient pools beyond major metropolitan hospital systems. |
Study Parameters
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from payer access specialist surveys and specialty pharmacy distribution data. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market size estimates.
Segmented outputs across product type, application, delivery mode, and end-user dimensions were generated across the analysis window. Treatment line stratification, regional regulatory clusters, and patient population severity distributions informed analytical framework construction. CAGRs were derived from fitted growth curves incorporating biologic penetration rates, biosimilar entry assumptions, and cold-chain infrastructure expansion timelines. Forecast inputs included IL-pathway inhibitor dosing interval evolution and topical JAK inhibitor formulation advancement.
The model assumes a particular technology adoption path for RNA interference therapeutics; alternative pathways for siRNA platform commercialization would alter the outlook for small-molecule dermatology asset valuations. Forecasts reflect assumptions regarding FDA accelerated approval pathway utilization, EMA centralized procedure timelines, and China NMPA domestic clinical trial requirements. Patent cliff timing, biosimilar substitution protocol adoption, and specialty pharmacy channel consolidation represent specific risk factors that could revise projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Impetigo Treatment Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Microneedling Market
Dermatology
Acne Scar Treatment Market
Dermatology
Scar Treatment Oils Market
Dermatology
Common Warts Market
Dermatology
Global Onychomycosis Market
Dermatology
Global Hirsutism Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Dermatophytic Onychomycosis Treatment Market
Dermatology
Lichen Sclerosus Treatment Market
Dermatology
Global Online Dermatology Consultation Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Hyperpigmentation Treatment Market
Dermatology
Global Dermatology Excimer Laser Market