
 Global Hirsutism Market | 2026-2036
Global Hirsutism Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hirsutism Market Foresight
Platform licensing for at-home laser devices is reshaping how manufacturers capture recurring revenue from hirsutism patients. Alma Lasers Ltd. extends its clinical installed base into consumer channels through controlled distribution partnerships. Lumenis Inc. dominates the professional segment with high-powered platforms that command premium placement in dermatology clinics. Ajanta Pharma competes on oral anti-androgen formulations across price-sensitive markets in South Asia and Southeast Asia.
Hirsutism denotes excessive terminal hair growth in androgen-dependent areas of female patients, typically quantified using the modified Ferriman-Gallwey scoring system where scores above eight indicate clinically significant presentation. The condition stems from ovarian or adrenal androgen overproduction, peripheral androgen conversion, or heightened follicular sensitivity, with treatment spanning pharmacological suppression and physical hair removal modalities. Anti-androgen drugs and oral contraceptives anchor the pharmaceutical segment where margin pools concentrate in patent-protected combination therapies. Hair removal devices represent the fastest-growing product category as diode and alexandrite laser technologies displace older IPL systems in clinical settings. Polycystic ovary syndrome as a therapy area sustains the largest patient flow into both endocrinology centers and cosmetic surgery units.
FDA premarket notification requirements govern laser and light-based hair removal devices in the United States, while the EU Medical Device Regulation reclassifies many aesthetic energy devices under stricter conformity assessment pathways. Health Canada and Japan's PMDA impose parallel clinical evidence standards that filter market entry for device manufacturers. The report identifies regulatory harmonization across these three jurisdictions as the critical variable determining which companies can scale hirsutism treatment platforms across multiple continents without duplicative trials.
Market Dynamics
Laser hair removal platforms are displacing older IPL systems in clinical settings, with diode and alexandrite technologies capturing premium placement as dermatology clinics expand treatment capacity across major metropolitan markets.
Growth Catalysts
- EU Medical Device Regulation reclassification:Stricter conformity assessment pathways for aesthetic energy devices are filtering market entry and elevating quality standards for surviving manufacturers.
- Polycystic ovary syndrome patient flow:Endocrinology centers and cosmetic surgery units are experiencing sustained demand as PCOS diagnosis rates climb in developed healthcare systems.
- At-home device platform licensing:Controlled distribution partnerships are extending clinical installed bases into consumer channels, creating recurring revenue streams from hirsutism patients.
Market Restraints
- FDA premarket notification tightening:Clinical evidence requirements for laser-based hair removal devices have intensified, extending approval timelines and raising development costs for manufacturers.
- Input concentration in laser component supply:High-powered diode arrays and precision optical systems depend on concentrated Asian manufacturing clusters, creating vulnerability to trade friction.
- Pharmaceutical patent cliffs:Oral anti-androgen formulations face generic competition in price-sensitive South Asian and Southeast Asian markets, compressing margin pools for originator products.
Strategic Opportunities
- Japan's PMDA parallel pathways:Clinical evidence standards that align with FDA and Health Canada requirements enable multi-continental scaling without duplicative trials for compliant manufacturers.
- Telemedicine-integrated prescription models:Remote endocrinology consultations are expanding access to anti-androgen therapies in underserved rural markets within developed healthcare systems.
- Combination therapy protocols:Pharmacological suppression paired with energy-based hair removal is creating bundled service offerings in dermatology clinics seeking differentiation.
Industry Challenges
- Specialized technician certification:Laser device operation requires trained personnel, creating bottlenecks as clinic expansion outpaces qualified workforce supply in key metropolitan markets.
- Reimbursement code fragmentation:Endocrine-related cosmetic interventions lack standardized coverage frameworks, forcing providers to navigate heterogeneous payer policies across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hirsutism Market |
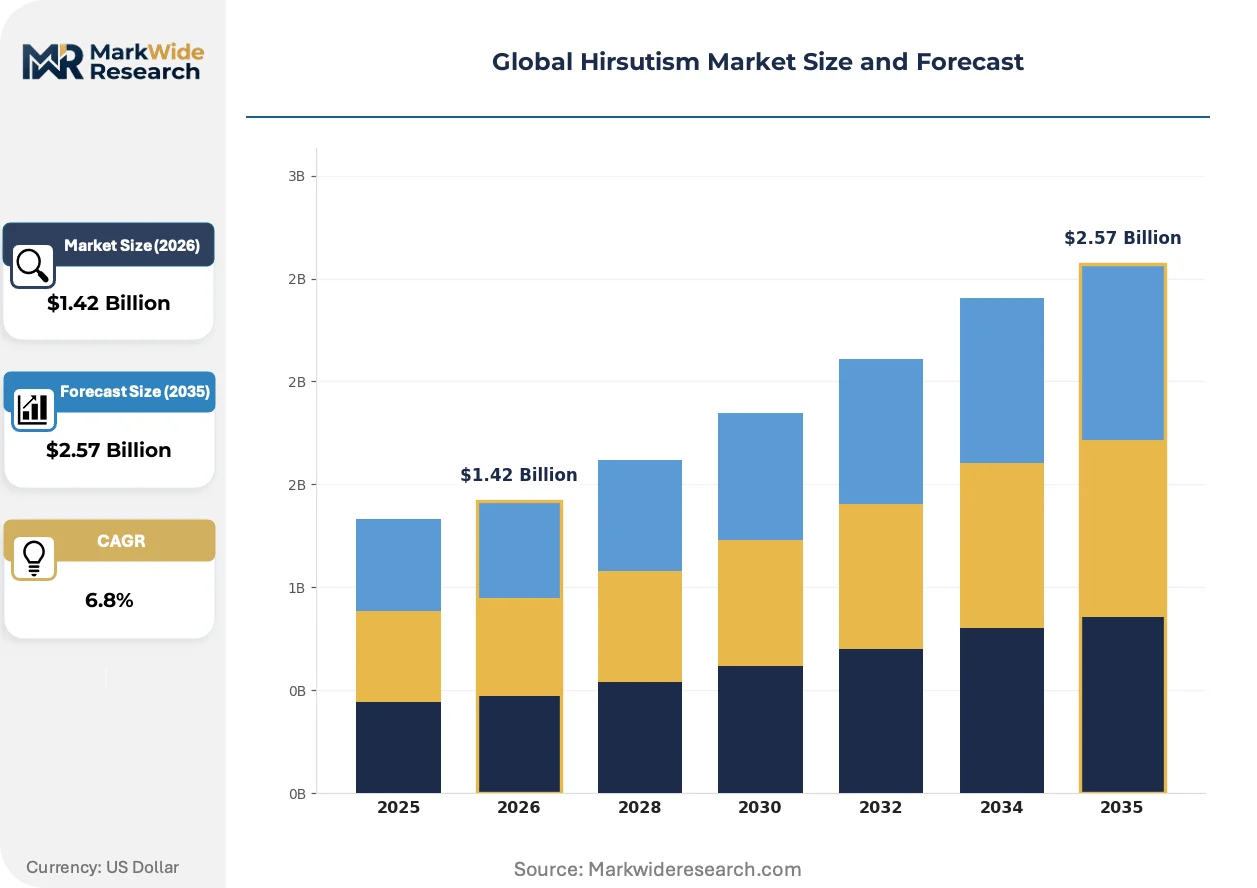
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Androgen Drugs, Oral Contraceptives, Topical Creams, Hair Removal Devices, Others Therapy Area: Endocrine Disorders, Cosmetic Treatment, Polycystic Ovary Syndrome, Idiopathic Hirsutism End User: Dermatology Clinics, Endocrinology Centers, Cosmetic Surgery Units, Medical Spas Distribution Channel: Pharmacies, Online Retail, Hospitals, Specialized Clinics |
| Companies Covered | Lumenis Inc., Alma Lasers Ltd., Cynosure Inc., Cutera Inc., Ajanta Pharma, Nisim Inc., Alpaya Dermaceuticals, Merck & Co., Inc., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hirsutism Market Shifts & Advancements
Device connectivity and software-enabled treatment protocols are transforming how hirsutism therapies are delivered, monitored, and reimbursed across clinical and consumer channels.
Artificial intelligence-powered skin analysis systems are digitizing treatment planning for laser hair removal platforms. Dermatology clinics in the United States and Germany are deploying these tools to customize energy delivery parameters based on real-time follicular assessment. This convergence is compressing the gap between professional-grade outcomes and at-home device efficacy expectations.
The EU Medical Device Regulation's stricter conformity assessment pathways are elevating clinical evidence burdens for aesthetic energy device manufacturers. European manufacturers must now demonstrate sustained safety and efficacy across broader patient phenotypes to maintain market access. This regulatory shift is accelerating consolidation among smaller device producers unable to absorb compliance costs.
Subscription-based access models for at-home laser devices are replacing traditional retail purchase patterns in North American and Western European markets. Direct-to-consumer channels are disintermediating specialty retailers as manufacturers capture recurring revenue through consumable and upgrade cycles. This behavioral shift is most visible among millennial and Gen-Z demographics seeking discreet, ongoing management of hirsutism symptoms.
Global Hirsutism Market Segmentation
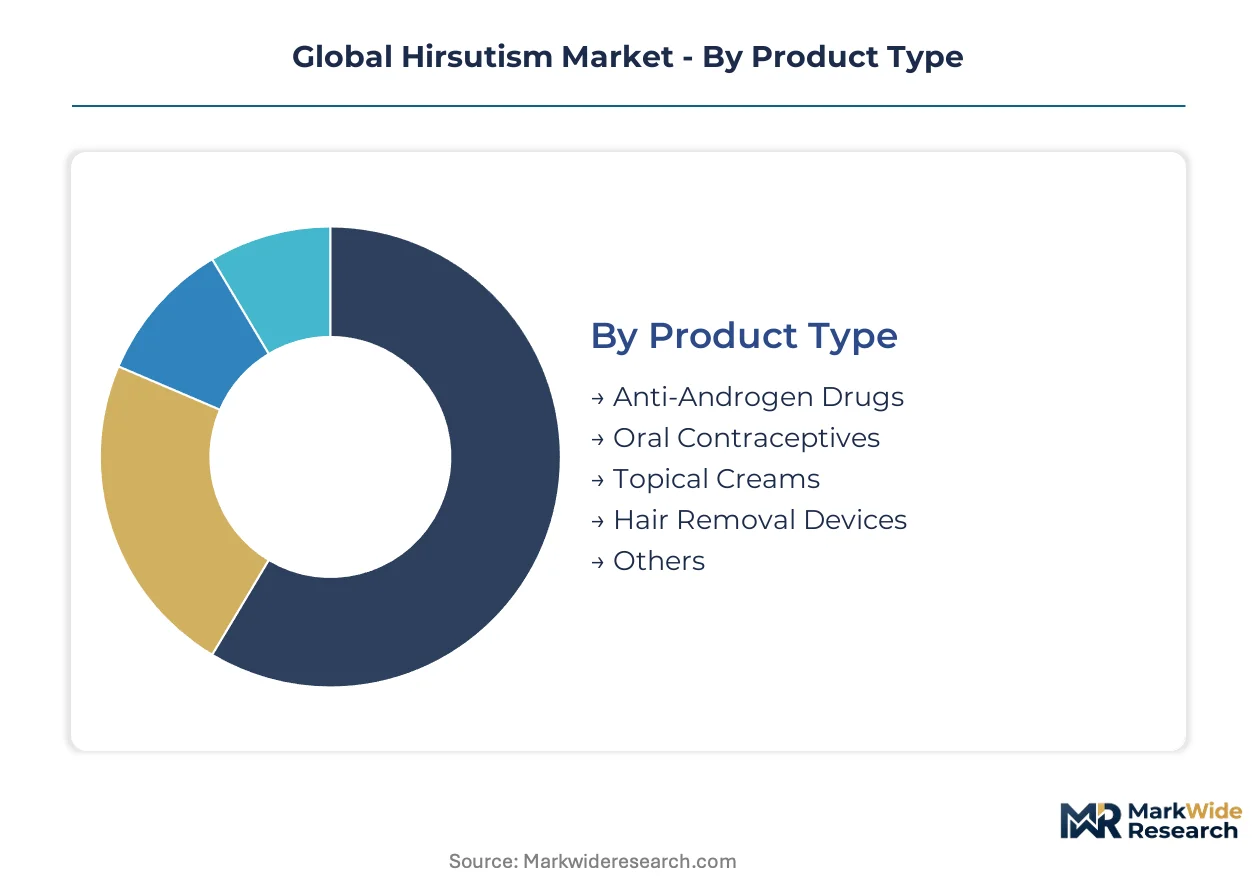
Hirsutism treatment markets fragment across therapeutic modalities and care settings, with pharmaceutical suppression and energy-based removal commanding distinct margin pools. Device manufacturers and drug developers pursue divergent commercial strategies as patient flows split between endocrinology-managed cases and cosmetic self-pay channels.
Product Type:
Mature pharmaceutical formats anchor volume while emerging device platforms capture premium positioning.
- Anti-Androgen Drugs:Spironolactone and finasteride formulations suppress androgen receptor activity at the follicular level. Demand concentrates in Germany and Japan where endocrinologists prescribe these as first-line PCOS-related interventions. Patent cliffs in South Asian markets compress originator margins.
- Hair Removal Devices:Diode and alexandrite laser systems deliver selective photothermolysis to melanin-rich follicles. Dermatology clinics in the United States and Japan deploy these for patients seeking durable cosmetic outcomes beyond pharmaceutical management. FDA and PMDA clearance pathways favor established manufacturers with longitudinal safety data.
- Oral Contraceptives:Estrogen-progestin combinations suppress ovarian androgen production through hypothalamic-pituitary feedback.
- Topical Creams:Eflornithine formulations inhibit ornithine decarboxylase to slow facial hair growth.
- Others:Adjunctive therapies including mechanical epilation and electrolysis retain niche application.
Anti-Androgen Drugs retain volume leadership; Hair Removal Devices hold the steepest expansion curve.
Therapy Area:
Application focus shifts from symptom masking toward underlying endocrine pathology as diagnostic capabilities improve.
- Polycystic Ovary Syndrome:Hyperandrogenism drives the largest patient flow into both pharmaceutical and device-based interventions. Endocrinology centers in the United States and Germany manage these cases through combined hormonal suppression and referral for laser hair removal.
- Cosmetic Treatment:Self-pay patients without diagnosed endocrine dysfunction pursue hair removal for psychosocial quality-of-life improvement. Medical spas in metropolitan Japan and Germany capture this demand through subscription-based treatment packages.
- Endocrine Disorders:Adrenal and ovarian tumors, Cushing's syndrome, and congenital adrenal hyperplasia require specialist endocrinology management.
- Idiopathic Hirsutism:Normal androgen levels with heightened follicular sensitivity present diagnostic challenges.
Polycystic Ovary Syndrome dominates patient volume; Cosmetic Treatment expands most quickly as stigma reduction drives self-referral.
End User:
Care setting determines reimbursement eligibility and treatment protocol complexity.
- Dermatology Clinics:Physician-supervised laser platforms command premium placement. Capacity expansion across United States metropolitan markets outpaces qualified technician supply.
- Endocrinology Centers:Hormonal evaluation and pharmaceutical management anchor the diagnostic pathway. Germany's integrated care networks route PCOS patients through these facilities before cosmetic referral.
- Cosmetic Surgery Units:Bundled service offerings combine pharmacological suppression with energy-based removal.
- Medical Spas:Technician-operated devices serve self-pay patients outside formal healthcare reimbursement.
Dermatology Clinics lead procedure volume; Medical Spas gain share fastest through direct-to-consumer marketing.
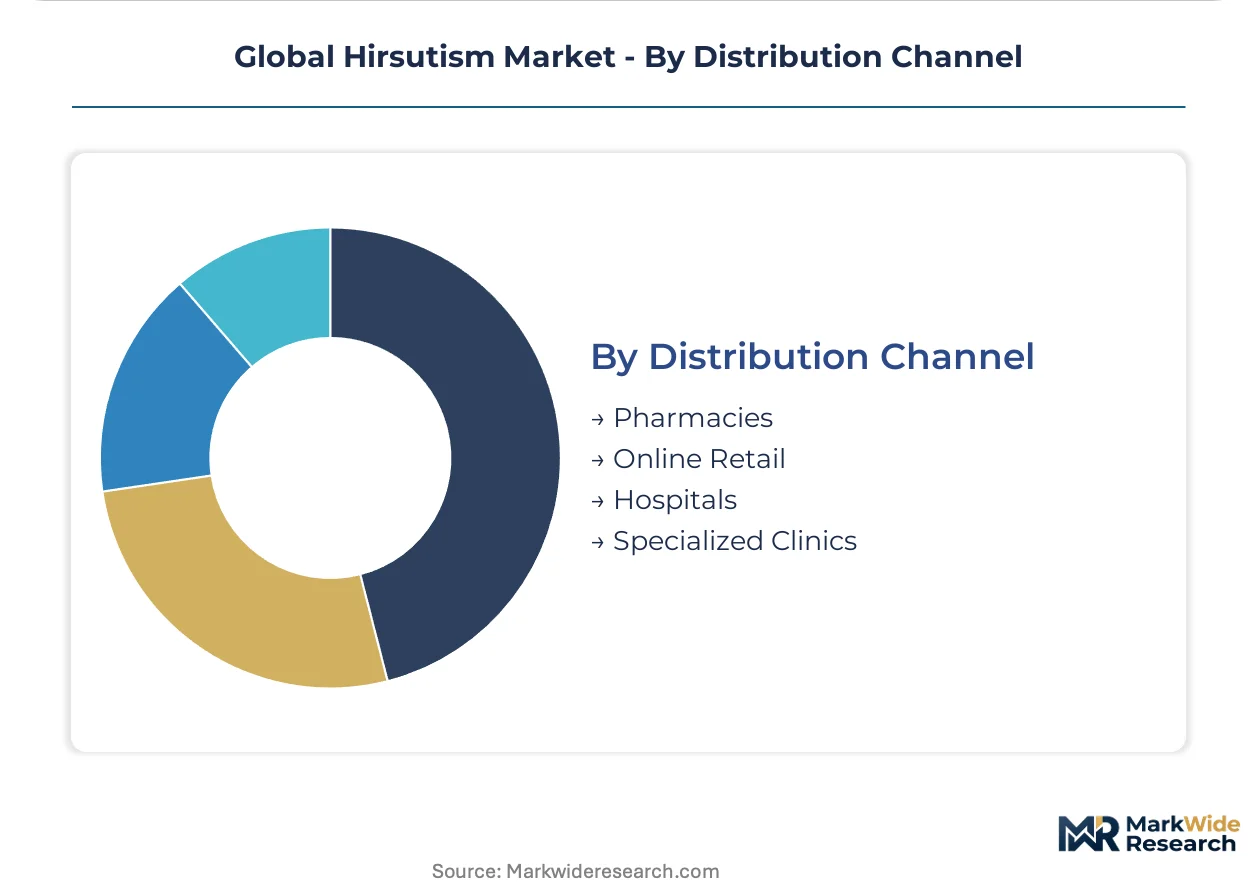
Distribution Channel:
Channel structure separates prescription-controlled pharmaceuticals from device and cosmetic product flows.
- Pharmacies:Anti-androgen and contraceptive dispensing requires prescription oversight. Japan's PMDA-regulated retail pharmacy network maintains strict hormonal product controls.
- Specialized Clinics:Device manufacturers bypass wholesale distribution to place laser platforms directly. Alma Lasers and Lumenis maintain field service organizations for United States clinical installations.
- Online Retail:At-home device licensing extends manufacturer reach into consumer channels.
- Hospitals:Academic medical centers manage complex endocrine cases requiring multidisciplinary coordination.
Pharmacies retain pharmaceutical volume leadership; Online Retail climbs the fastest for at-home device penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes device-based cosmetic interventions, Germany integrates pharmaceutical management into national care pathways, and Japan maintains strict regulatory oversight that filters market entry.
United States
Dermatology clinics in metropolitan markets drive laser platform deployment as self-pay cosmetic volumes expand. FDA premarket notification requirements for energy-based devices have intensified clinical evidence standards, extending clearance timelines for new entrants. The Dallas-Houston corridor and Southern California clusters concentrate the highest density of physician-supervised treatment capacity.
Germany
Integrated care networks route polycystic ovary syndrome patients through endocrinology centers before cosmetic referral, sustaining pharmaceutical volume leadership. The EU Medical Device Regulation reclassification imposes stricter conformity assessment on aesthetic energy devices entering the German market. Bavaria and North Rhine-Westphalia host the densest concentrations of academic medical centers managing complex endocrine cases.
Japan
PMDA parallel clinical evidence standards with FDA and Health Canada enable manufacturers to scale across multiple continents without duplicative trials. The national health insurance framework excludes most cosmetic interventions, channeling demand toward self-pay medical spas in Tokyo and Osaka. Kanto region clinics command premium placement for diode and alexandrite laser systems.
India
Price-sensitive markets in South Asia and Southeast Asia concentrate demand for oral anti-androgen formulations where generic competition compresses originator margins. CDSCO regulates hormonal products through prescription controls that vary across state-level pharmacy enforcement. Maharashtra and Gujarat pharmaceutical clusters manufacture active pharmaceutical ingredients for regional formulation.
United Kingdom
Mixed public-private reimbursement creates heterogeneous access to hirsutism therapies across NHS trusts and private dermatology networks. MHRA alignment with EU MDR standards maintains elevated device quality requirements post-Brexit. London and Southeast England concentrate both NHS endocrinology referral centers and private cosmetic surgery units.
Global Hirsutism Market Competitive Landscape
Capability concentration sits with specialized device manufacturers holding longitudinal safety data; scale advantage sits with diversified pharmaceutical incumbents with established distribution infrastructure. The market structures around three tiers: premium laser platform developers, mid-market pharmaceutical formulators, and emerging at-home device licensors. Consolidation pressure operates through regulatory compliance cost absorption and direct-to-consumer channel disintermediation.
Within the premium device tier, Lumenis Inc. and Alma Lasers Ltd. occupy positions defined by clinical installed base extension into consumer channels. Ajanta Pharma exemplifies the pharmaceutical formulator archetype competing across price-sensitive emerging markets. Cynosure Inc. and Cutera Inc. sit within the specialist aesthetic energy device segment where FDA and PMDA clearance portfolios determine geographic scalability.
| Leading Market Players |
|---|
| Lumenis Inc. |
| Alma Lasers Ltd. |
| Cynosure Inc. |
| Cutera Inc. |
| Ajanta Pharma |
| Nisim Inc. |
| Alpaya Dermaceuticals |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in diode laser manufacturing across East Asian production clusters is pushing device manufacturers toward long-term component offtake agreements and premium pricing for guaranteed supply. This utilization squeeze cascades into dermatology clinic procurement, where FDA-cleared platforms command placement premiums against uncertified alternatives.
Pricing Analysis
Long-term service contracts dominate hirsutism device procurement, with clinics locking in multi-year maintenance bundles alongside hardware placement. Price differentiation rests on FDA clearance tier and technician training depth, with PMDA-parallel certifications fetching additional premiums. Cost compression in oral anti-androgen generics is intensifying because Indian and Chinese API manufacturers have scaled finasteride and spironolactone output. Price-sensitive patients in South Asia gravitate toward unbranded pharmaceutical alternatives, while Japanese and German clinics absorb premium device pricing for liability protection.
Supply Chain Analysis
High-powered diode arrays draw from concentrated manufacturing in China, South Korea, and Japan, with precision optical systems resting on German and Japanese component feeds. Raw material dependencies span gallium arsenide wafers, rare-earth doped laser crystals, and medical-grade aluminum housings. Single-source vulnerability concentrates in epitaxial wafer growth capacity, where two East Asian suppliers control majority share. Distribution runs through manufacturer field service organizations for clinical installations, bypassing wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from AI-guided at-home devices that narrow the efficacy gap with clinical platforms. Defense requires building regulatory moats faster than consumer technology erodes professional channel value.
For Market Incumbents: Build longitudinal safety data moats through post-market surveillance investments that FDA and PMDA recognize for clearance pathway acceleration. Backward integration into diode array manufacturing reduces exposure to East Asian supply chokepoints. Channel control through exclusive technician certification programs locks clinic loyalty against lower-cost device competitors. For New Entrants and Emerging Players: Rural telemedicine corridors in the United States present underpenetration where remote endocrinology consultations can unlock anti-androgen prescription volumes outside metropolitan dermatology clusters. Direct-to-consumer subscription models bypass clinic gatekeepers entirely, capturing millennial patients seeking discreet symptom management. Go-to-market positioning should emphasize PMDA-FDA parallel pathway efficiency for multi-continental scaling without duplicative trials. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across laser device manufacturing as EU MDR compliance costs filter marginal players from European market access. Long-term viability favors manufacturers with installed base extension strategies into consumer channels rather than pure hardware plays. Acquisition targets should demonstrate software-enabled treatment protocol differentiation and recurring revenue attachment rates. Watch for CDSCO enforcement tightening in Indian pharmaceutical distribution as signal for generic margin compression inflection.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA-FDA Parallel Clearance Pathway | Enables manufacturers to scale diode laser platforms across Japan and North America without duplicative clinical trials. |
| Technician Certification Program Expansion | Addresses qualified workforce bottlenecks constraining dermatology clinic capacity growth in United States metropolitan markets. |
| Subscription-Based At-Home Device Licensing | Captures recurring revenue from millennial and Gen-Z demographics seeking ongoing hirsutism symptom management. |
| Backward Integration into Diode Array Manufacturing | Reduces vulnerability to concentrated East Asian supply clusters and trade friction exposure. |
| Telemedicine-Integrated Prescription Models | Expands anti-androgen therapy access in underserved rural markets within developed healthcare systems. |
Research Methodology
A spread of perspectives from dermatology clinic operators, endocrinology practice administrators, laser device biomedical engineers, pharmaceutical regulatory affairs leads, and medical spa purchasing managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, PMDA approval databases, EU MDR conformity assessment records, and hospital procurement contract disclosures. Bottom-up patient flow modeling triangulated against top-down manufacturer shipment data.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation modeled by therapeutic modality, care setting, regulatory jurisdiction cluster, and patient referral pathway. CAGRs were derived from installed base growth rates and replacement cycle analysis. Forecast inputs incorporated polycystic ovary syndrome diagnosis trend trajectories and laser device technology substitution curves.
Practitioners should monitor EU MDR enforcement tightening, PMDA parallel pathway harmonization delays, and Indian CDSCO generic pricing interventions for early signals of forecast revision. Cross-checking against CMS Medicare cosmetic procedure coding changes and Japanese national health insurance reimbursement updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Androgenetic Alopecia Market
Dermatology
Lentigo Maligna Melanoma Therapeutic Market
Dermatology
Inflammatory Skin Diseases Treatment Market
Dermatology
Microneedling Market
Dermatology
Chronic Spontaneous Urticaria Market
Dermatology
Global Dermatology Cro Market
Dermatology
Dermatology Drugs Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Homecare Dermatology Energy-Based Devices Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Dermal Facial Fillers Market
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
Hyperpigmentation Disorder Treatment Market
Dermatology
Impetigo Treatment Market
Dermatology
Global Onychomycosis Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market