
 Heavy Power Surgical Tools Market | 2026-2036
Heavy Power Surgical Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Power Surgical Tools Market Outlook
Surgeon training capacity for high-torque power tool operation is reorganizing how hospitals evaluate procurement contracts. Stryker Corporation leverages integrated power console ecosystems to dominate orthopedic suite configurations. Medtronic plc sustains cardiothoracic application leadership through specialized saw and drill attachments. Zimmer Biomet anchors reconstruction procedure workflows with shaver systems designed for revision joint surgeries.
Heavy power surgical tools are electromechanical and pneumatic instruments delivering rotational or oscillating force above 50,000 RPM for bone resection, tissue debridement, and sternal division in sterile operative fields. These systems integrate autoclavable handpieces with modular battery packs or nitrogen-driven turbines to maintain cutting precision under irrigation. Pneumatic technology leads unit shipments in trauma centers requiring sustained torque for prolonged orthopedic cases, while battery-operated platforms capture fastest-growing demand as ambulatory surgery centers eliminate tethered gas line infrastructure. Orthopedics commands the largest application share by procedure volume, though neurosurgery applications generate premium margin pools due to smaller batch production and tighter tolerance specifications.
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements shape product development timelines and market access costs for heavy power surgical tool manufacturers. ISO 13485 quality management standards govern supply chain qualification across component suppliers in Germany, the United States, and Japan. Stakeholders must monitor how battery chemistry regulations from the EU Battery Directive and state-level surgical smoke evacuation mandates in California and New York reshape handpiece design requirements and aftermarket service obligations.
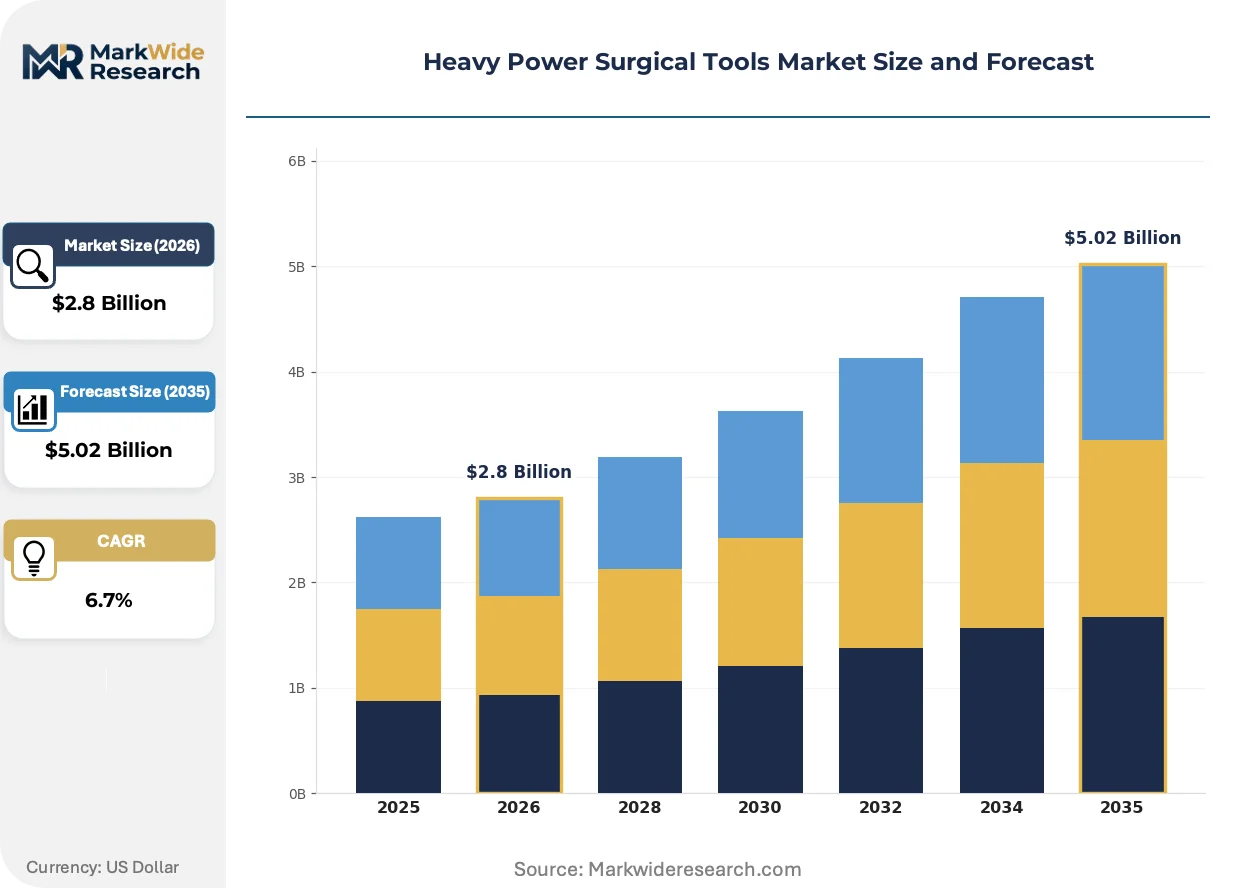
Market Dynamics
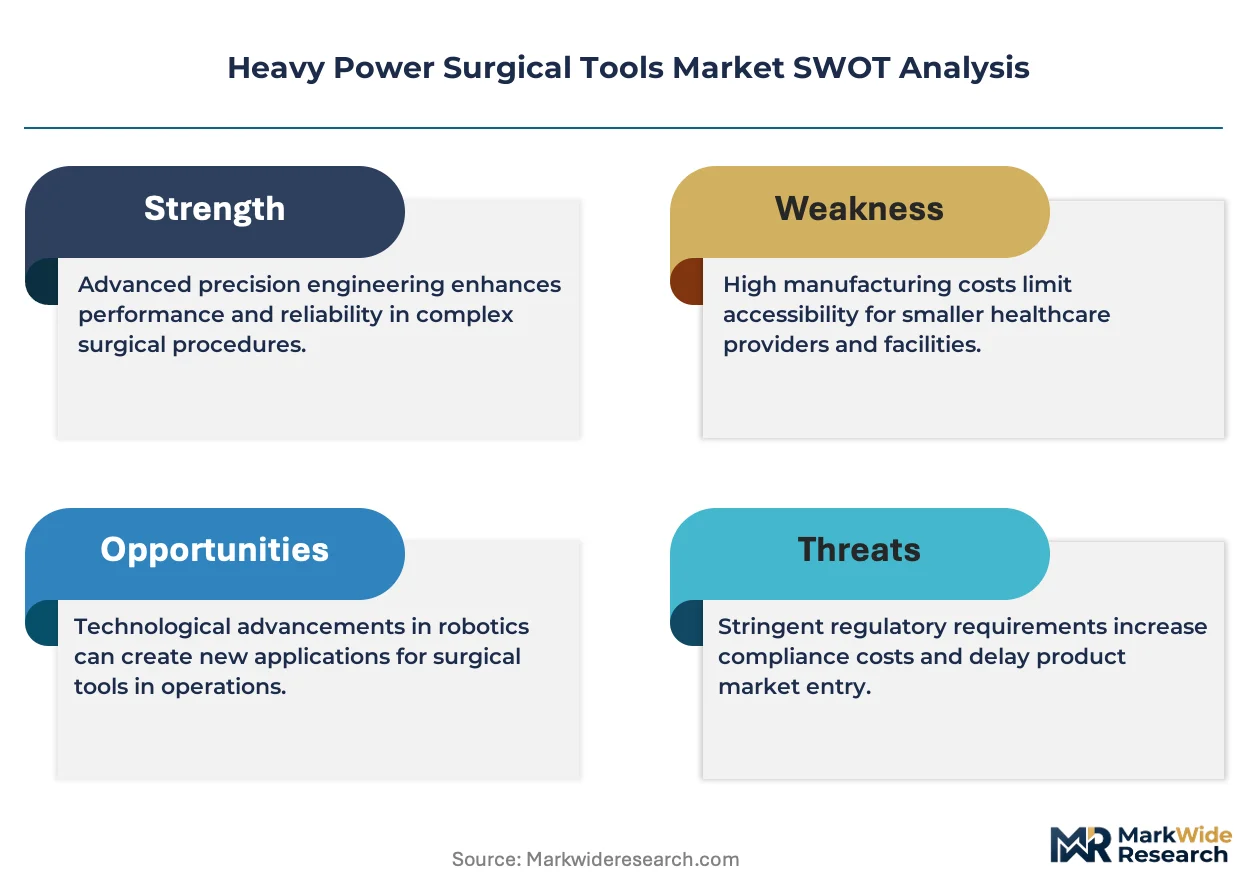
Battery chemistry migration from nickel-cadmium to lithium-ion is restructuring procurement economics for orthopedic suites, compressing total cost of ownership while elevating thermal management requirements for sterile field compatibility.
Growth Catalysts
- EU MDR Class IIa certification pathways:Elevated barrier requirements are filtering low-quality entrants and consolidating demand around qualified manufacturers with established quality management systems.
- Ambulatory surgery center infrastructure:Elimination of tethered nitrogen gas lines in outpatient facilities is accelerating battery-operated platform adoption for same-day joint procedures.
- Revision joint surgery volumes:Expanding patient populations requiring secondary orthopedic interventions are driving shaver system demand with specialized debridement capabilities.
Market Restraints
- Raw material concentration:Rare earth magnet supply dependence on Chinese processing facilities creates input cost volatility for high-torque motor assemblies.
- EU Battery Directive compliance:Extended producer responsibility mandates for lithium-ion cell recycling are elevating aftermarket service infrastructure costs.
- Pneumatic system entrenchment:Trauma center capital investment in nitrogen infrastructure limits conversion rates to cordless alternatives despite operational advantages.
Strategic Opportunities
- Neurosurgery precision applications:Smaller-batch production of sub-50,000 RPM instruments for cranial access procedures commands premium margin pools underserved by orthopedic-focused suppliers.
- California surgical smoke evacuation mandates:State-level requirements for integrated suction systems are creating design specification advantages for compliant handpiece architectures.
- Telemetric performance monitoring:Convergence of embedded sensors with cloud-based asset management is enabling predictive maintenance contracts that extend customer lifetime value.
Industry Challenges
- Surgeon retraining requirements:High-torque battery tool operation demands different tactile feedback protocols, slowing equipment turnover in teaching hospitals with established fellowship programs.
- ISO 13485 supply chain qualification:Multi-year vendor certification timelines for German, Japanese, and United States component suppliers compress product development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Power Surgical Tools Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drills, Saws, Shavers, Cutters Technology: Pneumatic, Electric, Battery-operated, Hydraulic End User: Hospitals, Surgical Centers, Ambulatory Surgery Centers, Specialty Clinics Application: Orthopedics, Cardiothoracic, Neurosurgery, General Surgery |
| Companies Covered | Stryker Corporation, Medtronic plc, Zimmer Biomet Holding Inc., CONMED Corporation, B. Braun Melsungen AG, Johnson & Johnson, Arthrex, Inc., De Soutter Medical, MicroAire Surgical Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Power Surgical Tools Market Strategic Shifts
Electrification of surgical power systems is fragmenting established procurement patterns while creating new competitive battlegrounds around battery ecosystem integration and sterile field thermal management.
Brushless DC motor architecture is bifurcating the high-torque instrument category. Ambulatory surgery centers in the United States are adopting these platforms at twice the rate of academic medical centers. The technology is bifurcating vendor strategies between premium integrated console ecosystems and modular handpiece-only suppliers.
EU MDR technical documentation requirements are extending product registration timelines by eighteen to thirty-six months for legacy device recertifications. Manufacturers are consolidating product portfolios to focus resources on highest-volume SKUs. Orthopedic power tool lines face disproportionate impact as Class IIa reclassification captures previously exempt accessories.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases. Third-party sterilization validation providers in Germany and the United States are capturing maintenance revenue previously retained by original equipment manufacturers. This disintermediation is most visible in multi-hospital systems negotiating enterprise-wide power tool standardization.
Heavy Power Surgical Tools Market Segmentation
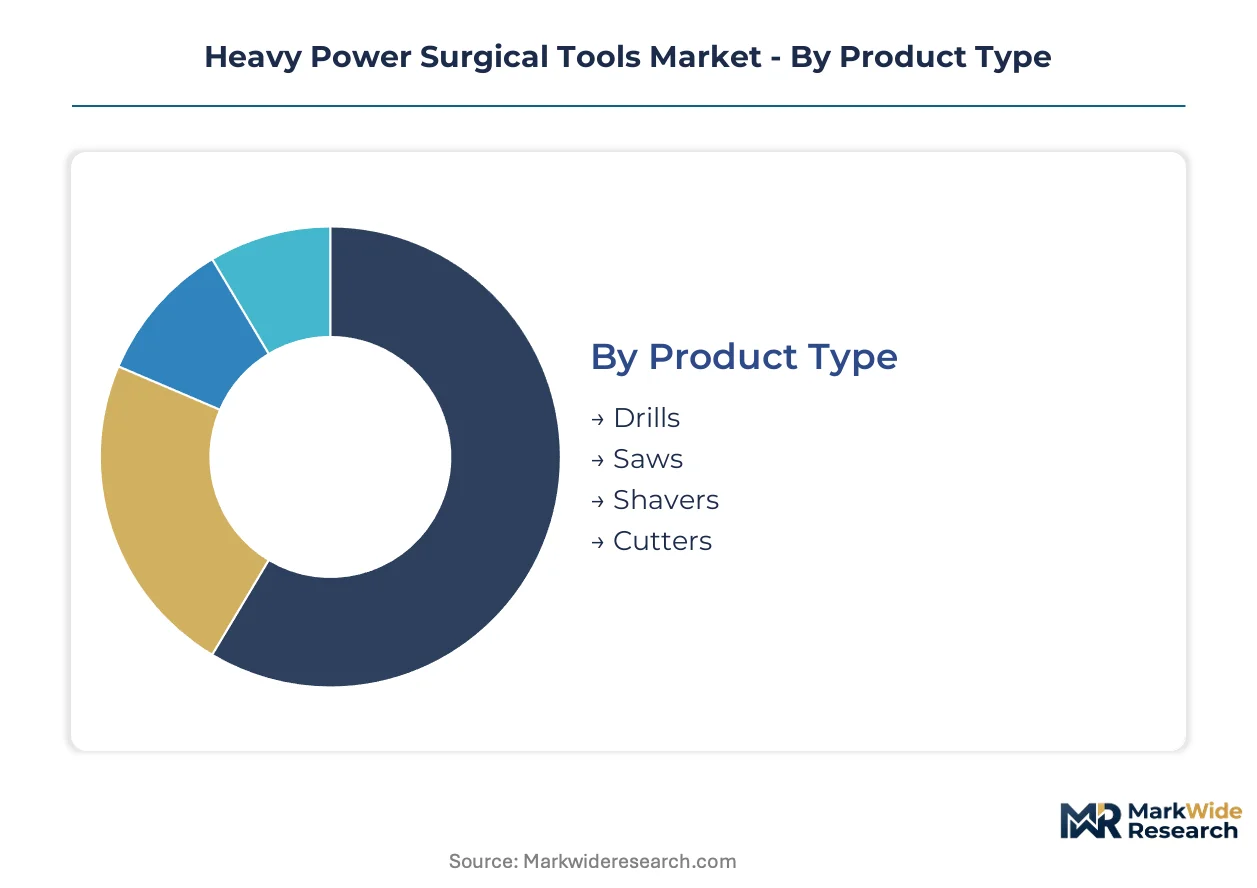
Segmentation in heavy power surgical tools reveals distinct procurement patterns across technology platforms and care settings. Each dimension exposes different margin structures, regulatory burdens, and customer loyalty dynamics that reshape competitive positioning.
Product Type:
Domestic production concentrates drills and saws in Germany and the United States for regional hospital supply chains. Shavers and cutters flow through more export-dependent manufacturing networks serving multiple continents.
- Drills:High-torque rotary instruments with modular chuck systems accommodate drill bits up to 6mm diameter for cortical bone penetration. Academic medical centers in the United States anchor procurement volumes for trauma reconstruction cases requiring sustained RPM stability under irrigation. Battery-operated variants from domestic suppliers are displacing pneumatic legacy systems in mid-tier hospitals.
- Saws:Oscillating and sagittal blade platforms deliver reciprocating motion for precise osteotomy cuts in joint replacement procedures. German hospital systems maintain entrenched demand for nitrogen-driven units, while ambulatory surgery centers in the United States prioritize cordless alternatives to eliminate gas line infrastructure costs. Sternal division attachments for cardiothoracic applications command premium pricing.
- Shavers:Rotating burr systems with integrated suction channels enable soft tissue debridement in arthroscopic procedures. Demand clusters in revision joint surgery workflows.
- Cutters:Guillotine and rotary blade configurations address specialized tissue resection requirements in general surgery suites. Procurement volumes trail orthopedic-focused alternatives.
Drills command the established base. The steepest expansion runs through shavers.
Technology:
Cost tier stratification separates capital-intensive pneumatic infrastructure from battery platforms with lower total cost of ownership. Electric corded systems occupy a narrowing mid-market position.
- Pneumatic:Nitrogen turbine systems deliver sustained torque above 80,000 RPM for prolonged orthopedic cases without thermal degradation. Trauma centers in Germany and trauma networks across the United States retain installed base advantages despite higher maintenance burdens. EU F-Gas Regulation compliance adds operational complexity for gas handling infrastructure.
- Battery-operated:Lithium-ion cell architectures with brushless DC motors achieve sterile field compatibility through advanced thermal management. Ambulatory surgery centers in the United States adopt these platforms at accelerated rates to support same-day discharge protocols. California and New York surgical smoke evacuation mandates favor integrated suction designs.
- Electric:Corded mains-powered systems persist in budget-constrained hospital systems with existing sterilization workflows for tethered handpieces.
- Hydraulic:Fluid-pressure actuation serves niche neurosurgery applications requiring extreme precision at sub-30,000 RPM ranges with minimal vibration transmission.
Pneumatic technology retains the revenue base. Battery-operated platforms are climbing the fastest.
End User:
Customer type determines service contract structures, with integrated delivery networks demanding enterprise-wide standardization against specialty clinic fragmentation.
- Hospitals:Multi-specialty institutions with centralized sterile processing departments manage mixed fleets of pneumatic and battery platforms. Orthopedic departments in the United States drive replacement cycles.
- Surgical Centers:Multi-procedure facilities prioritize cross-functional tool compatibility across orthopedic and general surgery service lines.
- Ambulatory Surgery Centers:Outpatient joint replacement hubs in the United States eliminate nitrogen infrastructure entirely. Battery ecosystem standardization reduces per-procedure setup time.
- Specialty Clinics:Concentrated orthopedic and sports medicine practices favor modular handpiece procurement with third-party maintenance contracts.
Hospitals command the established base. Ambulatory surgery centers represent the fastest-growing trajectory.
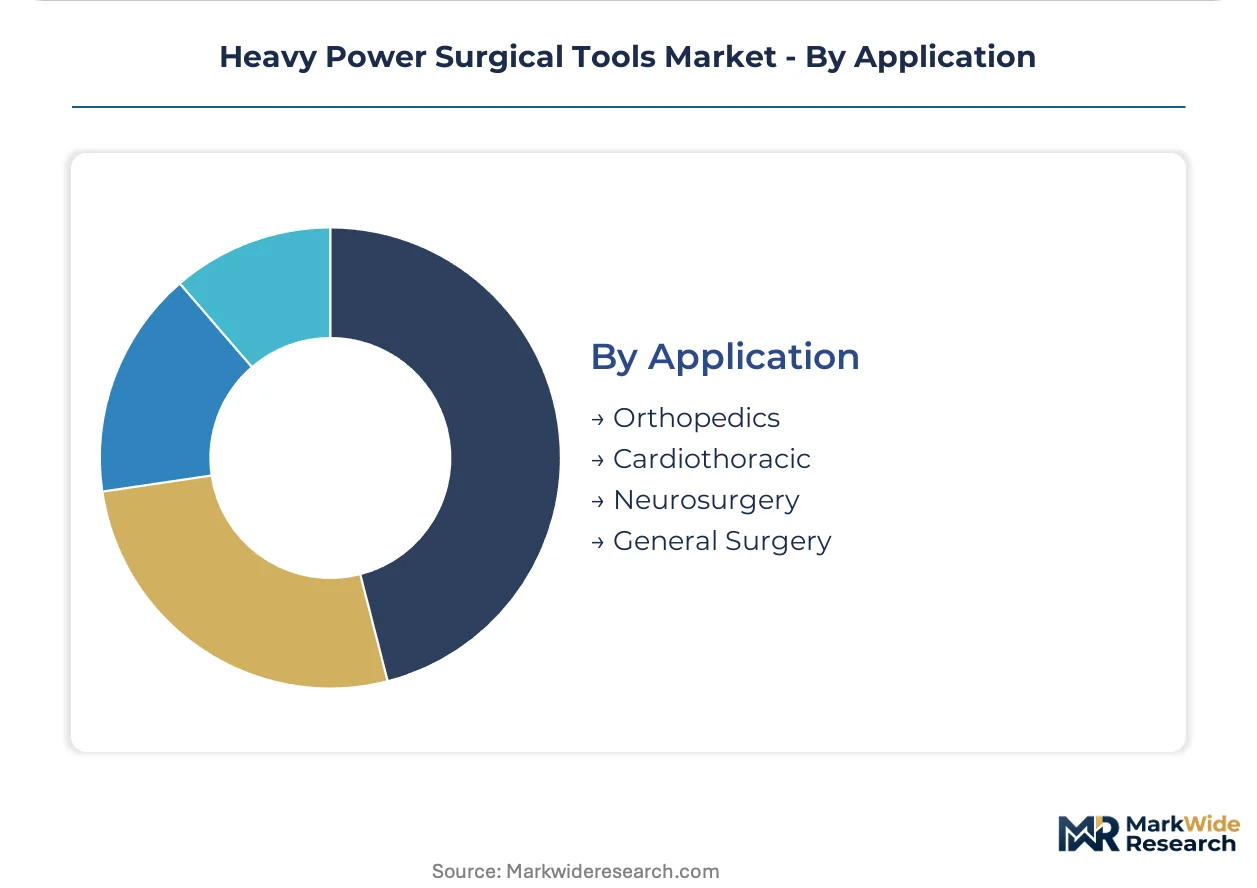
Application:
Volume concentration in orthopedics contrasts with margin concentration in neurosurgery, where batch sizes compress and tolerance specifications tighten.
- Orthopedics:Joint replacement and trauma procedures consume the highest unit volumes of drills, saws, and shavers. Revision surgery workflows in the United States and Germany drive recurring demand for specialized debridement attachments.
- Cardiothoracic:Sternal division and rib resection applications require oscillating saw platforms with integrated irrigation. Medtronic plc maintains attachment ecosystem dominance.
- Neurosurgery:Cranial access instruments operate below 50,000 RPM with sub-millimeter precision tolerances. Smaller production batches and tighter ISO 13485 quality requirements generate premium margin pools underserved by high-volume orthopedic suppliers.
- General Surgery:Soft tissue resection and sternal wire removal applications utilize modified orthopedic platforms with procedure-specific attachments.
Orthopedics commands the established base. Neurosurgery offers the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways in the United States establish the regulatory baseline that shapes product development economics across all major supply markets. Hospital procurement departments in three countries drive volume concentration for heavy power surgical tools.
United States
Ambulatory surgery centers in Texas and Florida are eliminating nitrogen infrastructure for same-day joint procedures. California and New York surgical smoke evacuation mandates from state health departments are reshaping handpiece design specifications. The Greater Boston cluster anchors orthopedic research partnerships between teaching hospitals and device manufacturers.
Germany
Trauma centers in North Rhine-Westphalia retain entrenched demand for pneumatic systems despite battery platform advances. EU MDR Class IIa certification requirements from BfArM extend product registration timelines for legacy device recertifications. The Stuttgart-Tübingen corridor concentrates precision motor assembly operations for high-torque surgical instruments.
China
Domestic hospital systems are scaling procurement of battery-operated platforms to address elective surgery backlogs in tier-one cities. NMPA medical device registration rules are elevating quality management requirements for local manufacturers. The Suzhou-Wuxi industrial zone hosts component suppliers qualified under ISO 13485 standards.
Japan
Academic medical centers in Kansai and Kanto regions maintain mixed fleets of pneumatic and battery platforms for orthopedic workflows. PMDA quality management system inspections govern supply chain qualification for imported surgical power tools. The Nagoya-Chubu corridor specializes in rare earth magnet processing for high-torque motor assemblies.
United Kingdom
NHS procurement frameworks are consolidating supplier contracts around enterprise-wide power tool standardization. MHRA post-market surveillance requirements align with EU MDR technical documentation standards. The Cambridge-Oxford-London triangle anchors surgeon training programs for high-torque battery tool operation protocols.
Heavy Power Surgical Tools Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in heavy power surgical tools, with console ecosystem providers commanding orthopedic suite configurations and attachment-focused suppliers anchoring procedure-specific workflows. The market structure favors incumbents with established quality management systems and multi-year hospital service contracts. Three archetypes dominate: integrated platform vendors with sterilization-compatible battery ecosystems, specialized attachment manufacturers for cardiothoracic and neurosurgery applications, and regional fabricators serving domestic hospital supply chains. Competitive moves concentrate on portfolio consolidation around highest-volume SKUs and predictive maintenance contract structures that extend customer lifetime value.
Among integrated platform vendors, Stryker Corporation and Medtronic plc occupy positions exemplifying console-centric competitive strategy, while Zimmer Biomet represents the specialized attachment archetype for revision joint surgery workflows. These three companies anchor distinct procurement patterns across hospital systems, with Stryker leveraging power console ecosystems, Medtronic sustaining cardiothoracic application leadership, and Zimmer Biomet targeting reconstruction procedure workflows. Their collective positioning illustrates how vendor selection in heavy power surgical tools increasingly hinges on ecosystem integration rather than standalone handpiece performance.
| Leading Market Players |
|---|
| Stryker Corporation |
| Medtronic plc |
| Zimmer Biomet Holding Inc. |
| CONMED Corporation |
| B. Braun Melsungen AG |
| Johnson & Johnson |
| Arthrex, Inc. |
| De Soutter Medical |
| MicroAire Surgical Instruments |
| Others |
Value Chain & Pricing Dynamics
Long-term service bundling contracts with integrated delivery networks lock in multi-year price visibility while securing sterilization-compatible battery ecosystem access for orthopedic suites. These arrangements concentrate procurement leverage among United States hospital systems and German trauma networks, compressing margin flexibility for modular handpiece-only suppliers.
Pricing Analysis
Geographic price spreads of 15-25% separate German pneumatic system premiums from United States ambulatory surgery center battery platform discounts. Three-tier pricing structure across premium integrated console, standard modular handpiece, and economy corded electric levels stratifies by FDA 510(k) clearance tier and ISO 13485 certification depth. Cost compression in mid-tier battery platforms intensifies because lithium-ion cell producers compete for surgical-grade thermal management contracts. Academic medical centers exhibit lowest price sensitivity due to fellowship training infrastructure lock-in, while specialty clinics negotiate aggressively on third-party maintenance terms.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for rare earth magnet shipments bound for German and Japanese motor assembly facilities. Component manufacturing concentrates in Germany, the United States, and Japan, with final handpiece assembly drawing from Chinese lithium-ion cell suppliers and Swiss precision bearing fabricators. Single-source vulnerability in neodymium magnet processing creates exposure to export license restrictions. Distribution runs through GPO contracts in United States hospital systems and direct OEM relationships in German trauma networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as ambulatory surgery center proliferation splinters procurement authority away from centralized hospital purchasing committees. This demand-side shift creates niches for modular suppliers with rapid battery ecosystem deployment capabilities.
For Market Incumbents: Fortify console ecosystem lock-in by embedding predictive maintenance telemetry that extends hospital service contract durations. Capture backward integration into lithium-ion sterilization-compatible cell production to offset raw material volatility from Chinese processing concentration. Priority lever rests on ISO 13485 supply chain qualification acceleration to compress competitor product development timelines. For New Entrants and Emerging Players: FDA 510(k) predicate device pathways offer fastest regulatory clearance for battery-operated drill platforms targeting United States outpatient joint replacement hubs. Neurosurgery precision instruments below 50,000 RPM represent the most penetrable white-space, with premium margin pools underserved by orthopedic-focused incumbents. Go-to-market angle should emphasize third-party sterilization validation partnerships that bypass OEM service infrastructure requirements. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors vertically integrated platform vendors with captive battery ecosystem control. Long-term viability over 5-10 year windows hinges on telemetric performance monitoring capabilities that transform capital equipment sales into recurring revenue streams. Acquisition target archetype: mid-cap specialists with EU MDR Class IIa certification depth and established German trauma center relationships. Signal to watch: California and New York surgical smoke evacuation mandate compliance rates as inflection indicator for integrated suction handpiece adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Pathway | BfArM technical documentation requirements filter low-quality entrants and consolidate demand around qualified manufacturers. |
| Hospital System Partnership | Enterprise-wide power tool standardization contracts with United States IDNs capture multi-year procurement commitments. |
| Software Companion Development | Telemetric performance monitoring platforms enable predictive maintenance contracts that extend customer lifetime value. |
| Reimbursement Strategy | CMS outpatient procedure coding alignment for same-day joint replacement drives ambulatory surgery center battery platform adoption. |
| CE Marking Pathway | MDR technical documentation consolidation around highest-volume SKUs optimizes regulatory resource allocation for orthopedic power tool lines. |
Study Parameters
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract registries preceded structured interviews with orthopedic department heads, biomedical engineering directors, GPO contracts managers, and sterile processing department leads. Secondary validation drew from ISO 13485 certification records, lithium-ion battery chemistry safety standards, and surgical smoke evacuation mandate compliance filings. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market size estimation.
Variance decomposition across technology platform, end-user setting, and application segments isolated growth contribution drivers over the projection horizon. Segmentation dimensions modeled include product type, power source architecture, care setting tier, and surgical specialty workflow. CAGRs derived from logistic adoption curves for battery platform displacement of pneumatic systems, calibrated against ambulatory surgery center infrastructure buildout rates and revision joint surgery volume trajectories.
Underlying assumptions cover lithium-ion thermal management certification stability, rare earth magnet supply continuity, and EU Battery Directive compliance cost pass-through elasticity, with deviation risk concentrated in Chinese export license policy shifts and state-level surgical smoke mandate expansion timing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Hemostatic Instruments Market
Surgical Instruments
Skin Graft Blades Market
Surgical Instruments
Gynecology Surgical Instruments Market
Surgical Instruments
Surgical Visualization Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Laparoscopic Gynecological Procedures Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Knee Surgical Impactor Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
Cold Disposable Biopsy Forceps Market
Surgical Instruments
Surgical Blades Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Disposable Spinal Instruments Market
Surgical Instruments
Electrosurgery Market