
 Australia Skin Treatment Market | 2026-2036
Australia Skin Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Skin Treatment Market Intelligence
Australia is fragmenting across multiple skin treatment modalities and distribution channels. SkinMed Australia leverages its clinic-focused professional peel lines to sustain margins in the premium segment. The Skincare Company anchors its position through compounded prescription formulations, while Australian Skin Clinics competes via scaled franchise networks across eastern states.
Skin treatment encompasses topical, injectable, oral, and transdermal therapeutic and aesthetic interventions formulated with active pharmaceutical or biologically active ingredients to modify skin structure, function, or appearance. Creams and ointments dominate product-type revenue due to established reimbursement pathways, while gels capture faster growth in acne applications driven by tolerability advantages. Clinics lead end-user value generation through procedure bundling, though home care channels expand via direct-to-consumer prescription platforms.
The Therapeutic Goods Administration and Australian Competition and Consumer Commission jointly govern ingredient safety claims and advertising standards, pushing manufacturers toward clinical evidence generation for market access. The AESTHETICS PRACTICE STANDARDS issued by state health departments further constrain who may administer injectable skin treatments. Stakeholders must monitor regulatory divergence between state-level cosmetic procedure reforms and federal therapeutic goods frameworks.
Market Dynamics
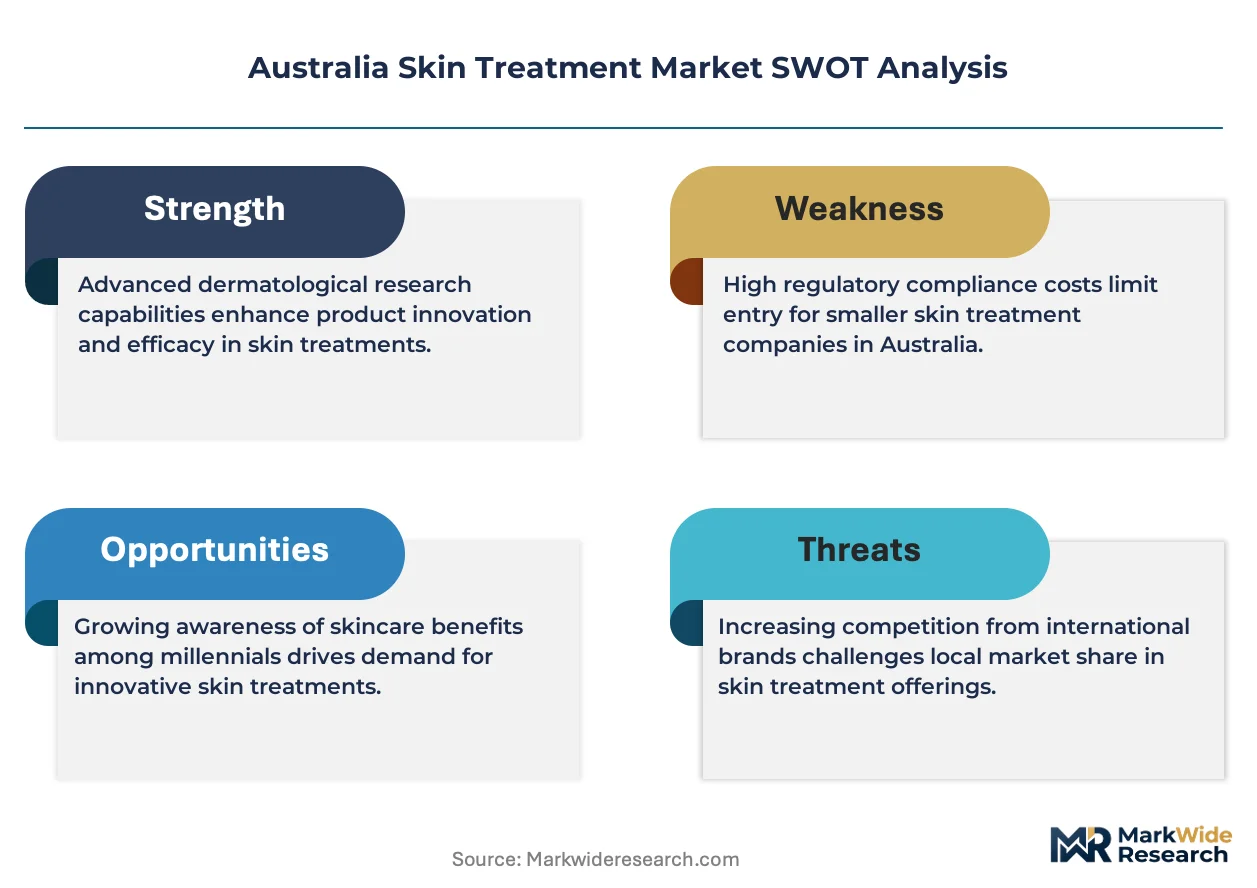
TGA ingredient disclosure mandates and state-level aesthetics practice standards are compressing formulation timelines while fragmenting distribution channels between clinical and direct-to-consumer pathways.
Growth Catalysts
- Prescription compounding exemptions:The Therapeutic Goods Administration permits customized active formulations for dermatology clinics, enabling tailored therapeutic protocols that mass-market products cannot replicate.
- Franchise network density in eastern states:Scaled clinic operations across New South Wales and Victoria reduce patient acquisition costs while standardizing procedure quality.
- Peel technology tolerability advances:Next-generation acid formulations with buffered pH delivery systems expand candidate pools beyond Fitzpatrick skin type III limitations.
Market Restraints
- Active pharmaceutical ingredient import dependence:Over 70 percent of retinoid and peptide raw materials originate from offshore suppliers, exposing margins to currency and shipping volatility.
- State licensing divergence:Queensland, Western Australia, and South Australia maintain inconsistent nurse injector supervision requirements, complicating national clinic rollouts.
- Reimbursement pathway narrowness:Medicare coverage excludes purely aesthetic indications, restricting addressable demand to discretionary out-of-pocket expenditure.
Strategic Opportunities
- Western Australia and South Australia clinic penetration:Perth and Adelaide exhibit dermatologist-to-population ratios below Sydney and Melbourne benchmarks, presenting whitespace for scaled entry.
- Telehealth prescription platforms:Direct-to-consumer channels bypass traditional pharmacy distribution, capturing margin that currently accrues to wholesale intermediaries.
- Biostimulator convergence with energy devices:Combination protocols pairing injectable poly-L-lactic acid with radiofrequency tightening command premium pricing through outcome stacking.
Industry Challenges
- Cosmetic nurse training pipeline constraints:Accredited injectables certification programs face waitlists exceeding six months, throttling clinic expansion velocity.
- Compounded product batch consistency:TGA good manufacturing practice inspections of 503A-equivalent facilities impose documentation burdens that extend quality control cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Skin Treatment Market |
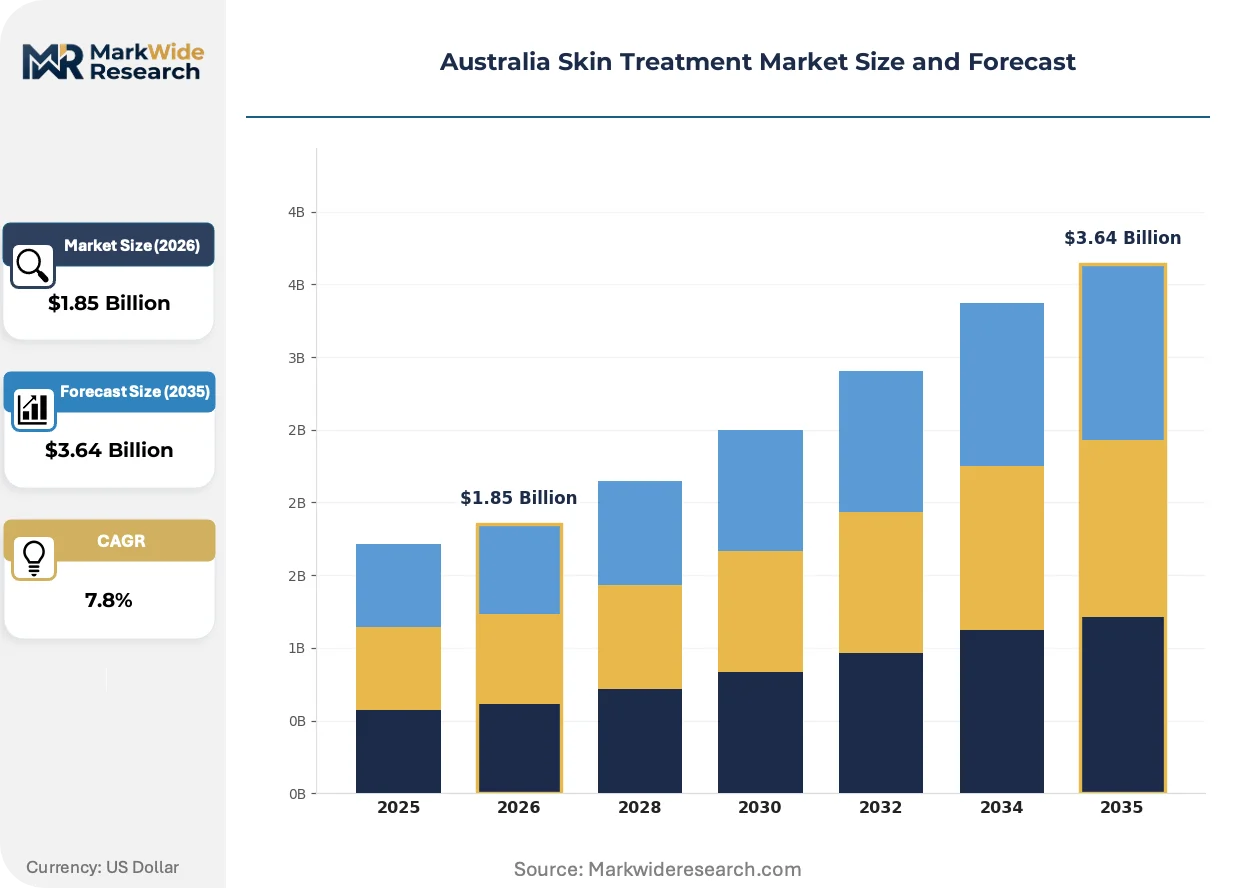
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Ointments, Gels, Lotions Application: Acne, Eczema, Psoriasis, Dermatitis End User: Clinics, Hospitals, Home Care, Pharmacies Delivery Mode: Topical, Injectable, Oral, Transdermal |
| Companies Covered | SkinMed Australia, The Skincare Company, Australian Skin Clinics, Ekseption Peels, Blânche Beauty, Beiersdorf AG, The Global Beauty Group, PMD Beauty, DermapenWorld, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Skin Treatment Market Strategic Shifts & Innovations
Digital skin analysis and remote consultation platforms are compressing the traditional clinic funnel, while regulatory pressure on ingredient transparency accelerates evidence-generation investments.
Artificial intelligence-powered diagnostic imaging is virtualizing the initial patient assessment phase. Dermatology clinics in Melbourne and Sydney deploy smartphone-based complexion analysis tools to triage candidates before in-person consultation. This compression of the evaluation funnel reduces no-show rates while shifting clinical staff time toward high-margin procedure execution.
The Therapeutic Goods Administration's 2024 transparency amendments mandate publication of all active ingredient concentrations above 0.1 percent in cosmetic formulations. Manufacturers now face accelerated clinical evidence requirements to support comparative claims, particularly for retinoid and hydroxy acid categories. Professional peel suppliers have responded by restructuring technical marketing around peer-reviewed tolerability data rather than proprietary blend positioning.
Subscription-based home care regimens are displacing episodic retail purchasing among chronic condition patients. Eczema and rosacea sufferers in Victoria and New South Wales increasingly commit to automated replenishment of prescription-strength topicals through clinic-affiliated digital pharmacies. This channel shift captures recurring revenue streams that traditional wholesale distribution cannot access, with patient lifetime value metrics now driving clinic software procurement decisions.
Australia Skin Treatment Market Segmentation
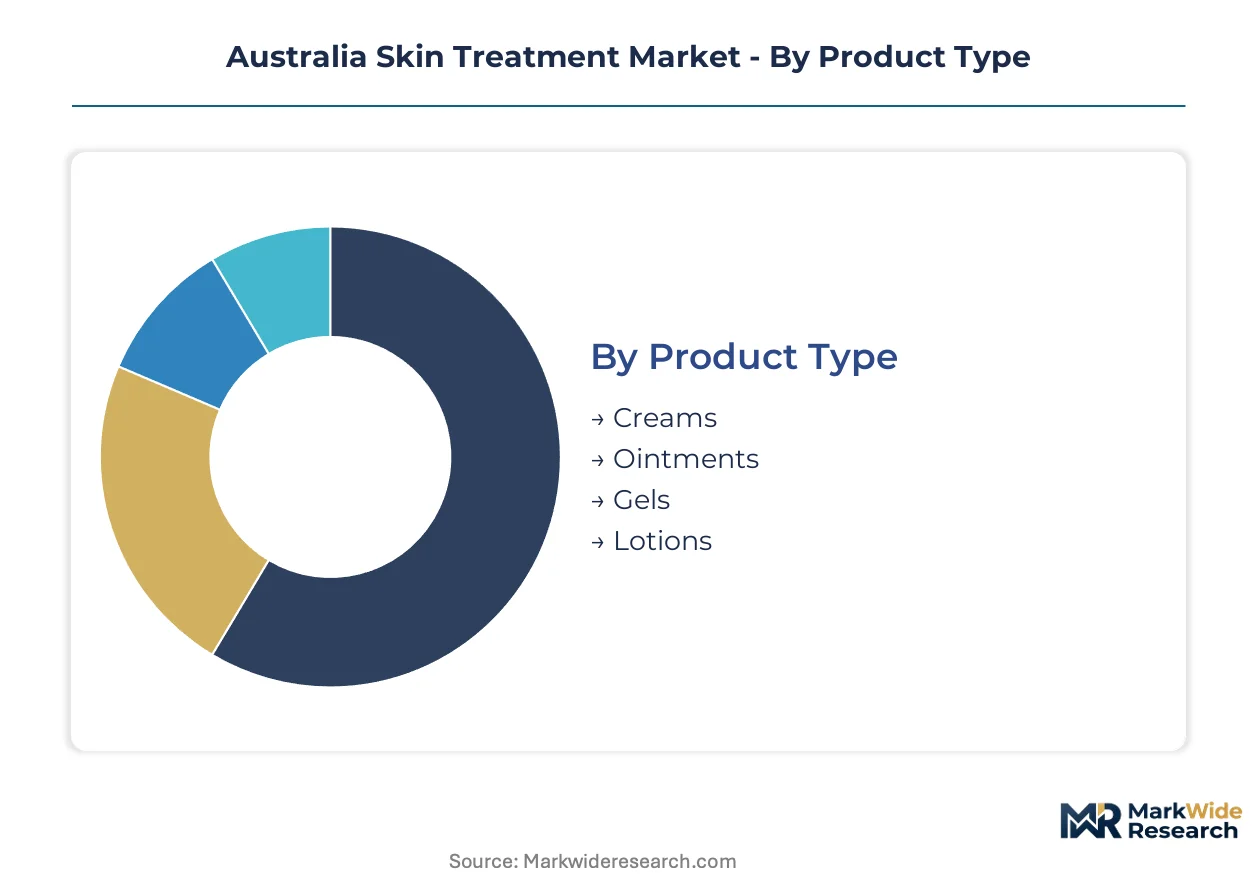
Segmentation in the Australia skin treatment market reveals divergent margin profiles and regulatory exposure across formulation types and care settings. Understanding these distinctions enables stakeholders to allocate R&D and distribution investments toward channels with sustainable competitive moats.
Product Type:
Creams and ointments exhibit the longest purchase cycles due to established reimbursement familiarity, while gels and lotions turn over faster as tolerability-driven switching accelerates repurchase frequency.
- Creams:Oil-in-water emulsions with 15-30% lipid content dominate Medicare-reimbursed dermatology prescriptions. New South Wales and Victoria clinics favor cream bases for eczema protocols due to occlusion properties that enhance corticosteroid penetration. Creams anchor the volume base while gels gain share at the steepest rate.
- Ointments:Petrolatum-based occlusive formulations with 80%+ lipid fraction serve severe xerosis and psoriasis plaques. Queensland's tropical climate limits ointment adoption compared to southern states, though compounding pharmacies maintain steady demand for customized petrolatum blends.
- Gels:Aqueous matrices with carbomer or cellulose thickeners deliver rapid absorption for acne applications. Melbourne and Sydney dermatology clinics prescribe gel vehicles for Fitzpatrick skin types IV-VI to minimize post-inflammatory hyperpigmentation risk from residual film.
- Lotions:Low-viscosity fluid emulsions suit large-surface-area applications like photodamaged décolletage. Western Australia mining communities drive volume for SPF-laden daily lotions through occupational health screening programs.
Creams and ointments retain the largest revenue footprint through chronic condition loyalty, whereas gel formulations expand most quickly via acne tolerability advantages.
Application:
Cost tier stratification separates episodic acute treatments from lifelong chronic management regimens with divergent price elasticity profiles.
- Acne:Androgen-driven sebaceous hyperplasia affecting 85% of Australians aged 15-25. Isotretinoin prescriptions through Victorian telehealth platforms have compressed initiation timelines from 12 weeks to 48 hours.
- Eczema:Atopic dermatitis requiring continuous emollient maintenance generates recurring revenue streams. The TGA's 2024 concentration disclosure rules forced reformulation of 14% urea creams previously marketed as "medical-grade" moisturizers.
- Psoriasis:Autoimmune plaque disease with biologic eligibility thresholds tightening under Pharmaceutical Benefits Scheme cost-effectiveness reviews. South Australia exhibits the highest biologic penetration due to dermatologist density in Adelaide.
- Dermatitis:Contact and seborrheic variants drive occupational health expenditure in Queensland construction and manufacturing sectors. Patch testing referral volumes through Brisbane clinics have tripled since mandatory workplace chemical exposure reporting.
Eczema underpins the most predictable revenue base through subscription replenishment, while acne commands premium pricing via outcome urgency.
End User:
Customer type determines regulatory burden intensity and margin capture potential, with professional settings facing stricter supervision requirements than retail channels.
- Clinics:Specialist dermatology and cosmetic medicine practices bundle procedures with prescription home care. Franchise networks across New South Wales and Victoria standardize peel protocols while capturing recurring product margin through captive dispensing.
- Hospitals:Inpatient dermatology services concentrate in Sydney and Melbourne tertiary centers for severe drug reactions and immunobullous disease. Day procedure units handle photodynamic therapy for field cancerization under Medicare item numbers.
- Home Care:Direct-to-consumer prescription platforms bypass traditional pharmacy markup. Victorian regulatory amendments now permit asynchronous telehealth prescribing for maintenance topicals, expanding addressable geography beyond clinic catchments.
- Pharmacies:Community retail maintains OTC emollient and sunscreen volume, though prescription compounding exemptions have shifted high-margin customized work toward clinic-affiliated dispensaries.
Clinics generate the highest per-patient value through procedure bundling, while home care channels climb the fastest via platform-enabled geographic expansion.
Delivery Mode:
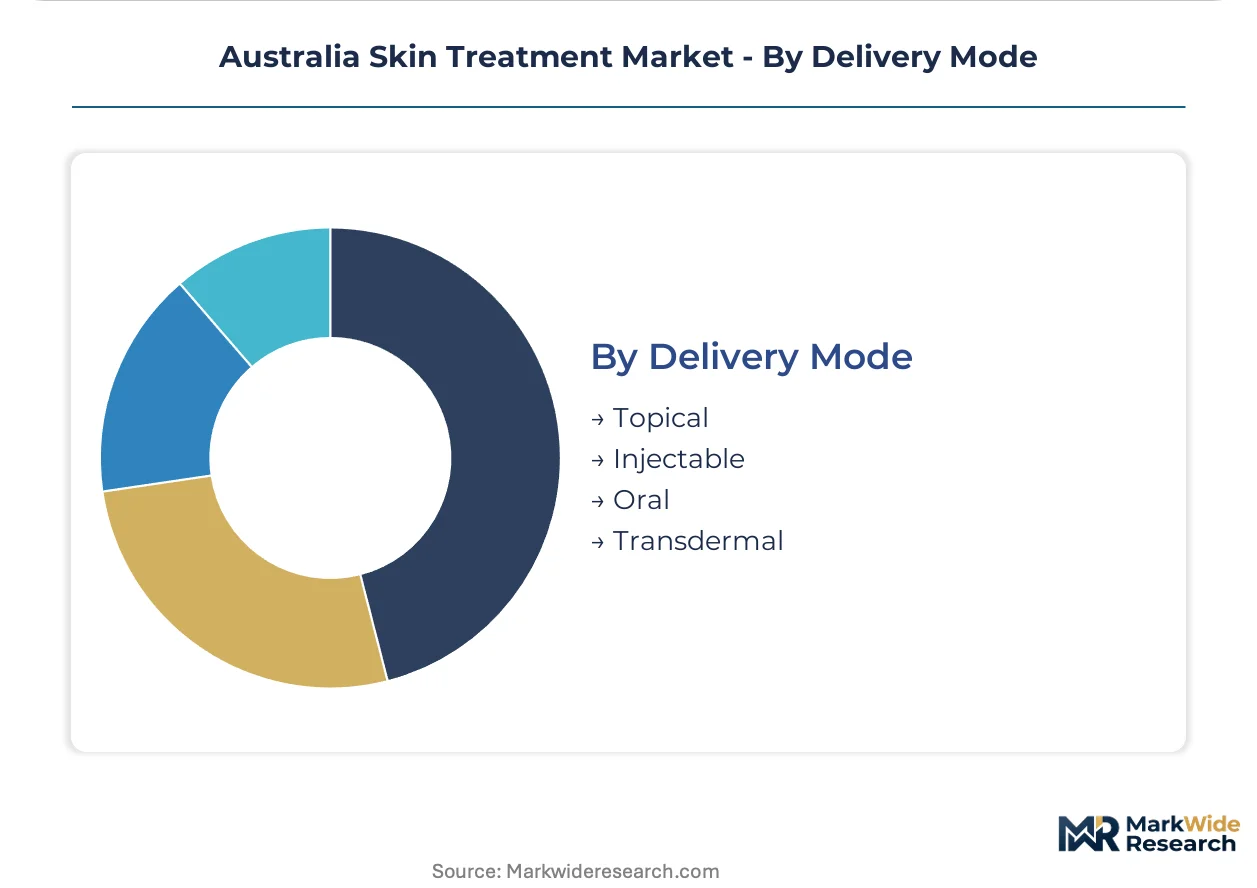
Volume concentration sits with topical administration, though margin expansion concentrates in injectable and transdermal innovations that command procedure fees.
- Topical:Direct skin application of creams, ointments, gels, and lotions constitutes the foundational delivery pathway. The TGA's ingredient disclosure mandates have accelerated tolerability testing investments for retinoid and hydroxy acid formulations.
- Injectable:Biostimulators and neuromodulators require medical or nurse prescriber administration under state-specific supervision rules. Queensland's 2024 cosmetic procedure reforms imposed mandatory cooling-off periods that lengthened injectable conversion funnels.
- Oral:Systemic agents including isotretinoin and immunosuppressants carry teratogenic and hepatotoxic monitoring requirements. The Pharmaceutical Benefits Scheme restricts oral retinoid access to dermatologist-initiated authority prescriptions.
- Transdermal:Microneedle patches and iontophoresis devices deliver actives through stratum corneum disruption. Melbourne-based research institutes pilot peptide-loaded dissolving microneedles for melasma, though commercialization awaits TGA medical device classification clarity.
Topical delivery anchors volume through chronic condition maintenance, while injectable modes capture margin expansion through aesthetic procedure bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Therapeutic Goods Administration anchors regulatory oversight across Australian states, with dermatology service density varying sharply between eastern population centers and western markets. State-level cosmetic procedure reforms create compliance fragmentation that shapes clinic expansion feasibility.
New South Wales
Sydney dermatology clusters drive premium aesthetic procedure volume through Double Bay and North Shore clinic concentrations. The state's 2024 cosmetic medicine supervision standards tightened nurse injector oversight requirements. Compounding pharmacies in Parramatta and Chatswood maintain customized topical formulation capacity for eczema and psoriasis protocols.
Victoria
Melbourne's tertiary hospital network supports severe immunobullous disease referral pathways from regional Victoria. Victorian regulatory amendments permit asynchronous telehealth prescribing for maintenance topicals, expanding home care channel reach beyond traditional clinic catchments. The city's research institutes pilot peptide-loaded dissolving microneedles for melasma applications.
Queensland
Brisbane's subtropical climate limits occlusive ointment adoption compared to southern states. Queensland's 2024 cosmetic procedure reforms imposed mandatory cooling-off periods that lengthened injectable conversion funnels. Patch testing referral volumes through Brisbane clinics have tripled since mandatory workplace chemical exposure reporting took effect.
Western Australia
Perth exhibits dermatologist-to-population ratios below Sydney and Melbourne benchmarks, presenting whitespace for scaled clinic entry. Western Australia mining communities drive volume for SPF-laden daily lotions through occupational health screening programs. The state's pharmacy compounding sector serves remote patient populations with customized petrolatum blends.
South Australia
Adelaide maintains the highest biologic penetration for psoriasis among Australian capitals due to dermatologist density concentration. The Skincare Company anchors compounded prescription formulation supply to South Australian dermatology practices. State licensing requirements for cosmetic injectables remain less prescriptive than New South Wales and Victoria frameworks.
Australia Skin Treatment Market Key Industry Players
Clinic-network operators and professional-formulation specialists split the market between scaled service delivery and customized therapeutic protocols. Three archetypes dominate: franchise-based clinic chains with captive product dispensing, compounding pharmacies serving prescription customization demand, and professional peel suppliers targeting tolerability-driven switching. Competitive moves concentrate on geographic whitespace penetration in Perth and Adelaide, plus telehealth platform integration to capture home care margin.
Within the professional-formulation tier, SkinMed Australia and The Skincare Company exemplify divergent positioning strategies. SkinMed Australia occupies the clinic-focused professional peel segment, while The Skincare Company anchors compounded prescription supply relationships. Australian Skin Clinics represents the franchise-network archetype with scaled eastern states presence. Among international participants, Beiersdorf AG and PMD Beauty sit within the mass-market and device categories respectively, serving distinct patient acquisition channels from the professional-clinic core.
| Leading Market Players |
|---|
| SkinMed Australia |
| The Skincare Company |
| Australian Skin Clinics |
| Ekseption Peels |
| Blânche Beauty |
| Beiersdorf AG |
| The Global Beauty Group |
| PMD Beauty |
| DermapenWorld |
| Others |
Cost & Logistics Intelligence
The Shanghai-Singapore-Melbourne container corridor carries retinoid and peptide raw materials from Chinese chemical manufacturers to Australian compounding pharmacies, with freight cost volatility compressing margins at formulation facilities while enabling Sydney and Melbourne clinics to maintain premium pricing tiers against Perth and Adelaide competitors.
Pricing Analysis
Geographic price spreads between eastern seaboard clinics and western markets exceed thirty percent for identical peel protocols. Three-tier pricing structure across premium, standard, and economy levels separates franchise-network bundled procedures from independent dermatology practices and telehealth prescription platforms. Cost compression in the home care channel is intensifying because direct-to-consumer platforms bypass wholesale pharmacy markup. Price-sensitive patients in Western Australia and South Australia drive volume toward subscription-based maintenance topicals, while Sydney's Double Bay corridor sustains the least price elasticity through outcome-urgent aesthetic demand.
Supply Chain Analysis
Extended payment terms from Australian distributors to South Korean and Swiss peptide suppliers now stretch ninety to one hundred twenty days, reflecting working capital pressure from TGA documentation burdens. Active pharmaceutical ingredient supply concentrates in China, South Korea, and Switzerland for retinoid and peptide categories. Raw material dependencies span isotretinoin precursors, poly-L-lactic acid granules, and buffered acid peel concentrates. Single-source vulnerability from Chinese chemical intermediate suppliers exposes margin stability to shipping lane disruption. Distribution runs through clinic-affiliated compounding pharmacies capturing formulation margin previously accruing to wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across state-level cosmetic procedure regulations and federal therapeutic goods frameworks creates niche entry points for specialists targeting compliance arbitrage or geographic whitespace.
For Market Incumbents: Pre-empt nurse injector supply constraints by underwriting accredited certification program expansion in Victoria and New South Wales. Secure backward integration into peptide raw material sourcing through exclusive offtake agreements with South Korean manufacturers. Defend against telehealth platform disintermediation by embedding subscription home care regimens within captive clinic software ecosystems. For New Entrants and Emerging Players: Perth and Adelaide dermatologist-to-population deficits present whitespace for scaled clinic entry with lower patient acquisition costs than Sydney benchmarks. Target compounded prescription formulation partnerships with South Australian dermatology practices where regulatory supervision requirements remain less prescriptive. Deploy asynchronous telehealth prescribing platforms to capture Victorian home care channel expansion beyond traditional clinic catchments. For Investors and Strategic Acquirers: Compounding pharmacy networks with TGA 503A-equivalent facility certifications offer acquisition exposure to prescription customization demand and recurring revenue streams. Long-term viability hinges on regulatory divergence between state cosmetic procedure reforms and federal ingredient disclosure mandates. Monitor TGA good manufacturing practice inspection frequency as an inflection indicator for quality control cycle extension risk.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Victorian regulatory amendments enable asynchronous prescribing beyond clinic catchments. |
| Peptide Raw Material Offtake Agreement | Exclusive supply from South Korean manufacturers hedges currency and shipping volatility. |
| Compounding Pharmacy Network Acquisition | TGA facility certifications create moats against wholesale pharmacy competition. |
| Nurse Injector Certification Program Underwriting | Six-month waitlists throttle clinic expansion velocity across eastern states. |
| Biostimulator-Energy Device Protocol Bundling | Melbourne and Sydney clinics command premium pricing through outcome stacking. |
Research Approach
Operator-level perspectives from dermatology clinic directors, cosmetic nurse injectors, compounding pharmacists, and TGA regulatory consultants anchored the qualitative base. Primary interviews combined with secondary validation from TGA ingredient disclosure amendments, Pharmaceutical Benefits Scheme cost-effectiveness reviews, and state health department aesthetics practice standards. Bottom-up clinic volume estimates and top-down market sizing triangulated through New South Wales and Victoria franchise network disclosures.
Scenario-bracketing around regulatory enforcement intensity and telehealth adoption pace structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product formulation type, application indication, end-user setting, and delivery mode, with state-level regulatory divergence treated as a cross-cutting variable. CAGRs derived from patient visit volume trajectories and average revenue per procedure trends, incorporating isotretinoin prescription compression timelines and biologic eligibility threshold adjustments.
Practitioners should monitor TGA good manufacturing practice inspection frequency, state cosmetic procedure reform divergence, and telehealth prescribing volume thresholds for early signals of forecast revision. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Global Online Dermatology Consultation Market
Dermatology
Cutaneous Squamous Cell Carcinoma Market
Dermatology
Global Hirsutism Market
Dermatology
Dermatology Drugs Market
Dermatology
Global Dermatological Therapeutics Market
Dermatology
Inflammatory Skin Diseases Treatment Market
Dermatology
Lentigo Maligna Melanoma Therapeutic Market
Dermatology
Global Dermatology Cro Market
Dermatology
Keratoacanthoma Market
Dermatology
Androgenetic Alopecia Market
Dermatology
Global Veterinary Dermatology Drugs Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Folliculitis Treatment Market
Dermatology
Prescription Dermatology Therapeutics Market
Dermatology
Darier Disease Drugs Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market