
 Varicella Zoster Infection Treatment Market | 2026-2036
Varicella Zoster Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Varicella Zoster Infection Treatment Market Outlook
mRNA platform refinement is tilting vaccine development toward more stable, thermotolerant formulations. GlaxoSmithKline plc leverages its recombinant zoster vaccine franchise to sustain leadership in adult immunization. Pfizer Inc. competes through broad antiviral manufacturing scale, while Merck & Co. Inc. anchors its position in pediatric varicella prophylaxis.
Varicella Zoster Infection Treatment encompasses pharmaceutical and biological interventions targeting primary chickenpox infection and herpes zoster reactivation, with recombinant glycoprotein E-based vaccines representing the most immunogenic preventive class. The clinical purpose centers on reducing post-herpetic neuralgia incidence and severe cutaneous complications across age-stratified populations. Vaccines command the largest revenue pool given two-dose adult regimens and national immunization schedule inclusion, while immune modulators show the fastest expansion as adjuvant therapy for refractory post-herpetic pain. Oral delivery dominates volume due to acyclovir and valacyclovir prescribing patterns, though subcutaneous vaccines capture disproportionate value per dose.
The FDA's Breakthrough Therapy designation streamlines antiviral pipeline advancement, while the EMA's Committee for Medicinal Products for Human Use shapes European market access through centralized immunization benefit assessments. WHO prequalification standards determine procurement eligibility for low-income country vaccine programs, directly influencing manufacturer capacity allocation. Stakeholders must monitor evolving payer evidence requirements for combination therapy regimens against monotherapy benchmarks.
Market Dynamics
The transition from live-attenuated to recombinant subunit vaccines is compressing manufacturing lead times while elevating cold-chain requirements. This platform shift is redistributing value capture toward adjuvant technology suppliers and specialized fill-finish contractors.
Growth Catalysts
- Adult Immunization Schedules:National health authorities in Germany, Japan, and Australia have added recombinant zoster vaccines to routine elderly care protocols. This expands addressable populations beyond prior risk-based targeting.
- EMA Centralized Assessment Pathways:The Committee for Medicinal Products for Human Use now prioritizes antiviral filings demonstrating post-herpetic neuralgia prevention. Accelerated timelines compress regulatory lag for novel mechanisms.
- Thermostable mRNA Formulation Advances:Lipid nanoparticle engineering is reducing vaccine storage burdens. Distribution reach extends to rural clinics lacking ultra-low temperature infrastructure.
Market Restraints
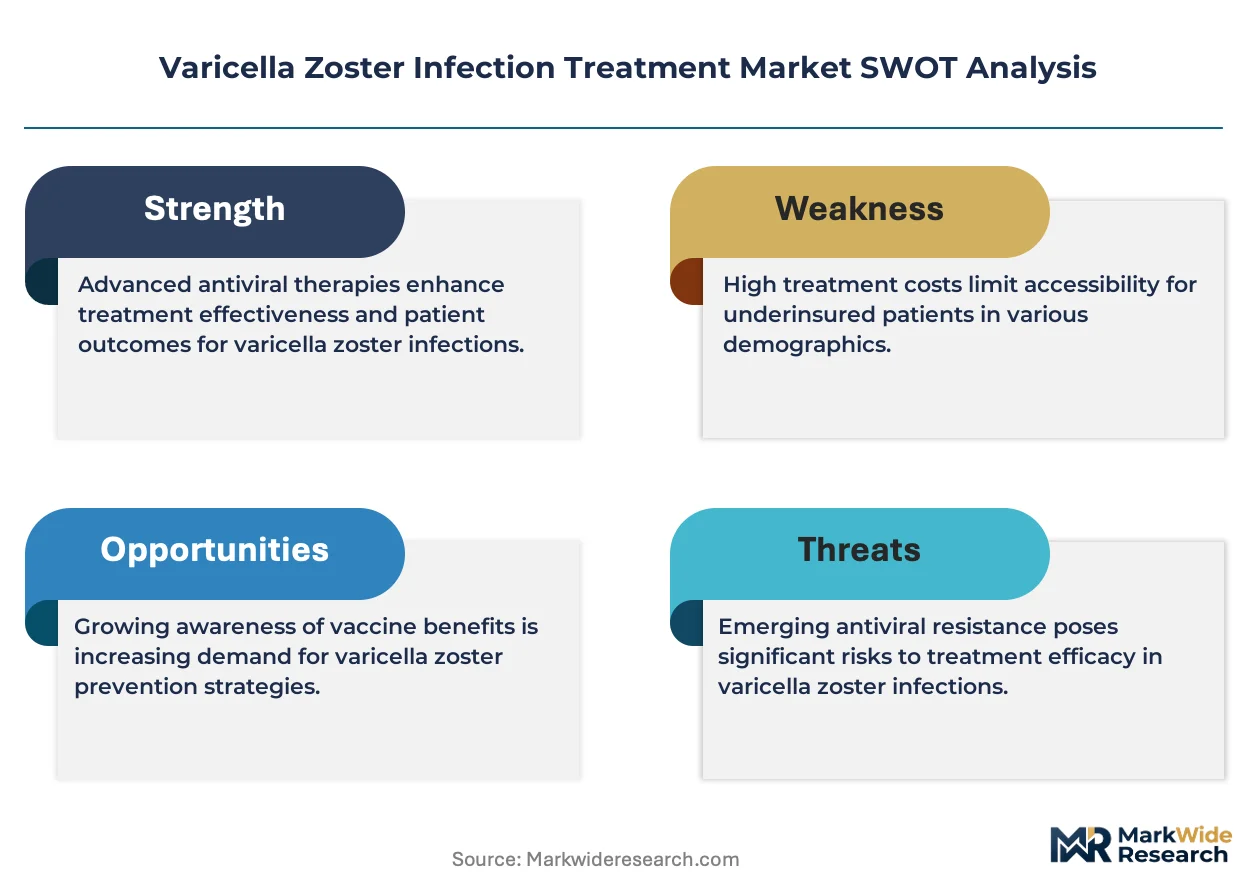
- API Supply Concentration:Acyclovir and valacyclovir active pharmaceutical ingredient production clusters in Hubei province and Gujarat state. Geopolitical friction or environmental enforcement disrupts oral antiviral availability.
- Reimbursement Compression:Payers in France and Italy apply strict cost-effectiveness thresholds for combination antiviral-immunomodulator regimens. Monotherapy benchmarks limit premium pricing for novel adjuncts.
- Live-Attenuated Vaccine Substitution:Pediatric varicella programs in some markets retain Oka strain products. Recombinant platforms face adoption friction where legacy supply contracts persist.
Strategic Opportunities
- Underpenetrated Southeast Asia:Vietnam, Indonesia, and Philippines maintain sub-fifteen-percent adult shingles vaccination coverage. Public-private partnerships with national immunization programs unlock volume.
- Combination Prophylaxis-Therapy Pipelines:Convergence of mRNA vaccines with long-acting antiviral implants addresses breakthrough infections. Development partnerships target immunocompromised patient segments.
- Direct-to-Pharmacy Distribution:Bypassing hospital procurement for adult boosters reduces administrative overhead. Retail pharmacy chains in Canada and Australia pilot standing-order protocols.
Industry Challenges
- Specialized Formulation Talent Scarcity:Lipid nanoparticle process development requires hybrid biologic-small molecule expertise. Competition with oncology and infectious disease programs elevates compensation costs.
- Legacy Electronic Health Record Integration:Adult vaccination registries in multiple jurisdictions use incompatible data standards. Patchwork tracking complicates reminder systems and coverage assessment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Varicella Zoster Infection Treatment Market |
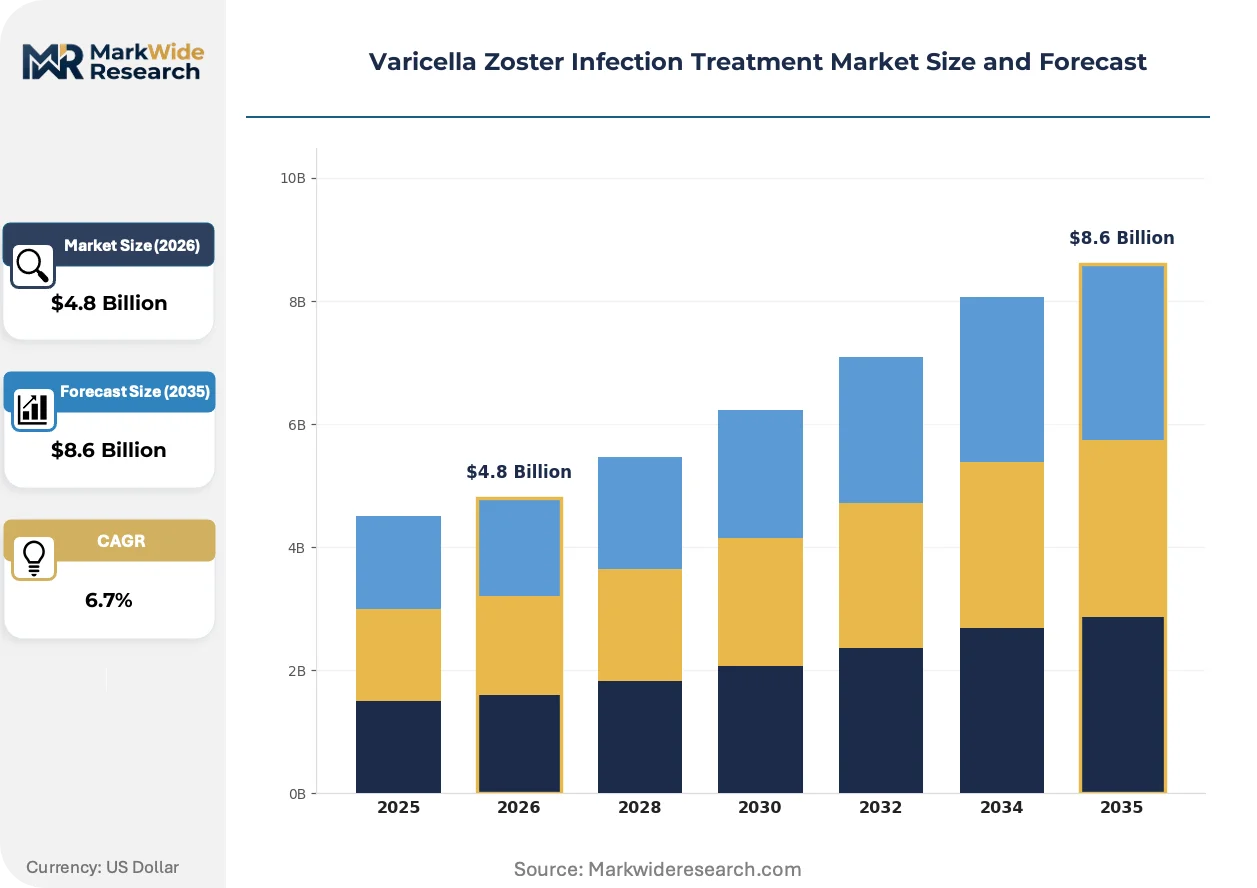
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antivirals, Topical Treatments, Immune Modulators End User: Hospitals, Clinics, Homecare Settings, Pharmacies Delivery Mode: Intravenous, Subcutaneous, Oral, Inhalation Therapy Area: Infectious Diseases, Dermatology, Pediatrics, Immunology |
| Companies Covered | GlaxoSmithKline plc, Pfizer Inc., Novartis AG, Teva Pharmaceutical Industries Ltd., Merck & Co. Inc., Sanofi, F. Hoffmann-La Roche Ltd., Sun Pharmaceutical Industries Ltd., Viatris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Varicella Zoster Infection Treatment Market Strategic Shifts
Platform diversification is fragmenting competitive advantage sources. Innovators now compete on formulation stability and delivery convenience rather than immunogenicity alone.
Self-amplifying mRNA constructs encode replicase enzymes that multiply antigen expression from minimal input doses. Vaccine developers at Bay Area and Boston biotech clusters are adopting these constructs for Phase II zoster candidates. The technology is collapsing dose-volume requirements, enabling single-vial presentation that simplifies field deployment.
EMA's Falsified Medicines Directive serialization mandates now extend to temperature-sensitive biologics. Manufacturers must integrate track-and-trace codes at the vial level, not just carton. European distribution partners are responding by consolidating logistics networks to reduce handoff points where compliance risk concentrates.
Hospital formulary committees increasingly unbundle vaccine procurement from administration service contracts. Purchasing managers negotiate antigen supply separately from immunization clinic staffing. This pattern is most visible in United States integrated delivery networks, where centralized procurement offices extract price transparency from manufacturers.
Varicella Zoster Infection Treatment Market Segmentation
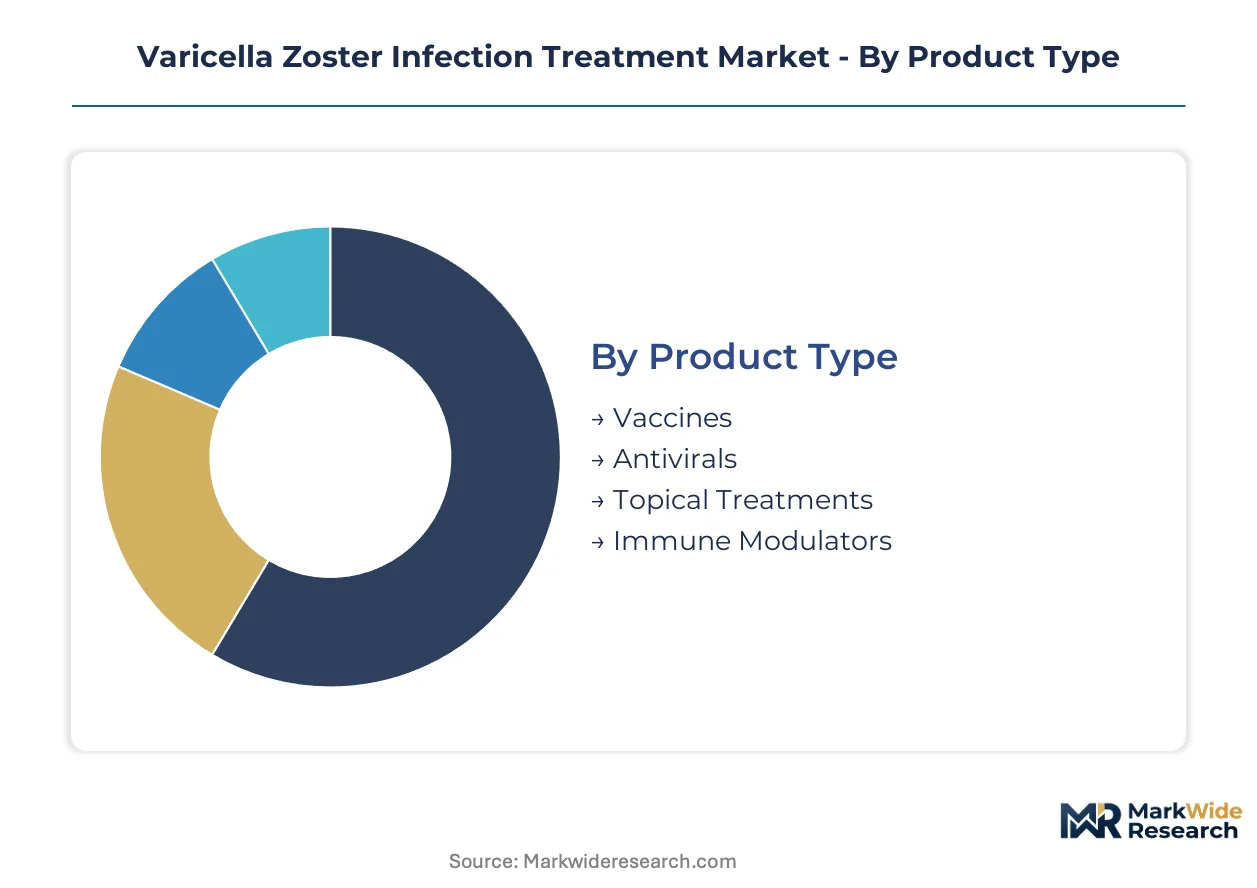
Segmentation in varicella zoster treatment reveals divergent margin profiles across prophylactic and therapeutic modalities. Vaccine platforms demand specialized cold-chain logistics, while oral antivirals compete on procurement scale. Understanding these structural differences guides capacity allocation and partnership strategy.
Product Type:
After-sales service intensity varies sharply across this category, with vaccines requiring temperature monitoring infrastructure and patient registry support that antivirals do not.
- Vaccines:Recombinant glycoprotein E subunit formulations dominate adult immunization with two-dose regimens. Demand concentrates in United States integrated delivery networks where standing-order protocols streamline administration. Cold-chain validation and adverse event reporting create ongoing manufacturer obligations.
- Antivirals:Acyclovir, valacyclovir, and famciclovir comprise the oral standard of care. Prescribing volume clusters in retail pharmacy chains across Germany and Japan where generic substitution pressures pricing. API sourcing from Hubei province and Gujarat state introduces supply continuity risks.
- Topical Treatments:Analgesic creams and antiviral ointments address localized cutaneous symptoms. Limited reimbursement in French and Italian markets constrains uptake.
- Immune Modulators:Adjunct therapies for refractory post-herpetic neuralgia. Emerging clinical protocols in Australian hospitals are expanding off-label utilization.
By volume, Antivirals leads. By growth pace, Immune Modulators is ahead.
End User:
Procurement authority patterns distinguish this category, with hospital formulary committees wielding concentrated purchasing power against fragmented retail pharmacy decision-making.
- Hospitals:Inpatient settings manage severe disseminated zoster and immunocompromised breakthrough infections. United States academic medical centers anchor adoption of novel antiviral combinations.
- Clinics:Outpatient facilities deliver routine adult vaccination and acute episode management. Volume concentrates in Japanese geriatric care clinics following national schedule updates.
- Homecare Settings:Infusion services administer IV acyclovir for resistant cases. Growth reflects aging-in-place preferences in Canadian provinces.
- Pharmacies:Retail chains capture shingles vaccine volume through direct-to-pharmacy distribution pilots. Australian pharmacy standing-order protocols reduce administrative friction.
By revenue concentration, Hospitals leads. By expansion trajectory, Pharmacies is climbing the fastest.
Delivery Mode:
Supply chain configuration determines competitive positioning here, with subcutaneous vaccines commanding premium logistics against commoditized oral tablet distribution.
- Subcutaneous:Recombinant zoster vaccines require adjuvanted formulation stability. Lipid nanoparticle engineering advances are extending reach to rural clinics lacking ultra-low temperature infrastructure.
- Oral:Tablet and capsule formulations dominate prescription volume through retail channels. Valacyclovir prodrug chemistry improves bioavailability over acyclovir.
- Intravenous:Hospital-administered acyclovir for severe or disseminated disease. Compounding pharmacy preparation standards vary across German states.
- Inhalation:Investigational delivery for localized antiviral action. Limited current commercial presence.
By patient volume, Oral leads. By value per dose, Subcutaneous is gaining share fastest.
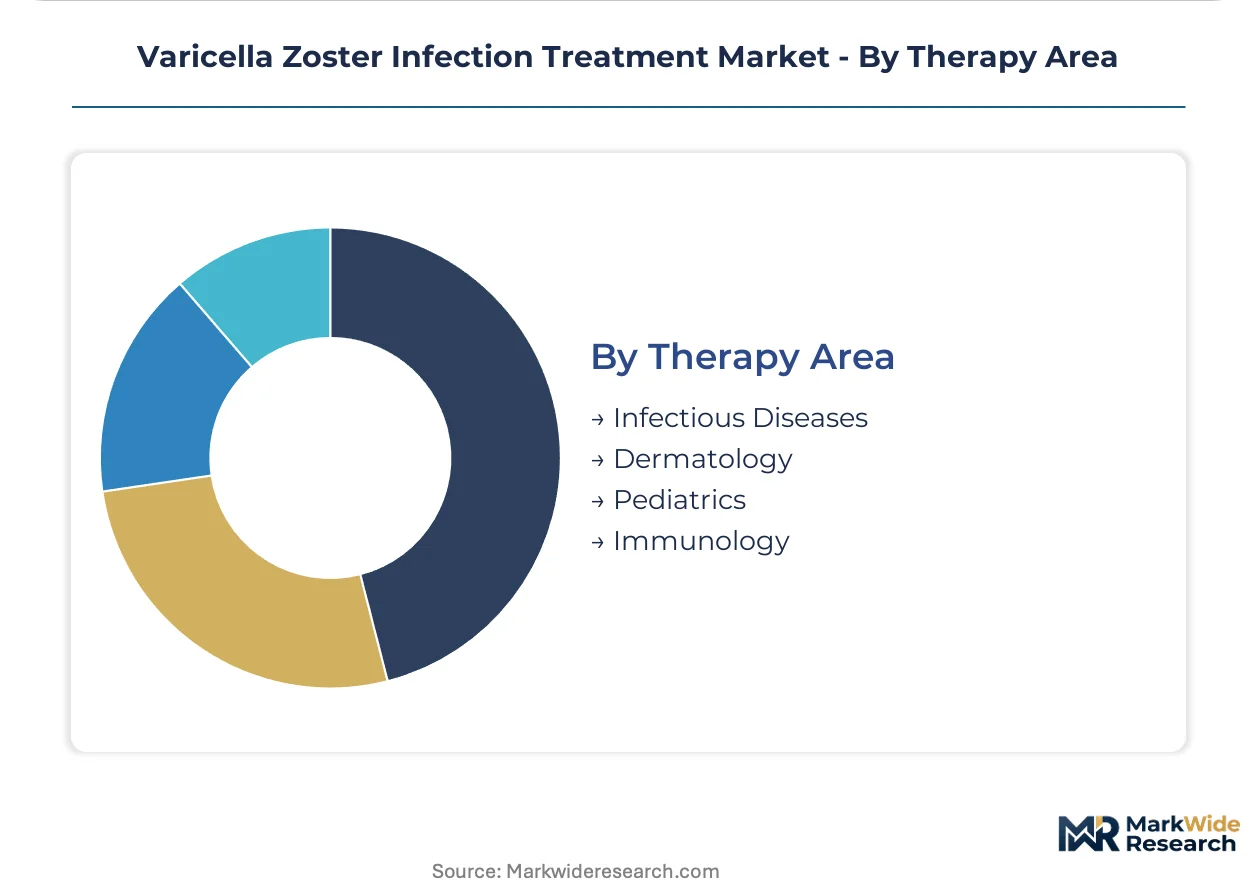
Therapy Area:
Regulatory pathway complexity structures this category, with infectious disease indications facing distinct evidentiary requirements versus dermatology claims.
- Infectious Diseases:Primary therapeutic classification for antiviral mechanisms. FDA Breakthrough Therapy designation streamlines novel mechanism advancement.
- Dermatology:Cutaneous complication management and post-herpetic neuralgia pain protocols. EMA prioritization of post-herpetic neuralgia prevention endpoints shapes filing strategy.
- Pediatrics:Varicella prophylaxis and breakthrough infection management. Live-attenuated vaccine retention in some markets creates platform competition.
- Immunology:Vaccine response optimization in compromised hosts. Combination prophylaxis-therapy pipelines target this segment specifically.
By established revenue, Infectious Diseases leads. By pipeline activity, Immunology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in varicella zoster treatments favor vaccine-producing nations, with recombinant subunit formulations commanding premium pricing in cross-border procurement. The United States imports limited finished doses but exports significant API intermediates to European fill-finish facilities. Japan and Germany maintain near-balanced trade in specialized adjuvant chemicals.
United States
Medicare Part D reimbursement expansion for adult shingles immunization drives pharmacy-based vaccination volume. The FDA's Breakthrough Therapy designation accelerates antiviral pipeline entries through streamlined evidentiary pathways. Boston-area biotech clusters host self-amplifying mRNA construct development for next-generation zoster candidates.
Germany
STIKO recommendation updates for elderly recombinant vaccination protocols expanded clinic-administered dose volume. EMA centralized assessment pathways prioritize post-herpetic neuralgia prevention endpoints in antiviral filings. North Rhine-Westphalia pharmaceutical manufacturing corridors anchor European fill-finish capacity for lipid nanoparticle formulations.
Japan
Ministry of Health, Labour and Welfare schedule inclusion for geriatric zoster prophylaxis shifted demand toward outpatient clinic settings. PMDA consultation programs compress review timelines for novel adjuvant mechanisms. Kanto region academic medical centers pilot combination prophylaxis-therapy protocols for immunocompromised patient segments.
Australia
National Immunisation Program funding for adult shingles vaccines elevated pharmacy standing-order protocol adoption. TGA priority review pathways expedite thermostable formulation registrations. Victorian hospital networks unbundle vaccine procurement from administration contracts, extracting price transparency through centralized procurement offices.
India
Universal Immunization Programme expansion into adolescent varicella prophylaxis generates public procurement volume. CDSCO accelerated approval pathways for biosimilar antivirals compress generic substitution timelines. Gujarat state API manufacturing clusters supply acyclovir intermediates to European formulation facilities.
Varicella Zoster Infection Treatment Market Competitive Environment
On the supply side, the industry is consolidating around platform technology ownership, with recombinant subunit and mRNA delivery systems creating distinct capability moats. Large-cap pharmaceutical incumbents dominate vaccine commercialization through established immunization infrastructure relationships. Three strategic archetypes define competitive positioning: platform technology licensors, specialized adjuvant suppliers, and integrated antiviral manufacturers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, particularly for lipid nanoparticle process development and cold-chain distribution reach.
Within the recombinant vaccine archetype, GlaxoSmithKline plc and Pfizer Inc. occupy positions reflecting divergent platform strategies—subunit glycoprotein E specialization versus broad antiviral manufacturing scale. Merck & Co. Inc. represents the live-attenuated legacy segment where pediatric varicella contracts persist. These three entities exemplify how technology platform choices dictate addressable market segments and regulatory pathway selection across national immunization programs.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Merck & Co. Inc. |
| Sanofi |
| F. Hoffmann-La Roche Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Viatris Inc. |
| Others |
Value Chain & Pricing Dynamics
Hubei province and Gujarat state acyclovir API manufacturing clusters concentrate upstream supply leverage, translating into margin compression for oral antiviral formulators while recombinant vaccine adjuvant technology captures premium value pools downstream.
Pricing Analysis
Hospital formulary committees anchor pricing negotiations through unbundled vaccine procurement contracts that separate antigen supply from clinic administration services. Three-tier pricing structure across premium recombinant subunit vaccines, standard live-attenuated pediatric products, and economy generic antivirals reflects brand immunogenicity data and cold-chain validation requirements. Pricing pressure stems from French and Italian payer cost-effectiveness thresholds that cap combination therapy premiums against monotherapy benchmarks. Retail pharmacy chains exhibit highest price sensitivity due to generic substitution policies, while academic medical centers accept premium novel antiviral combinations for immunocompromised protocols.
Supply Chain Analysis
Acyclovir and valacyclovir active pharmaceutical ingredient production draws from Hubei province in China and Gujarat state in India, with recombinant glycoprotein E subunit vaccine manufacturing concentrated in North Rhine-Westphalia corridors and Massachusetts biotech clusters. Lipid nanoparticle formulation inputs and specialized adjuvant chemicals hinge on Kanto region suppliers and Swiss chemical specialists. Single-source vulnerability in API intermediates exposes oral antiviral availability to environmental enforcement actions or geopolitical friction. Distribution runs through hospital centralized procurement offices for vaccine doses and retail pharmacy chains for antiviral tablets, with direct-to-pharmacy pilots reducing administrative handoffs in Canadian and Australian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recombinant zoster vaccine cold-chain monitoring services and patient registry support layers expand faster than antigen hardware, creating durable recurring revenue attachment opportunities for platform technology owners.
For Market Incumbents: Entrench market position through backward integration into lipid nanoparticle process development capabilities and captive adjuvant chemical supply from Kanto region specialists. Capacity expansion in thermostable mRNA formulation engineering counters emerging biotech cluster competition for specialized talent. FDA Breakthrough Therapy designation maintenance requires sustained post-herpetic neuralgia prevention endpoint investment to defend against novel mechanism entrants. For New Entrants and Emerging Players: Southeast Asian public-private partnerships with national immunization programs in Vietnam, Indonesia, and the Philippines represent the most penetrable entry point given sub-fifteen-percent adult shingles vaccination coverage. Combination prophylaxis-therapy pipelines targeting immunocompromised hospital segments offer differentiation against established monotherapy franchises. Go-to-market execution should prioritize standing-order protocol adoption with retail pharmacy chains to bypass hospital procurement consolidation. For Investors and Strategic Acquirers: Capital is best deployed toward specialized adjuvant technology suppliers and fill-finish contractors with lipid nanoparticle process development expertise, given hybrid biologic-small molecule capability scarcity across Bay Area and Boston talent markets. Long-term viability over the five-to-ten year horizon rests on platform diversification beyond live-attenuated legacy positions. The signal to watch is EMA centralized assessment pathway prioritization shifts for post-herpetic neuralgia prevention endpoints, which would accelerate novel mechanism valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Self-amplifying mRNA construct Phase II progression collapses dose-volume requirements for field deployment. |
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation streamlines novel antiviral evidentiary requirements for post-herpetic neuralgia endpoints. |
| Manufacturing Scale-Up | Lipid nanoparticle engineering advances extend thermostable vaccine reach to rural clinics lacking ultra-low temperature infrastructure. |
| Pipeline Diversification | Combination prophylaxis-therapy convergence addresses breakthrough infections in immunocompromised patient segments. |
| Strategic Partnership | Public-private partnerships with Vietnamese and Indonesian national immunization programs unlock underpenetrated adult vaccination volume. |
Study Parameters
A spread of perspectives from drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists converged on the working assumptions underlying this analysis. Primary interview insights were cross-validated against FDA filings, EMA centralized assessment submissions, ClinicalTrials.gov protocol registries, and hospital procurement database trends. Bottom-up prescription volume modeling and top-down immunization schedule inclusion analysis were triangulated to anchor segmentation outputs.
Demand-supply balance dynamics across the projection horizon were assessed through patient population epidemiology, national schedule update trajectories, and API manufacturing capacity utilization patterns. Segmentation dimensions modeled encompass treatment modality, delivery mode, end-user setting, patient age stratification, and regional regulatory cluster. CAGRs were derived from fitted adoption curves against historical immunization penetration benchmarks, with inputs from WHO prequalification standards and Gavi procurement eligibility criteria.
Stress conditions across API supply disruption scenarios, reimbursement compression thresholds, and mRNA platform transition timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway acceleration and cold-chain infrastructure expansion. Cross-checking against national immunization program budget allocation disclosures and formulary committee meeting minutes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Coxsackievirus Infections Treatment Market
Infectious Disease
Typhoid Treatment Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Pelvic Inflammatory Disease (PID) Treatment Market
Infectious Disease
Acute Vulvovaginal Candidiasis Treatment Market
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Global Leptospirosis Market
Infectious Disease
Viral Gastroenteritis Market
Infectious Disease
Measles Market
Infectious Disease
Japanese Encephalitis Market
Infectious Disease
Q Fever Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Virology Market
Infectious Disease
Actinomycosis Market