
 Deployable Military Shelters Market | 2026-2036
Deployable Military Shelters Market Size, Share, and Industry Trends Forecast 2026-2036
Deployable Military Shelters Market Intelligence
Buyer concentration among NATO defense procurement agencies is hardening as member states consolidate shelter acquisitions through framework agreements and joint capability development programs. General Dynamics Corporation leverages its systems integration expertise to anchor large-scale military contracts across multiple allied nations. HDT Global competes through specialized rapid deployment technologies designed for extreme climate operability. Alaska Structures sustains its position via advanced fabric engineering and expeditionary manufacturing scale.
Deployable military shelters are engineered structures designed for rapid assembly, disassembly, and transport to support tactical operations, personnel housing, medical facilities, and equipment storage in field conditions. These systems typically incorporate aluminum or composite framing with high-durability textile membranes rated for wind loads exceeding 100 mph and extended UV exposure, manufactured through precision welding and tensioned membrane processes to achieve setup times under thirty minutes. Container-based shelters dominate current procurement volumes due to their compatibility with standardized logistics chains and inherent transport efficiency. Expandable shelters represent the fastest-growing product type as forces prioritize footprint minimization during transit against operational space requirements. Air transportable deployment mode captures premium margin pools where strategic mobility timelines compress procurement evaluation criteria.
The U.S. Department of Defense mandates MIL-STD-810 environmental testing and MIL-PRF-32505 performance specifications for all expeditionary shelter acquisitions, while NATO's Standardization Office publishes STANAG agreements governing interoperability dimensions and interface protocols. The EU Green Deal's embodied carbon tracking requirements are beginning to influence material selection criteria for shelters deployed within European theater operations. Stakeholders must monitor evolving energy efficiency mandates and electromagnetic shielding standards as shelter networks integrate with command-and-control infrastructure.
Market Dynamics
NATO's modular open systems architecture mandate is compressing shelter procurement timelines while forcing interoperability across national defense inventories, reshaping how manufacturers design framing and membrane interface standards.
Growth Catalysts
- Expeditionary Operations Tempo:NATO member states in Germany, Poland, and the United Kingdom are accelerating rapid deployment unit acquisitions for forward-based missions. Air-transportable shelters with sub-thirty-minute assembly protocols dominate tender specifications.
- MIL-STD-810 Environmental Testing Mandate:The U.S. Department of Defense requires wind load ratings exceeding 100 mph and extended UV exposure durability for all expeditionary shelter acquisitions. Compliance creates procurement preference for certified textile membrane suppliers.
- Expandable Shelter Technology:Footprint-minimizing designs that maximize operational space upon deployment are displacing fixed-dimension container units in new procurement cycles. Composite framing advances enable this format transition.
Market Restraints
- Aluminum and Composite Input Volatility:Precision-welded frame manufacturing depends on aerospace-grade aluminum and carbon fiber composite feedstocks. Price swings in these materials compress margin predictability for shelter fabricators.
- Electromagnetic Shielding Certification Complexity:Integration with command-and-control infrastructure requires MIL-PRF-32505 compliance for electromagnetic interference protection. Testing bottlenecks extend qualification timelines for new market entrants.
- Rigid Logistics Chain Requirements:Container-based shelters dominate procurement volumes due to ISO standard compatibility. Alternative formats face adoption friction against entrenched military transport infrastructure.
Strategic Opportunities
- EU Green Deal Embodied Carbon Tracking:European theater operations now face material selection criteria influenced by carbon accounting mandates. Shelter manufacturers with low-carbon textile membrane production lines capture preferential positioning in EU defense tenders.
- Medical Facility Configuration Expansion:Field hospital and casualty evacuation shelter demand is accelerating beyond traditional personnel housing applications. Specialized climate control and sterilization interface capabilities open premium product tiers.
- STANAG Interoperability Framework Convergence:NATO Standardization Office agreements on dimensional and interface protocols create design-once, sell-many opportunities for compliant shelter platforms across allied procurement agencies.
Industry Challenges
- Tensioned Membrane Engineering Talent Scarcity:Precision welding and fabric engineering expertise for high-durability shelters concentrates among legacy defense contractors. Workforce development lags demand for these specialized manufacturing skills.
- Legacy System Integration Friction:New modular open systems architecture shelters must interface with existing national defense inventories. Retrofit compatibility requirements extend engineering cycles and inflate non-recurring development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deployable Military Shelters Market |
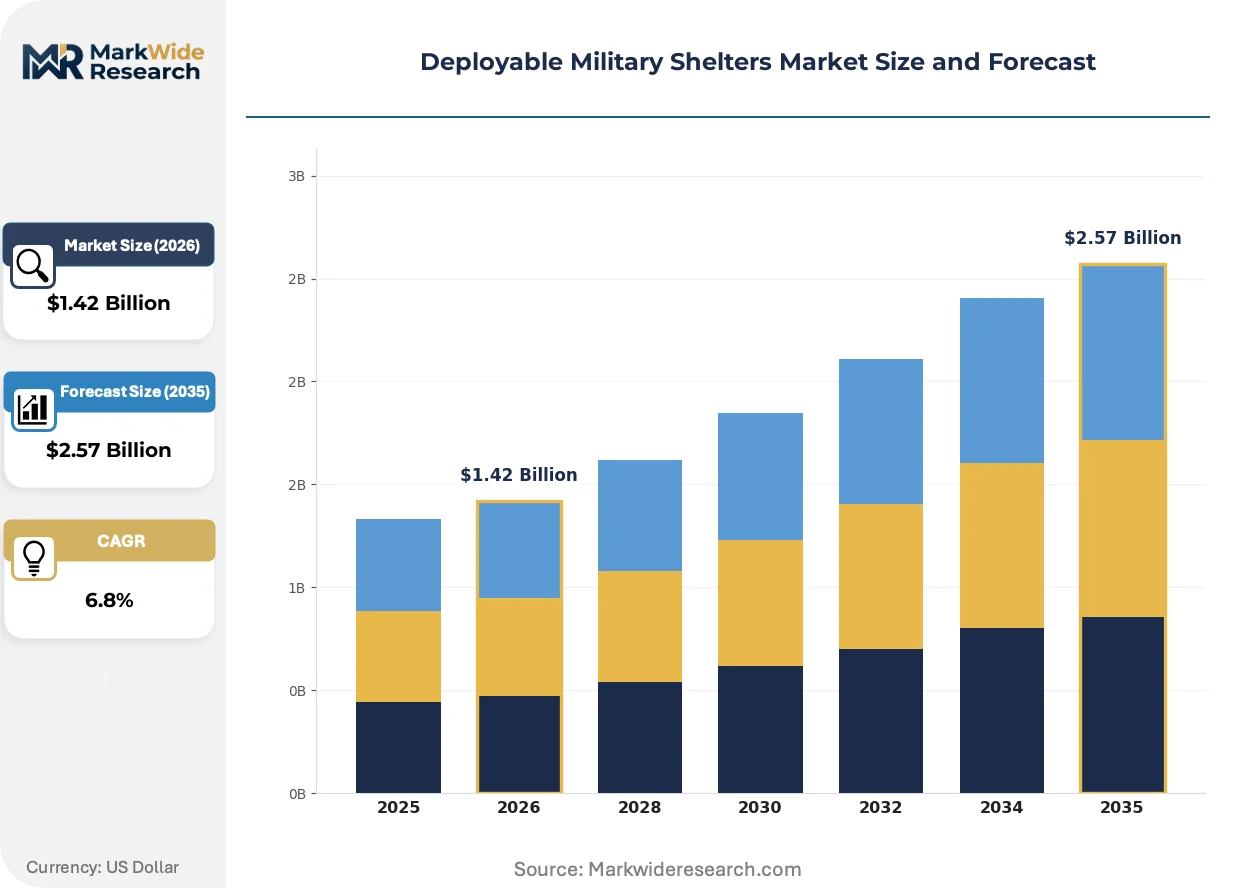
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tent Systems, Container-Based Shelters, Rapid Deployment Units, Expandable Shelters End User: Defense Forces, Emergency Services, Disaster Relief Agencies, NATO Entities Deployment Mode: Air Transportable, Ground Transportable, Marine Transportable, Modular Systems Size: Small Units, Medium Units, Large Units, Custom Sizes |
| Companies Covered | HDT Global, General Dynamics Corporation, AAR Corp., Alaska Structures, Weatherhaven Global Resources, UTS Systems, Rubb Buildings Ltd, Saab AB, Losberger GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deployable Military Shelters Market Strategic Shifts & Innovations
Active research into adaptive materials and energy-integrated shelter skins is compressing the gap between expeditionary infrastructure and fixed-base capability, with procurement agencies now specifying performance thresholds previously reserved for permanent construction.
Self-healing polymer membranes with embedded microcapsule repair chemistry are rewriting durability expectations for textile-based shelters. Expeditionary medical units and forward command posts in the U.S. defense sector are piloting these materials for 72-hour autonomous deployment scenarios. The technology is rewriting maintenance cost structures by eliminating field patch requirements and extending operational cycles between replacement.
The EU Green Deal's embodied carbon tracking requirements are mandating lifecycle emissions disclosure for shelters deployed within European theater operations. Defense procurement agencies in Germany and Poland now weight carbon intensity alongside wind load and UV ratings in evaluation matrices. Composite frame manufacturers are responding by qualifying bio-based resin systems and recycled aluminum feedstocks for STANAG-compliant platforms.
Buyer concentration through NATO framework agreements is consolidating shelter acquisitions under multi-year, multi-nation contracts. Traditional national tender processes are giving way to joint capability development programs where Germany, the United Kingdom, and Poland coordinate specifications. This pattern is most visible in rapid deployment medical shelter procurements, where interoperability testing now precedes rather than follows contract award.
Deployable Military Shelters Market Segmentation
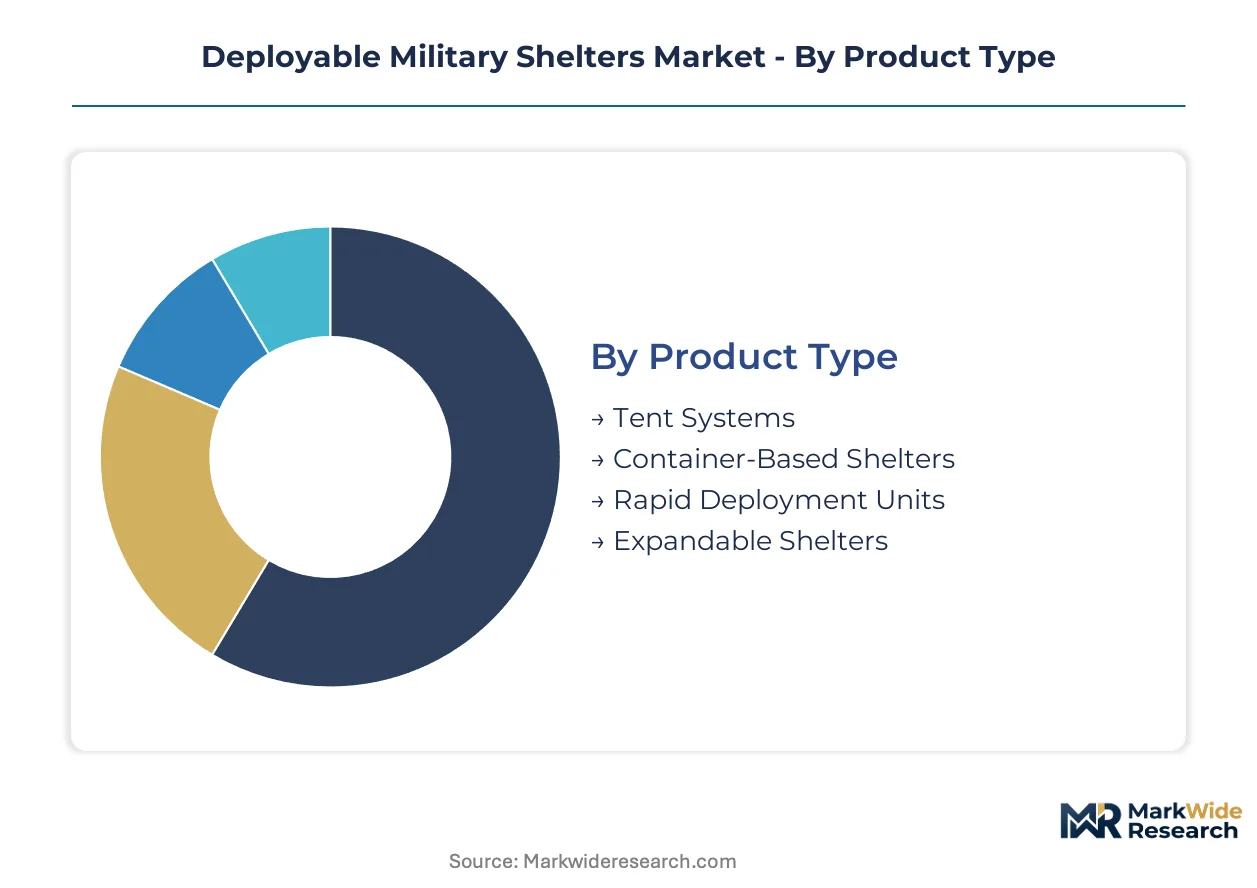
Deployable military shelter procurement decisions pivot on deployment velocity, logistics compatibility, and operational footprint constraints. Each segmentation dimension reflects distinct buyer priorities across NATO defense agencies and expeditionary force commanders.
Product Type:
Cost tier determines adoption velocity, with premium formats capturing rapid deployment contracts while standardized units anchor volume procurement.
- Container-Based Shelters:ISO-standard steel or aluminum enclosures with integrated climate systems and electromagnetic shielding. Germany and Poland anchor demand through framework agreements prioritizing logistics chain compatibility with existing military transport infrastructure.
- Expandable Shelters:Composite-framed units with telescoping or fold-out sections that minimize transport footprint while maximizing operational floor space. The United Kingdom's rapid deployment medical shelter tenders favor these designs for 72-hour autonomous field hospital establishment.
- Tent Systems:Tensioned membrane structures with aluminum or composite masts achieving sub-thirty-minute assembly protocols.
- Rapid Deployment Units:Pre-integrated shelter packages with embedded power distribution and environmental control systems.
Volume sits with Container-Based Shelters; growth tilts toward Expandable Shelters.
End User:
Application severity shapes specification intensity, with combat-deployed forces demanding hardened platforms versus humanitarian operators prioritizing rapid availability.
- Defense Forces:National military services requiring MIL-STD-810 environmental certification and MIL-PRF-32505 electromagnetic protection. The U.S. Department of Defense mandates modular open systems architecture compliance for all expeditionary shelter acquisitions.
- NATO Entities:Multi-national procurement bodies consolidating acquisitions through STANAG interoperability frameworks. Joint capability development programs in Germany, Poland, and the United Kingdom coordinate specifications across allied inventories.
- Emergency Services:Civil defense and first responder agencies deploying shelters for incident command and casualty staging.
- Disaster Relief Agencies:Humanitarian organizations operating under compressed procurement timelines with reduced certification requirements.
Procurement volume concentrates with Defense Forces; NATO Entities are climbing the fastest as framework agreements displace national tender processes.
Deployment Mode:
Strategic mobility timelines compress evaluation criteria, with air-transportable formats commanding premium positioning against ground-dependent alternatives.
- Air Transportable:Weight-optimized shelters meeting C-130, C-17, or A400M payload constraints with palletized loading interfaces. Poland's forward-based rapid deployment units specify these formats for expeditionary response timelines.
- Ground Transportable:Trailer-mounted or truck-integrated shelters leveraging existing military vehicle fleets.
- Marine Transportable:Corrosion-resistant framing and sealed membrane systems for naval vessel deployment and littoral operations.
- Modular Systems:Interconnectable shelter units enabling scalable base camp configuration.
Ground Transportable formats dominate current inventory; Air Transportable configurations gain share fastest as expeditionary tempo accelerates.
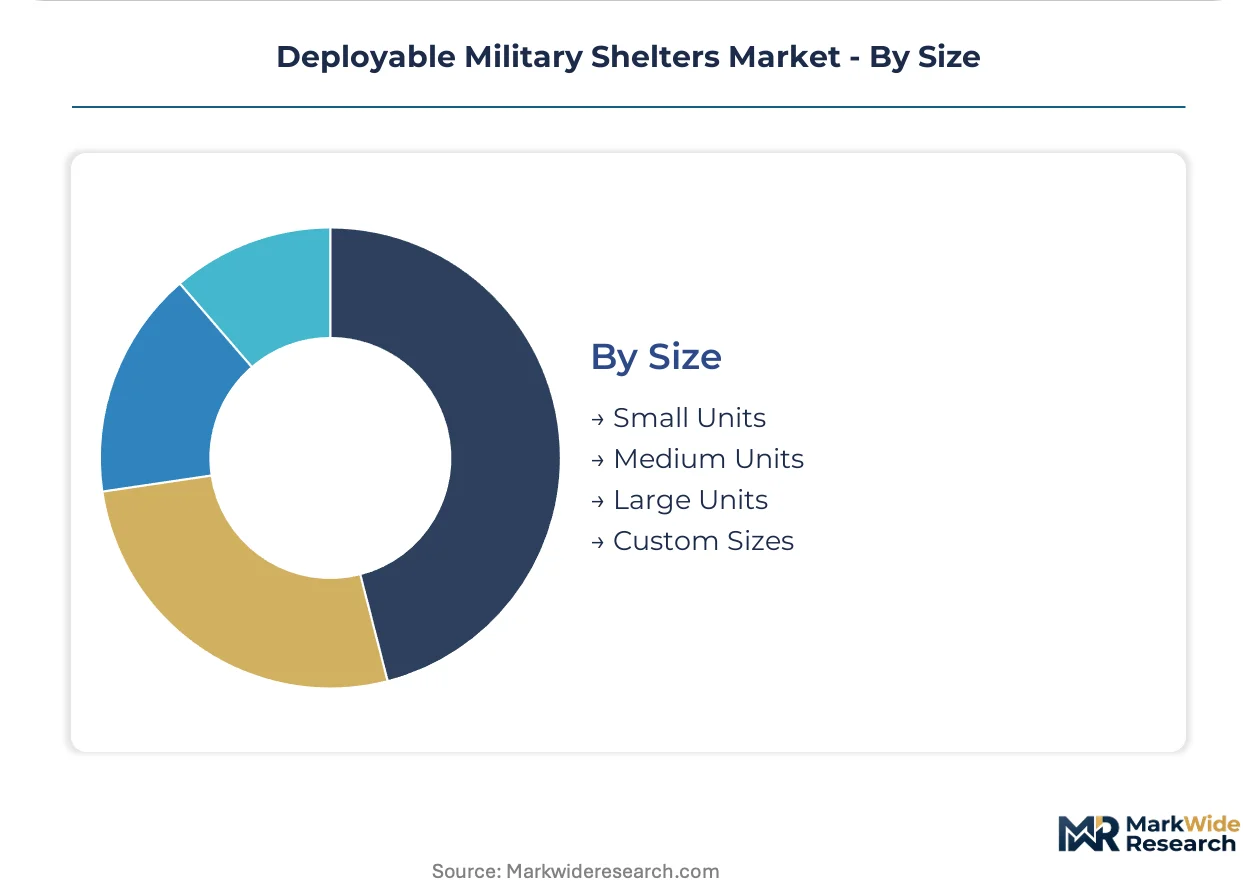
Size:
Operational scale requirements segment demand, with force protection and medical applications driving large-format specifications against personnel housing standardization.
- Large Units:Multi-bay shelters exceeding 500 square feet operational footprint for field hospitals, command posts, and maintenance facilities. Germany's medical infrastructure modernization targets these formats for casualty evacuation chains.
- Medium Units:Standardized footprints for personnel housing, dining facilities, and administrative operations.
- Small Units:Compact designs for checkpoint shelters, weapon storage, and individual crew quarters.
- Custom Sizes:Mission-specific dimensions for specialized equipment housing or unique terrain constraints.
Medium Units anchor procurement volume; Large Units show steepest expansion trajectory as field hospital configurations multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum smelting corridors in Quebec and Bavaria feed precision-welded frame manufacturing for expeditionary shelter fabricators. Composite resin production clusters in Japan and South Korea supply carbon fiber feedstocks. These material geographies shape where shelter assembly capacity concentrates.
United States
The U.S. Department of Defense's MIL-STD-810 environmental testing mandate drives procurement of wind-rated shelters exceeding 100 mph. The Pentagon's modular open systems architecture standards reshape interoperability requirements across expeditionary units. Huntsville, Alabama anchors systems integration activity where defense contractors coordinate shelter framing with command-and-control infrastructure.
Germany
Medical infrastructure modernization programs accelerate large-format field hospital shelter acquisitions. The EU Green Deal's embodied carbon tracking requirements influence material selection criteria for Bundeswehr deployments. Bavaria's composite engineering corridor hosts manufacturers qualifying bio-based resin systems for STANAG-compliant platforms.
Poland
Forward-based rapid deployment units specify air-transportable shelters compatible with C-130 and A400M payload constraints. NATO framework agreements consolidate Polish acquisitions with allied nations through joint capability development. Warsaw's defense procurement coordination with Germany and the United Kingdom standardizes tender specifications.
United Kingdom
Medical shelter tenders favor expandable designs achieving 72-hour autonomous field hospital establishment. The Ministry of Defence's expeditionary operations tempo compresses evaluation criteria toward sub-thirty-minute assembly protocols. Bristol's aerospace manufacturing base supplies precision-welded aluminum framing for tensioned membrane systems.
Canada
Arctic expeditionary training drives demand for extreme climate operability in shelter specifications. Canadian Forces procurement aligns with NATO STANAG interoperability frameworks for allied joint operations. Quebec's aluminum smelting and fabrication corridor feeds frame manufacturing for northern deployment scenarios.
Deployable Military Shelters Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized climate operability and rapid deployment technologies. The vendor base concentrates among defense-anchored systems integrators and fabric engineering specialists. Three archetypes dominate: aerospace-grade aluminum frame fabricators, composite-framed expandable shelter designers, and tensioned membrane engineering houses. Competitive moves center on STANAG interoperability certification and low-carbon material qualification for EU defense tenders.
Within the systems integration tier, General Dynamics Corporation and Saab AB represent defense-anchored multinationals leveraging multi-nation contract vehicles. HDT Global exemplifies the rapid deployment specialist archetype, occupying a position where extreme climate engineering differentiates positioning. Alaska Structures anchors the fabric engineering segment, sitting within a tier where expeditionary manufacturing scale and UV-durable membrane production create procurement preference.
| Leading Market Players |
|---|
| HDT Global |
| General Dynamics Corporation |
| AAR Corp. |
| Alaska Structures |
| Weatherhaven Global Resources |
| UTS Systems |
| Rubb Buildings Ltd |
| Saab AB |
| Losberger GmbH |
| Others |
Cost & Logistics Intelligence
Precision welding and tensioned membrane engineering talent concentrates in Bavaria and Quebec, where labor-cost differentials between these specialized manufacturing corridors and emerging assembly zones in Eastern Europe create pricing-tier spreads exceeding three-to-one for equivalent STANAG-certified shelter platforms.
Pricing Analysis
Volume concentrates with container-based shelters commanding standardized contract rates, while expandable and air-transportable formats capture premium positioning through performance-tier differentiation. Pricing stratifies across expeditionary-grade certification levels, with MIL-STD-810 and MIL-PRF-32505 compliance adding substantial cost premiums against commercial-grade alternatives. Cost compression in the container-based tier is intensifying as Polish and Romanian fabricators enter NATO framework agreements with lower overhead structures. Defense procurement agencies show least price sensitivity for medical facility configurations requiring 72-hour autonomous deployment protocols, whereas disaster relief agencies operating outside military certification mandates exhibit highest elasticity.
Supply Chain Analysis
Direct-to-defense-procurement channels handle framework agreement volumes, while specialized distributors serve rapid deployment unit spot requirements. Aerospace-grade aluminum feedstocks draw from Quebec and Bavaria smelting corridors, with carbon fiber composite resins sourcing from Japan and South Korea production clusters. Single-source vulnerability concentrates in precision-welded frame manufacturing, where qualified suppliers for military-specification shelter platforms number fewer than twelve globally. Distribution runs through NATO logistics coordination centers and national defense procurement agencies, with container-based formats leveraging existing ISO-standard military transport infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over textile membrane production and precision welding capacity determines margin capture against input volatility.
For Market Incumbents: Anchor position through captive supply of aerospace-grade aluminum framing and in-house tensioned membrane engineering to offset feedstock price swings. Pursue STANAG interoperability certification across multiple national defense inventories before joint capability development programs consolidate procurement. Counter emerging Polish and Romanian fabricators by embedding climate control and electromagnetic shielding integration as standard rather than optional configurations.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in air-transportable medical shelters offers viable entry terrain for specialized rapid deployment technologies. Target emergency services and disaster relief agencies operating under compressed procurement timelines with reduced certification requirements as the most penetrable buyer archetype. Differentiate through extreme climate operability engineering for Arctic and desert deployment scenarios where legacy defense contractors maintain thinner capability depth.
For Investors and Strategic Acquirers: The window for entry favors composite-framed expandable shelter designers with existing NATO framework agreement relationships and qualified low-carbon material production lines. Long-term viability hinges on positioning ahead of EU Green Deal carbon accounting mandates hardening into tender evaluation criteria. Monitor Poland's forward-based rapid deployment unit procurement acceleration as the signal indicating expeditionary tempo inflection and premium format demand expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Textile Membrane Production | Captures margin pools from specialized fabric engineering and reduces exposure to certified supplier bottlenecks. |
| STANAG Interoperability Certification Investment | Unlocks joint capability development program access across Germany, Poland, and United Kingdom defense procurement. |
| Low-Carbon Material Qualification Program | Positions for EU Green Deal tender preferences as Bundeswehr and allied forces embed carbon tracking into evaluation matrices. |
| Medical Facility Configuration Specialization | Opens premium tier demand from field hospital and casualty evacuation shelter procurements accelerating beyond personnel housing. |
| Extreme Climate Engineering Capability Buildout | Differentiates against standardized container-based competitors in Arctic and desert expeditionary training contracts. |
Research Approach
Multi-period observation of NATO framework agreement award patterns, defense procurement tender specifications, and aluminum-composite feedstock pricing anchored the trend analysis, supplemented by interviews with shelter systems integration engineers, Bundeswehr procurement officers, textile membrane manufacturing directors, and expeditionary logistics coordinators. Secondary validation drew from U.S. Department of Defense MIL-STD-810 and MIL-PRF-32505 documentation, NATO Standardization Office STANAG agreements, EU Green Deal carbon accounting guidance, and national defense infrastructure modernization program disclosures. Bottom-up shelter unit demand modeling triangulated against top-down NATO member state expeditionary operations budget allocations.
Segment-weighting across product type, end user, deployment mode, and operational size dimensions structured the analytical framework, with cross-dimensional interaction effects modeled for air-transportable medical configurations and expandable rapid deployment units. CAGRs were derived from deployment velocity projections tied to forward-based unit establishment timelines and framework agreement renewal cycles. Forecast inputs incorporated electromagnetic shielding certification backlog estimates, precision welding workforce development lag indicators, and bio-based resin system qualification timelines.
Inputs from defense procurement databases and shelter manufacturer technical documentation were available through the study window; gaps in classified expeditionary operations tempo planning introduce uncertainty bands around rapid deployment unit demand projections. Forecasts reflect assumptions regarding NATO interoperability mandate adherence timelines and EU carbon tracking enforcement intensity. Periodic stress-testing of base assumptions against aluminum price volatility and electromagnetic shielding testing capacity expansion is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Man Portable Military Electronics Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
Military Test Equipment Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Next Generation Military Power Supply Market
Military Equipment and Infrastructure
Global Stealth Warfare Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
Air-Based Remote Weapon Stations Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Howitzer Artillery System Market
Military Equipment and Infrastructure
Europe Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Wearable Computers Market