
 Deployable Military Shelter Systems Market | 2026-2036
Deployable Military Shelter Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Deployable Military Shelter Systems Market Analysis
The gap between legacy tent systems and integrated shelter platforms is narrowing as composite materials and modular architectures replace conventional canvas-and-aluminum designs. Saab AB leverages its aerospace heritage to dominate air-deployable shelter configurations. HDT Global anchors its position through sustained investment in environmental control systems that extend operational range across extreme climates.
Deployable military shelter systems are engineered structures designed for rapid assembly, disassembly, and transport to support personnel, equipment, and operations in expeditionary environments. These systems typically incorporate aluminum or composite framing with ballistic-rated fabric or hard-panel enclosures, achieving setup times under thirty minutes for standard configurations. Soft shelters lead volume demand due to their lighter logistics footprint and lower procurement cost, while hybrid shelters represent the fastest-expanding category as militaries seek combined hard/soft protection against kinetic and environmental threats. The defense forces end-user segment occupies the deepest margin pools given multi-year procurement contracts and technical qualification barriers that limit vendor entry.
The U.S. Department of Defense mandates MIL-STD-810 environmental testing and MIL-PRF-44103 shelter specifications, while NATO STANAG 2937 establishes interoperability benchmarks for multinational coalition operations. The EU Green Deal's embodied carbon requirements are beginning to shape material selection for European defense procurement, pressuring manufacturers to document lifecycle emissions. Stakeholders must monitor how emerging electromagnetic signature standards and climate resilience specifications reshape product roadmaps and supplier qualification timelines.
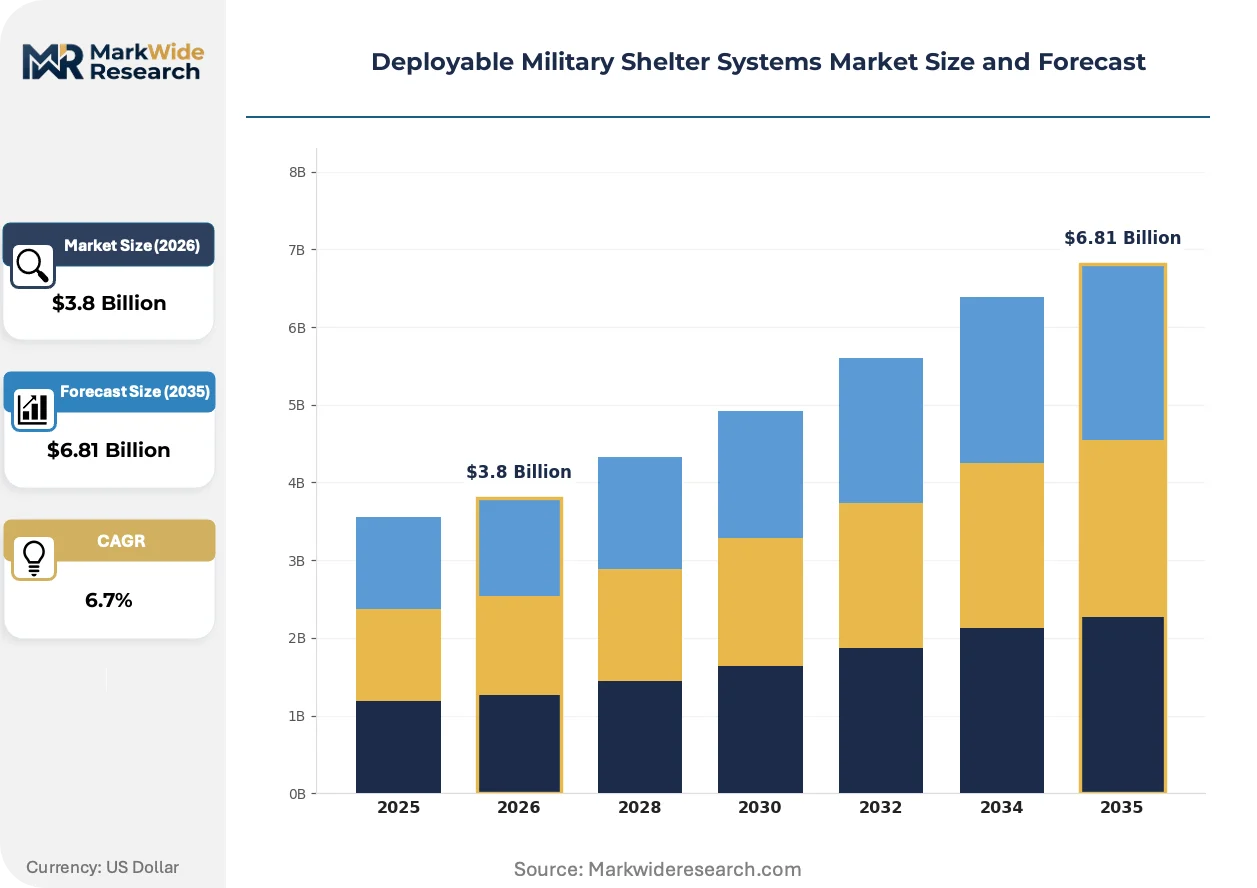
Market Dynamics
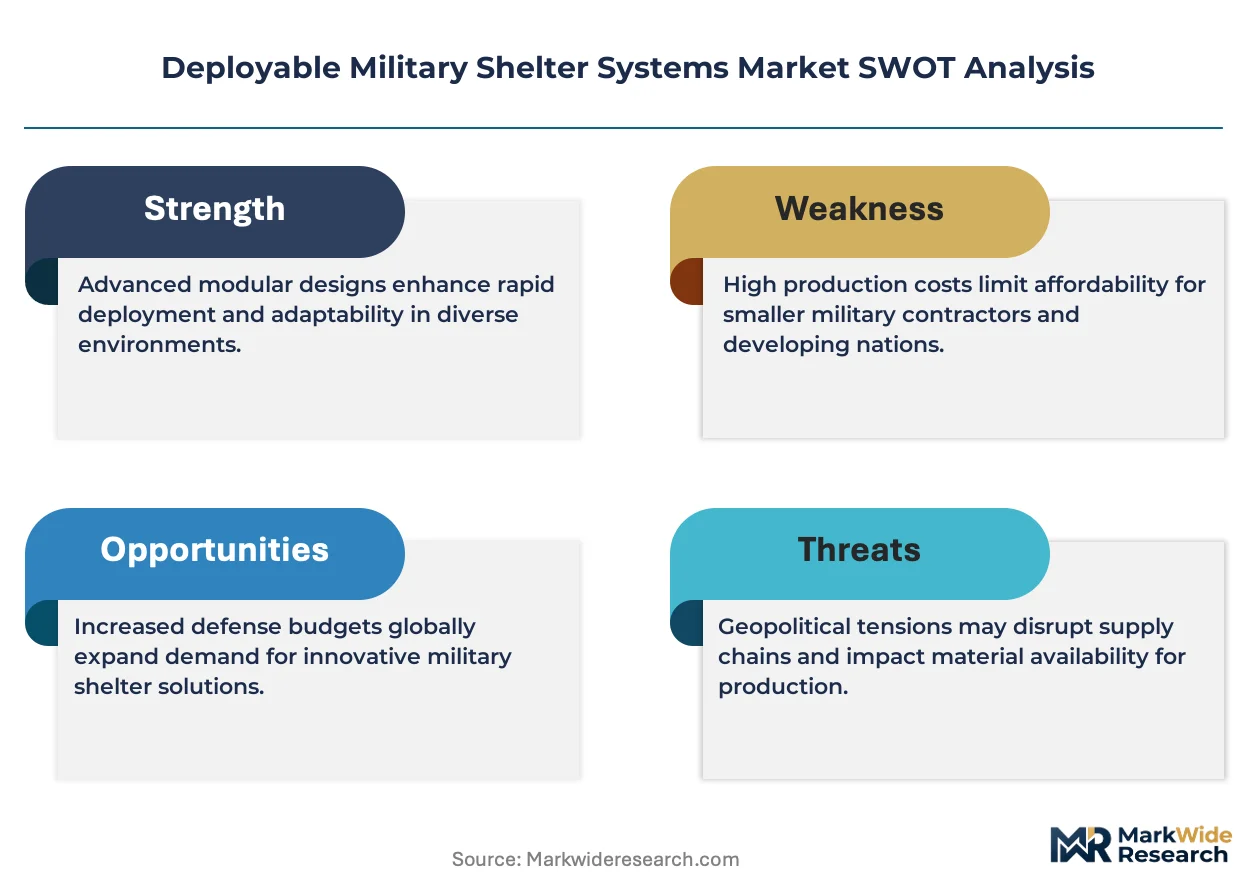
Expeditionary warfare doctrine is compressing deployment timelines, forcing shelter manufacturers to engineer sub-thirty-minute assembly systems that integrate power distribution, climate control, and CBRN protection within a single logistics footprint.
Growth Catalysts
- Expeditionary Force Modernization:NATO STANAG 2937 interoperability mandates are accelerating multinational procurement of standardized shelter platforms for coalition operations.
- Composite Material Adoption:Carbon-fiber framing and ballistic fabric laminates are reducing transport weight by forty percent versus legacy aluminum systems.
- United States Base Infrastructure:The Department of Defense's contingency preparedness programs sustain multi-year shelter replacement cycles across domestic and forward operating locations.
Market Restraints
- Aluminum Price Volatility:Primary aluminum input costs fluctuate with energy-intensive smelting economics, compressing margin on metal-intensive hard-panel shelters.
- Supplier Concentration:Ballistic-grade fabric weavers cluster in the United States and Western Europe, creating single-source vulnerability for armor-rated soft shelters.
- MIL-STD Qualification Burden:Environmental testing protocols extend product development cycles by eighteen to twenty-four months versus commercial equivalents.
Strategic Opportunities
- Arctic-Grade Climate Systems:Hardened environmental control units for extreme cold represent an underpenetrated segment as polar expeditionary operations expand.
- EU Green Deal Compliance:Embodied carbon documentation requirements create first-mover advantage for manufacturers with lifecycle emissions transparency.
- Electromagnetic Signature Reduction:Converging radar-absorbent materials with composite framing addresses emerging stealth requirements for forward command posts.
Industry Challenges
- Systems Integration Talent:Cross-functional engineers fluent in structural mechanics, HVAC, and electromagnetic compatibility remain scarce relative to program demand.
- Legacy Platform Interoperability:Retrofit compatibility with decades-old NATO shelter fleets complicates modular architecture design and testing matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deployable Military Shelter Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Shelters, Soft Shelters, Hybrid Shelters, Expandable Shelters End User: Defense Forces, Humanitarian Organizations, Disaster Relief Agencies, Private Contractors Deployment Mode: Ground Deployment, Air Deployment, Sea Deployment, Modular Arrangement Material: Tarpaulin, Aluminum, Fiberglass, Composite |
| Companies Covered | Saab AB, Marshall Aerospace and Defence Group Ltd., General Dynamics Corporation, Rubb Buildings Ltd., UTS Systems, HDT Global, Weatherhaven Global Resources Ltd., HTS TENTIQ GmbH, AAR CORP., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deployable Military Shelter Systems Market Emerging Trajectories
Material science breakthroughs and modular architecture standards are collapsing the traditional trade-off between shelter mobility and protection level, enabling platforms that reconfigure for threat environments without field depot support.
Ballistic-rated composite panels are migrating from specialized command-post applications to standard troop shelters. United States Marine Corps expeditionary units are field-testing these configurations for rapid force-projection scenarios. The technology is migrating from premium-tier procurement into volume production runs as manufacturing scale reduces unit cost curves.
EU Green Deal embodied carbon requirements are reshaping European defense procurement specifications. Manufacturers must now document cradle-to-grave emissions for aluminum extrusions, synthetic fabrics, and polymer coatings. French and German defense ministries are prioritizing suppliers with verified environmental product declarations in competitive tenders.
Performance-based logistics contracts are replacing traditional equipment-purchase agreements for large shelter programs. United States Army sustainment commands now contract for available shelter-days rather than owned inventory, transferring obsolescence risk to manufacturers. This model concentrates in contingency response units where deployment frequency exceeds storage economics.
Deployable Military Shelter Systems Market Segmentation
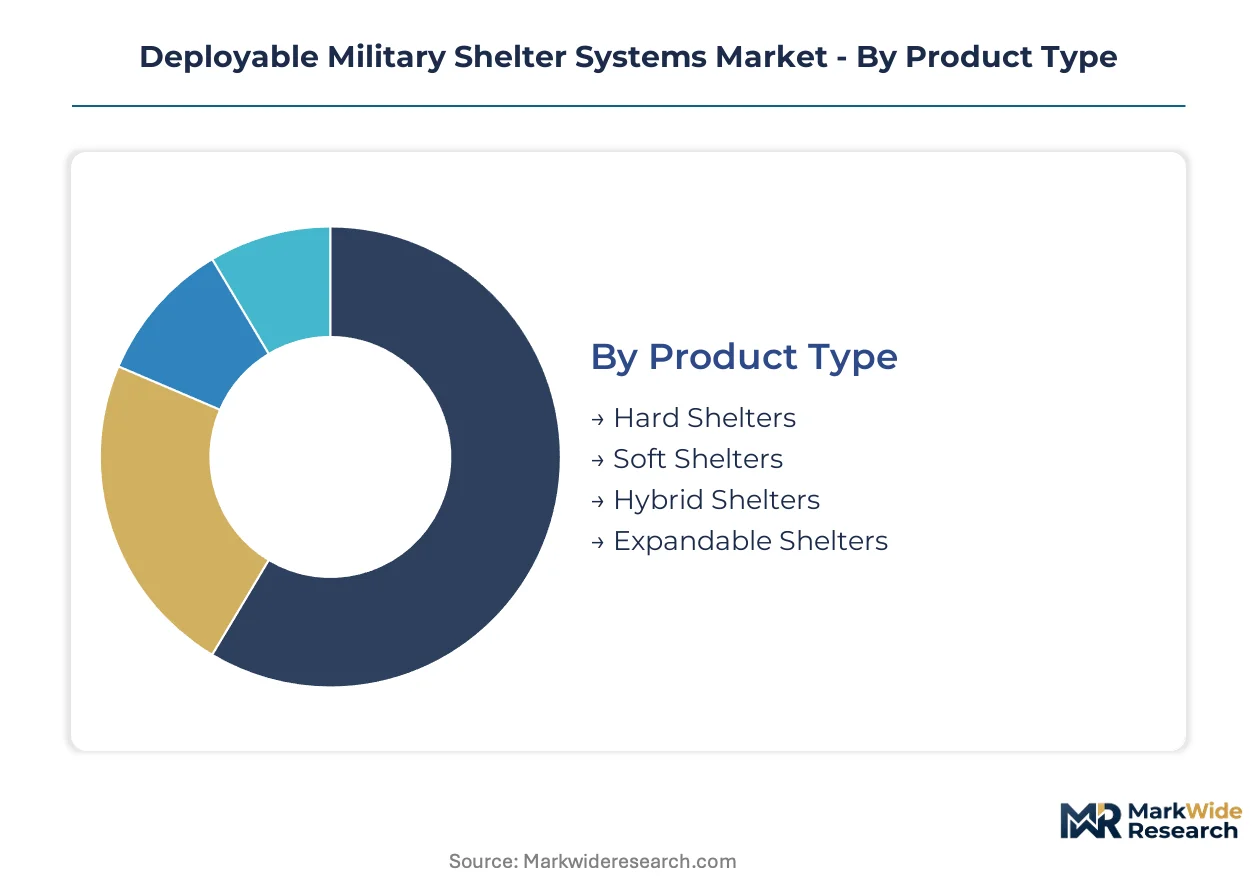
Deployable military shelter procurement divides sharply between expeditionary force requirements and fixed-base infrastructure, with material selection and deployment mode determining logistics compatibility across NATO coalition operations. Segmentation reveals where composite technologies displace legacy aluminum-and-canvas architectures.
Product Type:
Use cases span from permanent forward operating bases requiring hardened protection to rapid-response scenarios demanding thirty-minute assembly cycles.
- Soft Shelters:Ballistic-rated fabric enclosures with aluminum or composite framing achieve the lightest logistics footprint. United States expeditionary units prioritize these for airborne and light infantry deployments where transport weight constrains mission profiles.
- Hybrid Shelters:Combined hard-panel and fabric construction delivers kinetic protection against fragmentation while retaining modular reconfiguration. NATO STANAG 2937 interoperability testing accelerates procurement for multinational command posts requiring CBRN-overpressure capability.
- Hard Shelters:Rigid-panel systems provide maximum ballistic and environmental protection for fixed-site applications.
- Expandable Shelters:Mechanically deployed volumetric enclosures multiply interior space without external footprint expansion.
Established volume favors Soft Shelters; emerging adoption favors Hybrid Shelters.
End User:
Customer types range from multi-year defense procurement contracts to contingency-funded humanitarian operations with compressed decision cycles.
- Defense Forces:Multi-year shelter replacement programs sustain procurement through MIL-STD-810 qualification requirements. United States base modernization and contingency preparedness programs anchor demand with technical barriers limiting vendor entry.
- Humanitarian Organizations:UNHCR and ICRC procurement prioritizes rapid deployment over hardening. EU Green Deal embodied carbon documentation requirements increasingly shape competitive tender evaluation for European-funded operations.
- Disaster Relief Agencies:FEMA and equivalent national response units acquire shelters through emergency appropriations with accelerated delivery timelines.
- Private Contractors:Logistics and security firms purchase commercial-derivative shelters without full military qualification.
Defense Forces concentrate procurement value; Humanitarian Organizations expand fastest as climate-driven displacement accelerates.
Deployment Mode:
Transport modality determines structural engineering constraints from air-drop shock loading to maritime corrosion exposure.
- Air Deployment:Air-drop certified shelters withstand parachute shock and rough-field landing impact. United States Marine Corps expeditionary units field-test carbon-fiber framing configurations that reduce transport weight forty percent versus legacy systems.
- Ground Deployment:Standard truck and rail transport accommodates heavier hard-panel shelters with full environmental control integration.
- Sea Deployment:Marine-grade corrosion resistance and containerized packing dominate naval expeditionary requirements.
- Modular Arrangement:Interconnecting shelter units form integrated base complexes with shared power and climate systems.
Ground Deployment retains volume leadership; Air Deployment climbs fastest as expeditionary warfare doctrine compresses response timelines.
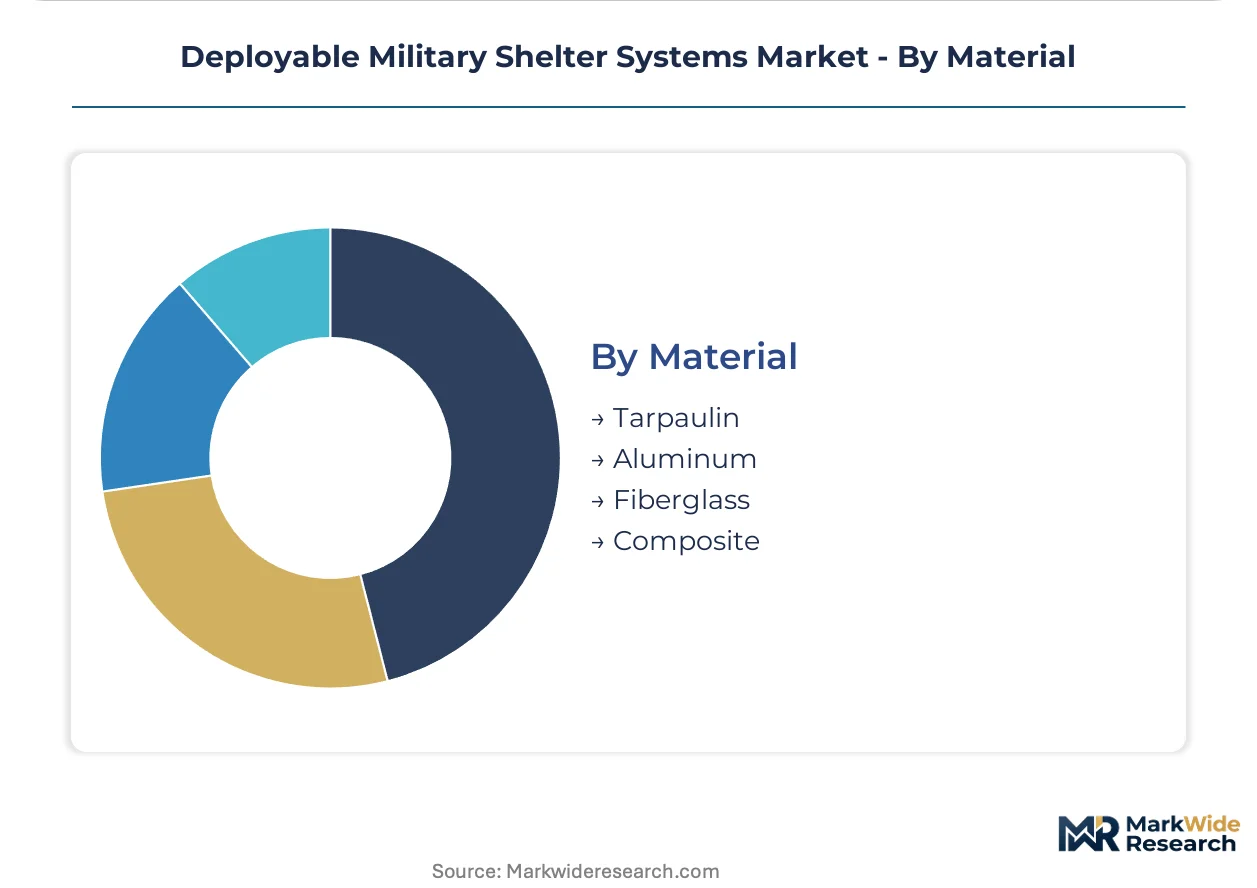
Material:
Input selection balances ballistic performance, environmental durability, and lifecycle emissions documentation under tightening procurement standards.
- Composite:Carbon-fiber and glass-reinforced polymer framing with ballistic fabric laminates delivers maximum strength-to-weight ratio. French and German defense ministries prioritize suppliers with verified environmental product declarations meeting EU Green Deal requirements.
- Aluminum:Extruded framing remains cost-competitive for volume procurement despite energy-intensive smelting economics and price volatility.
- Tarpaulin:PVC-coated polyester fabrics provide basic weather protection for training and humanitarian applications.
- Fiberglass:Molded panels offer electromagnetic transparency for communications and radar shelters.
Aluminum retains installed base dominance; Composite materials gain share fastest as embodied carbon transparency becomes mandatory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices and expeditionary force commands concentrate shelter demand across five national markets, each with distinct qualification requirements and operational doctrines shaping vendor access.
United States
Department of Defense contingency preparedness programs and base modernization cycles sustain multi-year procurement of hardened and soft shelter systems. MIL-STD-810 environmental testing and MIL-PRF-44103 specifications create technical barriers that limit qualified vendor pools. Huntsville, Alabama and the broader Tennessee Valley corridor host prime contractors integrating climate control and CBRN protection into expeditionary platforms.
Germany
Bundeswehr expeditionary force restructuring and NATO STANAG 2937 interoperability mandates drive standardization procurement for multinational coalition operations. EU Green Deal embodied carbon documentation requirements pressure manufacturers to verify lifecycle emissions for aluminum extrusions and synthetic fabrics. Munich and Stuttgart industrial clusters specialize in composite framing systems with environmental product declarations.
United Kingdom
Strategic Defence Review commitments to rapid reaction forces accelerate air-deployable shelter acquisition with sub-thirty-minute assembly requirements. Ministry of Defence procurement aligns with NATO standardization agreements while incorporating national electromagnetic signature standards. Bristol and southwest England host aerospace-heritage contractors leveraging carbon-fiber manufacturing capabilities.
France
Direction Générale de l'Armement prioritizes hybrid shelter configurations combining hard-panel protection with modular reconfiguration for African and Middle Eastern expeditionary deployments. EU Green Deal compliance documentation increasingly shapes competitive tender evaluation criteria. Toulouse and Occitanie defense industrial bases integrate ballistic-rated composite panel production with environmental certification processes.
Australia
Australian Defence Force regional force projection requirements and Indo-Pacific contingency planning expand procurement of sea-deployable containerized shelter systems. Department of Defence mandates corrosion-resistant marine-grade specifications for naval expeditionary platforms. Adelaide and South Australian shipbuilding clusters adapt containerized shelter architectures for amphibious operations.
Deployable Military Shelter Systems Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a market structured by MIL-STD qualification barriers and multi-year defense procurement cycles. Prime contractors with integrated systems capabilities anchor the premium tier, while component specialists occupy mid-market positions. Two strategic archetypes dominate: aerospace-heritage integrators leveraging composite manufacturing expertise, and environmental control specialists extending operational range through HVAC integration. Competitive moves concentrate on strategic partnerships for NATO interoperability certification and backward integration into ballistic fabric weaving to reduce single-source supplier vulnerability.
Within the aerospace-heritage integrator tier, Saab AB and Marshall Aerospace and Defence Group Ltd. exemplify players converting aircraft composite capabilities into air-deployable shelter configurations. HDT Global occupies a distinct position as an environmental control specialist, anchoring market presence through climate system integration rather than structural fabrication. These three companies represent how divergent technical origins—Swedish aerospace, British defense engineering, and American environmental systems—converge on expeditionary shelter platforms through qualification-driven procurement channels.
| Leading Market Players |
|---|
| Saab AB |
| Marshall Aerospace and Defence Group Ltd. |
| General Dynamics Corporation |
| Rubb Buildings Ltd. |
| UTS Systems |
| HDT Global |
| Weatherhaven Global Resources Ltd. |
| HTS TENTIQ GmbH |
| AAR CORP. |
| Others |
Supply Flow & Price Mechanics
Trans-Atlantic freight corridors from Hamburg to Norfolk anchor cost dynamics that compress margins on aluminum-intensive hard-panel shelters while enabling premium pricing for air-deployable composite systems. Supply concentration in German and French composite manufacturing clusters feeds downstream price differentiation between NATO-qualified and commercial-derivative shelter tiers.
Pricing Analysis
Cost-plus contracts with London Metal Exchange aluminum indexation dominate procurement for hard-panel shelters, while performance-based logistics agreements fix pricing per available shelter-day for expeditionary units. Price differentiation separates MIL-STD-810 qualified platforms from commercial training shelters, with certification grade and CBRN integration level as primary tiering factors. Pricing pressure stems from primary aluminum smelting energy costs, compressing margins on metal-framed systems. Defense procurement offices show lowest price sensitivity given mission-critical requirements, while humanitarian organizations and private contractors concentrate demand in cost-optimized soft shelter tiers.
Supply Chain Analysis
ITAR and EU dual-use export controls restrict ballistic-grade fabric laminate flows from United States and Western European weavers to qualified defense contractors. Supply concentrates in German carbon-fiber framing facilities, French composite panel molding operations, and American ballistic fabric production. Raw material dependencies center on aerospace-grade carbon fiber prepreg, aramid fiber weaves, and corrosion-resistant aluminum alloys. Single-source vulnerability in certified fabric weaving creates supply chain risk. Distribution runs through prime contractor integration facilities in Huntsville, Munich, and Bristol before military logistics channels deliver to expeditionary force commands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deployable military shelter systems sit in early-cycle expansion as expeditionary warfare doctrine accelerates adoption of sub-thirty-minute assembly platforms. NATO STANAG 2937 interoperability mandates are extending addressable demand beyond national replacement cycles into multinational coalition procurement.
For Market Incumbents: Insulate qualified vendor positions through backward integration into ballistic fabric weaving to eliminate single-source supplier vulnerability. Secure multi-year performance-based logistics contracts with United States Army sustainment commands before competitor qualification cycles complete. Anchor capacity in German and French industrial clusters with verified EU Green Deal environmental product declarations to capture European defense procurement preference shifts. For New Entrants and Emerging Players: Arctic-grade climate system integration represents underpenetrated white space as polar expeditionary operations expand without incumbent HVAC specialization. Electromagnetic signature reduction for forward command posts offers second entry angle with limited qualified competition. Pursue subcontractor qualification through prime contractor supply chain partnerships rather than direct MIL-STD-810 certification to compress market entry timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace conglomerates with dormant composite manufacturing capabilities applicable to shelter framing. Long-term viability rests on positioning for climate resilience specification expansion and electromagnetic compatibility requirements across NATO procurement. Monitor United States Marine Corps expeditionary unit field-test outcomes as inflection signal for carbon-fiber platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ballistic Fabric Weaving | Eliminates single-source supplier vulnerability for armor-rated soft shelters under NATO STANAG 2937. |
| EU Green Deal Environmental Product Declaration | Unlocks competitive tender priority in French and German defense ministry procurement evaluation. |
| Performance-Based Logistics Contract Conversion | Transfers obsolescence risk to manufacturers while securing multi-year shelter-day revenue streams. |
| Arctic-Grade Climate System Development | Addresses polar expeditionary operations expansion without incumbent HVAC specialist competition. |
| Electromagnetic Signature Reduction Certification | Captures emerging stealth requirements for forward command posts in United States and United Kingdom procurement. |
Methodological Framework
Operator-level perspectives from expeditionary force commanders, defense procurement officers, shelter program managers, and environmental control system engineers anchored the qualitative base. Primary interview insights combined with secondary validation from NATO STANAG documentation, United States Department of Defense MIL-STD specifications, EU Green Deal regulatory filings, and customs trade data for aluminum and carbon fiber inputs. Bottom-up shelter unit demand modeling triangulated against top-down defense budget allocation analysis.
Scenario-bracketing framed volume and value outputs across the analysis window, with segmentation dimensions covering product type, end-user category, deployment mode, and material composition. CAGRs derived from weighted average of historical procurement cycle analysis and doctrine-driven demand projection. Industry-specific forecast inputs incorporated expeditionary warfare timeline compression targets and EU embodied carbon documentation phase-in schedules.
Practitioners should monitor NATO interoperability certification queue lengths and United States Marine Corps field-test outcome releases for early signals of platform preference shifts. Forecasts reflect assumptions regarding aluminum price stability and composite manufacturing scale-up timelines. Material shifts in electromagnetic signature standards or polar expeditionary operation funding would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Defense Logistics Market
Military Equipment and Infrastructure
Latin America Defense Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
FLIR and Laser Designator Targeting Pods Market
Military Equipment and Infrastructure
Global Remote Weapon Station Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global CBRN Defense Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Global Landing String Equipment Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
Military Image Intensifier Tube Market
Military Equipment and Infrastructure
Air-Based Remote Weapon Stations Market
Military Equipment and Infrastructure
Global Stealth Warfare Market
Military Equipment and Infrastructure
Europe Military Aircraft Modernization and Retrofit Market