
 Howitzer Artillery System Market | 2026-2036
Howitzer Artillery System Market Size, Share, and Industry Trends Forecast 2026-2036
Howitzer Artillery System Market Analysis
Poland's military industrial expansion is reshaping trans-Atlantic howitzer supply dynamics. Rheinmetall leverages its new Polish manufacturing footprint to anchor Central European production capacity. KNDS sustains Franco-German design leadership through the Caesar and PzH 2000 platforms. BAE Systems competes across NATO markets with the M777 lightweight towed system.
A howitzer artillery system is a long-barrel, large-caliber indirect-fire weapon typically mounted on wheeled or tracked carriages, designed to deliver high-explosive projectiles across 15–40 kilometer ranges using 105mm to 300mm ammunition with split or modular propellant charges. Its primary purpose is to provide sustained, responsive fires against area targets, fortified positions, and armored formations in combined arms operations. Self-propelled 155mm platforms dominate procurement budgets due to their shoot-and-scoot survivability against counter-battery radar. Automated loading and digital fire control systems represent the fastest-growing operating mode segment as militaries reduce crew sizes and cut response times below two minutes. Towed systems retain relevance in expeditionary and air-mobile roles where strategic lift constraints favor lighter deployable weights.
The U.S. Department of Defense, NATO Standardization Office, and EU Permanent Structured Cooperation (PESCO) frameworks collectively define interoperability, safety, and performance benchmarks for cross-border howitzer operations. NATO's Ballistic Meteorology and Ammunition Working Groups mandate standardized 155mm projectile and propellant specifications that shape supplier qualification and market access. Procurement officers must weigh automated system integration costs against legacy fleet upgrade paths as ammunition commonality requirements tighten.
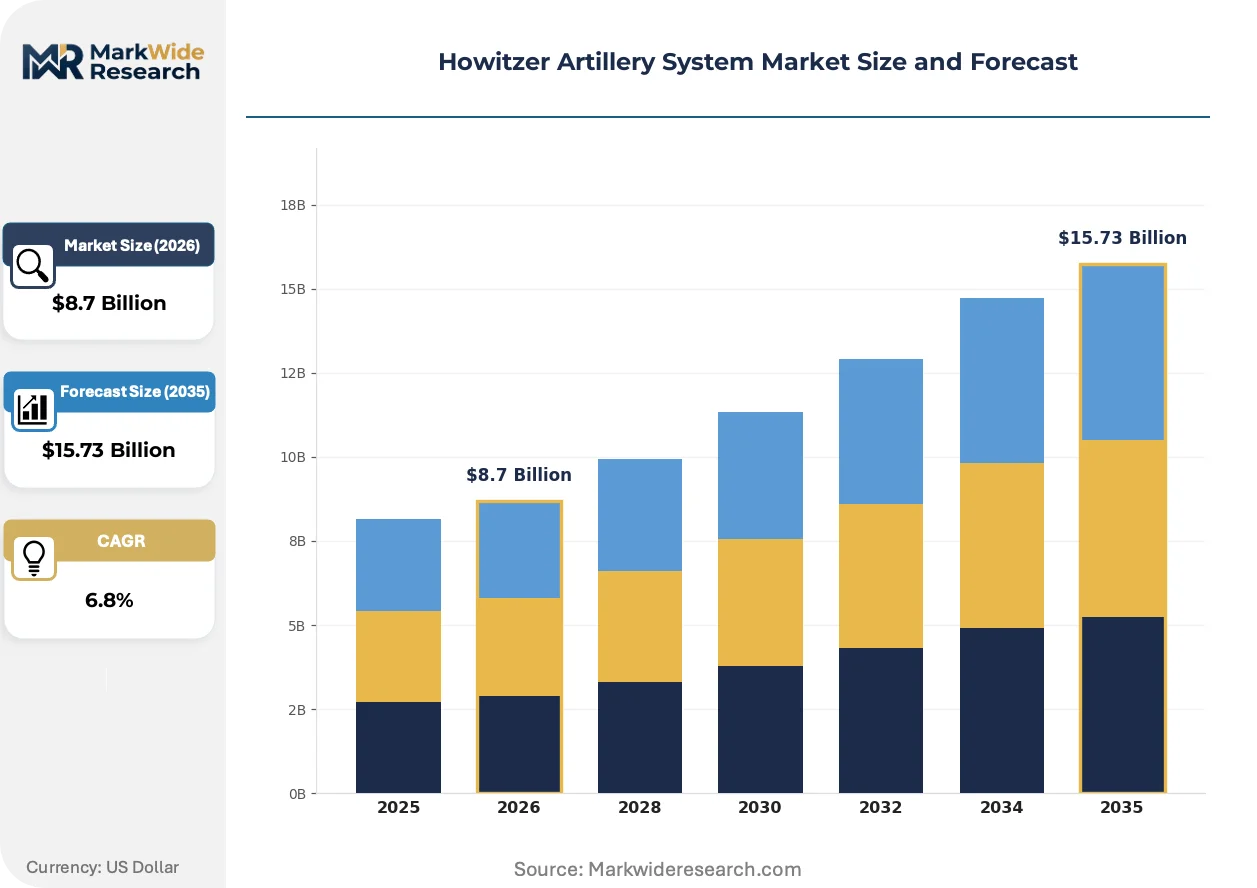
Market Dynamics
NATO's ammunition standardization mandates and the EU Permanent Structured Cooperation framework are compressing procurement timelines while forcing interoperability across national fleets. Defense ministries now prioritize platforms that integrate with shared digital fire control networks.
Growth Catalysts
- EU PESCO Framework:The Permanent Structured Cooperation mechanism pools member state R&D funding for cross-border artillery modernization programs. Joint procurement clauses reduce per-unit costs for automated loading systems.
- 155mm Ammunition Commonality:NATO's Ballistic Meteorology and Ammunition Working Groups have locked in projectile specifications. Standardized propellant charges simplify logistics chains across allied operations.
- Counter-Battery Radar Proliferation:Russian and Chinese sensor exports to conflict zones have accelerated demand for shoot-and-scoot mobility. Self-propelled platforms with sub-two-minute displacement cycles now dominate force planning.
Market Restraints
- Tungsten Supply Concentration:Penetrator core production depends on Chinese and Russian raw material flows. Export licensing volatility disrupts just-in-time manufacturing schedules for armor-piercing rounds.
- Barrel Steel Input Costs:High-grade chromium-molybdenum alloys face energy-intensive smelting requirements. European electricity pricing instability compresses forging margins at specialty metallurgy suppliers.
- REACH Chemical Compliance:The European Chemicals Agency restricts certain propellant stabilizers and bore-cleaning solvents. Reformulation R&D extends qualification timelines for ammunition lines.
Strategic Opportunities
- Polish Industrial Expansion:The country's military modernization program allocates substantial procurement volume to domestic assembly partnerships. Foreign primes can anchor Central European supply chains through local content mandates.
- AI-Enabled Fire Control:Machine learning algorithms for meteorological compensation and target tracking are converging with hardened military electronics. Early adopters gain first-mover advantage in automated battery coordination.
- US Army Long-Range Precision Fires:The Extended Range Cannon Artillery program creates demand for supercharged propellant and extended-length barrels. Component suppliers can penetrate a captive modernization pipeline.
Industry Challenges
- Gunsmith Trade Shortage:Precision barrel rifling and breech mechanism fitting require multi-year apprenticeships. Aging workforces at European arsenals constrain output scaling without knowledge transfer programs.
- Legacy System Integration:Digital fire control retrofits for 1980s-era towed howitzers demand custom mechanical-to-electrical interface engineering. Each national fleet requires bespoke adapter development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Howitzer Artillery System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Self-Propelled, Towed, Heavy, Lightweight Caliber: 105mm, 155mm, 200mm, 300mm Operating Mode: Conventional, Automated, Hybrid, Digital End User: Military, Defense Contractors, Government, Exporters |
| Companies Covered | Rheinmetall, KNDS, BAE Systems, NORINCO Group, Leonardo DRS, Elbit Systems, General Dynamics, Larsen & Toubro, Hanwha Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Howitzer Artillery System Market Emerging Trajectories
Electronics miniaturization and hardened computing architectures are enabling capabilities that were physically impossible in Cold War-era platforms. The convergence of automation, connectivity, and propellant chemistry is redefining crew requirements and tactical employment.
Modular charge systems with insensitive munitions propellant are hybridizing legacy ammunition logistics with next-generation safety standards. Artillery brigades in Poland and Germany are field-testing these configurations during live-fire certification cycles. The technology is hybridizing supply chain planning by allowing common inventory pools for both training and combat loads.
The EU AI Act's risk classification framework now captures autonomous target recognition modules in fire control computers. Manufacturers must demonstrate human-in-the-loop validation protocols before platform deployment. Self-propelled howitzer programs with automated laying systems face extended compliance timelines in member state procurement pipelines.
Defense ministries are consolidating maintenance contracts under performance-based logistics arrangements rather than transactional spare-part purchasing. Original equipment manufacturers in the United States and Germany are absorbing depot-level repair functions previously executed by uniformed technicians. Poland's military industrial expansion shows this shift most visibly, with Rheinmetall assuming full lifecycle accountability for domestically assembled platforms.
Howitzer Artillery System Market Segmentation
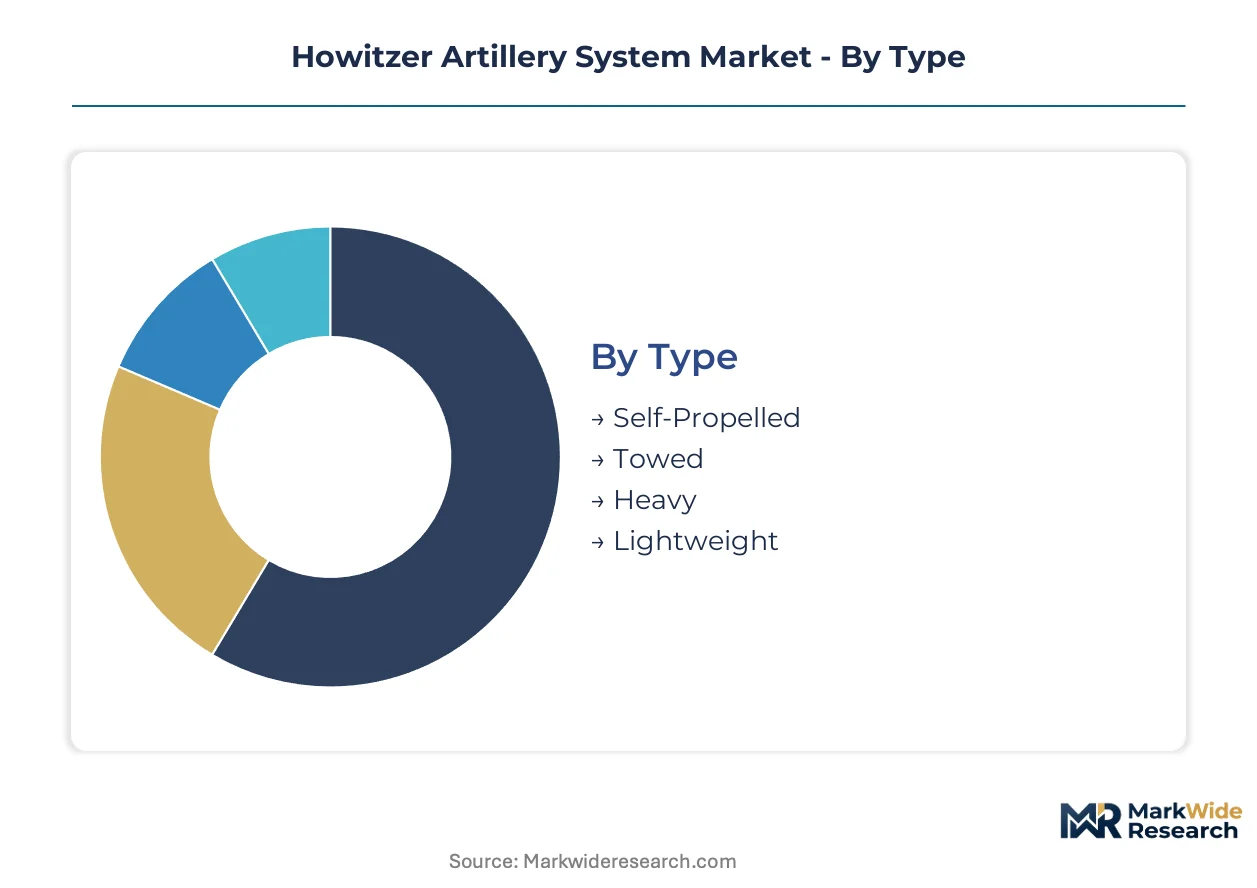
Howitzer procurement cycles vary dramatically by platform complexity, with automated systems requiring decade-long development timelines while towed variants refresh every five to seven years. Defense ministries weigh these rhythms against threat evolution when allocating modernization budgets across fleet categories.
Type:
Self-propelled platforms command the longest production cycles due to automotive-ordnance integration complexity, while towed systems turn over fastest from contract award to fielding.
- Self-Propelled:Tracked or wheeled chassis integrate turret-mounted 155mm ordnance with armor protection and automotive mobility. Poland's military modernization program anchors European demand for these shoot-and-scoot platforms as counter-battery radar proliferation accelerates displacement requirements.
- Towed:Lightweight carriages deploy by helicopter or tactical aircraft for expeditionary operations. The U.S. Army's airborne and light infantry formations sustain procurement of air-mobile systems where strategic lift constraints override survivability concerns.
- Heavy:Extended-range barrels and reinforced recoil systems exceed 50-ton combat weights. NATO's Ballistic Meteorology Working Group qualification protocols extend development timelines for these specialized platforms.
- Lightweight:Titanium or advanced aluminum alloys reduce emplacement weights below four tons. Mountain warfare units in Italy and Switzerland prioritize these systems for high-altitude deployment scenarios.
Self-propelled platforms anchor the volume base while automated variants gain share at the steepest rate.
Caliber:
Procurement economics stratify sharply by ammunition commonality, with standardized rounds reducing logistics burdens while niche calibers impose dedicated supply chain investments.
- 155mm:NATO's Ballistic Meteorology and Ammunition Working Groups have locked in projectile specifications that dominate allied inventories. Germany's KNDS and Rheinmetall compete for this standardized segment where interoperability mandates compress supplier qualification barriers.
- 105mm:Lightweight ammunition suits rapid deployment and training economies. The U.S. Marine Corps and allied expeditionary forces sustain demand for these systems where ammunition weight constrains sustainment planning.
- 200mm:Soviet-legacy platforms persist in Eastern European inventories requiring ammunition continuity. Specialized propellant production lines at Polish and Czech arsenals service this declining but still material fleet segment.
- 300mm:Rocket-assisted projectiles and extended-range charges stretch barrel life and recoil engineering. Russian and Chinese artillery exports to Middle Eastern and African clients sustain limited Western production of counter-battery systems in this caliber class.
155mm systems generate the dominant procurement volume while 105mm platforms expand most quickly in expeditionary force structures.
Operating Mode:
Automation depth determines crew size, response latency, and software qualification burden, with fully digital systems requiring multi-year cybersecurity certification cycles.
- Conventional:Manual laying, loading, and fire direction demand four to six crew members with extensive training pipelines. Legacy fleets in Southern and Eastern Europe retain these systems where upgrade funding competes with personnel expenditures.
- Automated:Mechanical ammunition handling and autonomous laying reduce crews to two or three soldiers while cutting emplacement times below 90 seconds. The EU AI Act's risk classification framework now extends compliance timelines for these platforms through human-in-the-loop validation mandates.
- Hybrid:Partial automation of specific functions—typically ammunition transfer or breech operation—bridges legacy and fully digital architectures. Defense contractors in Germany and the United States market these retrofits as cost-conscious modernization paths for 1990s-era fleets.
- Digital:Networked fire control with machine-learned meteorological compensation and automated target handoff. U.S. Army Long-Range Precision Fires program investments are accelerating fielding of these capabilities despite software vulnerability assessment requirements.
Conventional systems retain the installed base while digital platforms climb the fastest in new procurement allocations.
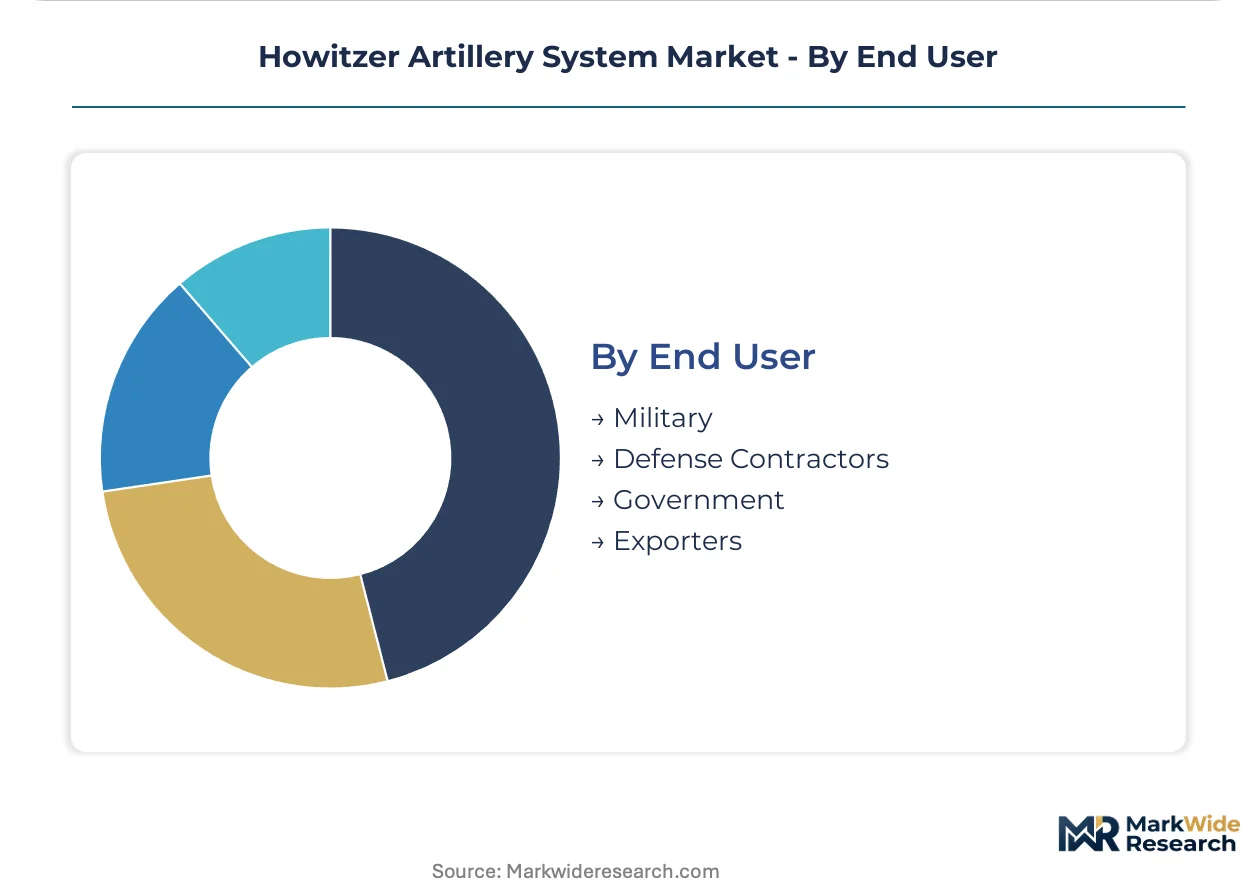
End User:
Contracting authority and funding mechanisms segment demand by procurement flexibility, with military end-users facing rigid appropriations cycles while defense contractors access private capital for speculative development.
- Military:Uniformed acquisition commands in NATO member states execute multi-year procurement with congressional or parliamentary oversight. Poland's Ministry of National Defense exemplifies this segment through its accelerated artillery modernization timeline.
- Defense Contractors:Prime integrators purchase subsystems and components for incorporation into platform deliveries. Rheinmetall's Polish manufacturing footprint sources barrel forgings and fire control modules through this channel.
- Government:Non-military security agencies and coast guard organizations acquire reduced-capability systems for territorial defense. Estonia and Latvia have routed Baltic defense funding through this classification for coastal artillery applications.
- Exporters:Foreign military sales intermediaries and licensed production arrangements transfer technology to allied nations. U.S. State Department Direct Commercial Sales and Pentagon Foreign Military Sales programs structure these transactions with end-use monitoring requirements.
Military end-users dominate procurement volume while defense contractor purchasing expands most rapidly through supply chain localization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Howitzer manufacturing concentrates in Germany, Poland, and the United States as NATO members accelerate 155mm platform procurement. Defense ministries in these countries anchor trans-Atlantic supply chains through localized assembly mandates and joint procurement frameworks.
United States
The U.S. Army's Long-Range Precision Fires program drives demand for extended-range artillery platforms with automated fire control systems. Pentagon acquisition timelines compress under the National Defense Authorization Act's rapid fielding authorities. Manufacturing clusters in Michigan and Alabama host prime integrators supplying NATO-standard 155mm systems.
Germany
KNDS and Rheinmetall anchor European howitzer production through Franco-German design partnerships and domestic assembly lines. EU Permanent Structured Cooperation frameworks pool R&D funding for cross-border artillery modernization. The Kassel and Unterlüß industrial corridors specialize in precision barrel forging and turret integration for export markets.
Poland
Poland's Ministry of National Defense executes Europe's fastest artillery modernization through domestic assembly partnerships with foreign primes. NATO ammunition standardization mandates enable interoperability with allied logistics chains. Rheinmetall's new Poznań facility anchors Central European production capacity for 155mm self-propelled platforms.
South Korea
Hanwha Aerospace supplies NATO-compatible artillery systems through licensed production and direct export arrangements. The country's defense procurement agency accelerates indigenous platform development under offset agreements with European primes. Changwon and Seoul metropolitan clusters concentrate precision manufacturing for automated loading mechanisms.
India
India's artillery modernization prioritizes 155mm towed and self-propelled systems under the Make in India defense manufacturing initiative. Larsen & Toubro anchors domestic production through technology transfer agreements with foreign OEMs. The Pune and Hyderabad industrial corridors specialize in barrel forging and fire control subsystem integration.
Howitzer Artillery System Market Vendor Landscape
European primes and U.S. defense contractors split the market between NATO-standard platforms and expeditionary lightweight systems. Consolidation around automated fire control and shoot-and-scoot mobility has compressed the viable supplier base to tier-one integrators with trans-Atlantic certification. Two archetypes dominate: full-system primes controlling turret-to-chassis integration, and subsystem specialists supplying barrel forgings and digital fire control modules. Capacity expansion in Central Europe and strategic partnerships for ammunition commonality represent the dominant competitive moves.
Among European full-system primes, Rheinmetall and KNDS exemplify the integrated-platform archetype through their positions in German and Franco-German artillery development. BAE Systems occupies a position bridging NATO expeditionary requirements with lightweight towed system specialization. These three anchors demonstrate how geographic proximity to NATO standardization bodies and defense ministry procurement commands shapes competitive positioning in this tightly regulated segment.
| Leading Market Players |
|---|
| Rheinmetall |
| KNDS |
| BAE Systems |
| NORINCO Group |
| Leonardo DRS |
| Elbit Systems |
| General Dynamics |
| Larsen & Toubro |
| Hanwha Aerospace |
| Others |
Supply Flow & Price Mechanics
Overcapacity at European specialty steel forges is compressing barrel forging margins while simultaneously granting procurement officers leverage in long-term platform contracts. This utilization asymmetry between upstream metallurgy and downstream system integration reshapes how defense ministries negotiate automated howitzer acquisitions.
Pricing Analysis
EU PESCO framework joint procurement clauses dictate the pricing tier structure for NATO member state acquisitions. Three-tier pricing structure across premium automated systems, standard self-propelled platforms, and economy towed configurations stratifies by automation depth and integration complexity. Cost compression in the standard tier is intensifying because Polish domestic assembly partnerships are absorbing lifecycle service margins previously captured by foreign primes. Expeditionary forces with air-mobile requirements exhibit the highest price sensitivity due to competing helicopter procurement priorities, while continental heavy armor formations prioritize capability over unit cost.
Supply Chain Analysis
Chromium-molybdenum alloy feedstock draws from German, Austrian, and Swedish specialty metallurgy suppliers with limited alternative sourcing. High-grade barrel steel, automated loading mechanism servo motors, and digital fire control hardened electronics constitute critical component dependencies. Single-source vulnerability concentrates in precision rifling equipment where German and Swiss machine tool builders dominate installed capacity. Distribution runs through prime integrator direct contracting with national defense ministries, supplemented by Foreign Military Sales channels for allied procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation between automated and conventional operating modes creates distinct competitive arenas where specialized subsystem suppliers can outmaneuver full-platform primes. NATO ammunition standardization is splintering demand into retrofit-upgrade versus clean-sheet procurement niches.
For Market Incumbents: Entrench automated fire control certification advantages through accelerated EU AI Act compliance timelines that smaller competitors cannot match. Deepen backward integration into barrel forging capacity at the Kassel industrial corridor to offset tungsten supply concentration risks from Chinese export licensing volatility. Absorb depot-level maintenance functions under performance-based logistics contracts to lock out aftermarket specialists. For New Entrants and Emerging Players: Mid-caliber 105mm expeditionary systems for NATO rapid reaction forces represent the most penetrable entry point given lighter regulatory qualification burdens. Digital fire control module retrofits for 1990s-era towed howitzer fleets in Southern and Eastern Europe offer second-mover revenue without full-platform development exposure. Pursue offset-driven partnerships with Poland's Ministry of National Defense to anchor Central European supply chain credibility. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated loading mechanism manufacturing as robotics integration demands expand. Long-term viability favors acquisition targets with established NATO Ballistic Meteorology Working Group qualification histories and transferable barrel forging apprenticeships. Monitor Polish industrial absorption rates as the inflection signal for Central European production capacity saturation.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Partnership | Rheinmetall's Poznań facility anchors EU PESCO-compliant production for Polish 155mm programs. |
| Automated Loading Mechanism Scale-Up | Hanwha Aerospace's Changwon cluster expands servo motor output for NATO-standard platforms. |
| Digital Fire Control Certification | EU AI Act human-in-the-loop validation extends compliance timelines for automated laying systems. |
| Performance-Based Logistics Consolidation | KNDS absorbs German Army depot repair functions previously executed by uniformed technicians. |
| Extended-Range Barrel Development | U.S. Army Long-Range Precision Fires program creates captive demand for supercharged propellant integration. |
Methodological Framework
Operator-level perspectives from artillery program executives at defense ministries, barrel forging plant managers, NATO standardization committee members, and fire control systems engineers anchored the qualitative base. Secondary validation drew from EU Permanent Structured Cooperation procurement disclosures, U.S. National Defense Authorization Act rapid fielding authorities, NATO Ballistic Meteorology Working Group technical specifications, and SEC 10-K filings from listed defense contractors. Bottom-up platform delivery tallies and top-down defense budget appropriation analysis were triangulated to constrain estimate variance.
Scenario-bracketing around counter-battery radar proliferation rates and EU AI Act compliance timeline uncertainty shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include platform type, caliber, operating mode automation depth, and end-user contracting authority. CAGRs were derived from fitted growth curves against historical procurement cycles and announced modernization program schedules. Inputs incorporated announced Polish military modernization allocations, U.S. Army Long-Range Precision Fires investment trajectories, and REACH chemical compliance cost pass-through assumptions.
Stress conditions across tungsten export licensing volatility, European electricity pricing instability, and gunsmith apprenticeship pipeline constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about NATO ammunition standardization adherence and PESCO framework durability. Cross-checking against national defense ministry budget execution reports and Foreign Military Sales notification databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
NATO Defense Market
Military Equipment and Infrastructure
Land Digital Battlefield Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
Military Tent and Shelter Market
Military Equipment and Infrastructure
Europe Digital Battlefield Market
Military Equipment and Infrastructure
Military Test Equipment Market
Military Equipment and Infrastructure
Air-Based Remote Weapon Stations Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Global Soldier Modernization Market
Military Equipment and Infrastructure
Rubber Tracks for Defense and Security Market
Military Equipment and Infrastructure
Global Remote Weapon Station Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Aircraft Carrier Arresting Systems Market
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market
Military Equipment and Infrastructure
FLIR and Laser Designator Targeting Pods Market
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market