
 Aircraft EMI Shielding Market | 2026-2036
Aircraft EMI Shielding Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft EMI Shielding Market Intelligence
The Federal Aviation Administration's (FAA) updated airworthiness directives on radio altimeter tolerance is decoupling legacy shielding performance from new certification requirements for commercial aircraft. This regulatory shift creates opportunities for specialized material suppliers. Parker Hannifin Corporation leverages its extensive portfolio of conductive elastomers and gaskets to meet these stringent standards. Henkel AG & Co. KGaA specializes in conductive coatings and adhesives for complex electronic enclosures.
Aircraft EMI shielding is the practice of protecting sensitive avionics from electromagnetic interference generated by internal and external sources. It utilizes materials like conductive coatings or metal shielding to block or absorb unwanted radio frequency signals, ensuring operational integrity. Conductive coatings and lightweight absorbers are increasingly preferred over heavier metal shielding for modern airframes. The commercial aviation sector constitutes the primary end user, but the UAV segment represents the fastest-growing market due to its dense electronic payloads.
Compliance with standards such as the FAA's regulations, the European Union Aviation Safety Agency's directives, and military specifications like MIL-STD-461 is mandatory for market access. These frameworks dictate the required attenuation performance and environmental testing for all shielding components on an aircraft. Material selection decisions will increasingly balance electromagnetic performance against weight, cost, and resistance to harsh aerospace environments.
Market Dynamics
The market's central dynamic is the tension between rising electronic density and strict airframe weight limits. This conflict forces a departure from heavy metallic shielding, a shift accelerated by new regulatory pressures from the FAA regarding 5G interference.
Growth Catalysts
- UAV Proliferation:The dense packaging of sensors, communication links, and flight controls in unmanned aerial vehicles necessitates sophisticated, compact shielding solutions to prevent self-interference and ensure mission reliability.
- 5G Interference Mandates:Directives from the FAA and EASA requiring mitigation of potential 5G C-band interference with radio altimeters create a non-discretionary need for new or upgraded shielding on commercial aircraft.
- Cabin Modernization:The push for enhanced in-flight entertainment and passenger connectivity on commercial airliners increases the amount of onboard electronics, requiring more comprehensive cabin-level EMI shielding.
Market Restraints
- Material Cost:The high cost of advanced conductive polymers and lightweight composite absorbers compared to traditional aluminum or copper mesh makes them prohibitive for some cost-sensitive general aviation applications.
- Retrofit Complexity:Integrating modern shielding solutions into legacy aircraft fleets is technically challenging and costly, often requiring extensive recertification and creating a barrier to widespread adoption on older airframes.
- Specialized Supply Base:The supply of aerospace-grade shielding materials compliant with RTCA DO-160 is concentrated among a few qualified vendors, creating potential procurement bottlenecks and price sensitivity.
Strategic Opportunities
- Urban Air Mobility (UAM):The emerging market for electric vertical takeoff and landing (eVTOL) aircraft, with their all-electric powertrains and complex fly-by-wire systems, presents a greenfield opportunity for integrated shielding solutions.
- Multifunctional Composites:There is significant opportunity in developing materials that combine EMI shielding with other properties, such as thermal management or structural reinforcement, reducing overall component count and weight.
- Indian Aerospace Growth:India's expanding domestic aerospace manufacturing ecosystem, supported by government initiatives, offers a new geographic market for shielding suppliers to target beyond North America and Europe.
Industry Challenges
- Certification Timelines:The lengthy and expensive process of qualifying new shielding materials under stringent standards like MIL-STD-461 and RTCA DO-160 can delay the introduction of innovative solutions by several years.
- Environmental Durability:Ensuring that shielding materials, particularly coatings and elastomers, maintain their performance over a 30-year aircraft lifecycle despite exposure to UV radiation and hydraulic fluids remains a key technical hurdle.
- System Integration Risk:Verifying that new shielding components do not adversely affect the performance of other interconnected avionics requires complex and costly system-level testing to avoid unintended electromagnetic compatibility issues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft EMI Shielding Market |
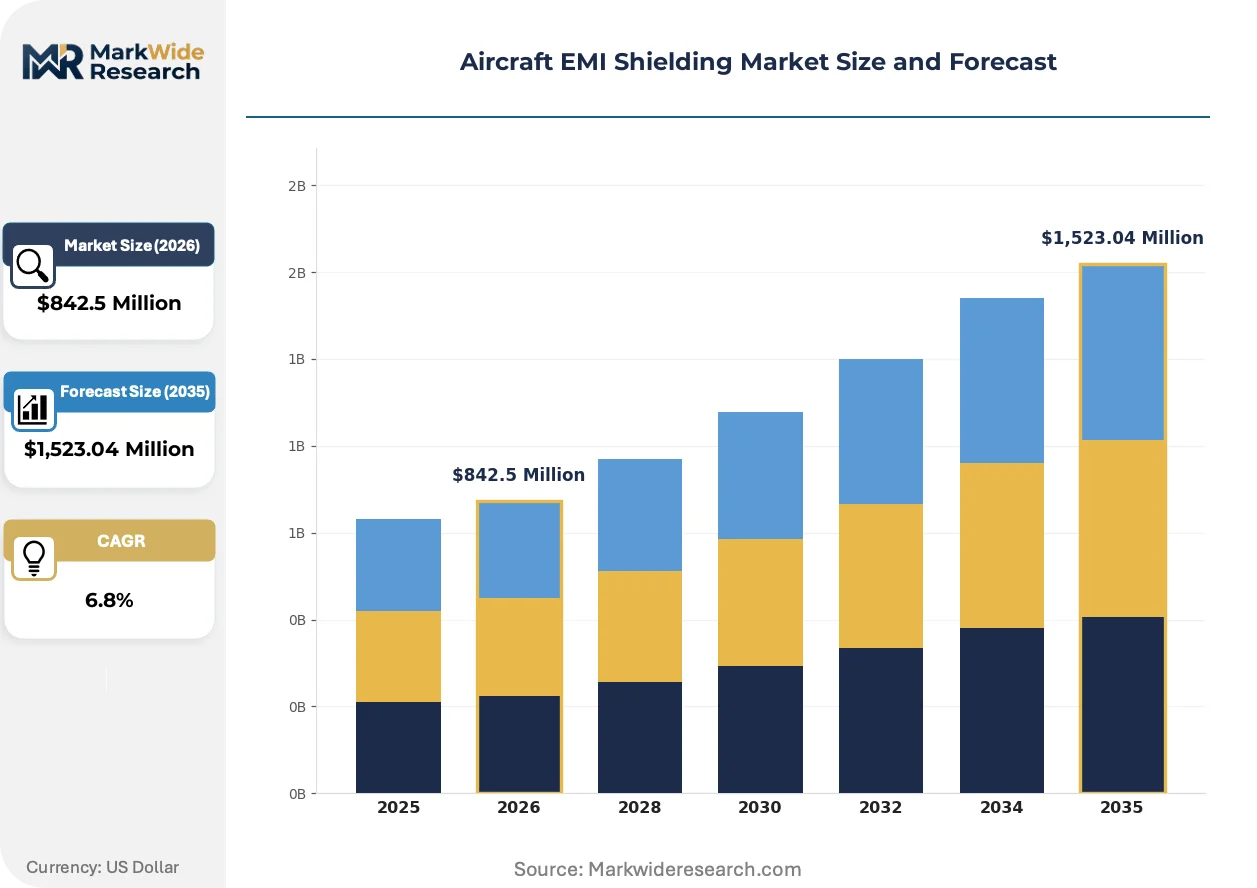
| Market Size in 2026 | $842.5 Million |
| Market Size in 2035 | $1,523.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Coatings, Metal Shielding, Absorbers, Hybrid Solutions End User: Commercial Aviation, Military Aircraft, UAVs, Spacecraft Technology: Passive Shielding, Active Shielding, Hybrid Shielding, EMI Filters Application: Avionics, Communication Systems, Navigation Systems, Power Distribution |
| Companies Covered | Laird Performance Materials, Henkel AG & Co. KGaA, Parker Hannifin Corporation, Kitagawa Industries Co., Ltd., Boyd Corporation, PPG Industries, Inc., W. L. Gore & Associates, Inc., Tech-Etch, Inc., 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft EMI Shielding Market Strategic Shifts & Innovations
Material science innovation is reshaping the approach to aircraft EMI protection. The industry is moving away from brute-force metal enclosures toward integrated, intelligent systems designed to manage the complex electromagnetic environment of modern electrified and connected aircraft.
Lightweight composite absorbers are advanced materials that integrate shielding properties directly into aircraft structural components. Aerospace OEMs are adopting these materials for new-generation airframes to achieve significant weight savings without compromising performance. This technology is unifying the previously separate functions of structural support and electromagnetic shielding into a single, optimized system.
The European Union Aviation Safety Agency (EASA) has issued specific airworthiness directives concerning the threat of 5G interference to radio altimeters. This mandate compels airlines and MROs to either upgrade avionics or install certified filters and shielding materials. The commercial aviation sector, particularly operators of older aircraft flying into Europe, is most affected and must demonstrate compliance.
Aircraft manufacturers are increasingly specifying EMI shielding performance requirements at the system level instead of prescribing specific materials. This performance-based specification model displaces the traditional component-by-component selection process, granting material suppliers greater design freedom. The shift is most pronounced within the military and UAV segments, where rapid design iteration is critical.
Aircraft EMI Shielding Market Segmentation
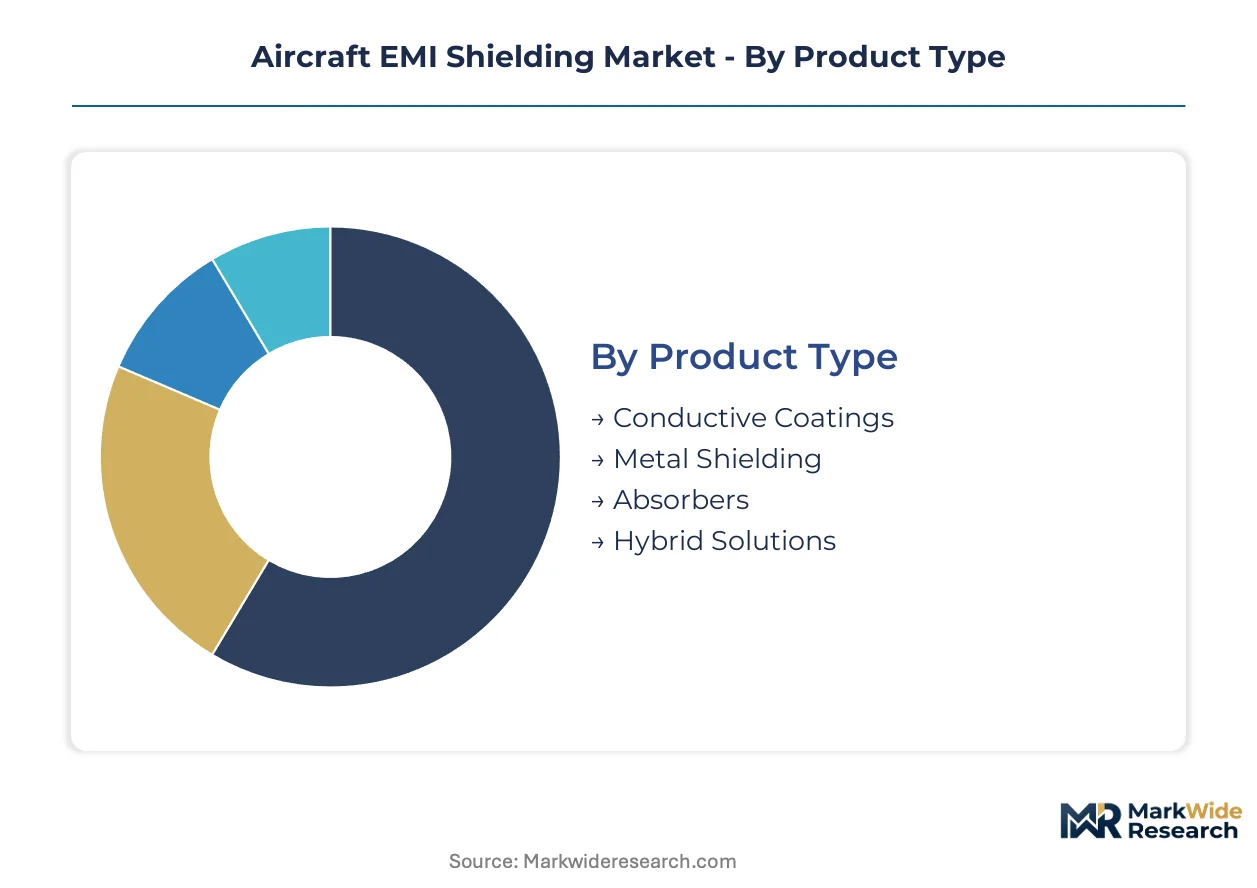
The Aircraft EMI Shielding Market is precisely segmented to reflect the diverse requirements and technological approaches across the aerospace industry. Understanding these segments is crucial for identifying areas of concentrated demand and emerging growth opportunities within this specialized market.
Product Type:
The product type segmentation differentiates between shielding solutions deployed as standalone components and those integrated directly into structural elements.
- Conductive Coatings:These thin, metallic or polymer-based layers are applied directly to surfaces or enclosures, providing electromagnetic attenuation. Demand concentrates in new-generation commercial aircraft and UAVs, driven by weight reduction mandates and complex form factors, particularly in the United States and Europe.
- Metal Shielding:Traditional metal enclosures or meshes block EMI, offering robust protection for sensitive components in both commercial and military aircraft.
- Absorbers:These materials convert electromagnetic energy into heat, reducing reflections and mitigating interference within confined spaces, especially critical for radar cross-section management.
- Hybrid Solutions:Hybrid solutions combine multiple shielding principles, such as conductive coatings with embedded absorbers or structural composites. This approach meets stringent EMI requirements for advanced military platforms and urban air mobility vehicles, balancing performance with weight and structural integrity.
Metal Shielding leads volumes today; Hybrid Solutions is gaining share fastest.
End User:
End-user categories reflect distinct operational environments and regulatory compliance frameworks for EMI shielding requirements.
- Commercial Aviation:This segment encompasses shielding for passenger and cargo aircraft, addressing interference from onboard electronics and external sources like 5G networks. Strict FAA and EASA regulations drive demand for certified shielding solutions in aircraft operating in the United States and European Union.
- Military Aircraft:Shielding for military platforms ensures operational integrity of mission-critical systems against hostile electronic warfare and internal EMI, adhering to MIL-STD-461 standards.
- UAVs:Unmanned aerial vehicles require compact and lightweight shielding due to their dense electronic payloads and need for reliable communication links. Proliferation of sophisticated sensors in military and commercial drones drives demand for miniaturized shielding in countries like Israel and China.
- Spacecraft:Shielding in spacecraft protects sensitive electronics from radiation and electromagnetic interference in extreme space environments, ensuring mission success.
Market share concentrates among Commercial Aviation and UAVs, reflecting high production volumes and rapid technological integration.
Technology:
The technology segmentation highlights various approaches to electromagnetic interference mitigation, from fundamental blocking to active cancellation.
- Passive Shielding:Passive shielding relies on conductive or magnetic materials to reflect or absorb electromagnetic waves, preventing them from reaching sensitive components. This foundational technology remains critical for avionics and communication systems across all aircraft types, particularly in legacy fleet upgrades.
- Active Shielding:Active shielding uses electronic circuits to generate counter-fields that cancel out incoming electromagnetic interference, offering dynamic protection.
- Hybrid Shielding:Hybrid shielding integrates elements of both passive and active methods, optimizing performance for specific frequency ranges and interference scenarios. This advanced approach is increasingly specified for next-generation military aircraft and eVTOL platforms, where weight and complex EM environments are primary concerns.
- EMI Filters:EMI filters are electronic components inserted into signal or power lines to suppress unwanted high-frequency noise, crucial for maintaining signal integrity.
Passive Shielding dominates current installations, while Hybrid Shielding exhibits the steepest expansion trajectory.
Application:
Application categories delineate the critical aircraft systems requiring robust electromagnetic interference protection for safe and reliable operation.
- Avionics:This segment covers shielding for flight control systems, navigation equipment, and other critical electronic systems vital for aircraft operation. Stringent RTCA DO-160 and MIL-STD-461 standards mandate high-performance shielding for avionics in commercial and military aircraft manufactured in the United States.
- Communication Systems:Shielding for communication systems protects radio transceivers, data links, and satellite communication equipment from internal and external interference. The increasing density of wireless systems in modern cabins, alongside 5G interference concerns, drives demand for enhanced shielding.
- Navigation Systems:Shielding protects GPS receivers, altimeters, and other navigational aids from electromagnetic interference to ensure accurate positioning and altitude data.
- Power Distribution:Shielding in power distribution systems prevents electromagnetic noise generated by electrical currents from affecting sensitive aircraft electronics and control units.
Future demand is increasingly driven by the need for enhanced shielding in Communication Systems due to expanding connectivity requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace engineering talent concentrations across several nations drive innovation in aircraft EMI shielding materials and systems. These specialized workforces, often clustered around major aerospace manufacturers and research institutions, propel advancements in lightweight and high-performance solutions. Regulatory bodies and defense procurement agencies further influence regional market dynamics.
United States
Extensive commercial and military aviation manufacturing underpins strong demand for advanced EMI shielding in the United States. Federal Aviation Administration (FAA) directives, particularly regarding 5G interference mitigation, mandate continuous upgrades for commercial fleets. Major aerospace hubs like Seattle, Wichita, and Southern California concentrate research and production for new airframes and component integration.
Germany
Germany's robust aerospace sector, with significant contributions to European aircraft programs, creates consistent demand for EMI shielding. European Union Aviation Safety Agency (EASA) regulations dictate stringent performance standards for both new aircraft and modifications. The Bavaria region, including Munich and Augsburg, serves as a key center for aerospace manufacturing and materials development.
France
France, home to major aircraft manufacturers and engine producers, requires sophisticated EMI shielding for its extensive aerospace activities. Compliance with EASA airworthiness directives is paramount for all aircraft components and systems. The Toulouse aerospace cluster, a global hub for commercial aviation, drives significant demand for integrated shielding solutions in new aircraft designs.
Japan
Japan's advanced materials science capabilities and growing domestic aerospace industry contribute to its EMI shielding market. The country's national regulators emphasize safety and electromagnetic compatibility for all aviation platforms. Manufacturers in regions like Aichi Prefecture, known for its strong industrial base, focus on precision engineering and lightweight composite applications.
India
India's expanding domestic aerospace manufacturing ecosystem, supported by government initiatives like the Make in India program, offers a new growth frontier. The country's defense modernization efforts also increase the need for military-grade EMI shielding. Bangalore, a prominent aerospace and defense hub, sees increasing investment in component manufacturing and system integration.
Aircraft EMI Shielding Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered market structure for aircraft EMI shielding. The industry sees a mix of large materials science companies offering broad portfolios and niche providers specializing in specific shielding technologies. Strategic archetypes include integrated solution providers, advanced material developers, and component fabricators. Dominant competitive moves involve portfolio diversification into lightweight composites and strategic partnerships for system integration.
Specialists in advanced material science, such as Henkel AG & Co. KGaA, occupy a position at the forefront of conductive coatings and adhesives. Parker Hannifin Corporation exemplifies a provider leveraging an extensive portfolio of conductive elastomers and gaskets for stringent aerospace standards. Laird Performance Materials also sits within the group of key players offering high-performance shielding solutions across various aircraft applications.
| Leading Market Players |
|---|
| Laird Performance Materials |
| Henkel AG & Co. KGaA |
| Parker Hannifin Corporation |
| Kitagawa Industries Co., Ltd. |
| Boyd Corporation |
| PPG Industries, Inc. |
| W. L. Gore & Associates, Inc. |
| Tech-Etch, Inc. |
| 3M Company |
| Others |
Cost & Logistics Intelligence
The transition to lightweight composite absorbers and advanced conductive coatings in aircraft EMI shielding reshapes cost economics by demanding specialized materials and concentrates supply among a few qualified vendors.
Pricing Analysis
The market primarily operates on a project-based pricing model for new aircraft designs, with transactional pricing for aftermarket MRO services. Pricing differentiation stems from stringent certification levels like RTCA DO-160 and MIL-STD-461, alongside the customization level required for specific airframes. Pricing pressure intensifies for basic applications due to the high material cost of advanced composites. Commercial aviation and military buyers exhibit lower price sensitivity compared to the cost-sensitive general aviation segment.
Supply Chain Analysis
Supply of aerospace-grade conductive elastomers and advanced composite absorbers rests on a specialized vendor base concentrated in the United States, Germany, and Japan. The market draws from critical inputs like high-purity metallic powders and advanced polymer resins. Single-source vulnerability for highly specialized, certified materials presents a structural risk. Distribution primarily runs through direct sales channels to major aerospace OEMs and Tier 1 integrators, with a smaller segment served by specialized MRO distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Aircraft EMI Shielding market functions as a regulatory compounder, with demand significantly driven by the Federal Aviation Administration's directives concerning 5G interference mitigation for radio altimeters. This regulatory milestone compels continuous innovation and upgrades across commercial fleets.
For Market Incumbents:Acquire advanced material science intellectual property to counter emerging threats from specialized composite developers. Incumbents should invest heavily in research and development for multifunctional composites that integrate EMI shielding with structural properties. Strengthening partnerships with major avionics integrators ensures early design-in opportunities and navigates complex certification timelines. This approach leverages established aerospace relationships against new material entrants.
For New Entrants and Emerging Players:Launch integrated shielding solutions directly to emerging Urban Air Mobility (UAM) and advanced UAV manufacturers, bypassing traditional aerospace procurement channels. Focus on developing lightweight composite absorbers for electric vertical takeoff and landing (eVTOL) aircraft, which represent a highly penetrable segment. Offer performance-based specifications rather than material prescriptions to align with rapid design iteration cycles. This strategy capitalizes on greenfield opportunities.
For Investors and Strategic Acquirers:Valuations sit cheapest among niche material science firms possessing proprietary conductive coating technologies and established certification pathways. The market offers strong long-term viability for the next decade, propelled by increasing aircraft electrification and cabin connectivity. Target specialized material developers with proven RTCA DO-160 compliance and a track record in lightweight composite innovation. Watch for rapid global expansion of 5G C-band deployments as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D into Multifunctional Composites | Unifies structural support with EMI shielding, reducing airframe weight for new-generation aircraft. |
| Strategic Partnerships with Avionics OEMs | Ensures early integration of shielding solutions into critical flight control systems. |
| Geographic Expansion into India | Capitalizes on India's expanding domestic aerospace manufacturing ecosystem and defense modernization. |
| Acquisition of Advanced Coating Specialists | Secures proprietary technologies for lightweight, high-performance electromagnetic attenuation. |
| Investment in Certification Testing Facilities | Accelerates qualification of new materials under RTCA DO-160 standards. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. Interviews included aerospace engineers, procurement leads at major OEMs, material scientists, and regulatory compliance officers. Secondary validation drew from FAA airworthiness directives, EASA publications, and MIL-STD-461 specifications. A rigorous bottom-up and top-down triangulation approach ensured data accuracy.
The rate-of-change decomposition framework analyzes growth drivers and restraints across the analysis window. Segmentation dimensions modeled include product type, end user, technology, application, and aircraft platform generation. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected market dynamics. Key industry-specific forecast inputs include new aircraft delivery schedules and unmanned aerial vehicle production volumes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid technological shifts or unforeseen regulatory changes. Forecasts reflect assumptions regarding certification timelines and material cost stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Global Helicopter Avionics Market
Avionics
Global Avionics Market
Avionics
Europe Military Aircraft Communication Avionics Market
Avionics
Customized Avionic Systems Market
Avionics
Commercial Electronic Flight Bag Market
Avionics
Display for Avionics Application Market
Avionics
Aircraft Computers Market
Avionics
Military Avionic Systems Market
Avionics
North America Military Aircraft Communication Avionics Market
Avionics
Electronic Flight Instrument System Market
Avionics
Europe Aircraft Avionics Market
Avionics
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market
Avionics
Global Commercial Avionics Systems Market
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Asia-Pacific Aircraft Health Monitoring System Market
Avionics
Autonomous Aircraft Flight Management Computers Market