
 Armor Protection Systems Market | 2026-2036
Armor Protection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Armor Protection Systems Market Outlook
Modular plate-carrier systems with scalable protection levels is recalibrating how defense and law enforcement buyers evaluate procurement value. BAE Systems plc leverages its integrated defense electronics footprint to bundle soft armor with communications mounting solutions. Rheinmetall AG anchors its position through captive metallurgy capabilities and direct military vehicle armor integration. Honeywell International, Inc. differentiates by controlling Spectra fiber supply chains for lightweight helmet applications.
Armor protection systems encompass engineered ballistic-resistant garments, hard plates, and headgear designed to defeat projectile and fragmentation threats through layered aramid, ceramic, or composite architectures typically rated against NIJ or STANAG threat levels. These systems serve military, law enforcement, and security personnel whose operational survival depends on weight-efficient stopping power against rifle and handgun munitions. Ceramic and composite material segments command premium positioning as military end users prioritize multi-hit capability against armor-piercing rounds. Body armor product configurations retain the largest volume share, though helmet demand is accelerating with integrated night-vision and communication mounting requirements.
NIJ certification protocols in the United States, STANAG standards across NATO operational frameworks, and the EU Green Deal chemical sustainability directives collectively shape product qualification timelines and material selection criteria for vendors seeking multi-jurisdiction contracts. Compliance with these overlapping frameworks extends development cycles but creates defensible barriers against uncertified competitors. Stakeholders must monitor evolving armor-piercing threat definitions and corresponding standard revisions to align R&D pipelines with procurement qualification windows.
Market Dynamics
Department of Defense modernization timelines are compressing procurement cycles for next-generation plate carriers and helmet systems, forcing suppliers to accelerate NIJ certification pipelines while managing ceramic-composite laminate supply constraints.
Growth Catalysts
- NIJ Level IV certification upgrades:US military procurement mandates are driving replacement of legacy Level III plates with multi-hit armor-piercing resistant systems across ground forces.
- Ultra-high-molecular-weight polyethylene fiber advances:Spectra and Dyneema fiber production scaling is enabling 40% weight reduction in helmet shells without ballistic degradation.
- Law enforcement equipment refresh cycles:Municipal police departments in Texas, California, and Florida are standardizing modular plate carriers with scalable protection levels.
Market Restraints
- Ceramic tile supply concentration:Boron carbide and silicon carbide substrate production clusters in limited US and European facilities, creating input vulnerability.
- EU Green Deal chemical sustainability directives:REACH restrictions on perfluorinated compounds are forcing reformulation of water-repellent ballistic fabric treatments.
- Aramid fiber price volatility:Para-aramid supply from DuPont and Teijin faces petrochemical feedstock cost pressure.
Strategic Opportunities
- Integrated night-vision mounting systems:Helmet platforms with pre-drilled universal shroud patterns are capturing premium positioning in special operations procurement.
- India defense modernization:Indian Army infantry modernization programs under the Ministry of Defence are opening tender opportunities for lightweight body armor.
- Additive manufacturing of ceramic matrix composites:3D-printed SiC/SiC components are reducing lead times for complex armor geometries.
Industry Challenges
- Ballistic testing facility bottlenecks:NIJ-certified laboratories in the US face 6-9 month queue times for Level IV plate validation.
- Multi-standard compliance complexity:Simultaneous STANAG, NIJ, and BIS certification requirements fragment R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armor Protection Systems Market |
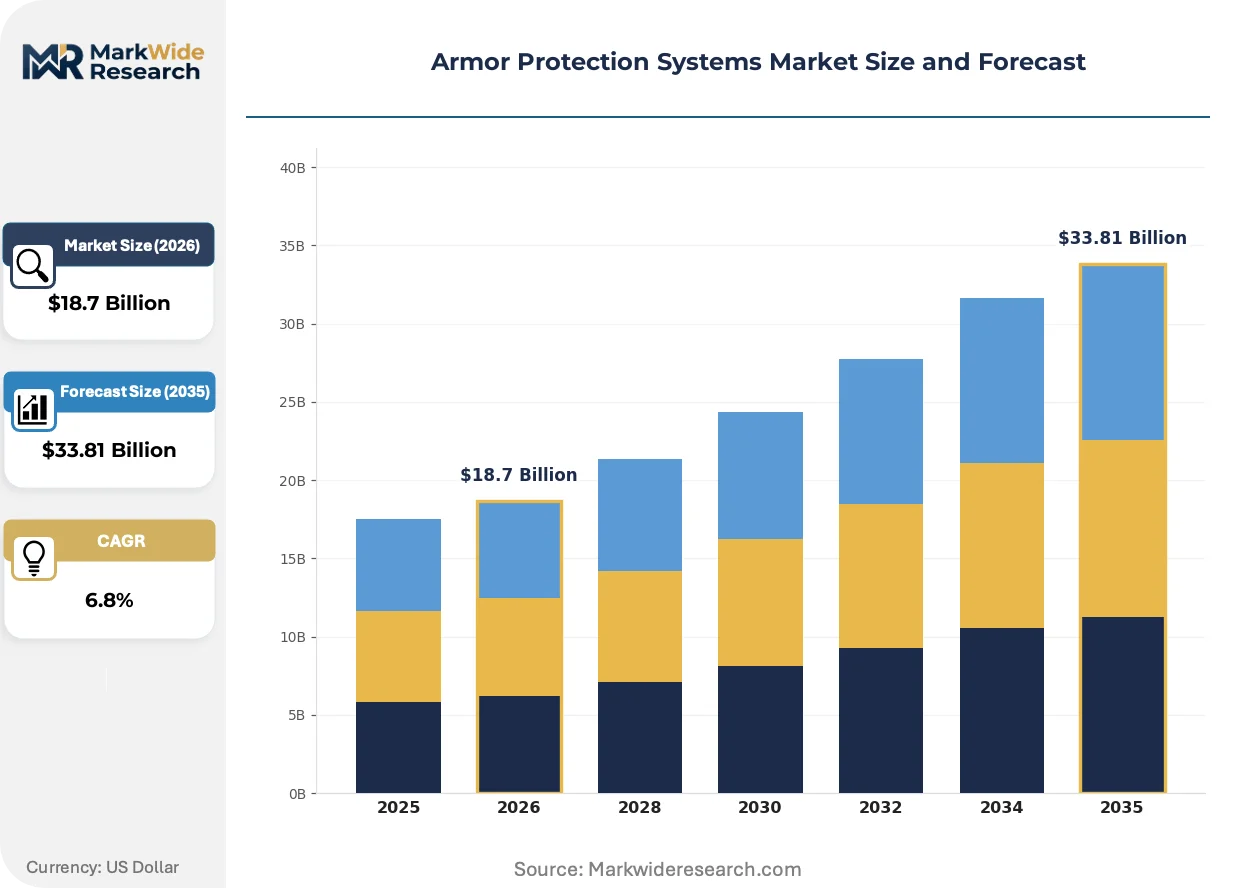
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Armor, Helmets, Shields, Plates Material: Kevlar, Steel, Ceramic, Composite End User: Military, Law Enforcement, Private Security, Civilian Deployment: On-field, Training, Home, Tactical Operations |
| Companies Covered | Point Blank Enterprises, Inc., BAE Systems plc, Safariland, LLC, Avon Protection plc, DuPont de Nemours, Inc., Rheinmetall AG, Honeywell International, Inc., ArmorSource LLC, Morgan Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armor Protection Systems Market Strategic Shifts
Armor protection systems are converging with wearable electronics and sustainable materials, creating new performance benchmarks that transcend traditional ballistic ratings alone.
Shear-thickening fluid impregnated fabrics are automating the transition between flexible comfort and rigid impact resistance. Special operations units in the US and UK are field-testing liquid armor vests that stiffen upon projectile impact. This technology is automating the elimination of rigid plate inserts for handgun threat protection, compressing the weight-bulk tradeoff that has constrained concealed wear.
REACH chemical restrictions in Europe are mandating substitution of legacy halogenated flame retardants in ballistic textiles. ECHA substance evaluation has placed decabromodiphenyl ether under sunset clause consideration. German and French defense contractors are accelerating bio-based aramid alternatives to maintain EU market access.
Unit-level procurement authority is consolidating under centralized defense logistics agencies. US Army Program Executive Office Soldier now controls plate carrier specification rather than individual brigade quartermasters. This concentration is compressing vendor count and elevating minimum contract thresholds, squeezing regional suppliers in the southeastern US manufacturing corridor.
Armor Protection Systems Market Segmentation
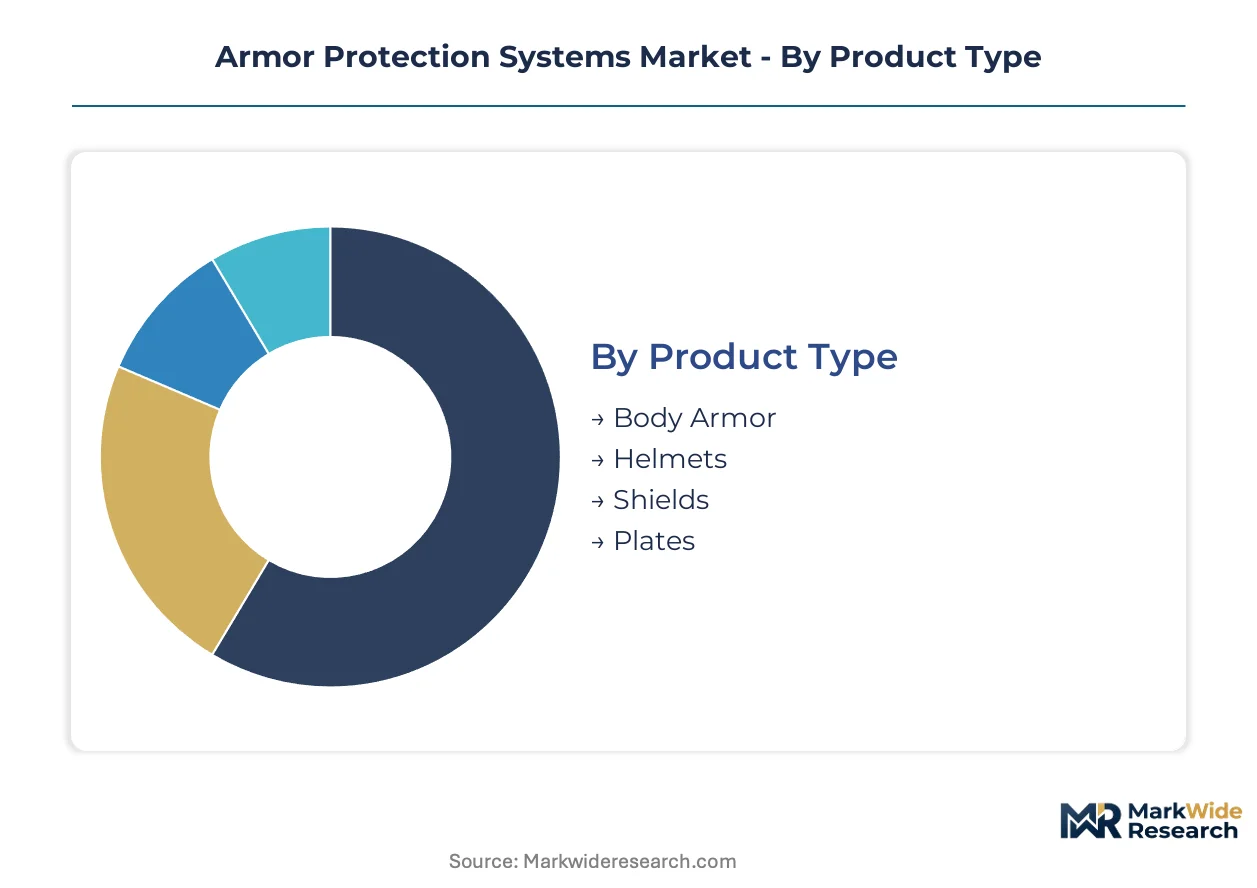
Armor protection procurement splits sharply between high-volume standardized equipment and premium systems with integrated electronics. Understanding these tiered demand patterns allows vendors to align certification investments with contract accessibility.
Product Type:
Volume concentration favors legacy body armor configurations, while premium positioning attaches to systems with modular scalability.
- Body Armor:Soft armor vests and plate carriers using aramid or polyethylene backing represent the procurement baseline for ground forces. US Army Program Executive Office Soldier mandates are compressing vendor qualification timelines for scalable protection systems.
- Helmets:Ballistic headgear integrating universal shroud patterns for night-vision mounting commands premium positioning. Special operations procurement in the United States and United Kingdom is accelerating demand for lightweight shell designs with communication routing.
- Shields:Portable ballistic barriers for entry teams and riot control units deploy ceramic-composite or transparent polycarbonate architectures.
- Plates:Hard armor inserts rated NIJ Level III through Level IV defeat rifle threats through ceramic, steel, or composite strike faces.
Mature deployment sits with body armor. Newer deployment is concentrated in helmets with integrated mounting systems.
Material:
Cost tier separation runs from commodity steel through engineered ceramics to fiber composites with captive supply chains.
- Kevlar:Para-aramid soft armor maintains dominance in concealable vest applications despite petrochemical feedstock price pressure. Law enforcement refresh cycles in Texas and California sustain baseline demand for this material class.
- Steel:Rolled homogeneous armor plate offers lowest unit cost but weight penalties limit deployment to vehicle mounting and budget-constrained procurement.
- Ceramic:Boron carbide and silicon carbide tiles deliver multi-hit armor-piercing protection for military plate applications. Supply concentrates in limited US and European production facilities, creating input vulnerability for tier-one integrators.
- Composite:Ultra-high-molecular-weight polyethylene fibers and ceramic-composite laminates enable 40% weight reduction without ballistic degradation. Spectra fiber supply chain control differentiates vendors competing for helmet contracts.
Mature deployment sits with Kevlar soft armor. Newer deployment is concentrated in ceramic-composite hybrid systems.
End User:
Customer type determines specification stringency, with military procurement setting performance ceilings that cascade to adjacent segments.
- Military:Ground forces procurement mandates NIJ Level IV multi-hit certification and STANAG compliance for NATO interoperability. Department of Defense modernization timelines are compressing replacement cycles for legacy plate carriers.
- Law Enforcement:Municipal police departments standardize modular plate carriers with scalable protection levels. Equipment refresh cycles in Florida, Texas, and California are consolidating procurement authority under state-level acquisition programs.
- Private Security:Executive protection and critical infrastructure guarding drives demand for concealable soft armor with handgun threat ratings.
- Civilian:Personal protection purchases span hunting, competitive shooting, and preparedness applications with price sensitivity shaping material selection toward steel and basic ceramic.
Mature deployment sits with military end users. Newer deployment is concentrated in law enforcement segments adopting modular configurations.
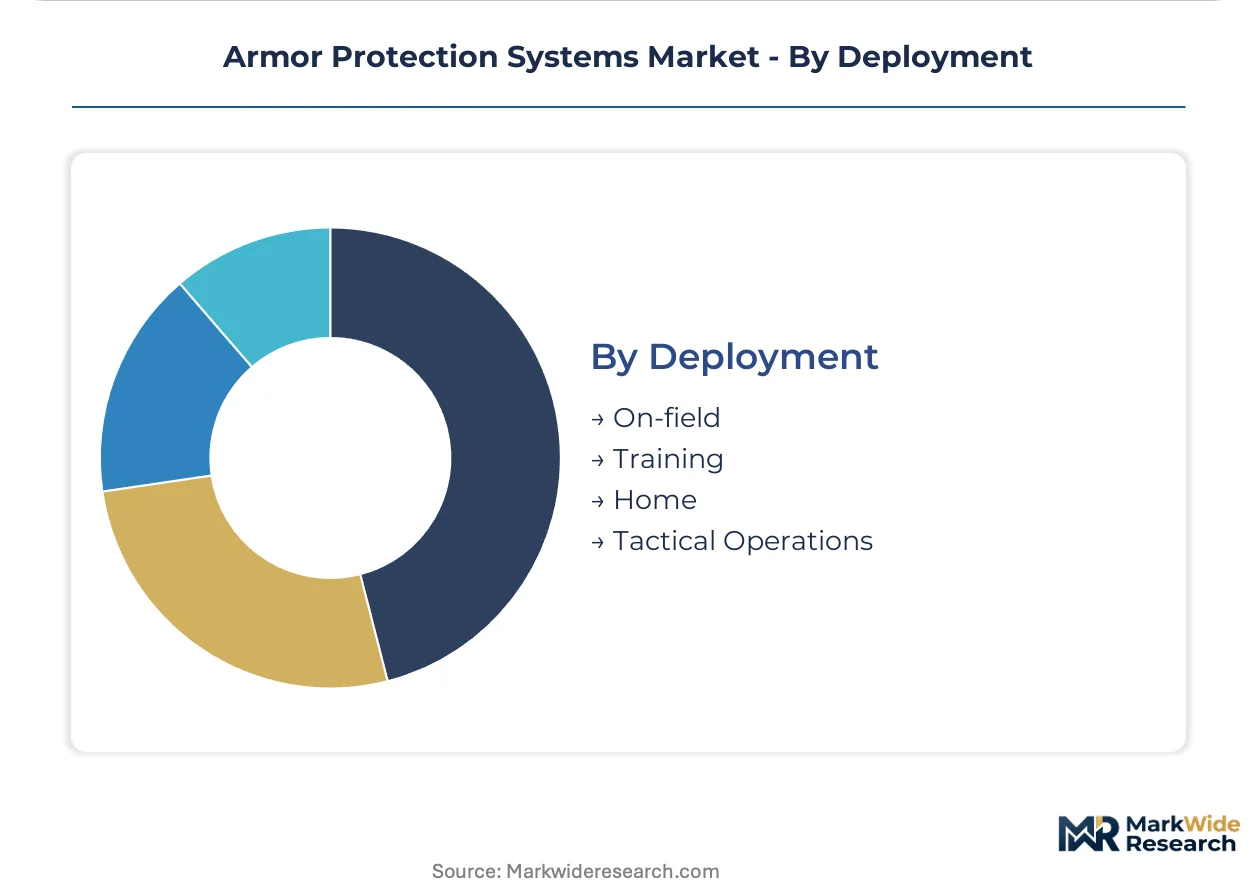
Deployment:
Application context determines weight-bulk tradeoffs and integration requirements across operational environments.
- On-field:Combat deployment demands maximum protection levels with integrated load-bearing equipment. Plate carriers for dismounted operations prioritize multi-hit capability against armor-piercing threats.
- Training:Repeated wear cycles require durability-focused designs with simplified maintenance protocols. Training armor often utilizes steel or lower-grade ceramic to reduce replacement costs.
- Home:Static defense applications accept weight penalties in exchange for cost reduction, with steel plate systems common in this segment.
- Tactical Operations:Dynamic entry and close-quarters battle require mobility-optimized configurations with rapid don-doff capability. Shear-thickening fluid impregnated fabrics are automating protection transitions in this application.
Mature deployment sits with on-field military systems. Newer deployment is concentrated in tactical operations with liquid armor field testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in US and European ceramic-composite facilities, while procurement demand clusters in NATO member states with active modernization programs. This geographic split creates supply chain tension as military procurement timelines compress.
United States
Department of Defense plate carrier replacement schedules and sustained law enforcement refresh cycles in Texas, California, and Florida anchor procurement volume. NIJ Level IV certification mandates from the Department of Justice compress vendor qualification timelines. Ceramic tile and UHMWPE fiber production clusters in South Carolina and Virginia supply domestic integrators.
Germany
Bundeswehr infantry modernization and vehicle armor integration programs sustain demand for STANAG-compliant systems. ECHA REACH restrictions on perfluorinated compounds force reformulation of water-repellent ballistic fabric treatments. Rheinmetall's captive metallurgy capabilities in Düsseldorf anchor vehicle armor integration.
United Kingdom
Special operations procurement for integrated night-vision helmet platforms drives premium segment demand. Ministry of Defence equipment programs mandate UK-defence-content thresholds for plate carrier contracts. Composite manufacturing concentrates in the Midlands and South West England.
India
Indian Army infantry modernization tenders under the Ministry of Defence open procurement for lightweight body armor. BIS certification requirements and the PLI scheme for defense manufacturing shape vendor qualification. Delhi-NCR and Pune clusters host emerging domestic fabrication capacity.
France
DGA procurement for next-generation soldier systems sustains demand for modular scalable protection. EU Green Deal chemical sustainability directives accelerate bio-based aramid development. Defense contractors in the Île-de-France and Auvergne-Rhône-Alpes regions reformulate legacy halogenated flame retardants.
Armor Protection Systems Market Competitive Environment
The competitive structure tilts toward integrated defense conglomerates with captive material supply chains and captive metallurgy capabilities. Tier-one vendors bundle soft armor with communications mounting solutions and vehicle armor integration. Three archetypes dominate: fiber producers controlling UHMWPE supply, ceramic-composite laminators with limited production facilities, and systems integrators with NIJ-certified testing pipelines. Consolidation concentrates under centralized defense logistics agencies, while regional suppliers face contract threshold compression.
Among US-based specialists, Point Blank Enterprises, Inc. and Safariland, LLC occupy positions within the law enforcement procurement tier, exemplifying vendors navigating municipal equipment refresh cycles. BAE Systems plc represents the integrated defense electronics archetype, anchoring systems bundling across NATO procurement frameworks. These named entities illustrate how geographic origin and corporate structure correlate with market positioning rather than determining it.
| Leading Market Players |
|---|
| Point Blank Enterprises, Inc. |
| BAE Systems plc |
| Safariland, LLC |
| Avon Protection plc |
| DuPont de Nemours, Inc. |
| Rheinmetall AG |
| Honeywell International, Inc. |
| ArmorSource LLC |
| Morgan Advanced Materials |
| Others |
Value Chain & Pricing Dynamics
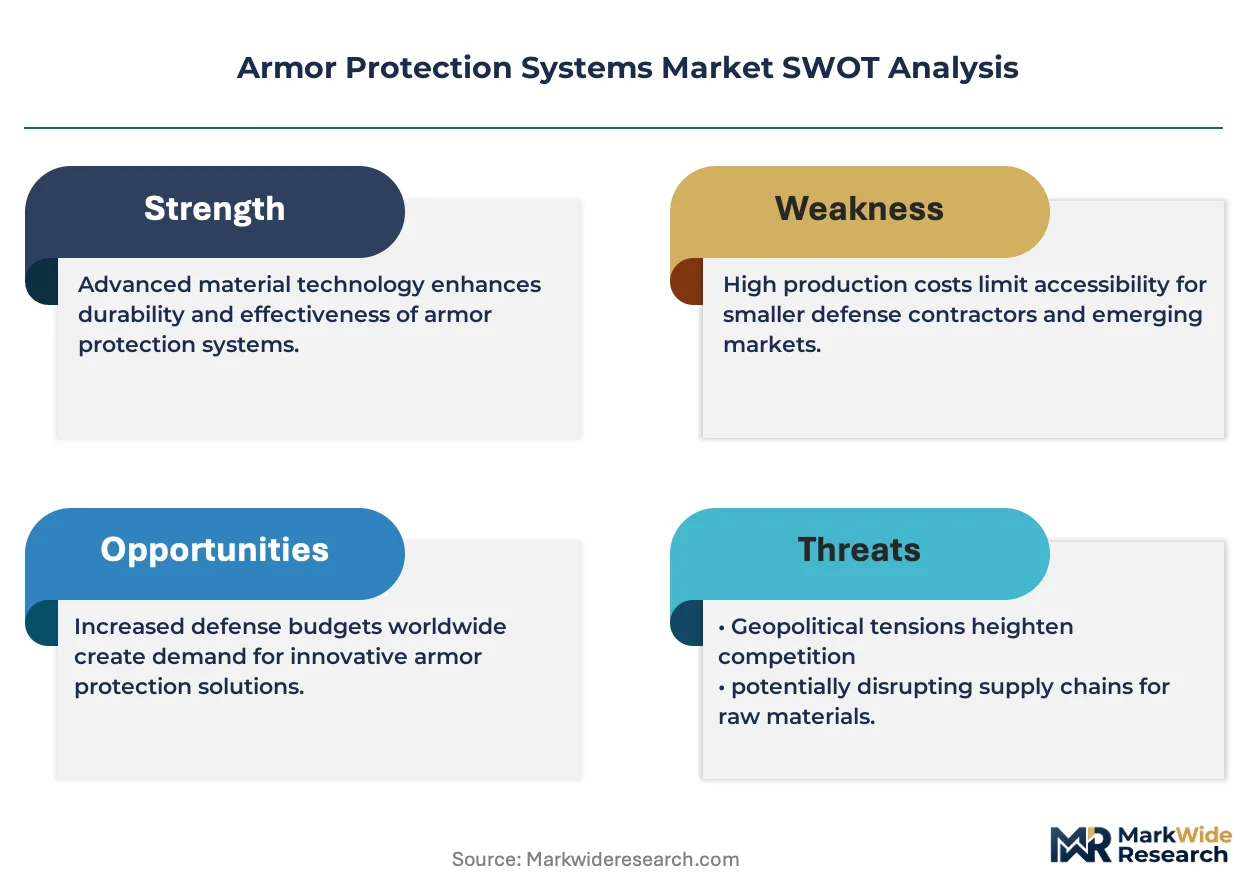
Boron carbide powder price indices cascade through ceramic-composite laminate tiers, compressing margins for tier-two integrators while amplifying pricing power for fiber producers with captive UHMWPE supply chains. Military procurement consolidation under centralized logistics agencies is forcing three-tier pricing stratification across premium NIJ Level IV systems, standard modular plate carriers, and economy steel-plate configurations.
Pricing Analysis
Cost-down pressure on standard-grade plate carriers accelerates because municipal police departments in Texas and California are consolidating procurement authority under state-level acquisition programs. Three-tier pricing structure across premium, standard, and economy levels separates multi-hit ceramic-composite systems from modular scalable carriers from baseline steel inserts. Certification grade and volume scale drive price differentiation, with NIJ Level IV validation adding substantial premium over Level III equivalents. Law enforcement segments exhibit highest price sensitivity, while special operations military procurement shows lowest sensitivity due to integrated electronics bundling.
Supply Chain Analysis
Dual-sourcing mandates from the Department of Defense and NATO procurement frameworks require tier-one integrators to qualify boron carbide substrates from multiple US and European production facilities. Ceramic tile supply concentrates in South Carolina and Virginia clusters, while Spectra fiber production anchors in Virginia draws from petrochemical feedstocks. Single-source vulnerability sits with limited silicon carbide substrate facilities. Distribution runs through defense logistics agency contracts and direct military vehicle armor integration channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Armor protection systems are consolidating around integrated defense conglomerates with captive material supply, squeezing regional suppliers unable to meet elevated contract thresholds. NIJ certification pipeline compression and centralized procurement authority are forcing weaker players toward exit or acquisition.
For Market Incumbents: Deepen backward integration into UHMWPE fiber production or ceramic-composite lamination to defend margin position against fiber producers expanding downstream. Additive manufacturing capabilities for complex armor geometries represent a critical R&D lever. Threat from REACH chemical restrictions and bio-based aramid substitutes demands accelerated reformulation investment to maintain EU market access. For New Entrants and Emerging Players: Begin with BIS certification pathways for Indian Army infantry modernization tenders, where domestic fabrication capacity in Delhi-NCR and Pune clusters creates penetrable white space. Shear-thickening fluid impregnated fabrics for tactical operations offer technology differentiation without ceramic supply chain dependency. Go-to-market angle should emphasize rapid NIJ certification partnerships with established testing laboratories. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier ceramic-composite laminators in the southeastern US manufacturing corridor facing contract threshold compression. Long-term viability hinges on STANAG and NIJ dual-certification capabilities across the analysis window. Watch Indian defense procurement tender announcements as inflection signal for geographic demand shift.| Strategic Initiative | Industry Significance |
|---|---|
| NIJ Level IV Certification Investment | Validates multi-hit armor-piercing resistance for Department of Defense plate carrier mandates. |
| UHMWPE Fiber Supply Integration | Captures Spectra or Dyneema supply chains for lightweight helmet shell production. |
| REACH-Compliant Fabric Reformulation | Maintains EU market access under ECHA restrictions on halogenated flame retardants. |
| Additive Manufacturing Capability Buildout | Reduces lead times for 3D-printed SiC/SiC ceramic matrix composite armor geometries. |
| Indian BIS Certification Partnership | Opens Ministry of Defence tender opportunities under PLI scheme incentives. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with defense procurement officers, NIJ-certified laboratory directors, ceramic substrate plant managers, and law enforcement equipment coordinators. Bottom-up and top-down triangulation validated against Department of Defense budget justification materials, ECHA substance evaluation databases, and BIS defense product registration records.
Granularity-level modeling disaggregated volume and value outputs by material tier, end-user procurement authority level, and certification grade across the projection horizon. CAGRs derived from time-series analysis of military modernization timelines and law enforcement refresh cycle patterns. Forecast inputs incorporated ceramic tile supply constraints and REACH regulatory phase-out schedules.
Underlying measurement precision varies by segment; military procurement volumes carry tighter precision than civilian personal protection estimates. Forecasts reflect assumptions on NATO interoperability mandates and Indian defense localization policies. Deviation in boron carbide supply disruption or NIJ threat-level standard revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Armored Vehicles
Armored Vehicle Navigation Systems Market
Armored Vehicles
Military Armored Car Market
Armored Vehicles
Asia-Pacific Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicles Market
Armored Vehicles
North America Armored Fighting Vehicles Market
Armored Vehicles
Europe Armored Fighting Vehicles Market
Armored Vehicles
Armored Vehicle Fire Suppression Systems Market
Armored Vehicles
Middle-East and Africa Armored Vehicles Market
Armored Vehicles
Global Ceramic Armor Market
Armored Vehicles
US Armored Vehicle Market
Armored Vehicles
Armored Fighting Vehicles Market
Armored Vehicles
Boom Arms Market
Armored Vehicles
Armoured Personnel Carrier (APC) Market
Armored Vehicles
Armored Personnel Carrier Market
Armored Vehicles
Armored Vehicles Upgrade and Retrofit Market
Armored Vehicles
Armored Vehicle Procurement and Upgrade Market