
 Air Independent Propulsion Systems for Submarine Market | 2026-2036
Air Independent Propulsion Systems for Submarine Market Size, Share, and Industry Trends Forecast 2026-2036
Air Independent Propulsion Systems for Submarine Market Analysis
Modular fuel cell packaging is hardening as the dominant procurement configuration, shifting buyer choice away from fully integrated hull designs toward plug-in AIP sections that shipyards can install during new construction or mid-life refit. Thyssenkrupp AG leverages its HDW fuel cell module lineage to anchor European supply chains for Type 212 and 214 platforms. SAAB AB competes through Stirling engine specialization for Swedish and Australian submarine programs. Naval Group differentiates via integrated lithium-ion battery hybrid architectures that extend submerged endurance without external air supply.
Air independent propulsion systems enable submerged submarine operation without surfacing or snorkeling by generating oxygen internally through chemical or electrochemical processes, typically achieving two to four weeks of submerged endurance compared with 48-72 hours for conventional diesel-electric boats. Fuel cell technology leads the segment due to its acoustic signature advantages and thermal efficiency in closed-loop operation, while Stirling engine configurations retain strong positions in Nordic and East Asian fleets where proven reliability outweighs efficiency trade-offs. Lithium-ion batteries represent the fastest-growing sub-segment as navies pursue hybrid AIP-battery architectures that optimize sprint-drift tactical profiles.
Germany's BAAINBw and Japan's METI both enforce stringent pressure-hull integration and hydrogen storage safety standards that shape product certification requirements for export markets. The US Navy's Naval Sea Systems Command influences allied procurement through cooperative submarine technology agreements that specify AIP interoperability benchmarks. Stakeholders must monitor evolving underwater endurance requirements as anti-submarine warfare sensor networks extend detection ranges against conventional diesel-electric signatures.
Market Dynamics
Modular fuel cell packaging is hardening as the dominant procurement configuration, shifting buyer choice away from fully integrated hull designs toward plug-in AIP sections that shipyards can install during new construction or mid-life refit. This structural force compresses vendor margins while expanding addressable market for retrofit specialists.
Growth Catalysts
- Japan's METI hydrogen energy roadmaps:These frameworks mandate closed-cycle propulsion architectures for next-generation submarine fleets, creating certified demand corridors for fuel cell module suppliers.
- Fuel cell acoustic signature advantages:Naval forces prioritize undetectable operation, driving procurement toward electrochemical systems that eliminate thermal and mechanical noise signatures of Stirling alternatives.
- South Korean shipyard competition:DSME and HHI vie for domestic and export AIP integration contracts, accelerating technology maturation and cost reduction through competitive pressure.
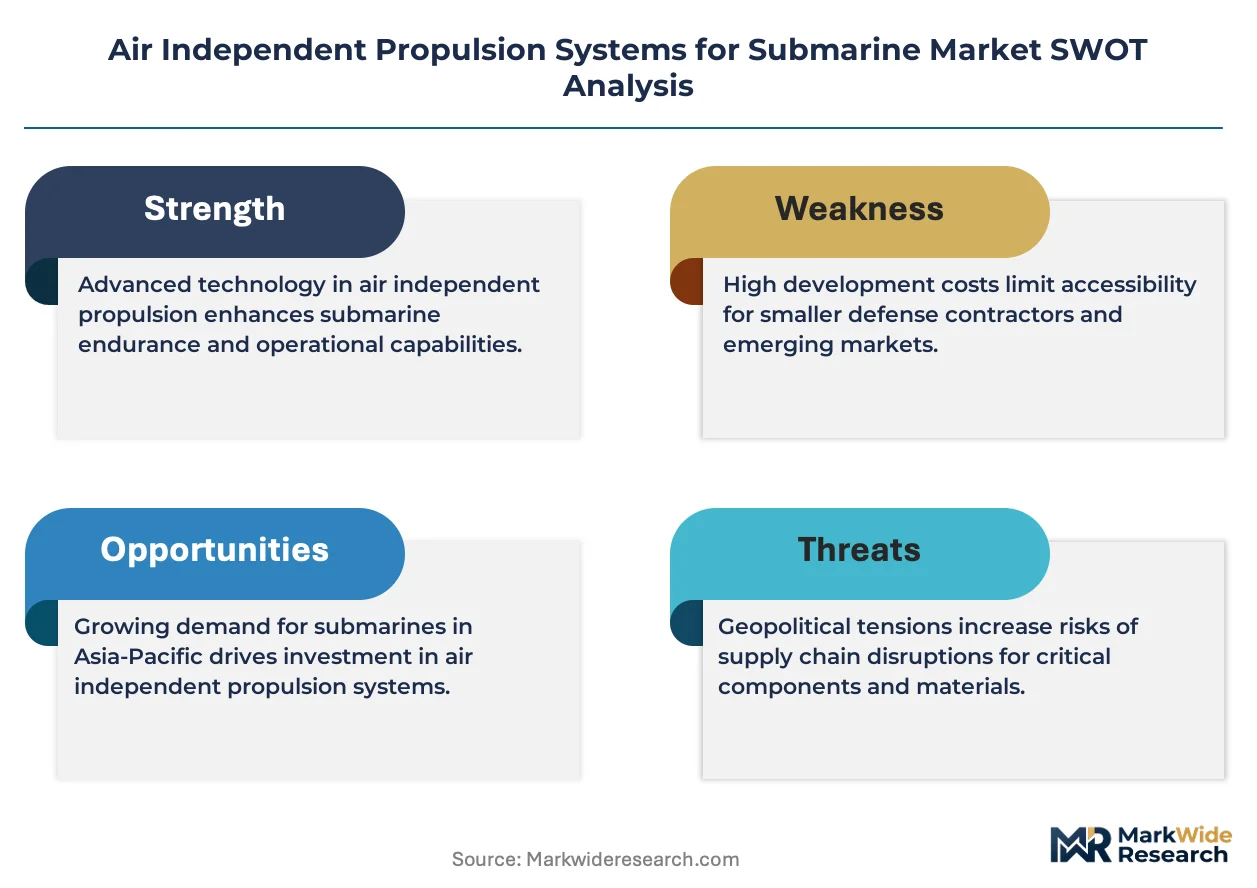
Market Restraints
- High-purity hydrogen storage costs:Metal hydride and compressed gas systems require exotic materials and precision manufacturing, inflating unit economics beyond diesel-electric baselines.
- German supply chain concentration:Thyssenkrupp's HDW module lineage anchors European fuel cell AIP production, creating single-source vulnerability for NATO-aligned submarine programs.
- Pressure-hull integration complexity:Closed-cycle systems demand hull penetrations and safety systems that extend construction timelines and amplify certification risk.
Strategic Opportunities
- Australian submarine modernization:The AUKUS framework creates demand for AIP-battery hybrid architectures in interim conventional platforms before nuclear transition.
- Lithium-ion battery convergence:Hybrid systems combining fuel cells with advanced batteries enable sprint-drift tactical profiles previously unattainable with single-mode propulsion.
- Mid-life refit channel expansion:Plug-in AIP modules open retrofit markets for existing diesel-electric fleets, extending service life without full hull replacement.
Industry Challenges
- Pressure-vessel welding certification:Hydrogen containment systems require specialized welder qualifications that outstrip current naval shipyard training pipelines.
- Legacy combat system integration:AIP modules must interface with existing platform management systems through proprietary protocols that resist standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Independent Propulsion Systems for Submarine Market |
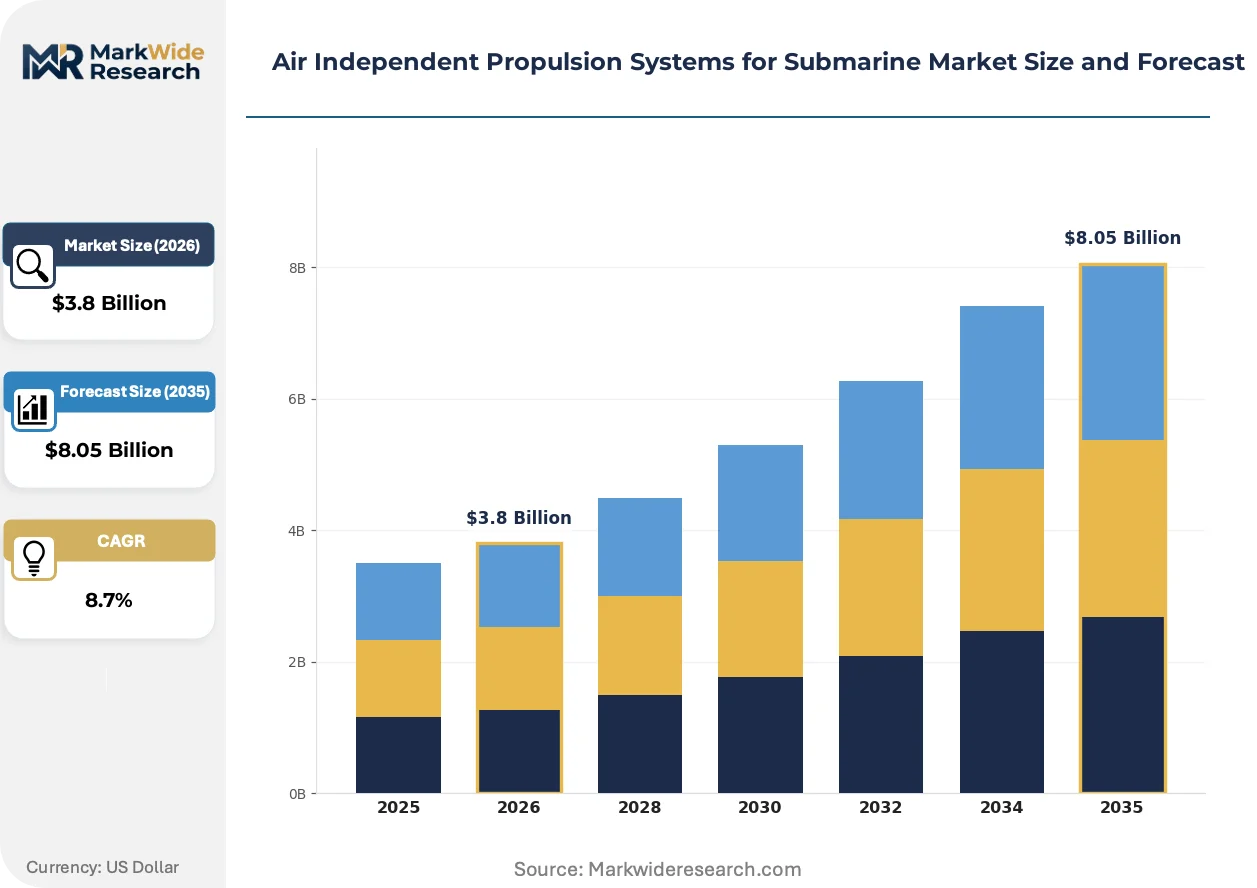
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fuel Cell, Stirling Engine, Closed Cycle Diesel, Lithium-Ion Batteries Application: Military, Research, Commercial, Underwater Operations Design Type: Modular, Integrated, Retro-Fit, Standardized End User: Naval Forces, Research Institutions, Private Companies, Defense Contractors |
| Companies Covered | Thyssenkrupp AG, General Dynamics Corporation, SAAB AB, United Shipbuilding Corporation, Kongsberg Gruppen, Siemens, Lockheed Martin Corporation, China Shipbuilding Industry Co., Ltd, Naval Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Independent Propulsion Systems for Submarine Market Emerging Trajectories
Active hydrogen storage research and hybrid propulsion architectures are rewriting competitive boundaries between fuel cell and Stirling engine suppliers. Technology convergence is compressing traditional technology silos.
Solid-state hydrogen storage in metal hydride matrices is rewriting submarine design constraints by eliminating compressed gas safety zones and hull volume penalties. Naval architects at Thyssenkrupp and Naval Group are embedding these systems into Type 212CD and Barracuda-class platforms. The technology is rewriting endurance calculations, enabling three-week submerged patrols without surfacing or snorkeling.
Germany's BAAINBw submarine modernization directives enforce stringent pressure-hull integration standards that reshape export certification requirements. These regulations compress product development timelines for non-European suppliers seeking NATO interoperability. South Korean and Japanese shipyards are responding by pre-certifying modules to BAAINBw specifications before bidding on European tender programs.
Buyer preference is compressing toward modular, shipyard-agnostic AIP sections that enable competitive sourcing across construction and refit phases. Traditional fully integrated hull designs are losing share to plug-in configurations that DSME and HHI market as risk-reduction tools. This pattern is most visible in Southeast Asian submarine procurement, where navies prioritize operational flexibility over single-vendor dependency.
Air Independent Propulsion Systems for Submarine Market Segmentation
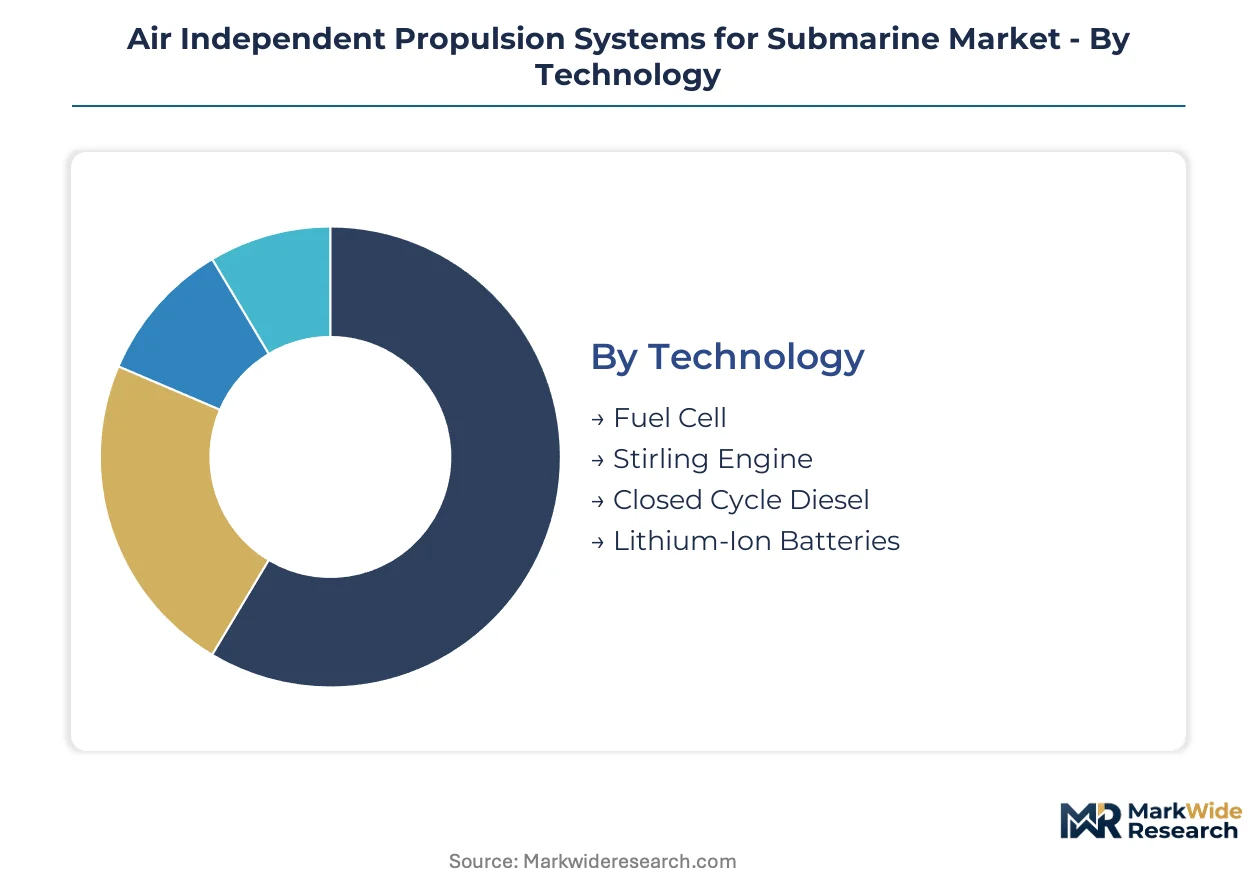
Segmentation in submarine AIP systems reveals how procurement patterns split across technical maturity, operational doctrine, and integration philosophy. Each axis carries distinct certification requirements and vendor qualification barriers that reshape competitive boundaries.
Technology:
Technology choice determines acoustic signature, thermal profile, and hydrogen logistics complexity for submerged endurance missions.
- Fuel Cell:Electrochemical systems generate power through hydrogen-oxygen reactions without combustion, eliminating mechanical noise. Procurement concentrates in Germany and Japan where METI roadmaps and BAAINBw directives enforce closed-cycle standards for next-generation fleets.
- Stirling Engine:External combustion engines offer proven reliability through closed thermodynamic cycles. Nordic and select East Asian navies favor this configuration where operational certainty outweighs efficiency penalties in Arctic or contested waters.
- Closed Cycle Diesel:Modified diesel engines operate with stored oxygen and exhaust scrubbing. Limited procurement persists in legacy platform refits where hull volume constraints preclude fuel cell retrofit.
- Lithium-Ion Batteries:Advanced electrochemical storage enables sprint-drift tactical profiles when paired with generation systems. Hybrid architectures are climbing the fastest as navies optimize for intermittent high-speed maneuvers.
Mature deployment sits with Stirling Engine configurations. Newer deployment is concentrated in Lithium-Ion Batteries paired with fuel cell generation.
Application:
Application scope reflects divergent endurance requirements and regulatory oversight intensity across underwater mission profiles.
- Military:Combat patrols demand 2-4 week submerged endurance with minimal acoustic exposure. Procurement dominates in South Korea, Germany, and Japan where submarine fleet modernization programs specify AIP for area-denial operations.
- Research:Scientific missions prioritize precision station-keeping and payload power over stealth. Academic and governmental oceanographic institutes in Norway and the United States fund specialized low-signature platforms.
- Commercial:Undersea mining and pipeline inspection require extended bottom-time without surface support. Emerging demand from seabed resource ventures in the Pacific Rim drives modular AIP interest.
- Underwater Operations:Special forces delivery and intelligence collection need rapid deployment with minimal logistics footprint. Covert insertion platforms in Southeast Asian and Middle Eastern markets favor compact plug-in modules.
Volume concentration rests with Military procurement. Steepest expansion trajectory is emerging in Commercial seabed applications.
Design Type:
Design philosophy determines shipyard flexibility, certification risk distribution, and lifecycle cost structure for platform integration.
- Modular:Self-contained AIP sections install during construction or mid-life refit without hull redesign. DSME and HHI compete aggressively on this configuration for export markets seeking vendor diversification.
- Integrated:Fully embedded systems optimize hull volume and acoustic isolation at the cost of single-source dependency. Naval Group and Thyssenkrupp anchor European supply chains on this architecture for Type 212 and Barracuda programs.
- Retro-Fit:Back-fit packages extend service life of existing diesel-electric hulls. Southeast Asian navies with aging fleets drive demand for plug-in solutions that avoid full replacement.
- Standardized:NATO interoperability specifications enable cross-platform module exchange. BAAINBw certification requirements shape these configurations for allied procurement alignment.
Shipyard preference is compressing toward Modular configurations. Integrated designs retain hold where sovereign industrial base policy mandates domestic hull construction.
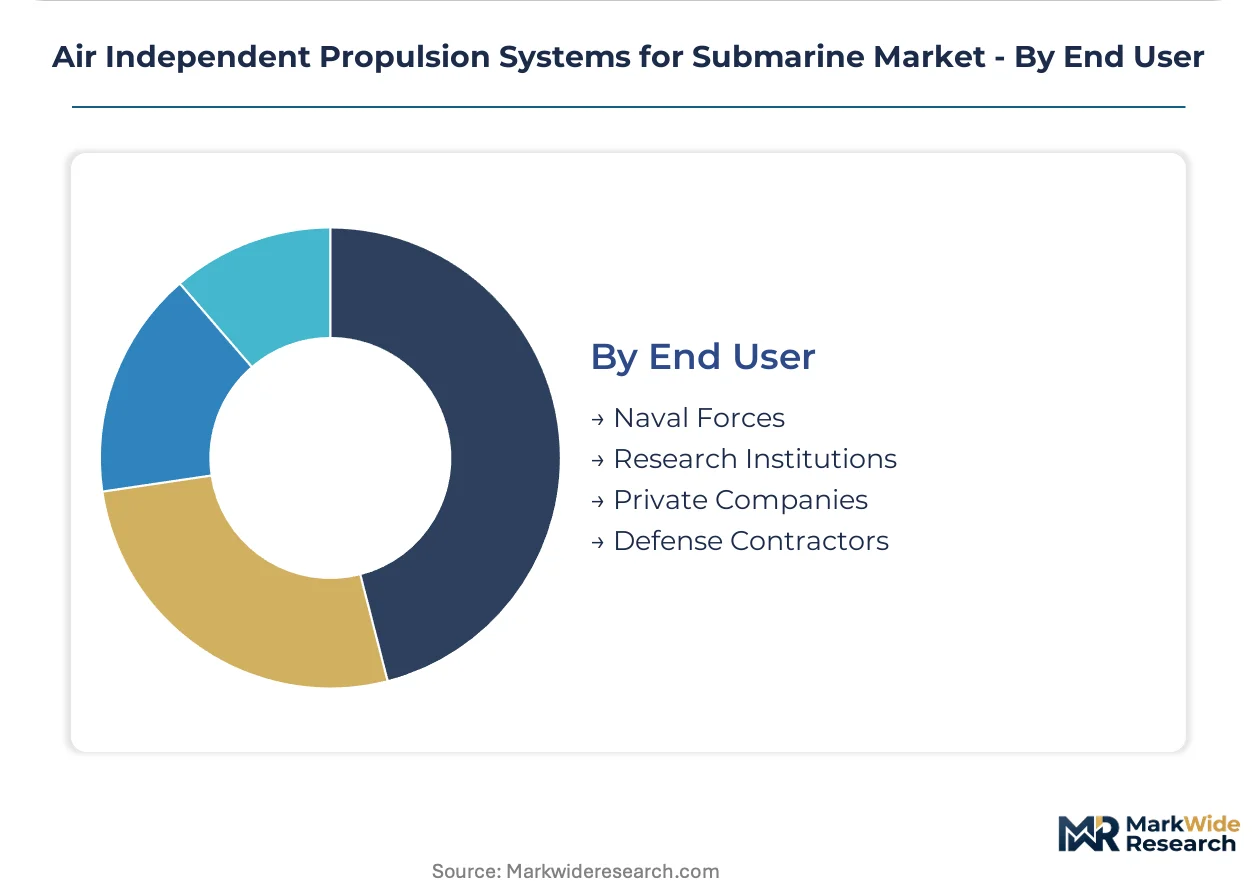
End User:
End user category determines procurement authority structure, budget cycle timing, and technical specification authority.
- Naval Forces:Sovereign submarine operators specify mission profiles and endurance requirements. Germany, Japan, and South Korea represent the largest state procurement channels with multi-hull fleet programs.
- Research Institutions:Academic and governmental science agencies fund specialized platforms for deep-ocean survey. Norwegian and United States oceanographic programs lead this segment.
- Private Companies:Seabed mining ventures and submarine tourism operators seek commercial-off-the-shelf AIP modules. Regulatory frameworks for civilian hydrogen storage remain underdeveloped in most jurisdictions.
- Defense Contractors:Prime platform integrators subcontract AIP modules for foreign military sales. Thales and Lockheed Martin source fuel cell systems for third-country submarine exports.
Budget authority concentrates with Naval Forces. Emerging demand channels are forming through Private Companies in seabed resource extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in South Korea's Busan-Ulsan corridor concentrate AIP module fabrication and submarine integration capacity. Germany's Bavaria region anchors European fuel cell supply chains through BAAINBw-certified production facilities. Japan's Kansai industrial belt houses METI-funded hydrogen storage research centers advancing closed-cycle propulsion architectures.
Germany
BAAINBw submarine modernization directives drive procurement of HDW fuel cell modules for Type 212 and 214 platforms. The Federal Office of Bundeswehr Equipment enforces stringent pressure-hull integration standards that reshape NATO export certification. Bavaria's Kiel-Flensburg shipbuilding cluster hosts Thyssenkrupp Marine Systems production facilities serving allied submarine programs.
Japan
METI hydrogen energy roadmaps mandate closed-cycle propulsion for next-generation Soryu-class successor submarines. The Ministry of Economy, Trade and Industry funds solid-state hydrogen storage research through public-private partnerships. Kobe's maritime industrial zone concentrates fuel cell module testing facilities and naval architect expertise.
South Korea
DSME and HHI compete for domestic KSS-III Batch-II and export AIP integration contracts. The Defense Acquisition Program Administration specifies modular plug-in configurations to enable vendor diversification. Busan-Ulsan special economic zones house submarine construction yards and fuel cell subsystem suppliers.
France
Naval Group develops integrated lithium-ion battery hybrid architectures for Barracuda-class platforms. The Direction Générale de l'Armement oversees certification of closed-cycle systems for export markets. Cherbourg's naval shipyard cluster specializes in sovereign hull-integrated AIP designs for domestic and foreign military sales.
Sweden
Swedish Navy procurement prioritizes Stirling engine reliability for Baltic Sea patrol operations. The Swedish Defence Materiel Administration specifies acoustic signature benchmarks for Gotland-class modernization. Karlskrona's naval base supports SAAB-led AIP integration and regional submarine maintenance capacity.
Air Independent Propulsion Systems for Submarine Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the AIP systems value chain. Tier-one defense primes anchor integrated hull designs while mid-scale fabricators capture modular retrofit opportunities. Strategic archetypes include sovereign hull-integrators, fuel cell module specialists, and battery-hybrid architects. Competitive moves center on technology licensing partnerships and backward integration into hydrogen storage materials.
Among European sovereign integrators, Thyssenkrupp AG and Naval Group occupy positions spanning fuel cell generation and battery-hybrid architectures. SAAB AB exemplifies the Stirling engine specialization archetype for Nordic and export markets. Siemens represents the industrial conglomerate tier supplying electrical and automation subsystems across multiple platform integrators.
| Leading Market Players |
|---|
| Thyssenkrupp AG |
| General Dynamics Corporation |
| SAAB AB |
| United Shipbuilding Corporation |
| Kongsberg Gruppen |
| Siemens |
| Lockheed Martin Corporation |
| China Shipbuilding Industry Co., Ltd |
| Naval Group |
| Others |
Supply Flow & Price Mechanics
Captive production of metal hydride hydrogen storage systems anchors both supply security and pricing power for AIP module integrators. German and Japanese procurement directives from BAAINBw and METI enforce certified supplier relationships that insulate prime contractors from spot-market volatility while compressing margins for non-certified competitors.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent naval procurement from scheduled fleet modernization programs. Three-tier pricing structure across BAAINBw-certified, NATO-interoperable, and non-standard configurations reflects certification grade and hull-integration complexity. Cost compression in modular retrofit segments is intensifying because South Korean shipyards compete aggressively on plug-in AIP packages. Research institutions and commercial seabed operators exhibit highest price sensitivity, while sovereign naval forces prioritize acoustic performance over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany's Bavaria corridor, South Korea's Busan-Ulsan zone, and Japan's Kansai belt coordinate hydrogen storage material flows to submarine construction yards. The supply chain draws from rare earth metal deposits, precision pressure-vessel fabrication capacity, and electrochemical membrane production. Single-source vulnerability concentrates in German HDW fuel cell module lineage for NATO-aligned programs. Distribution runs through defense contractor prime channels with direct shipyard integration protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certified fuel cell module suppliers as BAAINBw and METI safety standards eliminate marginal players lacking hydrogen storage integration expertise.
For Market Incumbents: Anchor market position through backward integration into solid-state hydrogen storage materials and pre-certification of modular AIP sections to BAAINBw specifications before tendering. Threat from Stirling engine specialists like SAAB AB in Nordic markets demands acoustic signature investment. Certification leverage represents the critical defensive moat. For New Entrants and Emerging Players: Digital-channel routes through defense contractor prime partnerships offer lower barriers than direct naval procurement. White-space targets concentrate in commercial seabed mining AIP modules and Southeast Asian retrofit markets for aging diesel-electric fleets. Go-to-market execution should emphasize shipyard-agnostic plug-in configurations that reduce integration risk for buyers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to tier-one defense primes seeking fuel cell AIP capabilities. Long-term viability favors specialists with METI or BAAINBw pre-certification and captive hydrogen storage material supply. Watch for inflection in Australian AUKUS-related conventional submarine procurement decisions as signal for interim platform AIP demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Storage Materials | Captive metal hydride supply insulates Thyssenkrupp and Naval Group from rare earth price volatility. |
| Modular AIP Pre-Certification | DSME and HHI accelerate bid responsiveness by pre-qualifying plug-in sections to BAAINBw standards. |
| Stirling Engine Reliability Positioning | SAAB AB defends Baltic Sea market share through proven Arctic operational performance. |
| Lithium-Ion Battery Hybrid Development | Naval Group extends Barracuda-class endurance through integrated sprint-drift architectures. |
| Commercial Seabed AIP Module Launch | Private mining ventures in Pacific Rim create non-military demand channel for compact fuel cell systems. |
Methodological Framework
Multi-period observation of submarine fleet modernization announcements, hydrogen storage patent filings, and naval procurement tender awards anchored the trend analysis, supplemented by interviews with submarine platform engineers, defense procurement officers at BAAINBw and DAPA, fuel cell R&D directors, and shipyard integration managers. Secondary validation drew from naval shipbuilding trade publications, METI hydrogen roadmap disclosures, NATO submarine cooperation agreements, and customs data on pressure-vessel alloy imports. Bottom-up module shipment estimates and top-down naval budget allocation analysis were cross-referenced for triangulation.
Input-output matrices mapped fuel cell generation capacity, hydrogen storage material supply, and hull integration labor across technology type, application scope, design philosophy, and end-user category. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs included projected submarine hull construction schedules, METI-funded research commercialization timelines, and BAAINBw certification pipeline throughput.
The model holds under stable naval procurement budget trajectories and continued METI hydrogen infrastructure investment; deviation in sovereign defense spending priorities or hydrogen safety regulatory stringency would shift module demand projections. Periodic stress-testing of base assumptions against actual tender awards and shipyard delivery schedules is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global Remote Weapon Station Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
FLIR and Laser Designator Targeting Pods Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
NATO Defense Market
Military Equipment and Infrastructure
Europe Digital Battlefield Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Rocket Solid Propulsion Market
Military Equipment and Infrastructure
Global Stealth Warfare Market
Military Equipment and Infrastructure
Air-Based Remote Weapon Stations Market
Military Equipment and Infrastructure
Latin America Defense Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market
Military Equipment and Infrastructure
Military Image Intensifier Tube Market