
 Asia-Pacific Military Aircraft Modernization and Retrofit Market | 2026-2036
Asia-Pacific Military Aircraft Modernization and Retrofit Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Military Aircraft Modernization and Retrofit Market Outlook
Multi-source avionics procurement is pivoting toward hybrid in-house and outsourced upgrade architectures across the region. Lockheed Martin leverages its F-16 sustainment footprint to anchor long-term service contracts in multiple Asia-Pacific air forces. Boeing competes through integrated platform upgrade packages that combine sensor refreshes with structural life-extension programs.
Military aircraft modernization and retrofit encompasses the structural, avionic, propulsion, and weapons-system overhaul of existing airframes to extend operational service life and restore mission relevance against evolving threat environments. Processes include airframe fatigue remediation, digital cockpit replacement, and engine hot-section refurbishment, all governed by original equipment manufacturer technical orders and military airworthiness directives. Fighter jets command the largest share of current upgrade spending as fourth-generation fleets face obsolescence against fifth-generation threats. Avionics represents the fastest-expanding technology segment, driven by software-defined radio and open-architecture mission computer replacements that reduce vendor lock-in.
Japan's METI coordinates industrial offset policies that steer F-15J upgrade work toward domestic facilities, while Australia's Defence Aviation Safety Authority enforces airworthiness certification standards that dictate retrofit scope and documentation depth. India's Defence Research and Development Organisation mandates progressively stringent indigenous content thresholds that reshape foreign OEM partnership structures. Stakeholders must weigh sovereign capability requirements against platform interoperability standards when structuring multi-national upgrade consortiums.
Market Dynamics
India's Defence Acquisition Procedure mandates progressively stringent indigenous content thresholds that reshape foreign OEM partnership structures across Asia-Pacific military aircraft upgrade programs.
Growth Catalysts
- Obsolescence Pressure:Fourth-generation fighter fleets across Southeast Asia face mission relevance erosion against fifth-generation threat environments, forcing capability refresh cycles.
- Maritime Patrol Modernization:Australia's P-8A Poseidon integration programs and regional anti-submarine warfare investments sustain long-range surveillance upgrade demand.
- Software-Defined Architectures:Open-architecture mission computer replacements reduce vendor lock-in and accelerate avionics refresh timelines for regional air forces.
Market Restraints
- Airworthiness Certification Burden:Australia's Defence Aviation Safety Authority enforces documentation depth requirements that extend retrofit approval timelines and inflate compliance costs.
- Domestic Content Mandates:India's DRDO indigenous content thresholds fragment supplier bases and complicate multi-national upgrade consortium structuring.
- Structural Life Limitations:Airframe fatigue remediation for legacy F-16 and MiG-29 platforms faces diminishing returns as original design service life approaches exhaustion.
Strategic Opportunities
- Vietnam's Fleet Expansion:Underpenetrated Vietnamese air force modernization creates entry points for avionics and sensor upgrade providers as Russian-origin equipment ages.
- Sensor Fusion Convergence:Integration of synthetic aperture radar with electro-optical targeting systems enables multi-spectral mission capability packages for regional strike aircraft.
- Japan's Industrial Offset Policy:METI-coordinated F-15J upgrade work steers contract value toward domestic MRO facilities, creating partnership templates for foreign OEMs.
Industry Challenges
- Airworthiness Engineer Shortage:Qualified military certification specialists with platform-specific expertise concentrate in Australia and Japan, creating talent access bottlenecks for emerging programs.
- Legacy System Integration Complexity:Analog-to-digital cockpit conversions on 1980s-era airframes require custom interface development that stretches engineering timelines and inflates non-recurring costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Military Aircraft Modernization and Retrofit Market |
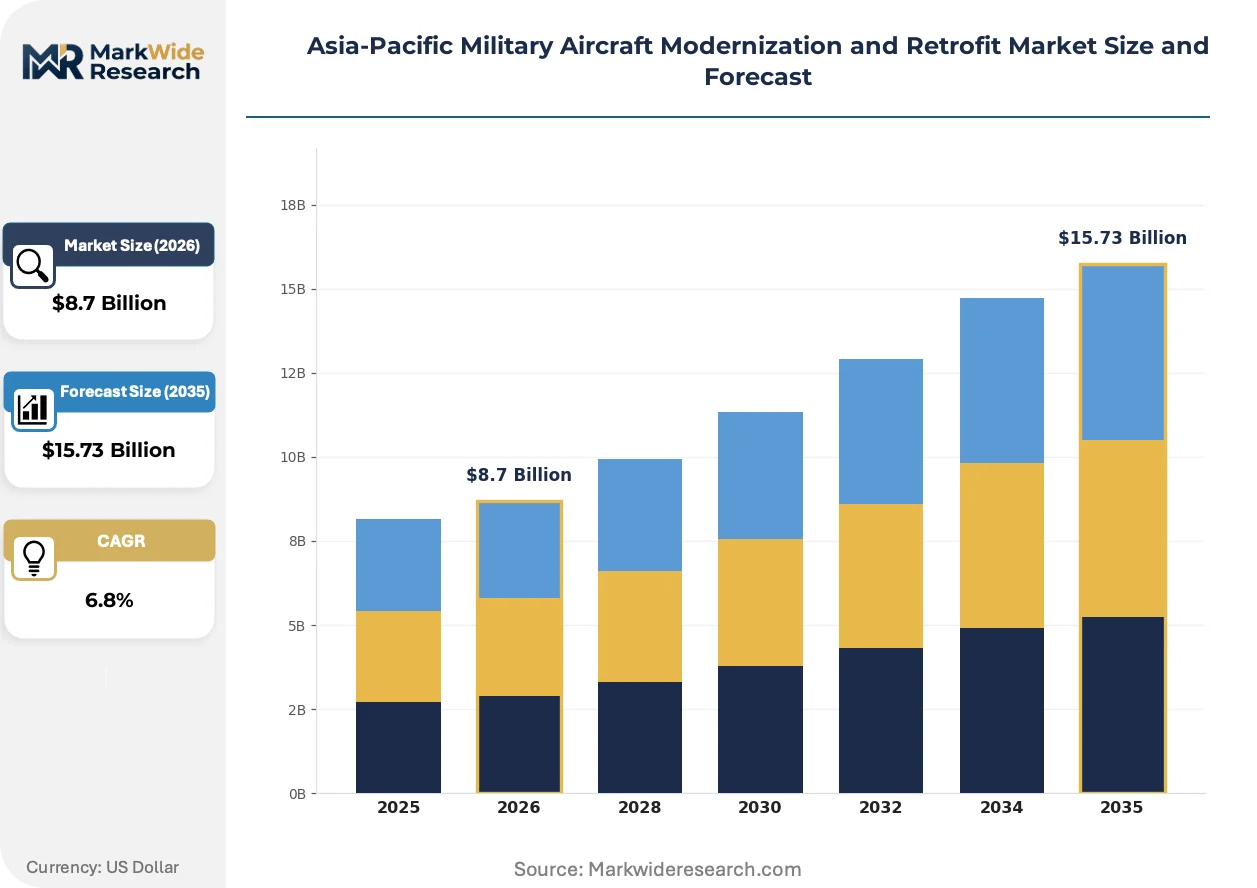
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fighter Jets, Transport Aircraft, Helicopters, UAVs Technology: Avionics, Propulsion Systems, Sensor Technologies, Weapon Systems End User: Military Forces, Government Agencies, Defense Contractors, Aerospace Firms Installation: On-site Maintenance, Upgrade Facilities, Depot Level, Mobile Support Units |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, BAE Systems PLC, Elbit Systems Ltd, Boeing, Mitsubishi Heavy Industries, Korea Aerospace Industries, Hindustan Aeronautics Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Military Aircraft Modernization and Retrofit Market Strategic Shifts
Digital engineering workflows are compressing retrofit development cycles across Asia-Pacific military aviation. Three concurrent developments reshape upgrade program execution and supplier positioning.
Model-based systems engineering is automating airframe fatigue analysis and avionics integration testing for F-16 and F-15 upgrade programs. Australian and Japanese defense contractors deploy these toolchains to reduce physical prototype dependency and accelerate certification submission preparation. This compression of design-validation timelines is automating competitive differentiation for first-mover upgrade providers.
Japan's METI industrial offset coordination for F-15J modernization establishes precedent for technology transfer thresholds in regional fighter upgrade contracts. The policy steers structural modification and software integration work toward domestic facilities while preserving foreign OEM system responsibility. Australian and Indian program offices observe this template for structuring sovereign capability requirements in forthcoming acquisition frameworks.
Performance-based logistics contracts displace transactional spare-part procurement across Asia-Pacific air forces. Royal Australian Air Force and Indian Air Force maintenance organizations now specify availability guarantees rather than component delivery schedules, transferring inventory risk to prime contractors. This reconfiguration concentrates most visibly in maritime patrol and fighter sustainment programs where platform age elevates reliability uncertainty.
Asia-Pacific Military Aircraft Modernization and Retrofit Market Segmentation
Modernization program scope varies dramatically by platform complexity and technology insertion depth. Segmentation reveals where capital deployment concentrates and which upgrade pathways offer suppliers the clearest entry points.
Product Type:
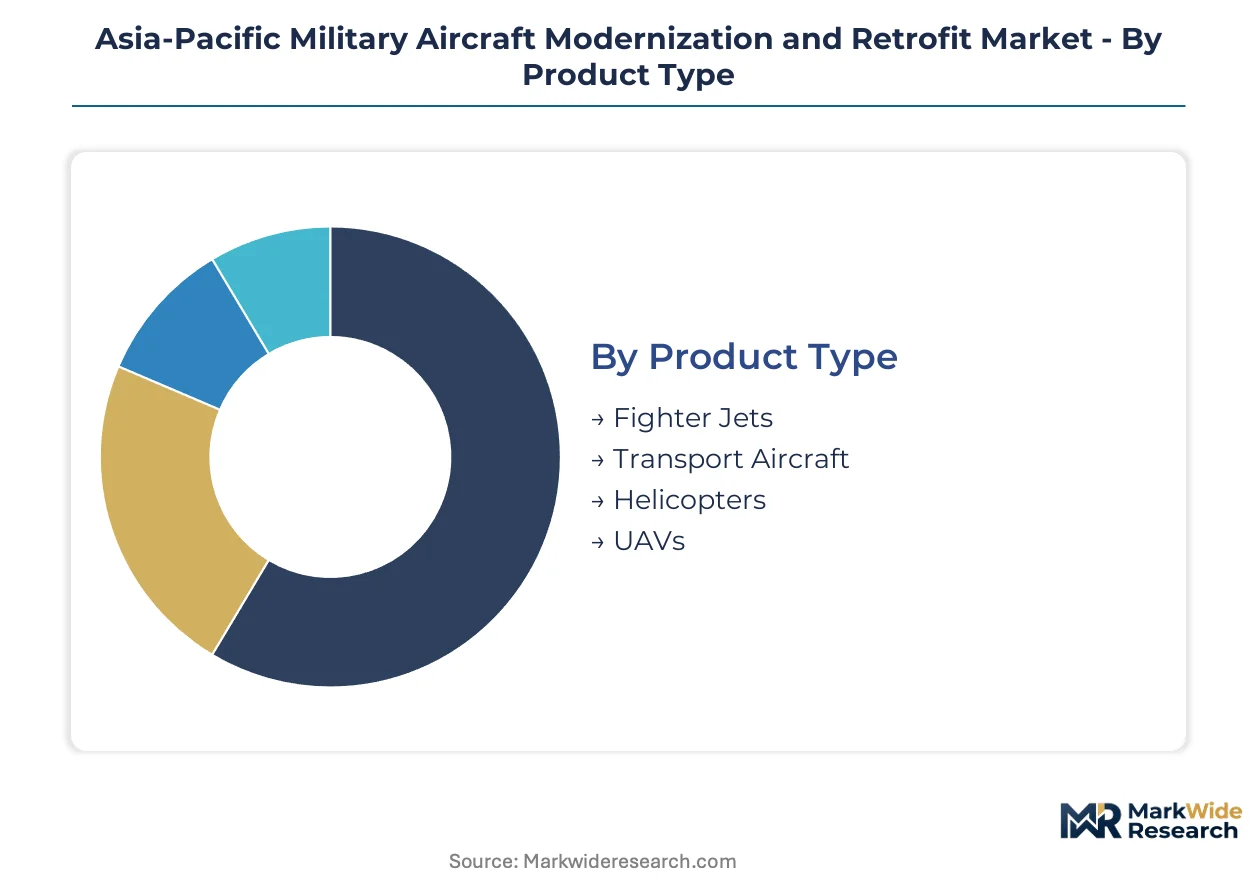
Fighter jets absorb the heaviest capital outlays per airframe due to structural life extension, cockpit digitization, and radar cross-section reduction requirements. Transport aircraft and helicopters follow at lower unit costs but higher fleet volumes.
- Fighter Jets:Fourth-generation F-16, F-15, and MiG-29 fleets dominate current upgrade pipelines. India's Tejas program and Australia's F/A-18 replacement timeline sustain multi-year avionics and engine refurbishment contracts.
- Transport Aircraft:C-130 Hercules and C-17 Globemaster structural fatigue programs concentrate in Royal Australian Air Force and Indian Air Force depots. These programs emphasize wing box replacements and cargo handling system digitization at lower technical risk than fighter conversions.
- Helicopters:Utility and attack rotorcraft upgrades focus on night vision compatibility and defensive aid suite integration across Southeast Asian militaries.
- UAVs:Sensor payload swaps and communication link encryption refreshes dominate unmanned platform modernization, particularly for tactical surveillance assets.
Most installed capacity flows through Fighter Jets. Expansion is steepest in UAVs.
Technology:
Technology segmentation tracks where engineering hours concentrate and which subsystems drive program cost escalation. Avionics and sensor technologies command premium pricing due to software complexity and military qualification requirements.
- Avionics:Open-architecture mission computers and software-defined radios replace proprietary 1980s-era systems. Australia's Defence Aviation Safety Authority certification standards dictate documentation depth for these conversions, extending approval timelines.
- Sensor Technologies:Synthetic aperture radar and electro-optical/infrared turret integration enables multi-spectral targeting. Japan's F-15J upgrade program steers this work toward domestic facilities under METI industrial offset coordination.
- Propulsion Systems:Engine hot-section refurbishment and full authority digital engine control retrofits restore thrust performance and fuel efficiency for aging fighter and transport fleets.
- Weapon Systems:Hardpoint structural reinforcement and fire control software updates accommodate precision-guided munition inventories, particularly for regional strike aircraft modernization.
Avionics captures the dominant share of engineering expenditure. Sensor Technologies climbs fastest as multi-spectral fusion becomes standard.
End User:
End user segmentation determines contracting vehicle structures and security clearance requirements. Military forces retain direct control over flight-critical modifications, while support services increasingly shift to contractor logistics support arrangements.
- Military Forces:Airworthiness certification and operational release authority remain with uniformed engineering officers. India's Defence Research and Development Organisation mandates indigenous content thresholds that reshape foreign OEM partnership structures.
- Defense Contractors:Performance-based logistics contracts transfer inventory risk to primes, specifying availability guarantees rather than component delivery schedules for maritime patrol and fighter sustainment programs.
- Government Agencies:Defense acquisition procedure offices in India and Australia's Capability Acquisition and Sustainment Group structure multi-year upgrade funding and milestone payment frameworks.
- Aerospace Firms:Domestic maintenance, repair, and overhaul facilities execute structural modifications under technology transfer arrangements, particularly in Japan and South Korea.
Military Forces control the certification gateway. Defense Contractors are capturing expanded scope through availability-based contracting.
Installation:
Installation mode segmentation reflects platform mobility requirements and technical facility thresholds. Depot-level work handles structural modifications requiring specialized tooling, while operational tempo pressures drive demand for forward-deployed capabilities.
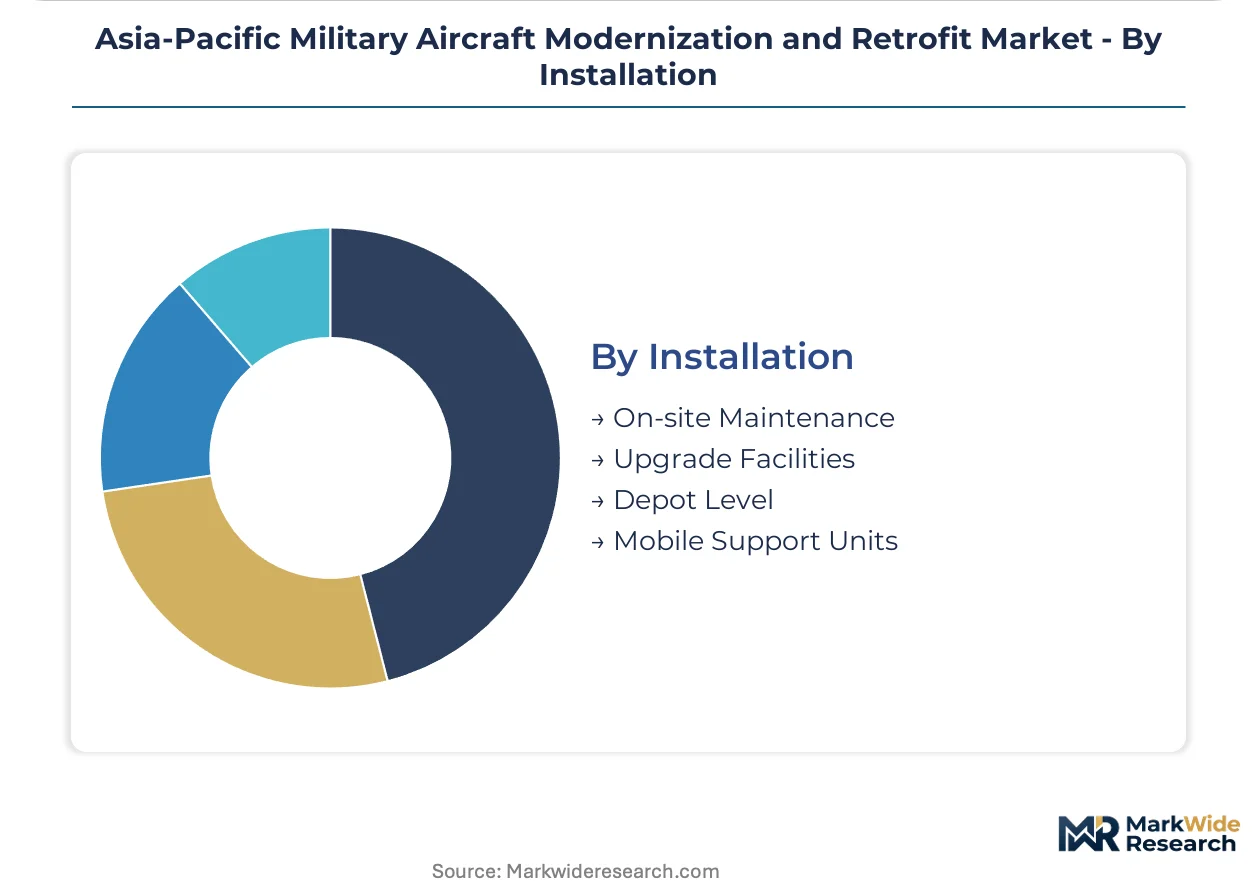
- Depot Level:Wing replacement, fuselage section joins, and major avionics rack installation require fixed-base facilities with climate-controlled hangars and non-destructive testing equipment. These constraints concentrate heavy maintenance in Australia, Japan, and India.
- On-site Maintenance:Line replaceable unit swaps and software uploads execute at operational airfields to minimize aircraft downtime. Royal Australian Air Force and Indian Air Force maintenance organizations prioritize these capabilities for fleet availability.
- Upgrade Facilities:Dedicated modernization centers house concurrent modification lines for multiple airframes, achieving economies of scope on F-16 and helicopter upgrade programs.
- Mobile Support Units:Deployable maintenance teams with containerized test equipment support expeditionary operations and distributed basing concepts across Southeast Asian archipelagos.
Depot Level handles the most complex structural work. On-site Maintenance is expanding fastest as operational readiness metrics tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru's defense aerospace cluster anchors Asia-Pacific military aircraft modernization capacity, hosting India's integrated systems engineering centers and flight test infrastructure. Regional upgrade demand concentrates in four national markets with distinct procurement frameworks and industrial offset requirements.
India
India's fighter jet upgrade pipeline drives the heaviest capital deployment, with Tejas indigenous production and Su-30MKI avionics refresh programs absorbing multi-year engineering resources. The Defence Acquisition Procedure mandates indigenous content thresholds that reshape foreign OEM partnership structures, forcing technology transfer commitments. Bengaluru and Hyderabad house the primary MRO facilities executing structural modifications and software integration under DRDO oversight.
Japan
Japan's F-15J modernization program sustains depot-level workload at Gifu and Komaki air bases, with structural life extension and radar cross-section reduction commanding premium engineering hours. METI coordinates industrial offset policies that steer contract value toward domestic MRO facilities while preserving foreign system responsibility. Mitsubishi Heavy Industries facilities in Aichi Prefecture execute wing box replacements and mission computer installations under these arrangements.
Australia
Australia's P-8A Poseidon integration and F/A-18 replacement timeline sustain maritime patrol and fighter sustainment programs at RAAF Amberley and Edinburgh bases. The Defence Aviation Safety Authority enforces airworthiness certification standards that dictate retrofit scope and documentation depth, extending approval timelines. Capability Acquisition and Sustainment Group offices in Canberra structure multi-year upgrade funding frameworks with availability-based contracting terms.
South Korea
South Korea's KF-21 indigenous fighter development creates parallel upgrade demand for legacy F-16 and F-15K fleets requiring avionics convergence and sensor fusion integration. Korea Aerospace Industries facilities in Sacheon anchor domestic structural modification capacity while technology transfer agreements govern foreign subsystem procurement. Seoul's Defense Acquisition Program Administration coordinates offset requirements that concentrate software integration work at domestic engineering centers.
Vietnam
Vietnam's Russian-origin Su-27 and Su-30 fleet obsolescence creates entry points for avionics and sensor upgrade providers as equipment ages beyond original design service life. The country's national defense procurement office evaluates non-Russian upgrade pathways amid supply chain realignment pressures. Bien Hoa and Phan Rang air bases represent the primary operational concentrations where maintenance organizations assess cockpit digitization and communication system replacement options.
Asia-Pacific Military Aircraft Modernization and Retrofit Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue sovereign capability partnerships and technology transfer arrangements. The supplier base concentrates around three strategic archetypes: foreign OEMs with platform-specific sustainment footprints, domestic aerospace conglomerates with METI or DRDO-mandated work share, and mid-tier avionics specialists capturing open-architecture mission computer replacements. Competitive dynamics center on performance-based logistics contract capture and industrial offset compliance rather than pure price competition.
Within the foreign OEM tier, Lockheed Martin Corporation and Boeing occupy positions defined by F-16 and integrated platform upgrade program legacies across multiple Asia-Pacific air forces. RTX Corporation exemplifies the avionics and sensor specialist archetype, while Hindustan Aeronautics Limited represents the domestic conglomerate model with DRDO-mandated indigenous content execution. These three anchors illustrate how supplier positioning stratifies across sovereign capability requirements and platform interoperability standards.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Northrop Grumman Corporation |
| BAE Systems PLC |
| Elbit Systems Ltd |
| Boeing |
| Mitsubishi Heavy Industries |
| Korea Aerospace Industries |
| Hindustan Aeronautics Limited |
| Others |
Value Chain & Pricing Dynamics
Australia's Defence Aviation Safety Authority certification mandates gate qualified supply access and sustain premium-tier pricing for avionics retrofit providers. Performance-based logistics contracts concentrate procurement risk with primes, compressing margins for subcontractors while elevating documentation compliance costs across the upgrade value chain.
Pricing Analysis
Input-cost pass-through from titanium alloys and gallium nitride semiconductors shapes contract escalation clauses for structural and avionics retrofits. Three-tier pricing structure across platform-integrated, subsystem-only, and component-replacement levels separates full-service upgrade providers from parts specialists. Pricing pressure stems from India's DRDO indigenous content mandates forcing technology transfer concessions. National air forces exhibit lowest price sensitivity for flight-critical avionics; Southeast Asian maintenance organizations show highest sensitivity for line-replaceable units.
Supply Chain Analysis
Freight cost volatility for precision avionics components from Japan, South Korea, and the United States elevates inventory carrying requirements at Australian and Indian depot facilities. Specialized mission computers and radar subassemblies draw from concentrated semiconductor fabrication in Taiwan and South Korea. Single-source vulnerability pervades software-defined radio chipsets. Distribution runs through prime contractor logistics networks rather than open market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
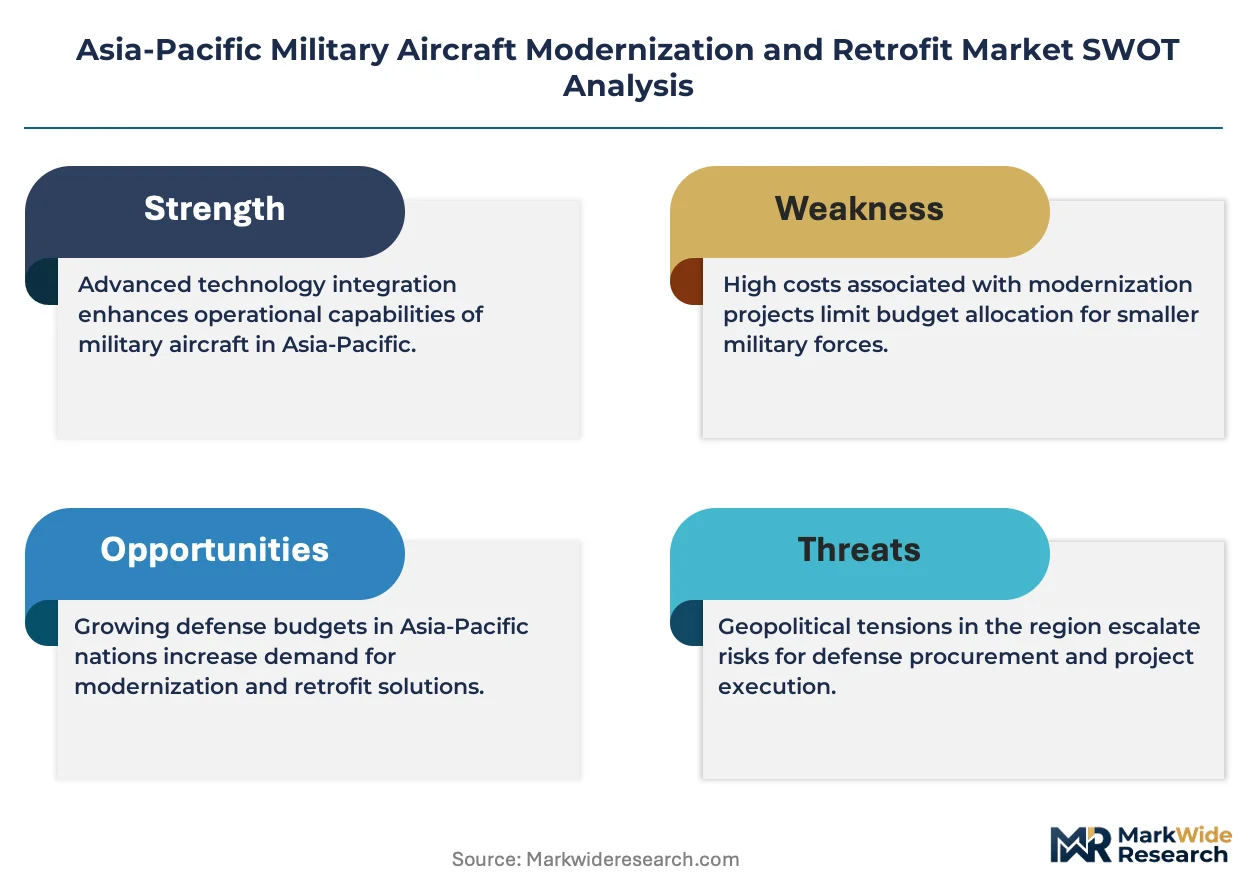
This market represents a late-cycle quality story as fourth-generation fighter obsolescence forces specification upgrades toward open-architecture mission computers and sensor fusion packages.
For Market Incumbents: Acquire airworthiness certification capabilities in Australia and Japan to defend against emerging MRO specialists. Lockheed Martin and Boeing sustainment franchises face pressure from Hindustan Aeronautics Limited and Korea Aerospace Industries capturing domestic work share through offset mandates. Backward integration into software-defined radio module production secures margin control against semiconductor supply volatility. For New Entrants and Emerging Players: Domestic MRO facilities in Vietnam and Indonesia represent the most penetrable channel partner type for avionics specialists seeking platform entry. Russian-origin fleet obsolescence across Southeast Asia creates white-space for cockpit digitization providers. Partner with national defense procurement offices to navigate sovereign capability requirements rather than competing directly for prime contracts. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier avionics specialists because performance-based logistics contracting concentrates long-term revenue with integrated platform providers. Five-to-ten year viability hinges on open-architecture mission computer positioning. Watch India's Defence Acquisition Procedure indigenous content threshold adjustments as the inflection signal for foreign OEM partnership restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Transfer Partnership | DRDO indigenous content mandates force foreign OEMs to cede software integration work to domestic facilities. |
| Airworthiness Certification Investment | Australia's DASA documentation requirements extend approval timelines and inflate compliance costs for new entrants. |
| Performance-Based Logistics Contract | Royal Australian Air Force availability guarantees transfer inventory risk from military operators to prime contractors. |
| Sensor Fusion Capability Buildout | Japan's F-15J upgrade program steers synthetic aperture radar integration toward Mitsubishi Heavy Industries. |
| Depot-Level Capacity Expansion | Bengaluru and Hyderabad MRO facilities absorb structural modification workload from India's Tejas and Su-30MKI programs. |
Study Parameters
Bottom-up fleet modeling reconciled against top-down defense budget tracking forms the analytical core. Primary interviews with program managers at India's Defence Acquisition Procedure offices, Australia's Capability Acquisition and Sustainment Group, Japan's Acquisition Technology and Logistics Agency, and maintenance directors at Royal Australian Air Force bases combined with secondary validation from parliamentary defense committee reports, national budget appropriations documents, and air force modernization white papers. Triangulation against OEM technical order releases and military airworthiness directive databases verified upgrade timeline assumptions.
Historical trendline analysis of F-16 and F-15 sustainment contract values established baseline expenditure patterns across the projection horizon. Segmentation modeling incorporated platform type, technology insertion depth, end-user contracting structure, and installation mode. CAGRs derived from fleet age distribution analysis and obsolescence-driven replacement cycles. Forecast inputs included India's indigenous fighter production ramp and Australia's maritime patrol aircraft replacement timeline.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sovereign capability policy shifts and regional threat environment evolution. Assumptions reflect documented procurement frameworks rather than speculative political scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
Man Portable Military Electronics Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
Global CBRN Defense Market
Military Equipment and Infrastructure
Next Generation Military Power Supply Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Europe Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Wearable Computers Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
CBRNE Defense Market
Military Equipment and Infrastructure
Global Mine Countermeasures Market
Military Equipment and Infrastructure
Global Soldier Modernization Market
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Military Optoelectronic System Market
Military Equipment and Infrastructure
Latin America Defense Market