
 Next Generation Military Power Supply Market | 2026-2036
Next Generation Military Power Supply Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Military Power Supply Market Outlook
The gap between custom-engineered high-reliability units and commercially adapted power modules is rebalancing as defense procurement offices tighten qualification thresholds while seeking cost discipline. Eaton Corporation PLC leverages its aerospace-electrical heritage to sustain long-term military contracts. SynQor, Inc. anchors its position through dense brick-format DC-DC converters purpose-built for harsh environments. XP Power competes by extending its high-voltage portfolio into radiation-tolerant and military-grade variants.
Next generation military power supply encompasses ruggedized electrical conversion and distribution equipment engineered to operate across input voltage ranges of 85-264 VAC or 16-40 VDC, withstanding temperature extremes from -55°C to +125°C, shock loads exceeding 40g, and electromagnetic interference per MIL-STD-461G; its core purpose is ensuring uninterrupted, clean power to mission-critical avionics, radar, and command systems under combat stress. DC power supplies dominate procurement volumes for ground vehicle and shipboard retrofits where 28-volt bus architectures remain standard. Advanced battery systems represent the fastest-expanding technology segment as lithium-sulfur and solid-state chemistries displace legacy sealed lead-acid in silent-watch applications. Multi-output supplies capture concentrated margin pools in satellite and unmanned platform programs where SWaP-C optimization drives specification.
The US Department of Defense enforces MIL-STD-704F and MIL-STD-461G as baseline electromagnetic and power quality standards, while the EU AI Act and CE marking under the Radio Equipment Directive shape access for European NATO suppliers. China's GB standards and MIIT certification requirements create parallel qualification tracks for dual-use components sourced through third-country channels. Stakeholders must monitor how AUKUS technology-sharing agreements reshape supplier eligibility across allied defense industrial bases.
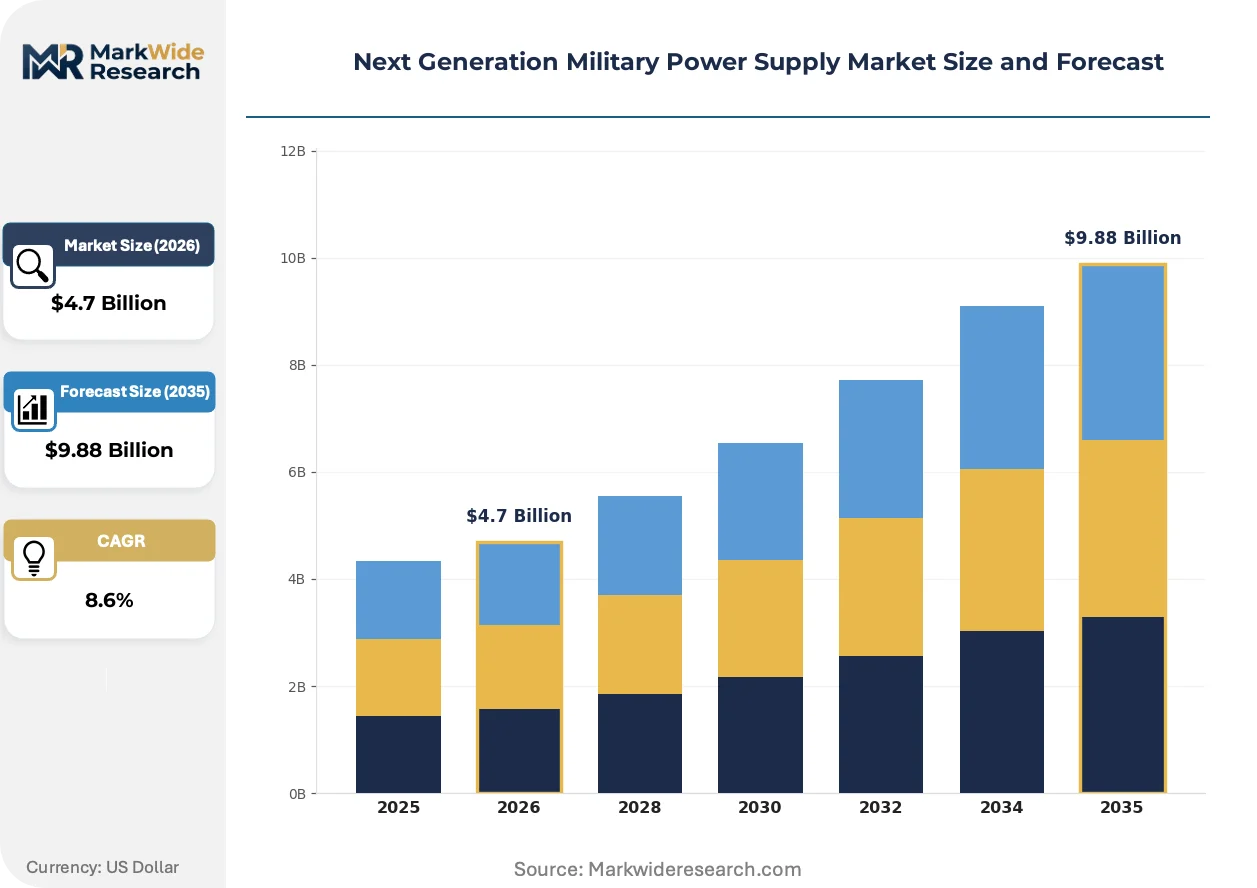
Market Dynamics
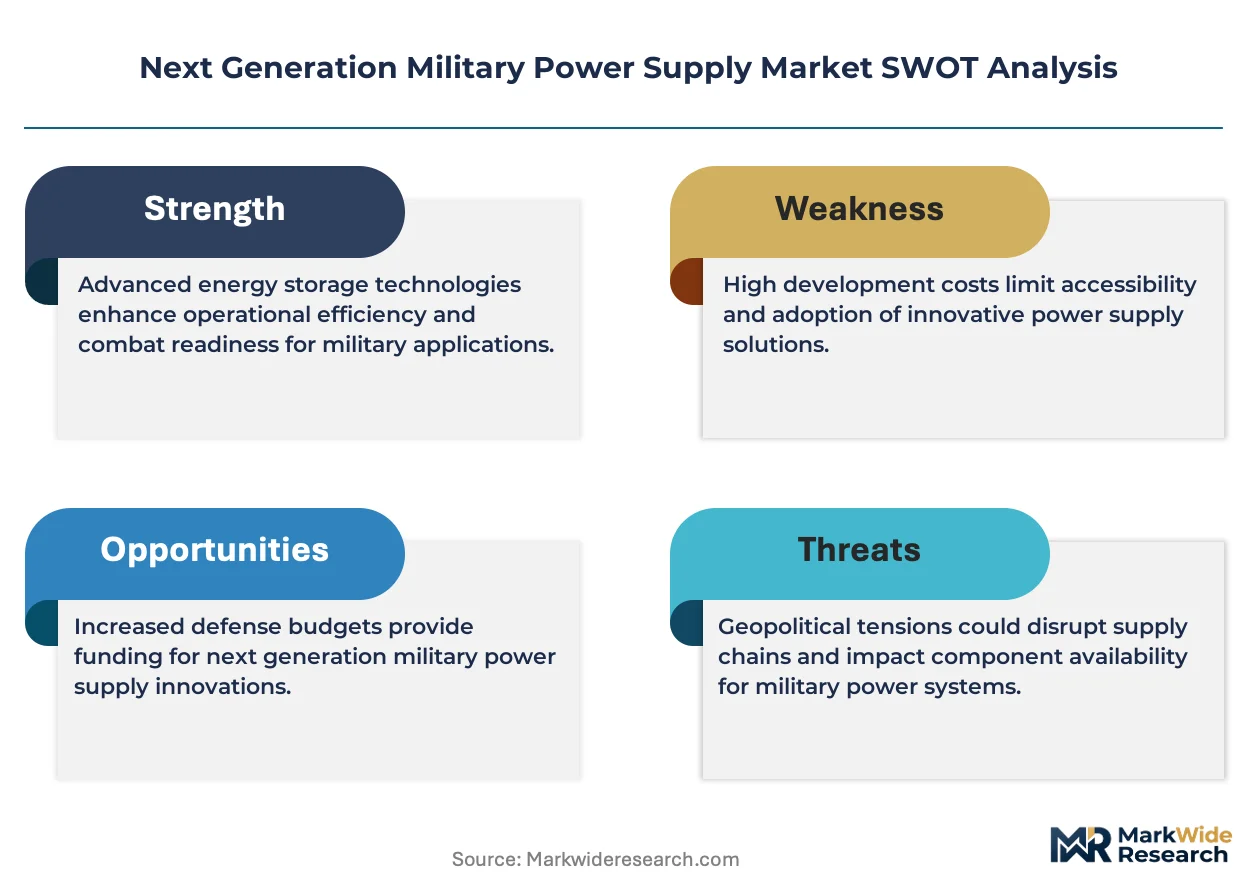
Defense procurement offices are tightening MIL-STD-704F and MIL-STD-461G qualification thresholds while simultaneously demanding cost discipline, forcing suppliers to reconcile high-reliability engineering with commercial-scale manufacturing economics.
Growth Catalysts
- Silent-watch lithium-sulfur batteries:Ground vehicle programs across NATO forces require extended silent operation without engine heat signatures, accelerating displacement of sealed lead-acid architectures.
- MIL-STD-461G electromagnetic compliance:Mandatory electromagnetic interference hardening for avionics and radar systems creates specification pull for qualified DC-DC converter suppliers.
- Indo-Pacific force posture expansion:Pentagon forward-deployment requirements for distributed maritime operations drive demand for ruggedized, lightweight power systems in Guam, Japan, and Australia.
Market Restraints
- Raw material concentration:Rare earth magnet and high-grade ferrite supply concentrates in Chinese processing facilities, exposing Western defense contractors to export restriction risk.
- Dual-use component licensing:US State Department ITAR controls and EU dual-use export regulations create multi-month approval delays for cross-border subsystem shipments.
- Legacy 28-volt bus lock-in:Existing armored vehicle and shipboard fleets require backward-compatible power architectures that constrain adoption of higher-efficiency 270-volt DC systems.
Strategic Opportunities
- AUKUS technology-sharing corridor:Trilateral US-UK-Australia submarine and unmanned systems agreements open supplier eligibility for power electronics vendors previously excluded from national programs.
- Solid-state battery integration:Convergence of solid-state electrolyte chemistry with silicon carbide switching semiconductors enables 40% volume reduction in satellite power systems.
- Direct-to-prime contracting:Tier-2 power module vendors are bypassing traditional subsystem integrators to contract directly with Northrop Grumman and Lockheed Martin platform teams.
Industry Challenges
- MIL-STD-810H environmental qualification timelines:Temperature cycling, shock, and vibration testing protocols extend product development cycles by 14-18 months.
- Power electronics engineering scarcity:Specialized talent in magnetics design, thermal management, and EMI suppression remains concentrated at a handful of defense-aerospace firms and university research centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Military Power Supply Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Power Supplies, DC Power Supplies, Multi-Output Supplies, Uninterruptible Power Supplies Application: Land Forces, Airborne Systems, Naval Operations, Critical Communications Technology: Solar Power, Wireless Energy Transfer, Fuel Cells, Advanced Battery Systems End User: Military Agencies, Government Contractors, Defense Research Organizations, Private Sector Suppliers |
| Companies Covered | Eaton Corporation PLC, TDK-Lambda Corporation, Mitsubishi Electric Corporation, SynQor, Inc., XP Power, Aegis Power Systems, Inc., Advanced Conversion Technology, Powerbox International AB, Vicor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Military Power Supply Market Strategic Shifts
Silicon carbide and gallium nitride wide-bandgap semiconductors are compressing converter size and thermal budgets, while procurement offices experiment with modular open-systems architectures that decouple power subsystem selection from platform prime contracts.
GaN-based switching devices are overtaking silicon IGBTs in 28-volt to 270-volt DC-DC conversion stages for unmanned aerial systems. Naval Air Systems Command and Army Futures Command programs specify GaN for new-start platforms, enabling 30% reduction in converter mass and extending operating temperature ranges to 175°C junction temperatures without derating.
EU AI Act risk-classification requirements are reshaping power supply documentation for autonomous weapon systems and AI-enabled sensor platforms. European NATO suppliers must demonstrate traceable electromagnetic compatibility test data and supply chain provenance to access CE-marked defense procurement channels, compressing vendor pools to firms with established EU notified-body relationships.
Platform primes are unbundling power subsystem procurement from airframe and vehicle integration contracts, creating direct purchasing relationships between end-users and specialized converter manufacturers. Raytheon and General Dynamics Land Systems now issue separate RFPs for power electronics, bypassing traditional tier-one system integrators and compressing supplier margins through competitive benchmarking against commercial-industrial equivalents.
Next Generation Military Power Supply Market Segmentation
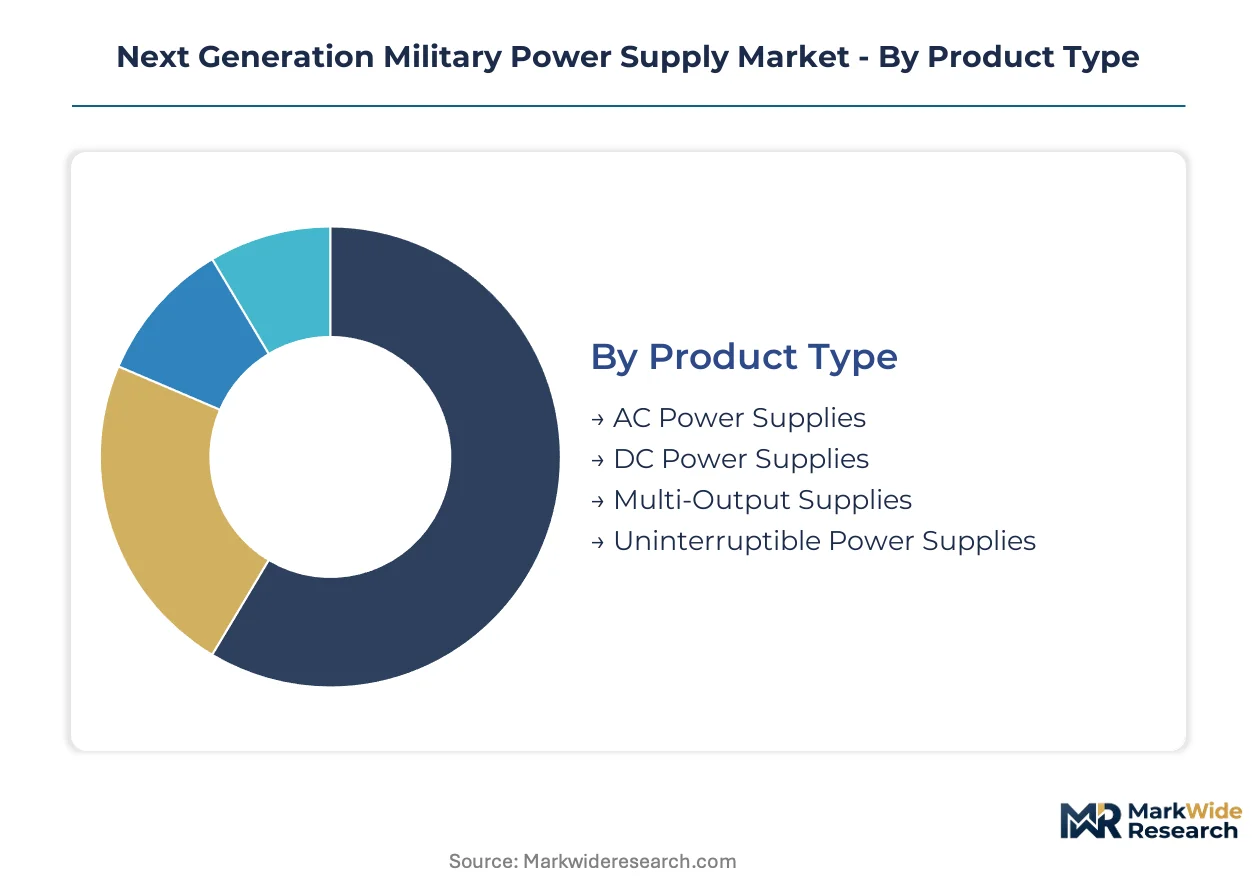
Military power supply segmentation reveals how procurement offices balance legacy platform compatibility against emerging mission requirements. Specification divergence across product architectures, operational domains, and energy technologies creates distinct competitive arenas with heterogeneous qualification barriers.
Product Type:
Technical specification hierarchies separate mission-critical avionics architectures from ground vehicle retrofit opportunities.
- DC Power Supplies:These units convert 16-40 VDC input to regulated output for 28-volt bus architectures standard across armored vehicle and shipboard fleets. Procurement concentrates in United States Army ground vehicle modernization programs and Navy shipboard retrofits where backward compatibility constraints dominate specification.
- Multi-Output Supplies:Single-unit architectures deliver synchronized voltage rails to avionics, radar, and command systems simultaneously. Demand clusters in satellite and unmanned platform programs where SWaP-C optimization drives Pentagon specification for distributed maritime operations in Guam and Japan.
- AC Power Supplies:Ruggedized units handle 85-264 VAC input ranges for forward operating base infrastructure and deployable command posts.
- Uninterruptible Power Supplies:Battery-backed systems ensure zero-transfer-time power continuity for critical communications nodes.
Mature deployment sits with DC Power Supplies. Newer deployment is concentrated in Multi-Output Supplies.
Application:
Operational domain determines environmental qualification severity and electromagnetic hardening requirements.
- Airborne Systems:Platforms demand power architectures operating across -55°C to +125°C temperature extremes while withstanding shock loads exceeding 40g. United States Air Force and Navy aviation programs in the Indo-Pacific drive specification for lighter, more efficient units compatible with extended-range missions.
- Land Forces:Ground vehicle programs require silent-watch capability and electromagnetic compatibility per MIL-STD-461G. NATO armored vehicle fleets across Germany and Poland are accelerating displacement of sealed lead-acid battery architectures.
- Naval Operations:Shipboard systems face salt-fog corrosion and continuous vibration profiles distinct from airborne or ground applications.
- Critical Communications:Command-and-control infrastructure demands uninterruptible power with MIL-STD-704F power quality compliance.
Established procurement volume rests with Land Forces. Steepest expansion trajectory belongs to Airborne Systems.
Technology:
Energy conversion chemistry and transmission modality separate proven battlefield architectures from experimental insertion programs.
- Advanced Battery Systems:Lithium-sulfur and solid-state chemistries displace legacy sealed lead-acid in silent-watch applications. Ground vehicle programs across NATO forces require extended engine-off operation without thermal signatures, driving chemistry qualification timelines.
- Solar Power:Photovoltaic arrays with MIL-STD-810H environmental hardening support expeditionary forward operating bases.
- Fuel Cells:Proton-exchange-membrane systems offer extended duration power for unmanned underwater vehicles and remote sensor networks.
- Wireless Energy Transfer:Inductive and resonant coupling architectures remain experimental for drone swarming and autonomous resupply.
Field-proven deployment concentrates in Advanced Battery Systems. Emerging validation focuses on Wireless Energy Transfer.
End User:
Contracting authority determines qualification pathway complexity and direct procurement access.
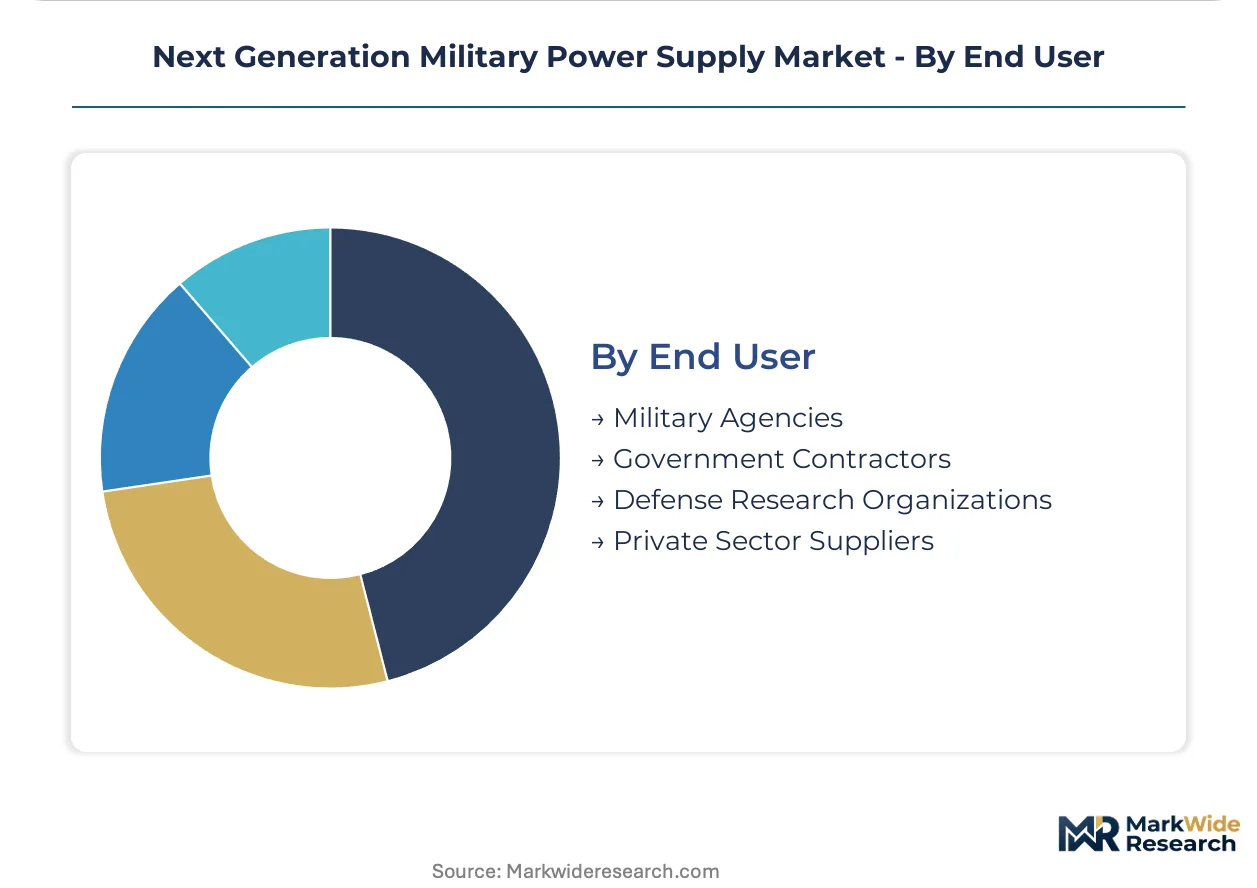
- Military Agencies:Pentagon program offices and service-specific acquisition commands enforce MIL-STD-704F and MIL-STD-461G as mandatory gatekeepers. United States Department of Defense modernization budgets concentrate demand through Defense Logistics Agency and service program executive offices.
- Government Contractors:Tier-1 platform primes including Northrop Grumman and Lockheed Martin issue separate RFPs for power electronics, bypassing traditional subsystem integrators.
- Defense Research Organizations:DARPA and service laboratories fund advanced chemistry and wide-bandgap semiconductor validation.
- Private Sector Suppliers:Commercial-industrial vendors seek ITAR registration and MIL-STD qualification for defense market entry.
Contractual authority concentrates with Military Agencies. Direct purchasing expansion is accelerating through Government Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Washington-Arlington-Alexandria metropolitan corridor concentrates Pentagon program offices and Defense Logistics Agency procurement commands that shape qualification requirements for military power supply vendors worldwide.
United States
Indo-Pacific force posture expansion and Army Futures Command modernization programs drive specification for ruggedized 28-volt and 270-volt DC architectures. The Department of Defense enforces MIL-STD-704F and MIL-STD-461G as mandatory gatekeepers through Naval Air Systems Command and Army program executive offices. Huntsville, Alabama and San Diego, California host concentrated prime contractor facilities where Northrop Grumman and Lockheed Martin teams issue direct RFPs for power electronics subsystems.
Germany
NATO armored vehicle fleet modernization across Bundeswehr ground forces accelerates displacement of sealed lead-acid battery architectures with lithium-sulfur silent-watch systems. The EU AI Act and CE marking under the Radio Equipment Directive reshape documentation requirements for autonomous platform power supplies. The Bavarian industrial corridor around Munich hosts specialized magnetics and thermal management engineering clusters serving European defense-aerospace supply chains.
United Kingdom
AUKUS submarine and unmanned systems agreements open supplier eligibility for power electronics vendors previously excluded from national programs. Ministry of Defence procurement offices specify DEF STAN 61-5 power quality standards alongside MIL-STD harmonization for interoperability. The Bristol-South Wales aerospace cluster concentrates BAE Systems platform integration teams sourcing qualified DC-DC converters for next-generation combat aircraft.
Australia
Trilateral technology-sharing commitments under AUKUS drive demand for submarine and autonomous underwater vehicle power systems compatible with US-UK supply chains. The Department of Defence enforces sovereign industrial capability priorities that favor local assembly of qualified subsystems. The Osborne naval shipyard in South Australia and Henderson maritime precinct in Western Australia anchor distributed maritime operations infrastructure requiring expeditionary power architectures.
Japan
Ministry of Defense fighter and maritime patrol aircraft programs specify wide-bandgap semiconductor power conversion for extended-range Indo-Pacific missions. METI industrial policy supports domestic SiC and GaN device fabrication to reduce import dependency for critical switching components. The Nagoya aerospace cluster and Kawasaki heavy industrial corridor host Mitsubishi Electric and tier-one subsystem integrators developing indigenous military power supply capabilities.
Next Generation Military Power Supply Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a market structure that consolidates around aerospace-electrical heritage firms and fragments among specialized converter boutiques. Tier-1 platform primes increasingly bypass traditional subsystem integrators to contract directly with power module vendors, compressing margins through competitive benchmarking. Three archetypes dominate: diversified industrial conglomerates with defense-aerospace divisions, pure-play power electronics specialists, and commercial-industrial vendors seeking ITAR registration for defense market entry. Dominant competitive moves include direct-to-prime contracting relationships and silicon carbide technology licensing for next-generation wide-bandgap architectures.
Within the diversified conglomerate tier, Eaton Corporation PLC represents aerospace-electrical heritage positioning, while TDK-Lambda Corporation exemplifies Japanese industrial group defense market participation. Among pure-play specialists, SynQor, Inc. anchors the dense brick-format DC-DC converter segment, and XP Power occupies a position extending commercial high-voltage expertise into radiation-tolerant and military-grade variants. These named entities illustrate how vendor pools compress to firms with established qualification track records and direct platform prime relationships.
| Leading Market Players |
|---|
| Eaton Corporation PLC |
| TDK-Lambda Corporation |
| Mitsubishi Electric Corporation |
| SynQor, Inc. |
| XP Power |
| Aegis Power Systems, Inc. |
| Advanced Conversion Technology |
| Powerbox International AB |
| Vicor Corporation |
| Others |
Value Chain & Pricing Dynamics
MIL-STD-461G electromagnetic compliance mandates gate premium-tier pricing access by restricting qualified supplier pools to firms with proven test-house relationships, while simultaneously concentrating procurement leverage among Pentagon program offices that demand cost discipline alongside certification rigor.
Pricing Analysis
Mission-uptime guarantees anchor value-based pricing for avionics-qualified DC-DC converters, with contracts tying payment milestones to mean-time-between-failure performance thresholds. Price differentiation separates MIL-STD-704F certified units from commercially adapted variants, while volume scale and customization depth modulate per-unit economics. Cost compression in brick-format converter tiers is intensifying because platform primes now benchmark specialized vendors against industrial-commercial equivalents. Government contractors exhibit lowest price sensitivity due to sole-source qualification lock-in, whereas private sector suppliers face acute margin pressure entering defense channels.
Supply Chain Analysis
Dual-sourcing requirements for rare earth magnets and high-grade ferrite cores compel Pentagon procurement offices to qualify secondary suppliers beyond Chinese processing facilities. Magnet materials concentrate in China, Japan, and the United States, while silicon carbide substrates draw from Japanese and German wafer fabrication. Supply chain risk centers on export restriction exposure for dual-use magnet processing. Distribution runs through Defense Logistics Agency stocking points and prime contractor direct procurement channels, bypassing traditional tier-one subsystem integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized magnetics engineering scarcity props pricing power for qualified vendors, constraining capacity expansion across wide-bandgap semiconductor converter architectures.
For Market Incumbents: Deploy direct-to-prime contracting relationships to bypass eroding subsystem integrator margins. Deepen backward integration into silicon carbide packaging capabilities to secure switching component supply against Japanese wafer allocation constraints. Lock in long-term qualification pipeline access through Naval Air Systems Command and Army Futures Command program early engagement. For New Entrants and Emerging Players: AUKUS technology-sharing agreements in Australia open a window for power electronics vendors previously excluded from US and UK national programs. White-space concentration sits in solid-state battery integration for satellite and unmanned underwater vehicle platforms, plus GaN-based converter supply for Japanese fighter modernization programs. Pursue ITAR registration paired with MIL-STD-810H environmental pre-qualification to accelerate Pentagon access timelines. For Investors and Strategic Acquirers: Direct RFP issuance from Northrop Grumman and Lockheed Martin platform teams is the leading indicator that tier-2 power module vendors are capturing margin pools previously held by subsystem integrators. Long-term viability favors acquisition targets with established EU notified-body relationships for CE-marked defense channels and existing wide-bandgap semiconductor licensing agreements. Watch for AUKUS submarine program power system specification releases as inflection signals for supplier eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| MIL-STD Qualification Pre-Investment | Early engagement with Naval Air Systems Command test houses accelerates Pentagon supplier gatekeeping timelines. |
| Wide-Bandgap Semiconductor Licensing | SiC and GaN device agreements with Japanese substrate suppliers anchor next-generation converter thermal performance. |
| Direct-to-Prime Contracting | Bypassing tier-one integrators captures margin pools in Lockheed Martin and Raytheon platform programs. |
| AUKUS Corridor Market Entry | Trilateral US-UK-Australia agreements open procurement access for previously excluded national program suppliers. |
| Solid-State Battery Integration | Convergence with silicon carbide switching enables 40% volume reduction in satellite power architectures. |
Study Parameters
Defense Logistics Agency procurement databases, Naval Air Systems Command specification releases, and SEC filings from aerospace-electrical heritage firms formed the secondary backbone, supplemented by primary interviews with power electronics program managers, MIL-STD test house engineers, prime contractor procurement leads, and magnetics design specialists. Bottom-up and top-down triangulation validated segment-level estimates against Pentagon modernization budget allocations and platform prime RFP issuance patterns.
Bottom-up modeling built from individual program requirements across Army Futures Command, Indo-Pacific force posture initiatives, and NATO armored vehicle modernization fleets, while top-down analysis cross-checked against aggregate defense electronics procurement trends. The forecast framework spans product type, operational domain, energy conversion technology, and contracting authority segments. CAGRs were derived from weighted program pipeline analysis and qualification timeline compression assumptions, with silicon carbide adoption curves and lithium-sulfur battery chemistry maturation serving as key technology inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery chemistry or gallium nitride switching semiconductors would alter the outlook for volume and mass reduction trajectories. Deviation in AUKUS technology-sharing implementation timelines or Chinese rare earth export licensing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Military Wearable Computers Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
FLIR and Laser Designator Targeting Pods Market
Military Equipment and Infrastructure
Deployable Military Shelters Market
Military Equipment and Infrastructure
Global Mine Countermeasures Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Europe Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Tent and Shelter Market
Military Equipment and Infrastructure
Howitzer Artillery System Market
Military Equipment and Infrastructure
Europe Digital Battlefield Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market