
 Global Stealth Warfare Market | 2026-2036
Global Stealth Warfare Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stealth Warfare Market Foresight
Buyer concentration among national defense ministries is realigning procurement leverage toward fewer, larger multi-year platform contracts. Lockheed Martin Corporation leverages its dominance in fifth-generation fighter production to sustain long-term revenue visibility. Northrop Grumman Corporation anchors the bomber and unmanned segments through classified development pipelines. BAE Systems competes across European cooperative programs while navigating transatlantic technology-sharing agreements.
Stealth warfare encompasses the design, engineering, and deployment of platforms, materials, and systems engineered to minimize detectability across radar, infrared, acoustic, and electromagnetic spectra, typically employing ferrite-based radar-absorbent coatings, geometric shaping, and plasma shielding to achieve radar cross-sections below 0.001 square meters on advanced aircraft. Aircraft platforms occupy the largest value pool given unit costs and platform longevity, while unmanned vehicles represent the fastest-expanding segment as autonomous swarming reduces risk to manned assets. Radar absorbing material technology commands premium margins due to formulation complexity and limited qualified suppliers, whereas acoustic dampening remains comparatively mature in submarine applications.
The U.S. Department of Defense, the EU's European Defence Agency, and China's SAMR set divergent technical standards that fragment market access and force dual-certification investments. FAA and EASA airworthiness requirements intersect with military secrecy protocols, complicating cross-border subsystem sales. Stakeholders must monitor export control evolution and sovereign content mandates to anticipate which technology tiers remain tradable.
Market Dynamics
Defense procurement consolidation around multi-year platform contracts is concentrating buyer leverage among national ministries, forcing suppliers to absorb longer development cycles and classified technology transfer obligations.
Growth Catalysts
- Low-Observable Platform Procurement:NATO member states are expanding orders for survivable strike assets. The U.S. Department of Defense prioritizes fifth-generation fighter and next-generation bomber programs in its budget allocations.
- Radar-Absorbing Material Advancement:Ferrite-based composites and metamaterial coatings are achieving radar cross-section reductions below 0.001 square meters. Formulation complexity sustains premium pricing for qualified suppliers.
- Autonomous Swarming Systems:Unmanned combat aerial vehicles reduce risk to manned crews. China's SAMR and the EU's European Defence Agency both fund classified development pipelines for loyal wingman programs.
Market Restraints
- Rare Earth Supply Concentration:Ferrite and neodymium processing concentrates in China. Export licensing unpredictability threatens radar-absorbent material production schedules for Western manufacturers.
- Dual-Certification Burden:Divergent technical standards between the U.S. Department of Defense, EDA, and SAMR force redundant qualification testing. Platform developers face 18-24 month delays for cross-border subsystem sales.
- Plasma Shielding Technical Limits:Power consumption and atmospheric interference constrain operational deployment. Current systems require substantial energy storage that compromises payload capacity.
Strategic Opportunities
- Indian Indigenous Development:India's DRDO advances domestic stealth fighter programs under the AMCA project. Technology transfer partnerships with France and Russia create subsystem entry points for foreign suppliers.
- Acoustic Dampening Modernization:Aging submarine fleets in the United Kingdom and Australia require infrared suppression retrofits. The AUKUS agreement channels funding toward coordinated platform upgrades.
- AI-Enabled Signature Management:Machine learning algorithms optimize real-time radar cross-section modulation. Convergence of adaptive materials and predictive analytics enables dynamic stealth performance.
Industry Challenges
- Specialized Workforce Scarcity:Electromagnetic compatibility engineering and classified materials science require security clearances. Talent pipelines lag demand across U.S., UK, and Australian defense industrial bases.
- ITAR Compliance Complexity:U.S. State Department export controls restrict technology sharing with allied co-development programs. Licensing timelines extend program schedules and erode competitive positioning.
- Legacy Platform Integration:Fourth-generation aircraft retrofit programs face structural modification limits. Airframe geometry constraints prevent full signature reduction achievable in clean-sheet designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stealth Warfare Market |
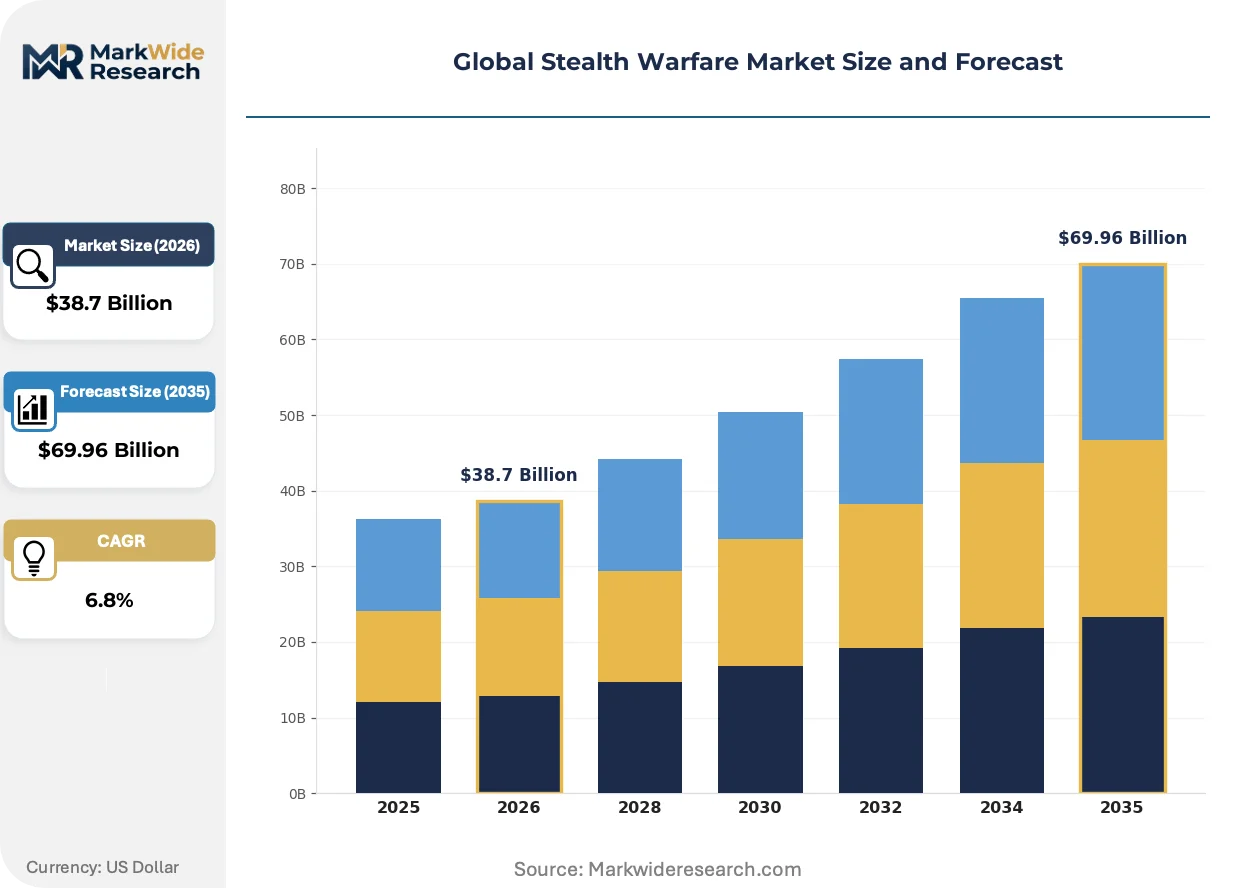
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
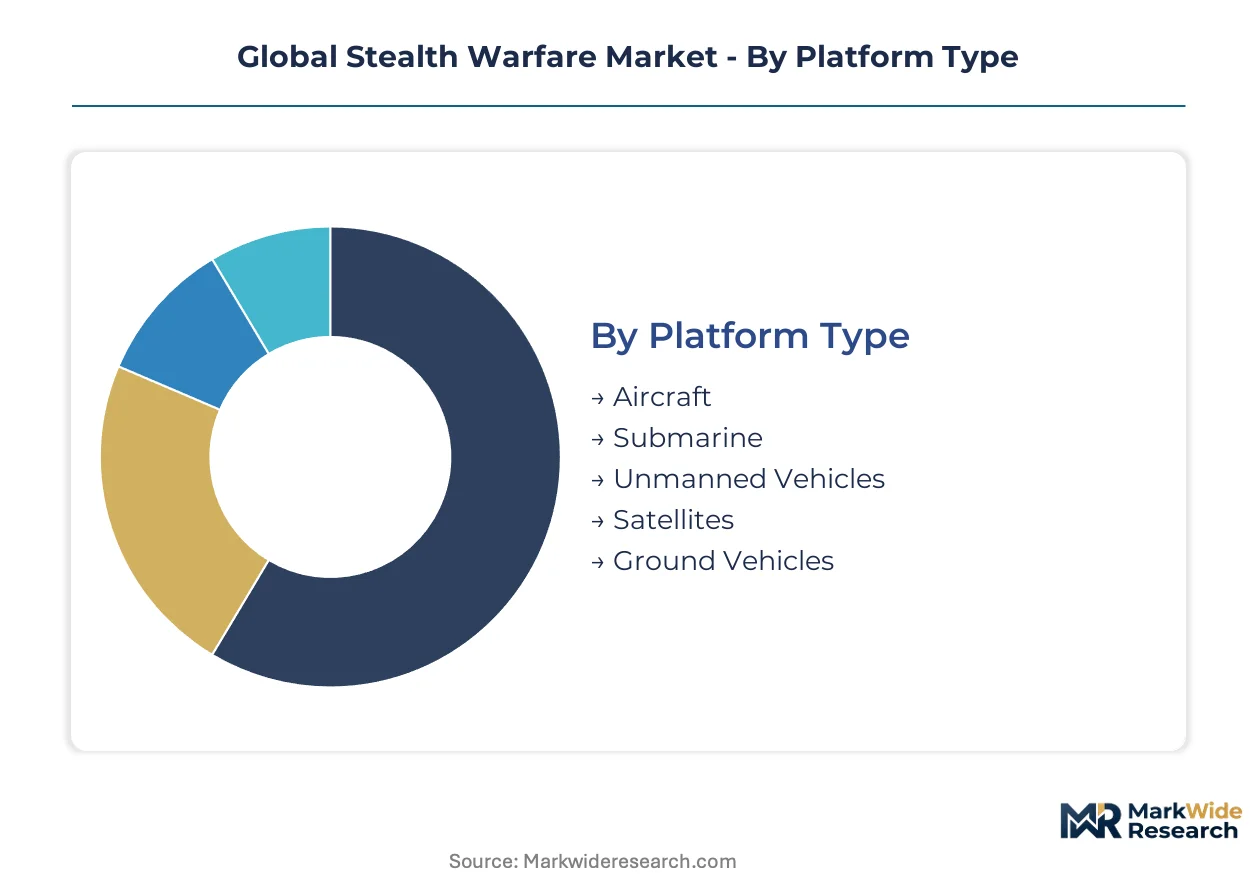
| Segmentation | Platform Type: Aircraft, Submarine, Unmanned Vehicles, Satellites, Ground Vehicles Technology: Radar Absorbing Material, Infrared Signature Reduction, Acoustic Dampening, Electromagnetic Interference, Camouflage Systems Application: Reconnaissance, Electronic Warfare, Target Acquisition, Suppression of Enemy Air Defenses, Signal Intelligence End User: Defense Forces, Intelligence Agencies, Defense Contractors, National Security Organizations |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems, Boeing, RTX Corporation, General Dynamics Corporation, Leonardo S.p.A, Thales Group, Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stealth Warfare Market Shifts & Advancements
Active signature management systems are displacing passive materials as the primary stealth mechanism, compressing development cycles and reshaping supplier relationships across classified defense programs.
Metamaterial antenna cloaks are integrating adaptive electromagnetic properties that respond to threat radar frequencies in real time. The U.S. Air Force Research Laboratory and China's CETC both pursue fieldable prototypes for 2030s platforms. This capability is integrating dynamic threat response into platform survivability architectures, reducing reliance on fixed geometry shaping.
EU Green Deal sustainability mandates are penetrating defense procurement criteria. REACH chemical restrictions and CSRD disclosure requirements now cover military supply chains, forcing reformulation of legacy radar-absorbent coatings. European cooperative programs including FCAS and Tempest are responding with bio-based binder research and closed-loop manufacturing commitments.
Defense ministries are consolidating subsystem procurement under prime contractor risk-bearing agreements. The United Kingdom's MoD and Australia's Defence Department now require single-point accountability for platform performance, displacing traditional component-level competitive bidding. This concentration is most visible in unmanned systems, where BAE Systems and Northrop Grumman negotiate total-system contracts spanning airframe, sensors, and signature management.
Global Stealth Warfare Market Segmentation
Stealth warfare procurement decisions diverge sharply across platform lifecycles, technology readiness levels, and operational doctrines. Defense ministries prioritize segments offering measurable survivability gains against quantified threat environments. Supplier positioning depends on matching technical capabilities to specific mission profiles rather than generic stealth performance claims.
Platform Type:
Manned versus unmanned requirements split procurement budgets between crew protection imperatives and expendable asset economics.
- Aircraft:Fifth-generation fighters and next-generation bombers integrate ferrite-based radar-absorbent coatings with planform alignment. The U.S. Department of Defense and China's PLAAF concentrate orders here, prioritizing survivable strike against integrated air defense networks.
- Unmanned Vehicles:Combat aerial vehicles and loyal wingman platforms reduce risk to human operators while enabling swarming tactics. The EU's European Defence Agency and China's SAMR both fund classified development pipelines, with autonomous coordination algorithms driving specification requirements.
- Submarine:Acoustic signature management through anechoic tile coatings and propulsor design dominates undersea stealth. The United Kingdom and Australia channel AUKUS agreement funding toward coordinated fleet modernization.
- Satellites:Low-observable bus designs and radar-transparent solar arrays minimize orbital detectability. Intelligence agencies in the United States and China prioritize signals intelligence platforms with reduced cross-section signatures.
- Ground Vehicles:Infrared suppression and radar-scattering geometry apply stealth principles to armored formations. Limited procurement volumes reflect tactical mobility trade-offs against signature reduction benefits.
Aircraft leads volumes today; unmanned vehicles are gaining share fastest.
Technology:
Material science complexity versus systems engineering integration determines supplier margin structures and qualification barriers.
- Radar Absorbing Material:Ferrite composites and metamaterial formulations achieve radar cross-section reductions below 0.001 square meters. Formulation complexity sustains premium pricing for qualified suppliers serving Lockheed Martin and Northrop Grumman production lines.
- Infrared Signature Reduction:Engine exhaust cooling, surface emissivity coatings, and plume suppressants counter thermal detection. The U.S. Department of Defense specifies these systems for rotorcraft and ground attack platforms operating in contested environments.
- Acoustic Dampening:Anechoic tiles and vibration isolation systems dominate submarine stealth architectures. The United Kingdom's Royal Navy and Australia's Royal Australian Navy coordinate AUKUS-funded retrofit programs for aging fleets.
- Electromagnetic Interference:Shielding and emission control reduce electronic detectability across platforms. Compliance with FAA and EASA airworthiness requirements intersects with military secrecy protocols for cross-border subsystem sales.
- Camouflage Systems:Adaptive visual and multispectral concealment applies stealth principles to ground forces. Maturity relative to other technologies limits procurement premiums despite operational relevance.
Radar absorbing material commands the steepest expansion trajectory; acoustic dampening remains comparatively mature.
Application:
Mission criticality and platform integration complexity shape technology selection and development timelines.
- Reconnaissance:Penetrating sensors and standoff collection platforms demand broadband signature reduction across radar, infrared, and visual spectra. The U.S. Air Force and China's PLAAF prioritize survivable intelligence-gathering against layered defenses.
- Electronic Warfare:Low-observable jamming platforms and escort aircraft require coordinated signature management with emitters active. The EU's European Defence Agency funds cooperative development through classified multinational programs.
- Target Acquisition:Designation systems operating within enemy weapon engagement zones need minimal detectability during extended loiter. Precision strike doctrines in the United States and China drive specification tightening.
- Suppression of Enemy Air Defenses:Destruction of integrated air defense nodes demands survivable penetration at tactical depths. NATO member states expand procurement of dedicated SEAD platforms with all-aspect stealth.
- Signal Intelligence:Passive collection platforms require electromagnetic silence and reduced intercept probability. Intelligence agencies in the United Kingdom and Australia coordinate Five Eyes technology sharing agreements.
Reconnaissance dominates current procurement volumes; electronic warfare applications are expanding most quickly.
End User:
Budget authority and classification requirements determine contract structures and technology access tiers.
- Defense Forces:Military services specify platform-level performance and absorb prime contractor risk through multi-year procurement. The U.S. Department of Defense, China's PLA, and the United Kingdom's MoD concentrate global demand.
- Intelligence Agencies:National technical means programs require specialized platforms with compartmentalized development. Budget opacity and security clearances limit supplier pools to pre-cleared contractors.
- Defense Contractors:Prime integrators subcontract subsystem development to qualified suppliers with ITAR or equivalent clearance. Lockheed Martin and Northrop Grumman anchor tiered supply chains through classified technology transfer.
- National Security Organizations:Border security and counter-terrorism units procure tactical stealth systems for specialized operations. Smaller contract values reflect limited operational scope relative to military services.
Defense forces lead volumes today; intelligence agencies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR channels state funding toward low-observable unmanned platforms while the United Kingdom's MoD consolidates procurement under prime contractor risk-bearing agreements. Sovereign defense budgets in both nations prioritize survivable strike assets over legacy platform upgrades.
United States
The U.S. Department of Defense prioritizes fifth-generation fighter and next-generation bomber programs in budget allocations. FAA airworthiness requirements intersect with military secrecy protocols, complicating cross-border subsystem sales. Lockheed Martin and Northrop Grumman anchor tiered supply chains through classified technology transfer in California and Maryland industrial clusters.
China
SAMR funds classified development pipelines for loyal wingman programs and autonomous swarming systems. Dual carbon goals and MEE emissions standards now penetrate defense procurement criteria. CETC pursues metamaterial antenna cloak prototypes in Beijing-Tianjin-Hebei cluster for 2030s platform integration.
United Kingdom
The MoD requires single-point accountability for platform performance under FCAS and Tempest cooperative programs. REACH chemical restrictions force reformulation of legacy radar-absorbent coatings. BAE Systems negotiates total-system contracts spanning airframe, sensors, and signature management from Lancashire and Bristol facilities.
India
DRDO advances domestic stealth fighter programs under the AMCA project with technology transfer partnerships. BIS standards and DGFT export licensing create dual-certification burdens for foreign subsystem suppliers. Development concentrates in Bangalore and Hyderabad defense corridors where foreign primes establish offset partnerships.
Australia
The Defence Department channels AUKUS agreement funding toward coordinated submarine fleet modernization with acoustic signature retrofits. TGA and Defence export control frameworks intersect with ITAR compliance complexity. Industrial activity clusters in South Australia and Western Australia around Osborne shipyard and Henderson precinct.
Global Stealth Warfare Market Competitive Landscape
United States producers anchor the prime contractor tier; European specialists hold cooperative program positions through technology-sharing agreements. The vendor base concentrates around classified development pipelines with limited qualified suppliers for radar-absorbent materials. Two strategic archetypes dominate: vertically integrated platform primes absorbing full system risk, and qualified subsystem suppliers with security clearances and ITAR compliance. Competitive moves center on multi-year sole-source contract capture and sovereign content mandate navigation.
Within the prime contractor tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify vertically integrated platform developers with long-term revenue visibility through classified production lines. BAE Systems occupies a position bridging transatlantic cooperative programs and European sovereign requirements. These three anchors represent the consolidation pattern where defense ministries concentrate procurement leverage under fewer, larger multi-year contracts.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| Boeing |
| RTX Corporation |
| General Dynamics Corporation |
| Leonardo S.p.A |
| Thales Group |
| Saab AB |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ITAR-cleared subsystem suppliers and commodity component vendors manifests in both pricing power and supply chain configuration. Prime contractors absorb full platform risk through sole-source contracts while qualified material suppliers command premium margins on ferrite-based radar-absorbent formulations.
Pricing Analysis
Capacity additions in Australia's defense industrial base are reshaping price floors for acoustic dampening retrofits under AUKUS funding channels. Three-tier pricing structure across ITAR-restricted, dual-use certified, and commercial-grade tiers reflects clearance complexity and sovereign content mandates. Cost compression in commercial-grade electromagnetic shielding intensifies as Chinese suppliers expand metamaterial production. Intelligence agencies exhibit lowest price sensitivity given compartmentalized procurement budgets and security-driven sole-source requirements.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing concentration for ferrite and neodymium inputs essential to radar-absorbent material production. Western manufacturers draw from Australian rare earth extraction, Japanese magnet fabrication, and domestic U.S. formulation capabilities. Tariff exposure on processed rare earth compounds threatens production schedules for qualified suppliers serving Lockheed Martin and Northrop Grumman. Distribution runs through prime contractor tiered supply chains with classified technology transfer protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in stealth warfare procurement rests on automation-driven cost reduction in radar-absorbent material fabrication and the shift toward total-system contracts bundling platform, sensors, and signature management.
For Market Incumbents: Hedge against rare earth supply disruption through backward integration into Australian extraction partnerships or long-term offtake agreements with Japanese processors. Absorb prime contractor risk-bearing obligations by consolidating subsystem procurement under single-point accountability contracts, displacing component-level competitive bidding that erodes margin visibility. For New Entrants and Emerging Players: Capture white-space in Indian AMCA subsystem partnerships where DRDO technology transfer creates entry points for foreign suppliers with BIS certification and DGFT licensing compliance. Target acoustic dampening modernization for aging UK and Australian submarine fleets under AUKUS coordination, leveraging lower ITAR exposure relative to airborne platform segments. For Investors and Strategic Acquirers: Consolidation pressure builds where qualified supplier pools with security clearances and ITAR compliance face specialized workforce scarcity across U.S., UK, and Australian defense industrial bases. Five-to-ten year viability favors acquisition of electromagnetic compatibility engineering specialists with existing prime contractor relationships. Monitor export control evolution as the inflection signal determining which technology tiers remain tradable versus sovereign-mandated domestic production.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Rare Earth Supply Agreement | Secures ferrite input streams against SAMR export licensing unpredictability for Western radar-absorbent material producers. |
| AI-Enabled Signature Management R&D Partnership | Converges adaptive metamaterials with machine learning algorithms for dynamic radar cross-section modulation on next-generation platforms. |
| Total-System Contract Negotiation | Consolidates airframe, sensor, and signature management procurement under single-point accountability demanded by UK MoD and Australian Defence Department. |
| Bio-based Binder Formulation Investment | Addresses REACH chemical restrictions and EU Green Deal sustainability mandates penetrating FCAS and Tempest cooperative programs. |
| Security Clearance Pipeline Expansion | Alleviates specialized workforce scarcity in electromagnetic compatibility engineering across U.S., UK, and Australian defense clusters. |
Research Methodology
Bottom-up defense ministry procurement modeling reconciled against top-down prime contractor production tracking forms the analytical core of this study. Primary interviews with platform program managers, radar-absorbent material formulation scientists, electromagnetic compatibility engineers, and defense procurement officers combined with secondary validation from FAA airworthiness filings, EDA cooperative program disclosures, SAMR patent registrations, and ITAR licensing databases. Triangulation across these sources ensures segmentation integrity across platform type, technology, application, and end user dimensions.
Input-output matrices mapping rare earth input flows to radar-absorbent material production volumes, then to platform integration rates, drive value forecasts across the analysis window. Segmentation dimensions modeled include manned versus unmanned platform architecture, material science versus systems engineering technology tiers, mission application criticality, and defense force versus intelligence agency end-user authority. CAGRs derive from platform lifecycle replacement schedules and technology readiness level progression curves specific to metamaterial and plasma shielding development pipelines.
Export control evolution, rare earth supply disruption, and plasma shielding technical maturation delays are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding sovereign content mandate trajectories and cross-border subsystem certification timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
NATO Defense Market
Military Equipment and Infrastructure
Military Test Equipment Market
Military Equipment and Infrastructure
CBRNE Defense Market
Military Equipment and Infrastructure
Global Remote Weapon Station Market
Military Equipment and Infrastructure
Europe Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Next Generation Military Power Supply Market
Military Equipment and Infrastructure
Deployable Military Shelters Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global Landing String Equipment Market
Military Equipment and Infrastructure
Military Image Intensifier Tube Market
Military Equipment and Infrastructure
Turret Handlers Market