
 Military Wearable Computers Market | 2026-2036
Military Wearable Computers Market Size, Share, and Industry Trends Forecast 2026-2036
Military Wearable Computers Market Analysis
A shift from sole-source to dual-source procurement for tactical displays is realigning vendor relationships across NATO defense ministries. BAE Systems leverages its UK manufacturing footprint to sustain long-term contracts with the British Army. Elbit Systems anchors Israeli defense exports through vertically integrated night-vision and display assembly. L3Harris Technologies competes on communication-integrated wearables, extending its radio franchise into soldier-worn computing nodes.
Military wearable computers comprise ruggedized computing platforms—typically MIL-STD-810H tested for shock, temperature, and electromagnetic interference—designed to deliver situational awareness, biometric monitoring, and networked communications to dismounted personnel. Head-mounted displays with augmented reality overlays dominate current procurement volumes, though sensor fusion architectures are capturing the fastest expansion as armies demand multi-spectral threat detection. Tactical vest systems concentrate margin pools where power management, thermal regulation, and data-backbone integration create high switching costs for defense buyers.
FDA clearance for battlefield health-monitoring algorithms and U.S. Army IVAS program requirements shape product specifications for vendors seeking Pentagon contracts. NATO STANAG standards and the U.S. MIL-STD-810H testing regime create compliance barriers that filter out commercial-grade suppliers. Stakeholders must monitor how export-control revisions under ITAR and emerging EU defense-funding mechanisms reshape addressable market boundaries for non-U.S. equipment providers.
Market Dynamics
The IVAS program's augmented-reality requirements are compressing development timelines across NATO defense ministries, forcing vendors to converge on common hardware architectures before proprietary differentiation matures.
Growth Catalysts
- Biometric monitoring mandates:FDA clearance pathways for battlefield health algorithms are accelerating Pentagon procurement specifications. Armed forces medical commands now require continuous physiological tracking for dismounted personnel.
- NATO STANAG 4694:Standardized power and data interfaces for soldier-worn equipment are reducing integration costs across member states' modernization programs.
- Multi-spectral sensor fusion:Threat detection requirements spanning thermal, night-vision, and electromagnetic spectra are driving demand for integrated computing platforms.
Market Restraints
- ITAR export controls:U.S. International Traffic in Arms Regulations restrict technology transfer to non-NATO partners, fragmenting addressable markets for component suppliers.
- GaN semiconductor supply:Gallium nitride substrate concentration in East Asian foundries creates vulnerability for radio-frequency power amplifiers in tactical wearables.
- Battery energy density limits:Lithium-ion cell chemistry constraints impose hard ceilings on mission duration for power-hungry head-mounted displays.
Strategic Opportunities
- EU defense funding mechanisms:The European Defence Fund's collaborative procurement windows are creating new entry points for non-U.S. system integrators.
- AI-enabled predictive maintenance:Machine-learning algorithms applied to component failure patterns can unbundle service contracts from hardware sales.
- Sweden and Poland:These NATO members maintain underpenetrated soldier modernization budgets relative to per-capita defense spending levels.
Industry Challenges
- MIL-STD-810H certification timelines:Environmental testing protocols for shock, temperature, and electromagnetic interference extend product development cycles.
- Embedded systems engineering talent:Scarcity of specialists capable of integrating real-time operating systems with military-grade security architectures constrains vendor scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Wearable Computers Market |
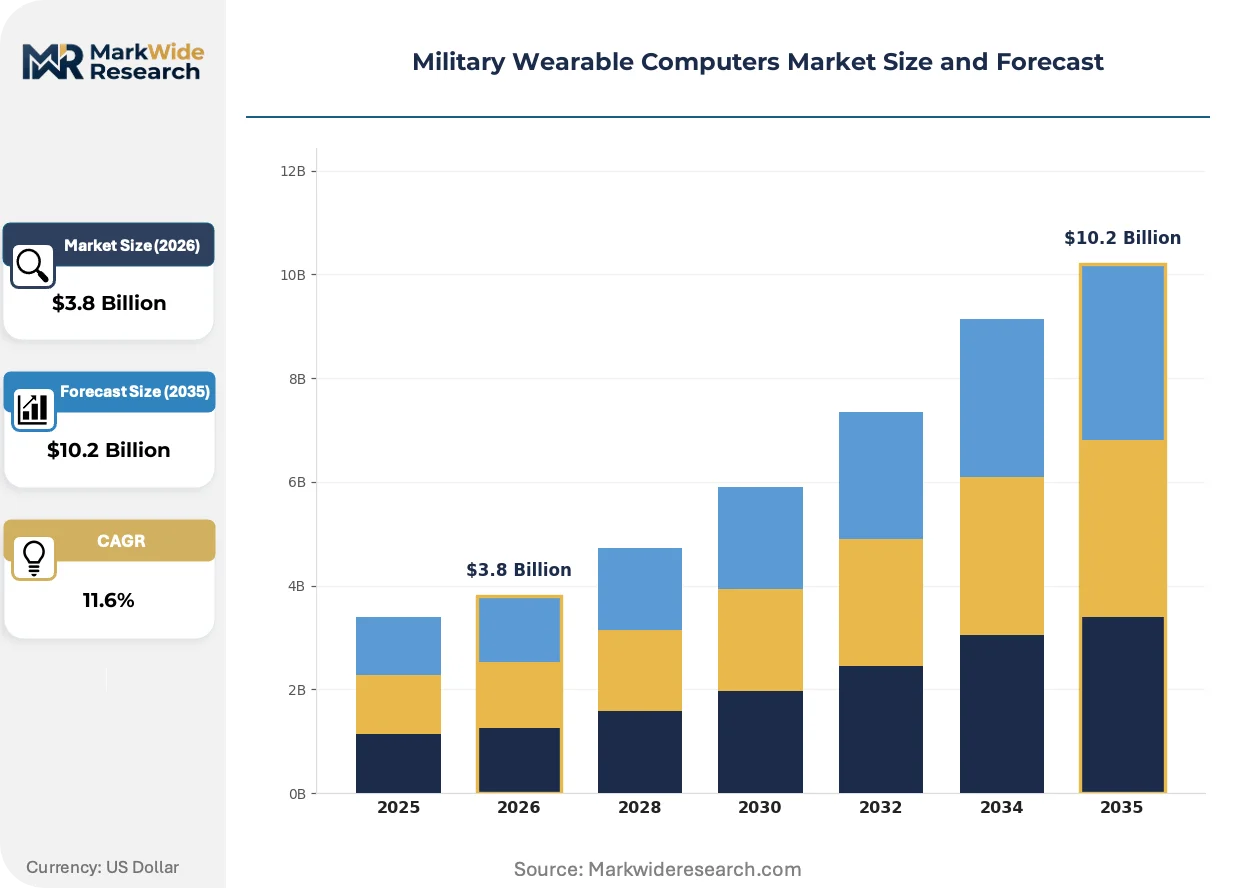
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-Mounted Displays, Smartwatches, Tactical Vest Systems, Handheld Devices Technology: Augmented Reality, Sensor Fusion, Advanced Graphics, Communication Systems End User: Armed Forces, Security Agencies, Defense Contractors, First Responders Application: Training Simulations, Battlefield Operations, Health Monitoring, Navigation Assistance |
| Companies Covered | General Dynamics Corporation, Elbit Systems, BAE Systems, Safran, Thales Group, L3Harris Technologies, Northrop Grumman Corporation, Curtiss-Wright Corporation, Lockheed Martin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Wearable Computers Market Emerging Trajectories
Edge computing architectures are redistributing processing load from centralized command nodes to individual soldiers, altering power budgets and thermal management requirements across tactical vest systems.
Mesh networking protocols are decentralizing communications reliance on fixed infrastructure. Special operations units in the United States and United Kingdom are field-testing self-healing radio networks that maintain connectivity when satellite links degrade. This topology is compressing the addressable market for traditional manpack radios.
The U.S. Army's IVAS program requirements are mandating specific display resolutions, field-of-view angles, and interoperability standards that cascade through NATO procurement specifications. European defense ministries are adapting national tender documents to align with these parameters, reducing design flexibility for regional suppliers.
Defense buyers are consolidating vendor relationships through multi-year framework agreements. The British Army's Land Systems Reference Architecture and similar U.S. Army programs are replacing transactional equipment purchases with integrated system-of-systems contracts. Israel and Australia display the most advanced adoption of this consolidated sourcing model.
Military Wearable Computers Market Segmentation
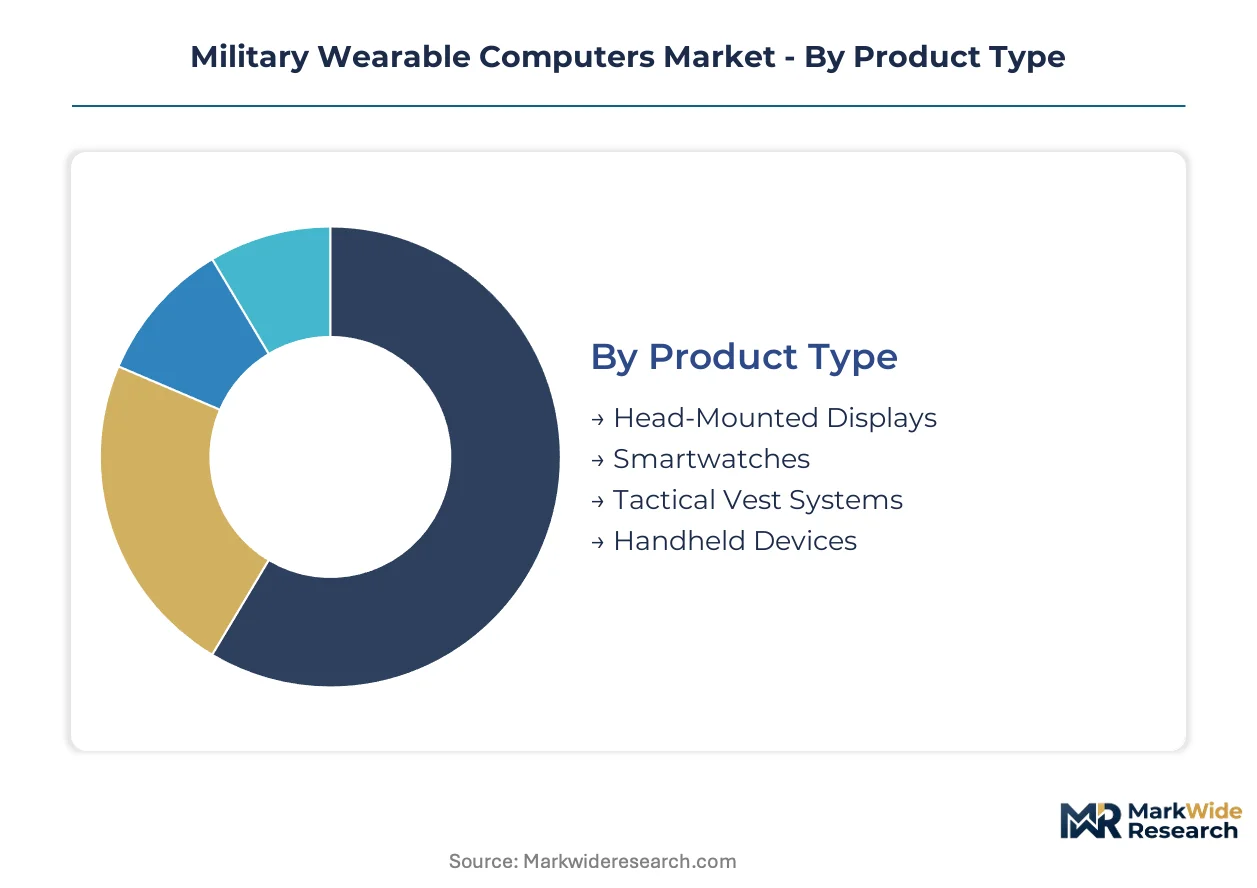
Military wearable computers segment across hardware form factors, enabling technologies, user categories, and mission applications. Procurement specifications from the U.S. Army IVAS program and NATO STANAG frameworks cascade through each dimension, compressing design flexibility for vendors.
Product Type:
Standardization pressures from NATO soldier modernization programs compress design variation across this hardware dimension, forcing vendors toward common mechanical and electrical interfaces.
- Head-Mounted Displays:Optical waveguide assemblies deliver augmented reality overlays with MIL-STD-810H shock certification. U.S. Army IVAS program requirements concentrate procurement volume, though battery energy density constraints limit mission duration for dismounted infantry.
- Tactical Vest Systems:Integrated power management, thermal regulation, and data-backbone architectures create high switching costs for defense buyers. British Army Land Systems Reference Architecture framework agreements favor multi-year contracts for vest-integrated computing nodes.
- Smartwatches:Continuous physiological monitoring platforms with FDA-cleared battlefield health algorithms.
- Handheld Devices:Ruggedized tablets and PDAs maintaining connectivity when head-mounted systems are impractical.
Most installed capacity flows through Head-Mounted Displays. Expansion is steepest in Tactical Vest Systems.
Technology:
Cost tiers separate mature communication architectures from emerging sensor fusion platforms requiring GaN semiconductor components.
- Sensor Fusion:Multi-spectral threat detection spanning thermal, night-vision, and electromagnetic spectra demands real-time processing at the tactical edge. Israeli defense exports anchor demand through vertically integrated night-vision assembly capabilities.
- Communication Systems:Mesh networking protocols decentralize reliance on fixed infrastructure, compressing the addressable market for traditional manpack radios. Special operations units in the United Kingdom field-test self-healing radio networks.
- Augmented Reality:Optical see-through displays with standardized field-of-view angles per IVAS specifications.
- Advanced Graphics:GPU-accelerated rendering for synthetic training environments and battlefield visualization.
Communication Systems retain the largest installed base. Sensor Fusion climbs the fastest as armies demand integrated threat detection.
End User:
Customer type determines certification requirements and procurement channel access, with armed forces commanding premium pricing for MIL-STD compliance.
- Armed Forces:Dismounted personnel programs in the United States, Israel, and the United Kingdom drive volume procurement with NATO STANAG 4694 power and data interface mandates. Pentagon medical commands now require continuous physiological tracking specifications.
- Defense Contractors:System integrators and subsystem suppliers serving prime contractors face ITAR export control fragmentation for non-NATO technology transfer.
- Security Agencies:Domestic intelligence and border protection units with reduced electromagnetic interference requirements.
- First Responders:Emergency services adopting militarized wearables for disaster response and tactical medical monitoring.
Armed Forces absorb the majority of production capacity. Defense Contractors show the steepest expansion trajectory as subsystem outsourcing accelerates.
Application:
Maturity curves separate established navigation and health monitoring from emerging synthetic training environments.
- Battlefield Operations:Real-time situational awareness and networked command-and-control for dismounted soldiers. IVAS program augmented-reality requirements compress development timelines across NATO defense ministries.
- Training Simulations:Synthetic environments replicate multi-spectral threat scenarios without live-fire exposure. Edge computing architectures redistribute processing load from centralized nodes to individual trainees.
- Health Monitoring:Biometric tracking with FDA clearance pathways for battlefield trauma prediction algorithms.
- Navigation Assistance:GPS-denied positioning through inertial measurement units and terrain-matching systems.
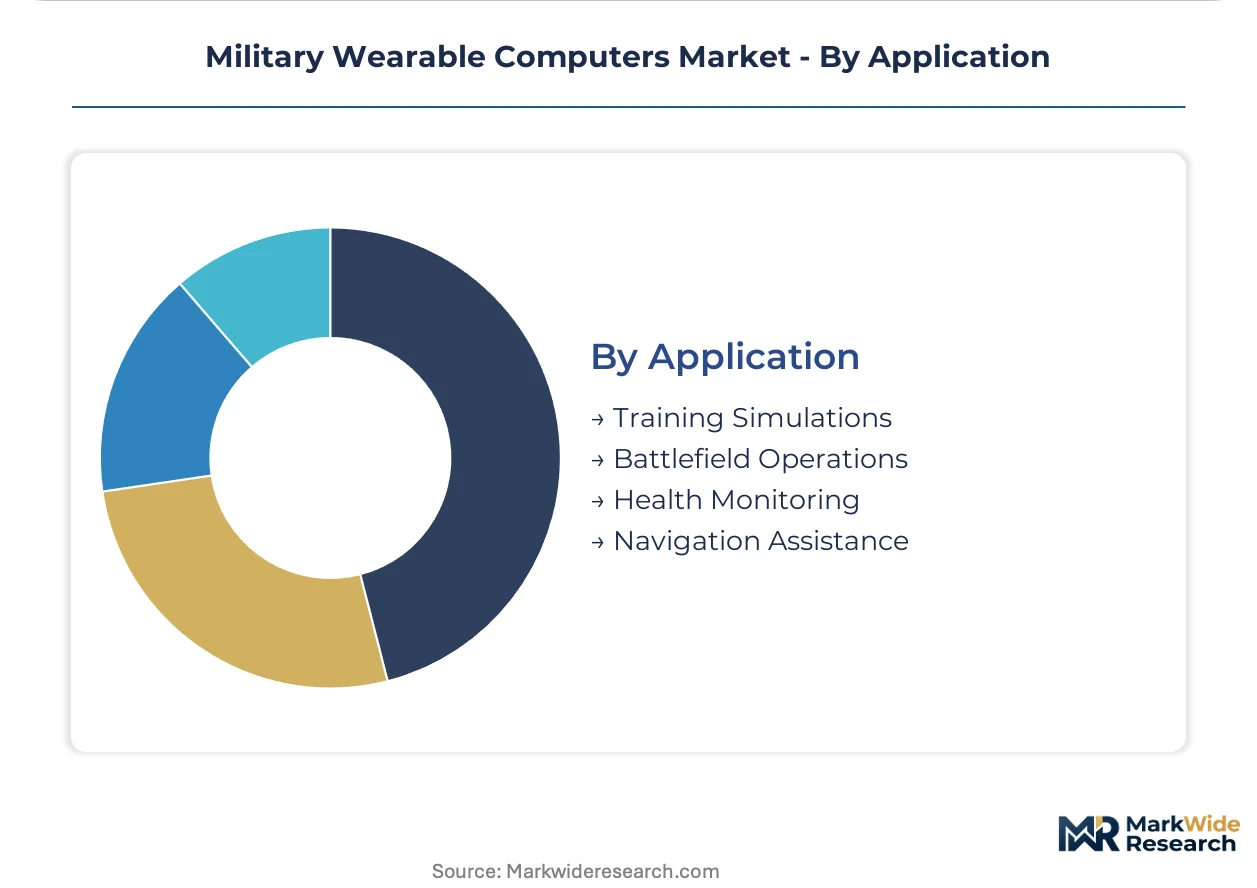
Battlefield Operations dominate current procurement. Training Simulations gain share fastest as synthetic environment fidelity improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Army's IVAS program in Aberdeen Proving Ground anchors procurement volume for head-mounted displays and tactical computing architectures. Defense ministries across NATO member states are adapting tender specifications to align with these technical parameters.
United States
Pentagon medical commands mandate continuous physiological tracking for dismounted personnel through FDA-cleared battlefield health algorithms. The U.S. Army's IVAS program compresses development timelines for augmented-reality display specifications. Huntsville's defense technology corridor concentrates prime contractor engineering facilities for soldier modernization systems.
United Kingdom
The British Army's Land Systems Reference Architecture favors multi-year framework agreements for integrated tactical vest systems. Ministry of Defence procurement guidelines align with NATO STANAG 4694 power and data interface standards. Bristol's aerospace and defense cluster houses BAE Systems manufacturing operations for ruggedized computing platforms.
Israel
Vertically integrated night-vision and display assembly capabilities drive Israeli defense export competitiveness in sensor fusion architectures. The country's national defense procurement authority prioritizes multi-spectral threat detection specifications for dismounted soldier programs. Haifa's defense technology corridor concentrates Elbit Systems research facilities for head-mounted display development.
Germany
Bundeswehr soldier modernization programs adopt NATO-standardized interfaces to reduce integration costs across member states. The Federal Office of Bundeswehr Equipment mandates MIL-STD-810H environmental testing certification for shock and electromagnetic interference. Bavaria's defense industrial base hosts subsystem suppliers for tactical radio and computing node integration.
Australia
The Australian Defence Force displays advanced adoption of consolidated sourcing models for system-of-systems soldier modernization contracts. Defence export control frameworks align with U.S. ITAR restrictions while permitting technology transfer within Five Eyes intelligence partnerships. Adelaide's defense technology precinct concentrates integration facilities for networked communications wearables.
Military Wearable Computers Market Vendor Landscape
Global majors compete with regional champions across defense procurement channels, with tiered concentration around prime contractors and specialized subsystem suppliers. Market structure favors long-term framework agreements over transactional equipment purchases, compressing vendor entry windows. Three archetypes dominate: vertically integrated defense primes, communication-technology extenders, and sensor-specialist exporters. Competitive moves concentrate on multi-year contract consolidation and backward integration into critical component supply.
Within the prime contractor tier, General Dynamics Corporation and Lockheed Martin exemplify scale-driven platform integration, while Elbit Systems anchors Israeli export competitiveness through captive night-vision supply chains. L3Harris Technologies occupies a position bridging radio franchise extension into soldier-worn computing nodes. These three entities represent distinct geographic and capability-based competitive positioning without overlapping core specializations.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| Elbit Systems |
| BAE Systems |
| Safran |
| Thales Group |
| L3Harris Technologies |
| Northrop Grumman Corporation |
| Curtiss-Wright Corporation |
| Lockheed Martin |
| Others |
Supply Flow & Price Mechanics
IVAS program augmented-reality specifications are compressing design flexibility for head-mounted display vendors, forcing supply chains toward GaN semiconductor substrates and optical waveguide assemblies that concentrate pricing power with East Asian foundries and specialized component suppliers.
Pricing Analysis
Input-cost pass-through from gallium nitride wafer shortages and lithium-ion cell chemistry constraints shapes contract negotiations for tactical vest systems. Three-tier pricing structure across MIL-STD-810H certified premium units, NATO STANAG-compliant standard configurations, and economy-grade commercial-off-the-shelf alternatives separates defense ministry procurement channels. Cost compression in sensor fusion architectures is intensifying because Israeli and Australian system integrators demand vertically integrated night-vision supply chains. First responder and security agency segments exhibit highest price sensitivity; armed forces medical commands show least sensitivity due to FDA clearance mandates for battlefield health algorithms.
Supply Chain Analysis
Freight cost volatility for ruggedized computing platforms shipped from Huntsville, Bristol, and Haifa defense corridors elevates landed cost variance for NATO procurement offices. Component supply draws from Taiwan and South Korea for radio-frequency power amplifiers, Israel for night-vision tube assemblies, and the United States for MIL-STD-810H testing certification. Single-source vulnerability concentrates in East Asian GaN substrate foundries serving tactical wearable amplifiers. Distribution runs through prime contractor integration facilities rather than open market channels, with British Army Land Systems Reference Architecture framework agreements locking in multi-year logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in tactical vest systems where power management and thermal regulation integration create switching-cost barriers, while FDA-cleared health monitoring algorithms command premium pricing tiers for Pentagon medical command contracts.
For Market Incumbents: Anchor long-term profitability through backward integration into optical waveguide manufacturing and captive GaN semiconductor sourcing. Elbit Systems' vertically integrated night-vision assembly demonstrates how in-house production of sensor fusion components defends against East Asian foundry concentration. Certification investment in FDA battlefield health pathways locks out commercial-grade competitors from Pentagon procurement specifications. For New Entrants and Emerging Players: Special operations units field-testing mesh networking protocols represent an underserved buyer archetype with compressed procurement cycles and reduced STANAG compliance requirements. Poland and Sweden maintain underpenetrated soldier modernization budgets relative to per-capita defense spending levels. Go-to-market positioning through EU Defence Fund collaborative procurement windows bypasses ITAR-controlled U.S. prime contractor channels. For Investors and Strategic Acquirers: Asymmetric upside sits with subsystem suppliers possessing embedded systems engineering capabilities for real-time operating system integration with military-grade security architectures. Five-to-ten year viability hinges on IVAS program specification cascades through NATO tender documents. Watch for European Defence Fund allocation announcements as inflection indicators for non-U.S. system integrator valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Semiconductors | Captive radio-frequency amplifier supply reduces exposure to East Asian foundry concentration for tactical wearable manufacturers. |
| FDA Clearance Pathway Investment | Battlefield health algorithm certification unlocks Pentagon medical command procurement specifications for biometric monitoring platforms. |
| EU Defence Fund Partnership | Collaborative procurement windows create entry points for non-U.S. system integrators excluded from ITAR-controlled channels. |
| Mesh Networking Protocol Development | Self-healing radio topologies displace traditional manpack radios in special operations units across United States and United Kingdom. |
| Multi-Year Framework Agreement Consolidation | British Army Land Systems Reference Architecture and similar programs replace transactional purchases with integrated system-of-systems contracts. |
Methodological Framework
Coverage spans United States, United Kingdom, Israel, Germany, and Australia, with primary inputs from each defense technology corridor. Program managers at Aberdeen Proving Ground, procurement officers at Ministry of Defence, and subsystem engineers at Haifa research facilities contributed operational data. Secondary validation drew from U.S. Army IVAS program disclosures, NATO STANAG documentation, FDA 510(k) clearance databases, and defense ministry tender archives. Bottom-up unit economics for head-mounted displays and tactical vest systems were triangulated against top-down defense budget appropriations.
Granularity-level modeling tracked hardware form factors, enabling technologies, user categories, and mission applications with country-specific procurement channel variations. Segment-level CAGRs were derived from IVAS program volume commitments, NATO interoperability mandate timelines, and export control regime shifts. Industry-specific inputs included GaN semiconductor supply forecasts, lithium-ion energy density improvement curves, and FDA algorithm clearance pipeline status.
Inputs from defense ministry procurement databases and prime contractor engineering disclosures were available through the study window; gaps in classified program budget allocations introduce uncertainty bands around special operations unit adoption trajectories. Forecasts reflect assumptions regarding NATO standardization timeline adherence and ITAR regime stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Europe Digital Battlefield Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global Remote Weapon Station Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
Rubber Tracks for Defense and Security Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
CBRNE Defense Market
Military Equipment and Infrastructure
CBRN Protection Equipment Market
Military Equipment and Infrastructure
Global CBRN Defense Market
Military Equipment and Infrastructure
NATO Defense Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Europe Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
FLIR and Laser Designator Targeting Pods Market
Military Equipment and Infrastructure
Global Stealth Warfare Market
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market