
 Man Portable Military Electronics Market | 2026-2036
Man Portable Military Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Man Portable Military Electronics Market Analysis
Special operations forces is collapsing the traditional infantry-centric procurement model for man portable military electronics. L3Harris Technologies leverages its software-defined radio portfolio to anchor U.S. special operations communications modernization. Elbit Systems competes through integrated soldier systems that extend battlefield awareness for Israeli and NATO special mission units. Thales Group dominates European dismounted soldier programs with its Felin and connected soldier architectures.
Man portable military electronics encompass battery-powered, body-worn systems designed to operate across -40°C to +71°C temperature ranges while weighing under 15 kilograms per soldier load. These devices integrate RF transceivers, GPS receivers, and tactical data links to enable real-time situational awareness, target designation, and secure voice or data transmission in contested electromagnetic environments. Communication Equipment leads product type revenue as legacy radio replacement cycles accelerate across NATO forces, while Navigation Systems represents the fastest-growing category driven by anti-jam GPS and alternative positioning investments. Weapon Systems concentrates margin pools through fire-control computer and smart-sight integration that commands premium pricing per unit.
The U.S. Department of Defense, NATO Standardization Office, and the U.K. Ministry of Defence shape demand through software-defined radio interoperability mandates, electromagnetic spectrum management directives, and soldier modernization budget allocations. These frameworks force vendors toward modular open systems architectures and common data link standards that reduce vendor lock-in while raising certification barriers for new entrants. Stakeholders must monitor evolving electronic warfare threats that could render current GPS and RF-dependent portfolios obsolete before planned replacement cycles conclude.
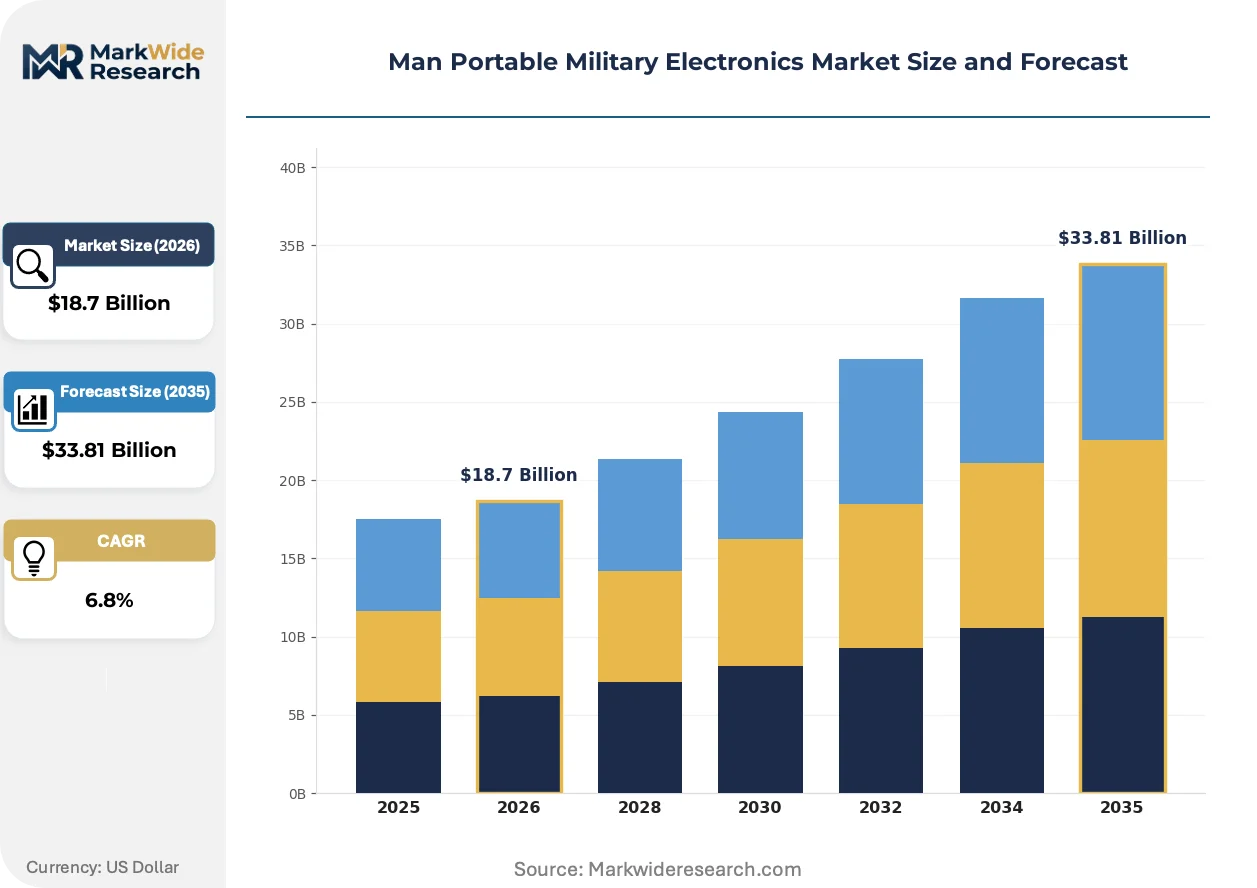
Market Dynamics
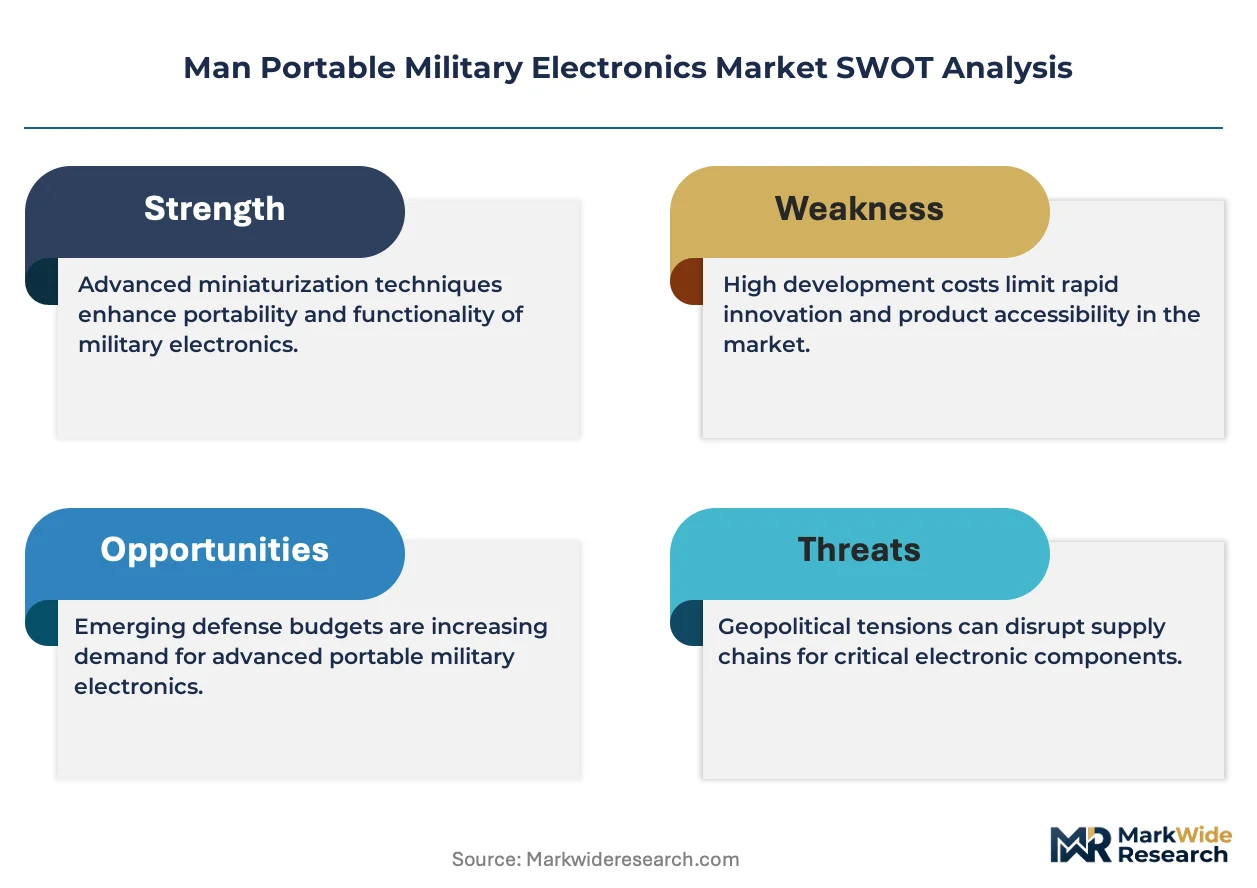
Software-defined radio mandates from the U.S. Department of Defense are forcing NATO-aligned procurement toward modular open systems architectures that eliminate vendor lock-in while raising certification barriers for new entrants.
Growth Catalysts
- Counter-insurgency readiness programs:Special operations forces across the United States, United Kingdom, and Israel are accelerating dismounted soldier modernization budgets. These units demand networked battlefield awareness systems that integrate RF transceivers with tactical data links.
- REACH electromagnetic compatibility standards:European defense procurement now mandates interoperable soldier electronics that operate across contested spectrum environments. This regulatory pressure expands addressable demand for certified navigation and communication equipment.
- Anti-jam GPS investments:Alternative positioning technologies are capturing procurement share as electronic warfare threats render legacy satellite-dependent systems vulnerable. Navigation systems now represent the fastest-expanding product category.
Market Restraints
- Lithium-ion battery supply concentration:Critical cell production clusters in East Asia create single-source vulnerability for man portable systems requiring sub-15 kilogram soldier loads. Temperature-rated power modules face extended lead times.
- GaN semiconductor fabrication bottlenecks:Gallium nitride foundry capacity limits RF amplifier output for software-defined radios. Defense-qualified wafer starts remain constrained against procurement timelines.
- ITAR classification friction:U.S. State Department export controls restrict technology transfer to allied special operations units. Cross-border program collaboration incurs 12-18 month licensing delays.
Strategic Opportunities
- Urban warfare sensor fusion:Israeli and NATO special mission units are piloting integrated soldier systems that combine thermal imaging with acoustic gunshot detection. These programs command premium pricing per unit.
- U.K. Ministry of Defence Network Enabled Capability:British soldier modernization frameworks mandate open architecture data links that reduce proprietary subsystem integration costs. Vendors certifying to these standards gain preferred supplier status.
- AI-enabled electronic warfare countermeasures:Machine learning algorithms for real-time spectrum sensing are converging with software-defined radio platforms. This technology pairing enables adaptive frequency hopping in jamming environments.
Industry Challenges
- Embedded systems security clearance pipeline:Firmware engineers with TS/SCI clearances remain scarce against program delivery schedules. Talent competition from commercial cybersecurity sectors extends hiring cycles.
- MIL-STD-810H environmental qualification timelines:Temperature cycling validation from -40°C to +71°C requires 8-14 months for new product introductions. Accelerated testing protocols risk field failure exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Man Portable Military Electronics Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Communication Equipment, Surveillance Devices, Navigation Systems, Weapon Systems Technology: GPS, RF, Electromagnetic, Data Link End User: Military, Defense Contractors, Law Enforcement, Emergency Services Application: Reconnaissance, Tactical Communication, Battlefield Management, Training |
| Companies Covered | Raytheon Technologies, Northrop Grumman, Thales Group, General Dynamics, BAE Systems, L3Harris Technologies, Leonardo S.p.A., Elbit Systems, Lockheed Martin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Man Portable Military Electronics Market Emerging Trajectories
Battlefield electronics are bifurcating between legacy hardware-dependent systems and software-reconfigurable platforms that enable rapid threat adaptation without physical replacement cycles.
Software-defined radio architectures are bifurcating procurement strategies across NATO forces. Special operations commands in the United States and United Kingdom now prioritize firmware-upgradable transceivers over fixed-frequency hardware. This shift compresses traditional 7-10 year radio replacement cycles into continuous capability refresh through over-the-air updates.
EU electromagnetic spectrum management directives are mandating cognitive radio capabilities for all new dismounted soldier programs. The European Standardization Office frameworks require dynamic spectrum access that senses and avoids interference in real-time. French and German land forces are responding with accelerated procurement of cognitive engine modules that overlay existing hardware platforms.
Consolidated program management offices are displacing service-specific acquisition channels for soldier electronics. The U.S. Army's Program Executive Office Soldier now centralizes funding decisions previously fragmented across infantry, armor, and aviation branches. This concentration is most visible in networked target designation systems where cross-domain interoperability requirements override legacy stovepipe procurement.
Man Portable Military Electronics Market Segmentation
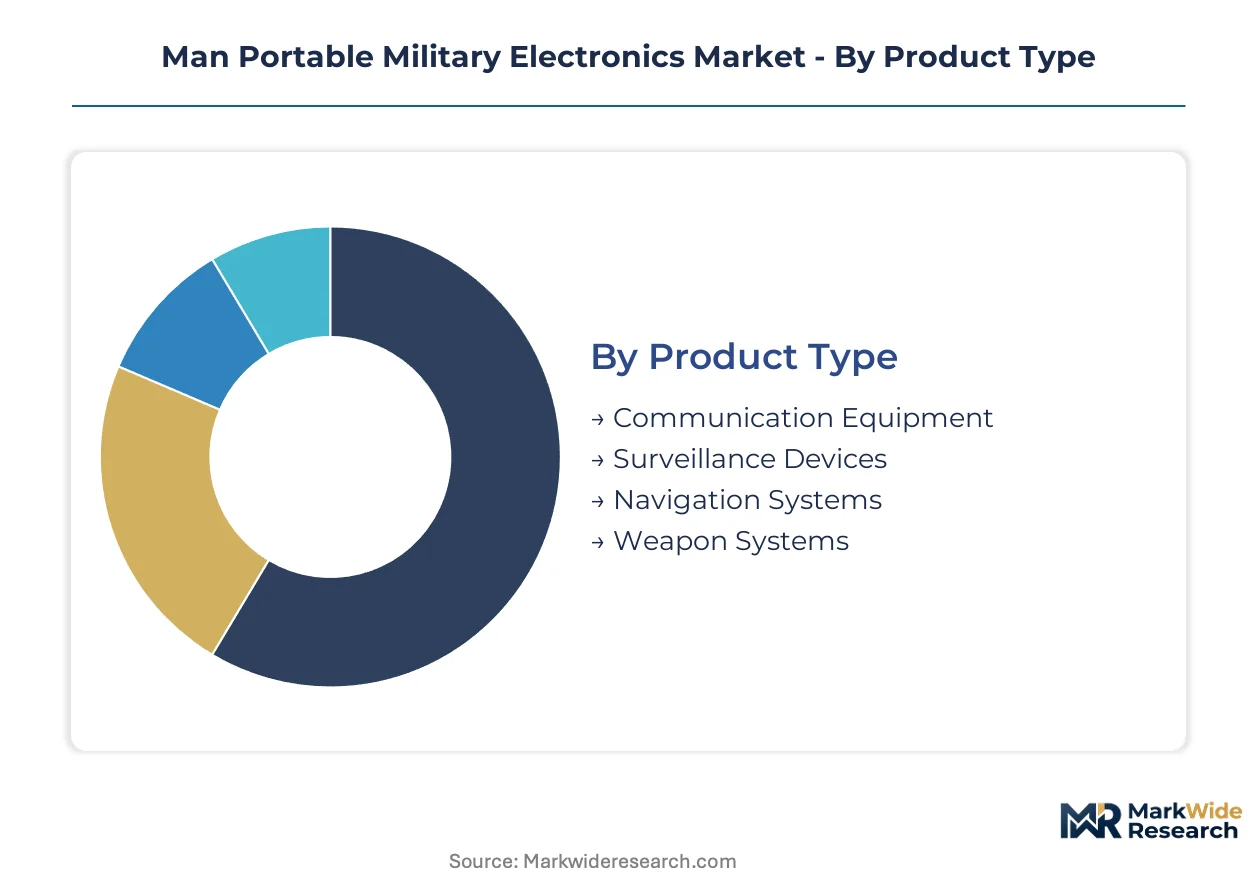
Segmentation in man portable military electronics reveals where procurement budgets concentrate and which technologies face displacement risk from emerging alternatives. Understanding these fault lines enables vendors to align R&D investment with actual program funding trajectories rather than assumed uniform demand.
Product Type:
Communication Equipment faces the most acute substitution pressure as software-defined radio architectures displace fixed-frequency hardware across NATO procurement cycles.
- Communication Equipment:RF transceivers and tactical radios form the revenue foundation, with legacy system replacement cycles accelerating across U.S. and European land forces. Special operations commands prioritize firmware-upgradable platforms that compress traditional hardware refresh timelines through over-the-air capability updates.
- Navigation Systems:GPS receivers and alternative positioning modules integrate anti-jam processing for contested electromagnetic environments. Israeli and U.S. special mission units drive procurement as electronic warfare threats render satellite-dependent systems operationally vulnerable.
- Surveillance Devices:Body-worn sensors and thermal imagers extend battlefield awareness for dismounted soldiers.
- Weapon Systems:Fire-control computers and smart-sight modules command premium unit pricing through precision targeting integration.
Communication Equipment anchors the volume base while Navigation Systems gains share at the steepest rate.
Technology:
Cost tier stratification separates proven GPS and RF implementations from emerging electromagnetic and data link investments requiring higher certification expenditure.
- RF:Radio frequency platforms dominate current procurement volumes, with gallium nitride amplifiers enabling software-defined radio performance in reduced form factors. Foundry capacity constraints limit defense-qualified wafer availability against procurement timelines.
- Data Link:Tactical networking modules enable real-time situational awareness across distributed soldier formations. U.K. Ministry of Defence Network Enabled Capability mandates accelerate open architecture certification for preferred supplier status.
- GPS:Satellite-dependent positioning remains embedded across navigation portfolios despite jamming vulnerability.
- Electromagnetic:Spectrum sensing and electronic warfare countermeasure technologies converge with cognitive radio capabilities.
RF commands the installed base while Data Link expands most quickly through networked soldier program mandates.
End User:
Customer type segmentation tracks procurement authority concentration, with military program offices consolidating funding decisions previously fragmented across service branches.
- Military:National defense forces represent the dominant procurement channel, with U.S. Army Program Executive Office Soldier centralizing acquisition authority for dismounted soldier electronics. Budget concentration enables cross-domain interoperability requirements that override legacy stovepipe procurement.
- Defense Contractors:System integrators and prime contractors absorb subcontracted component volumes for platform integration programs.
- Law Enforcement:Tactical units adopt militarized communication and surveillance equipment for counter-terror operations.
- Emergency Services:Disaster response agencies procure ruggedized navigation and communication systems for austere environment deployment.
Military end users dominate current procurement while Defense Contractors capture expanding subsystem integration value.
Application:
Maturity differentiation separates established reconnaissance and tactical communication deployments from emerging battlefield management system investments.
- Tactical Communication:Secure voice and data transmission systems anchor operational requirements for dismounted soldier modernization. NATO software-defined radio interoperability mandates force modular open systems architectures that eliminate vendor lock-in.
- Battlefield Management:Networked target designation and command-and-control platforms integrate sensor feeds with fire support coordination. Urban warfare sensor fusion pilots combine thermal imaging with acoustic gunshot detection for Israeli and NATO special mission units.
- Reconnaissance:Intelligence collection applications drive surveillance device procurement for forward-deployed elements.
- Training:Simulation and force-on-force exercise systems replicate operational electronics for skill development.
Tactical Communication maintains the largest installed base while Battlefield Management climbs the fastest through networked soldier program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli defense electronics flow primarily to NATO special operations commands and Indo-Pacific allied forces, establishing the dominant trade corridor for man portable military systems.
United States
U.S. Army Program Executive Office Soldier centralizes procurement authority for dismounted soldier modernization, consolidating budgets previously fragmented across service branches. Software-defined radio interoperability mandates from the Department of Defense force modular open systems architectures that eliminate vendor lock-in. Defense contractors in Massachusetts and Virginia anchor software-defined radio development for special operations communications.
United Kingdom
British special operations forces drive networked soldier program investments through counter-insurgency readiness frameworks. Ministry of Defence Network Enabled Capability mandates require open architecture data links that reduce proprietary subsystem integration costs. Industrial activity concentrates in Hampshire and the Midlands, where system integrators certify to preferred supplier standards.
Israel
Israeli special mission units pilot integrated soldier systems combining thermal imaging with acoustic gunshot detection for urban warfare applications. National procurement frameworks prioritize battlefield awareness systems that extend operational reach for counter-terror operations. Defense electronics clusters in Haifa and the Tel Aviv metropolitan area specialize in soldier system integration for export markets.
Germany
German land forces accelerate cognitive radio procurement under EU electromagnetic spectrum management directives requiring dynamic spectrum access. REACH electromagnetic compatibility standards mandate interoperable soldier electronics for contested spectrum environments. Bavaria-based defense contractors lead certification efforts for NATO-aligned dismounted soldier programs.
France
French defense procurement directs funding toward connected soldier architectures that replace legacy Felin system components with software-reconfigurable platforms. European Standardization Office frameworks require real-time interference sensing capabilities for new dismounted soldier electronics. The Paris-Saclay defense technology cluster hosts prime contractors developing cognitive engine modules for overlay deployment.
Man Portable Military Electronics Market Vendor Landscape
Player mix skews toward vertically integrated defense primes with established special operations relationships. Market structure concentrates around five to seven dominant system integrators controlling soldier modernization program awards. Two strategic archetypes prevail: software-defined radio specialists leveraging firmware-upgradable platforms, and integrated soldier system providers bundling sensor fusion with communications. Competitive moves center on modular open systems certification and cross-border program collaboration despite ITAR friction.
Among U.S.-based defense primes, Raytheon Technologies, Northrop Grumman, and General Dynamics occupy positions spanning communications hardware and integrated battlefield management systems. L3Harris Technologies exemplifies the software-defined radio archetype through its firmware-upgradable transceiver portfolio. Thales Group and BAE Systems represent European system integrators competing for NATO soldier modernization mandates. Elbit Systems anchors the Israeli defense electronics cluster, while Leonardo S.p.A. and Lockheed Martin sit within the tier of full-spectrum defense contractors pursuing dismounted soldier program awards across multiple geographies.
| Leading Market Players |
|---|
| Raytheon Technologies |
| Northrop Grumman |
| Thales Group |
| General Dynamics |
| BAE Systems |
| L3Harris Technologies |
| Leonardo S.p.A. |
| Elbit Systems |
| Lockheed Martin |
| Others |
Supply Flow & Price Mechanics
MIL-STD-810H environmental qualification requirements simultaneously gate supplier entry and stratify unit economics across certified and uncertified product tiers. Defense program offices award sole-source positions to vendors bearing full temperature-cycling validation costs from -40°C to +71°C, while commercial-grade alternatives face exclusion from soldier modernization budgets.
Pricing Analysis
Next-generation software-defined radio platforms command substantial premiums over legacy fixed-frequency hardware and prior-generation firmware-limited systems. Contract-based long-term offtake arrangements dominate procurement, with price differentiation resting on certification level and volume scale. Cost compression in standard-tier communication equipment is intensifying because gallium nitride foundry bottlenecks limit defense-qualified amplifier supply. Special operations forces demonstrate the least price sensitivity due to mission-critical interoperability mandates, while law enforcement tactical units face budget constraints that favor economy-tier configurations.
Supply Chain Analysis
Extended lead times for temperature-rated lithium-ion power modules and GaN RF amplifiers signal inventory stress across prime contractor networks. Critical cell production clusters in China, South Korea, and Japan create single-source vulnerability for sub-15 kilogram soldier loads. The supply chain draws from gallium nitride wafers, rare earth magnetics, and ITAR-controlled encryption chipsets. Tariff exposure on East Asian battery components threatens margin stability. Distribution runs through defense prime contractors integrating subsystems for program executive offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-moat business where ITAR classification and MIL-STD certification create switching costs that lock out unqualified competitors. Network effects consolidate around software-defined radio interoperability standards that privilege incumbents with existing NATO relationships.
For Market Incumbents: Secure gallium nitride foundry allocation through long-term supply agreements before procurement timelines collide with wafer-start constraints. Deepen backward integration into temperature-rated battery module production to offset East Asian supply concentration. The priority defensive move centers on accelerating cognitive radio firmware development before European electromagnetic spectrum mandates render legacy hardware obsolete. For New Entrants and Emerging Players: Post-contract aftermarket support and firmware update services represent underserved white space where primes prioritize new system sales. Emergency services procurement channels offer the most penetrable entry path, as disaster response agencies adopt militarized navigation and communication systems without full defense certification requirements. A direct-to-agency sales model bypassing prime contractor integration layers accelerates initial reference accounts. For Investors and Strategic Acquirers: U.S. Department of Defense software-defined radio mandate deadlines reshape the acquisition landscape toward firmware-upgradable platform specialists. Long-term viability over the coming decade favors vertically integrated system integrators with captive GaN amplifier supply and cleared engineering pipelines. The acquisition target archetype combines software-defined radio intellectual property with existing special operations relationships. Watch for European REACH electromagnetic compatibility standard enforcement as the inflection signal that triggers consolidation among uncertified component vendors.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Capacity Reservation | Defense-qualified wafer starts from WIN Semiconductors or Qorvo anchor RF amplifier output for NATO software-defined radio programs. |
| Cognitive Radio Firmware Development | Machine learning spectrum-sensing algorithms enable dynamic frequency hopping under EU electromagnetic spectrum management directives. |
| ITAR Compliance Infrastructure Investment | TS/SCI-cleared engineering pipelines reduce 12-18 month licensing delays for cross-border special operations collaboration. |
| Temperature-Rated Battery Backward Integration | In-house lithium-ion module production mitigates East Asian supply concentration for -40°C operational requirements. |
| Open Architecture Certification | U.K. Ministry of Defence Network Enabled Capability compliance unlocks preferred supplier status for British soldier modernization. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with U.S. Army Program Executive Office Soldier procurement officers, Israeli special mission unit equipment officers, defense prime contractor subsystem engineers, and GaN foundry operations managers. Secondary validation drew from Department of Defense budget justification documents, NATO Standardization Office interoperability frameworks, U.S. State Department ITAR licensing statistics, and SEC 10-K filings from listed defense contractors. Bottom-up unit shipment estimates triangulated against top-down program budget allocations across the analysis window.
Across the projection horizon, the analytical framework modeled demand by product type, technology generation, end-user category, and application mission profile. CAGRs were derived from program budget trajectory analysis and replacement cycle compression factors. Forecast inputs incorporated software-defined radio mandate compliance timelines, special operations force modernization priorities, and electronic warfare threat evolution patterns.
Forecasts assume regulatory continuity in U.S. ITAR classification regimes and EU REACH electromagnetic compatibility standards; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Military Displays Market
Military Equipment and Infrastructure
Air-Based Remote Weapon Stations Market
Military Equipment and Infrastructure
Military Tent and Shelter Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Wearable Computers Market
Military Equipment and Infrastructure
Military Optoelectronic System Market
Military Equipment and Infrastructure
CBRN Protection Equipment Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
Rocket Solid Propulsion Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
Military Image Intensifier Tube Market
Military Equipment and Infrastructure
Military Test Equipment Market
Military Equipment and Infrastructure
Howitzer Artillery System Market
Military Equipment and Infrastructure
Manpack Military Antennas Market