
 Used Serviceable Material (USM) Market | 2026-2036
Used Serviceable Material (USM) Market Size, Share, and Industry Trends Forecast 2026-2036
Used Serviceable Material (USM) Market Analytics
Aftermarket component refurbishment is reshaping margin distribution across the aviation value chain. GA Telesis leverages its global teardown network to capture feedstock for certified USM redistribution. AAR Corp anchors its position through vertical integration from aircraft disassembly to parts certification. HEICO Corporation differentiates via specialized PMA-USM hybrid offerings that compete with OEM new-part pricing.
Used Serviceable Material denotes airframe and engine components removed from retired aircraft, inspected to OEM or FAA/EASA equivalent standards, and reintroduced into operational fleets with full traceability documentation. These materials undergo non-destructive testing, dimensional restoration, and coating reapplication to meet specified flight cycles or hours limits. The aerospace application segment dominates value generation as narrowbody fleet renewals expand teardown volumes. The refurbished condition category leads procurement volumes among MRO buyers seeking documented service history. The metals material type sustains the largest share given titanium and aluminum alloy recovery from engine and landing gear assemblies.
FAA airworthiness directives and EASA Part 145 certification requirements govern USM eligibility, traceability, and installation rights across regulated fleets. The EPA oversees hazardous material handling in teardown operations, while the EU Green Deal circular economy framework shapes cross-border material flows and recycling quotas. Stakeholders must monitor evolving regulator alignment between FAA and EASA on USM documentation standards to anticipate market access shifts.
Market Dynamics
Fleet retirement waves from pandemic-era storage are flooding teardown channels with narrowbody feedstock, compressing USM pricing cycles and forcing redistribution networks to absorb unprecedented component volumes.
Growth Catalysts
- EASA Circular Economy Mandates:The EU Green Deal framework imposes material recovery quotas on aerospace OEMs, compelling certified USM sourcing for maintenance compliance.
- Titanium Alloy Recovery:Advanced non-destructive testing protocols now validate engine and landing gear components for second-life deployment without full metallurgical rework.
- India:DGFT import duty restructuring on aircraft spares is redirecting regional MRO procurement toward documented USM channels.
Market Restraints
- Feedstock Concentration Risk:Seventy percent of teardown-suitable airframes originate from lessors domiciled in Ireland and Singapore, creating supply chokepoints.
- FAA-EASA Documentation Misalignment:Divergent traceability standards between regulators block cross-certification of USM inventories, fragmenting resale liquidity.
- 3D-Printed Spare Substitution:OEM additive manufacturing programs for obsolescent part numbers are eroding addressable market for legacy USM categories.
Strategic Opportunities
- Indonesia:Underdeveloped domestic MRO infrastructure and expanding Lion Air Group fleet create first-mover advantage for USM distribution partnerships.
- Blockchain Traceability Convergence:Distributed ledger integration with existing ERP systems is enabling real-time component pedigree verification for leasing companies.
- CSRD Scope 3 Reporting:Mandatory EU emissions disclosure is elevating USM procurement as a measurable Scope 3 reduction lever for airline sustainability officers.
Industry Challenges
- NDT Technician Scarcity:Certified inspectors for eddy current and ultrasonic testing command premium wages, constraining teardown throughput expansion.
- Legacy Documentation Gaps:Pre-digital-era maintenance records from 1990s-vintage aircraft lack structured data formats, delaying USM eligibility determination.
- Airworthiness Directive Backlogs:FAA and EASA harmonization delays on USM installation rights create fleet-specific grounding risks for mixed-new-used maintenance programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used Serviceable Material (USM) Market |
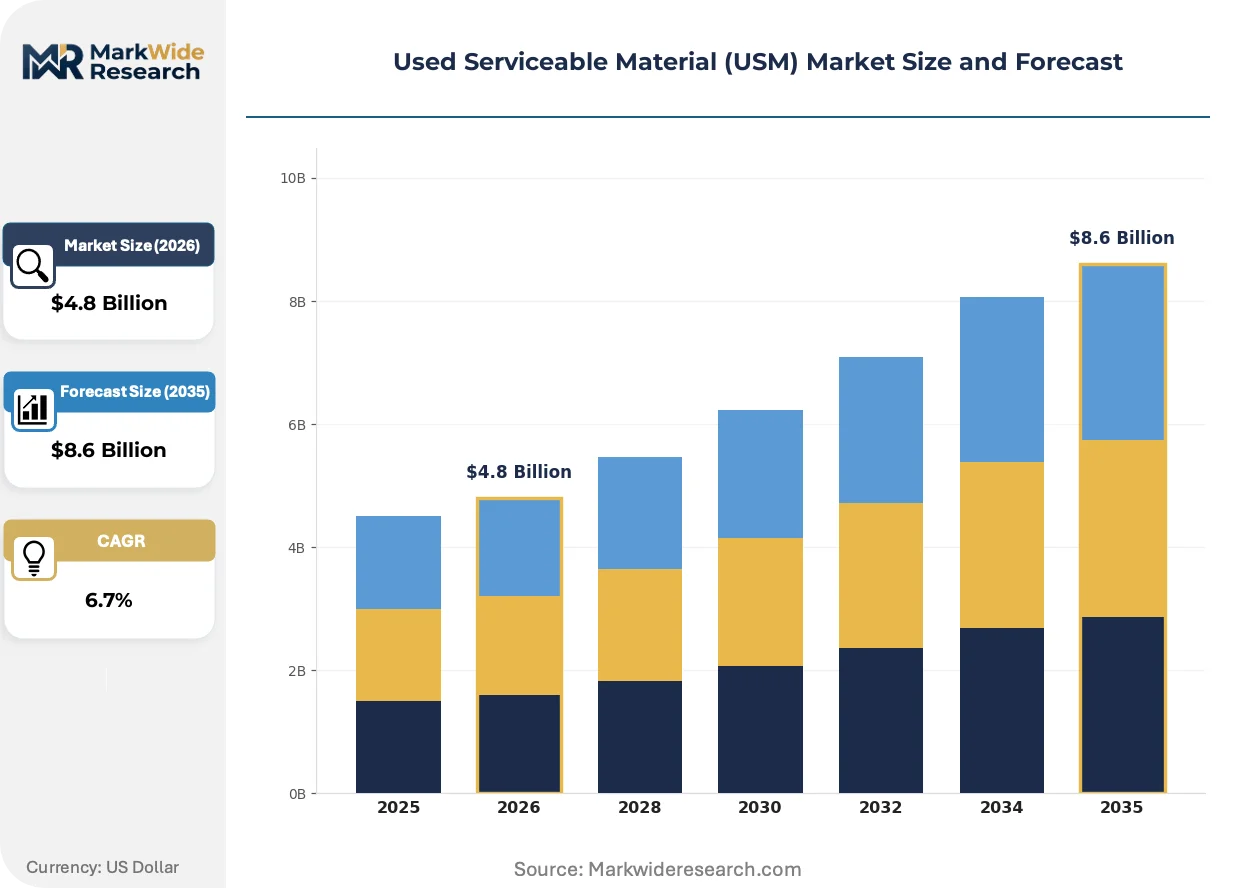
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
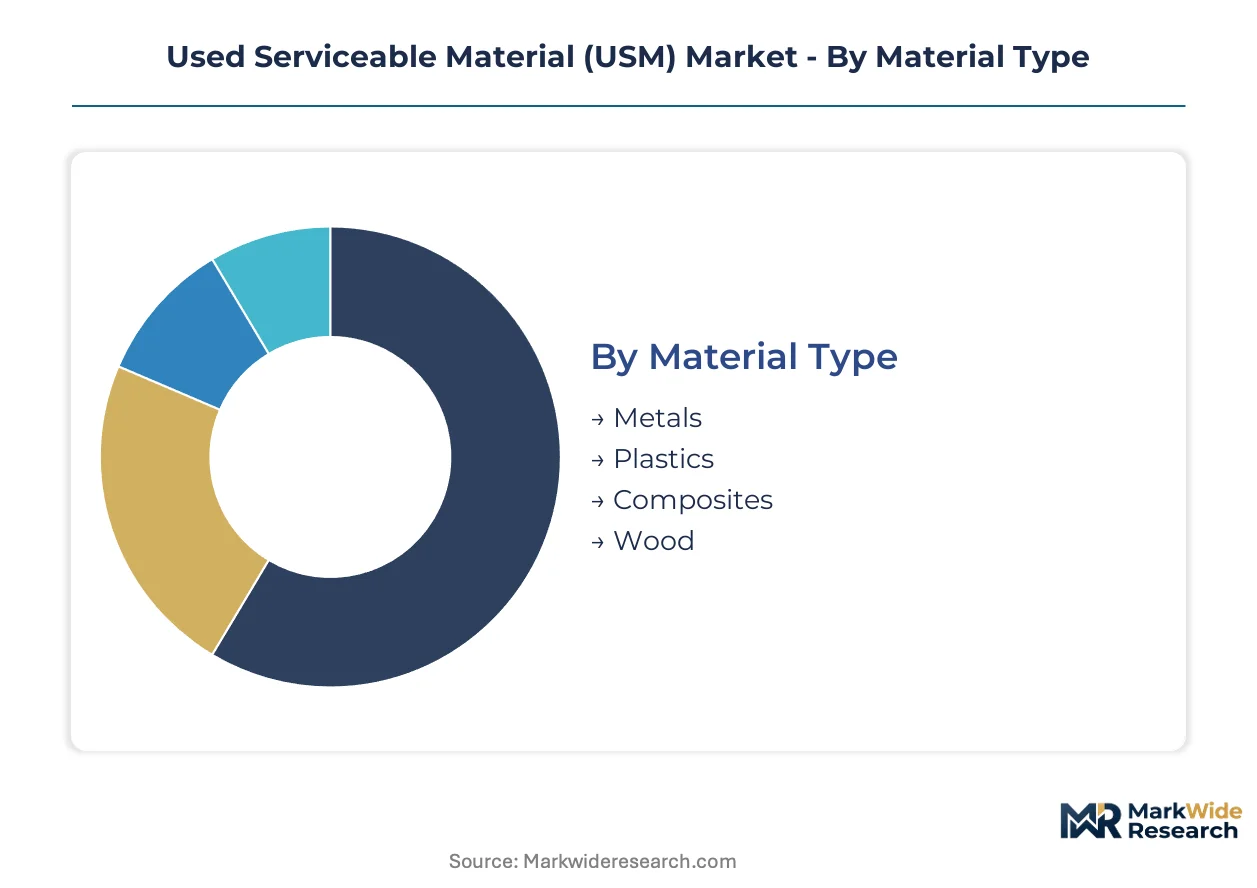
| Segmentation | Material Type: Metals, Plastics, Composites, Wood Application: Aerospace, Automotive, Construction, Electronics Condition: Refurbished, Recycled, Salvaged, Untested End User: Manufacturers, Retailers, Wholesalers, Contractors |
| Companies Covered | AAR Corp, GA Telesis, AJW Group, Unical Aviation, HEICO Corporation, AFI KLM E&M, Delta TechOps, AeroTurbine, Universal Asset Management, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used Serviceable Material (USM) Market Evolving Landscape
Digital pedigree systems and predictive material analytics are reconfiguring how MRO buyers evaluate component residual life, shifting procurement criteria from price-based to risk-adjusted total cost models.
Blockchain-enabled traceability platforms is hybridizing with traditional paper-based 8130-3 tag systems, creating interoperable audit trails for multi-owner component histories. Leasing companies and tier-one MROs are piloting these hybrid systems for engine modules. The technology is compressing due-diligence timelines from weeks to days, accelerating inventory velocity for redistributors.
REACH substance restrictions on hexavalent chromium coatings are forcing coating reapplication shops across Europe to adopt trivalent alternatives or plasma-spray ceramic substitutes. The industrial consequence is elevated refurbishment costs for landing gear and engine hot-section components. Narrowbody operators with high-cycle utilization profiles are absorbing these costs most aggressively to maintain EASA Part 145 compliance.
Airline procurement departments are consolidating vendor relationships from fragmented spot-buy networks to preferred-supplier frameworks with guaranteed availability clauses. Long-term offtake agreements with teardown specialists are displacing auction-based component sourcing for high-rotation part numbers. This consolidation is most visible among US legacy carriers managing mixed Boeing-Airbus fleets through centralized material planning functions.
Used Serviceable Material (USM) Market Segmentation
USM procurement decisions pivot on material certification grade, application-specific airworthiness requirements, and documented traceability chains. Each segmentation dimension carries distinct margin profiles and regulatory burdens that reshape supplier selection criteria across MRO buyers.
Material Type:
Cost tier differentiation separates aerospace-grade certified feedstock from general industrial recovery streams.
- Metals:Titanium and aluminum alloys recovered from engine castings and landing gear forgings undergo vacuum hot isostatic pressing to restore fatigue life. Demand concentrates among US-based narrowbody operators managing high-cycle utilization fleets under FAA airworthiness directives.
- Plastics:Engineering-grade thermoplastics from interior panels and ducting require flame-retardant re-certification to FAR 25.853 standards. German automotive suppliers are expanding sourcing for cabin component remanufacturing to meet EASA circular economy quotas.
- Composites:Carbon fiber prepreg recovery from control surfaces and fairings.
- Wood:Specialized plywood and veneer from vintage aircraft interiors.
Metals commands the established base. The steepest expansion runs through Composites as next-generation airframes reach retirement age.
Application:
Application scope determines documentation depth and testing protocol intensity.
- Aerospace:Airframe and powerplant components requiring FAA 8130-3 or EASA Form 1 airworthiness tags with complete back-to-birth traceability. Delta TechOps and GA Telesis redistribution networks dominate procurement volume for engine modules and landing gear assemblies.
- Automotive:Powertrain castings and suspension forgings repurposed from aerospace-grade titanium surplus. Indian commercial vehicle manufacturers are absorbing aluminum alloy recovery through DGFT duty-restructured import channels.
- Construction:Structural aluminum sections and architectural metals.
- Electronics:Connector housings and shielding components from avionics retirements.
Aerospace retains the dominant value pool. Automotive is gaining share fastest as material substitution accelerates.
Condition:
Volume distribution across condition grades reflects buyer risk tolerance and MRO integration depth.
- Refurbished:Components restored to OEM or FAA/EASA equivalent specifications through dimensional reworking, coating reapplication, and non-destructive testing. US legacy carriers with centralized material planning functions prefer this grade for guaranteed availability clauses in long-term offtake agreements.
- Recycled:Material processed to raw feedstock specifications without component-level traceability. Indonesian MRO startups are sourcing this grade to bypass documentation bottlenecks while building technical capabilities.
- Salvaged:As-removed components pending inspection and certification.
- Untested:Raw teardown output requiring complete evaluation.
Refurbished holds the procurement majority. Untested shows the steepest volume climb as pandemic-era fleet retirements flood teardown channels.
End User:
Customer type segmentation reveals divergent technical capabilities and compliance sophistication.
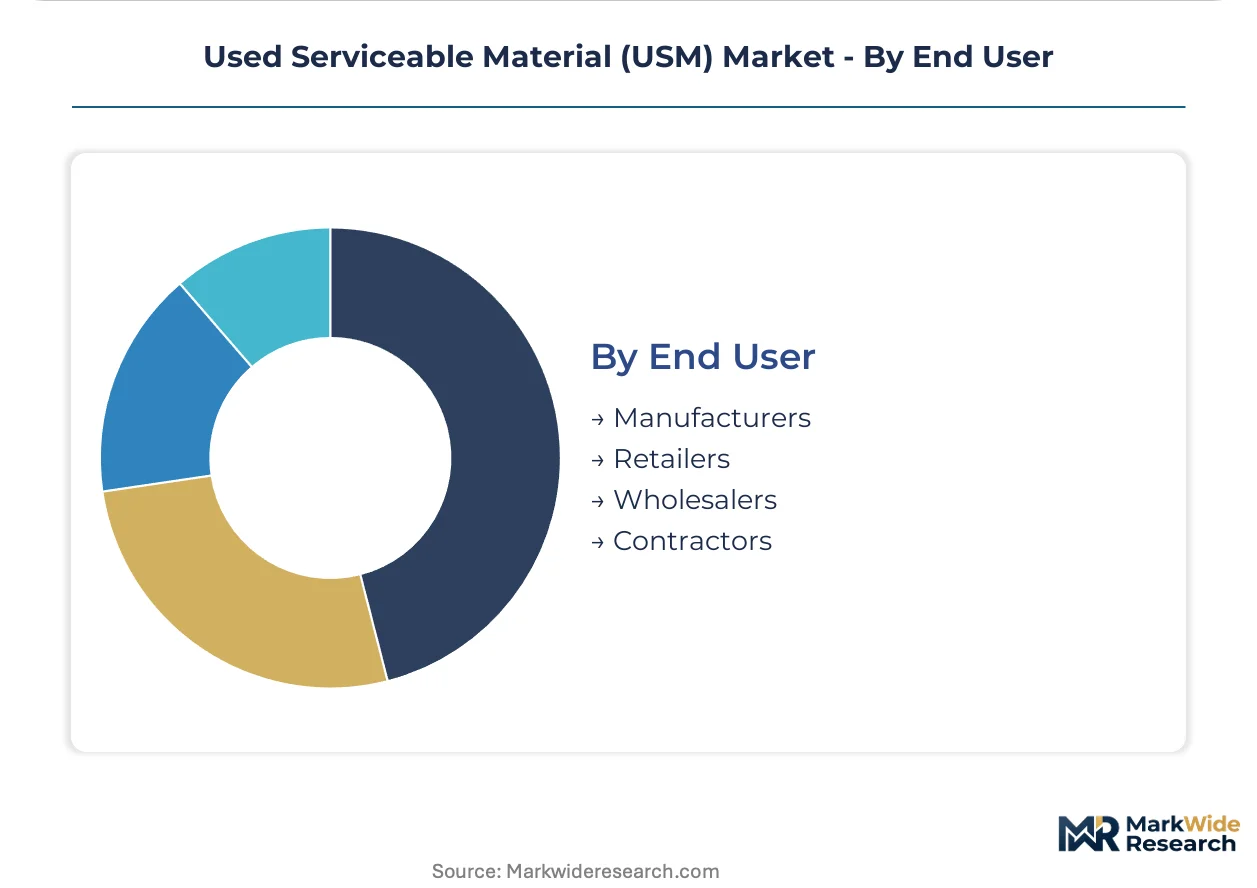
- Manufacturers:Tier-one aerostructures and systems integrators requiring serialized component histories for production line insertion. Boeing and Airbus supplier networks in the United States are mandating blockchain-verified pedigree documentation for USM acceptance.
- Retailers:Specialized aviation parts distributors serving owner-operator and corporate flight departments. French and German distributors are consolidating spot-buy relationships into preferred-supplier frameworks under EU Green Deal compliance pressure.
- Wholesalers:Inventory aggregators bridging teardown specialists and point-of-use buyers.
- Contractors:Project-based MRO service providers with variable quality systems.
Manufacturers anchor the premium tier. Wholesalers are expanding most quickly as distribution networks consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes USM primarily through centralized airline procurement functions, whereas European carriers integrate circular economy compliance into sourcing decisions, and Asian markets prioritize cost arbitrage through duty-restructured import channels.
United States
Delta TechOps and GA Telesis operate teardown and redistribution facilities serving narrowbody fleet operators under FAA airworthiness directives. The EPA oversees hazardous material handling in disassembly operations. Miami and Atlanta anchor the national redistribution network where long-term offtake agreements displace auction-based sourcing.
Germany
REACH substance restrictions on hexavalent chromium coatings force trivalent alternative adoption in landing gear refurbishment. EASA Part 145 certification requirements govern component eligibility and traceability documentation. Hamburg and Frankfurt concentrate MRO infrastructure where blockchain-verified pedigree systems are piloting for engine modules.
United Kingdom
CSRD Scope 3 reporting mandates elevate USM procurement as a measurable emissions reduction lever for airline sustainability officers. The UK Civil Aviation Authority aligns with EASA documentation standards for cross-certification. London and the Midlands host distributor consolidation from fragmented spot-buy networks to preferred-supplier frameworks.
India
DGFT import duty restructuring on aircraft spares redirects regional MRO procurement toward documented USM channels. The central bank monitors foreign exchange flows for teardown feedstock acquisitions. Mumbai and Delhi-NCR emerge as distribution hubs where underdeveloped domestic infrastructure creates partnership opportunities with global redistributors.
Singapore
Seventy percent of teardown-suitable airframes originate from lessors domiciled in Ireland and Singapore, creating supply chokepoints for regional redistribution. The Civil Aviation Authority of Singapore enforces airworthiness tag standards equivalent to FAA and EASA. Changi aerospace precinct concentrates teardown specialist operations serving Asia-Pacific carrier fleets.
Used Serviceable Material (USM) Market Competitive Landscape
Capability concentration sits with teardown specialists commanding certified inspection protocols; scale advantage sits with redistributors operating global logistics networks. The market structures around three tiers: integrated airline MRO units, independent teardown specialists, and parts certification intermediaries. Dominant competitive moves include backward integration into feedstock acquisition and geographic expansion through distribution partnerships.
Within the integrated airline tier, Delta TechOps exemplifies captive supply chain control. Among independent specialists, GA Telesis and AAR Corp occupy positions spanning teardown networks to certification services. HEICO Corporation anchors the hybrid PMA-USM segment where specialized offerings compete with OEM new-part pricing structures.
| Leading Market Players |
|---|
| AAR Corp |
| GA Telesis |
| AJW Group |
| Unical Aviation |
| HEICO Corporation |
| AFI KLM E&M |
| Delta TechOps |
| AeroTurbine |
| Universal Asset Management |
| Others |
Value Network & Pricing Analysis
Narrowbody teardown overcapacity in the United States is compressing component recovery economics and forcing redistributors toward long-term offtake structures that lock in volume commitments at the expense of spot-market flexibility. This utilization-driven pricing posture rewards buyers with centralized procurement functions while squeezing spot-market arbitrageurs.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement for high-rotation part numbers, displacing auction-based spot buying among US legacy carriers. Price differentiation rests on certification grade and documented traceability depth, with FAA 8130-3 tagged components commanding premiums over EASA Form 1 equivalents. Pricing pressure stems from pandemic-era fleet retirements flooding teardown channels with surplus feedstock. MRO contractors with variable quality systems exhibit the highest price sensitivity, whereas tier-one manufacturers prioritize pedigree verification over unit cost.
Supply Chain Analysis
Upstream feedstock acquisition centers on Ireland, Singapore, and the United States, where lessor-domiciled airframes generate seventy percent of teardown-suitable supply. The supply chain draws from titanium alloy engine castings, aluminum landing gear forgings, and carbon fiber prepreg control surfaces. Single-source vulnerability concentrates in Irish and Singaporean lessor networks, creating chokepoints for regional redistribution. Distribution runs through Miami, Atlanta, and Changi aerospace precincts where integrated teardown-to-certification facilities anchor global logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USM market fragmentation creates opportunity across documentation-intensity tiers, as EASA circular economy mandates and FAA-EASA misalignment generate niche demand for hybrid certification specialists.
For Market Incumbents: Build captive inspection capacity moats by acquiring NDT technician pipelines and certifying proprietary testing protocols before labor scarcity intensifies. Delta TechOps and GA Telesis demonstrate backward integration into feedstock acquisition through direct lessor relationships. AAR Corp anchors position via in-house production of certified component documentation that satisfies both FAA and EASA traceability requirements. For New Entrants and Emerging Players: Indonesia's underdeveloped domestic MRO infrastructure presents first-mover advantage for USM distribution partnerships serving Lion Air Group expansion. Target the recycled condition grade segment where documentation bottlenecks delay incumbent response times. Blockchain-verified pedigree systems offer a go-to-market angle for leasing company pilot programs seeking compressed due-diligence timelines. For Investors and Strategic Acquirers: Long-term, this sits as a circular economy infrastructure play because EASA Green Deal material recovery quotas and CSRD Scope 3 reporting mandates structurally elevate USM procurement priority. Acquisition targets should exhibit teardown-to-certification integration depth and established lessor feedstock relationships. The signal to watch is FAA-EASA harmonization progress on USM installation rights, which would unlock cross-certification liquidity and revalue compliant inventories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Teardown Feedstock | Captive supply from Irish and Singaporean lessors secures component pipeline against concentration risk. |
| Blockchain Traceability Platform Deployment | Hybrid ledger systems with 8130-3 tags compress due-diligence timelines for leasing company engine modules. |
| NDT Technician Pipeline Development | Proprietary certification programs address eddy current and ultrasonic inspector scarcity constraining throughput. |
| Trivalent Chromium Coating Transition | REACH-compliant reapplication shops capture EASA Part 145 landing gear refurbishment demand. |
| Indonesia Distribution Partnership | Underdeveloped MRO infrastructure creates channel control opportunity for Lion Air Group fleet support. |
Research Methodology
Initial hypotheses were tested against primary input from teardown facility operators, MRO procurement directors, airline sustainability officers, and aviation regulatory consultants, and refined through secondary validation against FAA airworthiness directive filings, EASA Part 145 certification databases, EPA hazardous material handling records, and customs trade data on aircraft spares. Bottom-up component volume estimates from teardown specialists were triangulated with top-down fleet retirement projections.
Demand-supply-balance modeling across the analysis window incorporated material type segmentation by certification grade, application-specific airworthiness requirements, condition-tier documentation depth, and end-user technical sophistication. CAGRs were derived from teardown feedstock availability curves, fleet renewal cycle timing, and regulatory compliance cost trajectories. Industry-specific inputs included narrowbody retirement wave sequencing and REACH substance restriction implementation timelines.
Practitioners should monitor FAA-EASA documentation harmonization negotiations, DGFT duty restructuring announcements, and CSRD Scope 3 reporting adoption rates for early signals of forecast revision. Quarterly review of teardown channel volume indicators, NDT technician wage inflation, and blockchain traceability pilot expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Military Displays Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
Europe Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global Mine Countermeasures Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Military Wearable Computers Market
Military Equipment and Infrastructure
Land Digital Battlefield Market
Military Equipment and Infrastructure
Military Test Equipment Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Global CBRN Defense Market
Military Equipment and Infrastructure
Aircraft Carrier Arresting Systems Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Air-Based Remote Weapon Stations Market