
 Global Armor Materials Market | 2026-2036
Global Armor Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Armor Materials Market Foresight
Ultra-high-molecular-weight polyethylene is broadening its addressable market as a lightweight alternative to traditional ceramic and metallic armor systems. DuPont de Nemours leverages decades of aramid fiber expertise to anchor its position in personal protection layers. Teijin Limited sustains competitive pressure through specialized para-aramid production at scale. Honeywell International Inc. differentiates via proprietary Spectra fiber technology for maritime and aerial platforms.
Armor materials encompass engineered substances designed to absorb, disperse, or defeat kinetic energy from ballistic threats, blast fragments, and shaped charges, typically achieving areal densities below 45 kg/m² for personnel systems while maintaining V50 ballistic limits specified by military test protocols. Their primary purpose is to protect human operators and critical equipment across combat, law enforcement, and security environments. Ceramics and composites command the dominant share of military vehicle application spending due to superior hardness-to-weight ratios against armor-piercing rounds. Polyethylene segments in flexible fabric form factors are capturing accelerated growth in law enforcement and security firm procurement as agencies prioritize mobility over maximum threat protection.
The U.S. Department of Defense's MIL-STD-662F ballistic test requirements, NATO's STANAG 4569 protection levels, and the EU's REACH chemical registration framework collectively shape material certification pathways and supplier qualification timelines. These standards create structural barriers to entry for unproven formulations while mandating environmental compliance across European defense supply chains. Stakeholders must monitor evolving lightweight hybrid system specifications as military end users demand multi-hit capability without the weight penalties of pure ceramic solutions.
Market Dynamics
The NATO vehicle modernization pipeline is compressing qualification timelines for next-generation ceramic-composite hybrid systems, forcing suppliers to accelerate multi-hit testing protocols while maintaining V50 ballistic thresholds under 45 kg/m² areal density limits.
Growth Catalysts
- STANAG 4569 Level 6 penetration requirements:NATO members Germany, Poland, and the United Kingdom are mandating upgraded protection for wheeled and tracked platforms, pulling boron carbide and silicon carbide formulations into active procurement cycles.
- Ultra-high-molecular-weight polyethylene fiber advances:Maritime patrol aircraft and fast-attack craft operators are specifying Spectra and Dyneema fabrics to reduce fuel burn while maintaining fragmentation protection.
- Law enforcement mobility priorities:Municipal SWAT units and federal protective services across the United States are trading maximum rifle-rated protection for flexible concealable systems that permit eight-hour wear cycles.
Market Restraints
- Boron carbide powder supply concentration:Over 70% of ceramic precursor material originates from Chinese state-controlled refineries, exposing NATO defense contractors to export licensing volatility and strategic stockpile depletion risks.
- REACH chemical registration burdens:ECHA's Substances of Very High Concern screening is extending qualification timelines for novel aramid curing agents by 18-24 months, freezing formulation innovation for European suppliers.
- Titanium diboride substitution pressure:Emerging ceramic-metal composites are threatening traditional alumina market share in vehicle appliqué applications where multi-hit resilience outweighs single-shot performance.
Strategic Opportunities
- India's indigenization mandates:The country's PLI scheme for defense manufacturing is opening qualification pathways for foreign armor material suppliers willing to establish joint ventures with Bharat Forge or Tata Advanced Materials.
- Additive manufacturing convergence:Binder jet printing of silicon carbide preforms is enabling topology-optimized tile geometries that were previously unmoldable, collapsing lead times for prototype vehicle integration.
- EU Green Deal embodied carbon thresholds:Defense procurement directives in France and Germany are creating preferential scoring for armor systems with lifecycle carbon footprints below 85 kg CO₂-equivalent per kilogram of protection.
Industry Challenges
- MIL-STD-662F multi-hit certification timelines:The U.S. Army's Aberdeen Test Center backlog is stretching qualification from 14 to 22 months, freezing supplier revenue recognition and compressing contract bid windows.
- Legacy vehicle integration complexity:M1 Abrams and Bradley platform armor attachment points were engineered for 1980s steel-ceramic arrays, forcing expensive structural reinforcement when retrofitting lighter composite solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Armor Materials Market |
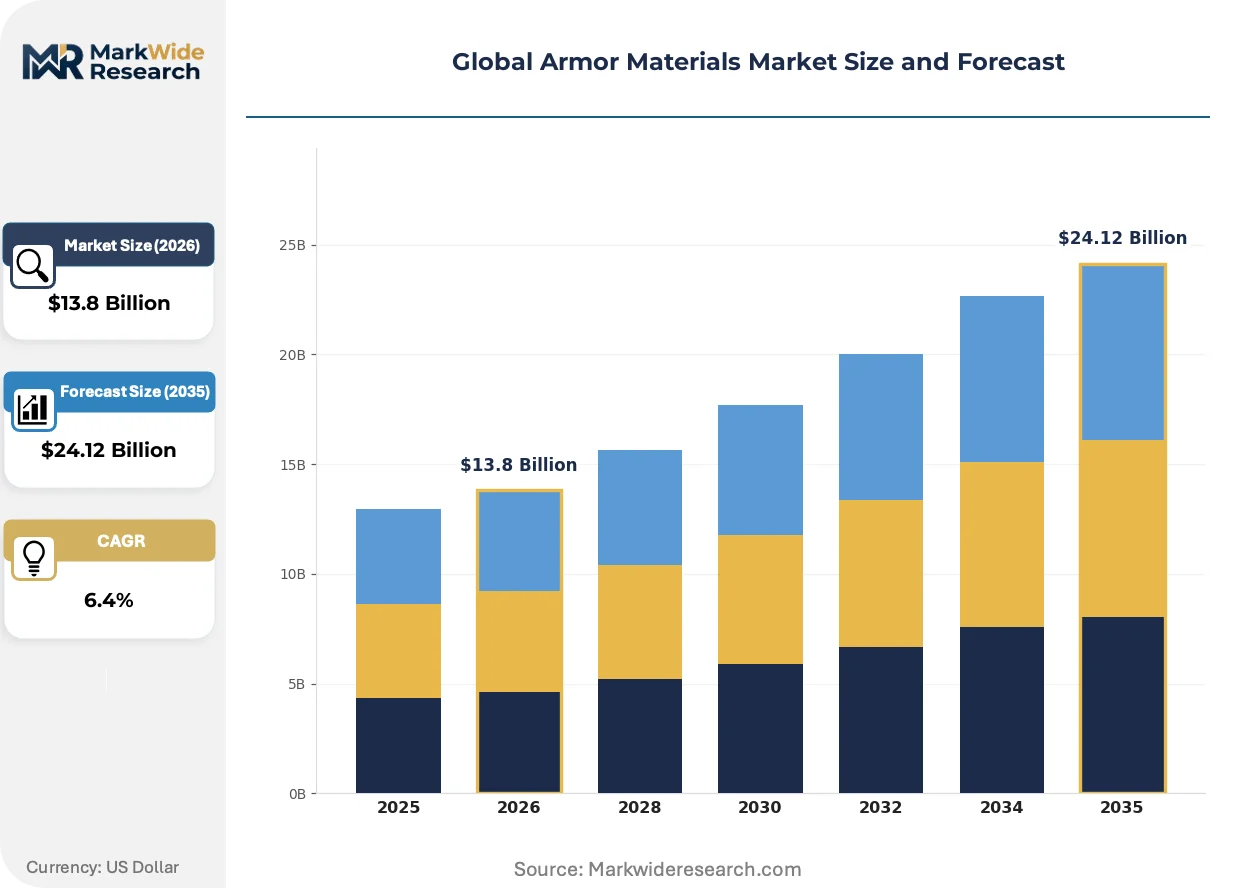
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Ceramics, Composites, Steel Alloys, Polyethylene, Laminates Application: Military Vehicles, Personal Protection, Aerospace Defense, Border Security, Riot Control End User: Defense Contractors, Law Enforcement Agencies, Security Firms, Aerospace Manufacturers, Border Patrol Form Factor: Rigid Plates, Flexible Fabrics, Modular Panels, Hybrid Systems, Foams |
| Companies Covered | DuPont de Nemours, Teijin Limited, Honeywell International Inc., 3M Company, Saint-Gobain, BAE Systems, ATI Inc., SSAB AB, CeramTec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Armor Materials Market Shifts & Advancements
Computational materials science and automated manufacturing are collapsing the iteration cycle between ballistic simulation and physical validation, compressing what required five years into eighteen-month development sprints.
Machine learning-driven microstructure optimization is automating the discovery of ceramic-matrix composite architectures that balance fracture toughness against areal density. The U.S. Army Research Laboratory and DARPA are fielding these algorithms to predict multi-hit damage propagation without destructive testing. This capability is automating the supplier qualification process, allowing smaller specialty firms to compete against legacy defense primes on technical merit rather than testing budget scale.
The EU's REACH authorization list expansion is forcing reformulation of legacy aramid fiber sizing chemistries used in European personal protection equipment. ECHA's 2024 restriction proposal on per- and polyfluoroalkyl substances is threatening water-repellent fabric treatments standard in military textiles. French and German defense ministries are responding with accelerated green chemistry procurement mandates that favor bio-based fiber finishes from domestic suppliers.
Law enforcement agencies are consolidating purchasing through federal cooperative contracts rather than municipal competitive bidding, concentrating buyer power with the U.S. General Services Administration and the Defense Logistics Agency. This channel compression is squeezing regional distributors and forcing direct manufacturer relationships with end-users. The shift is most visible in California and Texas, where state-level procurement offices are mirroring federal contract vehicles for body armor standardization.
Global Armor Materials Market Segmentation
Armor material selection hinges on threat level, mobility requirements, and platform integration constraints. Procurement patterns diverge sharply between vehicle integrators prioritizing areal density and personal protection buyers trading ballistic performance for wearability.
Material Type:
Cost tiers separate legacy metallic solutions from advanced ceramic and polymer alternatives, with qualification timelines and raw material scarcity driving buyer stratification.
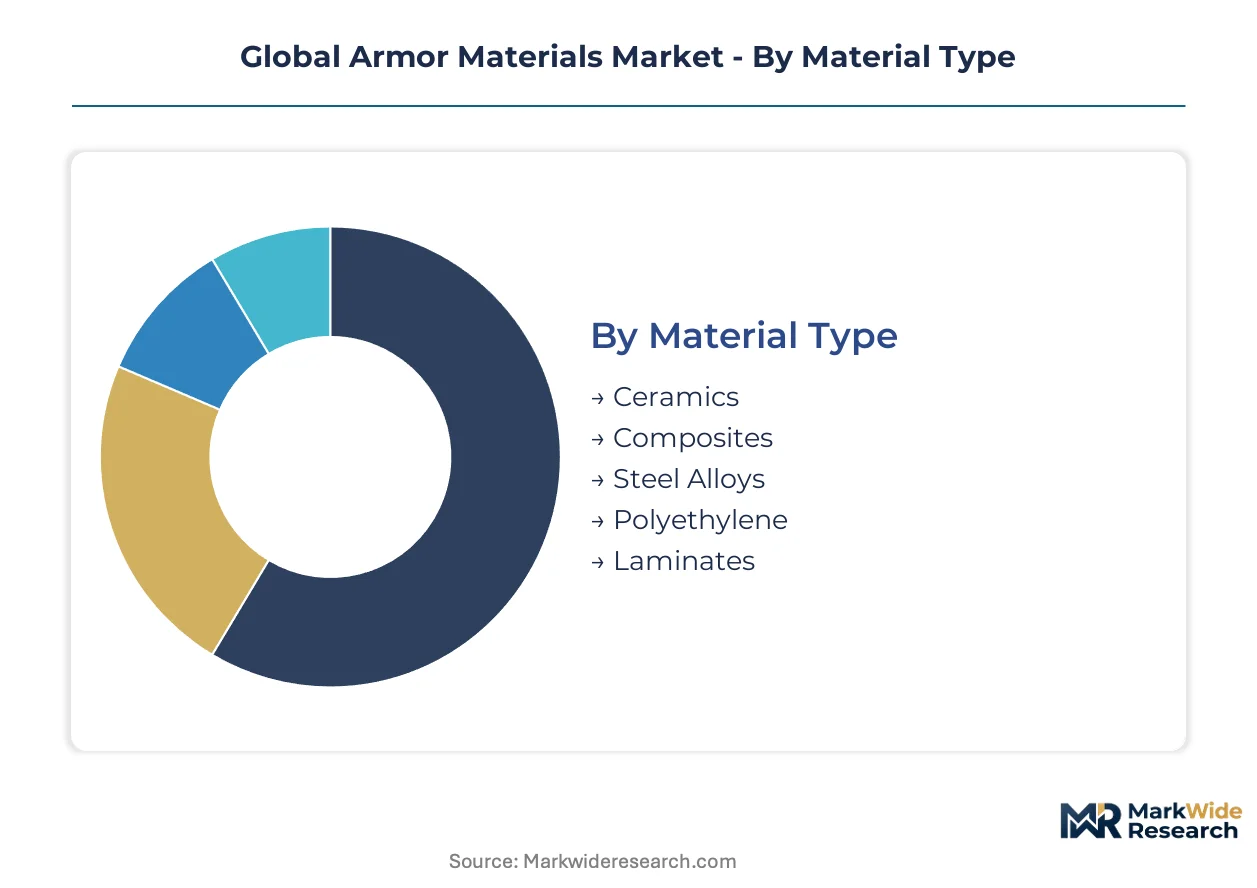
- Ceramics:Boron carbide and silicon carbide formulations achieve V50 thresholds against armor-piercing threats at sub-45 kg/m² densities. Pentagon ground vehicle programs and NATO STANAG 4569 Level 6 mandates concentrate procurement in the United States, Germany, and Poland, though Chinese state-controlled refineries supply over 70% of precursor powders, injecting supply security risk into buyer evaluations.
- Polyethylene:Ultra-high-molecular-weight polyethylene fibers—Spectra and Dyneema—deliver fragmentation protection at 40% weight reduction versus ceramics. Maritime patrol aircraft operators and fast-attack craft specifications in the United States and United Kingdom prioritize fuel burn reduction, accelerating adoption where rifle-rated threats are secondary.
- Composites:Ceramic-matrix and polymer-matrix hybrids balance multi-hit resilience with weight constraints. Demand clusters in next-generation vehicle modernization programs seeking to retrofit legacy platforms without structural reinforcement penalties.
- Steel Alloys:Rolled homogeneous armor remains cost-effective for training vehicles and lower-threat environments. Procurement concentrates in budget-constrained defense contractors and secondary market vehicle refurbishment.
- Laminates:Glass-reinforced and aramid-polymer layered systems address specific spall and blast fragmentation requirements. Niche applications include helicopter crew compartments and vehicle interior lining.
Volume sits with ceramics; growth tilts toward polyethylene.
Application:
Customer procurement authority—federal defense budgets versus municipal law enforcement appropriations—shapes specification stringency and contract scale.
- Military Vehicles:Wheeled and tracked platform armor accounts for the largest contract values, with STANAG 4569 certification requirements and MIL-STD-662F testing protocols governing qualification. Germany's KBA and the U.S. Army Aberdeen Test Center validate designs, while EU Green Deal embodied carbon thresholds now influence French and German scoring criteria.
- Personal Protection:Body armor and helmet systems prioritize eight-hour wear cycles over maximum threat ratings. U.S. municipal SWAT units and federal protective services are consolidating purchases through General Services Administration cooperative contracts, compressing distributor margins and favoring direct manufacturer relationships.
- Aerospace Defense:Rotary-wing and fixed-wing crew protection demands extreme weight minimization. Specifications from the FAA and military aviation authorities mandate fire resistance and fragmentation containment without compromising fuel efficiency.
- Border Security:Static checkpoint and mobile patrol vehicle requirements span threat levels from small arms to improvised explosive devices. Procurement fragmentation across national border agencies limits standardization.
- Riot Control:Non-ballistic protection against blunt trauma and chemical exposure dominates. Municipal police budgets and crowd management doctrine variability create geographically dispersed, low-volume demand.
Contract scale peaks with military vehicles; specification velocity runs highest in personal protection.
End User:
Maturity gradients separate defense primes with captive testing infrastructure from security firms reliant on commercial off-the-shelf certification.
- Defense Contractors:Tier-one integrators—Lockheed Martin, Rheinmetall, BAE Systems—maintain internal ballistic laboratories and direct supply relationships with ceramic powder processors. Their specifications cascade through subcontractor tiers, setting de facto industry standards.
- Law Enforcement Agencies:State and municipal departments in California, Texas, and New York are migrating to federal contract vehicles for body armor standardization. This channel compression eliminates regional distributor layers and accelerates price transparency.
- Security Firms:Private sector guarding services prioritize concealable polyethylene systems for executive protection details. Procurement flexibility exceeds government agencies, though liability exposure drives NIJ certification adherence.
- Aerospace Manufacturers:Boeing, Airbus Defence and Space, and Leonardo integrate armor as original equipment on military derivative aircraft. Their specifications emphasize traceability and lot consistency for airworthiness certification.
- Border Patrol:National agencies in the United States, Germany, and Australia operate mixed fleets requiring modular upgrade paths. Budget cyclicality and mission profile shifts between interdiction and humanitarian response complicate long-term planning.
Technical authority rests with defense contractors; procurement agility favors security firms.
Form Factor:
Supply concentration in ceramic tile pressing and fiber weaving infrastructure dictates regional manufacturing footprints and export licensing exposure.
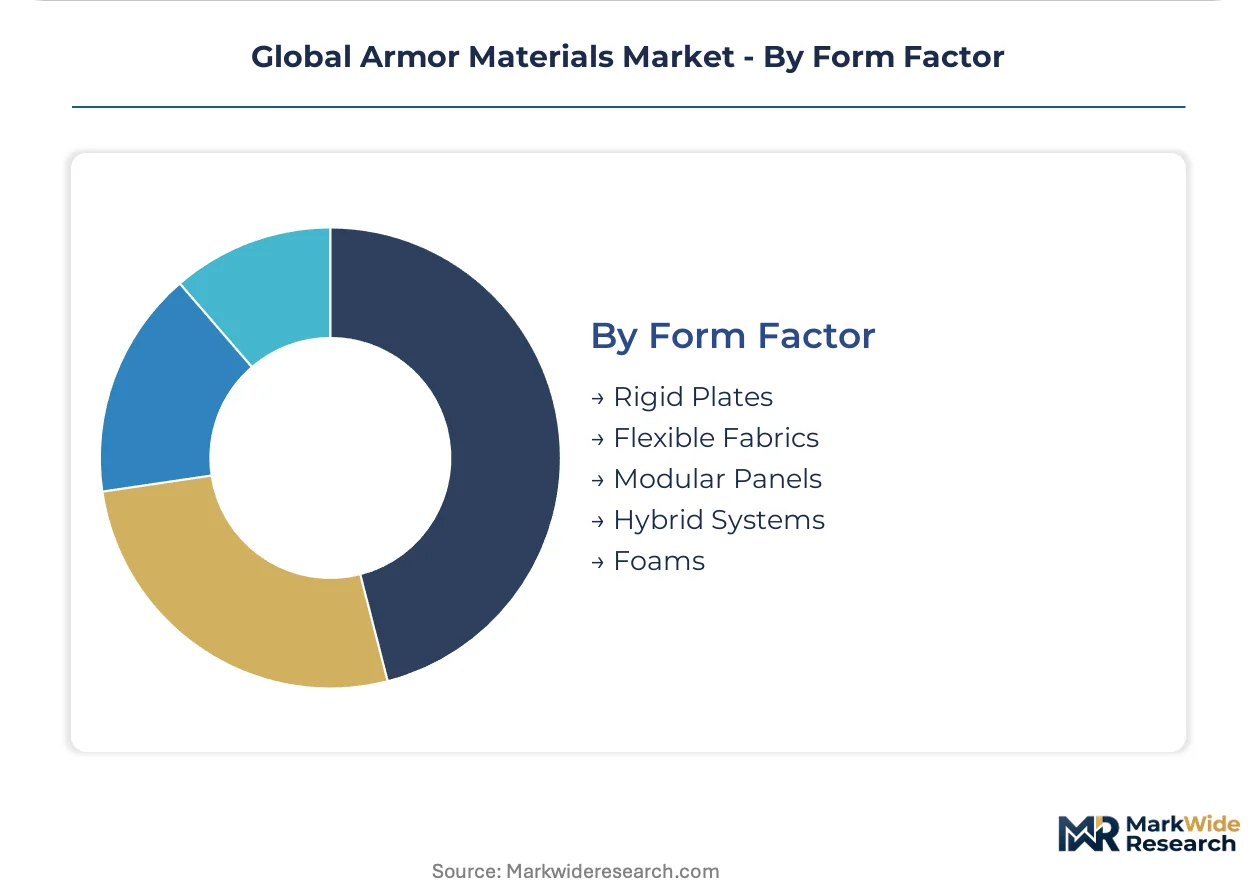
- Rigid Plates:Monolithic and multi-curve ceramic tiles require hot pressing and diamond grinding equipment concentrated in the United States, Germany, and Japan. Dimensional tolerances for vehicle integration demand precision machining capabilities that limit supplier bases.
- Flexible Fabrics:Woven and unidirectional polyethylene and aramid textiles enable concealable vests and helmet covers. Teijin in Japan and Honeywell in the United States control proprietary fiber spinning capacity, constraining independent fabric converter expansion.
- Modular Panels:Appliqué systems attach to vehicle exteriors without hull penetration, permitting field upgrade. NATO rapid deployment requirements and Ukrainian battlefield experience are accelerating scalable protection procurement.
- Hybrid Systems:Ceramic-faced composite backings combine strike-face hardness with multi-hit absorption. Additive manufacturing of silicon carbide preforms via binder jet printing is collapsing prototype lead times for topology-optimized geometries.
- Foams:Aluminum and polymer cellular structures address blast mitigation and spall containment. Niche applications include mine-resistant vehicle hulls and aircraft floor panels where impulse distribution outweighs projectile defeat.
Manufacturing scale concentrates in rigid plates; technology disruption targets hybrid systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense industrial zones in the United States, Germany, and India concentrate armor material procurement through targeted tax incentives and production-linked incentive schemes that reward domestic manufacturing capacity.
United States
Pentagon ground vehicle modernization programs and expanding law enforcement federal contract vehicles drive procurement concentration. MIL-STD-662F certification requirements from the U.S. Army Aberdeen Test Center govern supplier qualification timelines. The Baltimore-Washington corridor hosts dense defense contractor clusters where Lockheed Martin and BAE Systems maintain captive ballistic testing laboratories.
Germany
NATO STANAG 4569 Level 6 mandates for wheeled and tracked platforms accelerate boron carbide and silicon carbide formulation demand. KBA vehicle certification protocols and EU Green Deal embodied carbon thresholds reshape material selection scoring. The Rhineland-Palatinate and Bavaria regions concentrate Rheinmetall production facilities and ceramic armor integration sites.
India
Indigenization mandates under the PLI scheme for defense manufacturing open qualification pathways for foreign suppliers establishing joint ventures. DGFT export licensing frameworks and Bharat Forge partnership requirements structure market entry. The Pune-Aurangabad industrial corridor in Maharashtra anchors Tata Advanced Materials and domestic armor fabrication capacity expansion.
United Kingdom
Maritime patrol aircraft and fast-attack craft specifications prioritize ultra-high-molecular-weight polyethylene for fuel efficiency gains. Ministry of Defence procurement directives align with NATO standardization requirements. The South West England aerospace cluster around Bristol and Yeovil integrates armor systems for rotorcraft and naval platforms.
Poland
Eastern flank NATO reinforcement commitments accelerate military vehicle armor procurement cycles. National defense ministry rapid acquisition protocols compress supplier qualification windows. The Bumar-Łabędy industrial zone in Gliwice concentrates tracked vehicle modernization and ceramic armor retrofit capacity.
Global Armor Materials Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fiber spinners and ceramic powder processors commanding upstream margins while vehicle integrators capture downstream contract value. The supplier base organizes into three tiers: multinational chemical conglomerates with proprietary fiber technology, specialized ceramic component fabricators, and defense primes with captive armor integration capabilities. Consolidation pressure runs highest among mid-scale ceramic tile manufacturers facing qualification backlog delays. Strategic moves center on backward integration into precursor material supply and additive manufacturing partnerships for topology-optimized geometries.
Within the multinational fiber technology tier, DuPont de Nemours, Teijin Limited, and Honeywell International Inc. occupy positions defined by decades of aramid and polyethylene fiber development. These entities exemplify the upstream concentration where proprietary spinning capacity constrains independent fabricator expansion. Their market presence anchors personal protection and maritime armor segments where lightweight fragmentation resistance commands premium positioning against ceramic alternatives.
| Leading Market Players |
|---|
| DuPont de Nemours |
| Teijin Limited |
| Honeywell International Inc. |
| 3M Company |
| Saint-Gobain |
| BAE Systems |
| ATI Inc. |
| SSAB AB |
| CeramTec GmbH |
| Others |
Supply & Pricing Matrix
Chinese state-controlled refineries anchor the upstream boron carbide powder supply, enabling Beijing to weaponize export licensing against NATO defense contractors while simultaneously compressing margin structures for ceramic armor fabricators in Germany and the United States.
Pricing Analysis
Lead-time premiums for STANAG 4569 Level 6 certified ceramic tiles command substantial markups over standard-grade inventory held by U.S. distributors. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-662F certified multi-hit systems from commercial-grade polyethylene panels and surplus steel alloy appliqué. Cost compression in economy-tier steel solutions is intensifying because Indian and Polish contractors are flooding secondary vehicle refurbishment markets. Law enforcement agencies exhibit the highest price sensitivity, while aerospace OEMs prioritize lot consistency over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale Pentagon and NATO procurement, while specialized distributors serve municipal law enforcement and security firm demand. Ceramic precursor production concentrates in China, boron carbide hot pressing clusters in Germany and Japan, and polyethylene fiber spinning anchors in the United States and Japan. The supply chain draws from boron carbide powder, ultra-high-molecular-weight polyethylene resin, and aramid fiber inputs. Single-source vulnerability around Chinese state-controlled refineries exposes NATO contractors to strategic stockpile depletion. Distribution runs through defense primes with captive integration, tier-one ceramic fabricators, and regional body armor assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The armor materials sector is consolidating around backward integration into precursor supply, with fiber spinners acquiring weaving capacity and ceramic fabricators pursuing captive powder processing to escape Chinese supply leverage.
For Market Incumbents: Acquire ceramic powder processing assets or polyethylene resin production to insulate margin structures from Chinese export volatility. Lockheed Martin and Rheinmetall are already consolidating testing infrastructure to compress Aberdeen Test Center qualification timelines for subcontractors. Prioritize additive manufacturing partnerships for silicon carbide preform production to collapse prototype lead times against emerging topology-optimized competitors. For New Entrants and Emerging Players: Begin with India's PLI scheme joint venture pathways, where Bharat Forge and Tata Advanced Materials partnerships offer qualification shortcuts into the world's fastest-growing defense procurement market. Target law enforcement polyethylene segments where NIJ certification barriers are lower than MIL-STD-662F military requirements and federal cooperative contracts concentrate buyer power with fewer intermediaries. Lead with bio-based fiber finishes to exploit EU Green Deal embodied carbon scoring advantages. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale ceramic tile manufacturers facing 22-month Aberdeen Test Center backlogs in the United States, where qualification delays have frozen revenue recognition and compressed valuations. Long-term viability hinges on additive manufacturing convergence and green chemistry reformulation capabilities. Watch ECHA per- and polyfluoroalkyl substance restriction implementation as an inflection indicator for aramid fiber incumbent disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Ceramic fabricators acquiring boron carbide powder capacity escape Chinese state refinery leverage. |
| Additive Manufacturing Partnership | Binder jet printing of silicon carbide preforms collapses prototype lead times for vehicle integrators. |
| Green Chemistry Reformulation | Bio-based fiber finishes from domestic suppliers capture EU Green Deal procurement scoring advantages. |
| Joint Venture in India | PLI scheme partnerships with Bharat Forge open qualification pathways into indigenized defense procurement. |
| Captive Testing Infrastructure | Defense primes maintaining internal ballistic laboratories accelerate subcontractor qualification and de facto standard-setting. |
Research Methodology
Independent corroboration across defense procurement officers, ceramic materials scientists, and law enforcement equipment buyers underwrites the qualitative findings in this study. Primary interviews with Pentagon program managers, Rheinmetall platform engineers, and NIJ certification laboratory directors combined with secondary validation from MIL-STD-662F test protocols, STANAG 4569 specification documents, and ECHA REACH authorization databases. Bottom-up triangulation across material type demand and top-down reconciliation against NATO member defense budget allocations anchored volume estimates.
Rate-of-change decomposition across the analysis window isolates vehicle modernization program pull-through effects from personal protection replacement cycles. Segmentation dimensions modeled include material type, application platform, end-user procurement authority, and form factor manufacturing complexity. CAGRs derive from regression analysis against historical Pentagon and NATO procurement trajectories, with boron carbide supply elasticity and EU embodied carbon threshold implementation timelines as armor-specific forecast inputs.
Underlying measurement precision varies by segment; military vehicle ceramics carry tighter precision than law enforcement polyethylene given classified program visibility. Forecasts reflect assumptions around Chinese export licensing continuity, Aberdeen Test Center backlog resolution, and ECHA restriction finalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Next Generation Military Power Supply Market
Military Equipment and Infrastructure
Military Image Intensifier Tube Market
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Man Portable Military Electronics Market
Military Equipment and Infrastructure
Deployable Military Shelters Market
Military Equipment and Infrastructure
Defense Logistics Market
Military Equipment and Infrastructure
Military Test Equipment Market
Military Equipment and Infrastructure
Aircraft Carrier Arresting Systems Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global Soldier Modernization Market
Military Equipment and Infrastructure
Rubber Tracks for Defense and Security Market
Military Equipment and Infrastructure
Global Landing String Equipment Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market