
 Europe Military Aircraft Modernization and Retrofit Market | 2026-2036
Europe Military Aircraft Modernization and Retrofit Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Military Aircraft Modernization and Retrofit Market Foresight
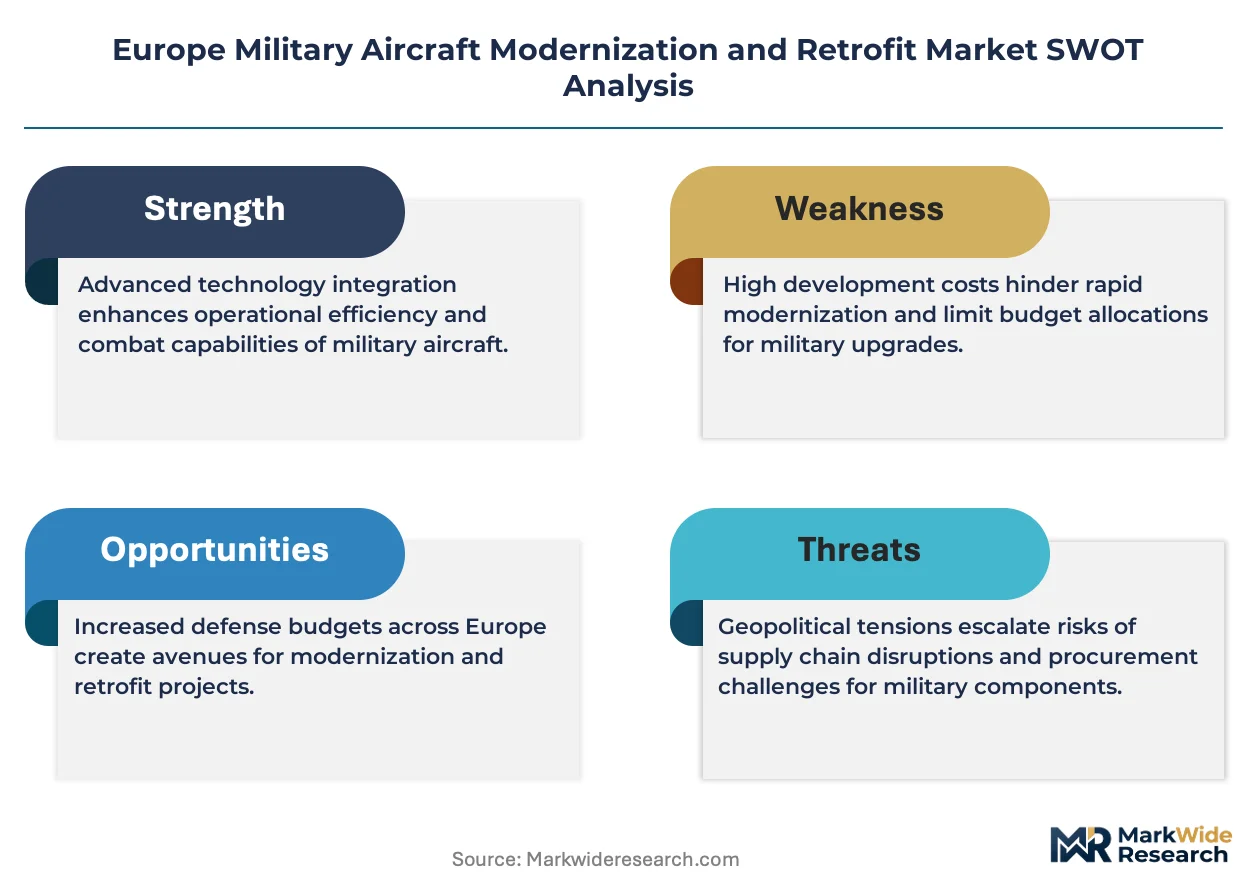
Modular avionics bundling is realigning how European air forces contract for capability upgrades, shifting from discrete component purchases to integrated mission-system packages. Airbus SE leverages its pan-European supply chain to dominate multi-national upgrade programs for transport and combat fleets. Saab AB anchors Nordic modernization efforts with specialized electronic warfare retrofit kits. Leonardo S.p.A. competes aggressively on trainer aircraft avionics refresh contracts across Italy and export markets.
Military aircraft modernization and retrofit encompasses the structural, avionic, propulsion, and mission-system overhaul of in-service fixed-wing and rotary-wing platforms to extend operational life, restore airworthiness margins, and insert new combat capabilities without full airframe replacement. Typical interventions include glass cockpit conversions, AESA radar integration, and engine hot-section refurbishment to recover thrust-specific fuel consumption within original type-certificate parameters. Combat aircraft retrofits absorb the largest share of technology spending as fourth-generation fighters require sensor fusion architectures to network with fifth-generation assets. Avionics upgrades represent the fastest-expanding technology segment because software-defined radios and open mission systems architectures reduce future obsolescence risk. Engine upgrades retain mature margin pools where OEMs control proprietary technical data packages and spare part provisioning.
The European Defence Agency coordinates cross-border retrofit standardization under Permanent Structured Cooperation frameworks, while EASA military type-certificate requirements shape airworthiness compliance costs for national upgrade programs. REACH and RoHS constraints restrict certain legacy materials in electrical harnesses and thermal coatings, forcing suppliers to requalify substitute compounds. Stakeholders must monitor how the EU AI Act classification rules affect autonomous mission-system retrofits on unmanned platforms and legacy manned aircraft alike.
Market Dynamics
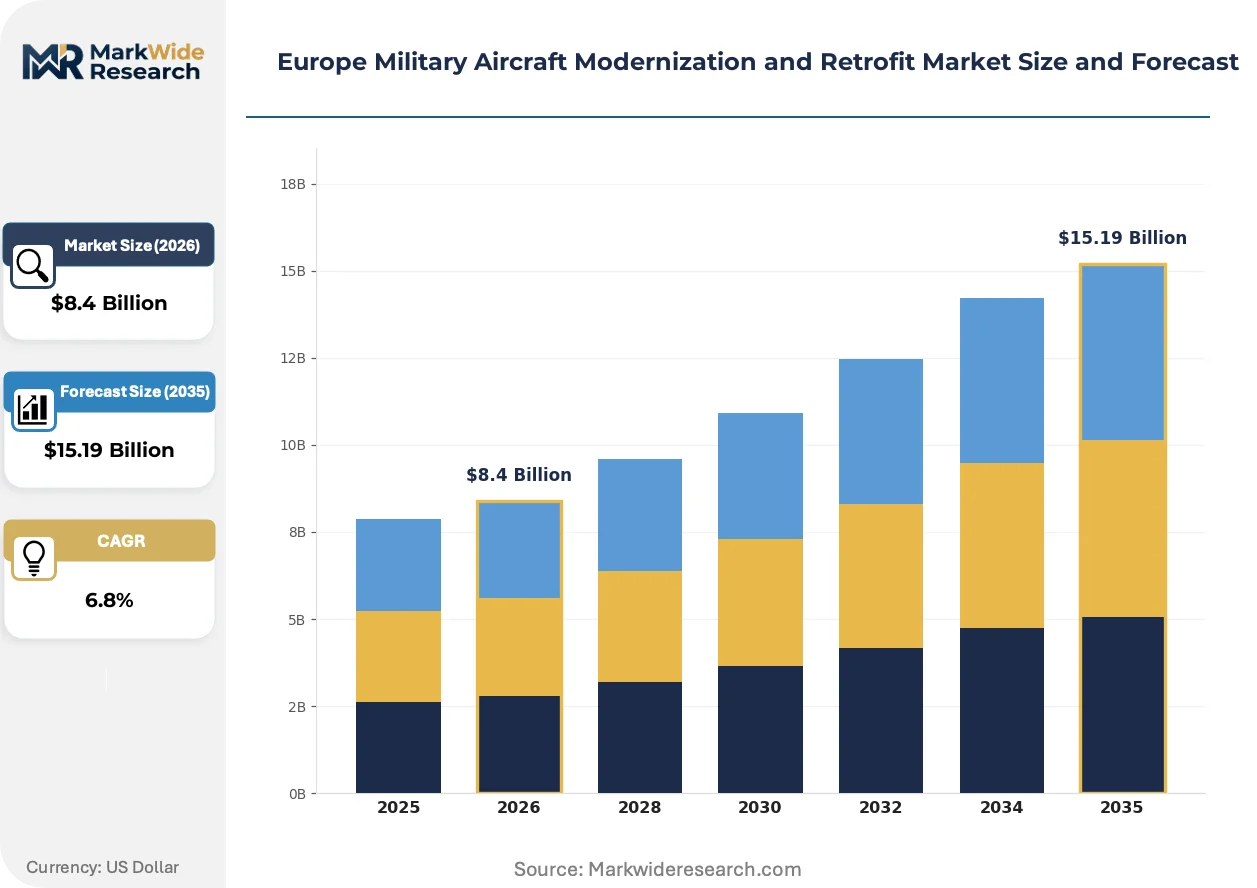
Modular avionics bundling is compressing contracting cycles across European air forces, forcing suppliers to integrate mission-system packages rather than deliver discrete hardware upgrades. This structural shift is reshaping how defense procurement offices evaluate vendor proposals and lifecycle cost models.
Growth Catalysts
- F-Gas Regulation:The EU's phasedown of hydrofluorocarbon propulsion coolants is compelling engine OEMs to develop lower-emission hot-section refurbishment protocols for legacy fighter fleets.
- Permanent Structured Cooperation:This EDA-coordinated framework is harmonizing cross-border retrofit standards, enabling pooled procurement for AESA radar integration programs among participating member states.
- Sensor fusion architectures:Fourth-generation combat aircraft require upgraded avionics backbones to network with fifth-generation assets, driving demand for open mission systems retrofits.
Market Restraints
- Proprietary technical data packages:Engine OEMs restrict access to critical maintenance documentation, locking national upgrade programs into captive spare part provisioning at inflated lifecycle costs.
- REACH substance restrictions:The European chemicals framework is banning legacy cadmium and hexavalent chromium compounds in electrical harnesses, forcing expensive requalification of substitute thermal coatings.
- Single-source avionics dependencies:Glass cockpit conversion kits for transport aircraft concentrate with two pan-European suppliers, creating vulnerability to delivery delays and price escalation.
Strategic Opportunities
- Polish and Romanian fighter modernization:These NATO eastern flank air forces operate aging Soviet-era platforms requiring Western-compatible mission systems retrofits to achieve interoperability.
- EU AI Act autonomous mission systems:The regulation's risk-classification framework for artificial intelligence is creating compliant retrofit pathways for unmanned platform operators seeking beyond-visual-line-of-sight certification.
- Software-defined radio convergence:Open-architecture waveform programming is enabling multi-national frequency harmonization without hardware replacement, reducing future obsolescence risk for tactical aviation fleets.
Industry Challenges
- Airworthiness certification timelines:EASA military type-certificate requirements for structural life-extension modifications extend program schedules by 18-24 months, compressing operational availability windows.
- Legacy 1553 bus integration:Newer open mission systems architectures must bridge to obsolete MIL-STD-1553 data buses in aging platforms, introducing signal latency and verification complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Military Aircraft Modernization and Retrofit Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Combat Aircraft, Transport Aircraft, Trainer Aircraft, UAVs Technology: Avionics, Radar Systems, Engine Upgrades, Communication Systems End User: Air Forces, Defense Contractors, Government Agencies, Private Sector Service Type: Maintenance, Upgrade, Overhaul, Repair Services |
| Companies Covered | Airbus SE, Saab AB, Dassault Aviation, Thales Group, Leonardo S.p.A., Lockheed Martin Corporation, The Boeing Company, Elbit Systems Ltd., BAE Systems plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Military Aircraft Modernization and Retrofit Market Shifts & Advancements
European military aviation is pivoting toward software-centric upgrade pathways that decouple capability insertion from hardware replacement cycles. This transformation is compressing the traditional decade-long platform refresh rhythm into continuous incremental improvement models.
AESA radar technology is penetrating fourth-generation fighter retrofit programs as a force-multiplying sensor upgrade. German and French tactical aviation commands are prioritizing active electronically scanned array integration to restore combat relevance against peer adversaries. This hardware refresh is converging with open-architecture computing standards that permit future algorithmic enhancements without airframe penetration.
The EU AI Act's risk-tier classification system is mandating formal conformity assessments for autonomous mission systems retrofits on unmanned platforms. Defense contractors must now document algorithmic decision transparency and human oversight protocols before national military type certification. Unmanned aerial system operators in Italy and Spain are restructuring development roadmaps to accommodate these pre-market compliance obligations.
Air force procurement offices are consolidating discrete component purchases into integrated performance-based logistics contracts. This contracting evolution transfers obsolescence risk to prime integrators while guaranteeing fleet availability metrics. The United Kingdom's Defence Equipment and Support organization has pioneered this model for its transport aircraft avionics refresh programs, with Nordic commands now evaluating similar arrangements.
Europe Military Aircraft Modernization and Retrofit Market Segmentation
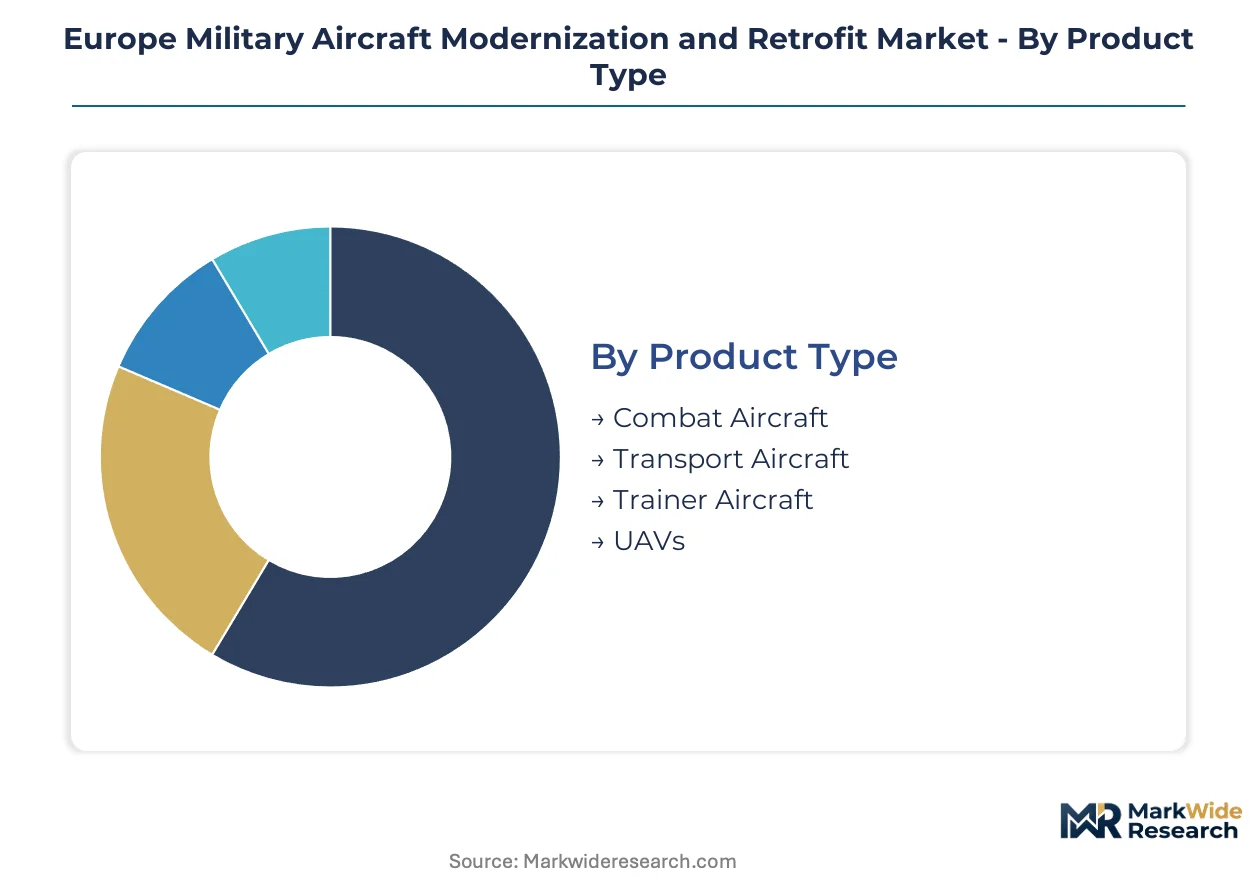
Segmentation in European military aircraft modernization reveals how upgrade cycles concentrate spending across platform types and capability domains. Understanding these divisions exposes where procurement budgets flow and which technology layers command premium investment.
Product Type:
Upgrade cycles vary dramatically by airframe role, with combat platforms absorbing disproportionate retrofit investment due to sensor complexity and threat environment pressures.
- Combat Aircraft:Fourth-generation fighters dominate European retrofit pipelines through AESA radar integration and sensor fusion architectures. German and French tactical aviation commands prioritize these platforms to restore combat relevance against peer adversaries, with Poland and Romania adding Eastern flank demand for Soviet-era platform Westernization.
- Transport Aircraft:Glass cockpit conversions and communication system refreshes extend service lives for strategic airlift fleets. The United Kingdom's Defence Equipment and Support organization has pioneered performance-based logistics contracts for this segment, transferring obsolescence risk to prime integrators.
- Trainer Aircraft:Leonardo S.p.A. competes aggressively on avionics refresh contracts across Italy and export markets for this segment.
- UAVs:The EU AI Act's risk-tier classification system mandates formal conformity assessments for autonomous mission systems retrofits on unmanned platforms.
Combat Aircraft sits at the top of the volume ranking, with UAVs climbing the fastest.
Technology:
Cost tiers separate mature hardware refresh from software-centric capability insertion, with premium pricing attaching to systems that reduce future obsolescence exposure.
- Avionics:Software-defined radios and open mission systems architectures represent the fastest-expanding technology segment. Modular bundling compresses contracting cycles as air forces shift from discrete component purchases to integrated mission-system packages.
- Radar Systems:AESA technology penetration into fourth-generation fighter retrofit programs acts as a force-multiplying sensor upgrade. German and French commands prioritize active electronically scanned array integration to network with fifth-generation assets.
- Engine Upgrades:OEMs control proprietary technical data packages and spare part provisioning, retaining mature margin pools despite F-Gas Regulation pressures on hydrofluorocarbon propulsion coolants.
- Communication Systems:Open-architecture waveform programming enables multi-national frequency harmonization without hardware replacement.
Avionics commands the largest addressable spend, with Radar Systems gaining share fastest.
End User:
Customer type determines procurement authority and compliance burden, with sovereign air forces facing distinct certification requirements versus contractor-operated fleets.
- Air Forces:National tactical aviation commands in Germany, France, and the United Kingdom sustain expanded defense procurement budgets for fleet life-extension programs. EASA military type-certificate requirements shape airworthiness compliance costs for these direct customers.
- Defense Contractors:Prime integrators absorb obsolescence risk through performance-based logistics contracts while guaranteeing fleet availability metrics.
- Government Agencies:The European Defence Agency coordinates cross-border retrofit standardization under Permanent Structured Cooperation frameworks for pooled procurement participants.
- Private Sector:Limited penetration in European military aviation due to sovereign control of combat and strategic transport platforms.
Air Forces account for the dominant procurement volume, with Defense Contractors expanding their share through contracting model innovation.
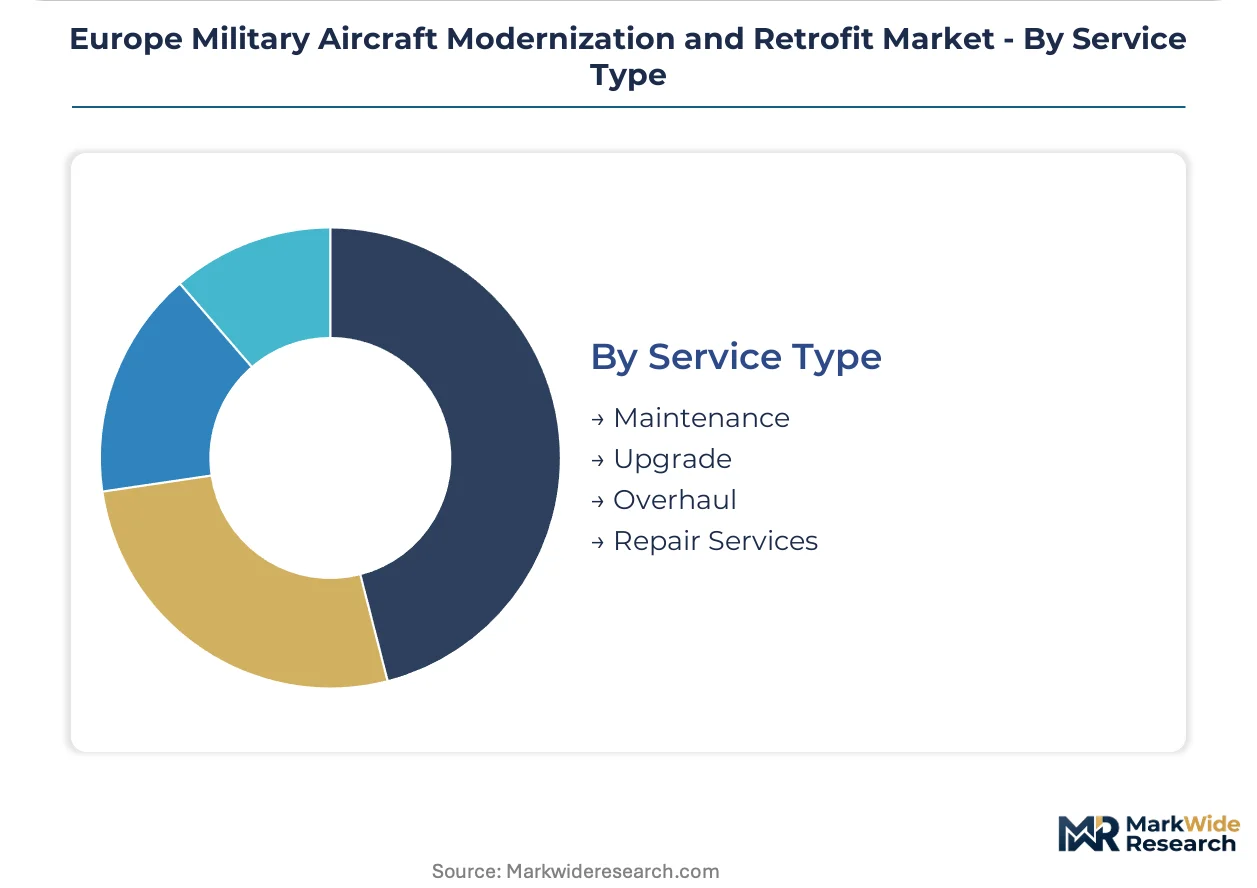
Service Type:
Service maturity stratifies margin profiles, with overhaul and upgrade work commanding technical premiums over routine maintenance.
- Maintenance:Routine airworthiness preservation generates recurring revenue but faces pressure from performance-based contracting that transfers risk to suppliers.
- Upgrade:Capability insertion through structural, avionic, and mission-system overhaul extends operational life without full airframe replacement. This segment absorbs the largest technology spending share.
- Overhaul:Engine hot-section refurbishment recovers thrust-specific fuel consumption within original type-certificate parameters, with REACH and RoHS constraints forcing requalification of substitute thermal coatings.
- Repair Services:Reactive interventions for battle damage or component failure, concentrated in operational theaters with active deployment cycles.
Upgrade services generate the highest revenue concentration, with Overhaul expanding most quickly as legacy platforms age beyond original design service lives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European military aviation modernization traces its industrial lineage to post-war state-owned arsenals in France, the United Kingdom, and Germany, which evolved into today's transnational defense conglomerates. These historical foundations established the continent's distributed but interconnected upgrade ecosystem.
Germany
The Luftwaffe's Eurofighter Typhoon fleet drives sustained demand for AESA radar retrofits and sensor fusion architectures. The F-Gas Regulation compels engine OEMs to reformulate hydrofluorocarbon coolants in hot-section refurbishment protocols. Bavaria's aerospace cluster around Munich anchors multi-national upgrade program management for combat aircraft avionics.
France
Dassault Aviation's Rafale modernization pipeline absorbs substantial retrofit investment for electronic warfare and mission-system enhancements. The EU AI Act's risk-tier classification mandates conformity assessments for autonomous mission systems on unmanned platforms. The Île-de-France region concentrates systems integration expertise for pan-European fighter upgrade programs.
United Kingdom
The Royal Air Force's Typhoon and F-35 interoperability requirements accelerate open-architecture avionics refresh cycles. EASA military type-certificate requirements shape airworthiness compliance costs for structural life-extension modifications. The Midlands aerospace corridor hosts specialized radar integration facilities serving NATO pooled procurement frameworks.
Italy
Leonardo S.p.A.'s trainer aircraft avionics refresh contracts expand domestic modernization capacity while capturing export markets. REACH substance restrictions ban legacy cadmium compounds in electrical harnesses, forcing thermal coating requalification. Piedmont's Turin-based engineering centers specialize in glass cockpit conversions for transport aircraft fleets.
Poland
The Polish Air Force's Soviet-era MiG-29 and Su-22 platforms require Western-compatible mission systems retrofits to achieve NATO interoperability. Permanent Structured Cooperation frameworks enable pooled AESA radar procurement with neighboring member states. The Central Industrial Region around Warsaw hosts emerging upgrade facilities for Eastern flank fighter Westernization programs.
Europe Military Aircraft Modernization and Retrofit Market Competitive Landscape
Premium-margin players sit above commodity-margin players across intellectual property control and technical data package ownership. The European military aircraft modernization sector exhibits consolidated tiering around prime integrators with captive supply chains, mid-tier specialists in electronic warfare subsystems, and regional maintenance providers competing on airworthiness certification speed. Three strategic archetypes dominate: pan-European conglomerates leveraging cross-border supply chains, national champions anchoring sovereign procurement preferences, and Israeli-American transplants capturing NATO interoperability niches. Competitive dynamics center on performance-based logistics contracting that transfers obsolescence risk to integrators, and vertical integration into proprietary avionics architectures that locks national customers into long-term spare part provisioning.
Within the prime integrator tier, Airbus SE and Saab AB exemplify divergent geographic strategies for multi-national program capture. Leonardo S.p.A. occupies a specialized position in trainer and light combat aircraft avionics refresh, while BAE Systems plc anchors UK-centric sovereign capability preservation. These named entities represent structural archetypes rather than exhaustive market coverage, with each embodying distinct approaches to technical data package control and cross-border consortium formation.
| Leading Market Players |
|---|
| Airbus SE |
| Saab AB |
| Dassault Aviation |
| Thales Group |
| Leonardo S.p.A. |
| Lockheed Martin Corporation |
| The Boeing Company |
| Elbit Systems Ltd. |
| BAE Systems plc |
| Others |
Supply & Pricing Matrix
Systems integration engineers concentrated around Munich, Toulouse, and London anchor labor-cost differentials that widen pricing-tier spreads between sovereign air force contracts and pooled multinational upgrade programs. F-Gas Regulation compliance costs for engine hot-section refurbishment protocols compress margins on lower-tier service packages while premium integrated mission-system bundles capture technical premiums.
Pricing Analysis
Performance-based logistics contracting dominates procurement structures across European tactical aviation commands, transferring obsolescence risk to prime integrators while guaranteeing fleet availability metrics. Price differentiation hinges on EASA military type-certificate validation tiers and proprietary technical data package access levels. Cost compression in engine overhaul services intensifies because REACH substance restrictions force expensive requalification of substitute thermal coatings. National air forces exhibit highest price sensitivity for discrete component purchases, while defense contractors absorbing fleet availability risk show lowest sensitivity to upfront unit costs.
Supply Chain Analysis
Regional distribution centers in Bavaria, Île-de-France, and the English Midlands coordinate hub-and-spoke patterns for AESA radar modules and glass cockpit conversion kits. Manufacturing concentration rests on Germany, France, and the United Kingdom for avionics integration, with Italy and Spain contributing specialized electronic warfare subsystems. Supply chains draw from gallium nitride semiconductors, rare earth thermal coatings, and hydrofluorocarbon propulsion coolants. Single-source dependencies on proprietary engine technical data packages create vulnerability to captive spare part provisioning. Distribution runs through sovereign military procurement offices and EDA-coordinated Permanent Structured Cooperation frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular avionics bundling compresses contracting cycles and shifts margin pools toward integrators controlling open mission systems architectures, with software-defined capability insertion enabling premium-tier capture beyond hardware replacement economics.
For Market Incumbents: Lock in proprietary technical data package control over engine hot-section refurbishment protocols to defend against emerging propulsion retrofit specialists. Deepen backward integration into gallium nitride semiconductor supply for AESA radar production, anchoring margin pools that REACH-compliant thermal coating substitutes cannot easily replicate. For New Entrants and Emerging Players: Capture Polish and Romanian fighter Westernization demand through NATO interoperability certification pathways for Soviet-era platform mission systems retrofits. Target unmanned platform autonomous mission systems compliance under EU AI Act risk-tier frameworks, leveraging algorithmic transparency documentation as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Prime defense contractors with captive avionics architectures are the most active acquirers in this space, consolidating mid-tier electronic warfare specialists to secure sensor fusion integration capabilities. Long-term viability centers on performance-based logistics contract portfolios with sovereign air forces. Watch for Permanent Structured Cooperation pooled procurement announcements as inflection indicators for cross-border program scale.| Strategic Initiative | Industry Significance |
|---|---|
| Open Mission Systems Architecture Adoption | Airbus SE leverages pan-European supply chains to reduce future obsolescence risk for fourth-generation fighter fleets. |
| Performance-Based Logistics Contracting | The United Kingdom's Defence Equipment and Support organization transfers fleet availability risk to prime integrators. |
| AESA Radar Integration Program | German and French tactical aviation commands restore combat relevance against peer adversaries through sensor upgrades. |
| EU AI Act Compliance Pathway | Italian and Spanish unmanned system operators restructure development roadmaps for beyond-visual-line-of-sight certification. |
| Permanent Structured Cooperation Procurement | The European Defence Agency harmonizes cross-border retrofit standards for pooled AESA radar programs. |
Research Methodology
Bottom-up air force fleet modeling reconciled against top-down defense procurement budget tracking forms the analytical core of this study. Primary interviews with platform program managers, military type-certificate engineers, defense procurement officers, and avionics integration specialists combined with secondary validation against EDA capability development reports, EASA certification databases, national defense budget appropriations, and REACH regulatory filings. Triangulation between fleet age profiles and documented upgrade program announcements grounds volume estimates.
Input-output matrices map avionics, radar, engine, and communication system spending across combat aircraft, transport aircraft, trainer aircraft, and UAV platform categories over the projection horizon. Segmentation dimensions include product type, technology layer, end-user category, and service maturity tier. CAGRs derive from fitted growth curves against documented program timelines and defense budget trajectory assumptions. Forecast inputs incorporate F-Gas Regulation phase-down schedules and EU AI Act implementation timelines.
Defense budget reallocation, program delay announcements, and regulatory compliance timeline shifts are the dominant revision risks for military aircraft modernization forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Military Optoelectronic System Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
Global Mine Countermeasures Market
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
CBRNE Defense Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
Military Image Intensifier Tube Market
Military Equipment and Infrastructure
Man Portable Military Electronics Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Next Generation Military Power Supply Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
CBRN Protection Equipment Market