
 Turret Handlers Market | 2026-2036
Turret Handlers Market Size, Share, and Industry Trends Forecast 2026-2036
Turret Handlers Market Insights
OEM-direct procurement channels for precision handler systems is reconfiguring as semiconductor capital equipment buyers consolidate vendor relationships. Cohu leverages its installed base in test-cell integration to sustain aftermarket service revenues. ASM Pacific Technology anchors Asia-Pacific supply through regional manufacturing footprints. TESEC Corporation specializes in compact handler architectures for legacy test platform retrofits.
A turret handler is a rotational indexing machine that transfers semiconductor devices between process stations using a cam-driven or servo-controlled turret mechanism, typically achieving placement accuracies within ±25 micrometers. These systems automate device orientation, thermal conditioning, and socket loading during final test and burn-in operations. Electric turret handler architectures now lead capital allocations due to energy efficiency mandates and sub-micron positioning repeatability demands. Robotics integration technology commands premium positioning as fabs adopt lights-out handling protocols. Pneumatic systems retain share in legacy analog device test floors where upgrade cycles lag digital semiconductor nodes.
Japan's METI sets machinery efficiency benchmarks that shape handler motor and drive specifications. China's SAMR enforces GB standards for industrial equipment electromagnetic compatibility and operator safety interlocks. South Korea's MFDS-aligned semiconductor facility codes influence cleanroom-compatible material selections. Stakeholders must monitor divergence between Asian equipment certification regimes and European CE machinery directives as dual-track compliance costs reshape sourcing geography.
Market Dynamics
Electric servo architectures are displacing pneumatic turret mechanisms across semiconductor test floors as energy efficiency mandates from Japan's METI and China's SAMR harden into procurement specifications. Handler vendors must now certify electromagnetic compatibility under GB standards while achieving sub-micron repeatability for advanced packaging nodes.
Growth Catalysts
- Memory chip fabrication corridors:South Korea's Pyeongtaek and Yongin clusters are expanding burn-in capacity for HBM3E and DDR5 modules, requiring high-throughput thermal conditioning handlers.
- OSAT packaging hub expansion:Malaysia's Penang and Kulim free trade zones are scaling automated test-cell integration to service fabless design houses migrating advanced packaging from Taiwan.
- MIIT equipment upgrade mandates:China's Ministry of Industry and Information Technology is pressuring domestic fabs to replace legacy analog test handlers with energy-efficient electric architectures by 2027.
Market Restraints
- Rare-earth magnet supply concentration:High-performance servo motors depend on neodymium-iron-boron magnets where Chinese processing facilities control 87% of global separation capacity.
- Cleanroom material certification lag:Japan's PMDA-aligned pharmaceutical semiconductor hybrids require extended outgassing validation for polymer turret components, stretching qualification timelines.
- Legacy pneumatic platform lock-in:Analog device test floors in automotive tier-2 fabs retain pneumatic handlers due to socket standardization and technician familiarity, slowing electric conversion.
Strategic Opportunities
- Vietnam OSAT greenfield builds:Amkor and Intel are constructing advanced packaging facilities near Ho Chi Minh City without legacy pneumatic infrastructure, enabling pure electric handler deployment.
- EU AI Act chip traceability:European semiconductor users must document test-handling provenance for high-risk AI applications, creating demand for handlers with integrated data-logging modules.
- Silicon carbide power device testing:Electric vehicle inverter manufacturers require turret handlers capable of 175°C continuous operation for wafer-level burn-in of SiC MOSFETs.
Industry Challenges
- Multi-physics simulation talent scarcity:Turret mechanism design now requires coupled thermal-mechanical-electromagnetic modeling expertise that remains concentrated in Japanese and German engineering consultancies.
- Dual-track certification burden:Handlers destined for simultaneous Asian and European deployment must satisfy divergent METI efficiency benchmarks and CE machinery directive safety interlock protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turret Handlers Market |
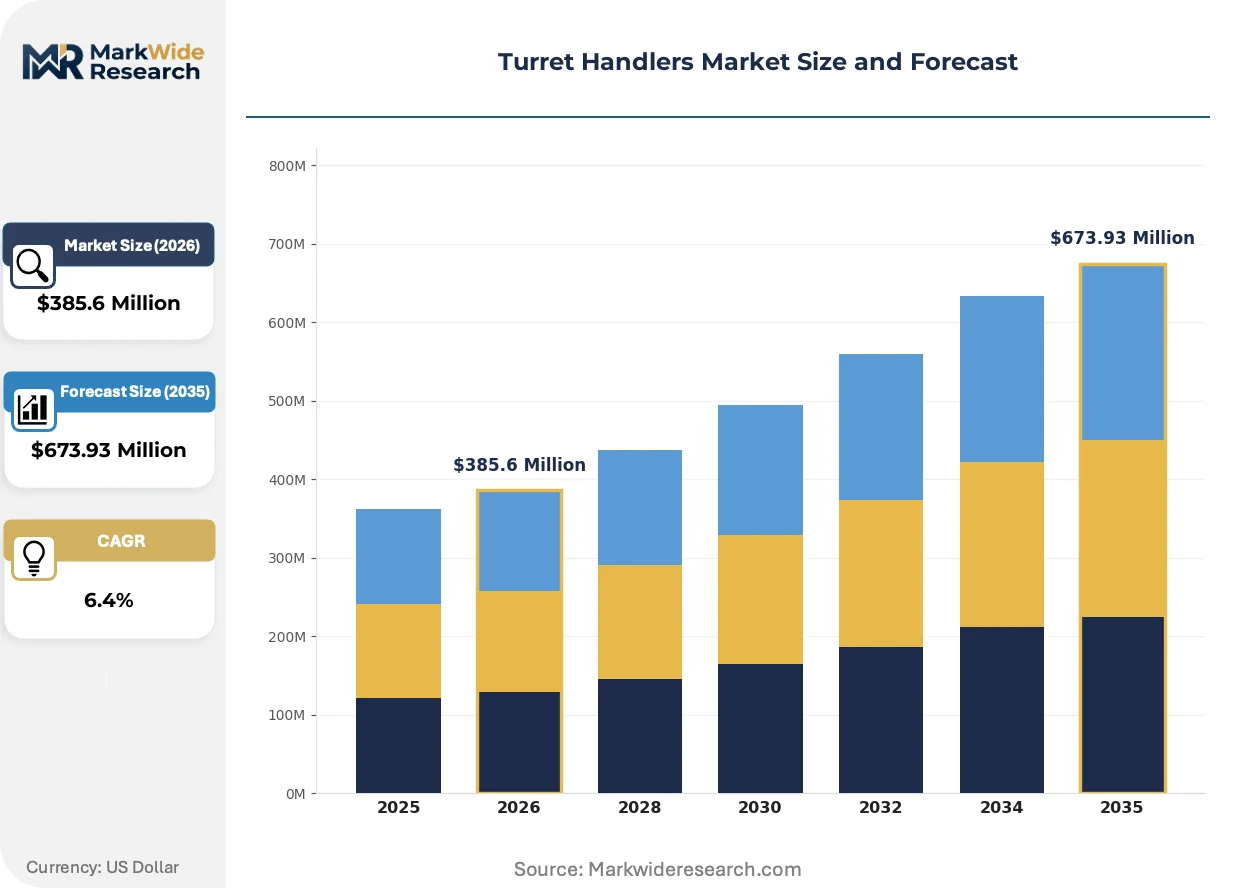
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Turret Handler, Electric Turret Handler, Pneumatic Turret Handler, Hybrid Turret Handler Technology: Robotics Integration, Automated Guidance System, Remote Control Interface, Sensor-Based Positioning, Manual Operation Application: Metal Fabrication, Shipbuilding, Aerospace Assembly, Heavy Machinery, Defense Manufacturing End User: Shipyards, Aerospace Manufacturers, Machine Shops, Defense Contractors |
| Companies Covered | Cohu, TESEC Corporation, Innogrity Pte Ltd, UENO SEIKI, ASM Pacific Technology, WEB Technology Inc., Boston Semi Equipment LLC, Xyrius Solutions Sdn Bhd, Advantest Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turret Handlers Market Trends and Innovations
Handler architectures are converging with collaborative robotics and edge computing to enable lights-out semiconductor test operations. Three developments are compressing equipment refresh cycles and reconfiguring vendor competitive positioning.
Digital twin platforms are digitizing turret mechanism validation before physical prototype build. ASM Pacific Technology and Cohu are deploying Siemens NX MCD and proprietary physics engines to simulate cam profiles, thermal drift, and placement accuracy across 10,000+ virtual cycles. Korean memory fabs are adopting these virtual commissioning workflows to compress handler qualification from 14 weeks to 6 weeks for new product introductions.
Japan's METI 2030 carbon neutrality roadmap for machinery is tightening motor efficiency standards that directly shape handler drive specifications. The regulation mandates IE4 premium efficiency motors for equipment above 0.75kW, forcing redesigns of legacy turret indexing drives. Domestic handler manufacturers are responding with integrated permanent magnet synchronous motors that exceed the threshold while maintaining ±25 micrometer placement repeatability.
Consolidated vendor relationships are compressing procurement decision cycles among capital equipment buyers. Semiconductor fabs are reducing qualified handler suppliers from 4-5 to 2-3 per test-cell platform, prioritizing vendors with integrated test-handler-burn-in system capabilities. This concentration is most visible in South Korea, where Samsung and SK hynix are standardizing on single-source handler-test cell configurations for HBM volume ramps.
Turret Handlers Market Segmentation
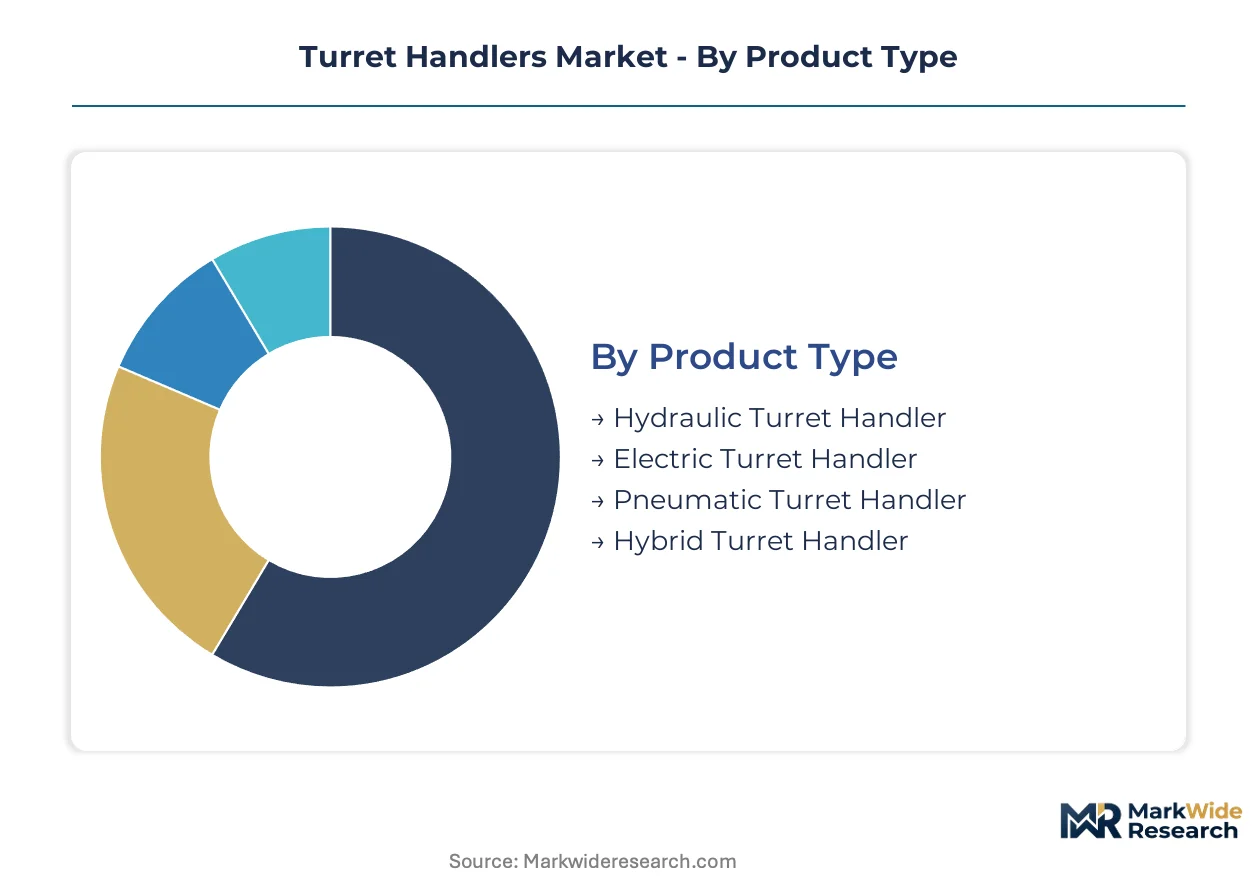
Turret handler procurement decisions diverge sharply across product architectures and operational environments. Semiconductor fabs prioritize precision and energy efficiency, while heavy manufacturing sectors emphasize payload capacity and durability.
Product Type:
Cost tier differentiation separates capital-efficient pneumatic systems from premium electric architectures with servo-controlled indexing.
- Electric Turret Handler:Servo motors and permanent magnet drives achieve sub-micron placement repeatability for advanced packaging test floors. South Korea's memory chip corridors are standardizing on these systems as METI efficiency mandates harden into procurement specifications.
- Pneumatic Turret Handler:Compressed air mechanisms dominate legacy analog device test floors where socket standardization and technician familiarity slow upgrade cycles. Malaysia's OSAT packaging hubs retain these for cost-sensitive burn-in operations.
- Hydraulic Turret Handler:Fluid power systems command heavy-lift applications in shipbuilding and aerospace assembly where torque density exceeds electric motor limits.
- Hybrid Turret Handler:Combined pneumatic-electric architectures bridge upgrade paths for fabs transitioning from legacy test platforms without full infrastructure replacement.
Electric architectures command the established base in semiconductor back-end assembly. The steepest expansion runs through hybrid systems serving mixed-technology test floors.
Technology:
Application maturity separates lights-out robotics integration from operator-dependent manual interfaces across fabrication environments.
- Robotics Integration:Collaborative robot arms and autonomous mobile platforms enable fully automated test-cell operations without human intervention. Samsung and SK hynix fabs in Pyeongtaek are deploying these for HBM3E volume ramps.
- Sensor-Based Positioning:Machine vision and laser triangulation systems provide real-time placement feedback for ±25 micrometer accuracy requirements. These systems concentrate in advanced packaging nodes handling silicon carbide power devices.
- Automated Guidance System:Pre-programmed motion paths optimize turret indexing sequences for high-throughput thermal conditioning cycles.
- Remote Control Interface:Networked operator stations enable centralized monitoring of multi-handler test cells from cleanroom exterior positions.
- Manual Operation:Hand-actuated turret mechanisms persist in defense manufacturing and prototype machine shops where batch sizes resist automation economics.
Robotics integration anchors new fab construction. The fastest technology climb is occurring in sensor-based positioning for advanced packaging nodes.
Application:
Volume concentration patterns separate high-mix semiconductor test floors from low-mix heavy fabrication environments.
- Metal Fabrication:Structural steel processing and plate forming operations utilize turret handlers for automated punch-press feeding and part orientation. These applications prioritize throughput over micrometer-level precision.
- Aerospace Assembly:Titanium and composite component handling demands cleanroom-compatible materials and electromagnetic interference shielding for avionics integration.
- Shipbuilding:Heavy plate positioning and hull section alignment require hydraulic turret mechanisms with multi-ton payload capacity.
- Heavy Machinery:Mining equipment and construction vehicle manufacturing employs handlers for weldment reorientation and assembly line feeding.
- Defense Manufacturing:Secure facility requirements and ITAR compliance constrain supplier qualification to domestic vendors with cleared personnel programs.
Metal fabrication holds the installed base concentration. Aerospace assembly is gaining share fastest from commercial aviation production recovery.
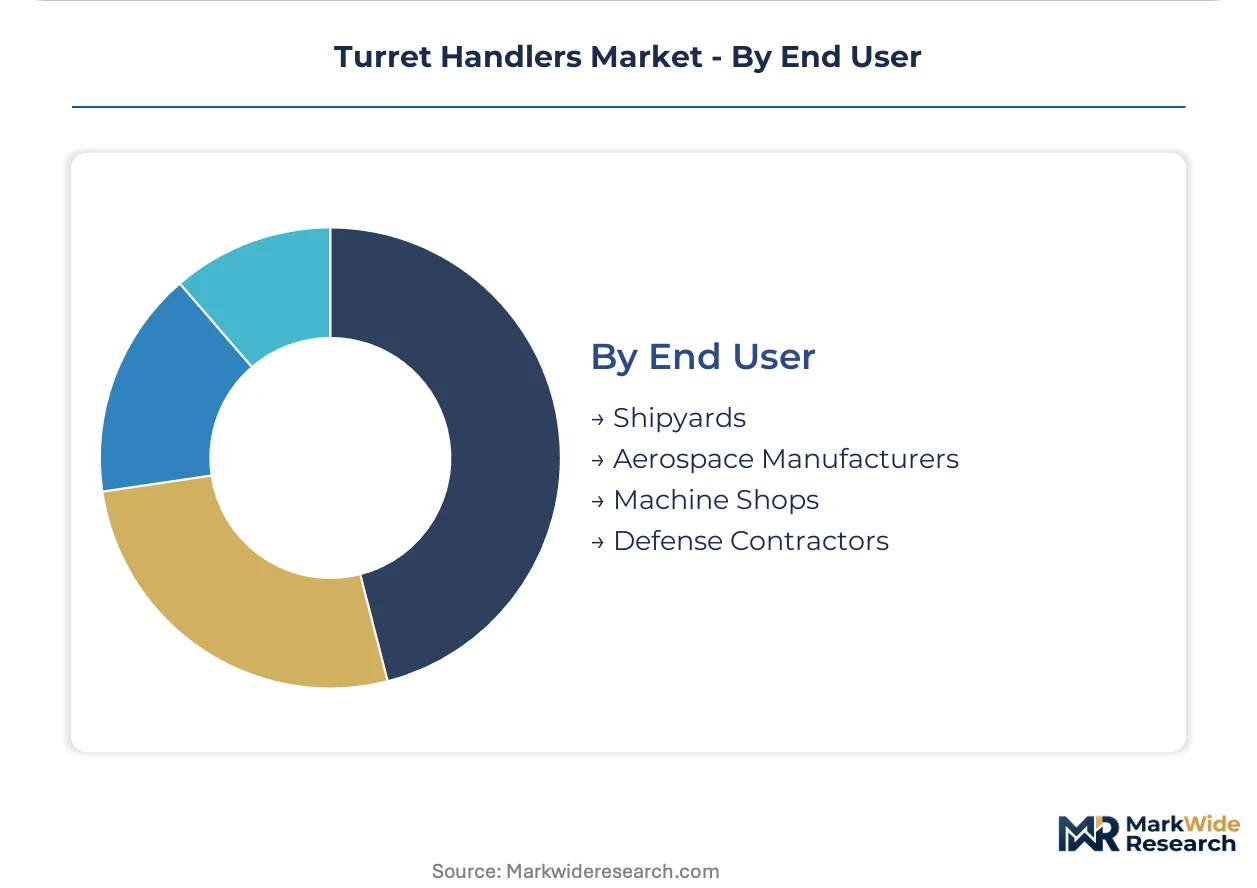
End User:
Customer type fragmentation separates consolidated capital equipment buyers from fragmented job shop operators with divergent procurement cycles.
- Shipyards:Korean and Chinese mega-yards in Ulsan and Shanghai consolidate handler procurement through integrated automation system vendors. These buyers prioritize 20-year operational life and localized spare parts logistics.
- Aerospace Manufacturers:Boeing, Airbus, and their tier-1 suppliers specify handlers with AS9100 quality certification and full material traceability for flight-critical component handling.
- Machine Shops:Small-batch contract manufacturers in Germany's Mittelstand and Japan's manufacturing clusters favor flexible handlers with rapid changeover between part families.
- Defense Contractors:Lockheed Martin, Northrop Grumman, and BAE Systems impose security-cleared installation protocols and air-gapped control systems for sensitive production lines.
Shipyards represent the most concentrated demand base. Defense contractors are expanding procurement fastest from Indo-Pacific rearmament programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korean memory corridors where handler qualification cycles compress timelines, while Malaysian OSAT hubs compete on capital efficiency metrics that favor pneumatic platform retention.
United States
Defense manufacturing and aerospace assembly anchor handler demand from Lockheed Martin and Boeing tier-1 networks. FAA electromagnetic interference standards constrain cleanroom-compatible material selections for avionics component handling. Greater Phoenix semiconductor corridors are scaling electric handler deployment for silicon carbide power device test floors serving EV inverter manufacturers.
China
MIIT equipment upgrade mandates are pressuring domestic fabs to retire legacy analog test handlers by 2027. GB standards for industrial electromagnetic compatibility and SAMR safety interlock protocols tighten certification requirements for precision servo architectures. Yangtze River Delta packaging hubs in Suzhou and Wuxi are consolidating vendor relationships to single-source handler-test cell configurations.
Japan
METI machinery efficiency benchmarks mandate IE4 premium efficiency motors for equipment above 0.75kW, forcing turret indexing drive redesigns. PMDA-aligned pharmaceutical semiconductor hybrids require extended outgassing validation for polymer components. Chubu-Nagoya industrial automation clusters are deploying integrated permanent magnet synchronous motors that exceed efficiency thresholds while maintaining placement repeatability.
South Korea
Pyeongtaek and Yongin memory chip corridors are expanding burn-in capacity for HBM3E and DDR5 modules, requiring high-throughput thermal conditioning handlers. MFDS-aligned semiconductor facility codes influence cleanroom-compatible material specifications. Samsung and SK hynix fabs are standardizing on single-source handler configurations, compressing procurement decision cycles among capital equipment buyers.
Malaysia
Penang and Kulim free trade zones are scaling automated test-cell integration to service fabless design houses migrating advanced packaging from Taiwan. Legacy pneumatic platform lock-in persists in cost-sensitive burn-in operations where socket standardization slows electric conversion. OSAT packaging hubs retain pneumatic handlers for analog device test floors serving automotive tier-2 suppliers.
Turret Handlers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision indexing mechanisms and thermal conditioning modules. The vendor base compresses toward consolidated relationships as semiconductor fabs reduce qualified suppliers from four or five to two or three per test-cell platform. Three archetypes dominate: integrated test-handler-burn-in system vendors, standalone handler manufacturers with regional manufacturing footprints, and compact architecture specialists serving legacy platform retrofits. Competitive moves concentrate on strategic partnerships for test-cell integration and portfolio diversification into robotics-enabled lights-out handling protocols.
Among Asia-Pacific headquartered platform integrators, ASM Pacific Technology and Cohu exemplify the consolidated vendor relationship model that Korean memory fabs are standardizing upon. TESEC Corporation occupies a position within the compact architecture specialist tier, serving legacy test platform retrofits where pneumatic-to-electric upgrade paths require bridging solutions. These three entities represent distinct competitive vectors: regional manufacturing scale, installed base leverage for aftermarket service, and specialized retrofit expertise.
| Leading Market Players |
|---|
| Cohu |
| TESEC Corporation |
| Innogrity Pte Ltd |
| UENO SEIKI |
| ASM Pacific Technology |
| WEB Technology Inc. |
| Boston Semi Equipment LLC |
| Xyrius Solutions Sdn Bhd |
| Advantest Corporation |
| Others |
Pricing and Supply Chain Analysis
Rare-earth magnet processing concentration in Chinese separation facilities anchors cost structures for high-performance servo motors, concentrating margin capture upstream while handler assemblers in South Korea and Japan compete on placement precision specifications. Electric turret handler premiums reflect this feedstock dependency, with configured-to-order pricing widening against standard pneumatic platform quotes.
Pricing Analysis
Configured-to-order pricing for electric servo architectures commands substantial premiums over standard pneumatic platform quotes. Three-tier pricing structure across premium IE4 motor configurations, standard servo systems, and economy pneumatic tiers segments buyers by thermal conditioning throughput requirements. Cost compression in pneumatic tiers intensifies as Malaysia's OSAT hubs consolidate procurement volumes. Analog device test floors in automotive tier-2 fabs exhibit highest price sensitivity, while Korean memory corridors prioritize placement repeatability over unit economics.
Supply Chain Analysis
Neodymium-iron-boron magnet feedstock draws from Chinese processing facilities, Japanese motor winding operations, and Korean precision machining centers. Permanent magnet synchronous motors, ceramic bearing assemblies, and cleanroom-grade polymer turret components constitute critical input tiers. Single-source vulnerability concentrates in rare-earth separation capacity. Distribution runs through OEM-direct channels for semiconductor capital equipment buyers consolidating vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turret handler markets exhibit defensive moat characteristics rooted in METI efficiency certification entrenchment and test-cell switching costs that lock Korean memory fabs into validated supplier configurations.
For Market Incumbents: Pre-empt emerging compact architecture specialists by accelerating IE4 motor certification timelines ahead of China's 2027 MIIT upgrade mandates. Deepen backward integration into permanent magnet synchronous motor production to offset rare-earth feedstock volatility. Secure single-source handler configurations with Samsung and SK hynix through integrated test-handler-burn-in system capabilities. For New Entrants and Emerging Players: Vietnam OSAT greenfield builds near Ho Chi Minh City represent the most penetrable entry point, free from legacy pneumatic infrastructure lock-in and receptive to pure electric handler deployment. Silicon carbide power device test floors serving EV inverter manufacturers offer second-mover advantage in 175°C continuous operation specifications. Lead with robotics-enabled lights-out handling protocols as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Capital is best deployed toward compact architecture specialists with proven pneumatic-to-electric retrofit expertise and established relationships with Japan's PMDA-aligned pharmaceutical semiconductor hybrid facilities. Long-term viability hinges on dual-track certification capabilities spanning METI efficiency benchmarks and CE machinery directive safety interlocks. Monitor divergence between Asian equipment certification regimes and European directives as inflection indicator for sourcing geography shifts.| Strategic Initiative | Industry Significance |
|---|---|
| IE4 Motor Certification Investment | METI 2030 carbon neutrality roadmap mandates premium efficiency thresholds for equipment above 0.75kW. |
| Digital Twin Platform Deployment | Siemens NX MCD integration compresses handler qualification from 14 weeks to 6 weeks for Korean memory fabs. |
| Backward Integration into Magnet Supply | Captive neodymium-iron-boron sourcing mitigates Chinese separation facility concentration risk. |
| Robotics-Enabled Lights-Out Protocol | Collaborative robot arms enable fully automated test-cell operations without human intervention. |
| Dual-Track Certification Buildout | Simultaneous METI efficiency and CE machinery directive compliance expands addressable geography. |
Research Methodology
Initial hypotheses were tested against primary input from semiconductor capital equipment procurement directors, test-cell integration engineers, aftermarket service heads, and cleanroom facilities managers, then refined through secondary validation against SEC 10-K filings from listed handler manufacturers, METI machinery efficiency benchmark publications, MIIT equipment upgrade mandate documents, and customs/trade data for rare-earth magnet flows. Bottom-up unit economics modeling triangulated against top-down semiconductor capital expenditure projections.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture type, technology integration level, application environment, and end-user consolidation tier. CAGRs derived from fitted growth curves applied to equipment replacement cycles and greenfield capacity announcements. Forecast inputs incorporated MIIT 2027 mandate compliance deadlines and HBM3E volume ramp schedules from Korean memory corridors.
Practitioners should monitor rare-earth export license restrictions, METI motor efficiency standard revisions, and EU AI Act chip traceability implementation for early signals warranting forecast reassessment. Cross-checking against SEMI equipment market statistics and individual fab capex disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Military Displays Market
Military Equipment and Infrastructure
Howitzer Artillery System Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
Air-Based Remote Weapon Stations Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
NATO Defense Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Image Intensifier Tube Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
FLIR and Laser Designator Targeting Pods Market
Military Equipment and Infrastructure
Deployable Military Shelters Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
Global Landing String Equipment Market
Military Equipment and Infrastructure
Man Portable Military Electronics Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Global CBRN Defense Market