
 Mergers and Acquisitions (Manda) in Aerospace and Defense Market | 2026-2036
Mergers and Acquisitions (Manda) in Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Mergers and Acquisitions (Manda) in Aerospace and Defense Market Foresight
Hypersonic propulsion and autonomous systems integration is tilting capital allocation toward dual-use technology portfolios. The Boeing Company leverages its commercial aviation footprint to sustain defense-adjacent manufacturing scale. Lockheed Martin anchors classified program execution through vertically secured supply chains. BAE Systems competes across transatlantic electronic warfare niches with sovereign facility networks.
Mergers and acquisitions in aerospace and defense encompass the strategic consolidation, asset restructuring, and equity transactions through which firms combine operational capabilities, intellectual property, and government contracting access; these transactions typically involve security clearance transfers, ITAR-controlled asset migration, and cost synergy validation against multi-year procurement cycles. The transaction type dimension shows acquisitions dominating flow volume as primes absorb niche technology holders, while joint ventures expand in satellite constellations and hypersonic test facilities where sole investment risk exceeds balance sheet tolerance. Deal size stratification reveals mega transactions concentrating among platform integrators, with medium deals proliferating in cyber and space subsystems where margin pools exceed hardware commoditization curves.
The US Department of Defense, the UK's Competition and Markets Authority, and France's Direction Générale de l'Armement collectively shape transaction feasibility through foreign ownership thresholds, national security reviews, and offset requirements that extend due diligence timelines. CMMC compliance mandates from the Pentagon now function as pre-qualification filters that eliminate uncertified targets from strategic buyer consideration sets. Stakeholders must monitor how AUKUS technology-sharing protocols reshape cross-border target eligibility before committing capital to transatlantic consolidation plays.
Market Dynamics
CMMC compliance mandates from the Pentagon now eliminate uncertified targets from strategic buyer consideration sets, compressing the addressable universe for defense technology acquisitions and elevating cleared assets to premium valuations.
Growth Catalysts
- Hypersonic test infrastructure:NATO members accelerate capital deployment into shared ground test facilities and wind tunnels, creating pooled demand for specialized engineering firms with cleared personnel rosters.
- CMMC 2.0 framework:The Pentagon's tiered cybersecurity certification creates acquisition premiums for Level 3-compliant entities, rewarding early compliance investments with strategic buyer access.
- Foreign military sales channels:The State Department's streamlined Direct Commercial Sales approvals enable faster technology transfer timelines, expanding the viable target pool for subsystem exporters.
Market Restraints
- Titanium and superalloy input volatility:Russian-sourced sponge titanium disruptions force primes to absorb 18-24 month qualification cycles for alternative suppliers, inflating working capital requirements.
- ITAR-controlled asset migration friction:State Department licensing timelines extend integration planning horizons, compressing synergy realization windows and elevating execution risk premiums.
- Single-source sensor dependencies:Gallium arsenide and indium phosphide substrate concentration in East Asian foundries exposes electronic warfare subsystem suppliers to export control cascade risks.
Strategic Opportunities
- UK sovereign satellite constellations:The Ministry of Defence's ISTARI program generates first-mover advantages for domestic payload integrators with end-to-end encryption capabilities.
- AUKUS technology-sharing protocols:Trilateral submarine and hypersonic collaboration creates cross-border joint venture structures previously blocked by bilateral ITAR constraints.
- AI-enabled predictive maintenance:Convergence of machine learning with legacy platform telemetry streams opens aftermarket revenue pools exceeding original equipment margins for avionics retrofit specialists.
Industry Challenges
- Cleared engineering talent scarcity:SCI-level clearance processing backlogs exceed 14 months, constraining target evaluation teams and post-close integration velocity.
- Legacy platform code base integration:1970s-era avionics architectures resist modular software insertion, forcing expensive hardware-software co-design cycles that erode deal synergies.
- Facility security accreditation timelines:SCIF construction and DSS approval cycles extend 18-24 months, delaying revenue recognition from acquired classified contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mergers and Acquisitions (Manda) in Aerospace and Defense Market |
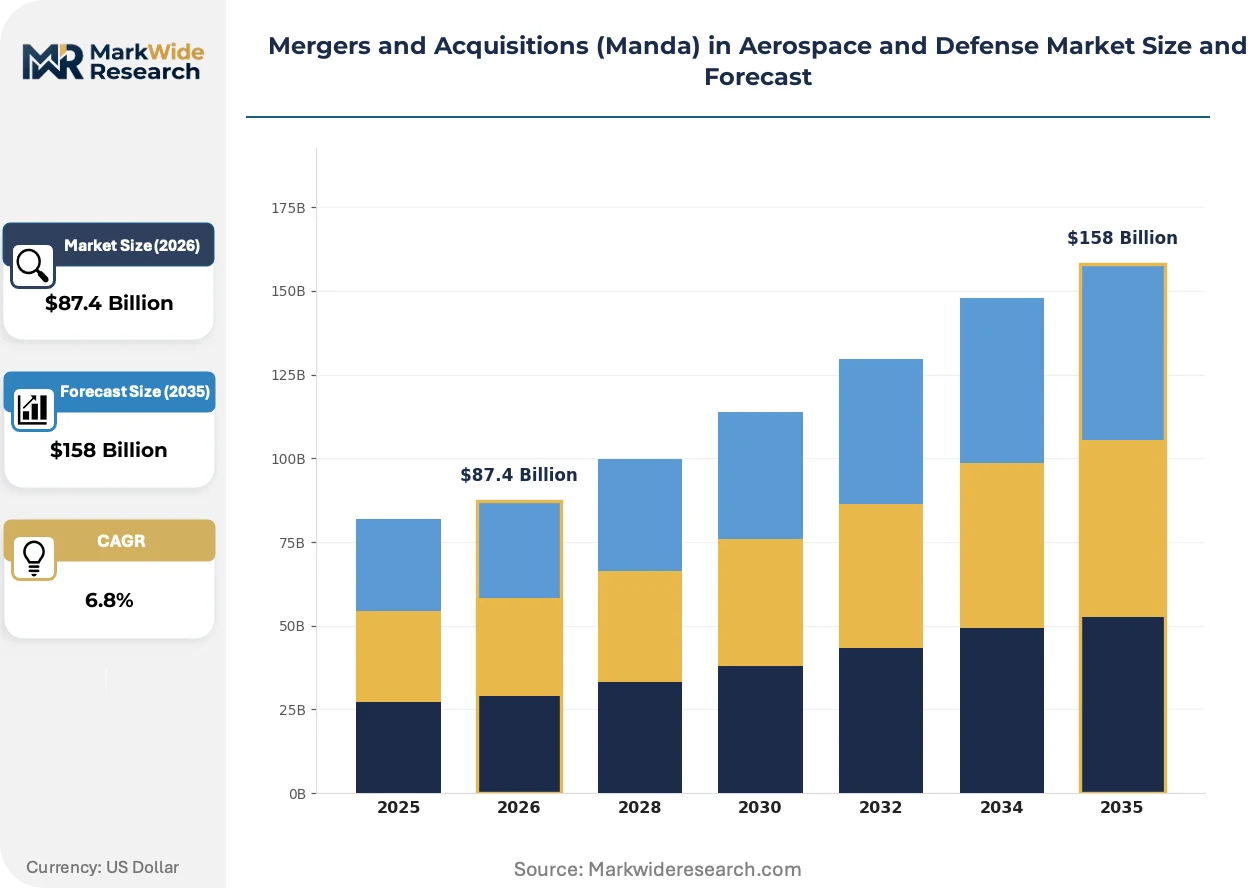
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transaction Type: Acquisition, Merger, Joint Venture, Divestiture Deal Size: Small, Medium, Large, Mega Buyer Type: Strategic Buyer, Financial Buyer, Government Agency, Consortium Target Sector: Defense Contractors, Aerospace Manufacturers, Technology Providers, Support Services |
| Companies Covered | Parker Hannifin Corporation, The Boeing Company, Airbus SE, RTX Corporation, BAE Systems, L3Harris Technologies, Lockheed Martin, Northrop Grumman, Thales, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mergers and Acquisitions (Manda) in Aerospace and Defense Market Shifts & Advancements
Digital engineering environments now compress design iteration cycles while regulatory fragmentation across NATO allies complicates cross-border asset migration. These forces reshape how acquirers value intellectual property and cleared infrastructure.
Model-based systems engineering is digitizing requirements traceability across the acquisition lifecycle. The Navy's Digital Twin initiative mandates physics-based simulation for all new platform proposals, forcing legacy drawing-based suppliers into expensive capability builds. Primes now prioritize targets with existing digital thread architectures that accelerate contract transition timelines.
France's Direction Générale de l'Armement imposes escalating local content thresholds through its Loi de Programmation Militaire, requiring foreign acquirers to maintain sovereign engineering headcount. This policy redirects transatlantic deal flow toward joint venture structures rather than outright asset purchases. Electronic warfare and space subsystem categories face the steepest offset escalation curves.
Defense procurement offices now unbundle long-term sustainment contracts from initial platform awards, creating standalone service revenue pools that exceed hardware margins. The Pentagon's Performance-Based Logistics mandates require contractors to assume availability risk, shifting valuation models toward predictive maintenance capabilities. This pattern concentrates in rotorcraft and maritime patrol segments where operating cost guarantees dominate source selection criteria.
Mergers and Acquisitions (Manda) in Aerospace and Defense Market Segmentation
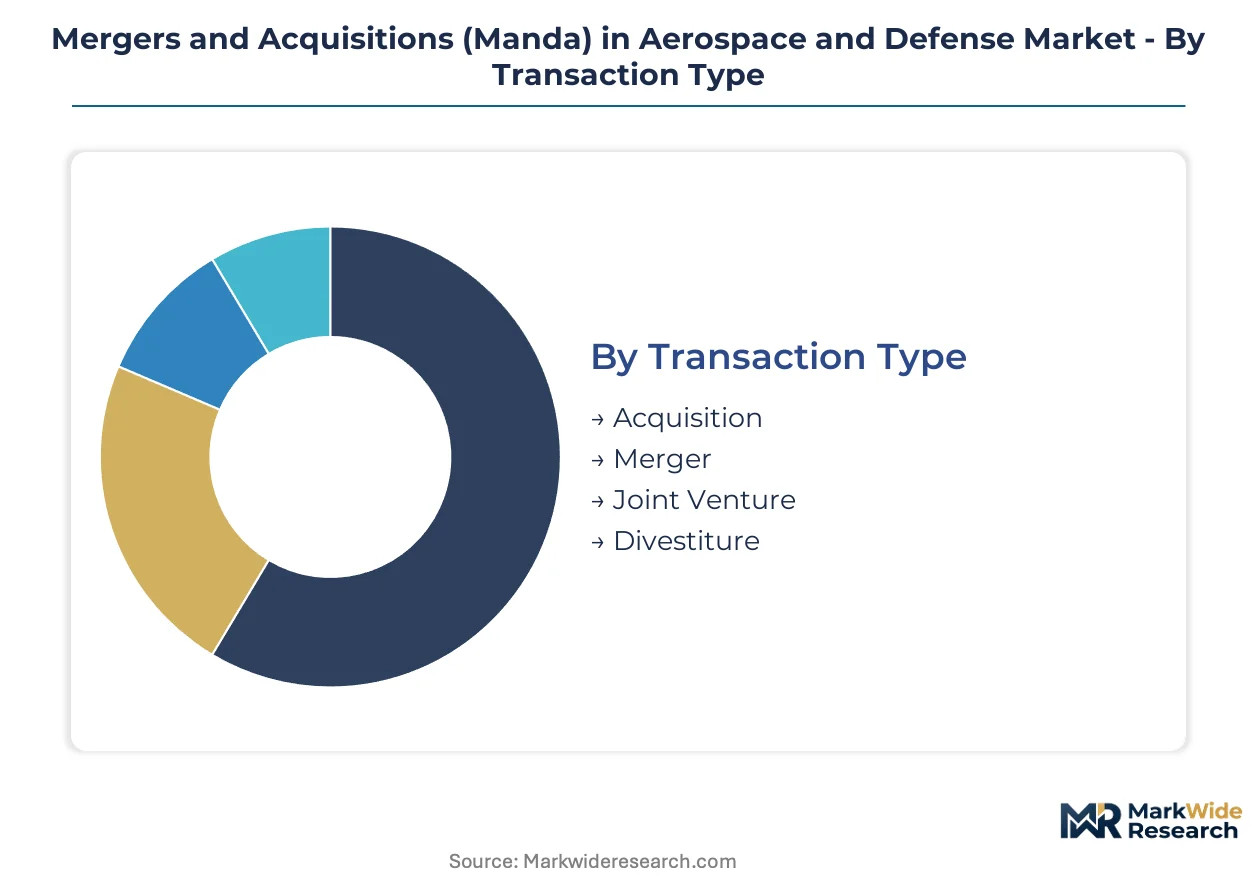
Transaction velocity varies dramatically across M&A categories in aerospace and defense. Deal timelines stretch from weeks for small divestitures to years for mega mergers requiring multi-jurisdictional security reviews.
Transaction Type:
Cycle times compress from years for complex mergers to months for targeted acquisitions, with joint ventures occupying the middle ground where risk-sharing negotiations extend structuring phases.
- Acquisition:Dominates flow volume as primes absorb niche technology holders with cleared personnel rosters. The Pentagon's CMMC 2.0 framework accelerates due diligence for targets with existing Level 3 compliance, compressing closing timelines for cyber and space subsystem purchases.
- Joint Venture:Expands in satellite constellations and hypersonic test facilities where sole investment risk exceeds balance sheet tolerance. AUKUS technology-sharing protocols now enable trilateral structures previously blocked by bilateral ITAR constraints, opening cross-border collaboration in submarine and advanced propulsion domains.
- Merger:Concentrates among platform integrators seeking manufacturing scale and overlapping government contracting access. These transactions face extended timelines from security clearance transfer requirements and facility SCIF accreditation cycles.
- Divestiture:Accelerates as primes shed non-core manufacturing assets to fund digital capability builds. The Navy's Digital Twin initiative pressures legacy drawing-based suppliers into portfolio rationalization.
Acquisitions dominate installed base. Joint ventures are where expansion concentrates.
Deal Size:
Cost tiers stratify sharply, with mega transactions commanding dedicated integration teams and small deals flowing through standardized playbooks.
- Mega:Concentrate among platform integrators pursuing transformational scale. These transactions trigger mandatory CFIUS reviews and extended foreign ownership threshold negotiations across NATO regulatory regimes.
- Large:Cluster in electronic warfare and space subsystems where margin pools exceed hardware commoditization curves. France's Direction Générale de l'Armement imposes escalating local content thresholds, redirecting deal flow toward joint venture structures.
- Medium:Proliferate in cyber and autonomous systems where technology refresh cycles outpace organic development timelines. CMMC compliance premiums elevate valuations for cleared assets.
- Small:Capture specialized engineering firms with SCI-cleared personnel rosters, addressing the talent scarcity constraining target evaluation velocity. Processing backlogs exceed 14 months for new clearance applications.
Mega transactions anchor prime consolidation. Medium deals are climbing the fastest.
Buyer Type:
Customer type determines access to classified contract pipelines and preferred vendor status in defense procurement.
- Strategic Buyer:Primes leverage existing security infrastructure to accelerate post-close integration. These acquirers prioritize targets with digital thread architectures that compress contract transition timelines under the Navy's Digital Twin initiative.
- Financial Buyer:Private equity firms with cleared operating partners target aftermarket service revenue pools unbundled from initial platform awards. Performance-Based Logistics mandates shift valuation models toward predictive maintenance capabilities.
- Government Agency:Sovereign wealth and defense ministry investment vehicles concentrate in UK satellite constellations and hypersonic ground test facilities. The Ministry of Defence's ISTARI program generates first-mover advantages for domestic payload integrators.
- Consortium:Multi-party structures emerge where AUKUS protocols enable pooled capital deployment into trilateral submarine and hypersonic collaboration. These arrangements distribute ITAR compliance burden across national boundaries.
Strategic buyers dominate transaction volume. Consortium structures are gaining share fastest.
Target Sector:
Supply concentration varies dramatically, with technology providers facing foundry dependencies and support services offering distributed execution models.
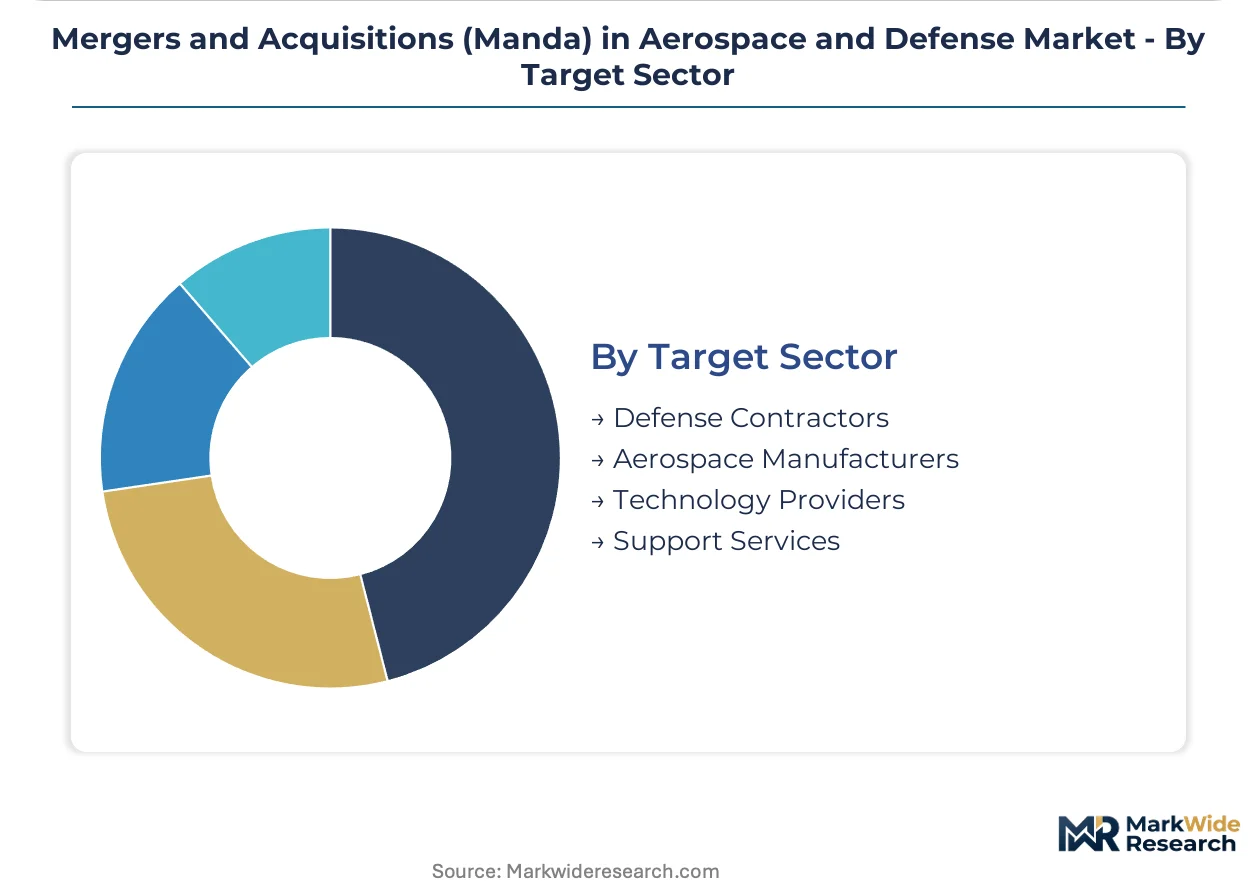
- Defense Contractors:Prime targets carry multi-year backlog visibility and established source selection relationships. Titanium and superalloy input volatility forces extended supplier qualification cycles, inflating working capital requirements.
- Aerospace Manufacturers:Commercial aviation footprints sustain defense-adjacent manufacturing scale. These assets face pressure from Russian-sourced sponge titanium disruptions and 18-24 month alternative supplier qualification timelines.
- Technology Providers:AI-enabled predictive maintenance capabilities open aftermarket revenue pools exceeding original equipment margins. Gallium arsenide substrate concentration in East Asian foundries exposes electronic warfare suppliers to export control cascade risks.
- Support Services:Cleared engineering talent scarcity elevates valuations for firms with existing SCI-level personnel rosters. Facility security accreditation timelines extend 18-24 months for SCIF construction and DSS approval.
Defense contractors dominate installed base. Technology providers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Strategic buyers concentrate deal flow in the United States, the United Kingdom, France, Germany, and Japan, where defense procurement scale and security clearance infrastructure create acquisition premiums for cleared assets.
United States
The Pentagon's budget trajectory and foreign military sales channels sustain platform and subsystem deal flow. CMMC 2.0 compliance mandates from the Department of Defense eliminate uncertified targets from buyer consideration sets. Greater Washington DC and California's aerospace corridor concentrate cleared engineering talent pools that accelerate post-close integration velocity.
United Kingdom
The Ministry of Defence's ISTARI satellite program generates first-mover advantages for domestic payload integrators with end-to-end encryption capabilities. The Competition and Markets Authority shapes transaction feasibility through foreign ownership thresholds and national security reviews. BAE Systems anchors sovereign facility networks across transatlantic electronic warfare niches.
France
The Direction Générale de l'Armement imposes escalating local content thresholds through the Loi de Programmation Militaire, redirecting transatlantic deal flow toward joint venture structures. Electronic warfare and space subsystem categories face the steepest offset escalation curves. The Île-de-France region concentrates prime contractor headquarters and classified engineering facilities.
Germany
Rheinmetall and Hensoldt drive consolidation in ground systems and sensor architectures as NATO military modernization accelerates. The Federal Cartel Office reviews transactions against European defense industrial base consolidation criteria. Bavaria and Baden-Württemberg host specialized engineering clusters with ITAR-compliant manufacturing infrastructure.
Japan
METI's defense equipment export guidelines reshape cross-border target eligibility for primes seeking trilateral collaboration frameworks. The relaxation of arms export principles enables joint venture structures in satellite constellations and hypersonic test facilities. The Kanto region around Tokyo concentrates cleared personnel rosters and SCIF-accredited facilities.
Mergers and Acquisitions (Manda) in Aerospace and Defense Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered acquisition categories. Platform integrators dominate mega-transactions through manufacturing scale and overlapping government contracting access. Cyber and space subsystem specialists command medium-deal premiums where margin pools exceed hardware commoditization curves. Primes absorb niche technology holders to secure cleared personnel rosters, while joint ventures expand where sole investment risk exceeds balance sheet tolerance.
Among US-based primes, The Boeing Company, Lockheed Martin, and Northrop Grumman exemplify the channel-controlling archetype through vertically secured supply chains and classified program execution capabilities. These entities occupy positions that reward early CMMC compliance investments with strategic buyer access to cleared assets. BAE Systems represents the transatlantic specialist model with sovereign facility networks spanning electronic warfare niches. RTX Corporation and L3Harris Technologies sit within the subsystem consolidation tier where technology refresh cycles outpace organic development timelines.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| The Boeing Company |
| Airbus SE |
| RTX Corporation |
| BAE Systems |
| L3Harris Technologies |
| Lockheed Martin |
| Northrop Grumman |
| Thales |
| Others |
Supply & Pricing Matrix
Russian-sourced sponge titanium disruptions determine both pricing tier spreads and supply chain shape across aerospace and defense manufacturing, forcing primes to absorb extended qualification cycles for alternative suppliers while elevating cleared, ITAR-compliant assets to premium valuations. CMMC certification tiers now stratify acquisition costs, with Level 3-compliant entities commanding substantial premiums over uncertified competitors eliminated from Pentagon consideration sets.
Pricing Analysis
Cost-plus contracts with Economic Price Adjustment clauses indexed to Producer Price Index for aerospace materials dominate prime-subcontractor relationships, embedding inflation pass-through mechanisms that protect margins against titanium and superalloy volatility. Price differentiation hinges on cybersecurity certification grade and security clearance infrastructure density, with SCI-cleared engineering rosters attracting strategic buyer premiums. Cost compression in non-compliant tiers is intensifying because CMMC 2.0 mandates filter uncertified targets from addressable buyer pools. Defense agencies exhibit lowest price sensitivity for mission-critical subsystems, while commercial aerospace adjacencies face sharper procurement scrutiny.
Supply Chain Analysis
Contract manufacturing concentration rests on specialized foundries in Taiwan, South Korea, and the United States for gallium arsenide and indium phosphide substrates essential to electronic warfare systems. Raw material dependencies draw from Russian titanium sponge, Chinese rare earth processing, and Japanese precision components. Single-source vulnerability in East Asian semiconductor foundries exposes subsystem suppliers to export control cascade risks. Distribution runs through prime contractor tiered supplier networks with DSS-accredited facility requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a cyclical recovery phase driven by NATO military modernization programs, with procurement backlogs extending visibility for cleared contractors while supply chain reconfigurations create acquisition windows for assets with alternative supplier qualifications.
For Market Incumbents: Pre-empt CMMC compliance gaps by accelerating Level 3 certification investments ahead of mandatory implementation timelines, securing strategic buyer access before uncertified competitors face exclusion. Absorb niche technology holders with existing cleared personnel rosters to address SCI-level clearance processing backlogs exceeding fourteen months, consolidating talent scarcity advantages.
For New Entrants and Emerging Players: Build out digital thread architectures aligned with the Navy's Digital Twin initiative, targeting legacy drawing-based suppliers pressured into portfolio rationalization. Focus initial penetration on AI-enabled predictive maintenance for rotorcraft and maritime patrol segments where Performance-Based Logistics mandates shift valuation toward availability guarantees rather than hardware margins.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors subsystem specialists with CMMC pre-certification and established foreign military sales channels, positioning for premium exit multiples as primes absorb technology refresh capabilities. Monitor AUKUS technology-sharing protocol implementations as the inflection indicator for cross-border joint venture feasibility previously blocked by bilateral ITAR constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| CMMC Level 3 Certification Investment | Pentagon compliance mandates now eliminate uncertified targets from strategic buyer consideration sets entirely. |
| Cleared Personnel Roster Acquisition | SCI-level clearance processing backlogs exceeding fourteen months create scarcity premiums for existing cleared engineering teams. |
| Digital Thread Architecture Buildout | Navy Digital Twin initiative mandates physics-based simulation for all new platform proposal submissions. |
| AUKUS Joint Venture Structuring | Trilateral technology-sharing protocols enable cross-border collaboration previously blocked by bilateral ITAR constraints. |
| Predictive Maintenance Capability Integration | Performance-Based Logistics mandates shift contractor risk profiles toward availability guarantees exceeding original equipment margins. |
Research Methodology
The analysis maps platform integrators, cyber and space subsystem specialists, electronic warfare niche players, and cleared support services providers, each validated through program management executives at prime contractors, government contracting officers, security clearance processing specialists, and M&A advisory leads at defense-focused investment banks. Secondary sources include Pentagon budget justification documents, State Department Direct Commercial Sales approval records, CMMC accreditation registries, and NATO procurement announcements. Bottom-up transaction tallies triangulate against top-down defense expenditure allocations.
Assumptions held fixed include current NATO military modernization funding trajectories and existing ITAR regulatory frameworks, while variables span AUKUS protocol implementation pace and CMMC enforcement stringency. Segmentation dimensions encompass transaction type, deal size tier, buyer archetype, and target sector specialization across the projection horizon. CAGRs derive from regression analysis against historical deal flow patterns and procurement cycle timing. Forecast inputs incorporate foreign military sales channel velocity and cleared engineering talent pipeline constraints.
Sensitivities concentrate around export control expansion to additional technology categories and titanium supplier qualification timeline extensions. Forecasts reflect documented assumptions regarding regulatory continuity and alliance cohesion. Quarterly review of CMMC accreditation velocity and AUKUS implementation milestones is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Land-Based Smart Weapons Market
Defense and Military Systems and Equipment
Global Battlefield Management System Market
Defense and Military Systems and Equipment
Network Centric Warfare (NCW) Market
Defense and Military Systems and Equipment
Military Parachute Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal Market
Defense and Military Systems and Equipment
Command and Control Systems Market
Defense and Military Systems and Equipment
Military Embedded System Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Display Systems Market
Defense and Military Systems and Equipment
Military Aerospace and Defense Lifecycle Management Market
Defense and Military Systems and Equipment
Military High Altitude Radio Jamming System Market
Defense and Military Systems and Equipment
Airborne Electronic Warfare Market
Defense and Military Systems and Equipment
Anti-Drone Guns Market
Defense and Military Systems and Equipment
Mechanical and Electronic Fuzes Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal (EOD) Equipment Market
Defense and Military Systems and Equipment
Europe Defense Logistics Market
Defense and Military Systems and Equipment
Europe Missiles and Missile Defense Systems Market