
 Military Test Equipment Market | 2026-2036
Military Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Military Test Equipment Market Foresight
A shortage of RF engineering specialists is reorganizing how prime contractors structure their test equipment supply chains. Keysight Technologies leverages its software-defined instrumentation portfolio to capture advanced signal analysis contracts. Rohde & Schwarz anchors European demand through its deep calibration and measurement heritage. Teledyne Technologies competes by sustaining dense investment in ruggedized portable diagnostics for field-deployed forces.
Military test equipment comprises precision instruments engineered to verify, validate, and troubleshoot defense systems under operational conditions, typically operating across frequency ranges from DC to millimeter-wave bands and meeting shock/vibration specifications per MIL-STD-810. These systems ensure mission readiness by certifying avionics, communications, radar, and electronic warfare subsystems before deployment. Measurement equipment dominates current procurement budgets due to obsolescence-driven replacement of legacy analog suites. Software-defined technology is capturing the fastest expansion as programmable architectures reduce hardware refresh cycles and enable remote firmware updates. Portable units command premium positioning where expeditionary forces require rapid-deploy diagnostic capability outside fixed base infrastructure.
FAA airworthiness directives and DoD MIL-STD-461G electromagnetic compatibility standards shape product design requirements, forcing manufacturers to embed shielding and filtering architectures that extend development timelines. NIST traceability mandates and ISO/IEC 17025 accreditation requirements govern calibration service revenue streams, creating recurring revenue dependencies for incumbent suppliers. Stakeholders must monitor how export control revisions under ITAR and EAR classifications reshape cross-border technology transfer permissions for software-defined test platforms.
Market Dynamics
Defense procurement cycles are compressing as MIL-STD-461G electromagnetic compatibility mandates force premature retirement of analog test suites that cannot accommodate firmware-defined reconfiguration. This regulatory pressure is restructuring supplier relationships around software-centric instrumentation portfolios.
Growth Catalysts
- Electronic warfare modernization:Bundeswehr programs in Germany are driving sustained investment in RF signal analysis systems for radar and communications validation.
- MIL-STD compliance mandates:Updated Department of Defense requirements are accelerating replacement cycles for legacy analog equipment across fixed and expeditionary installations.
- Software-defined architectures:Programmable test platforms reduce hardware refresh cycles and enable remote firmware updates, extending operational lifespans in field-deployed conditions.
Market Restraints
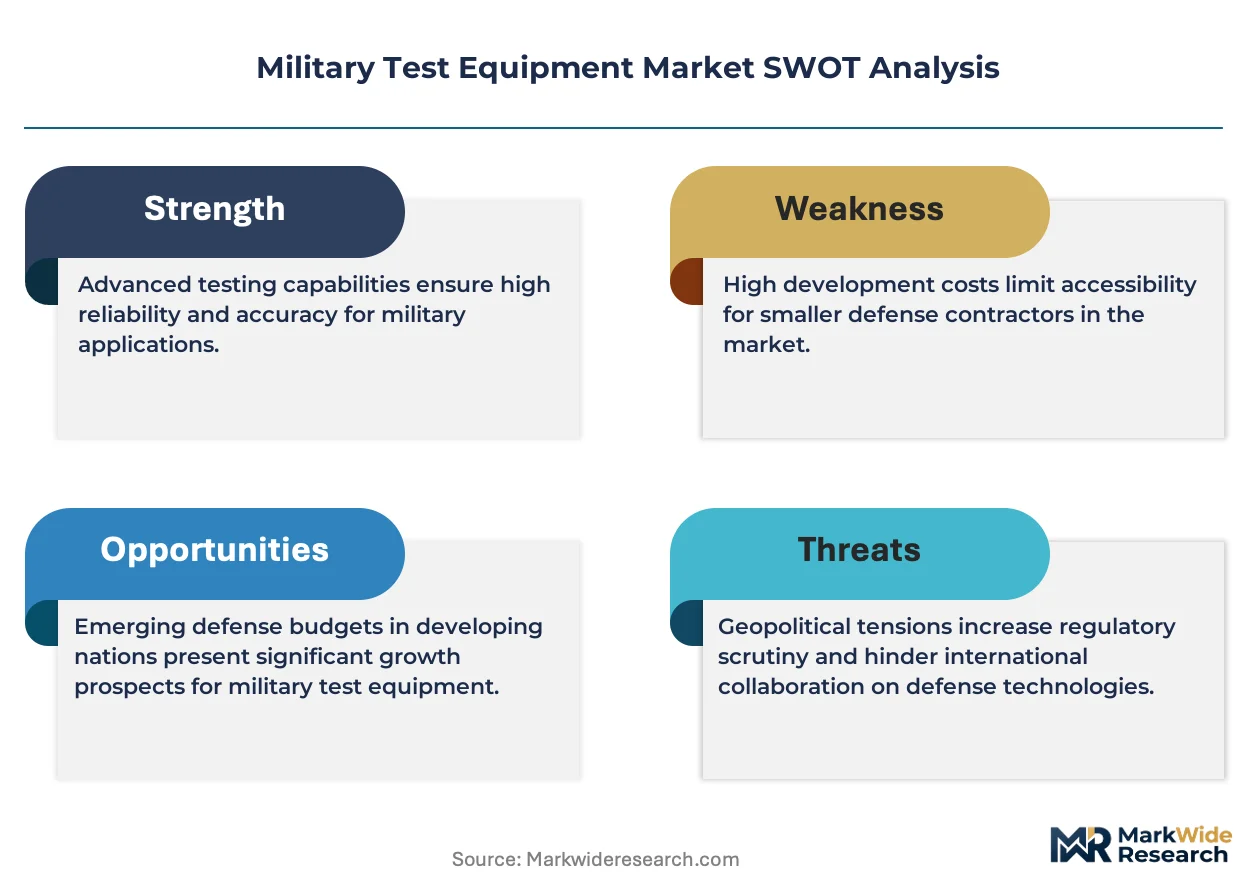
- RF engineering talent scarcity:Prime contractors face structural shortages of millimeter-wave design specialists, forcing reliance on concentrated supplier networks.
- Calibration infrastructure concentration:NIST traceability requirements create recurring revenue dependencies that lock buyers into incumbent supplier relationships.
- ITAR classification friction:Export control revisions under EAR classifications reshape cross-border technology transfer permissions for software-defined platforms.
Strategic Opportunities
- Expeditionary portable diagnostics:Rapid-deploy diagnostic capability outside fixed base infrastructure commands premium positioning among expeditionary forces.
- Remote firmware distribution channels:Over-the-air update capabilities create new service revenue streams independent of physical hardware shipments.
- European calibration services:Rohde & Schwarz production anchoring in Germany enables regional service density that US suppliers struggle to replicate.
Industry Challenges
- Legacy system integration complexity:Analog-to-digital test bed transitions require custom interface development that extends deployment timelines.
- ISO/IEC 17025 accreditation timelines:Calibration service expansion demands lengthy laboratory certification processes that constrain geographic coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Test Equipment Market |
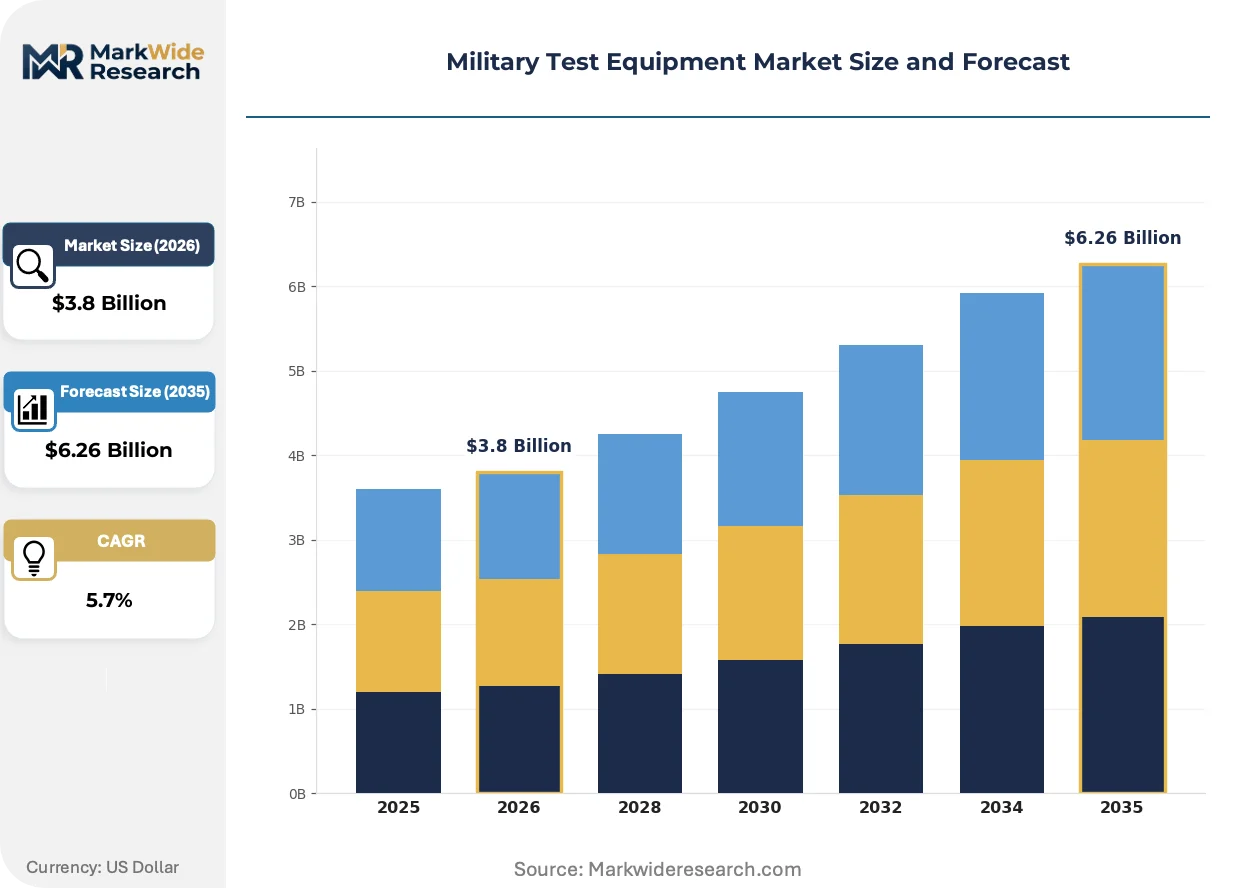
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Measurement Equipment, Simulation Tools, Calibration Devices, Diagnostic Instruments Technology: Analog, Digital, RF, Software-Defined End User: Defense Contractors, Government Agencies, Military Organizations, Research Institutions Installation: Portable Units, Fixed Installations, Onboard Systems, Mobile Testing Stations |
| Companies Covered | Raytheon, Northrop Grumman, Keysight Technologies, CACI International, United Technologies, AMETEK, Teledyne Technologies, Rohde & Schwarz, National Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Test Equipment Market Shifts & Advancements
Instrumentation architectures are fragmenting as programmable logic displaces fixed-function hardware, while electromagnetic compatibility standards harden certification requirements. Buyers are reconfiguring procurement models around capability delivery rather than asset ownership.
Software-defined radio test sets are decomposing traditional hardware-bound measurement workflows into modular, firmware-upgradable components. Naval aviation maintenance units are adopting these platforms fastest, replacing discrete spectrum analyzers with reconfigurable baseband processors. This decomposition is compressing supplier margins on standalone hardware while expanding recurring software license revenue.
FAA airworthiness directives and DoD MIL-STD-810 shock specifications are embedding shielding and filtering architectures that extend development timelines. Manufacturers must now prototype electromagnetic hardening earlier in design cycles, raising non-recurring engineering costs. Avionics test segments absorb these impacts most acutely, with certification-driven redesigns consuming 18-24 month qualification windows.
Service contract unbundling is separating calibration and repair functions from original equipment purchases. Defense maintenance depots now source measurement traceability from third-party laboratories, bypassing manufacturer service networks. This pattern concentrates in Germany and the United States, where independent metrology providers have achieved NIST-equivalent accreditation density.
Military Test Equipment Market Segmentation
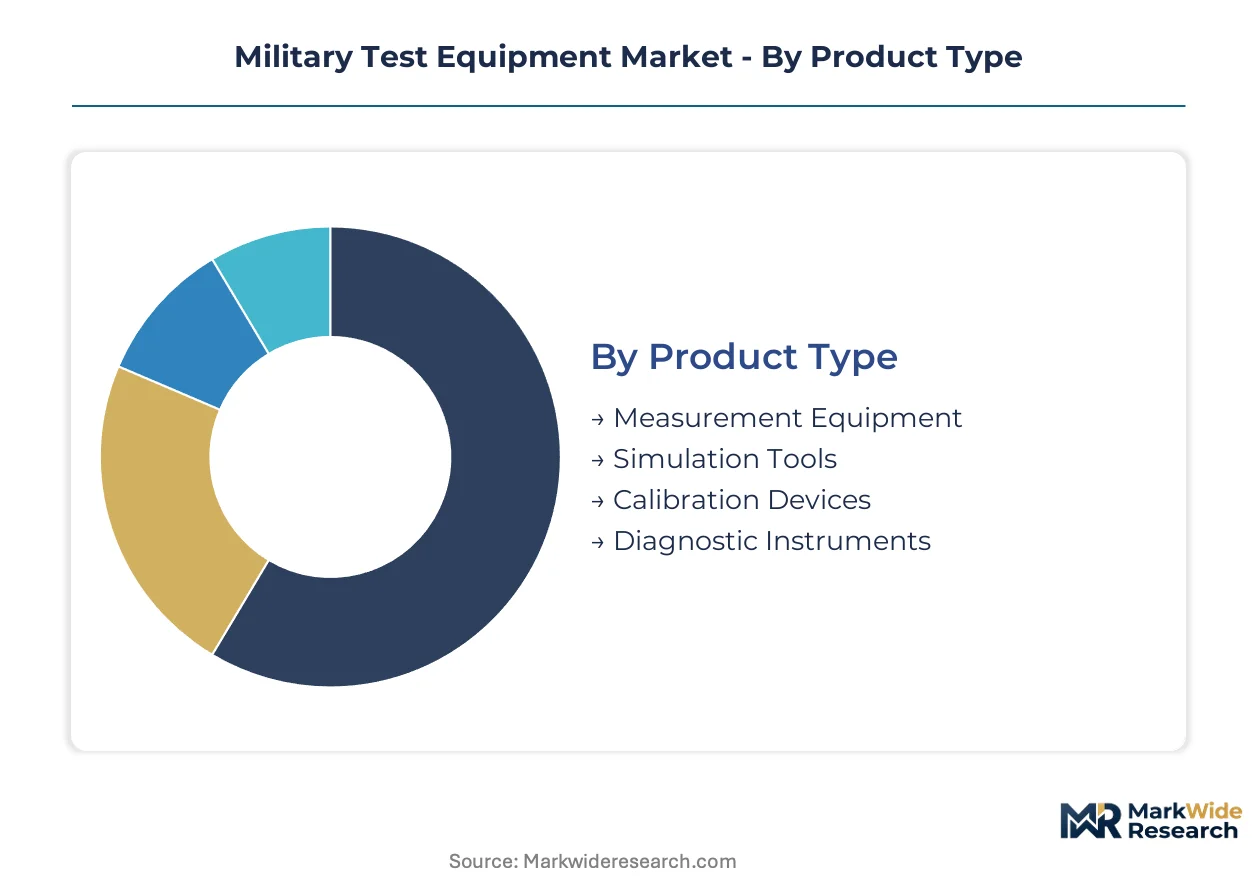
Segmentation in military test equipment reveals how procurement priorities split across regulatory compliance burdens, operational deployment modes, and technology refresh cycles. Understanding these divisions clarifies where defense budgets concentrate and which supplier capabilities command premium positioning.
Product Type:
MIL-STD-461G electromagnetic compatibility mandates and FAA airworthiness directives impose divergent certification burdens across instrument categories, reshaping supplier investment priorities.
- Measurement Equipment:Precision instruments operating across DC to millimeter-wave bands verify avionics, radar, and communications subsystem performance. Procurement concentrates in fixed-base installations across the United States and Germany where Bundeswehr and Department of Defense modernization programs drive obsolescence-driven replacement of legacy analog suites.
- Simulation Tools:Hardware-in-the-loop and software-in-the-loop platforms replicate operational electromagnetic environments for pre-deployment validation. Demand clusters with defense contractors in the United States developing electronic warfare countermeasures under compressed procurement cycles.
- Calibration Devices:NIST-traceable standards ensure measurement integrity across distributed maintenance networks.
- Diagnostic Instruments:Field-portable troubleshooting systems support expeditionary force readiness outside fixed infrastructure.
Measurement Equipment handles the majority of throughput; Simulation Tools is the fastest mover on share.
Technology:
Cost tier differentiation separates legacy sustainment investments from next-generation procurement, with firmware-upgradable architectures commanding substantial price premiums over fixed-function hardware.
- Software-Defined:Programmable architectures enable remote firmware updates and reduce hardware refresh cycles through reconfigurable baseband processing. Naval aviation maintenance units in the United States adopt these platforms fastest, replacing discrete spectrum analyzers with modular components that compress standalone hardware margins while expanding recurring software license revenue.
- RF:Millimeter-wave signal analysis systems address electronic warfare and radar validation requirements. Procurement concentrates in Germany where Rohde & Schwarz anchors regional production and deep calibration heritage supports sustained Bundeswehr investment.
- Digital:Precision data acquisition platforms with embedded processing for automated test sequences.
- Analog:Legacy instrumentation facing premature retirement under updated MIL-STD compliance mandates.
Software-Defined captures the steepest expansion trajectory; RF maintains the largest installed base requiring sustainment.
End User:
Customer type determines contract structure, with defense contractors favoring capability-as-a-service models while government agencies prioritize asset ownership and long-term calibration lock-in.
- Defense Contractors:Prime contractors and subsystem suppliers procure test suites for design verification and production acceptance. Structural shortages of RF engineering specialists in the United States force reliance on concentrated supplier networks, accelerating software-defined adoption to reduce in-house hardware maintenance burdens.
- Military Organizations:Service branches and expeditionary units demand ruggedized portable diagnostics for field-deployed conditions. Investment concentrates in rapid-deploy capability outside fixed base infrastructure where premium positioning reflects operational criticality.
- Government Agencies:National laboratories and test ranges require highest-precision reference standards.
- Research Institutions:Academic and defense research centers source flexible platforms for prototype validation.
Defense Contractors dominate procurement volume; Military Organizations is gaining share fastest through expeditionary modernization priorities.
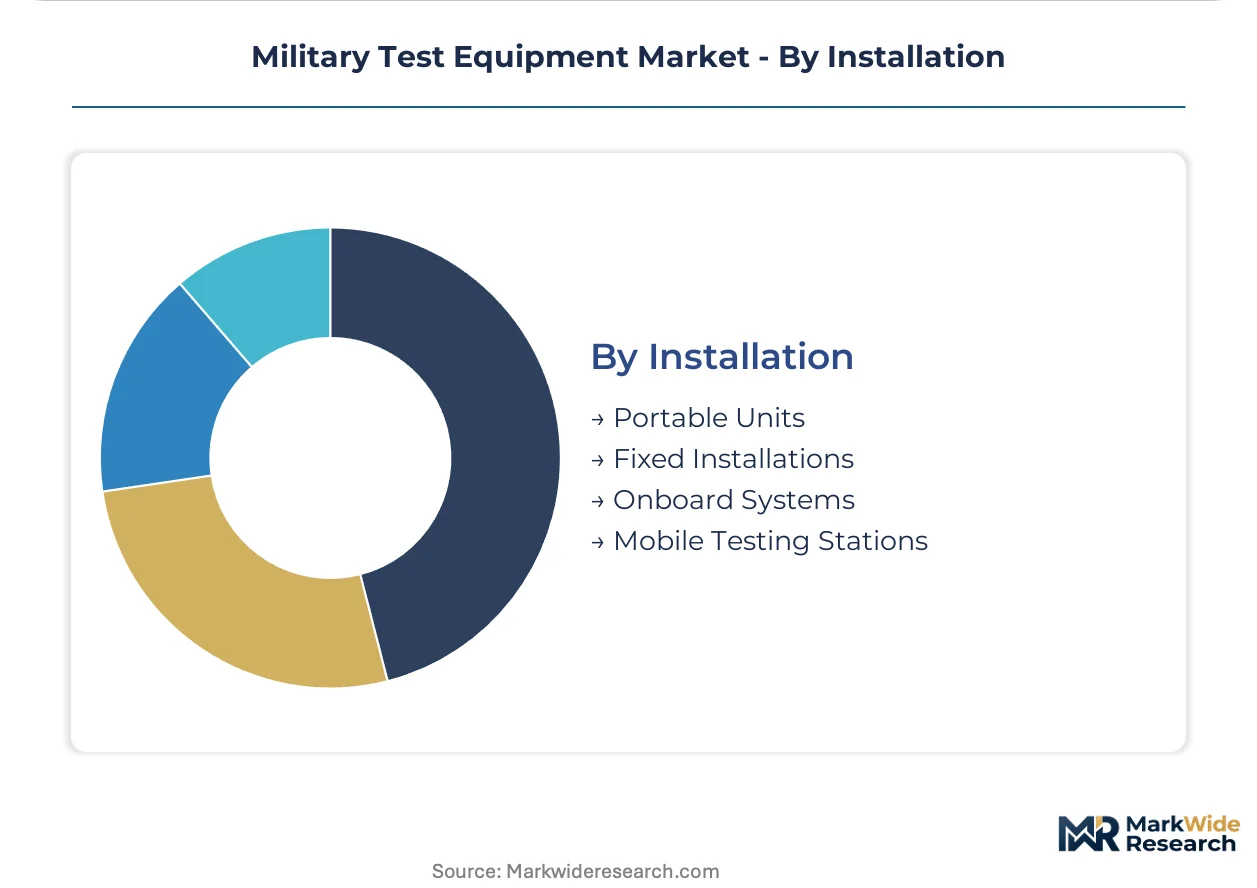
Installation:
Deployment mode dictates environmental hardening requirements, with portable and onboard systems absorbing disproportionate development costs from MIL-STD-810 shock and vibration specifications.
- Portable Units:Battery-operated or vehicle-transportable diagnostics for expeditionary maintenance outside fixed infrastructure. FAA airworthiness directives and DoD shock specifications embed shielding and filtering architectures that extend development timelines and raise non-recurring engineering costs, particularly for avionics test segments.
- Fixed Installations:Permanent test beds in depots, laboratories, and production facilities. These systems face accelerating replacement cycles as MIL-STD-461G mandates force retirement of analog equipment that cannot accommodate firmware-defined reconfiguration.
- Onboard Systems:Integrated flight-line or vehicle-embedded diagnostics for immediate fault isolation.
- Mobile Testing Stations:Containerized or vehicle-mounted laboratories for forward-deployed sustainment.
Fixed Installations account for the largest revenue base; Portable Units is expanding most quickly through expeditionary force restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Department of Defense procurement mandates from the FAA and MIL-STD frameworks anchor demand concentration. Defense contractors across multiple geographies respond to these compliance pressures with differentiated regional strategies.
United States
Naval aviation maintenance units drive software-defined test platform adoption for reconfigurable baseband processing. FAA airworthiness directives and DoD MIL-STD-810 specifications impose shielding and filtering requirements that extend development timelines. California and Maryland host concentrated defense contractor clusters where electronic warfare countermeasure development accelerates procurement cycles.
Germany
Bundeswehr modernization programs sustain investment in RF signal analysis systems for radar validation. The country's national defense procurement office aligns requirements with EU defense industrial strategy frameworks. Bavaria anchors regional production density where deep calibration heritage supports sustained military investment.
United Kingdom
Royal Air Force and Royal Navy expeditionary force restructuring prioritizes portable diagnostic capability outside fixed infrastructure. The UK's national aerospace regulator enforces electromagnetic compatibility standards aligned with MIL-STD-461G. Southwest England hosts avionics test engineering clusters where certification-driven redesigns consume extended qualification windows.
Japan
Ministry of Defense electronic warfare modernization drives millimeter-wave test system procurement. METI industrial standards govern measurement traceability requirements for defense subcontractor networks. Tokyo-Osaka corridor concentrates prime contractor engineering facilities where RF specialist scarcity forces supplier network reliance.
Israel
Defense research institutions source flexible platforms for prototype validation and electronic warfare system development. The country's national security export control framework shapes technology transfer permissions for software-defined architectures. Tel Aviv metropolitan area hosts dense startup-to-prime contractor ecosystems where rapid-deploy diagnostic innovation commands premium positioning.
Military Test Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the military test equipment sector. The vendor base separates into three tiers: diversified defense conglomerates with systems integration scale, specialized measurement technology firms with calibration heritage, and modular software-defined platform developers. Consolidation pressure concentrates around software-centric instrumentation portfolios. Competitive moves center on strategic partnerships for firmware distribution channels and geographic expansion of NIST-traceable calibration service networks.
Among diversified defense conglomerates, Raytheon and Northrop Grumman exemplify systems integration scale that spans test equipment through full mission system delivery. Specialized measurement technology is represented by Keysight Technologies, which occupies a position within the software-defined instrumentation archetype. These three anchors illustrate how supplier relationships reorganize around concentrated capability networks rather than distributed procurement.
| Leading Market Players |
|---|
| Raytheon |
| Northrop Grumman |
| Keysight Technologies |
| CACI International |
| United Technologies |
| AMETEK |
| Teledyne Technologies |
| Rohde & Schwarz |
| National Instruments |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four-month qualification windows for avionics test segments concentrate supply-side leverage with incumbent calibration laboratories, compressing buyer negotiation room while elevating premiums for NIST-traceable service bundles. This lead-time rigidity anchors pricing power in Germany and the United States where accreditation density locks defense maintenance depots into recurring revenue relationships.
Pricing Analysis
Geographic price spreads of 15-25 percent separate German calibration service premiums from US-based third-party laboratory rates, reflecting Rohde & Schwarz's regional production anchoring against distributed American metrology competition. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with MIL-STD-461G-compliant instruments commanding top-tier positioning. Pricing pressure stems from software-defined platform commoditization as firmware-upgradable architectures displace discrete hardware margins. Defense contractors exhibit highest price sensitivity due to compressed procurement cycles, while government agencies accept premium positioning for long-term calibration lock-in.
Supply Chain Analysis
Strategic stockpiling of millimeter-wave components and shielding materials dominates inventory strategy, displacing just-in-time preferences given single-source vulnerabilities in RF semiconductor foundries. Manufacturing concentrates in the United States, Germany, and Japan where defense-industrial base protections sustain domestic production. Supply chains draw from gallium nitride substrates, precision machined enclosures, and programmable logic devices as critical inputs. Tariff exposure on Chinese-sourced rare earth elements for magnetic shielding constitutes primary structural risk. Distribution runs through authorized defense contractor channels with ITAR-controlled logistics networks limiting parallel import pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are restructuring military test equipment procurement around firmware-delivery ecosystems rather than hardware-asset ownership, with remote update interoperability emerging as the decisive competitive moat.
For Market Incumbents: Fortify calibration service density through accelerated ISO/IEC 17025 accreditation expansion in expeditionary force corridors, countering third-party laboratory unbundling that threatens recurring revenue streams. Deepen backward integration into programmable logic supply to mitigate single-source foundry risk from Taiwan and South Korea concentration. Prioritize firmware distribution channel partnerships with naval aviation maintenance units where reconfigurable baseband adoption concentrates. For New Entrants and Emerging Players: Remote firmware distribution capability gaps in legacy supplier portfolios expose white-space opportunity for modular software-defined platform developers targeting rapid-deploy diagnostic requirements. European expeditionary force modernization programs present most penetrable geography given Bundeswehr restructuring timelines and calibration infrastructure undersupply. Pursue capability-as-a-service contract structures that separate measurement traceability from original equipment purchases, mirroring defense depot unbundling patterns. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because calibration service dependencies and NIST traceability mandates generate durable incumbent lock-in resistant to hardware commoditization cycles. Acquisition target archetype: specialized measurement technology firms with deep calibration heritage and software-defined instrumentation pipelines. Monitor export control revision velocity under ITAR and EAR classifications as inflection indicator for cross-border technology transfer permission shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Distribution Channel Partnership | Naval aviation maintenance units adopt reconfigurable baseband platforms fastest, expanding recurring software license revenue. |
| ISO/IEC 17025 Accreditation Expansion | Third-party laboratory unbundling concentrates in Germany and the United States where independent metrology providers achieve NIST-equivalent density. |
| Backward Integration into Programmable Logic | Single-source foundry risk in Taiwan and South Korea threatens millimeter-wave signal analysis system production continuity. |
| Capability-as-a-Service Contract Structure | Defense maintenance depots now source measurement traceability separately from original equipment purchases, bypassing manufacturer service networks. |
| Expeditionary Portable Diagnostic Development | FAA airworthiness directives and DoD MIL-STD-810 specifications embed shielding architectures that extend development timelines and raise non-recurring engineering costs. |
Research Methodology
A spread of perspectives from defense procurement officers, RF engineering specialists at prime contractors, calibration laboratory directors, and export compliance attorneys converged on the working assumptions driving segmentation splits. Primary interviews with these stakeholders combined with secondary validation from DoD MIL-STD documentation, FAA airworthiness directive filings, Bundeswehr procurement announcements, and NIST calibration service registries. Bottom-up equipment shipment tracking and top-down defense budget appropriation analysis triangulated market sizing across the analysis window.
Segmentation dimensions modeled include product type, technology architecture, end-user category, and installation mode, with additional granularity on firmware-upgradable versus fixed-function hardware splits. CAGRs were derived from replacement cycle compression analysis under MIL-STD-461G mandates and software-defined adoption curves in naval aviation maintenance units. Forecast inputs incorporated electromagnetic compatibility certification timeline data and expeditionary force restructuring announcements from Germany, the United Kingdom, and Japan.
Forecasts assume regulatory continuity in FAA airworthiness frameworks and DoD MIL-STD compliance regimes; material policy shifts in electromagnetic compatibility standards or export control classifications would require re-modeling. Technology transition risk from analog-to-digital test bed integration complexity and RF engineering talent scarcity constitute primary forecast revision factors. Practitioners should keep alternative scenarios live as Bundeswehr modernization program pacing and ITAR classification friction evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Europe Digital Battlefield Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
Rocket Solid Propulsion Market
Military Equipment and Infrastructure
Military Optoelectronic System Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Latin America Defense Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
Global Landing String Equipment Market
Military Equipment and Infrastructure
Deployable Military Shelters Market
Military Equipment and Infrastructure
Land Digital Battlefield Market
Military Equipment and Infrastructure
Aircraft Carrier Arresting Systems Market
Military Equipment and Infrastructure
Global Armor Materials Market