
 Dental Impression System Market | 2026-2036
Dental Impression System Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Impression System Market Intelligence
Polyether is repositioning alginate in high-precision crown and bridge applications, compressing per-procedure material costs while elevating margin capture for manufacturers. Dentsply Sirona leverages its captive scanner portfolio to lock in recurring material revenue. 3Shape A/S anchors the open-architecture segment, allowing third-party mills and labs to compete on finishing quality. GC Corporation specializes in silicone formulations that sustain premium pricing across Asian dental laboratories.
A dental impression system comprises devices and consumables that capture negative replicas of oral anatomy for prosthetic fabrication, restoration planning, and orthodontic modeling, typically achieving accuracy tolerances within 25 microns for full-arch digital scans. Digital impression systems lead the product landscape, with optical scanning technology capturing the fastest expansion as chairside CAD/CAM integration eliminates plaster model logistics. Conventional alginate and silicone materials still occupy substantial volume in emerging markets where equipment capital constraints persist.
FDA 510(k) clearance pathways and EU MDR Class IIa requirements shape product development timelines and clinical validation burdens for manufacturers seeking market access. ISO 13485 quality management standards and biocompatibility testing under ISO 10993 further filter supplier participation, concentrating procurement among vertically integrated incumbents. Stakeholders must monitor whether optical scanning resolution improvements will displace laser scanning in premium segments or merely segment the installed base by procedure complexity.
Market Dynamics
The dental impression system market pivots on optical scanning resolution advances compressing procedure timelines and eliminating plaster model logistics from clinical workflows.
Growth Catalysts
- EU MDR Class IIa biocompatibility mandates:Tighter material validation standards in Europe accelerate digital system replacement of conventional alginate workflows in German and French dental clinics.
- Chairside CAD/CAM integration:Same-day crown fabrication demand pulls intraoral scanner adoption across United States group dental practices seeking throughput advantages.
- Silicone formulation durability:Advanced polyether and addition-cure silicones extend working time precision, reducing remake rates in Japanese crown and bridge laboratories.
Market Restraints
- Capital equipment intensity:Digital scanner hardware and software subscriptions impose five-figure entry costs constraining adoption in Brazilian and Indian independent clinics.
- Optical scanning depth limitations:Subgingival margin capture remains technically unreliable for deep preps, preserving laser scanning niche in premium implantology segments.
- Raw material concentration:Medical-grade silicone precursor supply clusters in German and Chinese chemical manufacturing, exposing impression material producers to input volatility.
Strategic Opportunities
- Cloud-based scan storage architectures:Remote laboratory collaboration platforms enable United States rural clinics to access metropolitan milling capacity without capital investment.
- Orthodontic clear aligner workflows:Direct-to-consumer aligner brands in Japan and South Korea create scanner demand among general dentists previously excluded from orthodontic services.
- FDA 510(k) streamlined pathways:Predicate device referencing for iterative scanner hardware reduces regulatory timeline friction for secondary market entrants.
Industry Challenges
- Digital workflow retraining requirements:Conventional impression technicians face competency gaps transitioning to CAD/CAM software interfaces, slowing laboratory automation returns.
- Legacy plaster model integration:Hybrid practices maintaining physical and digital workflows absorb duplicate inventory and storage overhead without full system replacement benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Impression System Market |
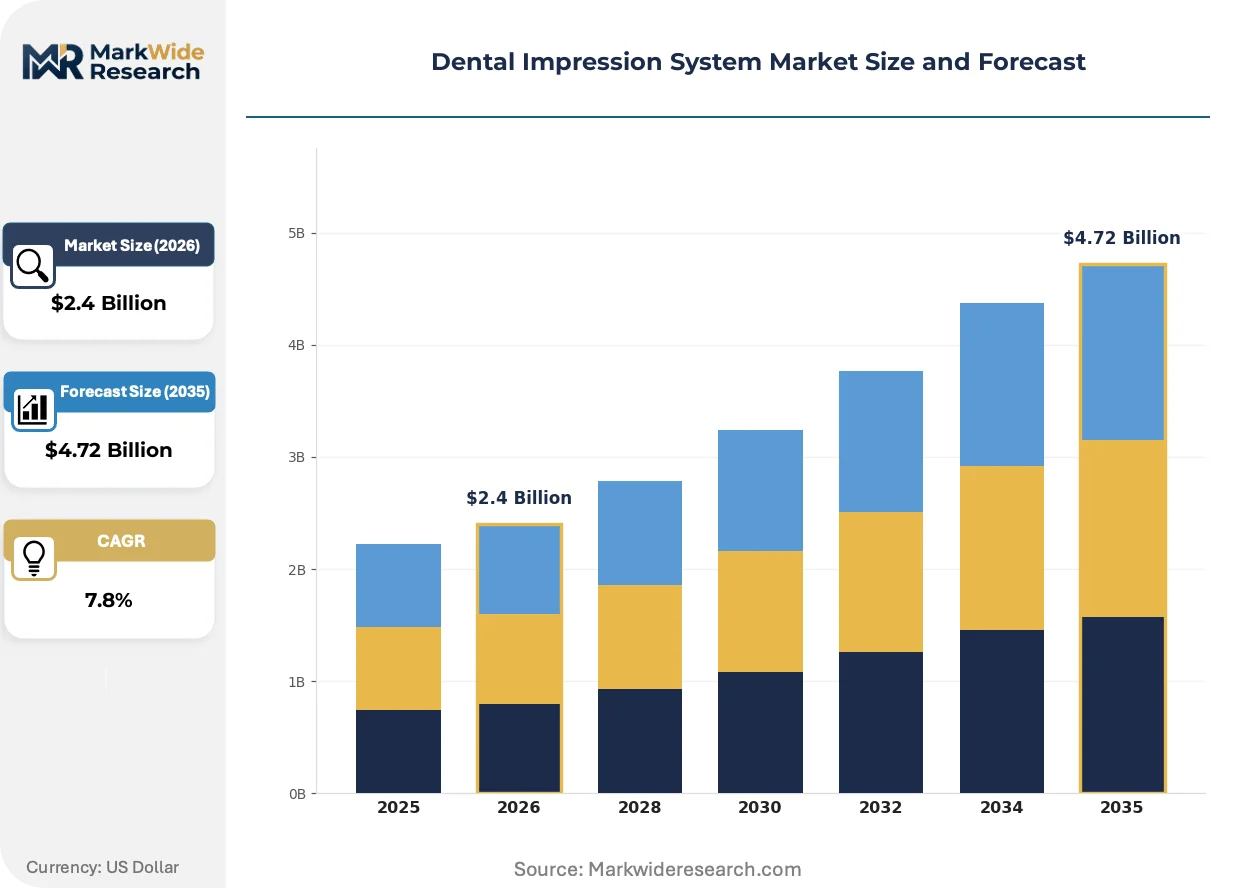
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Impression Systems, Conventional Impression Systems, Automated Impression Systems, Hybrid Impression Systems End User: Dental Clinics, Dental Laboratories, Hospital Dental Departments, Academic Institutions Technology: Optical Scanning, Laser Scanning, 3D Printing, CAD/CAM Integration Material: Acrylic Materials, Polyether, Alginate, Silicones |
| Companies Covered | Dentsply Sirona, 3Shape A/S, Align Technology, Ivoclar Vivadent, Planmeca Oy, GC Corporation, Henry Schein, Solventum, Envista, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Impression System Market Strategic Shifts & Innovations
Optical scanning resolution convergence with artificial intelligence margin detection is compressing the distinction between digital and physical impression accuracy thresholds.
Confocal microscopy and structured blue light scanning is unifying sub-10 micron accuracy across full-arch captures. German and Swiss dental laboratories now specify these systems for implant-supported prosthesis fabrication where passive fit tolerance is non-negotiable. The technology is unifying previously separate scanning, design, and milling verification stages into single-visit protocols.
EU MDR Annex I general safety and performance requirements impose clinical evidence burdens on impression material biocompatibility claims. Manufacturers must demonstrate cytotoxicity, sensitization, and irritation profiles under ISO 10993 series testing. German notified bodies are extending review timelines for silicone-based materials, compressing product refresh cycles and elevating documentation costs for European market access.
Dental group procurement consortia in the United States are unbundling scanner hardware from proprietary material supply agreements. Large multi-site operators negotiate direct optical scanner purchases while sourcing compatible third-party impression materials through separate tenders. This purchasing behavior fragmentation pressures Dentsply Sirona and Straumann to defend captive material revenue through software feature differentiation rather than hardware lock-in.
Dental Impression System Market Segmentation
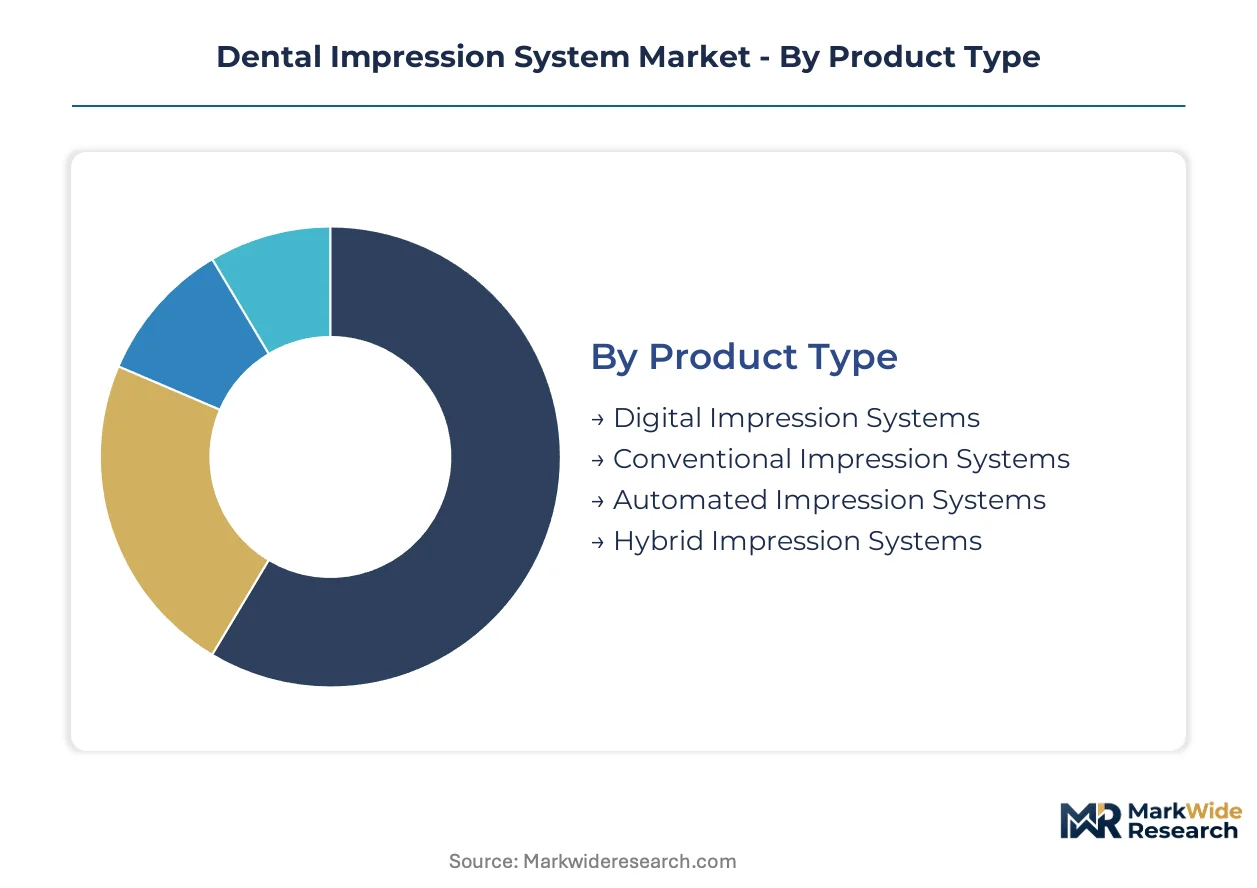
Dental impression system segmentation reveals how capital intensity, regulatory compliance burdens, and workflow integration requirements split demand across clinical settings. Manufacturers configure product portfolios around these fault lines to capture recurring material revenue or one-time hardware sales.
Product Type:
Capital requirements vary dramatically across this category, with hardware-software bundles demanding six-figure investments while consumable-dependent alternatives require minimal upfront outlay.
- Digital Impression Systems:Chairside optical scanners paired with proprietary software platforms capture intraoral anatomy at sub-25-micron tolerances. United States group dental practices absorb subscription costs to enable same-day crown fabrication workflows.
- Conventional Impression Systems:Alginate and silicone trays with manual mixing protocols dominate Brazilian and Indian independent clinics where scanner capital remains prohibitive.
- Automated Impression Systems:Robotic tray positioning and material dispensing reduce technician variability in high-throughput Japanese dental laboratories.
- Hybrid Impression Systems:Dual-mode hardware accommodates both physical model pouring and digital scan export for transitional workflows in German academic institutions.
Most installed capacity flows through Conventional Impression Systems. Expansion is steepest in Digital Impression Systems.
End User:
Procurement authority and reimbursement structures determine which customer types drive premium versus volume sales.
- Dental Clinics:Private practices and group operators purchase chairside scanners to compress appointment sequences and eliminate laboratory shipping delays. FDA 510(k) clearance predicates guide their hardware selection criteria.
- Dental Laboratories:Independent milling centers and prosthesis fabricators invest in high-resolution desktop scanners to serve remote clinic clients through cloud-based case management platforms.
- Hospital Dental Departments:Academic medical centers balance research requirements against throughput needs, often maintaining hybrid conventional-digital workflows.
- Academic Institutions:Dental schools train students on both legacy and emerging technologies, creating replacement demand cycles tied to curriculum refresh schedules.
Procurement volume concentrates in Dental Laboratories. Margin capture is strongest in Dental Clinics.
Technology:
Resolution specifications and integration depth separate premium positioning from commodity alternatives.
- Optical Scanning:Structured blue light and confocal microscopy achieve full-arch captures with sub-10-micron accuracy for implant-supported prosthesis fabrication in Swiss and German laboratories.
- Laser Scanning:Triangulation-based systems penetrate subgingival margins where optical methods fail, preserving niche demand in complex implantology cases.
- 3D Printing:Photopolymer and resin-based additive manufacturing produces surgical guides and diagnostic models from digital impression files without traditional stone casting.
- CAD/CAM Integration:Seamless design-to-mill connectivity eliminates file format translation errors, locking clinics into end-to-end vendor ecosystems.
Technical leadership resides in Optical Scanning. CAD/CAM Integration is gaining share fastest among new installations.
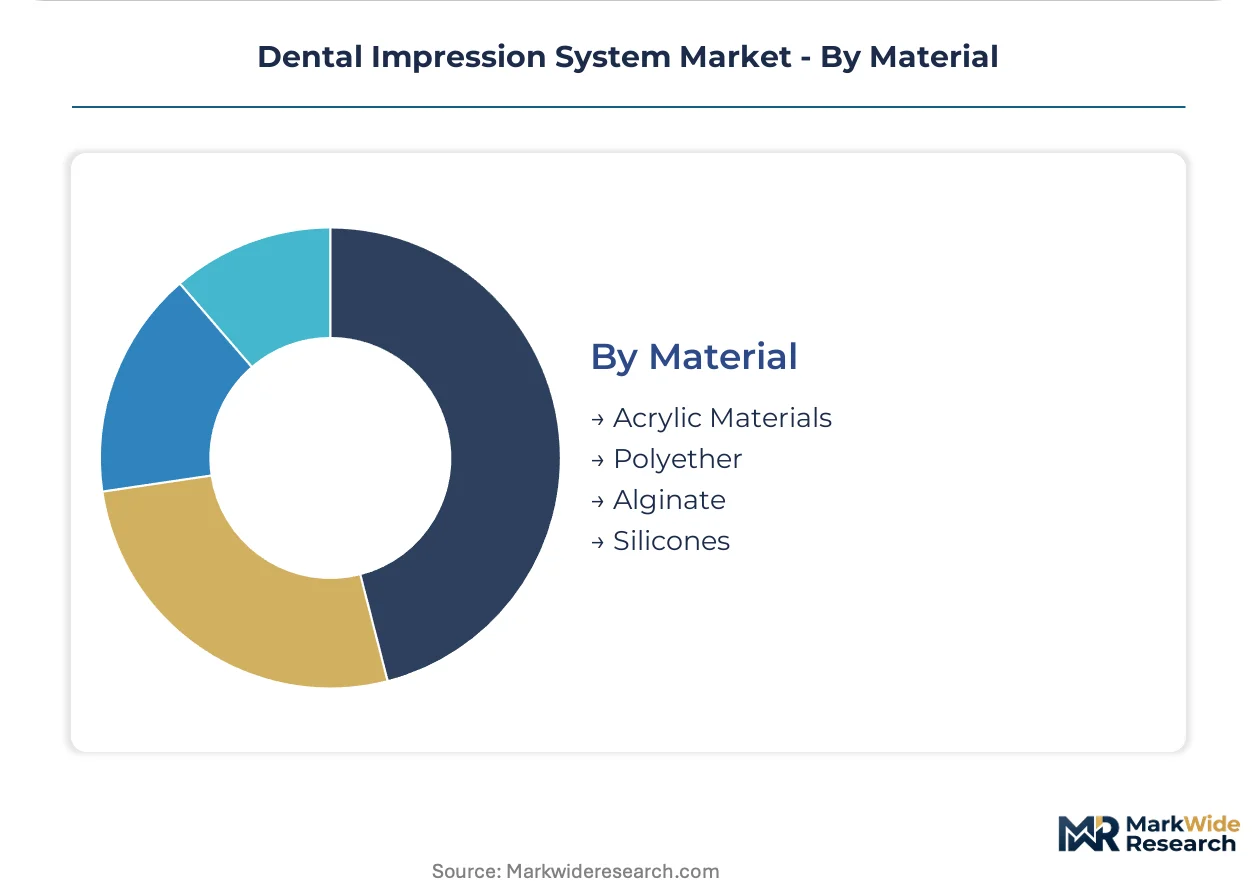
Material:
Biocompatibility certification tiers and working time characteristics stratify pricing across clinical applications.
- Polyether:Hydrophilic elastomers with superior flow characteristics capture marginal detail in moist environments, commanding premium pricing for crown and bridge applications in German clinics facing EU MDR compliance deadlines.
- Silicones:Addition-cure formulations deliver dimensional stability across extended working periods, sustaining material revenue for manufacturers serving Japanese crown and bridge laboratories.
- Acrylic Materials:Provisional and diagnostic applications utilize these cost-effective resins where long-term dimensional accuracy is less critical.
- Alginate:Irreversible hydrocolloid remains the default for preliminary impressions and orthodontic study models in price-sensitive emerging markets.
Volume consumption clusters in Silicones. Polyether is climbing the fastest among precision-oriented segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dental laboratories in Stuttgart and Munich drive precision demand for implant-supported prosthesis fabrication where sub-10-micron accuracy tolerance is mandatory. FDA 510(k) clearance pathways in the United States and EU MDR Class IIa biocompatibility mandates in Europe reshape procurement patterns across developed markets.
United States
Group dental practices in Texas and Florida absorb chairside scanner subscriptions to enable same-day crown fabrication workflows. FDA 510(k) predicate device referencing accelerates hardware refresh cycles for secondary market entrants. Metropolitan milling centers in Chicago and Los Angeles now serve rural clinics through cloud-based scan storage architectures.
Germany
Dental clinics in Bavaria and North Rhine-Westphalia face compressed EU MDR compliance deadlines for silicone-based impression material validation. German notified bodies extend review timelines for biocompatibility documentation under ISO 10993 series testing. Stuttgart laboratories specify confocal microscopy systems for passive-fit implant prosthesis fabrication.
Japan
Crown and bridge laboratories in Osaka and Tokyo sustain premium material pricing through addition-cure silicone formulations with extended working precision. METI standards guide optical scanning resolution specifications for domestic equipment certification. Nagoya academic institutions maintain hybrid conventional-digital workflows for curriculum breadth.
Brazil
Independent clinics in São Paulo and Rio de Janeiro confront five-figure digital scanner entry costs that preserve alginate volume in preliminary impression applications. ANVISA registration requirements filter imported equipment participation. Minas Gerais dental schools train technicians on legacy plaster model protocols alongside emerging CAD/CAM interfaces.
China
Dental manufacturing clusters in Shenzhen and Shanghai supply optical scanner hardware components to international OEMs while domestic clinics lag in chairside adoption. NMPA Class II medical device registration shapes product development timelines for multinational entrants. Yangtze River Delta laboratories increasingly export milled prostheses to Southeast Asian markets.
Dental Impression System Market Key Industry Players
Portfolio diversification dominates the current landscape as incumbents defend recurring material revenue against unbundling procurement consortia. The vendor base separates into three tiers: vertically integrated conglomerates with captive scanner-material ecosystems, open-architecture specialists enabling third-party compatibility, and regional material formulators serving price-sensitive emerging markets. Two competitive moves define current positioning: software feature differentiation to replace hardware lock-in strategies, and cloud-based platform development to capture remote laboratory collaboration revenue.
Within the conglomerate tier, Dentsply Sirona and Envista represent the integrated hardware-material model, while 3Shape A/S anchors the open-architecture segment. Henry Schein occupies distribution-scale positioning across North American dental group procurement channels.
| Leading Market Players |
|---|
| Dentsply Sirona |
| 3Shape A/S |
| Align Technology |
| Ivoclar Vivadent |
| Planmeca Oy |
| GC Corporation |
| Henry Schein |
| Solventum |
| Envista |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up dental equipment specialists have consolidated scanner distribution networks across North America, compressing procurement leverage for independent clinics while amplifying pricing power for recurring material subscriptions. This ownership pattern ties supply exclusivity to software licensing tiers, embedding cost structures that resist unbundling by large dental group purchasing organizations.
Pricing Analysis
Medical-grade silicone precursor costs pass through directly to impression material pricing, with German and Chinese chemical feedstock volatility translating into quarterly adjustments for polyether and addition-cure silicone formulations. Pricing stratifies across premium, standard, and economy tiers based on optical scanning resolution specifications and ISO 10993 biocompatibility certification levels. Cost compression in the economy tier is intensifying as Brazilian and Indian independent clinics demand alginate alternatives at sub-premium price points. Dental laboratories exhibit the highest price sensitivity due to thin prosthesis fabrication margins, while United States group practices absorb subscription premiums for same-day crown workflow enablement.
Supply Chain Analysis
Direct-to-clinic channels handle hyperscale demand from United States dental service organizations, while distributor-mediated routes serve fragmented European and Asian independent practices. Manufacturing concentrates in Germany, China, and Japan, with Stuttgart and Munich hosting precision optics fabrication for confocal microscopy systems and Shenzhen supplying scanner hardware components to international OEMs. Supply chains draw from medical-grade silicone precursors, optical sensor arrays, and precision-machined aluminum housings. Single-source vulnerability clusters around German notified body capacity for EU MDR biocompatibility documentation, extending lead times for material validation. Distribution runs through Henry Schein's North American logistics network and regional dental supply cooperatives in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between FDA 510(k) streamlined pathways in the United States and EU MDR extended review timelines in Europe, with cost differentials favoring predicate-device referencing strategies over de novo clinical validation burdens.
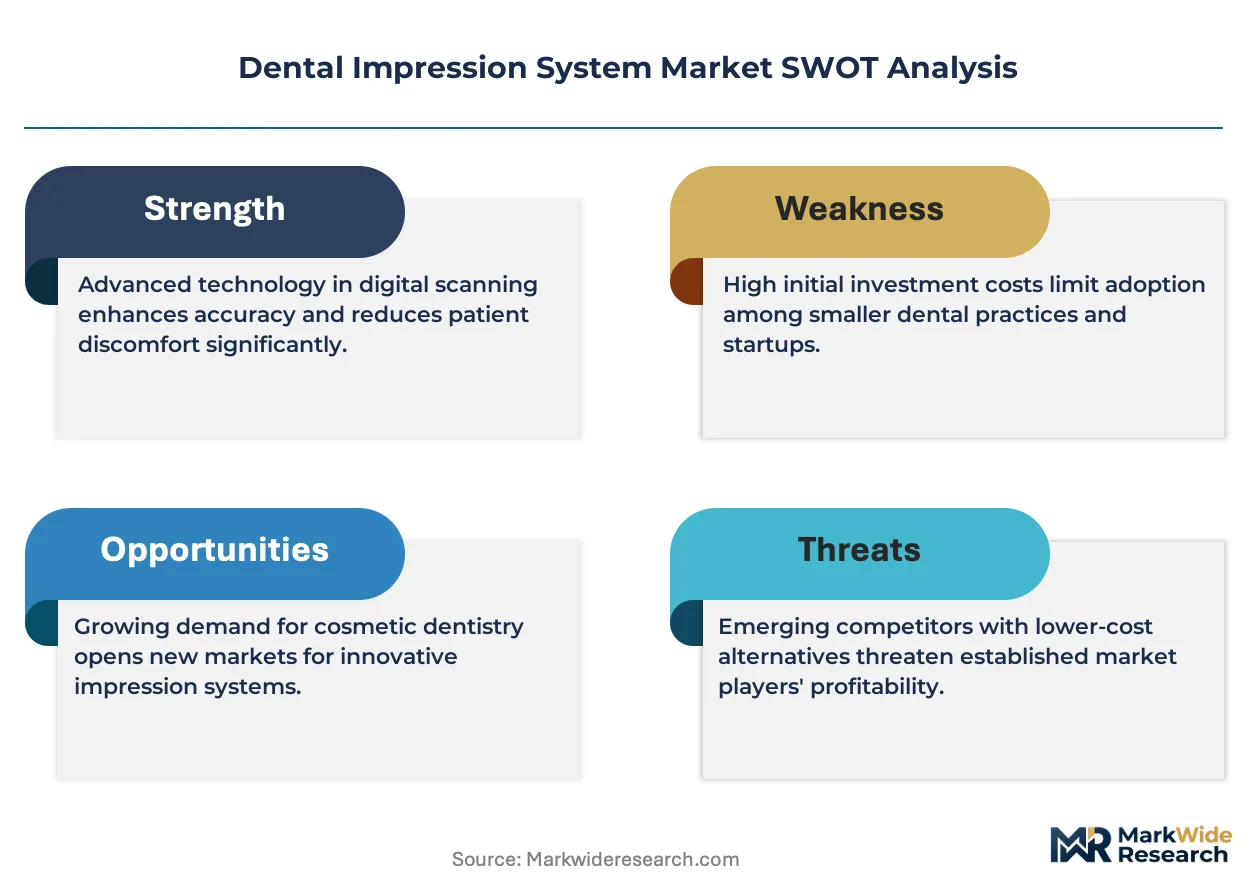
For Market Incumbents: Lock in recurring material revenue through software feature differentiation that replaces hardware lock-in strategies, as United States dental group procurement consortia unbundle scanner purchases from proprietary supply agreements. Defend against open-architecture competitors by deepening CAD/CAM ecosystem integration and acquiring cloud-based scan storage platforms to capture remote laboratory collaboration revenue. For New Entrants and Emerging Players: FDA 510(k) streamlined pathways in the United States open a window for predicate-device referencing strategies that compress regulatory timelines against EU MDR documentation burdens. Target Brazilian and Indian independent clinics with hardware leasing models and third-party-compatible material sourcing, penetrating the most price-sensitive tier through capital-light entry structures rather than six-figure scanner sales. For Investors and Strategic Acquirers: Valuations sit cheapest among regional silicone material formulators serving Asian dental laboratories, where premium pricing on addition-cure formulations sustains margin profiles absent scanner hardware depreciation cycles. Target acquisition archetypes include cloud-based scan storage platforms with established United States rural clinic networks and Japanese crown and bridge laboratories with METI-certified optical scanning integration. Watch for inflection when German notified bodies clear backlog for silicone-based material biocompatibility reviews, signaling reopened European market access.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Scan Storage Platform | Enables United States rural clinics to access metropolitan milling capacity without capital investment. |
| EU MDR Biocompatibility Certification | Accelerates digital system replacement of alginate workflows in German and French dental clinics. |
| Open-Architecture Scanner Development | Allows third-party mills and labs to compete on finishing quality against integrated incumbents. |
| Orthodontic Clear Aligner Workflow Integration | Creates scanner demand among Japanese and South Korean general dentists previously excluded from orthodontic services. |
| Silicone Formulation R&D Investment | Extends working time precision for Japanese crown and bridge laboratories demanding premium material performance. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with dental clinic owners, dental laboratory technicians, biomedical engineers at scanner OEMs, GPO contracts managers, and regulatory affairs specialists at material manufacturers. Secondary validation draws from FDA 510(k) filings, EU MDR notified body documentation, ISO 13485 certification records, and dental supply customs data. Bottom-up demand modeling triangulates against top-down market sizing across hardware unit shipments and material volume consumption.
Rate-of-change decomposition separates hardware replacement cycles from consumable recurring revenue streams across the projection horizon. Segmentation dimensions modeled include product type, end user, technology, material, and regional regulatory cluster. CAGRs derive from installed base penetration curves and per-procedure material intensity assumptions. Forecast inputs incorporate optical scanning resolution improvement trajectories and EU MDR compliance deadline impacts on material substitution patterns.
Revisions become necessary when FDA predicate device clearance pathways narrow, EU MDR notified body capacity constraints extend, or optical scanning resolution convergence displaces laser scanning in premium implantology segments faster than modeled. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
North America Dental Implants and Prosthetics Market
Dental Devices
Chile Dental Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
Dental Implants and Abutment Systems Market
Dental Devices
Chile Dental Devices Market
Dental Devices
Orthodontics Market
Dental Devices
North America Dental Lab Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
Endodontics and Orthodontics Market
Dental Devices
3D Printed Clear Dental Aligners Market
Dental Devices
Italy Dental Devices Market
Dental Devices
Dental Sealants Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Dental Radiometer Market
Dental Devices
Nano Dentistry Market
Dental Devices
Europe Dental Lab Market