
 Dental Diamond Burs Market | 2026-2036
Dental Diamond Burs Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Diamond Burs Market Outlook
A shift from single-source procurement to multi-source qualification is recalibrating how dental distributors manage bur inventories. Brasseler USA leverages its domestic manufacturing footprint to sustain reliable supply for North American dental laboratories. Dentsply Sirona Inc. competes through integrated digital dentistry ecosystems that bundle diamond burs with CAD/CAM workflows. Komet USA LLC specializes in precision-grit formulations that anchor its position in prosthetic finishing applications.
Dental diamond burs are rotary cutting instruments with diamond particles electroplated or sintered onto a stainless-steel shank, typically operating at 300,000–500,000 RPM for enamel and composite removal. Their primary purpose is to deliver controlled, efficient tooth preparation with minimal thermal damage during restorative and prosthetic procedures. Round burs dominate entry-level restorative kits due to universal utility in cavity preparation, while surgical applications drive demand for specialized inverted cone geometries. The prosthetic segment commands premium positioning as chairside milling and zirconia crown placement expand.
The FDA regulates dental diamond burs as Class II medical devices under 21 CFR 872.4120, requiring premarket notification and adherence to quality system regulations. ISO 7785-1 specifies dimensional and performance standards for diamond rotary instruments, shaping export eligibility for manufacturers in Japan and Germany. Stakeholders must monitor evolving MDR requirements in Europe, where notified body scrutiny of biocompatibility and particle adhesion testing intensifies market access thresholds.
Market Dynamics
Multi-source qualification is displacing single-source procurement across dental distribution, forcing bur manufacturers to demonstrate redundant production capacity and quality system equivalence to retain shelf placement.
Growth Catalysts
- CAD/CAM workflow integration:Chairside milling systems in US dental clinics bundle diamond burs with digital impression scanners, creating locked-in consumable demand that expands procedure throughput.
- MDR biocompatibility scrutiny:Europe's intensified notified body review of particle adhesion testing is elevating technical barriers that favor established sintered-diamond producers with validated quality systems.
- Zirconia crown placement:Prosthetic finishing applications in German and Japanese laboratories require specialized grit formulations that command premium positioning and repeat purchase cycles.
Market Restraints
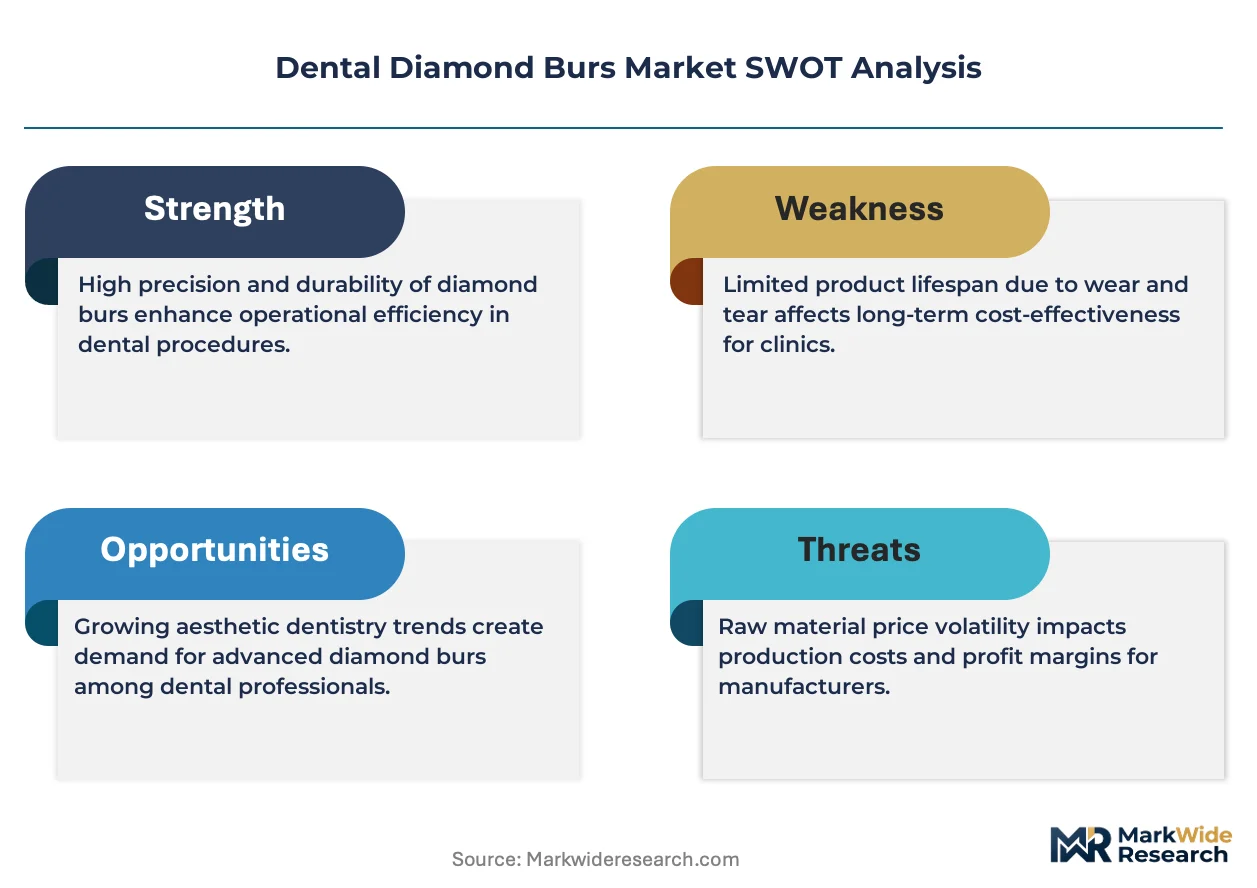
- Raw material concentration:Synthetic diamond grit supply concentrates among Chinese producers, exposing cost volatility when export licensing tightens.
- FDA premarket notification burden:Class II device classification under 21 CFR 872.4120 imposes 90-180 day review timelines that delay new geometry introductions.
- Carbide bur substitution:Tungsten carbide alternatives capture price-sensitive restorative segments where thermal sensitivity concerns are secondary.
Strategic Opportunities
- India dental clinic expansion:Underpenetrated tier-2 and tier-3 cities present volume potential as CDSCO streamlined medical device registration accelerates import market access.
- AI-driven bur selection:Convergence of machine vision with inventory management software enables automated grit-grade matching to procedure codes in large dental service organizations.
- Direct-to-laboratory e-commerce:Specialized distributors bypass traditional dental supply houses to capture margin through subscription replenishment models.
Industry Challenges
- ISO 7785-1 certification timelines:Dimensional and performance testing for diamond rotary instruments extends 8-14 months, compressing product refresh cycles.
- Electroplating technician scarcity:Precision particle bonding requires skilled operators whose training pipelines have narrowed across US and European manufacturing bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Diamond Burs Market |
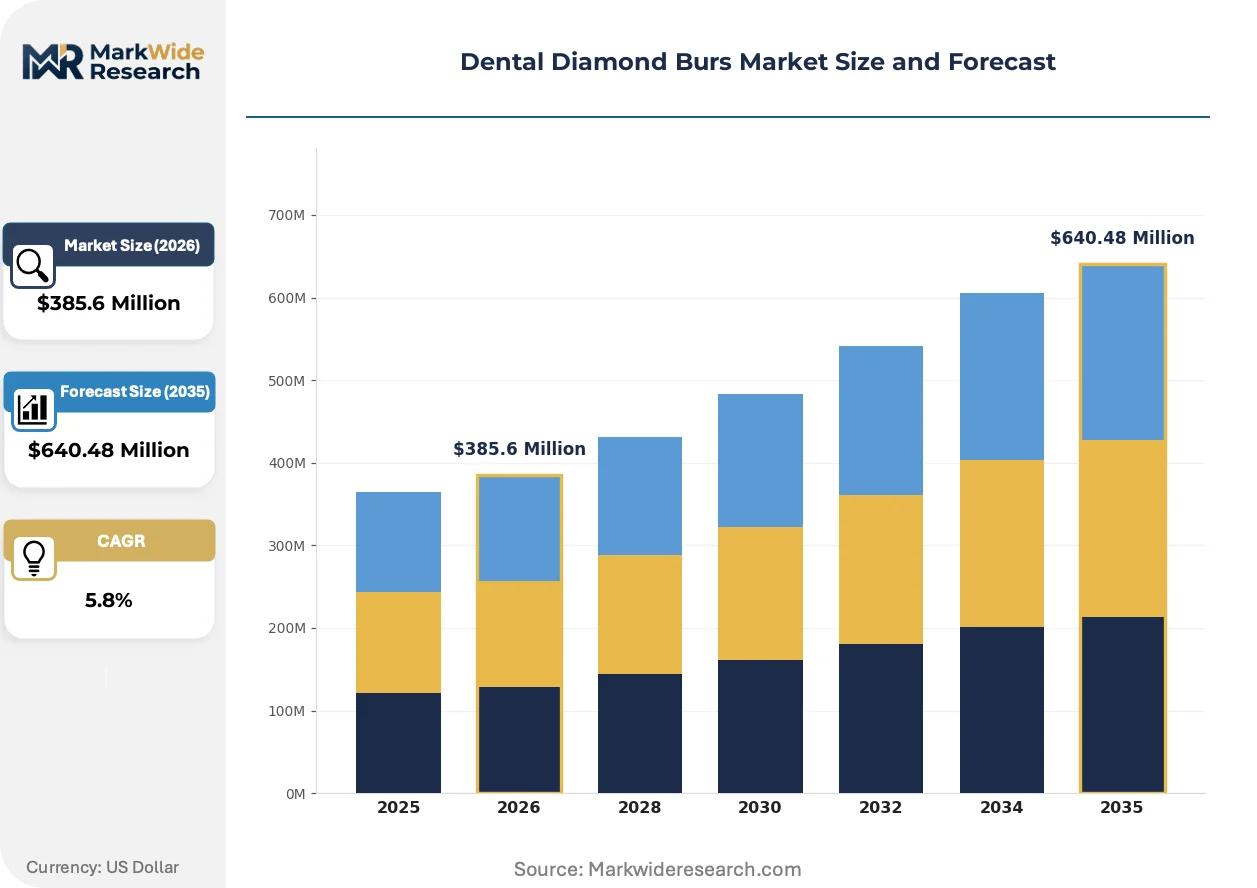
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round, Flat, Pear, Inverted Cone Application: Restorative, Preventive, Surgical, Prosthetic Size: Small, Medium, Large, Extra Large End User: Dentists, Orthodontists, Dental Clinics, Dental Laboratories |
| Companies Covered | HuFriedyGroup, Brasseler USA, Dentsply Sirona Inc., Komet USA LLC, Henry Schein Inc., SHOFU Inc., SS White Dental Inc., Prima Dental Group, MANI Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Diamond Burs Market Strategic Shifts
Digital dentistry ecosystems are compressing traditional equipment-consumable boundaries, forcing diamond bur producers to embed their instruments within software-controlled workflows rather than standalone sales.
Multi-layer sintered diamond technology is unifying cutting efficiency with extended service life in a single instrument design. German prosthetic laboratories are adopting these hybrid-construction burs for zirconia and lithium disilicate finishing, reducing instrument change frequency by half. This unification is compressing the aftermarket for economy-grade electroplated alternatives.
Europe's MDR implementation is tightening biocompatibility documentation requirements for particle adhesion and nickel release testing. Manufacturers must now submit comprehensive technical files to notified bodies before CE marking renewal, extending compliance timelines by four to six months. German and Italian producers with pre-validated testing protocols are capturing shelf space from smaller competitors.
Dental service organizations are consolidating purchasing decisions into centralized procurement functions that demand outcome-based performance guarantees from bur suppliers. Independent dental clinics in the US are losing negotiating leverage as DSOs capture 35-40% of restorative procedure volume. This concentration is visible in Texas and Florida metropolitan corridors where multi-location chains dominate.
Dental Diamond Burs Market Segmentation
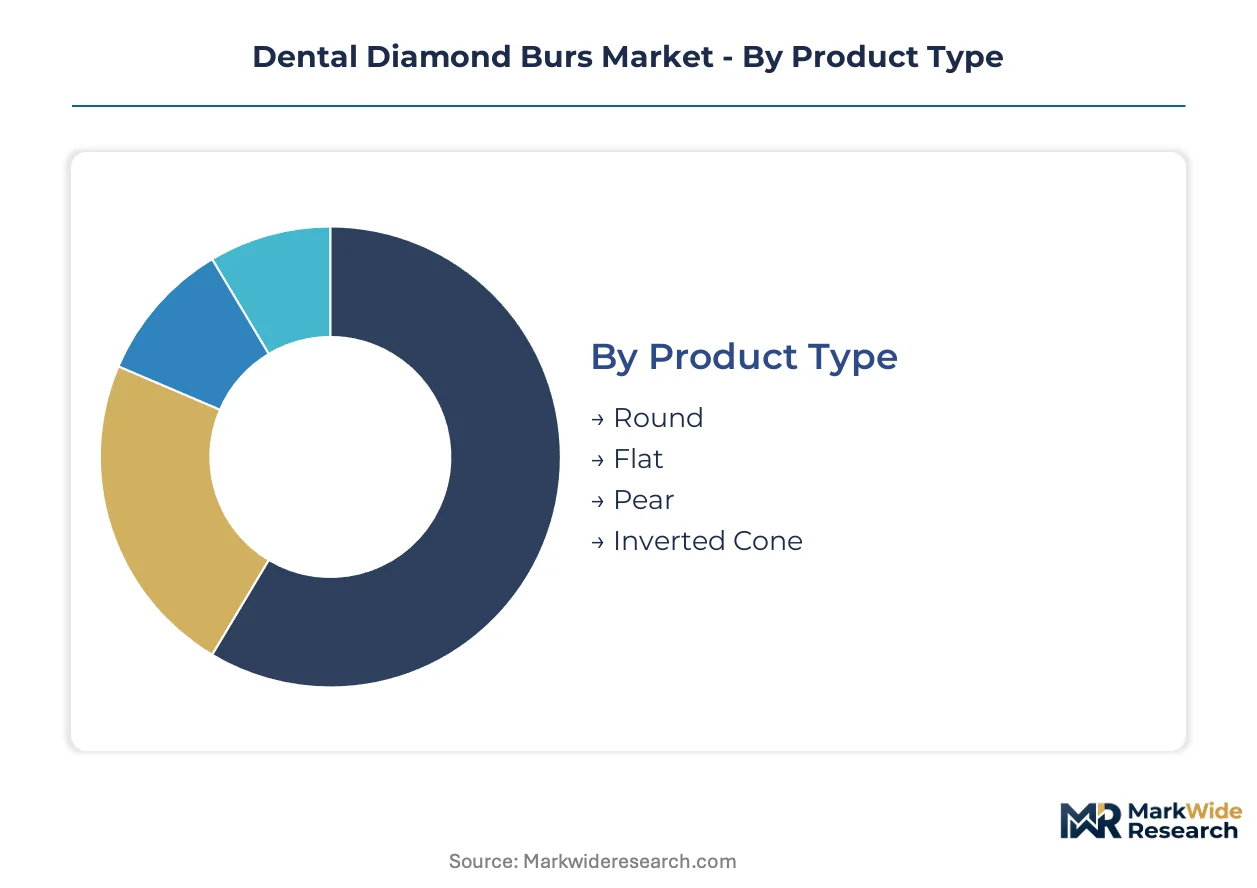
Dental diamond burs segment across multiple dimensions that determine regulatory pathways, pricing tiers, and procurement channels. Each category carries distinct certification burdens and end-use requirements that reshape competitive positioning.
Product Type:
FDA Class II classification under 21 CFR 872.4120 applies uniformly across all geometries, though specialized shapes trigger additional ISO 7785-1 dimensional validation cycles.
- Round:Spherical diamond-coated heads dominate cavity preparation and initial enamel penetration. US dental clinics in Texas and Florida metropolitan corridors consume this geometry most heavily as DSOs standardize entry-level restorative kits.
- Flat:Cylindrical cutting surfaces with flat-end geometry excel in margin refinement and axial wall preparation. German prosthetic laboratories specify this shape for zirconia crown finishing where precision plane creation determines restoration fit.
- Pear:Teardrop contour suits occlusal surface shaping and fissure extension in posterior restorations.
- Inverted Cone:Undercut geometry enables mechanical retention in Class I and II cavity preparations.
Leading the category by volume: Round. Growing fastest: Flat.
Application:
Procedure-specific demand concentrates margin and repeat purchase patterns across four clinical domains with divergent instrument wear rates.
- Restorative:Cavity preparation and caries removal consume the highest bur volume per procedure. Chairside CAD/CAM integration in US dental clinics bundles diamond burs with digital impression workflows, locking in consumable replenishment cycles.
- Prosthetic:Crown and bridge finishing commands premium pricing as zirconia and lithium disilicate hardness accelerate instrument degradation. Japanese laboratories pay three-tier pricing premiums for validated grit consistency in final glaze removal.
- Preventive:Enameloplasty and sealant preparation require minimal cutting depth with short instrument life.
- Surgical:Bone contouring and osteotomy procedures utilize specialized geometries with extended shank lengths.
Restorative procedures generate the largest absolute volume. Prosthetic applications deliver the steepest expansion trajectory.
Size:
Dimensional classification determines RPM compatibility and handpiece coupling standards under ISO 7785-1 specifications.
- Small:Precision head diameters below 1.0mm enable conservative tissue removal in pediatric and aesthetic zone procedures. California dental clinics specializing in minimally invasive techniques specify this size for veneer preparations.
- Medium:Standard 1.0–1.6mm heads balance cutting efficiency with control in general restorative practice.
- Large:1.6–2.3mm diameters accelerate bulk reduction in full-coverage preparations.
- Extra Large:Specialized crown removal and aggressive tooth reduction applications.
Medium sizes dominate procurement volumes. Small diameters are climbing the fastest as conservative dentistry protocols spread.
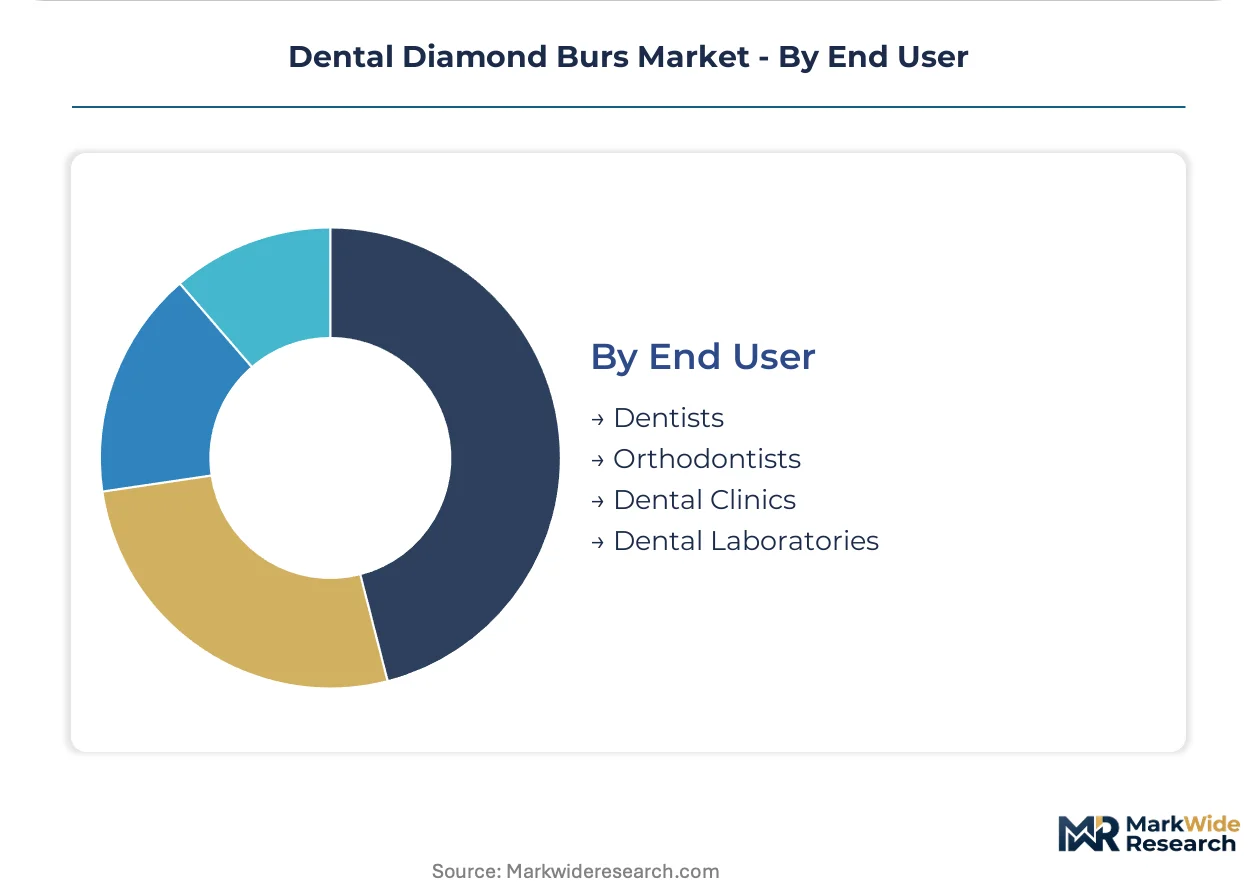
End User:
Customer type dictates purchasing authority, contract structures, and outcome-based performance requirements.
- Dental Clinics:Multi-location chains in US metropolitan corridors centralize procurement through DSOs that demand redundant supply capacity and quality system documentation. These organizations capture 35–40% of restorative procedure volume.
- Dental Laboratories:German and Japanese prosthetic facilities specify premium sintered-diamond formulations with validated particle adhesion protocols under intensified MDR biocompatibility scrutiny.
- Dentists:Independent practitioners retain direct purchasing authority in underpenetrated tier-2 and tier-3 Indian cities.
- Orthodontists:Enamel stripping and bracket placement procedures require specialized geometries with lower wear tolerance.
Dental clinics lead absolute consumption. Dental laboratories concentrate the fastest-growing premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic diamond grit production concentrates in Zhengzhou, China, anchoring raw material flows for electroplated and sintered instrument manufacturing worldwide.
United States
Texas and Florida metropolitan corridors host dense concentrations of dental service organizations capturing 35-40% of restorative procedure volume. FDA Class II oversight under 21 CFR 872.4120 shapes 90-180 day premarket notification timelines for new geometries. Brasseler USA leverages domestic manufacturing in the Southeast to supply North American dental laboratories with redundant capacity.
Germany
Prosthetic finishing applications for zirconia and lithium disilicate crown placement drive premium-tier demand from Bavarian and North Rhine-Westphalian laboratories. MDR biocompatibility scrutiny intensifies notified body review of particle adhesion testing, extending compliance timelines four to six months. Stuttgart-based precision tooling clusters specialize in multi-layer sintered diamond technology.
China
Domestic dental clinic expansion in tier-2 and tier-3 cities accelerates consumption of entry-level restorative kits. NMPA medical device registration pathways align with international standards while permitting accelerated domestic market access. Zhengzhou industrial zones concentrate synthetic diamond grit supply, exposing cost volatility when export licensing tightens.
Japan
Laboratory demand for validated grit consistency in final glaze removal commands three-tier pricing premiums. METI industrial standards and PMDA quality system requirements shape export eligibility for precision rotary instruments. Osaka-Kobe manufacturing corridors sustain specialized production of prosthetic finishing formulations.
India
Underpenetrated tier-2 and tier-3 cities present volume potential as CDSCO streamlined medical device registration accelerates import market access. Independent dental practitioners retain direct purchasing authority outside consolidated procurement structures. Maharashtra and Gujarat dental clinic clusters represent the fastest-expanding addressable base.
Dental Diamond Burs Market Competitive Environment
Global majors compete with regional champions across quality system documentation and redundant production capacity. The vendor base stratifies into three tiers: integrated dental equipment suppliers bundling consumables with digital workflows, precision instrument specialists commanding prosthetic finishing premiums, and scale-driven manufacturers serving price-sensitive restorative segments. Dominant competitive moves include M&A to capture CAD/CAM ecosystem integration and capacity expansion to satisfy multi-source qualification requirements from consolidated dental service organizations.
Among US-based manufacturers, Brasseler USA and Komet USA LLC exemplify the precision-specialist archetype, while Dentsply Sirona Inc. occupies a position representing integrated equipment-consumable bundling. These three anchors illustrate divergent strategic paths: domestic manufacturing footprint versus digital dentistry ecosystem integration versus precision-grit formulation specialization.
| Leading Market Players |
|---|
| HuFriedyGroup |
| Brasseler USA |
| Dentsply Sirona Inc. |
| Komet USA LLC |
| Henry Schein Inc. |
| SHOFU Inc. |
| SS White Dental Inc. |
| Prima Dental Group |
| MANI Inc. |
| Others |
Value Chain & Pricing Dynamics
Multi-layer sintered diamond technology is compressing cost economics for premium-tier manufacturers while simultaneously concentrating production capability among German and Japanese precision tooling clusters. This transition rewards validated quality systems with pricing power while exposing electroplated-bur producers to margin compression from shorter instrument lifecycles.
Pricing Analysis
Warranty-backed performance guarantees separate premium sintered-diamond formulations from unbundled economy-grade electroplated alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 7785-1 certification grade and validated particle adhesion protocols. Pricing pressure stems from carbide bur substitution in price-sensitive restorative segments where thermal sensitivity ranks below unit cost. Independent dental practitioners in underpenetrated Indian tier-2 cities exhibit highest price sensitivity, while German prosthetic laboratories demonstrate lowest sensitivity due to outcome-based procurement mandates.
Supply Chain Analysis
Freight cost volatility from Zhengzhou synthetic diamond grit shipments to US and European manufacturing bases is compressing landed cost predictability. Raw material supply draws from Chinese synthetic diamond producers, German precision steel shank suppliers, and Japanese electroplating chemistry specialists. Single-source vulnerability concentrates in Zhengzhou industrial zones where export licensing fluctuations disrupt grit availability. Distribution runs through dental service organization procurement hubs in Texas and Florida metropolitan corridors, with secondary channels serving independent laboratories through specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around quality system documentation capabilities as MDR biocompatibility scrutiny and multi-source qualification requirements force smaller electroplated-bur producers toward exit.
For Market Incumbents: Hedge against carbide substitution by embedding diamond burs within CAD/CAM workflow bundles that lock in consumable replenishment cycles. Expand redundant production capacity in Southeast US manufacturing corridors to satisfy DSO multi-source qualification mandates. Deepen ISO 7785-1 pre-validation protocols to compress CE marking renewal timelines under intensified notified body review.
For New Entrants and Emerging Players: Direct-to-laboratory e-commerce platforms offer the most penetrable route around consolidated dental supply house distribution. Target underpenetrated tier-2 and tier-3 Indian cities where independent practitioners retain direct purchasing authority outside DSO procurement structures. Deploy subscription replenishment models with automated grit-grade matching to procedure codes as the primary go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated dental equipment suppliers seeking consumable bundling capabilities. Long-term viability favors precision sintered-diamond specialists with validated MDR technical files and established German or Japanese laboratory relationships. Watch CDSCO registration acceleration in India as the inflection signal for import market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical File Pre-Validation | Compresses CE marking renewal timelines by four to six months for German notified body submissions. |
| CAD/CAM Workflow Integration | Locks diamond bur replenishment into Dentsply Sirona digital dentistry ecosystem bundles. |
| Southeast US Capacity Expansion | Satisfies multi-source qualification requirements from Texas and Florida DSO procurement hubs. |
| Direct-to-Laboratory E-Commerce Launch | Bypasses Henry Schein supply house intermediaries to capture margin through subscription models. |
| India CDSCO Registration Acceleration | Opens tier-2 and tier-3 city access as streamlined medical device pathways reduce import barriers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with dental laboratory managers, DSO procurement directors, biomedical engineers, and GPO contracts managers. FDA 510(k) premarket notification databases, ISO 7785-1 certification registries, and European notified body technical file disclosures provided secondary validation. Bottom-up procedure volume estimates from US dental clinics and German prosthetic laboratories triangulated against top-down synthetic diamond grit trade flows.
Granularity extended to product type, application, size tier, and end-user archetype across the analysis window. CAGRs derived from weighted procedure growth assumptions and instrument replacement cycle frequencies. Zirconia crown placement expansion rates and CAD/CAM system adoption curves served as demand-side forecast inputs, while electroplating technician pipeline constraints and MDR compliance timeline extensions anchored supply-side adjustments.
The model holds under stable regulatory enforcement intensity; deviation in FDA premarket notification backlog or Chinese export licensing stringency would shift manufacturer capacity allocation and pricing power distribution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Restorative Dentistry Market
Dental Devices
Dental CAD Market
Dental Devices
Dental Dam Market
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
North America Dental Implants and Prosthetics Market
Dental Devices
Dental Crown Removal Market
Dental Devices
Middle East and Africa Dental Lab Market
Dental Devices
Malocclusion Market
Dental Devices
China Dental Implants Market
Dental Devices
Endodontics and Orthodontics Market
Dental Devices
Asia Pacific Dental Market
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
3D Printed Clear Dental Aligners Market
Dental Devices
Orthodontics Market
Dental Devices
Dental Floss Market