
 Chile Dental Devices Market | 2026-2036
Chile Dental Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Dental Devices Market Outlook
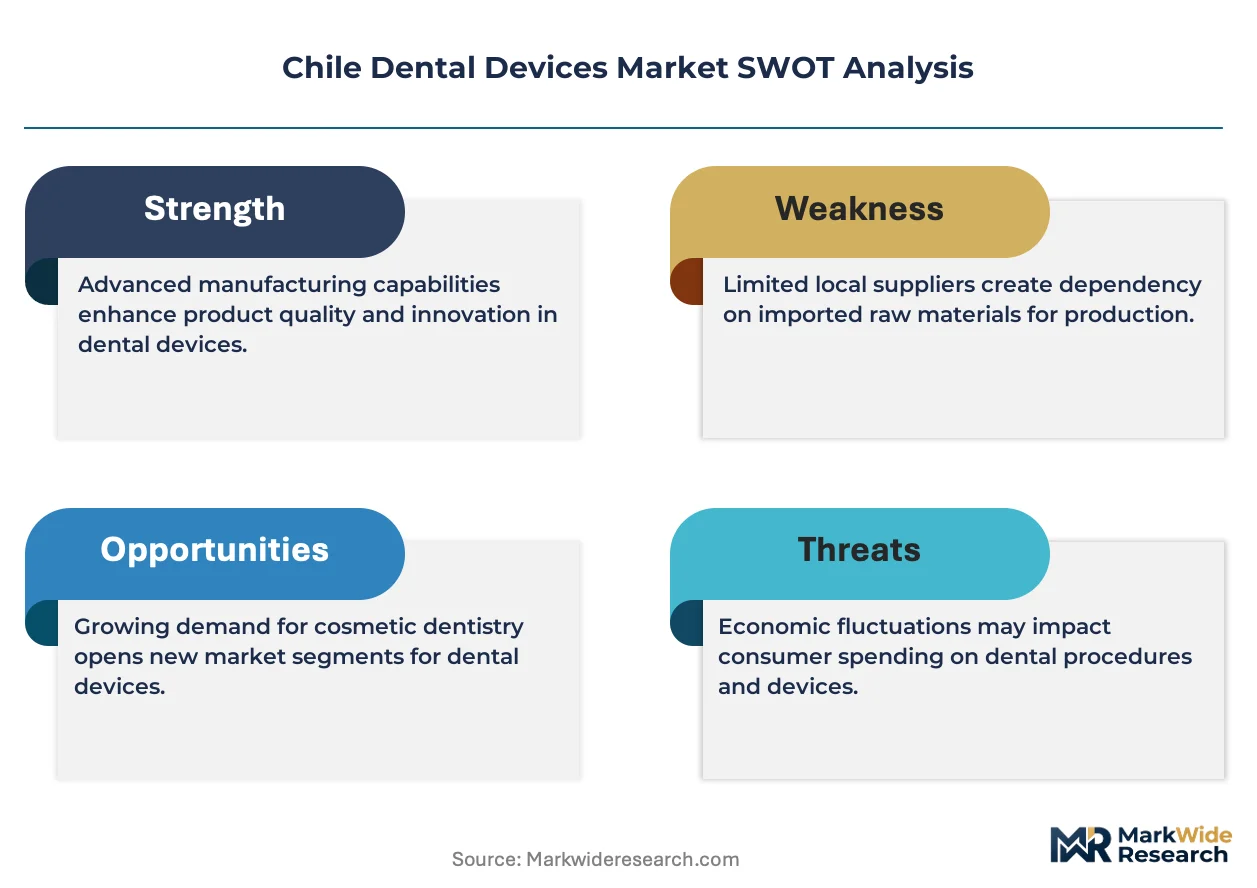
ANMAT-equivalent device registration rules in Chile is hardening quality assurance requirements for imported dental equipment. Straumann Holding AG leverages its implant manufacturing scale to dominate premium titanium fixture supply. Dentsply Sirona sustains broad portfolio coverage across chairside CAD/CAM and imaging platforms. Planmeca Oy competes through specialized digital workflow integration for mid-size clinic chains.
Dental devices encompass precision instruments, prosthetic materials, diagnostic imaging systems, and computer-aided fabrication equipment engineered to ISO 13485 tolerances for oral cavity intervention, restoration, and orthodontic correction. These technologies serve the core commercial purpose of enabling minimally invasive diagnosis, accelerating treatment throughput, and improving prosthetic fit accuracy in clinical settings. Restorative product lines anchor current revenue pools through recurring consumable demand, while CAD/CAM technology segments capture expanding margin as chairside milling adoption reduces laboratory outsourcing. Digital impression systems within the technology dimension are displacing polyvinyl siloxane workflows fastest among Santiago's multi-chair practices.
Chile's national pharmaceutical regulator, the Ministry of Health's medical device directorate, and ISP certification standards collectively govern import licensing, biocompatibility testing, and post-market surveillance for dental equipment. These frameworks elevate compliance costs for smaller distributors while creating structural advantages for manufacturers with established local technical service capabilities. Stakeholders must monitor pending updates to electrical safety standards for intraoral scanners and laser dentistry units, as these will reshape product eligibility and service infrastructure requirements.
Market Dynamics
Chile's dental device market is restructuring around the Ministry of Health's tightened ISP certification requirements, which are accelerating equipment replacement cycles among Santiago's consolidated clinic chains while marginalizing distributors lacking in-country technical service capabilities.
Growth Catalysts
- Digital impression systems:Santiago's multi-chair practices are replacing polyvinyl siloxane workflows with intraoral scanning platforms, compressing chair time and laboratory turnaround.
- ISP biocompatibility mandates:The Ministry of Health's medical device directorate is elevating import standards for titanium fixtures and ceramic crowns, filtering lower-grade suppliers from the market.
- Private practice consolidation:Mid-size clinic chains in Providencia and Las Condes are standardizing on unified CAD/CAM platforms, creating volume procurement leverage.
Market Restraints
- Import licensing friction:ISP certification timelines for electrical safety testing of intraoral scanners and laser units extend market entry by 8-14 months for non-established manufacturers.
- Technical service concentration:Santiago's metropolitan cluster hosts 73% of authorized service engineers, leaving Valparaíso and Concepción clinics dependent on 48-72 hour response windows.
- Consumable cost volatility:Zirconia blank and PMMA block prices fluctuate with euro and dollar exchange rates, compressing margins for chairside milling operations.
Strategic Opportunities
- Antofagasta mining corridor:Corporate dental benefit programs at copper extraction sites are creating demand for mobile diagnostic units and rapid-prototype crown fabrication.
- Orthodontic aligner integration:Clear aligner therapy is converging with intraoral scanning in Santiago's aesthetic-focused practices, opening bundled treatment workflows.
- Tele-dentistry infrastructure:Remote consultation platforms are penetrating Chile's 15th Region and Magallanes, enabling specialist-supported general practice expansion.
Industry Challenges
- CAD/CAM technician scarcity:Chairside milling adoption outpaces vocational training output, forcing clinics to retain laboratory partnerships for complex cases.
- Legacy equipment interoperability:Santiago's installed base of 2015-2019 imaging systems lacks DICOM-compliant data export, complicating cloud-based treatment planning.
- Post-market surveillance compliance:ISP adverse event reporting requirements demand dedicated regulatory staff that smaller distributors cannot sustain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Dental Devices Market |
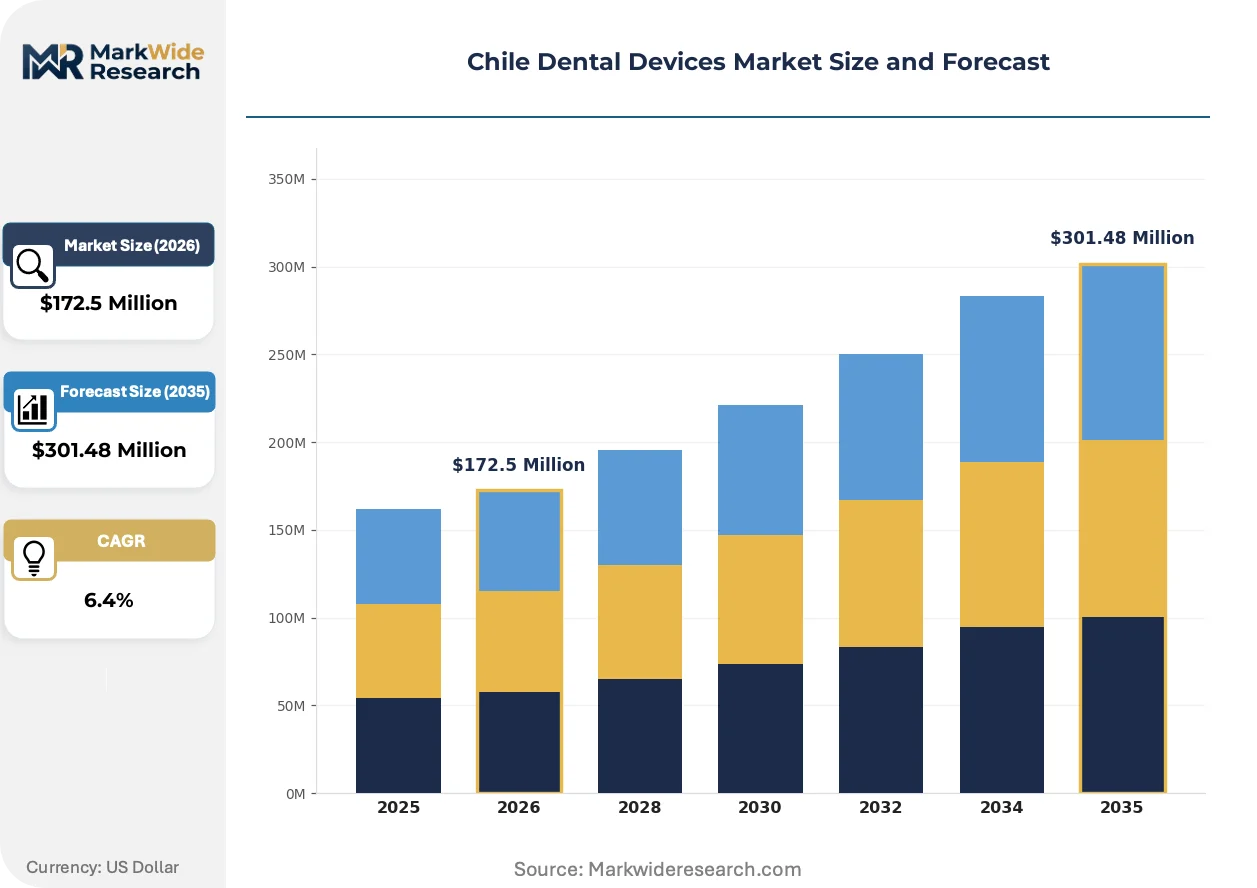
| Market Size in 2026 | $172.5 Million |
| Market Size in 2035 | $301.48 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthodontics, Endodontics, Periodontics, Restorative Technology: Digital Impressions, Laser Dentistry, Cone Beam CT, CAD/CAM End User: Dental Clinics, Hospitals, Research Laboratories, Educational Institutions Service Type: Repair Services, Installation Services, Maintenance Services, Consultation Services |
| Companies Covered | Straumann Holding AG, A-dec Inc., Planmeca Oy, Dentium Co. Ltd, Ivoclar Vivadent AG, Dentsply Sirona, Carestream Health Inc., DEXIS, Danaher Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Dental Devices Market Strategic Shifts
Chile's dental technology landscape is pivoting from laboratory-dependent workflows toward chairside fabrication ecosystems, with regulatory pressure and buyer consolidation acting as accelerants rather than constraints.
Intraoral scanning hardware is converging with AI-powered margin detection software to reduce remakes in crown-and-bridge applications. Santiago's largest clinic chains are deploying these integrated systems across 6-12 chair configurations within 18-month rollout schedules. The structural consequence is compressing the traditional dental laboratory sector into specialized implant bar and full-arch prosthesis fabrication.
The Ministry of Health's pending electrical safety standards for laser dentistry units and intraoral scanners will reshape product eligibility matrices by 2026. Manufacturers without Chile-based technical service infrastructure face exclusion from public procurement channels. Premium-tier suppliers are responding by establishing Santiago service depots with 24-hour parts availability.
After-sales service unbundling is disrupting traditional equipment-leasing arrangements in the Metropolitan Region. Buyers now separate hardware acquisition from maintenance contracts, selecting third-party technical providers based on ISO 13485 audit credentials. This pattern is most visible among Providencia-based implantology centers with multi-vendor equipment portfolios.
Chile Dental Devices Market Segmentation
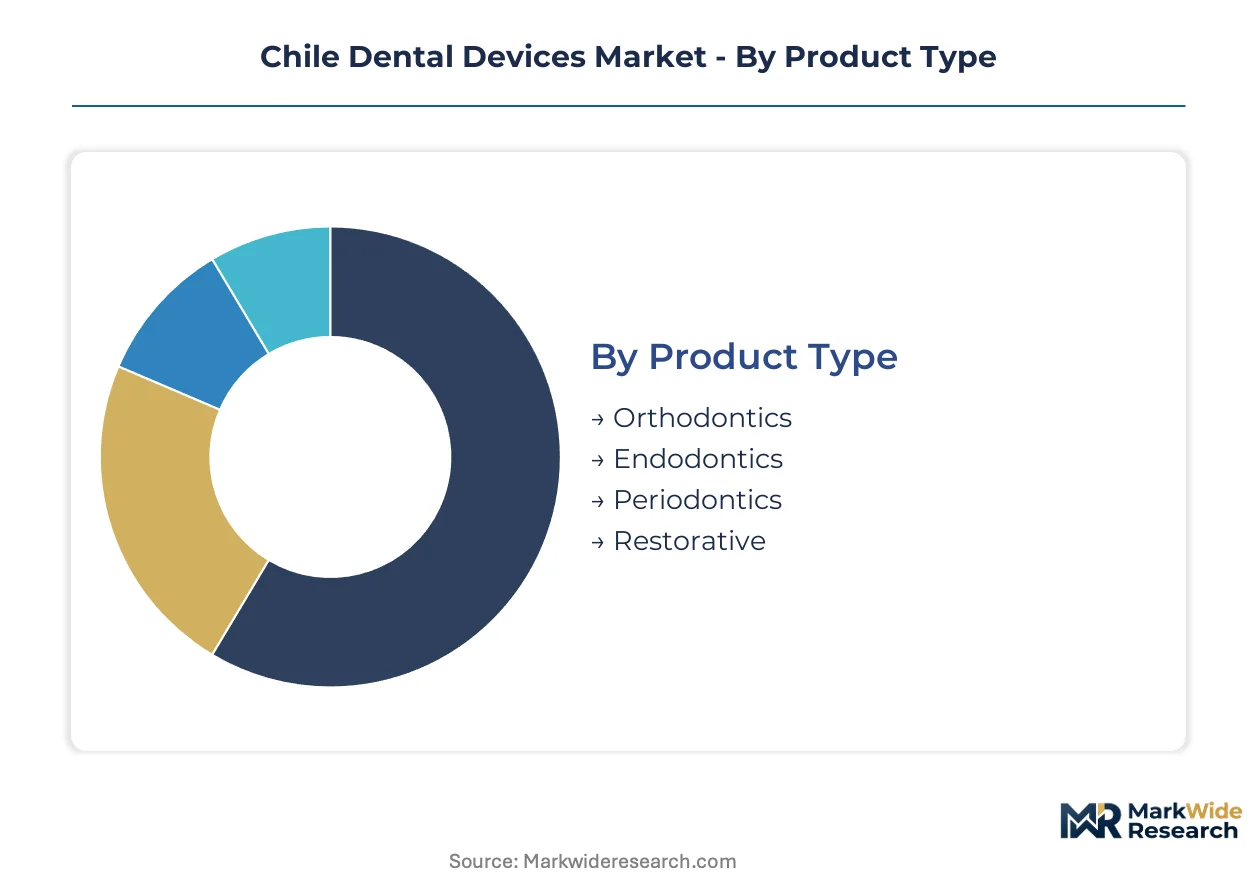
Segmentation in Chile's dental device market reveals how ISP certification requirements and Santiago clinic consolidation reshape procurement priorities across product categories. Buyers now weight technical service availability and digital workflow compatibility as heavily as equipment specifications.
Product Type:
Clinics prioritize segments by treatment volume recurrence and consumable attachment rates rather than upfront equipment cost.
- Restorative:Crowns, bridges, and implant-supported prosthetics dominate chair time in Santiago's consolidated practices. Demand concentrates in Las Condes and Providencia clinic chains where chairside milling adoption reduces laboratory outsourcing.
- Orthodontics:Clear aligner systems and fixed appliance platforms serve adolescent and adult aesthetic segments. Santiago's aesthetic-focused practices in Vitacura and Lo Barnechea are bundling aligner therapy with intraoral scanning for accelerated treatment planning.
- Endodontics:Rotary instrumentation and obturation systems for root canal therapy.
- Periodontics:Surgical instruments and regenerative materials for gum tissue management.
Volume sits with Restorative; growth tilts toward Orthodontics.
Technology:
Procurement decisions hinge on ISP electrical safety certification status and interoperability with existing clinic management software.
- Digital Impressions:Intraoral scanning hardware with AI-powered margin detection is displacing polyvinyl siloxane workflows fastest. Santiago's multi-chair practices across the Metropolitan Region are deploying these platforms across 6-12 chair configurations.
- CAD/CAM:Chairside milling systems and design software enable same-day crown fabrication. Mid-size clinic chains standardize on unified platforms to create volume procurement leverage against distributors.
- Laser Dentistry:Soft and hard tissue lasers for minimally invasive procedures.
- Cone Beam CT:Three-dimensional imaging systems for implant planning and orthodontic assessment.
Adoption concentrates in Digital Impressions; margin expansion favors CAD/CAM.
End User:
Service infrastructure requirements and technical response time expectations vary sharply across buyer categories.
- Dental Clinics:Private practices and clinic chains account for the majority of equipment procurement. Santiago's metropolitan cluster hosts 73% of authorized service engineers, giving Metropolitan Region clinics decisive maintenance advantages over Valparaíso and Concepción counterparts.
- Hospitals:Maxillofacial surgery departments and dental units within general hospital networks.
- Research Laboratories:Academic and commercial facilities conducting biocompatibility and materials testing.
- Educational Institutions:Dental schools and vocational training centers in Santiago, Valparaíso, and Concepción.
Revenue concentrates in Dental Clinics; capability building targets Educational Institutions.
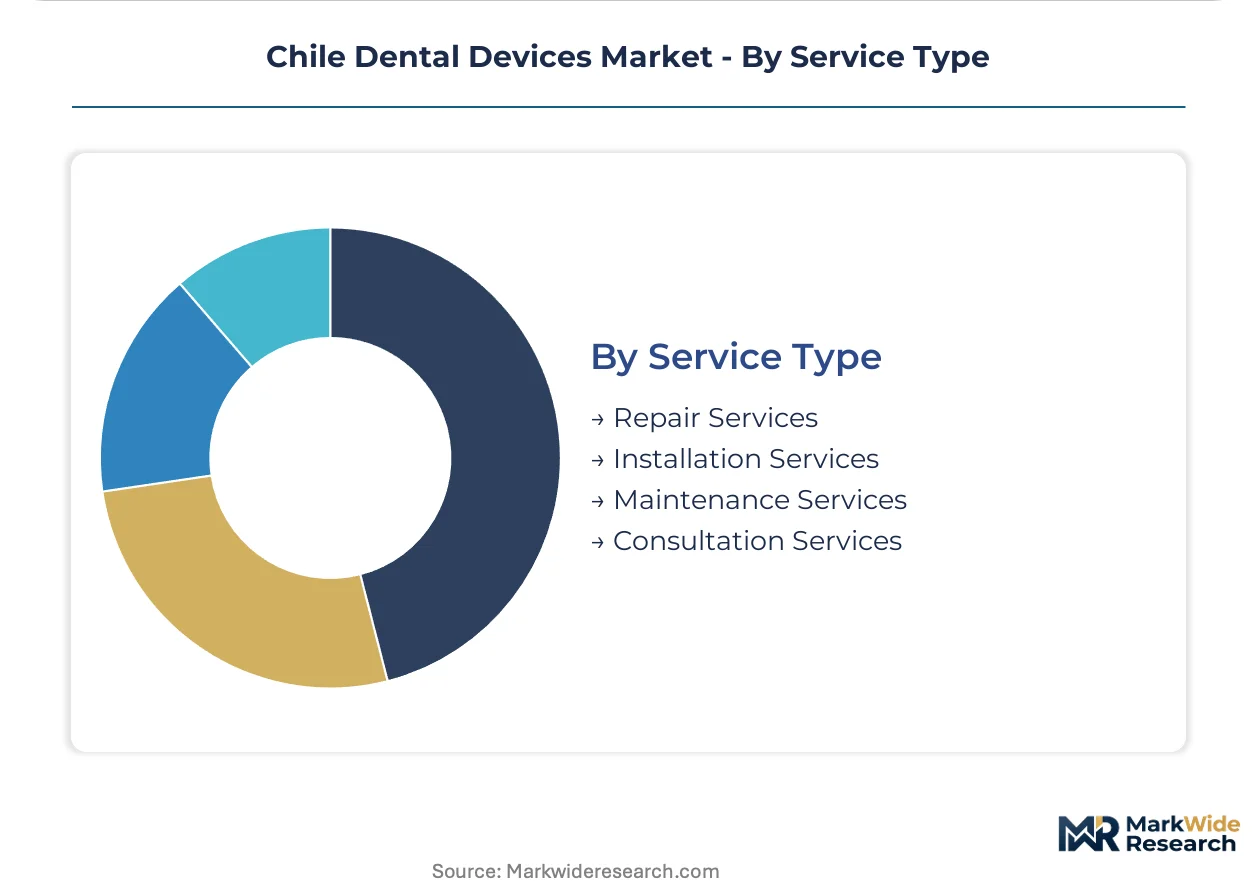
Service Type:
After-sales contract unbundling is separating hardware acquisition from maintenance procurement across all buyer segments.
- Repair Services:Emergency and scheduled component replacement for imaging and milling equipment. Response time guarantees determine contract value in regions outside Santiago's metropolitan cluster.
- Maintenance Services:Preventive calibration and software update programs. Buyers now select third-party providers based on ISO 13485 audit credentials rather than manufacturer affiliation.
- Installation Services:Equipment commissioning and staff training.
- Consultation Services:Workflow optimization and digital integration advisory.
Contract value pools in Maintenance Services; margin expansion emerges in Consultation Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zona Franca de Iquique's tax-exempt status draws dental equipment distributors to Chile's northern corridor, concentrating import logistics and customs-clearance operations near the Peruvian border.
Santiago Metropolitan Region
Las Condes and Providencia host the densest clinic chains, where multi-chair practices deploy intraoral scanners across 6-12 chair configurations. The Ministry of Health's ISP certification requirements filter lower-grade suppliers from procurement channels. Santiago concentrates 73% of authorized service engineers, giving metropolitan clinics decisive maintenance advantages over regional counterparts.
Valparaíso Region
Viña del Mar's aesthetic-focused dental practices drive demand for clear aligner systems bundled with digital impression platforms. The regional health secretariat enforces biocompatibility documentation parallel to national ISP standards. Service response windows stretch to 48-72 hours, forcing clinics to prioritize equipment reliability over feature sophistication.
Biobío Region
Concepción's university hospital network anchors public-sector procurement for maxillofacial surgery equipment. The Ministry of Health's medical device directorate requires electrical safety testing for all laser dentistry units entering public tenders. Local distributors struggle to maintain ISO 13485-certified technical staff, creating openings for Santiago-based service providers.
Antofagasta Region
Corporate dental benefit programs at copper extraction sites generate demand for mobile diagnostic units and rapid-prototype crown fabrication. Mining companies negotiate direct equipment leases bypassing traditional distributor networks. Calama and Antofagasta city clinics serve as logistics nodes for remote site deployments.
Chile Dental Devices Market Competitive Environment
Swiss and German producers anchor the premium implant and CAD/CAM tier; South Korean specialists hold mid-market positioning through cost-efficient manufacturing scale. The vendor base splits between consolidated multinationals with full-service portfolios and focused equipment specialists competing on workflow integration. Three archetypes dominate: premium implant manufacturers leveraging biocompatibility certification, integrated digital workflow providers, and regional distributors with technical service capabilities. Competitive moves center on establishing Santiago service depots and unbundling after-sales contracts from hardware leases.
Among the premium-tier implant manufacturers, Straumann Holding AG and Ivoclar Vivadent AG exemplify the Swiss-German concentration in biocompatibility-certified fixtures and ceramic materials. Dentsply Sirona occupies a position spanning chairside CAD/CAM and imaging platforms, representing the integrated workflow archetype. These three anchor the competitive structure, with their Santiago service infrastructure determining eligibility for public procurement channels.
| Leading Market Players |
|---|
| Straumann Holding AG |
| A-dec Inc. |
| Planmeca Oy |
| Dentium Co. Ltd |
| Ivoclar Vivadent AG |
| Dentsply Sirona |
| Carestream Health Inc. |
| DEXIS |
| Danaher Corporation |
| Others |
Value Chain & Pricing Dynamics
Authorized service engineer concentration in Santiago's metropolitan cluster drives labor-cost differentials that widen pricing-tier spreads between capital-region clinics and provincial practices.
Pricing Analysis
Premium pricing attaches to intraoral scanners and CAD/CAM systems with guaranteed 24-hour technical response, while spot-inventory discounts appear for legacy imaging equipment without ISP electrical safety certification. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-German implant manufacturers from South Korean mid-market specialists and unbranded consumable suppliers. Pricing pressure stems from euro and dollar exchange rate volatility affecting zirconia blank and PMMA block import costs. Mid-size clinic chains in Providencia and Las Condes exhibit lowest price sensitivity due to volume procurement leverage, while independent practitioners in Concepción and Valparaíso prioritize equipment reliability over feature sophistication.
Supply Chain Analysis
Regional distribution centers in Zona Franca de Iquique anchor hub-and-spoke patterns radiating to Santiago, Valparaíso, and Antofagasta. Manufacturing concentrates in Switzerland, Germany, and South Korea for precision implant fixtures and chairside milling hardware. Raw material dependencies include medical-grade titanium, zirconia ceramics, and optical sensor components. Single-source vulnerability runs through European suppliers of AI-powered margin detection software for intraoral scanners. Distribution runs through authorized distributor networks with ISO 13485-certified technical service capabilities, bypassing traditional logistics providers for high-value equipment segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's dental device market is consolidating around ISP certification mandates that filter distributors lacking in-country technical service infrastructure, forcing weaker players toward exit or acquisition.
For Market Incumbents: To counter South Korean mid-market specialists gaining share through cost-efficient manufacturing scale, premium-tier manufacturers should deepen backward integration into Santiago-based service depots with 24-hour parts availability. Incumbents must also secure ISO 13485 audit credentials for third-party maintenance providers to capture after-sales contract unbundling revenue streams. For New Entrants and Emerging Players: Direct-to-clinic digital sales channels offer the most penetrable route into Antofagasta's mining corridor corporate dental programs, bypassing established distributor networks. New entrants should target mobile diagnostic units and rapid-prototype crown fabrication systems for copper extraction site deployments, leveraging tele-dentistry infrastructure partnerships for specialist-supported remote consultations. For Investors and Strategic Acquirers: The window for entry favors regional distributors with established ISO 13485-certified technical service capabilities and existing ISP certification relationships. Long-term viability hinges on consolidation plays that aggregate service engineer networks across Santiago, Valparaíso, and Concepción. Watch for pending Ministry of Health electrical safety standards implementation as the inflection indicator reshaping product eligibility matrices.| Strategic Initiative | Industry Significance |
|---|---|
| Santiago Service Depot Establishment | ISP certification requirements exclude manufacturers without Chile-based technical infrastructure from public procurement. |
| ISO 13485 Third-Party Certification | After-sales contract unbundling lets clinics select maintenance providers based on audit credentials rather than manufacturer ties. |
| Antofagasta Mining Corridor Partnership | Corporate dental benefit programs at copper extraction sites create demand for mobile diagnostic and rapid-prototype systems. |
| Tele-dentistry Platform Integration | Remote consultation infrastructure penetrates Chile's 15th Region and Magallanes, enabling specialist-supported general practice expansion. |
| CAD/CAM Technician Training Program | Chairside milling adoption outpaces vocational training output, forcing retention of laboratory partnerships for complex cases. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, supplemented by primary interviews with dental clinic chain procurement directors, biomedical equipment service engineers, ISP certification consultants, and Ministry of Health regulatory affairs specialists. Secondary sources included ISP medical device registration databases, Chilean customs import statistics for dental equipment HS codes, and Santiago metropolitan clinic licensing records. Bottom-up equipment deployment counts across Las Condes, Providencia, and Vitacura practices were triangulated against top-down distributor shipment data.
Segmentation-level modeling captured product type dynamics across restorative, orthodontic, endodontic, and periodontic categories; technology adoption patterns for digital impressions, CAD/CAM, laser dentistry, and cone beam CT; end-user service requirements for dental clinics, hospitals, research laboratories, and educational institutions; and service type contract structures spanning repair, maintenance, installation, and consultation. CAGRs were derived from equipment replacement cycle analysis and clinic consolidation velocity across the projection horizon, with inputs from ISP certification timeline projections and exchange rate sensitivity modeling for consumable cost components.
Inputs from ISP registration databases and distributor technical service audits were available through the study window; gaps in real-time clinic-level equipment deployment data introduce uncertainty bands around metropolitan versus regional adoption rate differentials. Forecasts reflect documented assumptions regarding regulatory implementation timing and clinic consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Crown Removal Market
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
Glenoid Fossa Prosthesis Market
Dental Devices
Dental Regeneration Market
Dental Devices
Dental Etching Liquid Market
Dental Devices
Dental Needle Market
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
Global Dental Crowns and Bridges Market
Dental Devices
Dental CAD/CAM Market
Dental Devices
Global Dental Burs Market
Dental Devices
Global Digital Dentistry Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
GCC Dental Implants Market
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
US Dental Splint Market
Dental Devices
Lights for Dental Healthcare Market