
 Orthodontics Market | 2026-2036
Orthodontics Market Size, Share, and Industry Trends Forecast 2026-2036
Orthodontics Market Intelligence
The EU Medical Device Regulation is decoupling European demand from legacy metal bracket systems by mandating enhanced biocompatibility traceability and post-market surveillance. Align Technology, Inc. leverages its proprietary SmartTrack material science to sustain premium positioning across clear aligner workflows. Dentsply Sirona anchors its orthodontic portfolio through integrated CAD/CAM chairside ecosystems that compete with standalone appliance manufacturers. 3M Company differentiates via advanced ceramic bracket formulations that dominate aesthetic-conscious patient segments in North America and Asia.
Orthodontics encompasses the diagnosis, prevention, and correction of malpositioned teeth and jaws through fixed appliances, removable devices, and adjunctive therapies using materials such as nickel-titanium archwires, medical-grade polymers, and ceramic composites engineered to deliver controlled force levels between 25–150 grams per tooth. The field serves both functional occlusion restoration and facial aesthetic optimization across pediatric, adolescent, and adult patient populations. Clear aligners represent the fastest-expanding product category as intraoral scanner penetration and AI-driven treatment planning software compress case turnaround times and expand general dentist participation. Digital impressions and 3D printing technology segments command disproportionate margin pools by converting labor-intensive laboratory workflows into chairside or centralized manufacturing models that reduce remake rates and improve fit precision.
The FDA Center for Devices and Radiological Health regulates orthodontic devices through premarket notification and quality system requirements that shape product development timelines and clinical evidence standards for novel materials. The EU MDR and REACH frameworks impose substance restriction and notified body oversight that filter market access for Asian manufacturers lacking European authorized representatives. Stakeholders must monitor evolving reimbursement parity between aligner and fixed appliance therapies across national health systems and private insurance schemes as treatment modality economics determine practice technology investment priorities.
Market Dynamics
Digital intraoral scanning is compressing orthodontic treatment planning cycles from weeks to days, forcing laboratories and chairside providers to reconfigure staffing models around same-day appliance production rather than traditional impression shipping workflows.
Growth Catalysts
- EU MDR biocompatibility mandates:Stricter post-market surveillance requirements for nickel-titanium archwires and polymer aligners are filtering out non-compliant imports and consolidating demand around certified European supply chains.
- Teen and young adult aesthetic preference:Social media visibility pressures are accelerating clear aligner requests among patients aged 12–25, expanding addressable case volume beyond traditional fixed-appliance candidacy.
- AI-driven treatment simulation:Machine learning algorithms predicting tooth movement outcomes are reducing case refinement rates and enabling general dentists to manage moderate malocclusion cases previously referred to specialists.
Market Restraints
- Medical-grade polymer cost volatility:Specialized polyethylene terephthalate glycol and thermoplastic polyurethane resins face petrochemical feedstock price swings that compress aligner manufacturing margins.
- Notified body capacity bottlenecks:EU MDR designation shortages for orthodontic device certification are extending European market entry timelines for Asian manufacturers lacking established European authorized representatives.
- Direct-to-consumer substitution threat:Unsupervised remote aligner services compete on price against clinically supervised treatment, risking patient safety incidents that trigger regulatory backlash against the entire category.
Strategic Opportunities
- India's orthodontic infrastructure gap:Low specialist-to-population ratios in tier-2 and tier-3 cities create whitespace for teledentistry-linked aligner workflows and mobile scanning units.
- Chairside 3D printing convergence:Integration of photopolymer printers with intraoral scanners enables same-day clear aligner and retainer production, capturing margin previously allocated to centralized laboratories.
- US IRA preventive care incentives:Expanded dental coverage in federally subsidized health plans is reducing out-of-pocket burdens for adult orthodontic treatment, stimulating demand among previously price-excluded demographics.
Industry Challenges
- Digital workflow integration complexity:Legacy practice management systems require costly middleware development to sync with cloud-based treatment planning platforms, delaying technology adoption for mid-sized practices.
- Orthodontist-digital technician skill mismatch:Shortage of professionals trained in both clinical biomechanics and CAD/CAM software is constraining the scale-up of in-house aligner production capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthodontics Market |
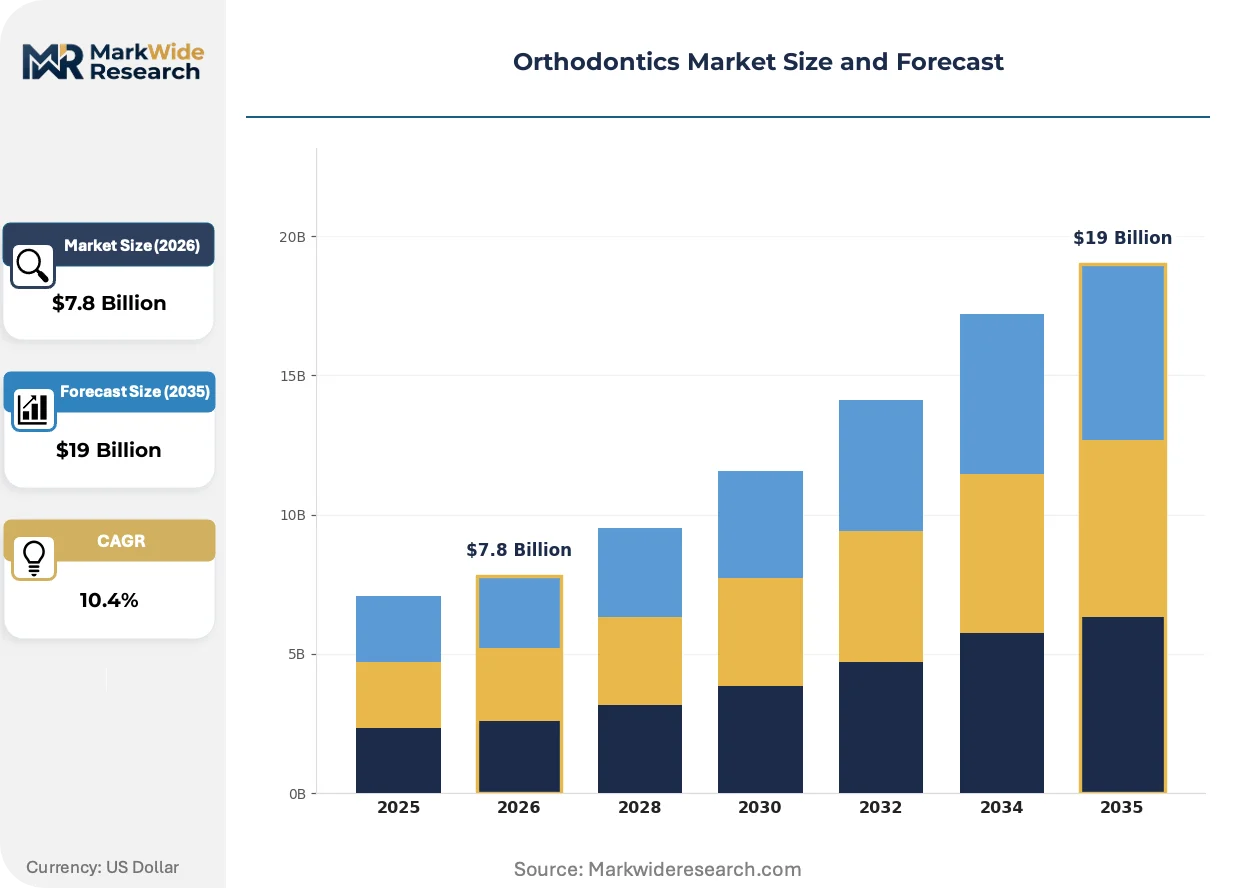
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $19 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brackets, Archwires, Elastics, Retainers, Aligners, Bonding Agents Technology: 3D Printing, CAD/CAM, Digital Impressions, Laser Scanning, Computer-Aided Design, Intraoral Scanners Application: Malocclusion Correction, Teeth Alignment, Bite Correction, Jaw Positioning, Space Maintenance, Facial Esthetics End User: Orthodontists, Dental Clinics, Hospitals, Specialty Clinics, Dental Laboratories, Academic Institutions |
| Companies Covered | Align Technology, Inc., Dentsply Sirona, Envista Holdings Corporation, Solventum, 3M Company, American Orthodontics, Ormco Corporation, Institut Straumann AG, Henry Schein Orthodontics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthodontics Market Strategic Shifts & Innovations
Orthodontic care delivery is fragmenting across multiple production models simultaneously, with centralized manufacturing, distributed chairside printing, and hybrid teledentistry workflows competing for dominance in different patient segments and geographies.
SmartTrack multilayer polymer engineering is unifying force delivery precision with aesthetic transparency in clear aligner systems. General dental practices in suburban United States markets are adopting these materials at twice the rate of metropolitan centers. This convergence is compressing the traditional referral pathway between generalists and orthodontic specialists.
REACH substance restriction protocols are tightening traceability requirements for nickel release in fixed appliances. Manufacturers must now document full material provenance from ore sourcing through final sterilization. Ceramic bracket suppliers in Germany and Switzerland are capturing volume as metal-system vendors requalify their supply chains.
Subscription-based aligner monitoring is displacing per-visit fee structures in private orthodontic chains. Patients receive remote progress tracking via smartphone imaging rather than monthly chair time. This model is achieving highest penetration in United Kingdom and Australian markets where labor costs pressure traditional appointment economics.
Orthodontics Market Segmentation
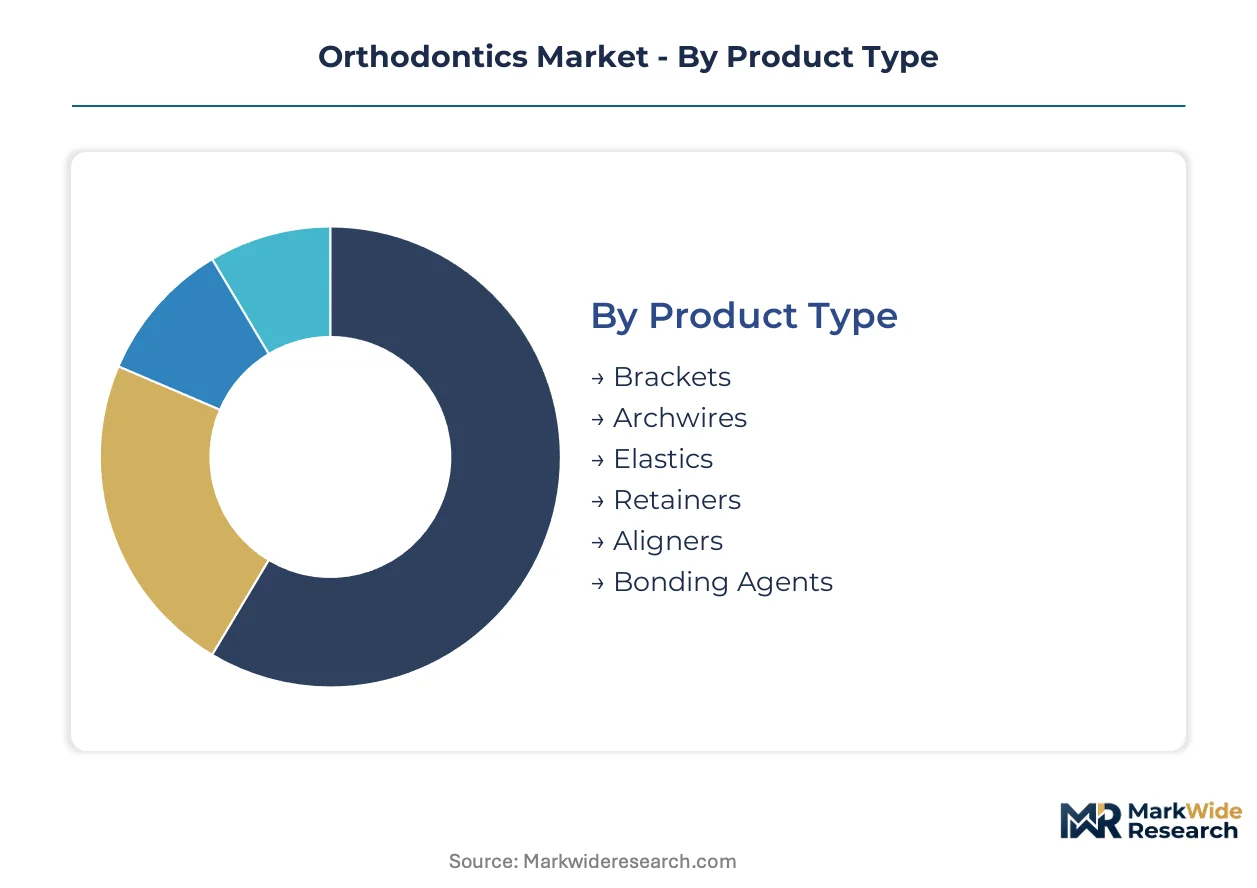
Orthodontic device segmentation reveals how treatment modality choices cascade through procurement decisions, technology investments, and reimbursement negotiations. Understanding these category boundaries helps stakeholders identify where digital workflows are compressing margins versus where specialized biomechanics sustain premium positioning.
Product Type:
Patient aesthetic tolerance and treatment complexity together determine which appliance categories command priority in practice procurement budgets.
- Aligners:Multilayer thermoplastic polymers engineered for sequential force delivery between 25–150 grams per tooth stage. Demand concentrates among teen and young adult patients in the United States and Germany where social media visibility pressures override cost sensitivity.
- Brackets:Ceramic, metal, or composite fixtures bonded to tooth surfaces for archwire engagement. Ceramic formulations dominate aesthetic-conscious segments across North American suburban practices and Asian metropolitan centers.
- Archwires:Nickel-titanium or stainless steel alloys providing controlled orthodontic force. Nickel-titanium superelastic variants face EU MDR biocompatibility scrutiny affecting import eligibility.
- Retainers:Removable or fixed devices maintaining post-treatment tooth position. Vacuum-formed clear retainers leverage aligner manufacturing infrastructure.
- Elastics:Latex or synthetic rubber bands applying interarch forces. Supply chains concentrate in Southeast Asian polymer processing hubs.
- Bonding Agents:Light-cure or chemical-cure adhesives securing brackets to enamel surfaces. Formulation improvements target moisture tolerance for reduced failure rates.
Aligners lead on scale; aligners also lead on momentum as general dentist participation expands addressable case volume.
Technology:
Capital deployment intensity varies dramatically across digital workflow stages, with front-end scanning and back-end production commanding disproportionate investment.
- Intraoral Scanners:Optical or confocal imaging devices capturing sub-50-micron accuracy digital impressions. Adoption accelerates in United States private orthodontic chains seeking same-day appliance turnaround.
- 3D Printing:Photopolymer or thermoplastic extrusion systems fabricating aligners, retainers, and surgical guides. Chairside installations in German and Swiss practices capture laboratory margin pools.
- CAD/CAM:Computer-aided design and manufacturing integrating treatment planning with appliance production. Dentsply Sirona and Align Technology compete through vertically integrated ecosystem control.
- Digital Impressions:Cloud-based storage and transfer protocols replacing physical model shipping. Compression of turnaround times from weeks to days forces staffing model reconfiguration.
- Laser Scanning:High-resolution surface mapping for complex craniofacial cases. Concentrated in academic medical centers and specialty craniofacial units.
- Computer-Aided Design:Treatment simulation software predicting tooth movement outcomes. Machine learning integration reduces case refinement rates and enables generalist case management.
Intraoral scanners lead on installed base; 3D printing leads on expansion trajectory as hardware costs decline and photopolymer biocompatibility improves.
Application:
Clinical indication severity determines whether cases route to specialist orthodontists or remain within general dental practice scope.
- Malocclusion Correction:Comprehensive treatment of Class I, II, and III bite discrepancies. Moderate cases increasingly managed by general dentists using AI-assisted planning tools.
- Teeth Alignment:Anterior aesthetic repositioning without significant occlusal change. Clear aligner penetration highest in this indication across United States, United Kingdom, and Australian markets.
- Bite Correction:Functional occlusion restoration addressing masticatory efficiency. Requires specialist oversight for complex skeletal discrepancies.
- Jaw Positioning:Orthognathic surgical planning and post-surgical orthodontic finishing. Concentrated in hospital-based craniofacial centers.
- Space Maintenance:Pediatric interceptive appliances preserving arch length. Band-and-loop and distal shoe designs persist in pediatric dental practices.
- Facial Esthetics:Treatment planning incorporating soft tissue and profile optimization. Demand driver in Asian markets where aesthetic outcomes influence social and professional advancement.
Teeth alignment leads on volume; malocclusion correction leads on value per case as complexity sustains specialist fee premiums.
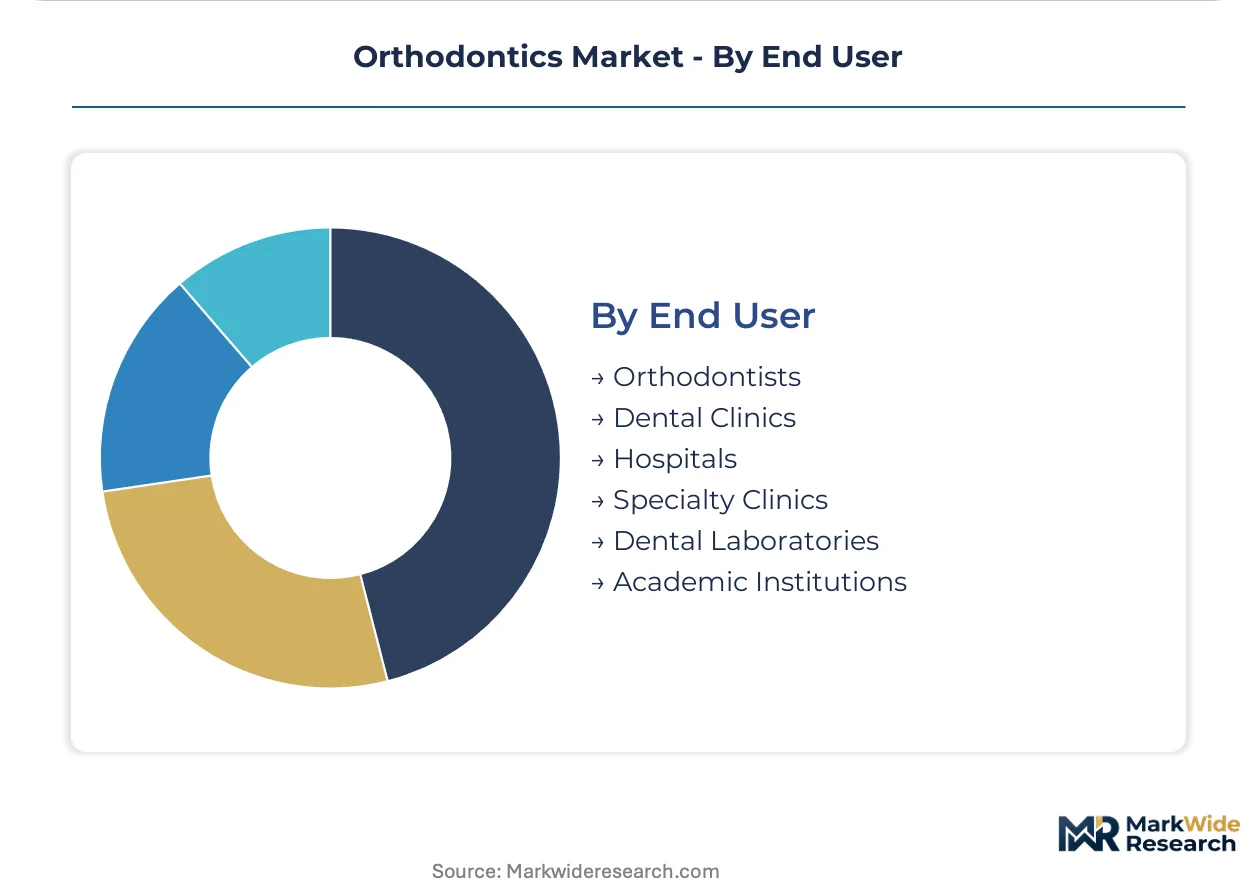
End User:
Provider type determines purchasing authority, with institutional procurement following different timelines than solo practitioner decisions.
- Orthodontists:Specialists completing advanced residency training in dentofacial orthopedics. Concentrated in United States urban corridors and European metropolitan clusters.
- Dental Clinics:General practice settings incorporating orthodontic services. Aligner adoption twice as fast in suburban versus metropolitan United States locations.
- Dental Laboratories:Centralized production facilities fabricating appliances from digital prescriptions. Margin pressure from chairside 3D printing adoption forces consolidation.
- Hospitals:Academic medical centers and community hospitals managing complex craniofacial cases. Orthognathic surgical coordination requires inpatient infrastructure.
- Specialty Clinics:Pediatric dentistry and prosthodontic practices offering limited orthodontic services. Teledentistry integration expanding reach in underserved geographies.
- Academic Institutions:Dental schools and residency programs training next-generation providers. Equipment purchasing influenced by curriculum accreditation requirements.
Orthodontists lead on case complexity; dental clinics lead on patient volume expansion as generalist scope broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthodontic device manufacturing originated in the United States during the early twentieth century with standardized bracket systems, then diffused to Germany and Switzerland through precision engineering traditions. Contemporary demand concentrates in three distinct national clusters where regulatory frameworks and reimbursement structures shape competitive positioning.
United States
Private orthodontic chains and dental service organizations drive capital deployment into digital workflows across suburban markets. The FDA Center for Devices and Radiological Health regulates clear aligners through premarket notification pathways that shape clinical evidence requirements. Dallas-Fort Worth and Phoenix metropolitan corridors host dense concentrations of aligner-focused practices competing on same-day turnaround capabilities.
Germany
EU MDR biocompatibility mandates filter market access for nickel-titanium archwire imports while ceramic bracket demand expands among aesthetic-conscious patient segments. ECHA REACH protocols enforce full material provenance documentation from ore sourcing through sterilization. Munich and Stuttgart industrial clusters anchor precision ceramic manufacturing for export throughout European markets.
China
Rapid urbanization and expanding middle-class dental awareness compress treatment initiation ages toward adolescent populations. NMPA medical device registration requirements for orthodontic materials intensify post-market surveillance obligations. Shenzhen and Shanghai manufacturing hubs integrate photopolymer 3D printing with intraoral scanner distribution networks serving domestic and Southeast Asian export demand.
India
Specialist orthodontist-to-population ratios below OECD benchmarks create whitespace for teledentistry-linked aligner workflows in tier-2 and tier-3 cities. CDSCO medical device rules impose import licensing requirements that favor domestic manufacturing partnerships. Bangalore and Hyderabad technology corridors incubate mobile scanning unit deployments connecting remote patient populations to centralized treatment planning.
Switzerland
Premium ceramic bracket and precision archwire manufacturing sustains export competitiveness through Swissmedic quality system certifications. Dual carbon goals under federal environmental frameworks pressure supply chain decarbonization for polymer-based aligner materials. Basel and Zürich precision engineering clusters maintain captive production of medical-grade nickel-titanium alloys with full biocompatibility traceability.
Orthodontics Market Key Industry Players
Premium-margin players sit above commodity-margin players across material science sophistication and digital workflow integration depth. The vendor base stratifies into three tiers: vertically integrated ecosystem controllers, specialized appliance manufacturers, and regional distributors with limited manufacturing capabilities. Strategic archetypes include proprietary polymer developers, chairside CAD/CAM integrators, and ceramic formulation specialists. Dominant competitive moves encompass backward integration into photopolymer resin production and strategic partnerships with intraoral scanner hardware vendors.
Among United States-based technology developers, Align Technology, Inc. and 3M Company exemplify divergent archetypes within premium-margin positioning. Align Technology, Inc. occupies a position representing proprietary multilayer polymer engineering and cloud-based treatment planning ecosystems. 3M Company anchors the advanced materials tier through ceramic bracket formulation expertise. Germany-based Dentsply Sirona sits within the integrated equipment category, representing chairside CAD/CAM convergence strategies that compete with standalone appliance vendors.
| Leading Market Players |
|---|
| Align Technology, Inc. |
| Dentsply Sirona |
| Envista Holdings Corporation |
| Solventum |
| 3M Company |
| American Orthodontics |
| Ormco Corporation |
| Institut Straumann AG |
| Henry Schein Orthodontics |
| Others |
Cost & Logistics Intelligence
Medical-grade polymer resin indices cascade through orthodontic supply chains into three distinct pricing tiers that separate premium SmartTrack-licensed aligners from standard thermoplastic alternatives and economy-grade fixed appliances. This cost transmission mechanism concentrates margin capture among vertically integrated manufacturers while compressing returns for standalone bracket and archwire suppliers facing EU MDR compliance burdens.
Pricing Analysis
Subscription-based per-case licensing dominates clear aligner economics, with price differentiation anchored in proprietary material science certification and treatment planning software access. Cost compression in standard-tier thermoplastics intensifies as Asian manufacturers scale PETG and TPU resin processing, while premium-tier buyers show lowest price sensitivity due to clinical outcome guarantees and reduced refinement liability. Economy metal bracket segments face acute pricing pressure from centralized dental laboratory consolidation and chairside 3D printing adoption.
Supply Chain Analysis
Dual-sourcing requirements for nickel-titanium archwires and medical-grade polymers mandate multi-supplier qualification across German, Swiss, and Chinese manufacturing bases. Raw material dependencies center on petrochemical feedstocks for aligner resins, nickel ore for superelastic wires, and zirconia precursors for ceramic brackets. Single-source vulnerability concentrates in EU MDR-certified nickel-titanium smelters, where notified body capacity constraints extend qualification timelines. Distribution runs through private orthodontic chains and dental service organizations in the United States, direct-to-clinic shipments in Germany, and hybrid laboratory-clinic networks in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
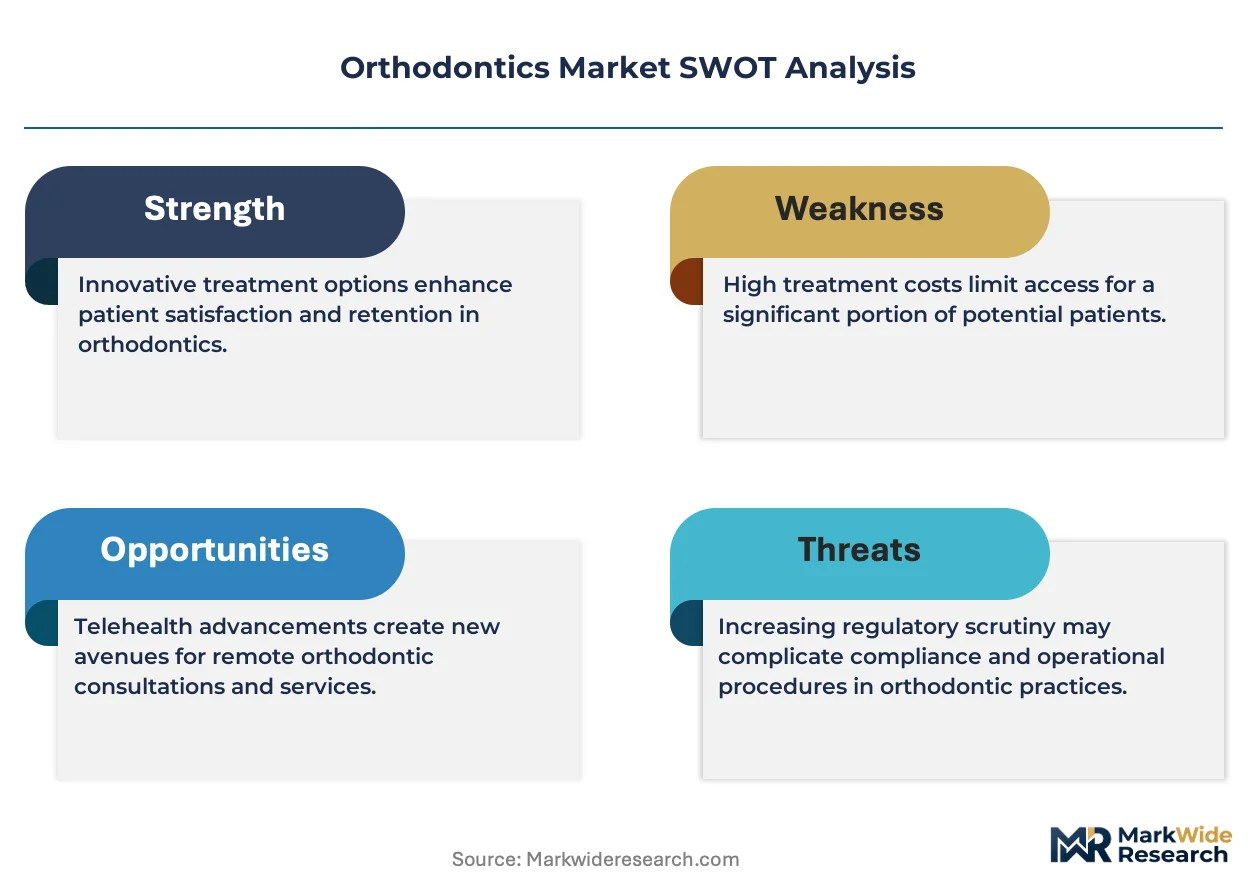
Orthodontics functions as a regulatory compounder where EU MDR biocompatibility mandates and FDA post-market surveillance requirements continuously elevate compliance barriers that filter marginal competitors and consolidate demand around certified supply chains.
For Market Incumbents: Extend proprietary material science moats through backward integration into photopolymer resin production and captive nickel-titanium alloy smelting. Direct-to-consumer substitution threats demand reinforced clinical outcome data packages that justify supervised treatment premiums against remote aligner competitors. Capacity addition in Swiss and German precision manufacturing clusters captures EU MDR-compliant volume as Asian imports face extended certification timelines. For New Entrants and Emerging Players: Tier-2 and tier-3 Indian cities present whitespace for teledentistry-linked aligner workflows targeting orthodontist-to-population ratios below OECD benchmarks. Mobile scanning unit deployments connecting remote patient populations to centralized AI-driven treatment planning offer the most penetrable go-to-market angle, bypassing fixed infrastructure requirements that constrain incumbent expansion economics. For Investors and Strategic Acquirers: Asymmetric upside sits with chairside CAD/CAM integrators possessing both intraoral scanner distribution networks and photopolymer 3D printing capabilities. Long-term viability over a multi-year horizon favors acquisition targets with dual revenue streams from appliance manufacturing and software licensing. The signal to watch is general dentist aligner case volume growth as an inflection indicator for addressable market expansion beyond specialist orthodontist channels.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Notified body designation secures market access as Asian competitors face exclusion. |
| Photopolymer Resin Backward Integration | Captive supply of medical-grade polymers insulates margin from petrochemical volatility. |
| AI Treatment Planning Platform Launch | Machine learning algorithms reduce case refinement rates and enable generalist participation. |
| Teledentistry Infrastructure Partnership | Remote monitoring capabilities capture subscription revenue from price-sensitive demographics. |
| Ceramic Bracket Formulation R&D | Advanced zirconia composites capture aesthetic-conscious segments in North America and Asia. |
Research Approach
Direct dialogue with orthodontic specialists, dental laboratory directors, biomedical materials engineers, and GPO contracts managers grounded qualitative insights that secondary validation subsequently cross-referenced. FDA 510(k) filings, EU MDR notified body certificates, customs trade records for nickel-titanium alloys and polymer resins, and hospital procurement database extracts provided quantitative anchors. Bottom-up installation counts for intraoral scanners and top-down resin consumption estimates triangulated market sizing across product categories.
Segment-level revenue projections across aligners, brackets, archwires, and digital workflow technologies emerged from integrated modeling of patient demographic trends, reimbursement parity evolution, and technology adoption curves over the projection horizon. CAGRs derived from regression analysis of historical procedure volumes against scanner penetration rates and general dentist participation indices. Industry-specific forecast inputs incorporated EU MDR transition timelines and NMPA registration queue depths.
Underlying measurement precision varies by segment; digital workflow technologies carry tighter precision than traditional appliance categories due to disclosed hardware shipments and software licensing disclosures. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and reimbursement policy continuity. Deviation in FDA direct-to-consumer aligner enforcement or EU notified body capacity expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Self-Ligating Bracket Sales Market
Dental Devices
Dental Anaesthetic Market
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
Global Dental Microscope Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
Dental Suction Systems Market
Dental Devices
Dental Etching Liquid Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Dental Apex Locator Market
Dental Devices
Global Dental Obturators Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Dental Whitening Lamps Market
Dental Devices
Global Digital Dentistry Market
Dental Devices
Dental Prosthetics Market
Dental Devices
3D-Printed Dental Restoration Market
Dental Devices
Dental Hand Tools Market