
 Italy Dental Devices Market | 2026-2036
Italy Dental Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Dental Devices Market Foresight
Private dental clinics is restructuring Italy's procurement landscape as practitioners invest in chairside digital workflows. Straumann Group anchors its position through implantology-focused R&D pipelines. Dentsply Sirona competes via integrated CAD/CAM ecosystems spanning imaging to restoration milling. GC Corporation specializes in glass ionomer and composite formulations for conservative dentistry.
Dental devices encompass instruments, equipment, and materials engineered to ISO 6875 biocompatibility standards for oral cavity diagnosis, treatment, and prosthetic rehabilitation. Restorative materials capture recurring revenue from resin composite and ceramic replacement cycles, while CAD/CAM systems command capital-intensive placements with multi-year depreciation schedules. Cone Beam CT is displacing conventional panoramic radiography in implant planning workflows across high-volume practices.
Italy's Ministry of Health enforces EU MDR conformity assessment for Class IIa and above dental devices, while ANMD (Agenzia Nazionale per i Dispositivi Medici) coordinates post-market surveillance and vigilance reporting. CE marking under MDR extends technical documentation requirements, compressing timelines for smaller manufacturers seeking market access. Stakeholders must monitor ANMD guidance on software-as-medical-device classification for AI-powered radiology tools.
Market Dynamics
Digital workflow integration is restructuring Italy's dental device procurement as private clinics in Lombardy and Veneto accelerate chairside CAD/CAM adoption ahead of southern regions. This technological bifurcation concentrates capital deployment in northern metropolitan clusters while compressing replacement cycles for conventional radiography equipment.
Growth Catalysts
- EU MDR Compliance Mandate:The Medical Device Regulation's CE marking requirements for Class IIa and above devices are accelerating equipment refresh cycles as clinics upgrade to certified systems.
- Implantology Volume Expansion:Rising edentulism rates among Italy's aging population are driving demand for surgical guides and prosthetic components across high-volume practices in Milan and Turin.
- Cone Beam CT Displacement:Three-dimensional imaging systems are replacing panoramic radiography in implant planning workflows, creating upgrade revenue for equipment manufacturers.
Market Restraints
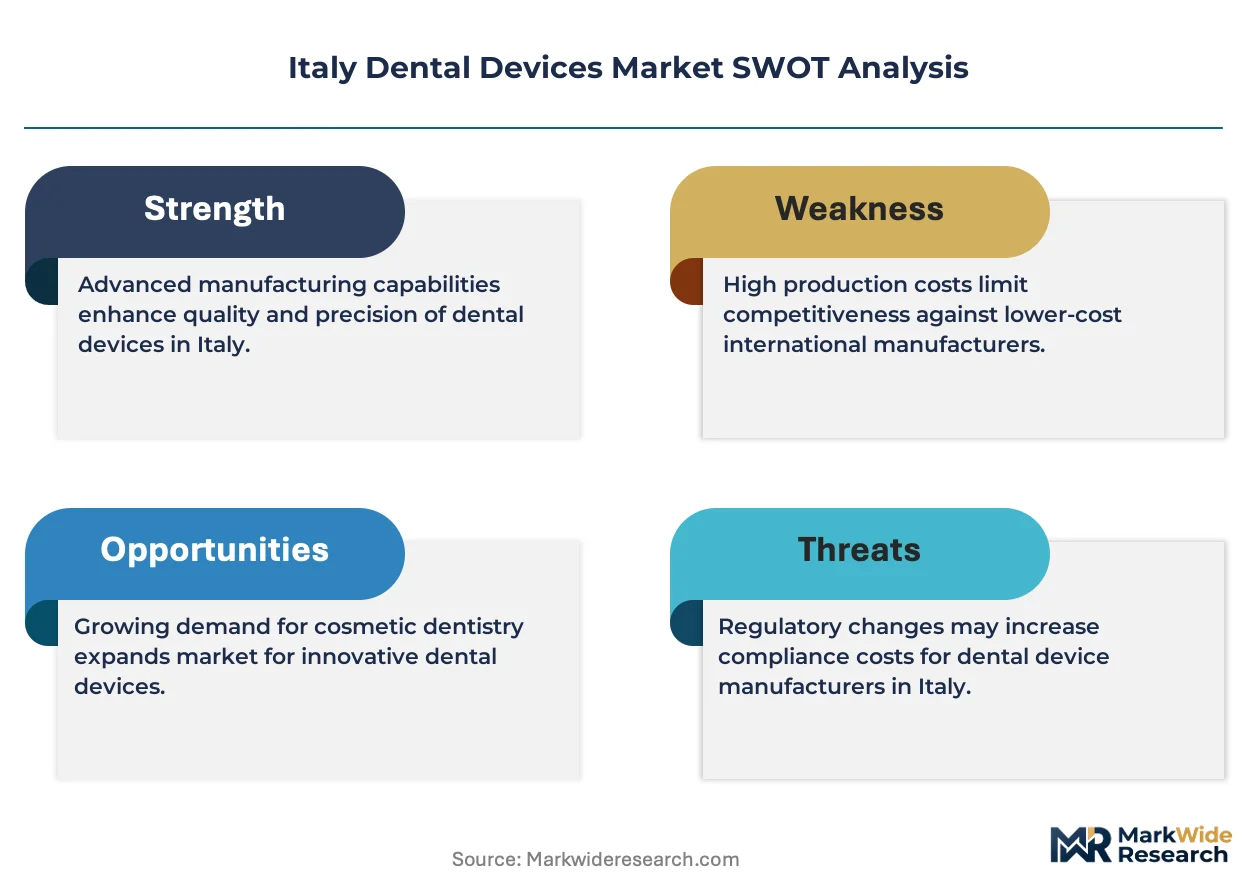
- Titanium Supply Concentration:Italian implant manufacturers depend on a narrow supplier base for medical-grade titanium feedstock, exposing margins to raw material volatility.
- EU MDR Documentation Burden:Extended technical documentation timelines compress market access windows for smaller domestic manufacturers seeking CE certification.
- Glass Ionomer Substitution:Resin composite materials are capturing share in conservative dentistry applications, pressuring traditional restorative material portfolios.
Strategic Opportunities
- Southern Italy Digital Gap:Underpenetrated regions including Sicily and Calabria present whitespace for mobile CAD/CAM service models and equipment leasing structures.
- AI-Enabled Radiology Classification:ANMD guidance on software-as-medical-device frameworks creates regulatory clarity for machine learning diagnostic tools.
- Subscription-Based Consumables:Recurring revenue models for resin blocks and milling burs are displacing transactional procurement in multi-chair practices.
Industry Challenges
- CAD/CAM Technician Scarcity:Digital dentistry workflows require specialized operators for design software and milling calibration, creating bottlenecks in practice expansion.
- Legacy Equipment Integration:New intraoral scanners must interface with existing practice management systems, complicating deployment timelines and training protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Dental Devices Market |
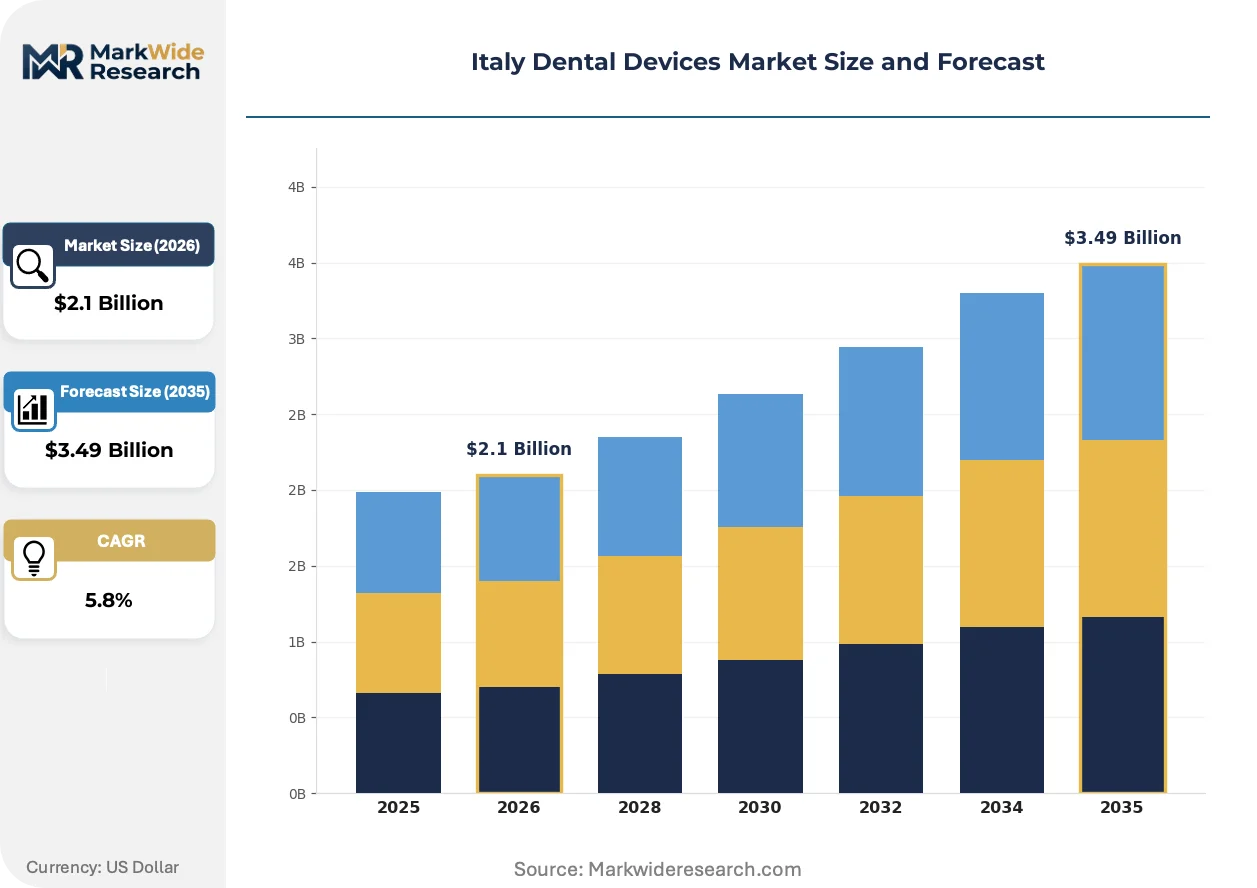
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthodontic Devices, Endodontic Equipment, Restorative Materials, Surgical Instruments Technology: CAD/CAM Systems, Lasers, 3D Printing, Cone Beam CT End User: Dentists, Dental Clinics, Hospitals, Research Institutions Distribution Channel: Online Sales, Distributors, Direct Sales, Retail Outlets |
| Companies Covered | GC Corporation, Straumann Group, Dentsply Sirona, Zimmer Biomet, Planmeca, 3M, Envista Holdings, Leone, Carestream Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Dental Devices Market Shifts & Advancements
Workflow digitization is collapsing traditional boundaries between diagnosis, design, and fabrication in Italian dental practices. Three interconnected developments are compressing treatment timelines and reshaping competitive positioning across the value chain.
Chairside milling systems are decentralizing prosthetic production from centralized dental laboratories to individual clinic operatories. High-volume practices in Bologna and Verona are installing compact five-axis units for same-day crown delivery. This shift is compressing the traditional two-week laboratory turnaround into single-appointment workflows, altering technician employment patterns across Emilia-Romagna.
ANMD's evolving stance on software-as-medical-device classification is creating compliance uncertainty for AI-powered radiology tools. The national regulator's draft guidance on machine learning diagnostic algorithms requires clinical validation datasets that extend development timelines. Domestic software developers are responding by partnering with established device manufacturers to leverage existing quality management systems.
Group purchasing organizations are consolidating procurement authority among independent dental practices in northern Italy. These buying collectives negotiate volume discounts on capital equipment and consumables, displacing traditional distributor relationships. The concentration effect is most pronounced in Lombardy, where multi-practice networks now represent the primary channel for CAD/CAM system vendors.
Italy Dental Devices Market Segmentation
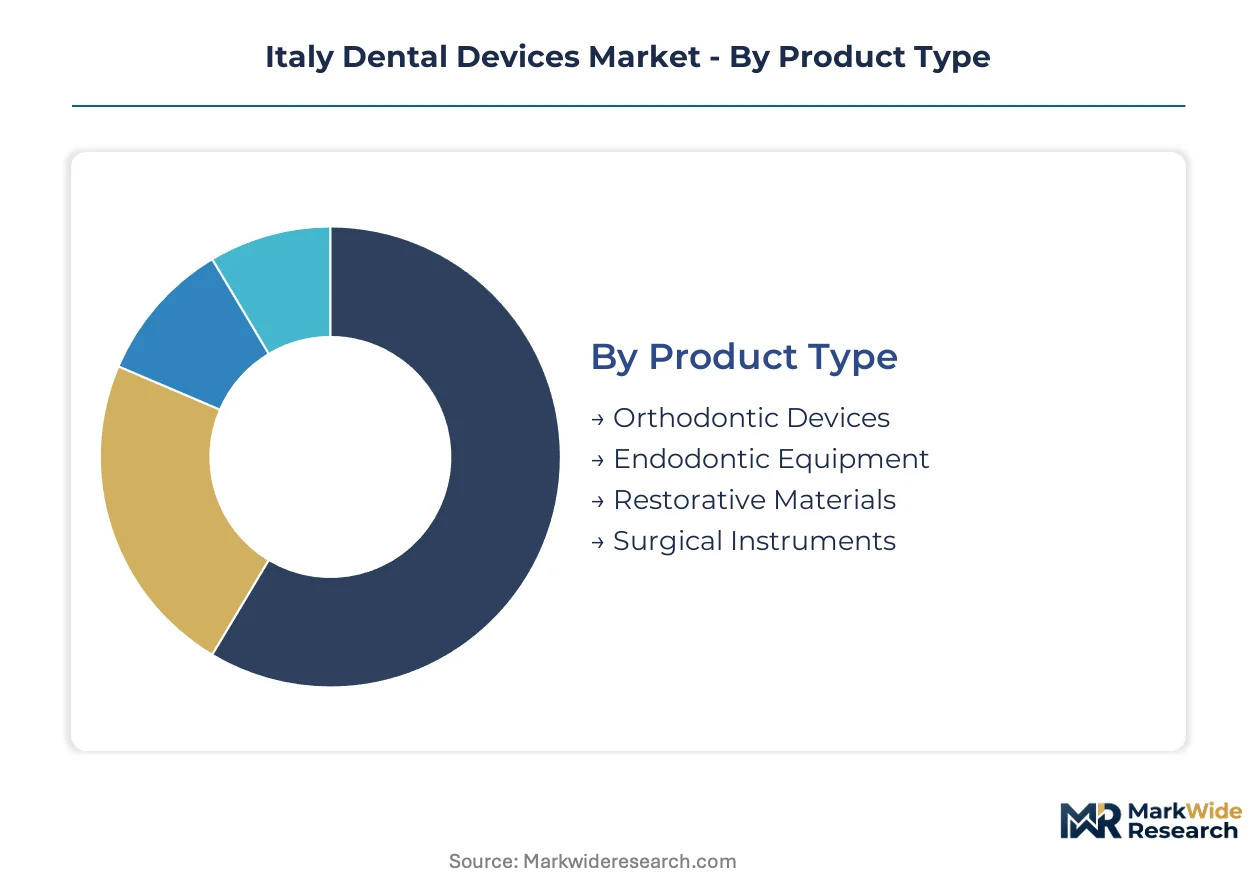
Segmentation reveals how procurement authority fragments across Italy's dental supply chain. Device categories, technology platforms, and channel structures each concentrate value in distinct stakeholder groups, creating multiple entry points for suppliers.
Product Type:
Standalone consumables dominate high-frequency procurement cycles, while capital equipment embeds into integrated treatment workflows.
- Restorative Materials:Resin composites and glass ionomer cements command recurring revenue through replacement-driven consumption. Milanese private clinics in Lombardy account for disproportionate volume as chairside CAD/CAM adoption accelerates ceramic block utilization.
- Orthodontic Devices:Clear aligner systems and fixed appliance brackets address malocclusion correction across pediatric and adult demographics. Demand concentrates in Turin's high-volume orthodontic practices where digital treatment planning reduces chair time per case.
- Endodontic Equipment:Rotary nickel-titanium instruments and electronic apex locators enable root canal therapy with standardized outcomes.
- Surgical Instruments:Implantology kits and periodontal handpieces serve specialized oral surgery procedures.
Restorative materials lead volumes today; orthodontic devices are gaining share fastest.
Technology:
Capital intensity varies dramatically across technology tiers, with subscription-linked platforms commanding premium positioning against depreciating hardware.
- CAD/CAM Systems:Intraoral scanners and chairside milling units compress prosthetic turnaround from weeks to single appointments. Bologna and Verona practices in Emilia-Romagna are deploying compact five-axis mills for same-day crown delivery, restructuring technician employment patterns.
- Cone Beam CT:Three-dimensional imaging systems displace panoramic radiography in implant planning workflows across high-volume northern practices. Veneto clinics are prioritizing these units for surgical guide fabrication, creating upgrade revenue streams.
- 3D Printing:Photopolymer resin printers produce surgical guides and orthodontic models with layer-resolution precision.
- Lasers:Soft-tissue diode and erbium systems enable minimally invasive periodontal and restorative procedures.
CBCT hardware anchors capital expenditure today; CAD/CAM software subscriptions are expanding most quickly.
End User:
Procurement authority concentrates in private practice networks, while institutional buyers emphasize compliance documentation and service bundling.
- Dental Clinics:Multi-chair private practices in Lombardy and Veneto aggregate purchasing power through group buying organizations. These networks negotiate volume discounts on capital equipment, displacing traditional distributor relationships across northern metropolitan clusters.
- Dentists:Solo practitioners and small partnerships retain transactional procurement patterns for consumables and handpiece replacements.
- Hospitals:Academic medical centers and public dental hospitals prioritize EU MDR-compliant systems with extended service contracts.
- Research Institutions:Universities and clinical trial centers source specialized imaging and biomaterial testing equipment.
Dental clinics dominate absolute spend; hospital procurement is climbing the fastest as public sector digitization accelerates.
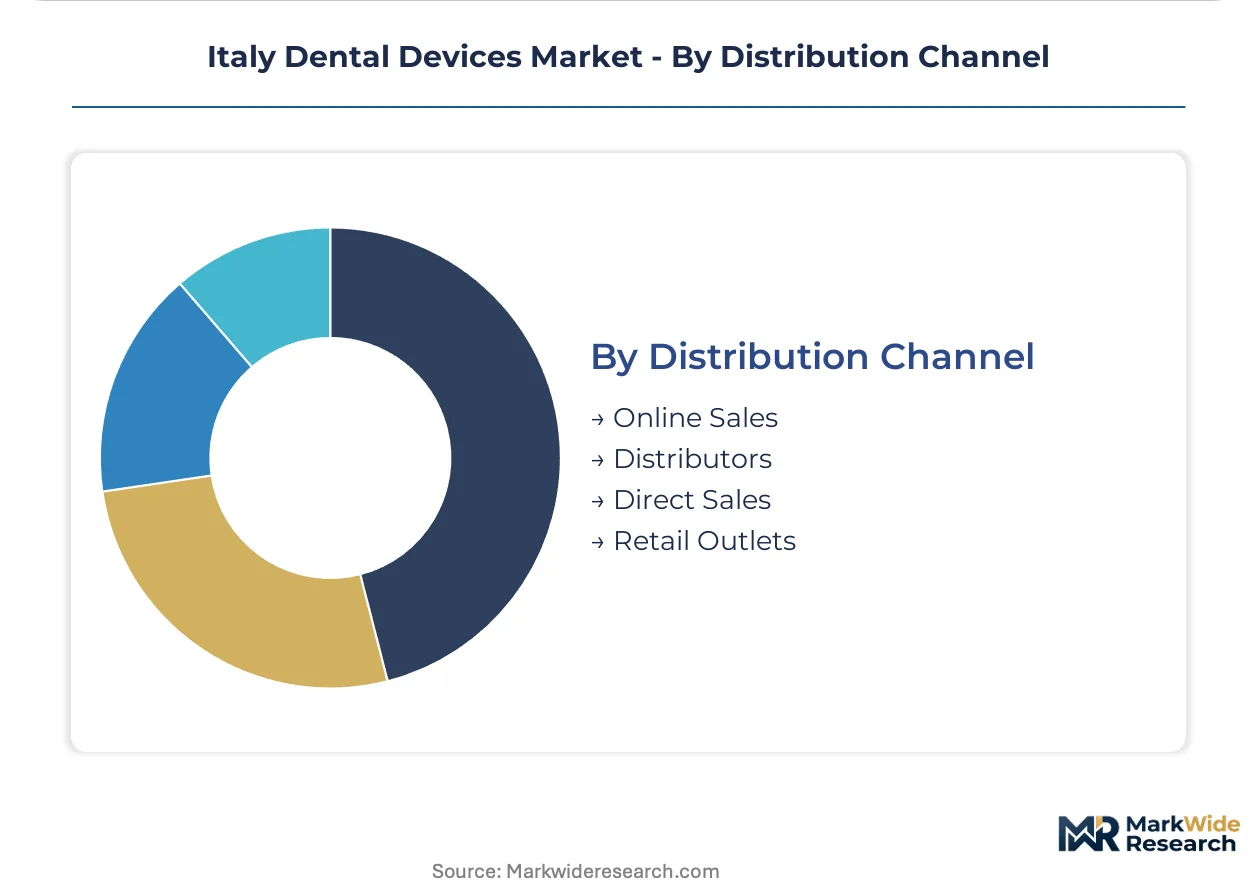
Distribution Channel:
Channel selection tracks practice scale and equipment complexity, with digital platforms capturing consumables while capital sales require physical presence.
- Distributors:Regional dental supply houses maintain inventory proximity and technical support relationships with mid-sized practices. These intermediaries retain relevance for handpiece repair services and emergency consumable replenishment across Sicily and Calabria.
- Direct Sales:Manufacturers deploy specialized representatives for CAD/CAM system installations and training protocols. This channel captures premium pricing through bundled implementation services in high-volume Lombardy clinics.
- Online Sales:E-commerce platforms capture commoditized consumables and small instrument orders from price-sensitive buyers.
- Retail Outlets:Limited presence for over-the-counter dental care products and basic hygiene instruments.
Distributor relationships retain majority volume today; direct manufacturer engagement is expanding most quickly for capital equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate to jurisdictions with streamlined CE marking pathways. Italy's Ministry of Health enforces EU MDR compliance through ANMD, creating cost-of-compliance gaps that favor established players with dedicated regulatory affairs infrastructure.
Lombardy
Private dental clinics in Milan and Brescia are deploying chairside CAD/CAM systems at the fastest rate nationally. ANMD's Milan regional office coordinates post-market surveillance for Class IIa implantology devices. The metropolitan cluster around Milan accounts for the densest concentration of digital workflow adoption, with group purchasing organizations consolidating procurement authority across multi-chair practices.
Veneto
Cone Beam CT installations are displacing panoramic radiography in Verona and Padua implantology practices. The Veneto Region's health authority aligns procurement specifications with EU MDR technical documentation requirements. High-volume surgical guide fabrication in Vicenza is driving demand for three-dimensional imaging systems with integrated treatment planning software.
Piedmont
Turin's orthodontic specialty practices are capturing clear aligner volume from both pediatric and adult demographics. The regional health system mandates CE-marked devices for all public hospital dental departments. The metropolitan area hosts concentrated demand for digital treatment planning platforms that reduce chair time per malocclusion case.
Emilia-Romagna
Chairside milling systems in Bologna and Modena are compressing prosthetic turnaround from weeks to single appointments. The region's medical device industry association provides regulatory guidance on MDR transition timelines. Compact five-axis units in Reggio Emilia are restructuring technician employment patterns as clinics internalize crown production.
Sicily
Underpenetrated markets in Palermo and Catania present whitespace for mobile CAD/CAM service models. The Ministry of Health's southern Italy digital health initiative channels funding toward equipment leasing structures. Distributor relationships retain relevance here for handpiece repair services and emergency consumable replenishment.
Italy Dental Devices Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents expand beyond core implantology into adjacent digital workflow categories. The vendor base organizes around three tiers: multinational conglomerates with integrated CAD/CAM ecosystems, mid-cap specialists in restorative materials, and regional distributors with service bundling capabilities. Two strategic archetypes have emerged: technology-integrators pursuing full-stack chairside solutions, and material-science specialists defending recurring revenue in consumables. M&A activity and strategic partnerships represent the dominant competitive moves, with acquisition targets selected for regulatory clearance portfolios and established ANMD relationships.
Among Swiss-anchored implantology specialists, Straumann Group and Zimmer Biomet occupy positions within the premium-tier technology-integrator archetype. Dentsply Sirona exemplifies the full-stack platform approach through its representation of integrated imaging-to-milling ecosystems. GC Corporation sits within the material-science specialist tier, with its Japanese corporate structure signaling long-horizon R&D commitment to conservative dentistry formulations. These three entities collectively illustrate how geographic origin and corporate heritage map to divergent strategic postures within Italy's EU MDR-regulated environment.
| Leading Market Players |
|---|
| GC Corporation |
| Straumann Group |
| Dentsply Sirona |
| Zimmer Biomet |
| Planmeca |
| 3M |
| Envista Holdings |
| Leone |
| Carestream Health |
| Others |
Supply & Pricing Matrix
Group purchasing organizations in Lombardy and Veneto are consolidating procurement authority across multi-chair private clinics, forcing suppliers to restructure channel economics and compress distributor margins to maintain volume access.
Pricing Analysis
Distributor margins absorb the primary compression as direct manufacturer engagement expands for capital equipment. Three-tier pricing structure across premium, standard, and economy levels tracks CE certification grade and after-sales service bundling. Pricing pressure stems from equipment leasing structures proliferating in underpenetrated southern regions. Solo practitioners exhibit highest price sensitivity, while hospital procurement committees prioritize compliance documentation over unit cost.
Supply Chain Analysis
Medical-grade titanium feedstock draws from Japanese and German specialty metallurgy producers, with Italian implant manufacturers tethered to this narrow supplier base. Ceramic block consumables for chairside milling rest on German and Swiss precision manufacturing. Single-source vulnerability concentrates in nickel-titanium rotary instruments. Distribution runs through regional dental supply houses in southern regions, while direct sales capture northern metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's dental device market represents a late-cycle quality story as private clinics prioritize EU MDR-compliant systems with validated clinical datasets over undifferentiated equipment.
For Market Incumbents: Acquire regulatory clearance portfolios and established ANMD relationships to defend against software-as-medical-device entrants. Deepen backward integration into ceramic block manufacturing to capture consumables margin. Prioritize technician training infrastructure to alleviate CAD/CAM operator scarcity bottlenecks. For New Entrants and Emerging Players: EU MDR in Italy opens a window for AI-powered radiology tools with validated clinical datasets. Target Sicily and Calabria with mobile CAD/CAM service models and equipment leasing structures. Deploy subscription-based consumables procurement to displace transactional relationships in multi-chair practices. For Investors and Strategic Acquirers: Asymmetric upside sits with material-science specialists defending recurring revenue in glass ionomer and composite formulations. Long-term viability favors targets with captive ANMD relationships and CE marking infrastructure. Monitor ANMD guidance finalization on machine learning diagnostic algorithms as inflection indicator for software valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements compress timelines for ANMD clearance. |
| Hospital System Partnership | Public sector digitization in Piedmont and Emilia-Romagna accelerates capital deployment. |
| Software Companion Development | AI-powered radiology tools require ANMD validation datasets for market access. |
| Reimbursement Strategy | National health service procurement specifications favor EU MDR-compliant systems. |
| Backward Integration | Ceramic block manufacturing captures consumables margin in chairside CAD/CAM workflows. |
Research Methodology
Direct dialogue with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers grounded qualitative findings in procurement decision dynamics. Secondary validation drew from ANMD vigilance reports, EU MDR technical documentation filings, hospital procurement databases, and dental supply trade data. Bottom-up and top-down triangulation reconciled equipment shipment volumes with consumables consumption patterns.
Bottom-up modeling aggregated practice-level CAD/CAM adoption rates and CBCT installation data across Lombardy, Veneto, Piedmont, Emilia-Romagna, and Sicily. Segmentation dimensions included product type, technology platform, end-user archetype, and distribution channel. CAGRs derived from equipment replacement cycle analysis and consumables per-procedure intensity metrics across the projection horizon. Forecast inputs incorporated EU MDR transition timelines and regional digital health funding allocations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ANMD guidance delays or titanium feedstock disruption. Projections reflect assumptions on equipment depreciation schedules and consumables replacement frequency. Material deviation in EU MDR enforcement intensity or southern Italy digital health funding warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Dental Endodontics Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Dental Implants and Dental Prosthetics Market
Dental Devices
Chile Dental Devices Market
Dental Devices
Europe Dental Aligners Market
Dental Devices
Dental Hand Tools Market
Dental Devices
Dental Impression System Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Surgical Dental Loupes and Camera Market
Dental Devices
Saudi Arabia Dental Devices Market
Dental Devices
Prophylaxis Pastes Market
Dental Devices
Global Dentures Market
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
Global Dental Microscope Market
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
North America Dental Lab Market