
 Prophy Dental Handpiece Market | 2026-2036
Prophy Dental Handpiece Market Size, Share, and Industry Trends Forecast 2026-2036
Prophy Dental Handpiece Market Analytics
Aftermarket service revenue is fragmenting across OEM networks and third-party repair specialists. Dentsply Sirona leverages its global parts logistics to capture recurring maintenance contracts. KaVo Dental anchors its position through factory-authorized service tiers that lock in clinic loyalty. NSK competes with regional technical training centers that certify independent technicians.
A prophy dental handpiece is a powered rotary or oscillating instrument designed for coronal polishing and preventive cleaning, typically operating at 5,000 to 25,000 RPM with autoclavable stainless steel or titanium alloy housings. The device reduces plaque and extrinsic stains through mechanical abrasion with prophylaxis paste, serving as a standard tool in preventive dentistry workflows. Electric handpieces with brushless motor technology command premium positioning due to torque consistency and reduced heat generation during extended procedures. Air-driven variants retain volume leadership in price-sensitive dental clinics, though battery-powered handpieces are gaining traction in mobile and community health settings where operatory infrastructure is limited.
The FDA regulates prophy handpieces as Class II medical devices under 21 CFR 872.4200, requiring 510(k) premarket notification for substantial equivalence. ISO 14457 specifies dimensional and performance requirements for dental handpieces, while the EU Medical Device Regulation mandates notified body conformity assessment for CE marking access. Dental clinics must weigh total cost of ownership against infection control compliance burdens when selecting between service-integrated and disposable-component platforms.
Market Dynamics
Electric motor architecture is displacing air-turbine dominance as clinics prioritize torque stability and thermal management during extended prophylaxis sessions, compressing replacement cycles and elevating service contract values.
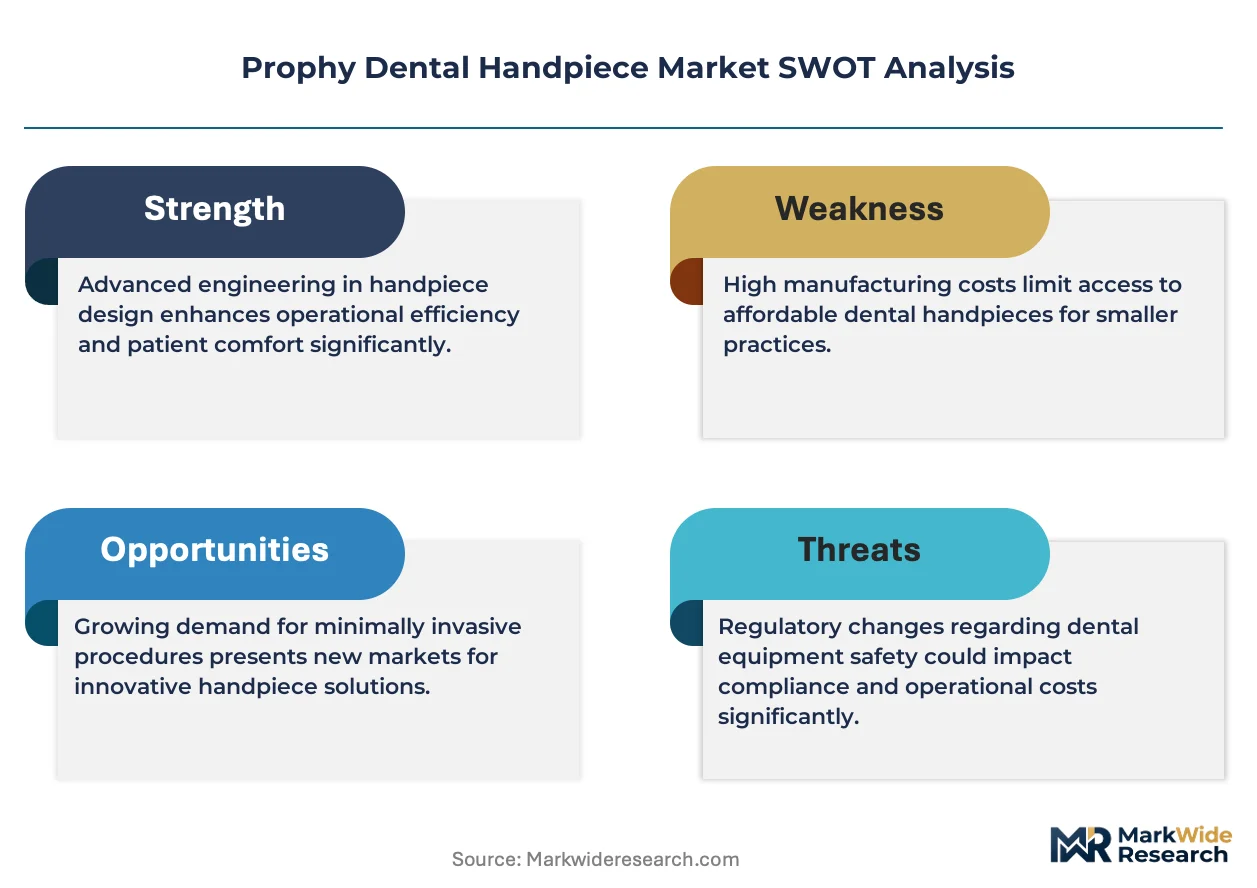
Growth Catalysts
- EU MDR conformity pathways:Stricter CE marking requirements for powered dental instruments are accelerating clinic equipment refresh cycles as legacy devices lose market access.
- Community health deployment:Battery-powered handpieces are penetrating mobile dentistry vans and school-based preventive programs where operatory infrastructure remains limited.
- Infection control protocol upgrades:Autoclavable titanium alloy housings are gaining preference over legacy chrome-plated alternatives as sterilization validation standards tighten across outpatient settings.
Market Restraints
- Brushless motor cost premiums:Rare-earth magnet supply volatility concentrated in Chinese processing facilities is inflating electric handpiece bill-of-materials.
- 510(k) pathway friction:FDA substantial equivalence determinations for novel speed-control algorithms are extending premarket notification timelines.
- Third-party repair ecosystem:Independent service technicians with factory-authorized training remain scarce outside major metropolitan dental clusters.
Strategic Opportunities
- German dental equipment replacement wave:Shortened depreciation schedules and infection control mandates are creating replacement demand concentrated in Bavarian and North Rhine-Westphalian clinic networks.
- Subscription-based maintenance models:Predictive monitoring via embedded torque sensors enables outcome-based service contracts that lock in multi-year clinic relationships.
- Convergence of LED illumination:Integrated fiber-optic systems combined with ultrasonic scaling compatibility are opening premium positioning in periodontal specialty practices.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing for novel polymer grip materials is extending product launch schedules by 8-14 months.
- Legacy air-line infrastructure:Retrofitting older operatories for electric handpiece power and data connectivity requires capital outlays that delay upgrade decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prophy Dental Handpiece Market |
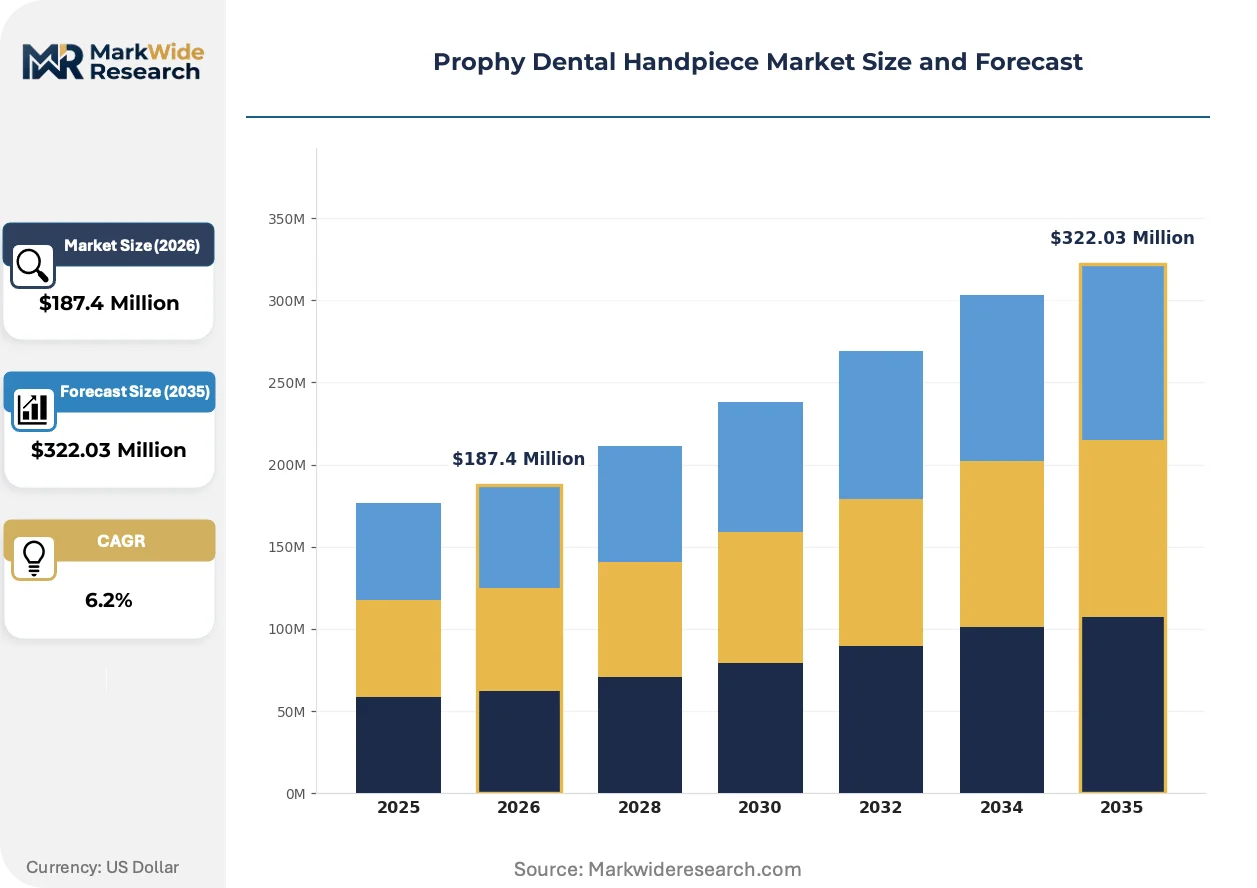
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $322.03 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Handpieces, Air-Driven Handpieces, Ultrasound Handpieces, Battery-Powered Handpieces Technology: Advanced Turbine, Brushless Motor, LED Integration, Oscillating Mechanism End User: Dental Clinics, Hospitals, Dental Schools, Research Institutions Distribution Channel: Online Retail, Direct Sales, Distributors, Medical Supply Stores |
| Companies Covered | Dentsply Sirona, KaVo Dental, NSK, Bien-Air Dental SA, W&H Dentalwerk Bürmoos GmbH, DENTALEZ, Inc., Aseptico Inc., Ultradent Products Inc., MTI Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prophy Dental Handpiece Market Evolving Landscape
Prophy handpiece engineering is pivoting toward smart instrument architectures that embed diagnostic feedback and connectivity, transforming preventive dentistry workflows from mechanical tools to data-generating clinical assets.
Brushless DC motor technology is migrating from premium electric handpieces into mid-tier product lines as magnet cost curves flatten and controller miniaturization advances. General practice clinics in the United States and Germany are adopting these systems at replacement rates exceeding air-turbine alternatives by a factor of two to one. The shift is compressing aftermarket service margins as sealed motor designs reduce field-repairability and shift revenue toward factory-authorized exchange programs.
REACH substance restrictions on chromium(VI) plating are forcing housing material transitions toward medical-grade titanium and PVD-coated stainless steel across European supply chains. Manufacturers with in-house metallurgy capabilities are capturing margin premiums while import-dependent assemblers face compliance delays. German and Swiss dental equipment producers are responding fastest, leveraging existing aerospace supplier relationships for certified material sourcing.
Clinic procurement patterns are fragmenting as dental service organizations consolidate purchasing power while independent practices migrate toward online distributor platforms with transparent price benchmarking. Group practice networks now represent the dominant volume channel in the United States, extracting volume discounts that compress manufacturer list pricing by fifteen to twenty-five percent. Independent clinics in Canada and Australia are countering this concentration through buying cooperatives that aggregate demand across regional networks.
Prophy Dental Handpiece Market Segmentation
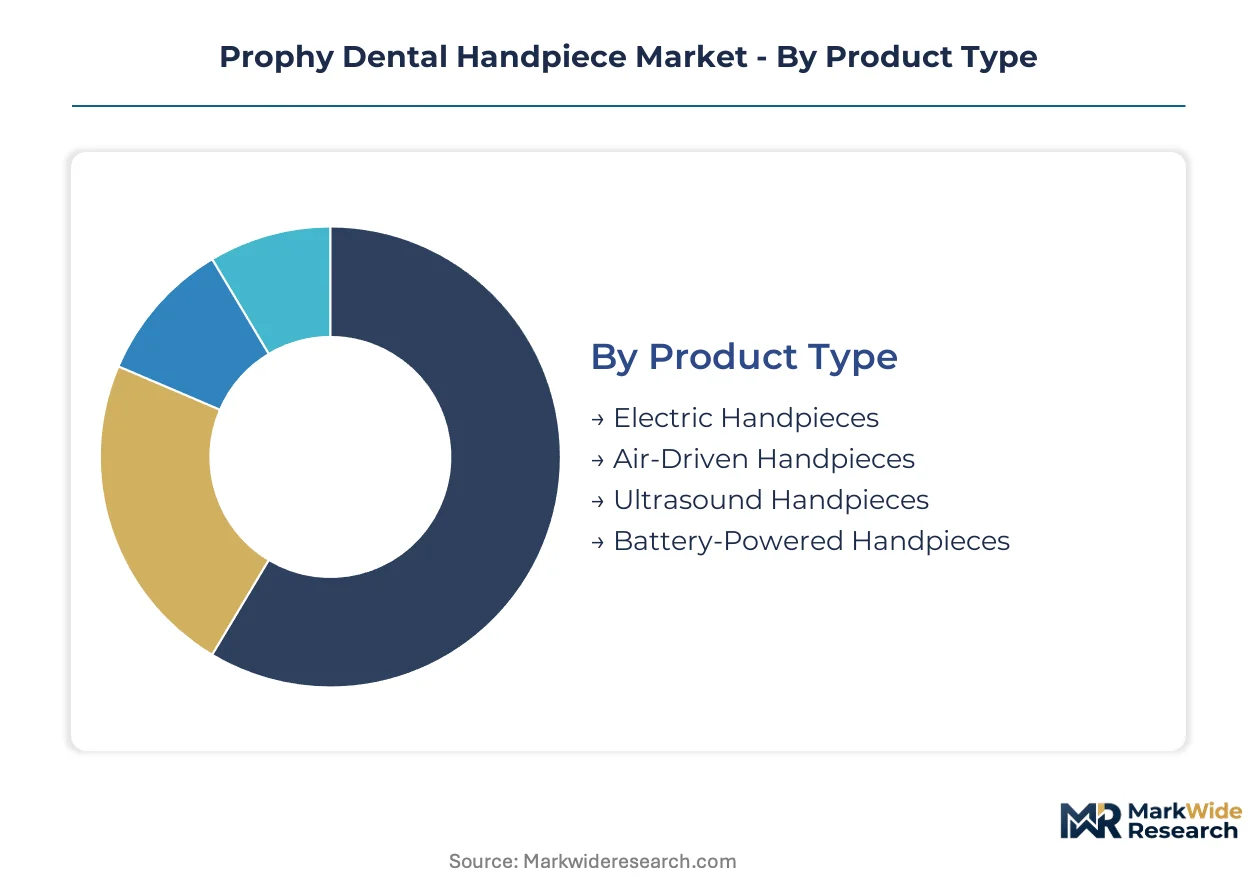
Prophy handpiece segmentation reveals diverging service contract economics across product architectures. Electric systems generate recurring revenue through sealed-motor exchange programs, while air-driven variants sustain third-party repair ecosystems that fragment aftermarket value capture.
Product Type:
After-sales-service intensity varies dramatically by drive mechanism, with sealed electric motors requiring factory-authorized exchange versus field-serviceable air turbines.
- Electric Handpieces:Brushless DC motors with torque sensors deliver consistent RPM under load. Demand concentrates in German and US group practice networks seeking predictive maintenance contracts and thermal stability during extended prophylaxis sessions.
- Air-Driven Handpieces:Traditional turbine designs operate via compressed air lines at 20,000-25,000 RPM. Price-sensitive independent clinics in Canada and Australia retain volume preference due to lower capital outlay and established repair technician networks.
- Ultrasound Handpieces:Piezoelectric oscillation for calculus removal alongside polishing functions.
- Battery-Powered Handpieces:Lithium-ion cordless systems penetrating mobile dentistry vans and school-based preventive programs where operatory infrastructure remains limited.
Air-driven handpieces hold the largest share; momentum sits with battery-powered systems.
Technology:
Cost tier stratification separates premium integrated systems from basic mechanical alternatives, with LED-illuminated brushless motors commanding factory-direct distribution.
- Advanced Turbine:Ceramic bearing assemblies reduce friction heat in high-speed air-driven units. Bavarian and North Rhine-Westphalian clinic networks in Germany are upgrading legacy turbines amid shortened depreciation schedules.
- Brushless Motor:Rare-earth magnet rotors with electronic commutation eliminate carbon brush wear. US dental service organizations specify these for multi-location standardization and reduced downtime costs.
- LED Integration:Fiber-optic illumination combined with ultrasonic scaling compatibility.
- Oscillating Mechanism:Reciprocating motion for periodontal specialty applications.
Brushless motor systems command premium positioning; LED integration is climbing the fastest.
End User:
Application requirements dictate specification divergence, with hospitals prioritizing autoclave cycle durability versus dental schools emphasizing training adaptability.
- Dental Clinics:General practice and specialty operators representing dominant procurement volume. US group practice networks extract fifteen to twenty-five percent manufacturer discounts through consolidated purchasing power.
- Hospitals:Outpatient surgery centers and dental departments requiring ISO 17664-compliant sterilization documentation. German hospital procurement favors titanium alloy housings under REACH substance restrictions.
- Dental Schools:Training institutions with high device turnover and curriculum standardization needs.
- Research Institutions:Academic centers evaluating novel prophylaxis protocols and material biocompatibility.
Dental clinics absorb the majority of volume; battery-powered deployment is expanding most quickly in hospital outreach programs.
Distribution Channel:
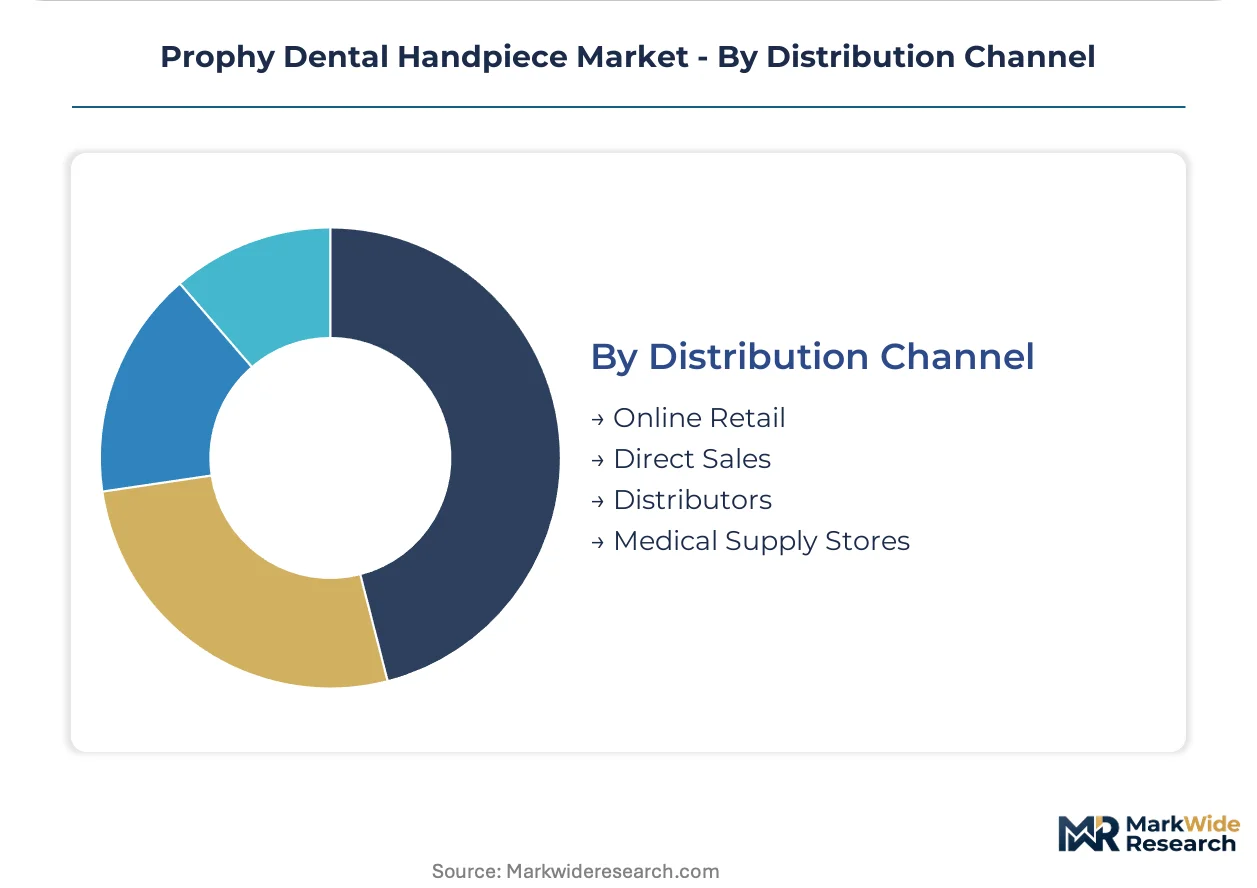
Customer type fragmentation separates institutional procurement through direct sales from independent practice purchasing via transparent online platforms.
- Online Retail:E-commerce platforms with price benchmarking tools serve Canadian and Australian independent clinics. Buying cooperatives aggregate regional demand to counter group practice purchasing power.
- Direct Sales:Manufacturer field representatives secure multi-year service contracts with US dental service organizations. Dentsply Sirona and KaVo Dental leverage global parts logistics for recurring maintenance revenue.
- Distributors:Regional medical device wholesalers with technical training capabilities.
- Medical Supply Stores:Local procurement for emergency replacement and small-practice convenience purchasing.
Direct sales capture premium system placements; online retail is gaining share fastest among independent practitioners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across geographies: German clinics absorb premium electric systems while Canadian independents cling to repairable air-turbine alternatives, creating divergent replacement elasticities that reshape manufacturer pricing power.
United States
Dental service organizations now command fifteen to twenty-five percent manufacturer discounts through consolidated procurement, compressing list pricing across group practice networks. FDA 510(k) premarket notification requirements for novel speed-control algorithms extend regulatory timelines, favoring incumbents with established clearance pathways. The Southeast and Pacific Northwest clinic clusters drive battery-powered adoption for mobile dentistry outreach programs.
Germany
Bavarian and North Rhine-Westphalian dental networks are compressing equipment depreciation schedules amid infection control mandate upgrades, accelerating replacement waves for legacy chrome-plated handpieces. EU MDR conformity assessment requirements for powered dental instruments block legacy device market access, forcing clinic equipment refreshes. Stuttgart and Munich manufacturing corridors supply REACH-compliant titanium alloy housings to domestic producers.
Canada
Independent clinics counter group practice purchasing concentration through regional buying cooperatives that aggregate demand across provincial networks. Health Canada medical device licensing maintains alignment with FDA substantial equivalence frameworks, streamlining parallel market entry for US-cleared products. Toronto and Vancouver metropolitan clusters sustain third-party repair technician networks that extend air-driven handpiece service life.
Australia
TGA conformity assessment for powered dental instruments imposes biocompatibility documentation burdens that delay novel polymer grip material launches by eight to fourteen months. Sydney and Melbourne dental schools drive training-institution procurement volume with high device turnover and curriculum standardization requirements. Independent practitioners migrate toward transparent online distributor platforms with price benchmarking capabilities.
Japan
PMDA premarket certification for brushless motor handpieces emphasizes torque consistency validation under extended procedural loads, elevating technical documentation requirements. METI industrial standards for medical device manufacturing concentrate production in the Chubu and Kansai industrial corridors. Osaka-based dental equipment assemblers leverage precision machining supplier relationships from adjacent electronics manufacturing ecosystems.
Prophy Dental Handpiece Market Competitive Landscape
Full-line dental equipment conglomerates and specialized handpiece engineering houses split the market into divergent service contract economics. Consolidation pressure intensifies as sealed electric motor designs shift aftermarket revenue toward factory-authorized exchange programs and away from field-repairable alternatives. Three archetypes dominate: integrated dental platform providers with global parts logistics, precision turbine specialists with aerospace metallurgy supply relationships, and regional assemblers serving price-sensitive independent clinics. Dominant competitive moves include predictive maintenance subscription models and REACH-compliant material sourcing alliances.
Among German and Swiss precision engineering specialists, W&H Dentalwerk Bürmoos GmbH and Bien-Air Dental SA exemplify the turbine-to-electric transition archetype, anchoring positions through in-house metallurgy capabilities and aerospace supplier relationships. Dentsply Sirona occupies a position representing the integrated platform model, leveraging global service infrastructure to capture recurring maintenance contract value. NSK sits within the precision component specialist tier, competing through regional technical training center networks that certify independent repair technicians outside major metropolitan clusters.
| Leading Market Players |
|---|
| Dentsply Sirona |
| KaVo Dental |
| NSK |
| Bien-Air Dental SA |
| W&H Dentalwerk Bürmoos GmbH |
| DENTALEZ, Inc. |
| Aseptico Inc. |
| Ultradent Products Inc. |
| MTI Dental |
| Others |
Value Network & Pricing Analysis
Rare-earth magnet processing concentration in Chinese facilities anchors cost structures for brushless motor handpieces, funneling margin pools toward OEMs with sealed-motor exchange programs that capture recurring service revenue over multi-year clinic relationships.
Pricing Analysis
After-sales service contracts drive lifetime value capture, with factory-authorized exchange programs commanding premium positioning over field-repairable alternatives. Three-tier pricing structure across premium brushless systems, standard air-turbine units, and economy battery-powered variants reflects certification grade and torque consistency validation. Cost compression in mid-tier electric segments is intensifying because magnet supply volatility feeds into bill-of-materials inflation. Independent clinics in Canada and Australia exhibit highest price sensitivity, while German group practice networks absorb premium positioning for predictive maintenance bundling.
Supply Chain Analysis
Supplier-financing facilities extended by German and Swiss precision equipment producers are tightening working capital requirements for import-dependent assemblers. Manufacturing concentrates in Germany, Switzerland, and Japan, with rare-earth magnet sourcing drawing from Chinese processing facilities and titanium alloy supply resting on aerospace supplier relationships in Stuttgart and Munich corridors. Single-source vulnerability in magnet procurement creates exposure to export restriction shocks. Distribution runs through manufacturer field representatives for institutional accounts and online platforms for independent practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prophy handpiece demand sits in early-cycle expansion as battery-powered architectures penetrate mobile dentistry infrastructure previously unreachable by traditional operatory-dependent systems.
For Market Incumbents: Entrench factory-authorized service tiers through predictive monitoring subscriptions that lock clinic loyalty before third-party repair networks mature. Deepen backward integration into titanium alloy metallurgy to capture REACH compliance premiums. Counter emerging battery-powered specialists by embedding torque sensors and connectivity modules that shift replacement revenue toward sealed-motor exchange programs. For New Entrants and Emerging Players: Build out technical training center networks in Canadian and Australian metropolitan clusters where independent repair technician scarcity sustains air-driven handpiece service life. Target hospital outreach programs in the US Southeast and Pacific Northwest where mobile dentistry deployment creates specification white space. Penetrate through buying cooperatives that aggregate independent clinic demand outside group practice purchasing concentration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dental equipment distributors consolidating regional service capabilities ahead of electric motor transition waves. Five-to-ten year viability hinges on recurring revenue intensity from sealed-system architectures displacing field-repairable alternatives. Watch FDA 510(k) clearance velocity for novel speed-control algorithms as inflection indicator for incumbent regulatory moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription | Torque sensor data enables outcome-based contracts that cement multi-year clinic relationships. |
| REACH-Compliant Material Sourcing | In-house titanium alloy capabilities capture margin premiums as chrome-plating restrictions tighten. |
| Battery-Powered Product Line Extension | Lithium-ion cordless systems unlock mobile dentistry vans and school-based preventive programs. |
| Regional Technical Training Network | Certified technician programs defend air-driven installed base against sealed-motor displacement. |
| LED-Ultrasonic Integration | Fiber-optic illumination combined with scaling compatibility opens periodontal specialty positioning. |
Research Methodology
A spread of perspectives from dental equipment procurement managers, biomedical engineers at hospital outpatient centers, GPO contracts administrators, and aftermarket service technicians converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, ISO 14457 technical documentation, EU MDR notified body assessments, and hospital procurement database extracts. Bottom-up demand modeling across clinic types triangulated against top-down manufacturer shipment estimates.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include drive mechanism architecture, motor technology tier, end-user facility type, and distribution channel structure. CAGRs derived from fitted growth curves applied to replacement cycle data and infection control mandate implementation timelines. Forecast inputs incorporated equipment depreciation schedule shifts and biocompatibility certification timeline extensions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-powered specialists or rare-earth magnet supply consolidators would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
GCC Dental Implants Market
Dental Devices
Mexico Dental Devices Market
Dental Devices
Italy Dental Devices Market
Dental Devices
Lights for Dental Healthcare Market
Dental Devices
Dental Scalers Market
Dental Devices
Prophylaxis Pastes Market
Dental Devices
Europe Dental Implants Market
Dental Devices
3D Printing Dental Device Market
Dental Devices
Global Dental Restorative Market
Dental Devices
US Orthodontics Market
Dental Devices
Dental Units Market
Dental Devices
Dental Caries and Endodontic Market
Dental Devices
Americas Acrylic Teeth Market
Dental Devices
Asia-Pacific Dental Lab Market
Dental Devices
Europe Dental Lab Market
Dental Devices
Dental Implants and Abutment Systems Market