
 Trial Prostheses Market | 2026-2036
Trial Prostheses Market Size, Share, and Industry Trends Forecast 2026-2036
Trial Prostheses Market Analytics
The EU Medical Device Regulation is repositioning competitive priorities across European prosthetic suppliers. Ossur leverages its Icelandic manufacturing base to sustain CE-marked product flows into continental rehabilitation networks. Zimmer Biomet anchors its position through orthopedic device portfolios that span pre-surgical planning through post-amputation fitting workflows. Smith & Nephew competes on wound-care-to-prosthetics continuity, offering clinicians integrated limb preservation and replacement pathways.
Trial prostheses are temporary wearable devices fabricated from silicone, thermoplastic, or carbon fiber composites that enable clinicians to evaluate fit, function, and patient adaptation before permanent prosthesis fabrication. These devices incorporate mechanical, hydraulic, or electronic articulation systems to simulate real-world load conditions and gait dynamics during the rehabilitation assessment phase. Lower limb trial sockets dominate volume due to higher amputation incidence and standardized fitting protocols, while electronic and bionic technology segments command premium positioning as microprocessor-controlled knee and ankle systems penetrate rehabilitation center procurement lists. Carbon fiber laminates are displacing thermoplastics in high-activity patient evaluations where durability under cyclic loading determines trial success rates.
FDA 510(k) clearance pathways govern US market entry for trial prosthetic components, while the EU MDR requires notified body intervention for all custom-fabricated temporary devices. ISO 10328 structural testing standards define static and cyclic load validation protocols that manufacturers must document for regulatory submission packages. Stakeholders should monitor how FDA breakthrough device designations for adaptive socket technologies reshape reimbursement coding and rehabilitation center capital allocation priorities.
Market Dynamics
Carbon fiber laminates are displacing thermoplastics in high-activity patient evaluations, compressing socket replacement cycles while elevating performance benchmarks that rehabilitation centers now demand from temporary fitting protocols.
Growth Catalysts
- EU Medical Device Regulation:MDR certification requirements are filtering out marginal suppliers, concentrating procurement authority within notified-body-approved manufacturers that hospital networks trust for compliance continuity.
- Microprocessor-controlled knee systems:Electronic articulation technology is penetrating rehabilitation center capital budgets as clinicians prioritize gait-matched resistance data over mechanical trial sockets.
- Germany's orthopedic cluster:Prosthetic fitting centers in Bavaria and North Rhine-Westphalia coordinate socket fabrication workflows directly with university hospital amputation wards, compressing trial-to-permanent fitting timelines.
Market Restraints
- Carbon fiber supply concentration:Toray Industries and Hexcel dominate aerospace-grade prepreg supply chains, exposing prosthetic laminators to input cost volatility when defense contractors absorb capacity.
- Notified body bottlenecks:EU MDR's expanded clinical evidence requirements have thinned the field of certifying organizations, extending CE-marking timelines for custom-fabricated trial devices by 8-14 months.
- 3D-printed socket substitutes:Direct-printed permanent prostheses from HP Multi Jet Fusion systems are collapsing the traditional trial-permanent fabrication sequence in select orthopedic networks.
Strategic Opportunities
- India's rehabilitation infrastructure:The PLI scheme for medical devices is attracting socket laminators to establish Bengaluru and Hyderabad production nodes serving South Asian amputation centers.
- Telehealth-integrated fitting:Remote socket adjustment protocols using pressure-mapping insoles and video gait analysis are opening rural patient access channels previously unreachable by metropolitan prosthetists.
- ISO 10328 alignment:Structural testing standardization is creating export pathway advantages for manufacturers that pre-validate cyclic load documentation, accelerating FDA 510(k) submissions.
Industry Challenges
- Certified prosthetist scarcity:The American Board for Certification in Orthotics, Prosthetics and Pedorthics reports examination backlogs extending credentialing timelines, constraining clinic expansion capacity.
- Legacy electronic system integration:Microprocessor knee units from established suppliers utilize proprietary software architectures that resist interoperability with third-party trial socket pressure sensors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trial Prostheses Market |
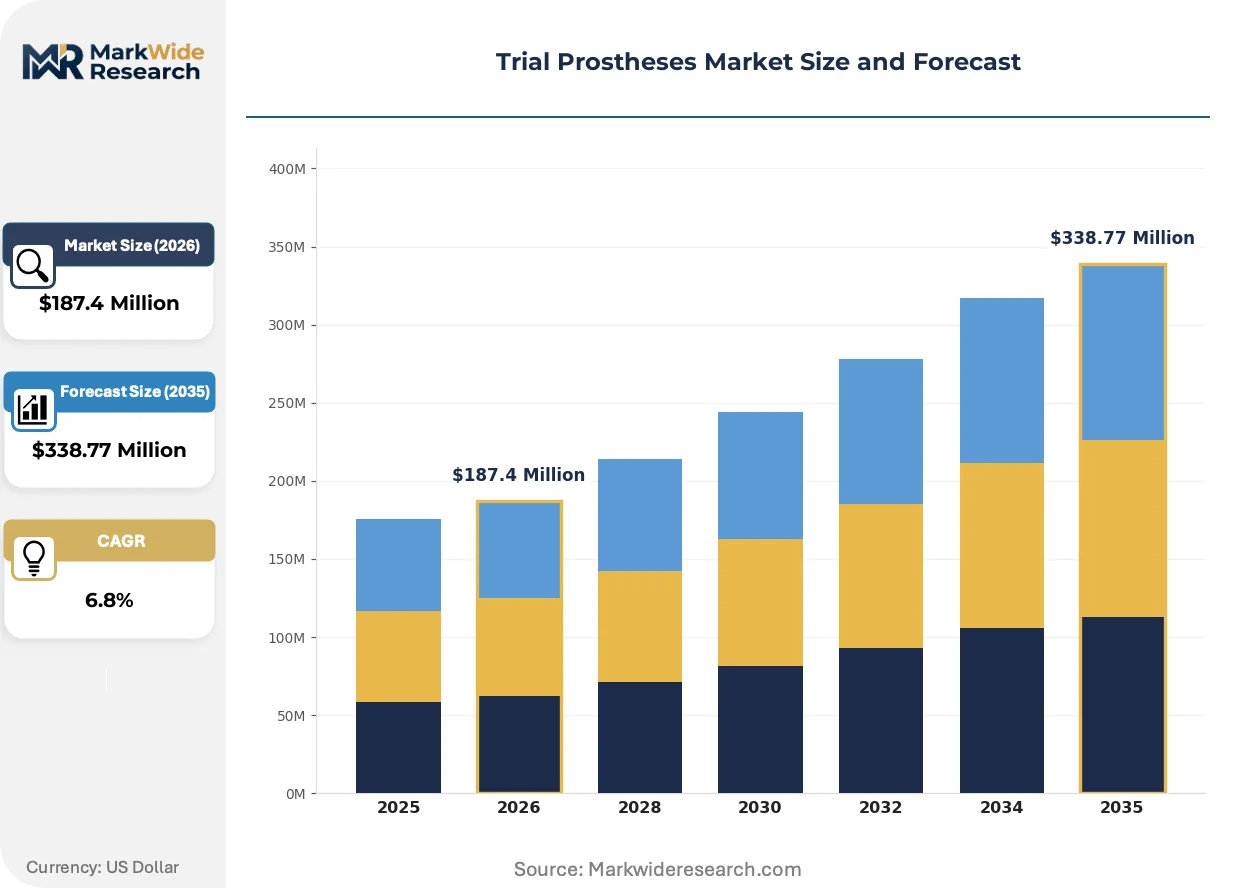
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upper Limb, Lower Limb, Cosmetic, Functional Material: Silicone, Thermoplastic, Carbon Fiber, Metal Technology: Mechanical, Hydraulic, Electronic, Bionics End User: Hospitals, Rehabilitation Centers, Home Care, Clinics |
| Companies Covered | Ossur, Smith & Nephew, Zimmer Biomet, Johnson & Johnson, B. Braun Melsungen, Hanger, The Ohio Willow Wood, Fillauer, Otto Bock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trial Prostheses Market Evolving Landscape
Digital fabrication workflows and sensor-embedded evaluation protocols are compressing the traditional trial fitting timeline while generating patient-specific datasets that permanent prosthesis manufacturers now require upstream.
Additive manufacturing is expanding into socket production as selective laser sintering of nylon-12 powders enables same-day turnaround for anatomically contoured trial interfaces. Rehabilitation centers in the Netherlands and Denmark are deploying in-house printing cells that bypass centralized fabrication labs. This distributed production model is compressing fitting appointment schedules from weeks to 48-hour cycles.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic clinical follow-up data collection for all custom-fabricated temporary devices. Manufacturers must now maintain vigilance systems tracking adverse events across the trial-to-permanent transition. German orthopedic networks are responding by integrating electronic health record APIs that auto-populate regulatory submission templates.
Hospital procurement departments are consolidating vendor lists around suppliers offering integrated limb preservation-to-replacement pathways. Integrated service contracts bundling wound care, trial fitting, and permanent prosthesis provision are displacing discrete component purchasing at major academic medical centers. This consolidation pattern is most visible in the US Veterans Health Administration's regional prosthetic procurement frameworks.
Trial Prostheses Market Segmentation
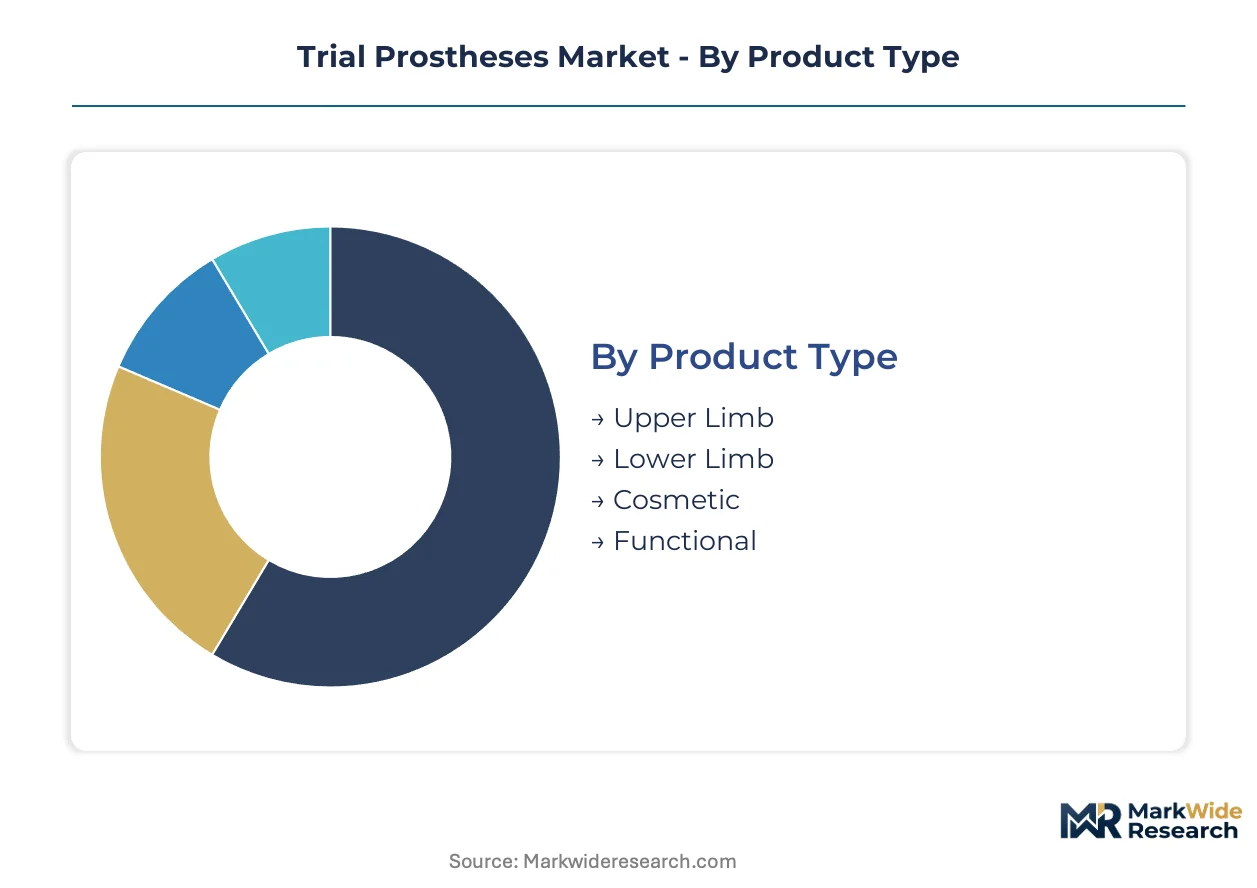
Trial prostheses segmentation reflects divergent clinical workflows across acute hospital settings and long-term rehabilitation pathways. Material selection and articulation technology determine whether devices serve brief pre-operative assessments or extended gait-training protocols.
Product Type:
Customization intensity varies sharply across limb categories, with lower extremity fittings demanding precise biomechanical matching while cosmetic trials prioritize rapid fabrication turnaround.
- Lower Limb:Transfemoral and transtibial trial sockets incorporate load-bearing pylons and dynamic response feet for gait laboratory validation. Germany's university hospital networks concentrate procurement of these systems where compressed trial-to-permanent timelines reduce patient bed days.
- Upper Limb:Terminal device prototypes range from body-powered hook mechanisms to myoelectric hand simulators. Rehabilitation centers in Bavaria coordinate closely with trauma surgery departments to evaluate prehensile function before definitive prosthesis commitment.
- Cosmetic:Silicone glove trials focus on skin tone matching and passive positioning aesthetics for bilateral amputees prioritizing social reintegration over functional restoration.
- Functional:Activity-specific trials for vocational or athletic use cases employ modular componentry that prosthetists reconfigure across multiple assessment sessions.
Most installed capacity flows through Lower Limb. Expansion is steepest in Functional.
Material:
Cost tiers stratify around durability requirements, with carbon fiber commanding premium positioning for high-activity evaluations while thermoplastics retain volume share in pediatric growth-adjustment protocols.
- Carbon Fiber:Aerospace-grade prepreg laminates deliver cyclic fatigue resistance exceeding 3 million loading cycles. Toray Industries and Hexcel supply chains serve German orthopedic clusters where durability benchmarks determine trial success rates.
- Thermoplastic:Polypropylene and copolymer socket materials enable heat-adjustable modifications during multi-week fitting sequences. These materials dominate pediatric applications where limb volume fluctuation necessitates frequent socket replacement.
- Silicone:Shore hardness-graded elastomers provide interface cushioning and suspension for sensitive residual limbs with compromised skin integrity.
- Metal:Aluminum and titanium alloy pylons supply structural rigidity for above-knee trial assemblies where patient mass exceeds standard composite load ratings.
Carbon Fiber captures the highest margin tier. Thermoplastic maintains the broadest addressable patient base.
Technology:
Volume concentration sits with mechanical systems, though electronic articulation is penetrating capital budgets as microprocessor data becomes integral to clinical decision-making.
- Mechanical:Friction-based knee joints and solid-ankle-cushion-heel feet deliver predictable kinematics for initial ambulation training. These systems retain dominance in price-sensitive procurement environments and emerging market rehabilitation infrastructure.
- Electronic:Microprocessor-controlled knee units from established suppliers generate real-time gait-phase data that clinicians export to permanent prosthesis specification sheets. FDA 510(k) clearance pathways govern US deployment of these systems.
- Hydraulic:Pneumatic resistance mechanisms simulate variable terrain response for transfemoral amputees anticipating active lifestyle restoration.
- Bionics:Pattern recognition and targeted muscle reinnervation interfaces represent frontier technology segments with limited current trial deployment but substantial research hospital interest.
Mechanical systems account for the largest installed base. Electronic technology is gaining share fastest in academic medical center procurement.
End User:
Customer type determines service intensity, with hospitals prioritizing rapid throughput while rehabilitation centers emphasize extended adaptation protocols.
- Rehabilitation Centers:Dedicated prosthetic facilities maintain in-house fabrication labs and certified prosthetist staffing for multi-week trial sequences. The US Veterans Health Administration operates the largest consolidated network of these centers.
- Hospitals:Acute care amputation wards require rapid-turnaround trial sockets for immediate post-operative limb shaping and early mobilization. EU MDR compliance documentation now accompanies every custom-fabricated device leaving hospital workshops.
- Clinics:Private prosthetic practices serve community-based patients with discrete component sourcing rather than integrated fabrication capabilities.
- Home Care:Emerging telehealth-integrated models enable remote socket adjustment with mailed trial components and video-guided fitting protocols.
Rehabilitation Centers process the highest trial volume per facility. Home Care represents the most nascent service configuration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German orthopedic pioneers established modern prosthetic fitting protocols in the post-war period, scaling university-hospital coordination models that now dominate European rehabilitation networks. These institutional frameworks have diffused selectively across North America and Asia-Pacific, creating geographically concentrated centers of excellence.
United States
The Veterans Health Administration operates the largest consolidated rehabilitation network, with regional prosthetic procurement frameworks bundling wound care through permanent fitting services. FDA 510(k) clearance pathways govern market entry for electronic articulation systems. Major academic medical centers in Boston and Baltimore coordinate trauma surgery wards with dedicated prosthetic facilities.
Germany
Bavaria and North Rhine-Westphalia host Europe's densest prosthetic fitting center clusters, where university hospital amputation wards coordinate socket fabrication workflows directly with rehabilitation facilities. EU MDR notified body requirements filter supplier lists to CE-marked manufacturers with documented ISO 10328 structural testing. The orthopedic cluster around Berlin-Brandenburg concentrates carbon fiber laminate supply for high-activity patient evaluations.
India
The PLI scheme for medical devices attracts socket laminators to establish Bengaluru and Hyderabad production nodes serving South Asian amputation centers. CDSCO medical device regulations govern import and domestic manufacturing compliance for trial prosthetic components. Rehabilitation infrastructure expansion concentrates in Maharashtra and Tamil Nadu, where metropolitan hospitals develop prosthetic fitting capabilities.
Japan
PMDA regulatory frameworks require clinical evidence documentation for microprocessor-controlled knee systems entering rehabilitation center procurement. METI industrial policy supports advanced materials research for carbon fiber composite applications in prosthetic devices. The Kansai region around Osaka maintains specialized prosthetic fabrication workshops serving aging-related amputation demand.
Netherlands
In-house additive manufacturing cells at rehabilitation centers in Randstad bypass centralized fabrication labs, compressing fitting schedules to 48-hour cycles. EU MDR post-market surveillance mandates systematic clinical follow-up data collection for custom-fabricated temporary devices. Eindhoven Region technical universities collaborate with prosthetic centers on sensor-embedded evaluation protocols.
Trial Prostheses Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the trial prostheses market. Vertically integrated manufacturers maintaining in-house carbon fiber lamination and electronic articulation assembly face competition from specialized socket fabricators sourcing modular components. The competitive structure stratifies into three archetypes: diversified orthopedic conglomerates spanning pre-surgical planning through post-amputation workflows; dedicated prosthetic specialists concentrating on rehabilitation center relationships; and materials-science entrants from aerospace composite supply chains. Dominant competitive moves include M&A to acquire notified body certification capabilities and strategic partnerships with university hospital networks to secure trial-to-permanent fitting referral pathways.
Among Iceland-based manufacturers, Ossur occupies a position representing Nordic regulatory optimization strategies for continental European market access. Zimmer Biomet exemplifies the diversified orthopedic conglomerate archetype, spanning device portfolios that integrate pre-surgical planning through post-amputation fitting workflows. Smith & Nephew anchors the wound-care-to-prosthetics continuity segment, offering clinicians integrated limb preservation and replacement pathways that hospital procurement departments increasingly favor.
| Leading Market Players |
|---|
| Ossur |
| Smith & Nephew |
| Zimmer Biomet |
| Johnson & Johnson |
| B. Braun Melsungen |
| Hanger |
| The Ohio Willow Wood |
| Fillauer |
| Otto Bock |
| Others |
Value Network & Pricing Analysis
Backward integration into carbon fiber lamination and electronic articulation assembly anchors both supply security and margin protection for trial prostheses manufacturers serving notified-body-certified procurement channels. This captive production model insulates German orthopedic clusters from aerospace-grade prepreg allocation shocks while supporting premium positioning against modular component assemblers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates microprocessor-controlled electronic systems from mechanical friction joints and basic thermoplastic sockets. Price differentiation rests on ISO 10328 structural testing documentation and EU MDR certification tier, with rehabilitation centers absorbing premium markups for gait-phase data capabilities. Cost compression in mechanical socket tiers is intensifying as Indian PLI-supported laminators enter South Asian procurement channels. Pediatric rehabilitation networks exhibit highest price sensitivity due to frequent replacement cycles, while German university hospital clusters prioritize performance benchmarks over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from notified bodies and hospital procurement departments mandate multi-supplier qualification for carbon fiber prepreg, microprocessor knee units, and silicone interface materials. Geographic supply concentration centers on Japan for aerospace-grade Toray Industries laminates, Germany for orthopedic cluster fabrication workflows, and India for emerging PLI-incentivized production nodes. Raw material dependencies include aerospace carbon fiber prepreg, nylon-12 powders for selective laser sintering, and proprietary microprocessor architectures. Single-source vulnerability persists in electronic knee system software where proprietary architectures resist interoperability. Distribution runs through rehabilitation center in-house fabrication labs, hospital-based workshops, and emerging telehealth-integrated direct-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trial prostheses function as a stable compounder anchored by irreversible demographic shifts toward aging-related amputation demand and permanent disability from trauma and vascular disease.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Acquire notified body technical documentation capabilities to compress CE-marking timelines for custom-fabricated devices. Establish captive carbon fiber lamination capacity in Germany's orthopedic cluster to defend input cost position against aerospace contractor absorption. Counter 3D-printed socket substitutes by integrating digital fabrication workflows into existing rehabilitation center partnerships. For New Entrants and Emerging Players: The mid-tier price gap between Ossur's premium electronic systems and Indian mechanical socket producers creates entry space for standardized microprocessor knee units at rehabilitation center price points. Target India's Maharashtra and Tamil Nadu metropolitan hospital networks where prosthetic fitting capabilities are expanding fastest under CDSCO compliance frameworks. Pursue telehealth-integrated fitting protocols as the go-to-market angle, leveraging remote socket adjustment to bypass certified prosthetist scarcity constraints. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR notified body bottlenecks strand marginal suppliers without certification continuity. The long-term viability window favors manufacturers with documented ISO 10328 cyclic load validation and established university hospital referral pathways. Acquisition target archetype: specialized socket fabricators with backward integration into carbon fiber lamination and existing CE-marked product flows. Monitor FDA breakthrough device designations for adaptive socket technologies as the inflection signal indicating reimbursement coding shifts that would accelerate capital allocation to electronic articulation systems.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body approval compresses competitive field to documented manufacturers with ISO 10328 validation. |
| Hospital System Partnership | German university hospital networks coordinate socket fabrication workflows directly with rehabilitation facilities. |
| Backward Integration | Captive carbon fiber lamination insulates margin position from Toray Industries and Hexcel allocation volatility. |
| Software Companion Development | Electronic health record APIs auto-populate regulatory submission templates for post-market surveillance compliance. |
| Reimbursement Strategy | FDA breakthrough device designations for adaptive sockets reshape rehabilitation center capital allocation priorities. |
Research Methodology
Coverage spans Germany, the United States, India, Japan, and the Netherlands, with primary inputs from each market's regulatory and procurement environments. Primary interviews incorporated prosthetists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare prosthetic claims data, and hospital procurement databases. Bottom-up facility-level capacity estimates triangulated against top-down market size calculations.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by product type, material grade, articulation technology, and end-user configuration. Modeled dimensions included lower versus upper limb categories, carbon fiber versus thermoplastic versus silicone material tiers, mechanical versus electronic versus hydraulic technology segments, and rehabilitation center versus hospital versus clinic versus home care delivery channels. CAGRs derived from fitted trend extrapolation adjusted for regulatory transition impacts and technology substitution elasticities. Industry-specific forecast inputs incorporated certified prosthetist supply constraints and carbon fiber prepreg allocation patterns from aerospace demand cycles.
Caveats apply where notified body capacity constraints, 3D-printed permanent prosthesis substitution rates, or telehealth reimbursement policy shifts could materially shift the outlook. Deviation in EU MDR post-market surveillance enforcement intensity or FDA breakthrough device designation pacing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hemoconcentrators Market
Medical Devices
Neurotech Devices Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Laryngeal Airway Mask Market
Medical Devices
Global Photomedicine Market
Medical Devices
Quadripodal Implants Market
Medical Devices
Stool Management Systems Market
Medical Devices
Intraoperative Sensor Market
Medical Devices
Asia-Pacific Bathroom and Toilet Assist Devices Market
Medical Devices
Laser BPH Devices Market
Medical Devices
Anesthesia Vaporizers Market
Medical Devices
Electromagnetic Navigation Bronchoscopy Market
Medical Devices
Helium Free MRI Scanners Market
Medical Devices
Sputum Ejection Machine Market
Medical Devices
Walkers and Rollators Market
Medical Devices
Pen Needles Market