
 Dental Radiometer Market | 2026-2036
Dental Radiometer Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Radiometer Market Outlook
Dental clinics is realigning procurement priorities toward digital radiometry platforms that integrate with practice management software. Dentsply Sirona leverages its installed base of imaging systems to cross-sell calibration accessories. Planmeca Oy anchors its competitive stance through vertical control over sensor manufacturing in the Nordic region. Envista Holdings Corporation differentiates via dedicated training infrastructure for clinic staff on radiometer operation protocols.
A dental radiometer measures optical output intensity from curing lights used in restorative dentistry, typically calibrated in milliwatts per square centimeter across wavelengths between 400 and 500 nanometers to verify adequate polymerization energy delivery. Portable devices dominate unit volumes due to chairside workflow integration, while digital sensors capture expanding margin pools as clinics replace analog verification methods. CMOS technology leads sensor architecture for intraoral applications, whereas spectroscopy segments serve laboratory quality control workflows requiring wavelength-specific measurement precision.
The FDA regulates dental radiometers as Class II medical devices under 510(k) premarket notification requirements, while the EU Medical Device Regulation mandates CE marking with notified body involvement for active therapeutic devices. ISO 10650 standards govern curing light performance testing, indirectly creating compliance demand for calibrated radiometry equipment. Stakeholders must monitor evolving harmonized standards for LED curing light validation as regulatory bodies tighten optical output documentation requirements across major markets.
Market Dynamics
The transition from analog verification to digital radiometry platforms is compressing replacement cycles and forcing calibration equipment vendors to embed software connectivity as a baseline capability.
Growth Catalysts
- EU Medical Device Regulation (MDR):Stricter documentation requirements for LED curing light validation are mandating calibrated radiometry equipment in dental practices across EU member states.
- CMOS sensor architecture:Intraoral applications are driving demand for compact digital sensors that integrate with chairside workflows and practice management systems.
- German precision manufacturing clusters:Concentrated dental equipment production in Baden-Württemberg and Bavaria is creating localized demand spikes for quality control instrumentation.
Market Restraints
- Optical component supply concentration:Specialty photodiodes and interference filters rely on a limited supplier base concentrated in East Asian semiconductor foundries.
- ISO 10650 compliance costs:Third-party calibration certification and traceability documentation impose recurring operational burdens on smaller dental clinic operators.
- Smartphone-based substitutes:Low-cost optical measurement apps with external sensors are capturing price-sensitive segments in emerging dental markets.
Strategic Opportunities
- Indian dental infrastructure expansion:Government health scheme rollouts and private clinic chains in Maharashtra and Karnataka are creating first-time equipment procurement waves.
- Spectroscopy-laboratory convergence:Wavelength-specific measurement precision is opening adjacent revenue streams in dental prosthetics manufacturing quality control.
- Cloud-connected calibration services:Remote sensor verification and automated compliance logging are enabling subscription-based revenue models for equipment vendors.
Industry Challenges
- Photonics engineering talent scarcity:Specialized expertise in radiometric detector design and optical system integration remains concentrated in German and Japanese research institutions.
- Legacy analog system integration:Hybrid workflows in mid-sized clinics require backward-compatible digital radiometers with dual readout capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Radiometer Market |
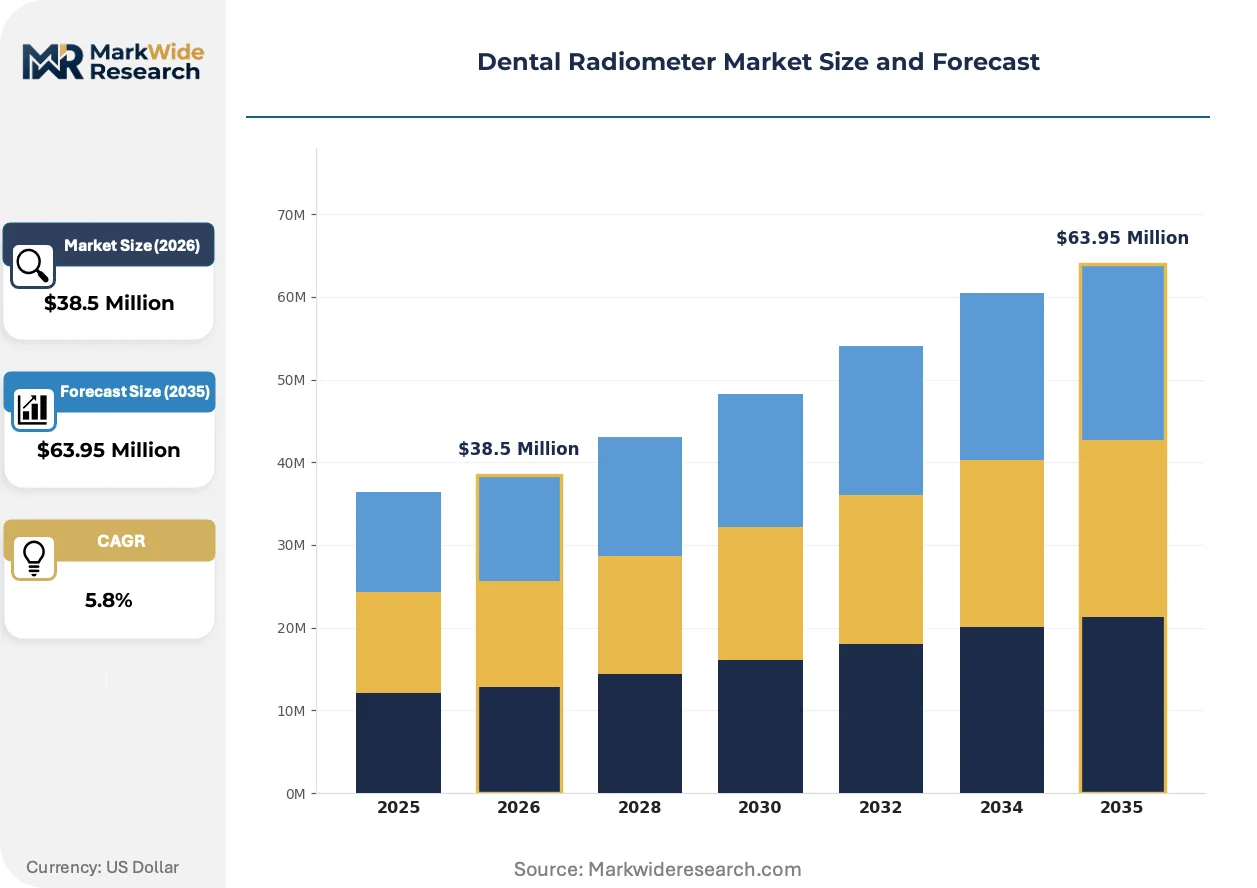
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $63.95 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Fixed Devices, Digital Sensors, Accessories End User: Dental Clinics, Hospitals, Research Laboratories, Educational Institutions Technology: CCD, CMOS, Spectroscopy, Digital Imaging Application: Diagnostics, Treatment Planning, Research, Quality Control |
| Companies Covered | Dentsply Sirona, Envista Holdings Corporation, Planmeca Oy, VATECH, Carestream Dental, ACTEON, J. Morita Corp, Kerr Corporation, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Radiometer Market Strategic Shifts
Sensor miniaturization and wireless data transmission are collapsing the form factor and connectivity constraints that previously segmented portable from laboratory-grade radiometry equipment.
Solid-state CMOS photodetector arrays are overtaking discrete photodiode configurations in intraoral radiometer designs. Dental clinics in Germany and Japan are adopting these platforms at replacement-cycle velocity. The shift is compressing margins for analog-legacy suppliers while enabling real-time output logging directly into electronic health records.
The EU Medical Device Regulation's intensified scrutiny of active therapeutic device documentation is forcing radiometer manufacturers to embed automated calibration traceability. Industrial consequence includes mandatory notified body involvement for software-upgradable measurement devices. Laboratory quality control segments are responding by consolidating vendor relationships to reduce compliance audit burden.
Buying committees in multi-location dental groups are centralizing radiometer procurement through group purchasing organizations. Traditional equipment distributors are losing volume to direct manufacturer contracts with price transparency portals. This pattern is most visible in the United States, where DSO-affiliated clinics now represent the dominant volume channel for digital verification systems.
Dental Radiometer Market Segmentation
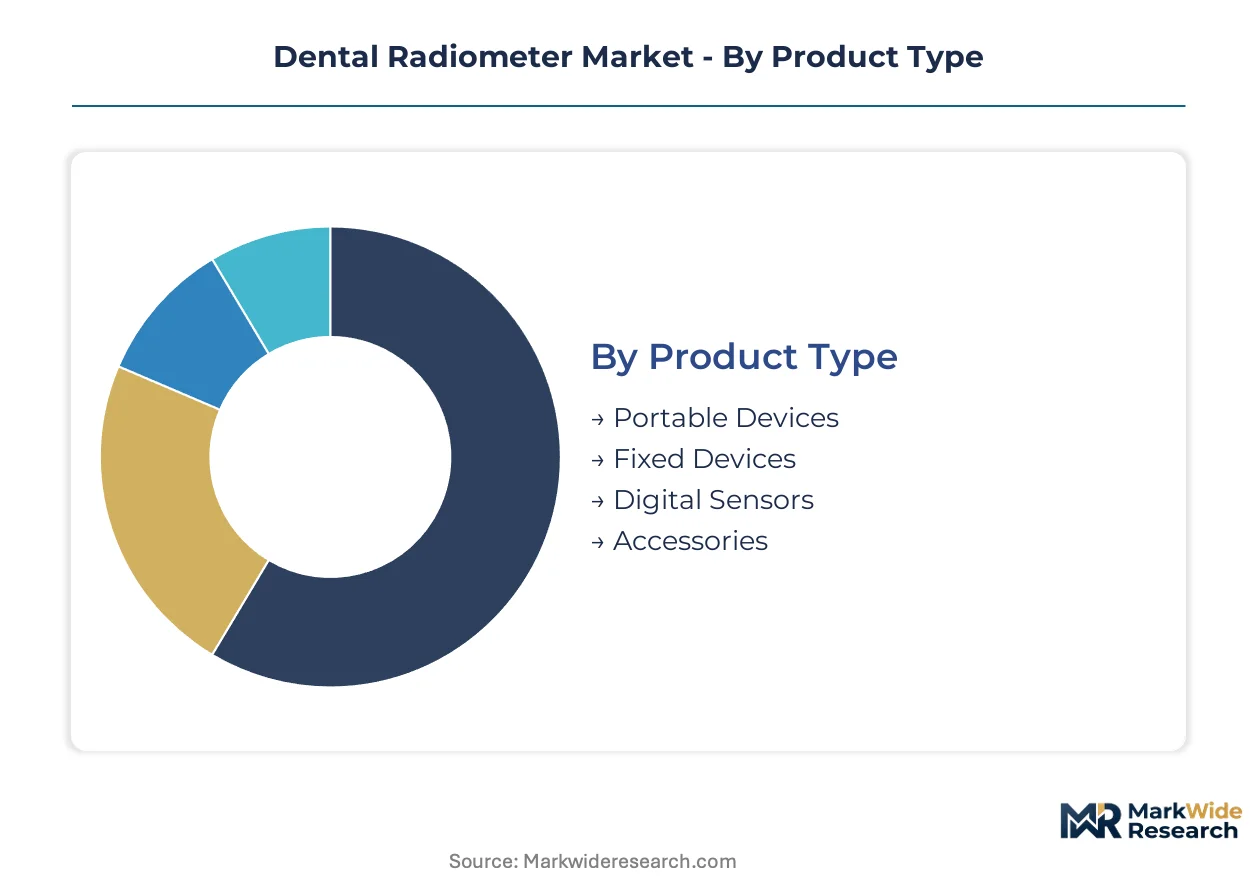
Dental radiometer segmentation reflects divergent workflow requirements across chairside diagnostics, laboratory quality control, and research validation. Equipment specifications vary sharply between portable chairside units demanding wireless connectivity and fixed laboratory systems requiring spectroscopic precision.
Product Type:
Form factor and mobility requirements differentiate procurement patterns across dental practice settings.
- Portable Devices:Battery-powered handheld units integrate CMOS photodetector arrays for chairside optical output verification. Dental clinics in Germany and Japan deploy these at replacement-cycle velocity for real-time curing light validation.
- Digital Sensors:Solid-state measurement modules capture expanding margin pools as clinics abandon analog verification methods. Demand concentrates in multi-location dental groups centralizing procurement through group purchasing organizations.
- Fixed Devices:Benchtop laboratory systems serve prosthetics manufacturers requiring wavelength-specific measurement documentation.
- Accessories:Calibration standards, protective housings, and interface cables support equipment lifecycle management.
Portable devices lead on scale; digital sensors lead on momentum.
End User:
Procurement authority and compliance burden shape vendor engagement strategies across customer categories.
- Dental Clinics:Independent practices and dental service organizations drive volume demand for integrated radiometry platforms. FDA 510(k) clearance requirements and EU MDR documentation obligations dominate vendor selection criteria.
- Hospitals:Academic medical centers and dental schools require multi-unit calibration systems with centralized data logging. Budget approval cycles extend procurement timelines compared to private practice channels.
- Research Laboratories:Spectroscopy-grade precision requirements support premium pricing for wavelength-resolved measurement systems.
- Educational Institutions:Dental training programs generate steady replacement demand for demonstration-grade equipment.
Dental clinics dominate absolute volume; research laboratories command premium pricing.
Technology:
Sensor architecture selection determines integration compatibility and measurement resolution specifications.
- CMOS:Complementary metal-oxide-semiconductor photodetector arrays enable compact intraoral designs with direct electronic health record connectivity. CMOS technology leads sensor architecture for intraoral applications across German and Japanese dental equipment markets.
- Spectroscopy:Wavelength-resolved measurement systems serve laboratory quality control workflows requiring precise optical characterization. Spectroscopy segments capture adjacent revenue streams in dental prosthetics manufacturing.
- CCD:Charge-coupled device sensors retain niche positioning in high-sensitivity laboratory instruments.
- Digital Imaging:Integrated camera-based verification systems support documentation requirements under intensified EU MDR scrutiny.
CMOS leads on deployment scale; spectroscopy leads on margin expansion.
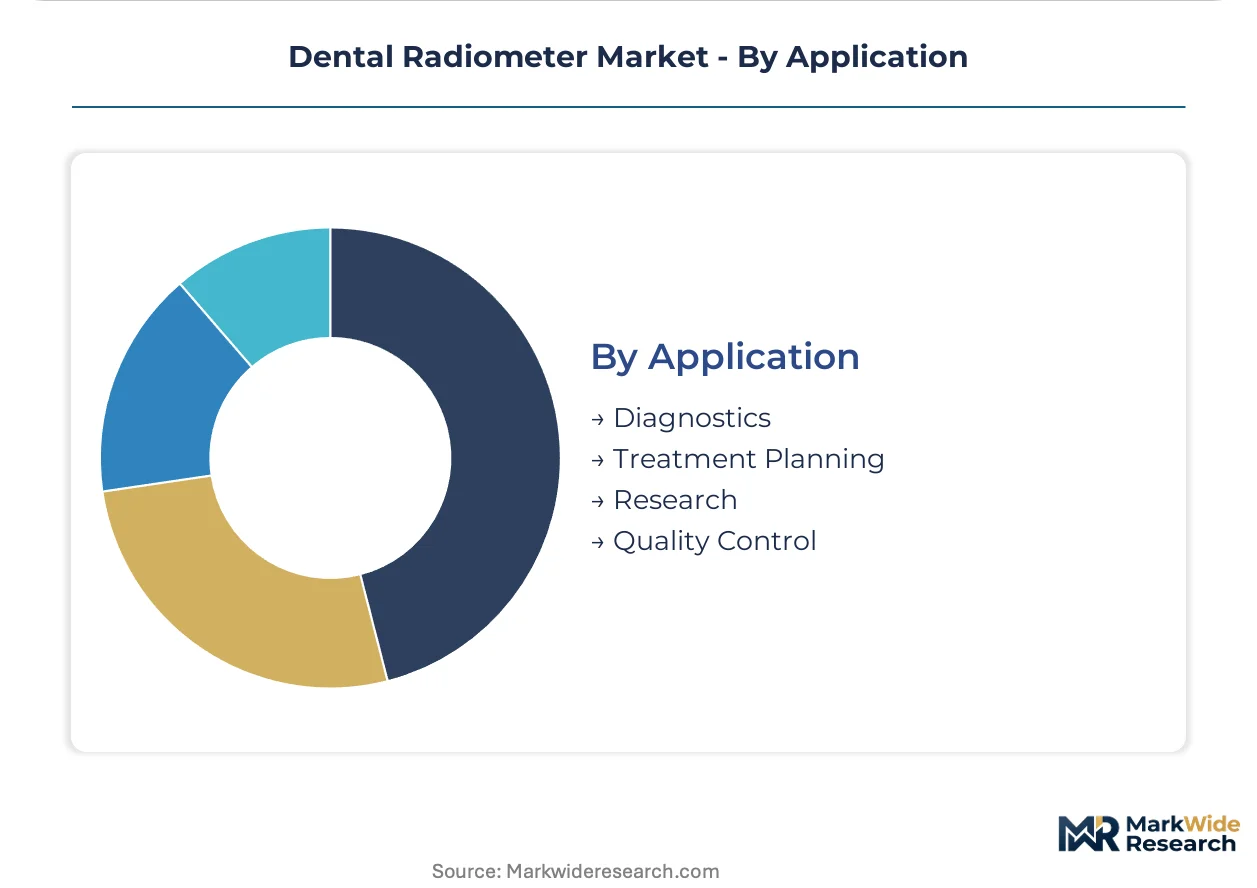
Application:
Functional use case determines performance specifications and regulatory documentation requirements.
- Diagnostics:Chairside curing light verification ensures adequate polymerization energy delivery for restorative procedures. Portable digital radiometers dominate this segment through workflow integration with practice management software.
- Quality Control:Laboratory-based optical output documentation supports ISO 10650 compliance for curing light manufacturers. Spectroscopy-equipped systems serve this application with wavelength-specific measurement precision.
- Treatment Planning:Pre-procedure light source verification reduces restoration failure rates and associated remediation costs.
- Research:Academic validation of LED curing light performance drives demand for calibrated reference radiometers with traceable certification.
Diagnostics leads on unit volume; quality control leads on specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision manufacturing clusters anchor European equipment demand, while regulatory divergence across major economies forces vendors to maintain parallel certification tracks. Dental service organization expansion in North America and government health scheme rollouts in Asia-Pacific are redrawing procurement geography.
United States
Dental service organizations now control the dominant procurement channel for digital verification systems. The FDA's 510(k) premarket notification requirements for Class II medical devices shape product clearance timelines and vendor selection criteria. Minneapolis-based calibration equipment distributors are losing volume to direct manufacturer contracts with price transparency portals.
Germany
Precision dental manufacturing in Stuttgart and Munich generates localized demand spikes for quality control instrumentation. The EU Medical Device Regulation mandates CE marking with notified body involvement for active therapeutic devices. Bavarian dental equipment production clusters require wavelength-specific measurement documentation for export compliance.
Japan
Intraoral CMOS photodetector adoption is accelerating at replacement-cycle velocity across Tokyo and Osaka metropolitan practices. METI standards harmonization with ISO 10650 creates streamlined compliance pathways for domestic manufacturers. Nagoya-area research institutions concentrate specialized photonics engineering expertise for radiometric detector design.
India
Government health scheme rollouts and private clinic chains in Maharashtra and Karnataka are creating first-time equipment procurement waves. The Central Drugs Standard Control Organization regulates medical device imports through mandatory registration requirements. Mumbai-based dental distributors are building calibration service capabilities to capture aftermarket revenue.
China
Domestic LED curing light manufacturing expansion in Guangdong and Jiangsu provinces is generating quality control equipment demand. The National Medical Products Administration enforces GB standards compliance for active therapeutic devices. Shenzhen semiconductor foundries supply specialty photodiodes to regional radiometer assemblers.
Dental Radiometer Market Competitive Environment
Strategic partnerships dominate the current landscape as equipment vendors seek embedded software connectivity capabilities. The vendor base stratifies across three tiers: multinational imaging conglomerates with installed base leverage, mid-scale dental equipment specialists with regional fabrication control, and component-focused sensor technology providers. Two strategic archetypes prevail—cross-sell platform players leveraging imaging system installed bases, and vertical integration specialists capturing margin through captive sensor manufacturing. Geographic expansion into Indian and Southeast Asian dental infrastructure markets represents the second dominant competitive move.
Among multinational imaging conglomerates, Dentsply Sirona and Envista Holdings Corporation exemplify cross-sell platform strategies. Planmeca Oy anchors the vertical integration archetype through its Nordic manufacturing footprint. These three companies occupy positions across the premium and standard equipment tiers, with Dentsply Sirona representing scale-driven consolidation, Envista Holdings Corporation exemplifying training infrastructure differentiation, and Planmeca Oy demonstrating regional manufacturing control.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Envista Holdings Corporation |
| Planmeca Oy |
| VATECH |
| Carestream Dental |
| ACTEON |
| J. Morita Corp |
| Kerr Corporation |
| 3M |
| Others |
Value Chain & Pricing Dynamics
EU MDR-mandated calibration documentation is forcing dental practices toward digitally connected radiometry platforms, compelling suppliers to absorb sensor certification costs while maintaining tiered pricing accessibility across clinic budget tiers.
Pricing Analysis
Specialty photodiode cost pass-through from East Asian foundries feeds directly into portable device pricing. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared systems with automated compliance logging from basic CMOS units and smartphone-tethered alternatives. Cost compression in economy tiers is intensifying because Indian clinic chains negotiate volume contracts. Price sensitivity peaks among independent Indian practitioners; German precision manufacturers show lowest sensitivity due to reimbursement clarity.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Minneapolis, and Osaka coordinate hub-and-spoke patterns for calibration equipment delivery. Manufacturing draws from German precision optics clusters, Japanese CMOS foundries, and Chinese LED component suppliers. Specialty interference filters and photodiodes rest on single-source vulnerability from Taiwan and South Korea semiconductor fabricators. Distribution runs through dental equipment distributors losing share to direct manufacturer portals serving DSO procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR compliance costs in member states create margin expansion opportunities for vendors with pre-certified platforms against Indian competitors facing registration delays.
For Market Incumbents: Hedge against smartphone-based measurement substitutes by embedding cloud-connected calibration services into hardware contracts. Capture margin through backward integration into CMOS sensor design rather than sourcing from Japanese foundries. Prioritize certification investment for software-upgradable devices ahead of intensified EU notified body scrutiny. For New Entrants and Emerging Players: Enter via Maharashtra and Karnataka dental clinic chains where government health scheme rollouts generate first-time procurement waves. Target laboratory spectroscopy segments where wavelength-specific precision commands premium pricing absent in saturated chairside portable markets. Deploy training infrastructure partnerships as primary go-to-market angle against established imaging conglomerates. For Investors and Strategic Acquirers: Asymmetric upside sits with component-focused sensor technology providers possessing captive photonics engineering talent. Five-to-ten year viability hinges on regulatory harmonization trajectories across FDA, EU MDR, and NMPA pathways. Watch for inflection when DSO-affiliated clinic procurement centralization crosses threshold to force distributor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Calibration Service Launch | Subscription revenue from Dentsply Sirona and Envista Holdings clinic networks displaces transactional hardware sales. |
| CMOS Sensor Architecture Investment | Vertical control over photodetector design secures Planmeca Oy margin against East Asian component volatility. |
| Indian Distribution Partnership | Mumbai-based calibration service capabilities capture aftermarket revenue from CDSCO-registered import channels. |
| EU MDR Software Documentation Pathway | Notified body pre-certification for upgradeable devices creates compliance moat against non-EU competitors. |
| Spectroscopy-Laboratory Segment Expansion | Wavelength-resolved systems penetrate dental prosthetics manufacturing quality control beyond chairside diagnostics. |
Study Parameters
Direct dialogue with dental equipment procurement managers, biomedical engineers at academic medical centers, GPO contracts administrators, and regulatory affairs specialists at imaging conglomerates grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, ISO 10650 standard revisions, and hospital procurement database extracts. Bottom-up clinic deployment estimates and top-down equipment manufacturer revenue analysis were triangulated for segmentation sizing.
Top-down macroeconomic framing anchored regional demand projections while bottom-up unit economics modeled replacement cycles and CMOS adoption curves across the analysis window. Segmentation dimensions included form factor mobility, sensor technology architecture, end-user procurement authority, and application workflow integration. CAGRs were derived from fitted adoption curves incorporating EU MDR implementation timelines and Indian health scheme expansion trajectories.
Inputs from regulatory filing databases and distributor shipment records were available through the study window; gaps in real-time DSO procurement transaction data introduce uncertainty bands around North American volume estimates. Forecasts reflect documented assumptions regarding MDR enforcement intensity and LED curing light validation standard harmonization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Dental Laboratory Welders Market
Dental Devices
Sleep Apnea Oral Appliances Market
Dental Devices
Periodontal Scalers and Curettes Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Dental Fittings Market
Dental Devices
GCC Dental Implants Market
Dental Devices
Global Dental Microscope Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
3D Printed Clear Dental Aligners Market
Dental Devices
Dental Aligners Market
Dental Devices
Global Dental Bone Graft Substitutes Market
Dental Devices
Dental Erbium Lasers Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
North America Aligner Sheet Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Dental Delivery System Market