
 Dental Impression Tray Market | 2026-2036
Dental Impression Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Impression Tray Market Intelligence
The capability gap between large-scale polymer manufacturing and specialized custom tray fabrication is rotating market dynamics. Global players like Ivoclar Vivadent leverage extensive material science R&D to offer a broad portfolio. In contrast, specialists such as Dental Tray System International focus on patented custom tray systems for specific procedures. PLANMECA OY integrates its tray offerings with its broader digital dentistry ecosystem, creating a distinct value proposition.
A dental impression tray is a device used to carry and control impression material for creating a negative imprint of oral structures. Trays are engineered from materials like plastic or metal, often featuring perforations or rim locks for mechanical retention. While disposable plastic trays command the largest market volume, custom trays are gaining share due to precision demands in implantology. Prosthodontics constitutes the primary application, with orthodontics emerging as a high-growth area.
Market access hinges on compliance with medical device regulations, such as the FDA's 510(k) process in the United States and CE marking under the EU's MDR. In Japan, the PMDA imposes similar stringent requirements for device registration, all of which mandate biocompatibility testing and influence material choices. The key decision for manufacturers will be balancing investment in digital-ready custom trays against optimizing production for high-volume, disposable stock trays.
Market Dynamics
The central structural force shaping the market is the bifurcation between high-volume, low-cost disposable trays and high-precision, digitally integrated custom trays. This divide is driven by expanding applications in implantology, which demand superior accuracy that standard trays cannot consistently provide.
Growth Catalysts
- Implantology Expansion:The rising procedural volume in dental implantology necessitates highly accurate impressions to ensure the precise fit of prosthetics, directly fueling demand for custom and specialized tray systems.
- Digital Workflow Integration:The combination of intraoral scanning with physical impressions for complex clinical cases creates a hybrid workflow, sustaining the need for advanced, digitally-compatible trays.
- Prosthodontic Standards:Advanced dental markets like Germany and Japan maintain rigorous standards for prosthodontics, which supports premium pricing and adoption of high-performance tray materials and designs for superior clinical outcomes.
Market Restraints
- Material Costs:The use of medical-grade, biocompatible polymers and metals for custom and reusable trays results in a significantly higher unit cost compared to disposable plastic alternatives, limiting their adoption in price-sensitive segments.
- Digital Substitution Threat:The continued advancement of full-arch intraoral scanners presents a long-term substitution risk, as these technologies aim to eliminate the need for physical impressions and trays altogether.
- Regulatory Compliance Burden:Stringent validation processes, such as the FDA's 510(k) clearance and the EU's MDR, create significant time and cost barriers for new product introductions and material innovations.
Strategic Opportunities
- Orthodontic Applications:The rapid expansion of the clear aligner market presents a significant opportunity for custom trays used in the initial impression-taking stage, which is critical for accurate aligner fabrication.
- 3D Printing Integration:Developing tray systems and materials optimized for in-office or lab-based 3D printing allows for rapid, cost-effective fabrication of patient-specific custom trays on demand.
- Emerging Market Education:Partnering with dental schools and professional associations in developing economies to provide training on advanced impression techniques can build long-term demand for specialized tray products.
Industry Challenges
- Technician Skill Gap:A shortage of dental laboratory technicians skilled in both traditional model work and digital design software creates a bottleneck in the production of high-quality custom trays.
- System Interoperability:The lack of standardization between different digital scanning systems and CAD/CAM software complicates the design and use of universal, digitally-ready impression trays.
- Supply Chain Complexity:Manufacturers must manage a dual supply chain: one optimized for mass production of stock trays and another built for the rapid, on-demand logistics of patient-specific custom trays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Impression Tray Market |
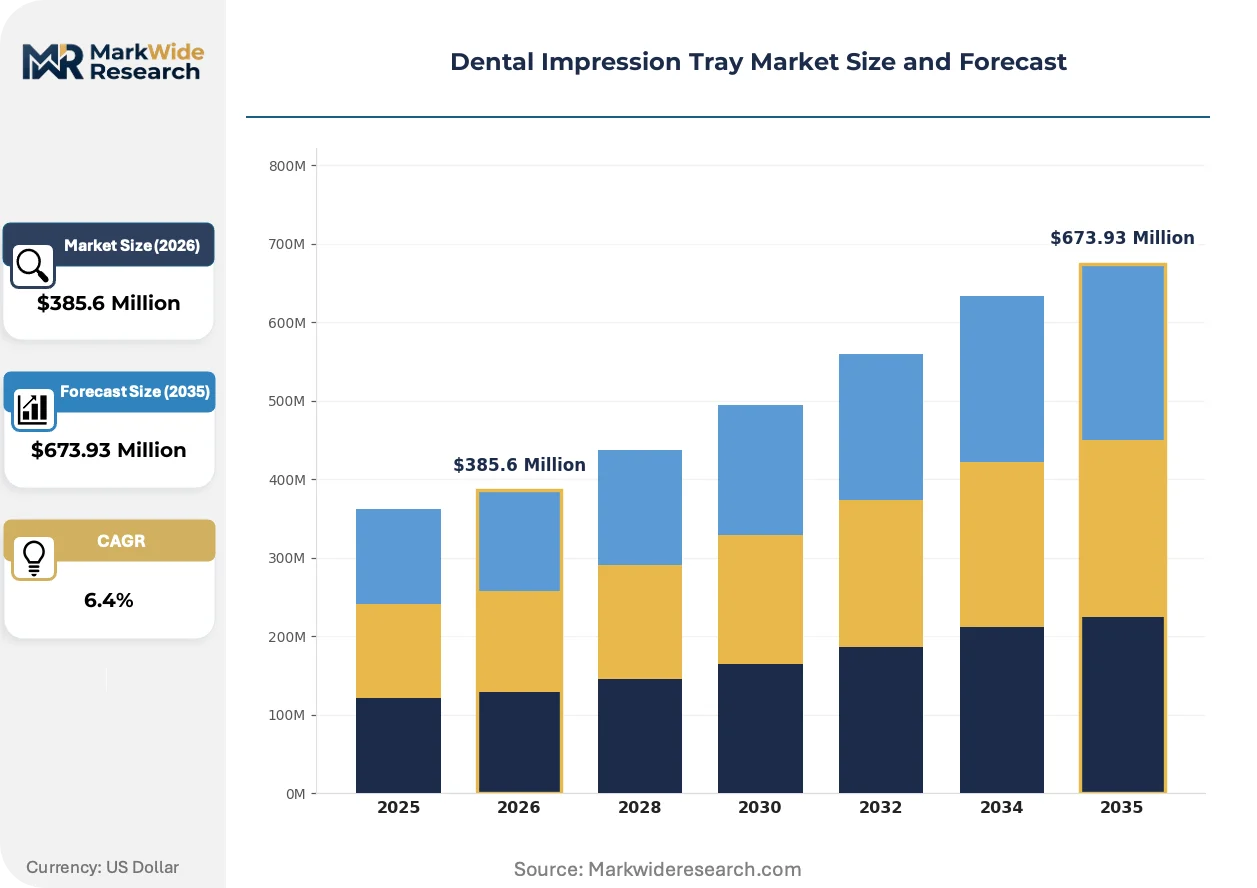
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Metal, Silicone, Polyether, Thermoplastic Elastomer Tray Type: Stock, Custom, Dual Arch, Perforated, Rim Lock Application: Prosthodontics, Orthodontics, Restorative Dentistry, Implantology, Pediatric Dentistry End User: Dental Clinics, Dental Laboratories, Specialty Clinics, Academic Institutions, Mobile Dental Units |
| Companies Covered | Zhermack SpA, AR Instrumed Deutschland, A. Schweickhardt, Dental Tray System International, Hager & Werken, Power Dental USA, SmithcareR, Ivoclar Vivadent, PLANMECA OY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Impression Tray Market Strategic Shifts & Innovations
A primary transformation involves the augmentation of traditional impression methods with digital tools, rather than outright replacement. This creates a hybrid clinical environment where physical trays gain new relevance as components within a broader digital workflow, especially for complex restorative cases.
The use of 3D printing technology allows for the on-demand fabrication of patient-specific custom trays directly from digital scan data. Dental laboratories and larger clinical practices are the primary adopters of this technology. On-site 3D printing is displacing the slower, more labor-intensive manual methods of creating custom trays, significantly reducing patient wait times and material waste.
Regulatory frameworks, particularly the EU's Medical Device Regulation (MDR), are elevating compliance requirements across the board. The MDR mandates more rigorous clinical data, biocompatibility testing, and post-market surveillance for all devices, including impression trays. This most acutely affects manufacturers of custom and reusable metal trays, forcing investment in enhanced quality management systems and more robust material traceability.
A notable behavioral shift is occurring as dental service organizations (DSOs) and large clinics move toward sourcing trays as part of integrated technology packages. This model disrupts the conventional sales channel, which relies on standalone product purchases through distributors. The trend is most pronounced in North America and Europe, where large vendors offer comprehensive digital dentistry ecosystems that bundle equipment, software, and consumables.
Dental Impression Tray Market Segmentation
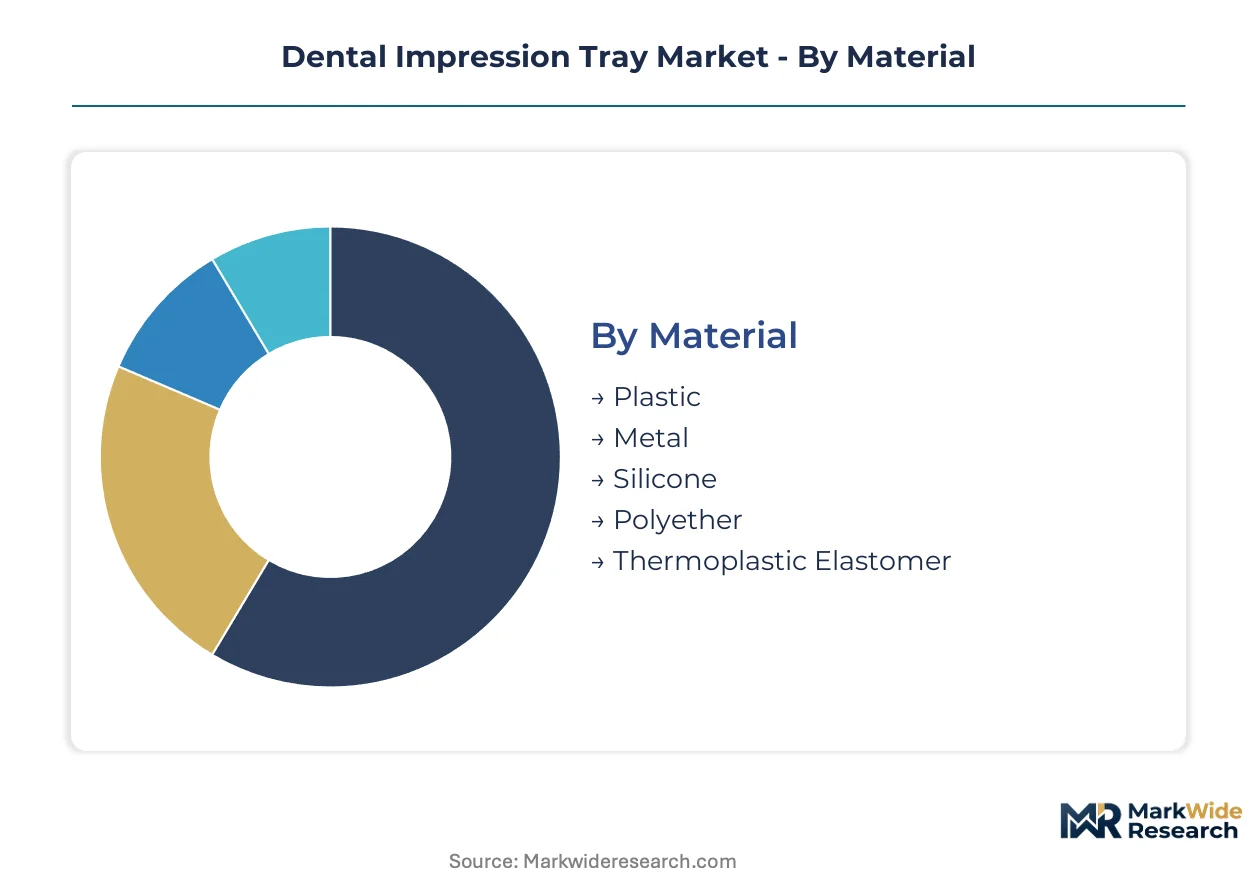
The dental impression tray market bifurcates across several critical dimensions, reflecting diverse clinical requirements and technological advancements. Understanding these segments clarifies the varying demand drivers and the specific competitive pressures faced by manufacturers in different product categories.
Material:
Segments categorized by material face strong substitution pressure from advancements in digital impression techniques, particularly for standard cases.
- Plastic:These trays are typically disposable, providing a cost-effective solution for routine dental procedures and general dentistry. Their widespread use in North America and Europe is driven by convenience and infection control protocols.
- Metal:Constructed from stainless steel or aluminum, metal trays are reusable and designed for durability, offering superior rigidity for high-precision impressions in advanced prosthodontics. Demand is concentrated in markets like Germany, where reusability and precision are highly valued.
- Silicone:Offering flexibility and comfort, silicone trays are often used for specific impression techniques where patient comfort or intricate detail capture is paramount.
- Polyether:Known for its exceptional accuracy and hydrophilic properties, polyether material is preferred for complex restorative cases requiring fine detail reproduction.
- Thermoplastic Elastomer:These materials combine properties of rubber and plastic, allowing for trays that can be customized with heat for a better fit during impression taking.
Plastic retains volume leadership; Metal holds the steepest expansion curve.
Tray Type:
Application needs significantly influence the selection of tray types, with specialized procedures driving demand for advanced designs.
- Custom:Individually fabricated for a patient's unique oral anatomy, custom trays ensure optimal fit and material distribution, which is critical for high-precision applications like implantology. Their demand is rising in countries with advanced dental care systems such as Japan.
- Stock:These are pre-manufactured, standardized trays available in various sizes, serving as a versatile and economical option for a broad range of general dental impressions. Stock trays maintain high usage volumes across all dental clinics.
- Dual Arch:Designed to capture opposing arches and the bite registration simultaneously, dual arch trays streamline impression procedures for specific restorative cases.
- Perforated:Featuring small holes across the tray surface, perforated trays provide mechanical retention for impression materials, ensuring better adhesion and stability.
- Rim Lock:Equipped with a rim or flange to mechanically lock the impression material, rim lock trays enhance material retention and prevent dislodgement during removal.
Stock trays represent the foundational volume; Custom trays demonstrate the most significant growth potential.
Application:
Volume drivers within the dental impression tray market are largely dictated by the prevalence and complexity of specific dental treatments.
- Prosthodontics:This segment encompasses impressions for dentures, crowns, bridges, and veneers, representing the largest application area due to the high global incidence of tooth loss and restorative needs.
- Orthodontics:Impressions are essential for diagnostic models, treatment planning, and the fabrication of orthodontic appliances, including clear aligners, which are driving demand in this segment.
- Implantology:Requiring highly accurate impressions for precise placement and prosthetic fit, implantology is a key growth catalyst for specialized and custom tray systems. The segment is expanding rapidly in developed economies.
- Restorative Dentistry:This category includes impressions for fillings, inlays, and onlays, focusing on restoring the function and integrity of damaged teeth.
- Pediatric Dentistry:Tailored for smaller oral anatomies, pediatric applications involve impressions for space maintainers, crowns, and diagnostic models in children.
Prosthodontics commands the largest market share; Implantology is expanding most quickly.
End User:
Customer types vary significantly in their procurement patterns and demand for different tray technologies.
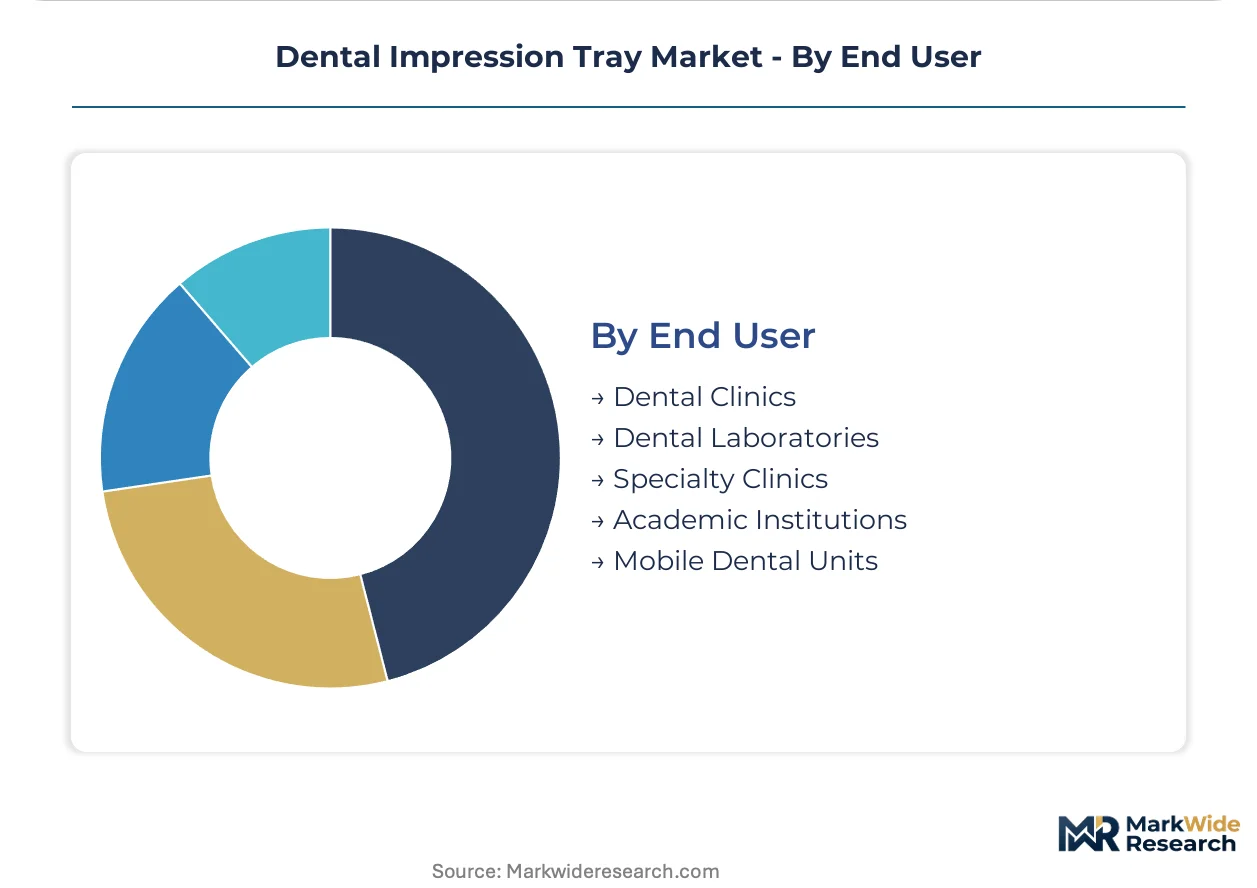
- Dental Clinics:These facilities represent the largest end-user segment, utilizing a wide range of impression trays for routine check-ups, restorative procedures, and specialized treatments.
- Dental Laboratories:Functioning as manufacturing hubs for dental prosthetics, laboratories require trays for model fabrication and often prefer custom or high-precision options.
- Specialty Clinics:Focused on specific disciplines like orthodontics or periodontics, these clinics demand specialized trays tailored to their unique procedural requirements.
- Academic Institutions:Dental schools and research centers use impression trays for educational purposes, research, and patient treatment within their teaching clinics.
- Mobile Dental Units:Providing dental care in remote or underserved areas, these units prioritize portable and efficient impression solutions, often favoring disposable options.
Dental Clinics form the core customer base, while Dental Laboratories represent a significant, technology-driven segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing-power asymmetry characterizes the dental impression tray market, with advanced economies like Germany commanding higher prices for precision instruments. Conversely, regions such as India prioritize cost-effectiveness, driving demand for high-volume, disposable solutions. This divergence shapes product development and market access strategies across global geographies.
United States
Demand for custom trays stems from complex implantology cases and a robust private dental insurance market. The FDA's 510(k) clearance process ensures rigorous material and device safety standards. Major dental equipment manufacturers in states like California and New York drive innovation in digital impression technologies.
Germany
High-precision prosthodontics and a strong emphasis on reusability fuel demand for metal impression trays. CE marking under the EU's MDR mandates stringent biocompatibility testing and quality management. Dental technology clusters in Bavaria and North Rhine-Westphalia specialize in advanced manufacturing for premium dental devices.
Japan
Rigorous quality standards in advanced dental care systems support the adoption of custom and high-accuracy impression trays. The PMDA imposes stringent device registration requirements, influencing material choices and product development. Tokyo and Osaka host numerous dental research institutions and specialized clinics advancing precision impression techniques.
China
Expanding access to dental care and a growing middle class increase the volume of routine dental procedures, boosting demand for stock plastic trays. The NMPA regulates medical devices, focusing on local manufacturing standards and product safety. Manufacturing hubs in the Yangtze River Delta region produce a wide range of dental consumables for domestic and export markets.
India
The rapid expansion of dental clinics in urban and semi-urban areas drives significant volume demand for cost-effective impression solutions. The CDSCO regulates medical devices, ensuring compliance with local manufacturing and import standards. Major cities like Mumbai and Bangalore are emerging as centers for dental tourism, requiring both standard and specialized trays.
Dental Impression Tray Market Key Industry Players
Concentration sits with established dental material science companies offering broad portfolios across various impression techniques. The market also includes specialized manufacturers focusing on niche solutions like custom tray systems. Strategic partnerships between digital dentistry providers and traditional tray manufacturers are reshaping competitive positioning. Companies increasingly pursue portfolio diversification to capture both high-volume disposable and high-precision custom tray segments.
Specialists in advanced dental materials, such as Ivoclar Vivadent, exemplify companies leveraging extensive material science R&D to offer comprehensive impression solutions. These firms often provide a broad range of products, from stock trays to specialized materials, catering to diverse clinical needs across various dental procedures. Dental Tray System International represents a focused approach, providing patented custom tray systems designed for specific, high-precision applications like implantology. This specialization allows them to cater to the growing demand for accuracy in complex cases. PLANMECA OY, integrating its tray offerings within a broader digital dentistry ecosystem, positions itself as a comprehensive technology provider. This strategy creates a distinct value proposition by bundling hardware, software, and consumables for a seamless digital workflow in dental practices.
| Leading Market Players |
|---|
| Zhermack SpA |
| AR Instrumed Deutschland |
| A. Schweickhardt |
| Dental Tray System International |
| Hager & Werken |
| Power Dental USA |
| SmithcareR |
| Ivoclar Vivadent |
| PLANMECA OY |
| Others |
Cost & Logistics Intelligence
The EU's Medical Device Regulation (MDR) gates supply qualification and mandates specific biocompatibility testing, simultaneously driving price differentiation for compliant, high-quality impression trays. This regulatory framework ensures product safety while influencing material choices and market access across Europe.
Pricing Analysis
The customization-premium spread defines the pricing model for dental impression trays, with per-unit transactional pricing dominating stock trays and value-based pricing applied to patient-specific custom solutions. Price differentiation stems from the level of customization required and the quality grade of medical-grade materials. Pricing softness runs through the high-volume disposable plastic tray segment, driven by intense competition from Asian manufacturers. Advanced dental markets, such as Germany, exhibit lower price sensitivity for precision metal trays, while emerging economies prioritize cost-effectiveness for stock plastic alternatives.
Supply Chain Analysis
Inventory management for dental impression trays balances rapid delivery for high-volume stock items against extended lead times for custom fabrication. Geographic supply concentration for raw materials like medical-grade polymers centers on China and the United States, while specialized metal tray manufacturing is strong in Germany. The supply chain relies on a dual sourcing strategy for mass-produced components and specialized inputs. Regulatory restrictions, such as those from the FDA and PMDA, represent a structural risk, influencing material procurement and market entry. Distribution runs through a hybrid model, utilizing both large dental distributors and direct-to-clinic or lab channels for specialized products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is poised for a cyclical recovery, driven by the increasing volume of elective dental procedures deferred during recent economic uncertainties.
For Market Incumbents: Shield against the digital substitution threat by investing heavily in hybrid workflow solutions that integrate physical trays with intraoral scanning. Leverage existing channel control through established distributor networks and Dental Service Organizations (DSOs) to push advanced material offerings. Prioritize certification investment under stringent regimes like the EU MDR to maintain a premium position in advanced markets.
For New Entrants and Emerging Players: Lead with specialized materials and manufacturing techniques for patient-specific custom trays, particularly those optimized for 3D printing. Target the rapidly expanding orthodontic segment, especially for clear aligner fabrication, which remains highly dependent on accurate initial impressions. A direct-to-lab sales model emphasizing rapid turnaround and digital integration can provide a strong go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the patient-specific custom tray manufacturing segment, driven by 3D printing investments. The long-term viability favors firms capable of integrating material science with digital dentistry platforms. Acquire specialized custom tray manufacturers or software providers that enhance impression accuracy and workflow efficiency. The signal to watch is the adoption rate of chairside 3D printers in larger dental practices.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Hybrid Workflow Solutions | Integrates physical impressions with digital scanning, preserving tray relevance in complex restorative cases. |
| Invest in 3D Printing Materials | Enables rapid, patient-specific custom tray fabrication, reducing lead times and material waste. |
| Target Orthodontic Clear Aligner Market | Captures demand from a high-growth segment requiring precise initial impressions for appliance accuracy. |
| Enhance Regulatory Compliance Infrastructure | Ensures market access and premium pricing in advanced markets with stringent medical device regulations. |
| Form Strategic Partnerships with Digital Dentistry Providers | Bundles tray offerings within broader ecosystems, creating a distinct value proposition for comprehensive solutions. |
Research Approach
A spread of perspectives from dental practitioners, lab owners, material science engineers, and regulatory compliance officers converged on the working assumptions underpinning this analysis. The study combined primary interviews with extensive secondary validation from sources including FDA 510(k) databases, EU MDR guidance documents, dental industry trade publications, and academic research on impression accuracy. Both bottom-up and top-down triangulation approaches were employed to ensure data consistency and robustness.
The forecast framework modeled segmentation dimensions across material, tray type, application, end-user, and regional regulatory environments over the projection horizon. Compound annual growth rates (CAGRs) were derived from historical trends and projected market influences, including global dental expenditure trends and clear aligner market penetration rates. This comprehensive approach provides a detailed understanding of market dynamics and future trajectories.
The analysis sits within stated boundaries; outcomes outside rapid advancements in intraoral scanning capabilities or unforeseen regulatory shifts would require recalibration. Forecasts reflect assumptions regarding technological evolution and market adoption rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
South Africa Dental Devices Market
Dental Devices
Dental Contouring Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
Dental Hand Tools Market
Dental Devices
Global Dental Endodontics Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Dental Regeneration Market
Dental Devices
Dental Radiometer Market
Dental Devices
3D Printed Clear Dental Aligners Market
Dental Devices
Lights for Dental Healthcare Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Self-Ligating Bracket Sales Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Dental Needle Market
Dental Devices
Dental Autoclave Market