
 Dental Implants and Abutment Systems Market | 2026-2036
Dental Implants and Abutment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Implants and Abutment Systems Market Analysis
Subscription-based equipment leasing is reconfiguring capital deployment across dental practices, lowering barriers for clinics to access premium implant systems. Straumann leverages its integrated digital workflow to sustain premium positioning across CAD/CAM-enabled procedures. Hiossen anchors its competitive stance through manufacturing scale and cost-optimized titanium implant portfolios. Osstem Implant dominates the Asian market through dense distributor networks and localized regulatory expertise.
Dental implants and abutment systems comprise titanium or zirconia fixtures surgically placed into jawbone, typically measuring 3.0–6.0 mm in diameter and 7.0–16.0 mm in length, designed to osseointegrate and support prosthetic crowns or bridges. Endosteal implants account for the dominant product category due to established clinical protocols and broad bone-type compatibility, while zirconia material segments are gaining traction among metal-allergic patient populations. CAD/CAM technology leads the technology dimension through precision-milled abutments, though 3D printing is emerging fastest for surgical guide production.
The FDA's 510(k) framework and the EU Medical Device Regulation (MDR) impose biocompatibility and sterility standards that filter market participants by testing capacity and quality-system maturity. ISO 13485 certification serves as a baseline predicate for international market access, particularly for manufacturers targeting multiple jurisdictions. Stakeholders must monitor evolving reimbursement codes and digital dentistry integration requirements as decisive variables for portfolio prioritization.
Market Dynamics
Digital dentistry workflows are compressing treatment timelines and forcing implant manufacturers to integrate CAD/CAM compatibility as a baseline requirement rather than a premium feature. This technological convergence is restructuring competitive advantage toward software-hardware integration capabilities.
Growth Catalysts
- MFDS reimbursement expansion:South Korea's national health insurance now covers select implant procedures for seniors, expanding addressable patient pools beyond private-pay segments.
- Titanium plasma-sprayed surfaces:Advanced osseointegration coatings are shortening healing periods from six months to eight weeks, accelerating procedure throughput in high-volume clinics.
- Subscription-based equipment leasing:Dental practices in Germany are accessing premium surgical motors and imaging systems through monthly payment structures, lowering capital barriers for implant service expansion.
Market Restraints
- Titanium feedstock concentration:Surgical-grade titanium sponge supply clusters in Chinese and Russian smelters, exposing manufacturers to geopolitical supply disruptions and input cost volatility.
- EU MDR compliance burden:The Medical Device Regulation's enhanced clinical evidence requirements for Class IIb devices are extending time-to-market for new abutment designs by 18-24 months.
- Zirconia brittleness limitations:Ceramic implants carry elevated fracture risk in posterior molar placements, restricting their addressable indication set versus titanium alternatives.
Strategic Opportunities
- India's underpenetrated tier-2 cities:CDSCO streamlined medical device registration pathways are enabling multinational manufacturers to establish distribution in Lucknow, Jaipur, and Kochi ahead of domestic competitor scale.
- Same-day immediate loading protocols:Convergence of 3D-printed surgical guides with intraoral scanning is enabling single-visit implant placement, capturing premium positioning in time-sensitive patient segments.
- Direct-to-clinic digital portals:Manufacturers are bypassing traditional dental distributors by selling CAD/CAM abutment libraries through proprietary cloud platforms, capturing margin and usage data.
Industry Challenges
- Digital workflow integration complexity:Clinics face steep learning curves unifying implant planning software with existing practice management systems, requiring dedicated IT support hires.
- ISO 13485 certification timelines:New market entrants face 12-18 month quality system audits before achieving predicate device eligibility for FDA 510(k) submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Implants and Abutment Systems Market |
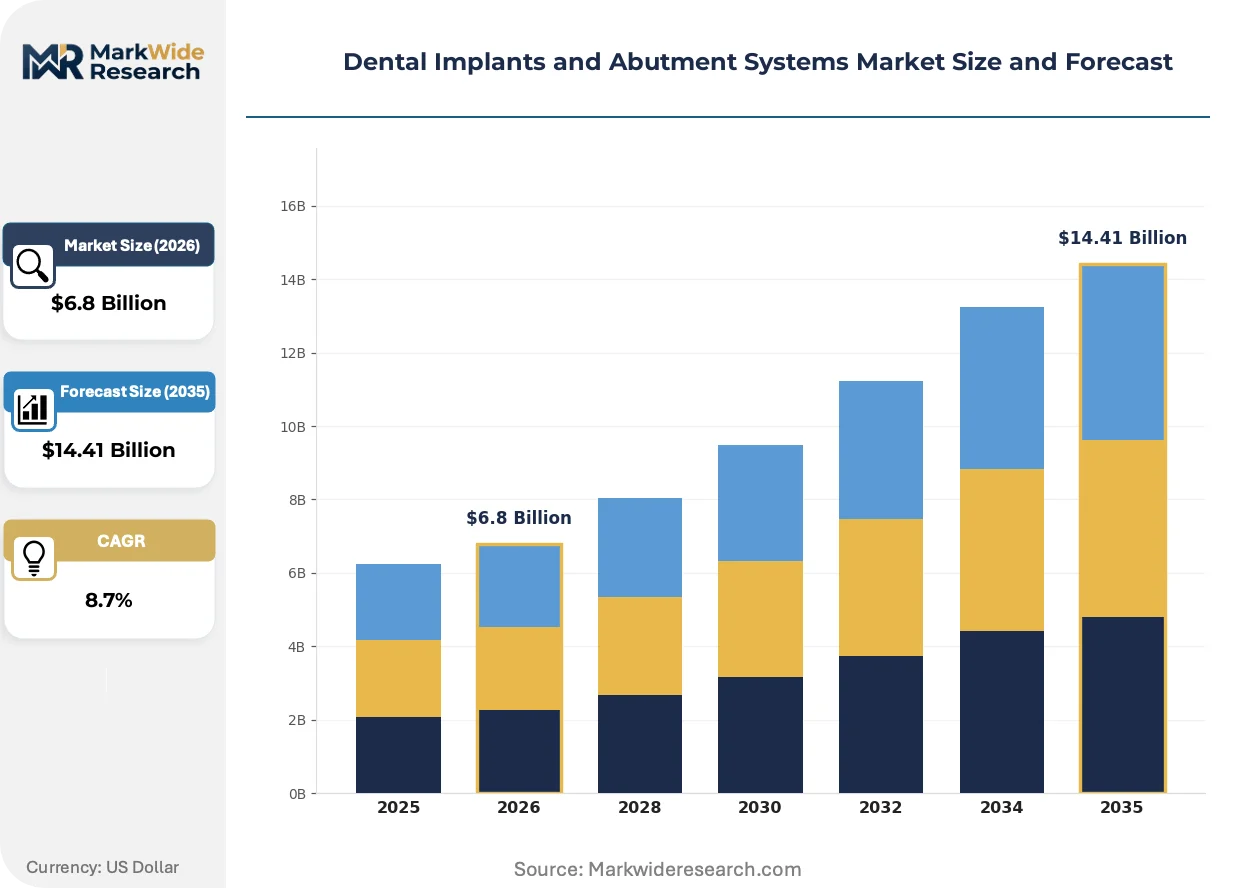
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endosteal, Subperiosteal, Zygomatic, Mini Material: Titanium, Zirconia, Polymer, Alloy Technology: CAD/CAM, 3D Printing, Laser, Bioactive Coatings End User: Dental Clinics, Hospitals, Research Institutions, Labs |
| Companies Covered | Dentsply Sirona, Hiossen, Straumann, MegaGen, Osstem Implant, Nobel Biocare, BioHorizons, Envista, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Implants and Abutment Systems Market Emerging Trajectories
Biomaterial science and regulatory digitization are converging to reshape how implant systems are designed, approved, and deployed across clinical settings. These developments are compressing traditional product lifecycles while elevating precision requirements.
Surface-modified titanium alloys incorporating nanostructured calcium phosphate coatings are hybridizing osseointegration performance with antibacterial properties. High-volume implant chains in the United States are adopting these surfaces for diabetic patient populations where healing complications elevate failure risks. The technology is hybridizing material selection criteria, forcing manufacturers to invest in dual-capability coating infrastructure rather than single-surface portfolios.
The EU Medical Device Regulation's Unique Device Identification mandate is requiring implant manufacturers to serialize every fixture and abutment for traceability. European distributors are restructuring inventory systems to accommodate UDI-compliant labeling, with German dental wholesalers investing in automated scanning infrastructure. Smaller Portuguese and Polish manufacturers lacking ERP integration capabilities are exiting the market rather than absorbing compliance costs.
Patients are demanding aesthetic outcomes that match natural dentition translucency, shifting preference toward zirconia abutments in anterior restoration cases. South Korean cosmetic dental clinics are specifying full-contour zirconia stacks rather than titanium-zirconia hybrids, pressuring laboratories to invest in multi-axis milling centers. This consumption pattern rotation is most visible in Seoul's Gangnam district, where premium clinics compete on Hollywood-smile portfolio differentiation.
Dental Implants and Abutment Systems Market Segmentation
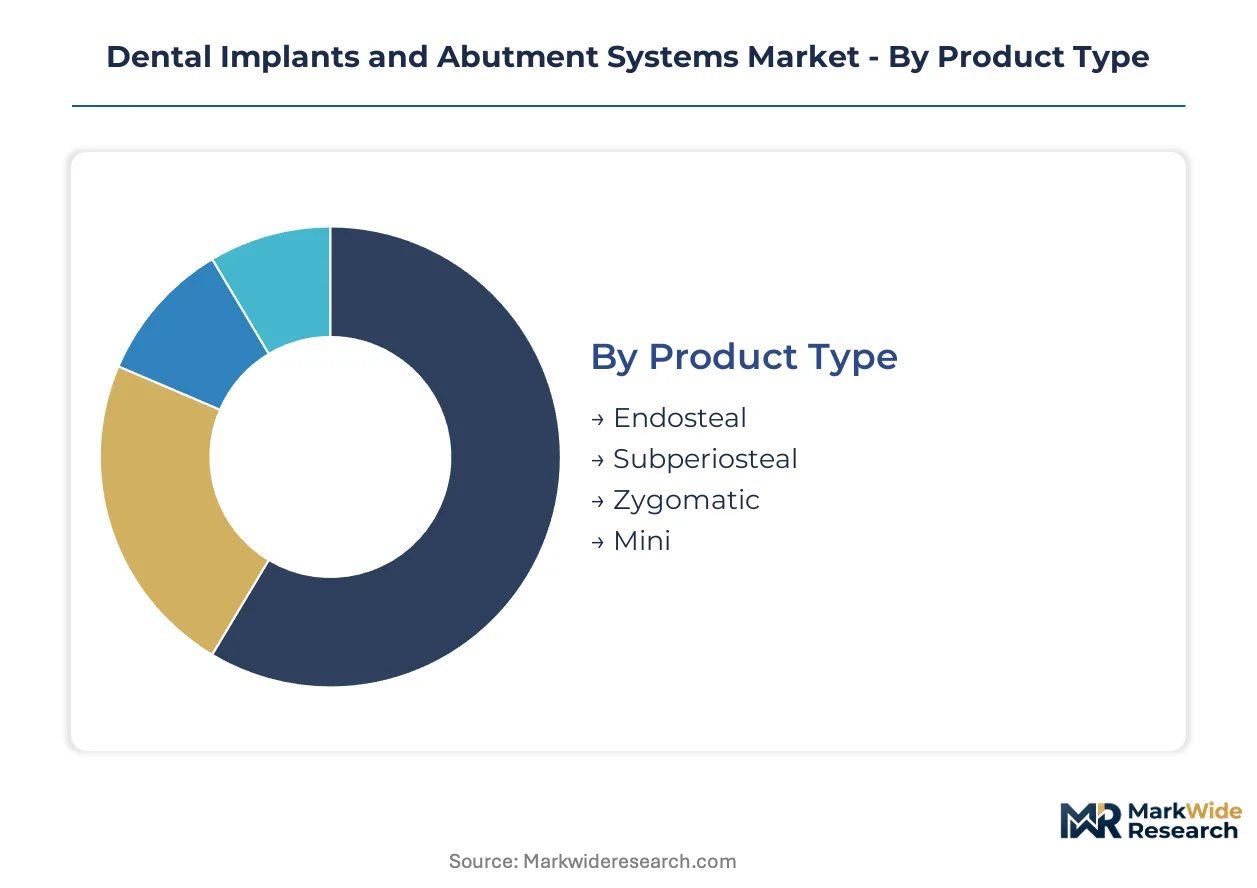
Segmentation in dental implant systems reveals how material science, digital workflows, and care delivery models compete for capital allocation. Manufacturers prioritize segments where reimbursement alignment and clinical throughput converge most favorably.
Product Type:
Mature screw-form designs dominate surgical protocols, while emerging alternatives address anatomical constraints that standard fixtures cannot resolve.
- Endosteal:These root-form fixtures embed directly into jawbone through osteotomy sites, typically ranging 3.0–6.0 mm in diameter. Demand concentrates in high-volume German dental chains where standardized surgical kits enable same-day loading protocols. Titanium plasma-sprayed surfaces accelerate osseointegration timelines from six months to eight weeks.
- Subperiosteal:Custom frameworks sit atop bone beneath periosteum, fabricated from patient CT data through CAD/CAM milling. South Korean MFDS reimbursement expansion for senior populations drives adoption where residual ridge height precludes endosteal placement. Surgical complexity limits deployment to university-affiliated hospitals.
- Zygomatic:Extended fixtures anchor in cheekbone for maxillary atrophy cases. French maxillofacial centers specify these for oncologic reconstruction patients.
- Mini:Narrow-diameter implants stabilize removable prostheses in limited vertical space. Indian tier-2 clinics adopt these for interim solutions ahead of definitive restoration.
Endosteal fixtures retain volume leadership; mini implants hold the steepest expansion curve.
Material:
Cost tiers separate premium biocompatible metals from emerging ceramics and experimental polymers.
- Titanium:Commercially pure grades 1–4 and Ti-6Al-4V ELI alloys constitute the clinical standard. US dental service organizations specify these for posterior load-bearing applications where flexural strength exceeds 900 MPa. Supply concentration in Chinese and Russian sponge smelters creates input cost volatility.
- Zirconia:Yttria-stabilized tetragonal polycrystals offer tooth-colored aesthetics for anterior restorations. Seoul's Gangnam cosmetic clinics demand full-contour zirconia stacks over titanium-zirconia hybrids, pressuring laboratories toward multi-axis milling centers. Brittleness restricts use in molar zones.
- Polymer:PEEK and bioresorbable scaffolds serve temporary space maintenance. Swiss research hospitals trial these for pediatric craniofacial applications.
- Alloy:Cobalt-chrome and gold-platinum combinations persist in select European prosthodontic traditions.
Titanium maintains procedural dominance; zirconia is gaining share fastest in aesthetic-focused markets.
Technology:
Digital integration separates baseline manufacturing methods from precision-enhancing innovations.
- CAD/CAM:Computer-guided milling produces patient-specific abutments with 10-micron tolerances. Straumann's integrated workflow captures premium positioning across German and US practices where digital dentistry compresses treatment timelines. This technology has shifted from premium feature to baseline requirement.
- 3D Printing:Powder-bed fusion and vat photopolymerization fabricate surgical guides and provisional restorations chairside. South Korean implant chains deploy these for immediate loading protocols that reduce appointment counts. Regulatory pathways for printed titanium fixtures remain under development at FDA.
- Laser:Selective laser melting creates porous surface topographies for enhanced bone ingrowth. Osstem Implant incorporates these in select Asian market portfolios.
- Bioactive Coatings:Nanostructured calcium phosphate and antimicrobial silver layers hybridize osseointegration with infection resistance. US high-volume chains adopt these for diabetic patient populations.
CAD/CAM retains volume leadership; 3D printing holds the steepest expansion trajectory.
End User:
Customer type determines purchasing authority and technical support requirements.
- Dental Clinics:Private practices and group dental organizations drive implant procedure volume. Subscription-based equipment leasing in Germany lowers capital barriers for surgical motor and imaging system acquisition. These clinics specify systems with streamlined digital workflow integration.
- Hospitals:Academic medical centers and community hospitals handle complex cases requiring general anesthesia. EU MDR compliance burdens extend procurement cycles for new abutment designs.
- Research Institutions:Universities and biomaterial laboratories validate novel surface modifications and loading protocols. ISO 13485 certification timelines constrain supplier selection.
- Labs:Dental laboratories mill abutments and fabricate prostheses from clinician digital impressions. Direct-to-clinic digital portals threaten traditional distributor relationships.
Dental clinics retain volume leadership; research institutions hold the steepest expansion curve for experimental protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private dental clinics in Germany, South Korea, and the United States concentrate procurement authority for premium implant systems, while hospital-based maxillofacial centers in France and India handle complex reconstructive cases requiring specialized regulatory pathways.
United States
High-volume dental service organizations drive demand for titanium plasma-sprayed surfaces that compress healing timelines. FDA's 510(k) clearance pathway streamlines commercial entry for established predicate devices. Phoenix and Dallas dental chains deploy subscription-based equipment leasing to lower capital barriers for surgical motor acquisition.
Germany
Standardized surgical kits enable same-day loading protocols across high-volume dental chains in Bavaria and North Rhine-Westphalia. EU MDR compliance burdens extend procurement cycles for new abutment designs by 18-24 months. Stuttgart laboratories invest in multi-axis milling centers to meet demand for precision-milled zirconia abutments.
South Korea
MFDS reimbursement expansion for senior populations broadens addressable patient pools beyond private-pay segments. Dense distributor networks in Seoul and Busan anchor Osstem Implant's regional dominance. Gangnam cosmetic clinics specify full-contour zirconia stacks, pressuring laboratories toward advanced CAD/CAM infrastructure.
India
CDSCO streamlined registration pathways enable multinational manufacturers to establish distribution in Lucknow, Jaipur, and Kochi ahead of domestic competitor scale. Mini implants gain traction in tier-2 clinics as interim solutions for limited vertical space. Mumbai and Delhi dental chains adopt immediate loading protocols to capture time-sensitive patient segments.
France
Maxillofacial centers in Paris and Lyon specify zygomatic implants for oncologic reconstruction patients requiring general anesthesia. ANSM enforces biocompatibility and sterility standards that filter market participants by testing capacity. French dental wholesalers invest in automated scanning infrastructure to accommodate EU MDR Unique Device Identification mandates.
Dental Implants and Abutment Systems Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three archetypes: integrated digital workflow providers, manufacturing-scale cost optimizers, and regional distribution specialists. Consolidation pressures favor entities with captive CAD/CAM software ecosystems and direct-to-clinic portal capabilities. Dominant competitive moves include M&A to absorb digital dentistry platforms and backward integration into titanium feedstock processing.
Among Swiss-anchored integrated providers, Straumann exemplifies the premium-tier digital workflow archetype through its CAD/CAM-enabled positioning. Hiossen and Osstem Implant represent the manufacturing-scale and regional-distribution archetypes respectively, with the latter sitting within dense Asian distributor networks. These three entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Hiossen |
| Straumann |
| MegaGen |
| Osstem Implant |
| Nobel Biocare |
| BioHorizons |
| Envista |
| Zimmer Biomet |
| Others |
Supply Flow & Price Mechanics
Shanghai-Rotterdam container freight corridors transmit titanium sponge cost volatility directly into European implant pricing, amplifying the margin squeeze on manufacturers lacking backward integration while enabling premium capture by those with captive smelter relationships.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange titanium sponge benchmarks dominate procurement between German dental chains and their implant suppliers. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification grade and CAD/CAM workflow integration depth. Cost compression in the economy tier is intensifying because South Korean manufacturers are flooding Asian export markets with volume-optimized portfolios. Price sensitivity concentrates among Indian tier-2 clinics selecting mini implants for interim solutions, while German academic medical centers exhibit minimal elasticity for zygomatic systems.
Supply Chain Analysis
Extended 90-day payment terms through supply-chain finance facilities have become standard between Chinese titanium sponge smelters and mid-sized European abutment manufacturers. Production gravity centers on China, Russia, and Japan for surgical-grade titanium feedstock, while precision milling concentrates in Germany and Switzerland. The supply chain rests on titanium plasma-sprayed surface coating inputs and nanostructured calcium phosphate precursors. Single-source vulnerability in Chinese sponge smelters exposes manufacturers to geopolitical disruption. Distribution runs through German dental wholesalers investing in UDI-compliant automated scanning infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
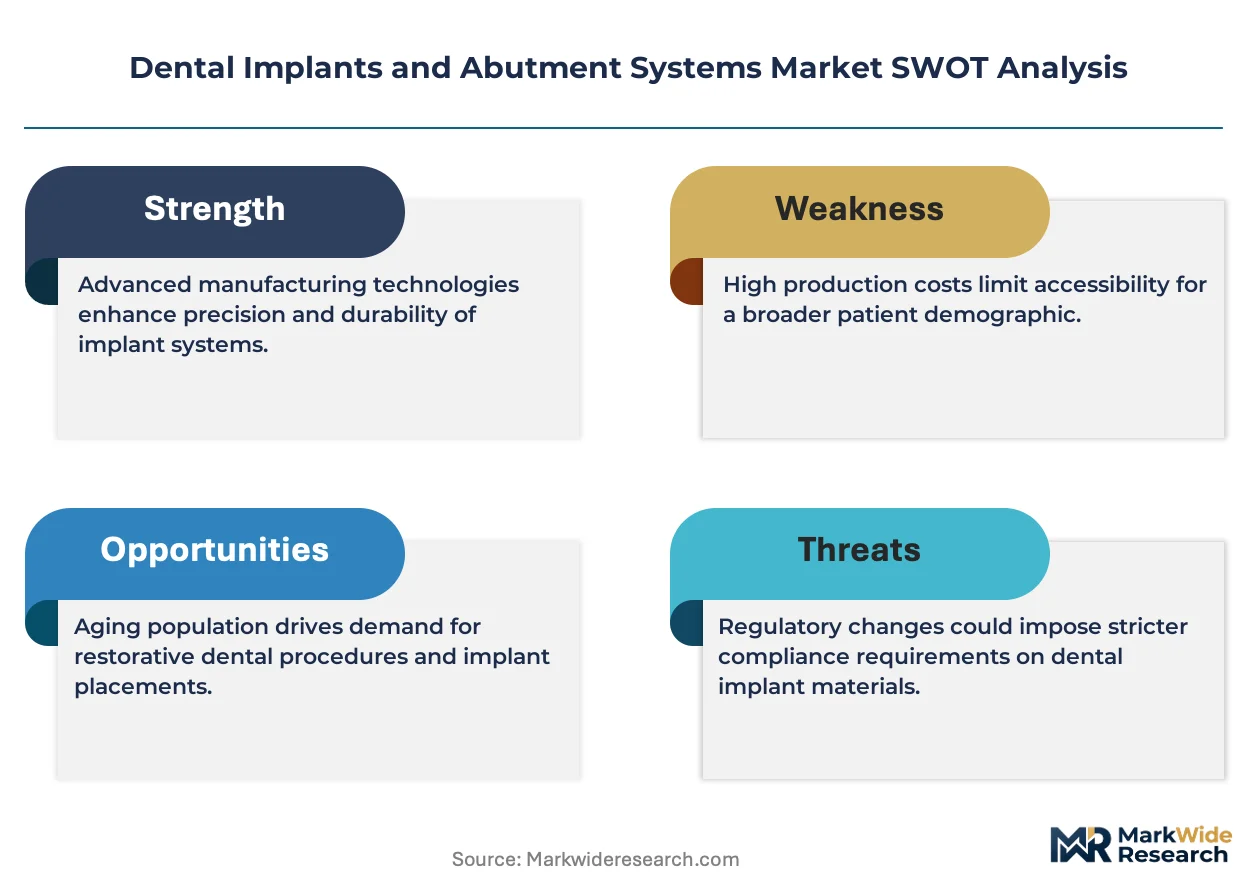
The dental implant market functions as a regulatory-moat industry where FDA 510(k) predicate device eligibility and ISO 13485 certification timelines create switching costs that entrench established players against insurgent competition.
For Market Incumbents: Pre-empt margin erosion by acquiring captive titanium feedstock processing capabilities and embedding CAD/CAM software ecosystems into clinic workflows before South Korean manufacturers replicate the integrated model. The threat of direct-to-clinic digital portals disintermediating traditional distributors demands immediate channel control investment. Backward integration into coating infrastructure for bioactive surfaces represents the critical defensive lever. For New Entrants and Emerging Players: India's underpenetrated tier-2 cities represent the most penetrable entry point for multinational manufacturers establishing distribution ahead of domestic competitor scale. Same-day immediate loading protocols enabled by 3D-printed surgical guides offer a technical wedge for time-sensitive patient segments. A go-to-market angle anchored to CDSCO streamlined registration pathways and localized distributor partnerships accelerates market access. For Investors and Strategic Acquirers: Carve-out targets emerge from European dental laboratories struggling to absorb EU MDR compliance costs and UDI-mandated ERP investments. The five-to-ten year viability window favors entities with captive digital dentistry platforms and direct-to-clinic portal capabilities. Acquisition target archetypes include Portuguese and Polish manufacturers exiting due to compliance burden. The signal to watch is MFDS reimbursement expansion velocity as an indicator of addressable patient pool growth.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Feedstock | Reduces exposure to Chinese and Russian smelter concentration for German manufacturers. |
| CAD/CAM Platform Ecosystem Development | Captures premium positioning across US and German practices compressing treatment timelines. |
| CDSCO Registration Pathway Investment | Enables first-mover distribution establishment in Lucknow, Jaipur, and Kochi ahead of domestic scale. |
| Direct-to-Clinic Digital Portal Launch | Bypasses traditional dental distributors while capturing margin and real-time usage data. |
| Bioactive Coating Infrastructure Buildout | Addresses diabetic patient populations where healing complications elevate failure risks in US chains. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with implant manufacturers, dental clinic procurement managers, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, MFDS reimbursement databases, EU MDR compliance registries, and hospital procurement contract repositories. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Forecast inputs span material type, product category, technology platform, and end-user channel across the projection horizon. CAGRs derived from procedure growth rates, reimbursement expansion trajectories, and digital dentistry adoption curves. Industry-specific inputs include titanium feedstock price indices and ISO 13485 certification pipeline volumes.
Practitioners should monitor MFDS reimbursement code expansion, EU MDR enforcement variance, and titanium sponge supply disruption signals for early indicators of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Endodontics and Orthodontics Market
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
Dental Composite Filling Market
Dental Devices
Global Dental Bone Graft Substitutes Market
Dental Devices
Global Digital Dentistry Market
Dental Devices
Argentina Dental Devices Market
Dental Devices
Digital Facebow Market
Dental Devices
Dental Amalgamators Market
Dental Devices
Single Tooth Implants and Dental Bridges Market
Dental Devices
Dental Handpieces Market
Dental Devices
Dental Hand Tools Market
Dental Devices
Dental Forceps Market
Dental Devices
Dental Suction Systems Market
Dental Devices
Global Dental Lasers Market
Dental Devices
Dental Caries and Endodontic Market
Dental Devices
Dental Carpule Market