
 Penile Prosthesis Market | 2026-2036
Penile Prosthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Penile Prosthesis Market Intelligence
Hospital procurement is tilting toward bundled contract arrangements that lock in device-supply relationships for multi-year terms. Boston Scientific Corporation leverages its cath lab infrastructure to cross-sell urological implants into integrated delivery networks. Coloplast Corp anchors its position through direct-to-surgeon training programs that build loyalty in high-volume implant centers. Zephyr Surgical Implants differentiates via European manufacturing standards that appeal to private-pay clinics seeking CE-marked alternatives.
A penile prosthesis is a surgically implanted medical device constructed from biocompatible silicone polymers and stainless steel or titanium mechanical components, designed to restore erectile function through either hydraulic inflation or manual positioning. The device replaces compromised cavernosal tissue with a controlled rigidity mechanism that permits user-activated sexual intercourse. Inflatable implants command the dominant revenue share due to superior patient satisfaction metrics and lower long-term revision rates compared to malleable alternatives. Peyronie's Disease applications represent the fastest-growing segment as diagnostic awareness expands and deformity-correcting designs gain surgical adoption.
The FDA enforces stringent premarket approval requirements under 21 CFR Part 876 for class III urological prostheses, while the EU Medical Device Regulation mandates notified body conformity assessments that extend market entry timelines. ISO 10993 biocompatibility testing and ASTM F748 material validation protocols form the baseline quality framework that manufacturers must satisfy across jurisdictions. Stakeholders should monitor how reimbursement coding changes for outpatient surgical settings reshape site-of-care decisions and device selection criteria.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while forcing manufacturers to embed training and service into device contracts, fundamentally restructuring how penile prosthesis suppliers compete for access.
Growth Catalysts
- Aging Demographics:Prostate cancer survivorship programs in the United States are expanding referral pathways for post-radical prostatectomy patients, creating sustained procedural demand for inflatable implant systems.
- ISO 10993 Biocompatibility Standards:Harmonized international testing protocols are accelerating regulatory submissions across multiple jurisdictions, reducing time-to-market for silicone polymer-based device iterations.
- Peyronie's Disease Diagnostic Protocols:Urology societies are formalizing deformity assessment guidelines, expanding the addressable patient population for curvature-correcting prosthetic designs.
Market Restraints
- Medical-Grade Silicone Price Volatility:Petrochemical feedstock fluctuations and specialized polymer purification requirements create input cost instability for biocompatible component manufacturers.
- FDA Class III Premarket Approval Pathway:The 21 CFR Part 876 notification process imposes multi-year clinical data requirements that constrain new entrant participation and limit design innovation cycles.
- Malleable Device Substitution Threat:Lower-cost semi-rigid alternatives retain preference in resource-constrained settings and among patients prioritizing mechanical simplicity over concealment.
Strategic Opportunities
- Private-Pay Clinic Expansion:Direct-to-consumer urology centers in Germany and Switzerland are adopting CE-marked devices outside national reimbursement frameworks, creating premium pricing corridors.
- Outpatient Surgical Migration:Ambulatory surgery center credentialing for prosthetic implantation is compressing facility fees and enabling same-day discharge protocols that attract commercially insured patients.
- EU Medical Device Regulation Convergence:Notified body standardization under MDR 2017/745 is reducing fragmentation for manufacturers seeking multi-country European market entry.
Industry Challenges
- Implantation Technique Specialization:The steep learning curve for infrapubic and penoscrotal surgical approaches limits the pool of qualified implanters, creating access bottlenecks in secondary markets.
- Revision Surgery Complexity:Device explantation and replacement procedures require advanced scar tissue management skills that general urologists often lack, concentrating follow-on care in high-volume tertiary centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Penile Prosthesis Market |
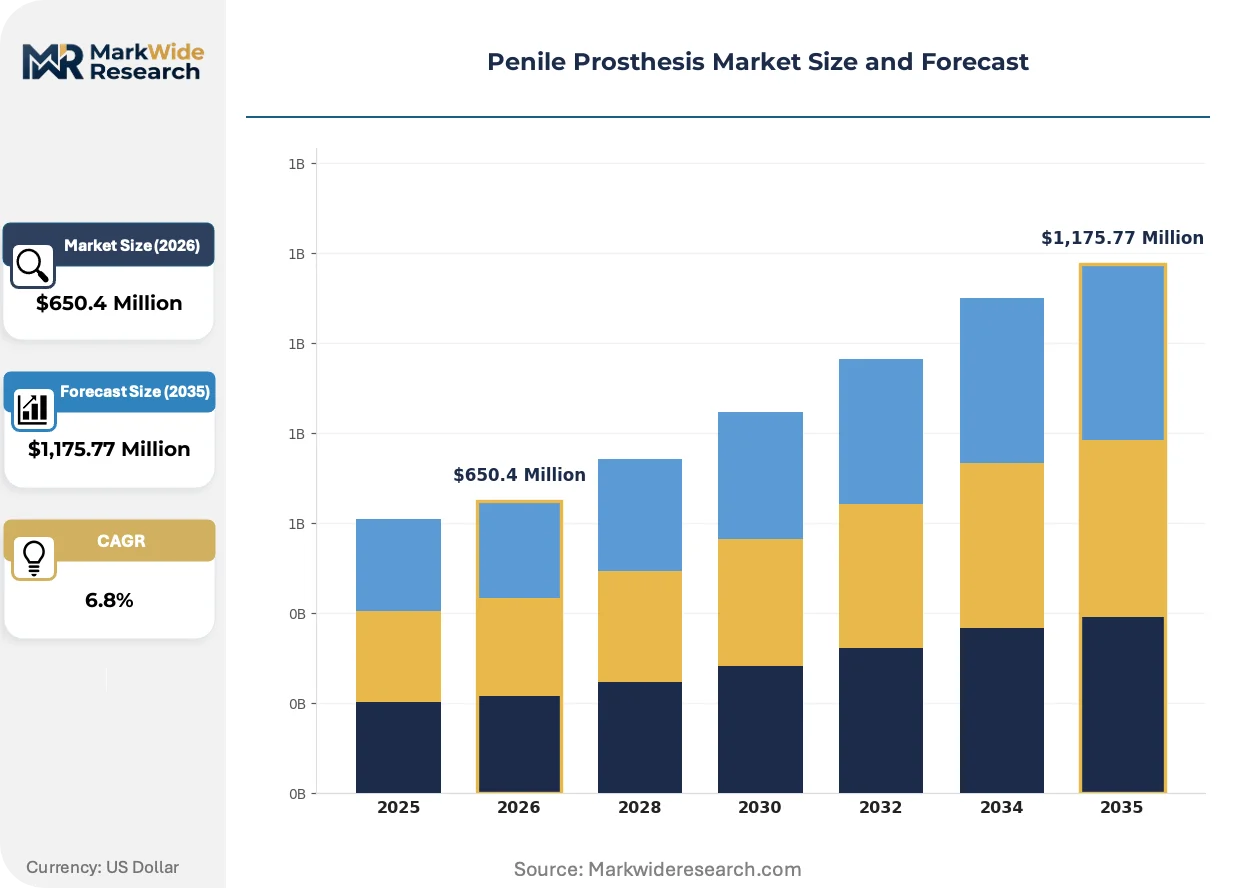
| Market Size in 2026 | $650.4 Million |
| Market Size in 2035 | $1,175.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Implants, Malleable Rods, Semi-Rigid Prostheses, Hydraulic Devices Application: Erectile Dysfunction, Peyronie’s Disease, Penile Trauma, Post-Prostatectomy Reconstruction End User: Urology Clinics, Specialized Hospitals, Ambulatory Surgical Centers, Private Clinics Deployment: Surgical Implantation, Office-Based Procedures, Hospital Operating Rooms, Outpatient Settings |
| Companies Covered | Promedon S.A., SILIMED, Boston Scientific Corporation, G. SURGIWEAR LTD, Advin Health Care, Coloplast Corp, Rigicon, Inc, Corza Medical, Zephyr Surgical Implants, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Penile Prosthesis Market Strategic Shifts & Innovations
Device architecture is converging with digital health infrastructure while regulatory frameworks force earlier clinical validation, reshaping how manufacturers prioritize R&D investment and surgeon education.
Antibiotic-impregnated silicone elastomer technology is hybridizing with traditional prosthetic construction to reduce post-implantation infection rates. High-volume implant centers in the United States are adopting these surfaces as standard of care, compressing demand for non-coated alternatives and forcing manufacturers to absorb material cost premiums or lose preferred vendor status.
EU Medical Device Regulation notified body assessments are extending technical documentation review timelines for class III urological prostheses. Manufacturers are responding by front-loading clinical evidence generation and establishing dedicated European regulatory affairs functions, with mid-cap suppliers facing disproportionate compliance cost burdens relative to revenue scale.
Site-of-care decisions are migrating toward ambulatory settings as payers compress inpatient reimbursement differentials. Integrated delivery networks in the United States are unbundling device procurement from facility fees, enabling direct manufacturer-to-physician contracting that bypasses traditional hospital supply chain intermediaries.
Penile Prosthesis Market Segmentation
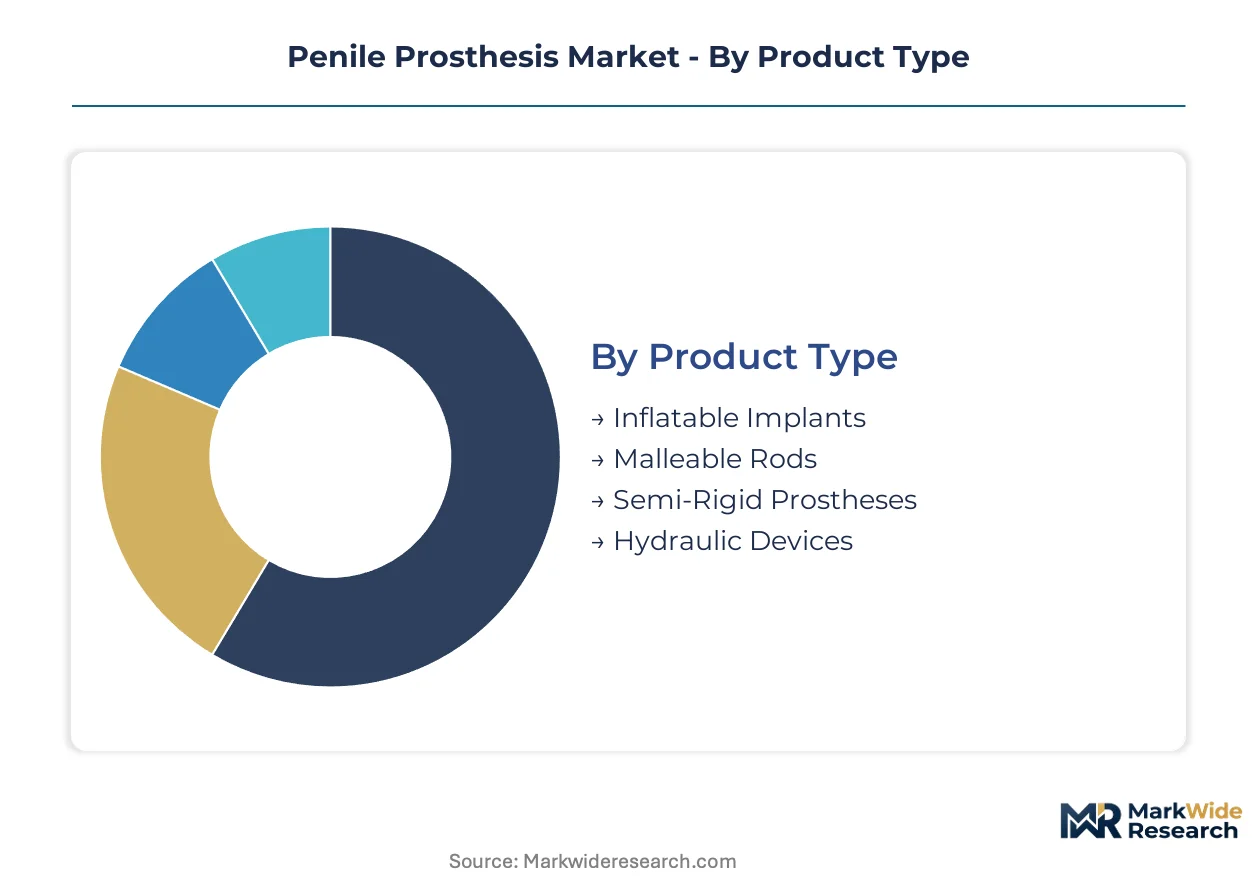
Segmentation in the penile prosthesis market reveals how clinical requirements, reimbursement pathways, and surgical expertise stratify demand across device architectures and care settings. Manufacturers configure product portfolios and commercial strategies around these divisions to capture volume in high-yield implant centers while managing regulatory complexity across deployment modes.
Product Type:
Mature hydraulic systems dominate revenue concentration while mechanical alternatives serve cost-sensitive niches and specific anatomical constraints.
- Inflatable Implants:Three-component hydraulic systems utilizing silicone polymer reservoirs and pump mechanisms deliver user-controlled rigidity with flaccid concealment. Demand concentrates in United States tertiary urology centers where prostate cancer survivorship programs generate post-radical prostatectomy referrals requiring functional restoration.
- Malleable Rods:Semi-rigid silicone-silver wire constructs maintain permanent positional rigidity through manual bending. German and Swiss private-pay clinics favor these devices for mechanical simplicity and lower explantation risk in older patient cohorts prioritizing reliability over cosmetic outcomes.
- Semi-Rigid Prostheses:Positional memory alloys and coated rod designs bridge the gap between malleable simplicity and inflatable functionality.
- Hydraulic Devices:Two-component fluid transfer systems reduce surgical complexity for specific anatomical presentations.
Inflatable implants handle the majority of throughput; Peyronie's-correcting hydraulic variants are expanding most quickly on share as diagnostic protocols formalize deformity indications.
Application:
Volume distribution tracks the prevalence of organic erectile impairment and the expansion of reconstructive urology subspecialization.
- Erectile Dysfunction:Organic vasculogenic failure from diabetes, cardiovascular disease, and iatrogenic nerve injury drives the foundational patient population. United States integrated delivery networks prioritize inflatable implantation for this indication within bundled payment frameworks.
- Peyronie's Disease:Fibrotic plaque-induced curvature and hourglass deformities create mechanical impairment resistant to pharmacotherapy. European urology societies are standardizing measurement protocols that expand surgical candidacy beyond severe angulation cases.
- Penile Trauma:Fracture, avulsion, and combat-related injuries requiring structural reconstruction.
- Post-Prostatectomy Reconstruction:Nerve-sparing failure after radical prostatectomy represents a concentrated high-volume indication.
Erectile dysfunction claims the largest procedure base; Peyronie's Disease is climbing the fastest as awareness campaigns and curvature-assessment training proliferate.
End User:
Site-of-care economics and surgeon credentialing density determine where manufacturers deploy clinical specialists and inventory.
- Urology Clinics:Dedicated men's health centers with high annual implant volumes leverage direct manufacturer relationships for device procurement and surgeon training. These settings capture commercially insured patients seeking discrete scheduling outside hospital systems.
- Specialized Hospitals:Academic medical centers with reconstructive urology fellowships manage complex revision cases and device infections requiring explantation expertise.
- Ambulatory Surgical Centers:Same-day discharge protocols attract payers compressing facility fee differentials.
- Private Clinics:Direct-to-consumer models outside national reimbursement frameworks operate in Germany, Switzerland, and select Middle Eastern markets.
Urology clinics process the dominant share of elective implantations; ambulatory surgical centers are gaining share fastest as payer site-of-care policies tighten.
Deployment:
Regulatory classification and reimbursement coding stratify where specific device iterations enter clinical use.
- Surgical Implantation:Infrapubic and penoscrotal approaches in sterile operating environments remain the standard for three-component inflatable systems. FDA 21 CFR Part 876 compliance and ISO 10993 biocompatibility validation anchor this deployment mode.
- Hospital Operating Rooms:Inpatient and short-stay surgical suites capture complex cases requiring concurrent procedures or extended monitoring.
- Office-Based Procedures:Malleable rod insertion under local anesthesia serves selected low-risk patients.
- Outpatient Settings:Ambulatory surgery center credentialing enables same-day discharge for standard inflatable implantation.
Surgical implantation in hospital operating rooms handles the majority of complex cases; outpatient settings are expanding most rapidly as anesthesia protocols and device reliability improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement frameworks and prostate cancer survivorship programs are reshaping procedural volumes across major markets. The United States, Germany, Japan, Brazil, and Australia concentrate the majority of implant activity, with regulatory pathways and private-pay dynamics creating distinct commercial environments in each jurisdiction.
United States
Medicare coverage determinations and commercial payer bundled payment models sustain elevated procedural rates for post-radical prostatectomy patients. The FDA's 21 CFR Part 876 premarket approval pathway governs device entry, with 510(k) clearance timelines averaging 180 days for predicate-based submissions. High-volume implant centers cluster in metropolitan areas with academic urology programs, particularly Houston, Cleveland, and Los Angeles, where surgeon credentialing density supports complex revision caseloads.
Germany
Statutory health insurance reimbursement for inflatable prostheses drives steady demand among aging males with vasculogenic erectile dysfunction. The EU Medical Device Regulation 2017/745 mandates notified body conformity assessments through BfArM-recognized entities, extending technical documentation review periods. Private-pay urology clinics in Munich and Hamburg are expanding direct-to-consumer services outside national reimbursement frameworks, capturing premium pricing for expedited scheduling.
Japan
Prostate cancer screening expansion and nerve-sparing surgical technique adoption are enlarging the post-operative patient pool eligible for prosthetic intervention. The PMDA's class IV medical device approval process requires local clinical bridging studies for foreign-manufactured implants. Tokyo and Osaka academic medical centers concentrate fellowship-trained implanters, with Kanto region hospitals processing the majority of curvature-correcting procedures for Peyronie's Disease.
Brazil
Private health plan coverage for urological prostheses is expanding as middle-class enrollment in supplementary insurance grows. ANVISA's registration requirements for class IV implants mandate in-country quality system audits and Portuguese-language labeling compliance. São Paulo and Rio de Janeiro host the principal reconstructive urology training programs, with southeastern state hospitals managing the bulk of trauma-related implantations.
Australia
Medicare Benefits Schedule item numbers for penile prosthesis implantation ensure public hospital access, though wait times push commercially insured patients toward private facilities. The TGA's medical device inclusion process aligns with EU MDR technical documentation standards, facilitating parallel submissions for manufacturers. Sydney and Melbourne tertiary centers are credentialing ambulatory surgery centers for same-day discharge protocols, compressing facility fee structures.
Penile Prosthesis Market Key Industry Players
On the supply side, the industry is consolidating around integrated medical device conglomerates with established urology portfolios, while specialized prosthesis manufacturers retain defensible positions in premium segments and regional markets. Three strategic archetypes dominate: diversified multinationals leveraging cath lab and endourology infrastructure for cross-selling; dedicated urological device specialists competing on surgeon training intensity and implant center loyalty; and regional fabricators serving price-sensitive markets with CE-marked or locally registered alternatives. Competitive dynamics center on hospital procurement consolidation demanding embedded service contracts, and direct-to-physician contracting that bypasses traditional supply chain intermediaries.
Among diversified device manufacturers, Boston Scientific Corporation and Coloplast Corp exemplify scale-driven archetypes with integrated delivery network penetration, while Zephyr Surgical Implants occupies a position within the European specialist tier. Promedon S.A. anchors the Latin American regional fabricator segment. These companies represent the spectrum of strategic positioning, from conglomerate-backed urology divisions to focused prosthesis specialists and emerging market suppliers.
| Leading Market Players |
|---|
| Promedon S.A. |
| SILIMED |
| Boston Scientific Corporation |
| G. SURGIWEAR LTD |
| Advin Health Care |
| Coloplast Corp |
| Rigicon, Inc |
| Corza Medical |
| Zephyr Surgical Implants |
| Others |
Cost & Logistics Intelligence
Transatlantic air freight corridors from Frankfurt and Amsterdam carry medical-grade silicone polymers and titanium components to device fabricators in the United States, with fuel surcharge volatility compressing margins for European-sourced inputs while amplifying price spreads between FDA-grade and CE-marked product tiers. This logistics cost structure reinforces supply concentration among manufacturers with captive polymer purification capabilities, enabling premium pricing for antibiotic-impregnated surfaces that hospital procurement committees now specify as standard.
Pricing Analysis
Certification level creates the primary spread between device tiers, with FDA 510(k)-cleared three-component inflatable systems commanding premium positioning against CE-marked alternatives in private-pay European clinics. Three-tier pricing structure across premium, standard, and economy levels reflects biocompatibility testing depth, with ISO 10993 full-panel validation separating top-tier offerings from abbreviated-protocol competitors. Cost compression in the malleable rod segment is intensifying because German statutory insurers have tightened reimbursement ceilings for semi-rigid devices. Ambulatory surgery centers exhibit the highest price sensitivity due to unbundled procurement models, while academic medical centers prioritize infection-rate metrics over unit cost.
Supply Chain Analysis
Export-control restrictions on medical-grade silicone precursor chemicals limit flows from specialized German and Japanese chemical manufacturers to device fabricators outside approved trade jurisdictions. Supply concentrates in the United States, Germany, and Switzerland for final device assembly, with raw material dependencies on Malaysian petrochemical feedstocks and Australian titanium sponge. Single-source vulnerability pervades the specialized polymer purification stage, where two European suppliers dominate pharmaceutical-grade silicone elastomer production. Distribution runs through integrated delivery networks in the United States and direct-to-surgeon channels in European private clinics, bypassing traditional hospital supply chain intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The penile prosthesis market sits in early-cycle expansion as Peyronie's Disease diagnostic protocols formalize curvature-assessment guidelines and expand surgical candidacy beyond historically severe cases. This awareness tailwind compounds with prostate cancer survivorship program growth to enlarge the addressable patient population.
For Market Incumbents: Entrench position through backward integration into medical-grade silicone polymer purification, securing captive supply against petrochemical feedstock volatility while absorbing material cost premiums that non-integrated competitors cannot match. Deepen implant center loyalty by embedding clinical specialists within high-volume urology clinics, creating switching costs that rival device contracts alone cannot replicate. Prioritize antibiotic-impregnated surface technology investment as hospital procurement committees increasingly specify infection-rate performance in vendor selection criteria.
For New Entrants and Emerging Players: Build out ambulatory surgery center credentialing capabilities, capturing procedural volume migration as payers compress inpatient reimbursement differentials and same-day discharge protocols gain adoption. Target Peyronie's Disease-correcting hydraulic variants, the fastest-growing application segment where diagnostic awareness expansion outpaces established manufacturer capacity. Pursue direct-to-consumer urology clinic partnerships in Germany and Switzerland, where private-pay models outside national reimbursement frameworks enable premium pricing corridors.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates seeking to divest non-core urology divisions amid portfolio rationalization pressures. Long-term viability hinges on regulatory compliance infrastructure and surgeon training ecosystem depth rather than device innovation alone. Monitor FDA premarket approval pathway timeline shifts as the inflection indicator, with accelerated 510(k) clearance processes signaling favorable conditions for mid-cap supplier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body standardization reduces fragmentation for multi-country European market entry. |
| Hospital System Partnership | Bundled contract arrangements lock in device-supply relationships for multi-year procurement terms. |
| Reimbursement Strategy | Coding changes for outpatient surgical settings reshape site-of-care decisions and device selection. |
| Software Companion Development | Digital health infrastructure integration enables remote device monitoring and patient outcome tracking. |
| FDA Submission | Premarket notification pathway for class III devices shapes manufacturer compliance investment priorities. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract records. Primary interviews with reconstructive urologists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers informed procedural volume assumptions and site-of-care migration patterns. Secondary validation drew from CMS Medicare reimbursement data, commercial payer bundled payment disclosures, and ISO 10993 biocompatibility testing registries. Bottom-up implant procedure estimates triangulated against top-down manufacturer revenue segmentation across product tiers.
Forecast inputs include prostate cancer incidence trajectories, nerve-sparing surgical technique adoption curves, and ambulatory surgery center credentialing expansion rates across the analysis window. Segmentation modeling incorporates device architecture, application indication, end-user setting, and deployment mode dimensions. CAGRs derive from procedural volume projections adjusted for revision surgery rates and device longevity assumptions. Peyronie's Disease diagnostic protocol formalization and private-pay clinic expansion in German-speaking markets constitute industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified medical device conglomerates into direct-to-physician contracting would shift outcomes beyond modeled parameters. Material shifts in FDA premarket approval pathway timelines or EU MDR notified body capacity constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
Pen Needles Market
Medical Devices
Global Deep Brain Stimulation Devices Market
Medical Devices
Nanotechnology in Medical Devices Market
Medical Devices
Ultrasound Stimulator Market
Medical Devices
Lumbar Disc Replacement Device Market
Medical Devices
Submucosal Injections Market
Medical Devices
Interphalangeal Fusion Market
Medical Devices
Light Therapy Market
Medical Devices
Medical Device Trays Market
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
US Mechanical Ventilator Market
Medical Devices
Medical LED Headlight Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
Global Digital Dentistry Devices Market
Medical Devices
Global Ventilators Market