
 Chile Dental Market | 2026-2036
Chile Dental Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Dental Market Insights
Market Context
Dental equipment distribution through regional dealer networks is reshaping how manufacturers reach Chile's fragmented clinic base. Straumann Holding AG leverages its implant-focused portfolio to sustain premium positioning across Santiago's specialist practices. Dentsply Sirona competes through broad restorative and imaging portfolios that anchor its presence in multi-chair corporate chains. Danaher Corporation differentiates via KaVo's integrated workflow systems that dominate high-throughput hospital dental departments.
Technical Definition and Structural Segments
Dental encompasses the diagnosis, prevention, and treatment of oral conditions using instruments, biomaterials, and digital systems operating under ISO 13485 quality management standards with biocompatibility requirements for intraoral contact. Restorative products occupy the largest revenue pool due to recurring consumable demand from resin composites and cement protocols, while CAD/CAM Systems generate the fastest expansion as chairside milling reduces laboratory turnaround from weeks to hours. Digital Imaging sustains stable replacement cycles tied to sensor upgrade timelines across Chile's clinic network.
Regulatory Framework
Chile's Instituto de Salud Pública registers dental devices under pharmaceutical-equivalent pathways, while the Ministry of Health sets FONASA reimbursement ceilings that directly shape product selection in public-affiliated clinics. ISP's vigilance over ISO 13485 compliance forces importers to maintain local technical documentation and adverse-event reporting infrastructure. Stakeholders must monitor whether proposed updates to Chile's medical device law will align with Mercosur technical regulations or maintain independent conformity assessment requirements.
Market Dynamics
FONASA reimbursement schedule revisions are compressing product selection criteria across Chile's public-affiliated clinic network, forcing manufacturers to recalibrate portfolio positioning between premium private channels and volume-driven subsidized segments.
Growth Catalysts
- CAD/CAM chairside milling:Santiago's premium clinic cluster deploys same-day crown fabrication to capture patient preference for reduced appointment cycles. This technology compresses laboratory outsourcing dependencies.
- FONASA benefit expansion:Chile's Ministry of Health widened subsidized care access for lower-income populations, expanding addressable patient volume across Valparaíso and Santiago Metropolitan Region public-affiliated facilities.
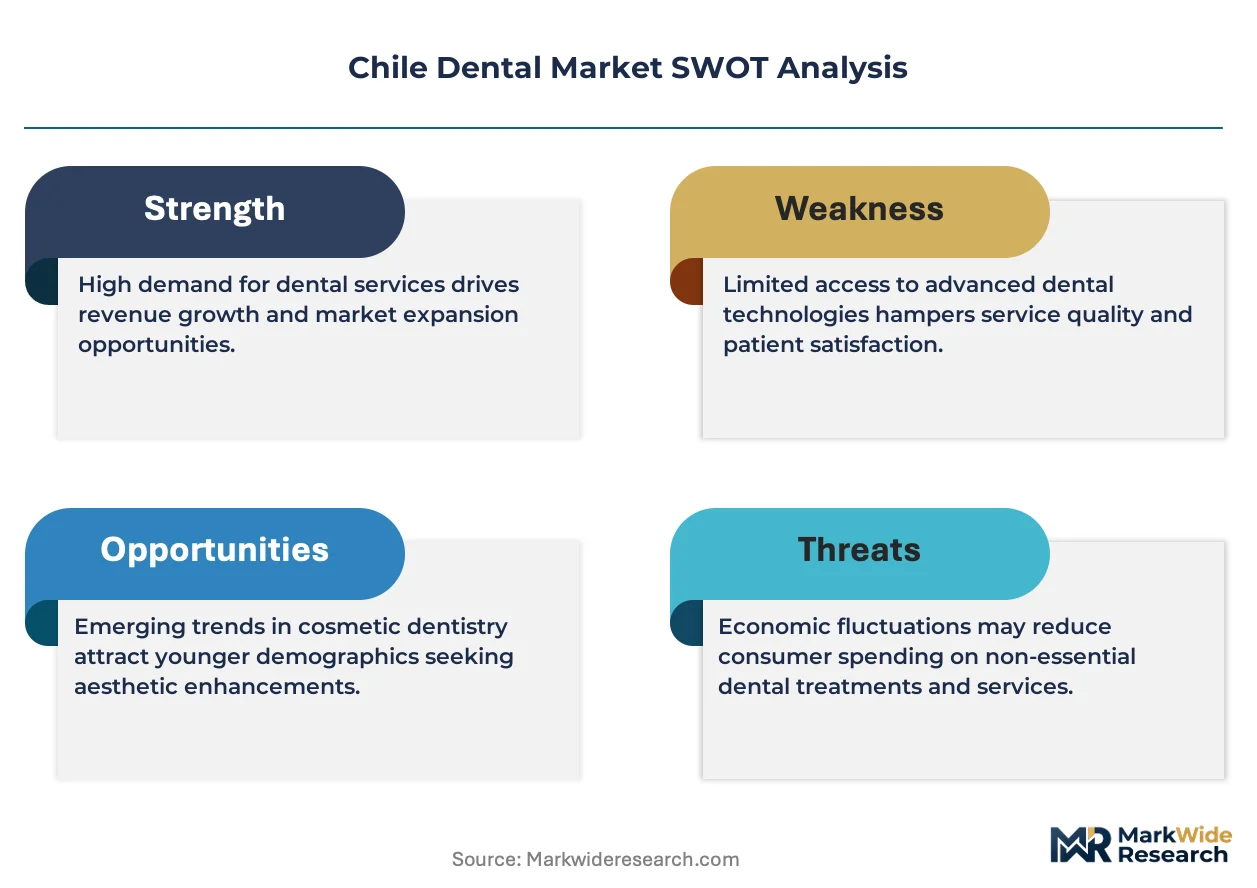
- Implantology demand concentration:Cosmetic and reconstructive procedures concentrate within Santiago's specialist practices, pulling premium biomaterial consumption toward metropolitan corridor clinics.
Market Restraints
- Import dependency for precision equipment:Chile's domestic manufacturing base lacks optical sensor and milling spindle production, exposing clinic capital expenditure timelines to international supply chain variability.
- FONASA reimbursement ceilings:The Ministry of Health's fixed payment schedules constrain product selection in public-affiliated clinics, filtering out premium-priced restorative materials regardless of clinical performance advantages.
- Specialist workforce geographic concentration:Implantology and advanced prosthodontics expertise clusters in Santiago and Valparaíso, limiting service penetration into Biobío and Araucanía regions.
Strategic Opportunities
- Regional clinic network expansion:Concepción and La Serena present underpenetrated demand for multi-chair corporate dental chains capable of standardizing equipment procurement across provincial markets.
- Digital workflow integration:Convergence of intraoral scanning with cloud-based laboratory communication platforms enables remote case management for dispersed clinic networks.
- Biocompatibility certification premium:ISP's ISO 13485 enforcement creates differentiation pathway for manufacturers maintaining superior adverse-event documentation and local technical file infrastructure.
Industry Challenges
- Prosthodontics technician shortage:Chile's vocational training pipeline produces insufficient CAD/CAM operators and dental ceramists to match chairside digital expansion.
- Legacy equipment integration friction:Santiago's established clinics face capital inefficiency when retrofitting digital imaging systems into pre-2015 operatory configurations.
- ISP registration timeline variability:The Instituto de Salud Pública's pharmaceutical-equivalent device pathway generates unpredictable market entry delays for novel biomaterial introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Dental Market |
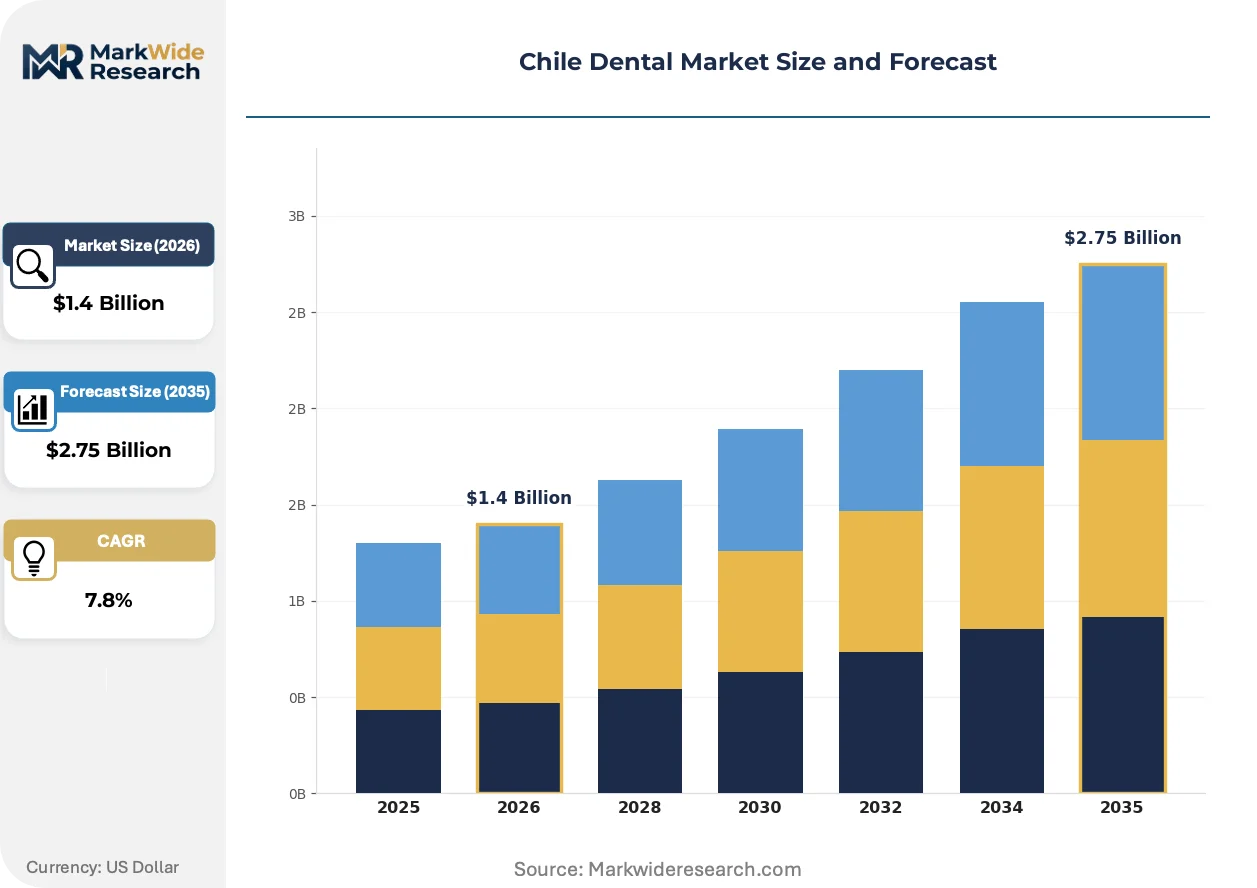
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preventive Care, Restorative Products, Orthodontic Devices, Surgical Instruments End User: Dental Clinics, Hospitals, Research Laboratories, Pharmacies Service Type: General Dentistry, Cosmetic Treatments, Emergency Services, Periodontics Technology: Digital Imaging, CAD/CAM Systems, 3D Printing, Laser Dentistry |
| Companies Covered | Straumann Holding AG, A-dec Inc., Planmeca Oy, Dentium Co. Ltd, Ivoclar Vivadent AG, Dentsply Sirona, Carestream Health Inc., DEXIS, Danaher Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Dental Market Trends and Innovations
Digital capture and fabrication systems are compressing traditional laboratory intermediation, while regulatory pressure on quality documentation reshapes competitive differentiation among equipment suppliers serving Chile's bifurcated public-private market structure.
Intraoral scanning systems are digitizing impression capture workflows across Santiago's corporate clinic chains, replacing polyvinyl siloxane and alginate protocols with optical triangulation. Mid-sized practices in the Metropolitan Region adopt these systems at accelerating replacement cycles as hardware costs decline and software interoperability improves. This digitization is eliminating physical model shipping and reducing case turnaround from days to hours.
Chile's Instituto de Salud Pública maintains pharmaceutical-equivalent registration pathways for dental devices, requiring importers to sustain local technical documentation and adverse-event reporting infrastructure comparable to pharmaceutical standards. Manufacturers must maintain ISO 13485 quality management certification with biocompatibility testing documentation for all intraoral-contact materials. High-throughput hospital dental departments face the strictest documentation scrutiny, filtering supplier selection toward established multinationals with dedicated regulatory affairs capacity.
Clinic procurement patterns favor bundled equipment-and-service contracts over discrete capital purchases, particularly among Santiago's expanding multi-location corporate operators. Traditional regional dealer networks face displacement by manufacturer-direct service organizations capable of delivering integrated workflow training and maintenance protocols. This shift concentrates most visibly within the Santiago Metropolitan Region's premium clinic cluster, where standardization across chair count drives volume-based supplier negotiations.
Chile Dental Market Segmentation
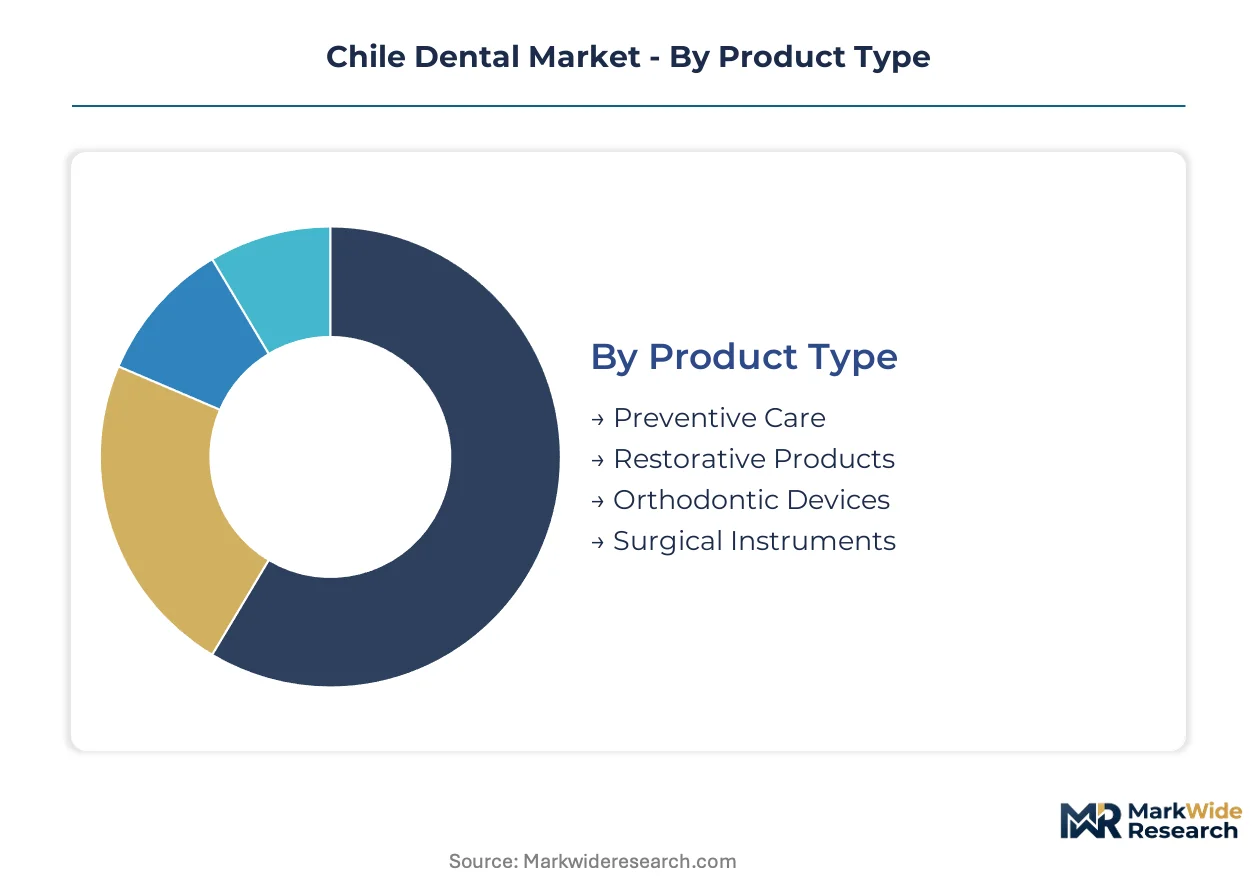
Chile's dental market segments reflect the bifurcation between high-volume subsidized care under FONASA and premium private services concentrated in Santiago's metropolitan corridor. Understanding these divisions illuminates where equipment procurement concentrates and which technologies penetrate each channel.
Product Type:
Use cases span from routine prophylaxis in public clinics to complex implantology in specialist practices, with product selection tightly coupled to reimbursement ceilings and patient payment capacity.
- Restorative Products:Resin composites, dental cements, and bonding agents constitute the largest revenue pool due to recurring consumable demand from both FONASA-affiliated and private channels. Santiago's corporate clinic chains drive volume through standardized procurement protocols that favor established biomaterial brands with ISP registration history.
- Preventive Care:Sealants, fluoride treatments, and prophylaxis pastes dominate patient touchpoints in Valparaíso's public-affiliated facilities where FONASA coverage expansion has widened access. Demand concentrates in bulk packaging formats suited to high-throughput community health centers.
- Orthodontic Devices:Clear aligners and fixed bracket systems serve Santiago's cosmetic-focused patient base with significant out-of-pocket payment capacity.
- Surgical Instruments:Implant placement kits and periodontal surgical tools cluster in specialist practices across the Metropolitan Region.
Established volume favors Restorative Products; emerging adoption favors Preventive Care.
End User:
Customer type determines capital expenditure cycles, with multi-chair corporate operators driving standardization and individual practitioners prioritizing flexibility.
- Dental Clinics:Santiago's expanding corporate chains and independent practices generate divergent procurement patterns—standardized bundled contracts versus discrete equipment purchases. FONASA reimbursement ceilings filter product selection in public-affiliated clinics while premium private channels absorb advanced imaging and milling systems.
- Hospitals:High-throughput dental departments in Santiago's public hospital network face strictest ISP documentation scrutiny, concentrating supplier selection toward multinationals with dedicated regulatory affairs capacity and ISO 13485 certification maintenance.
- Research Laboratories:University-affiliated facilities in Valparaíso and Santiago support biomaterial validation and CAD/CAM workflow development.
- Pharmacies:Retail channels distribute over-the-counter preventive products and basic oral care consumables.
Procurement scale concentrates in Dental Clinics; regulatory complexity peaks in Hospitals.
Service Type:
Margin structure varies sharply across service categories, with cosmetic procedures commanding premium pricing and emergency services operating under compressed reimbursement.
- Cosmetic Treatments:Teeth whitening, veneers, and aesthetic restorations concentrate within Santiago's premium clinic cluster where patient willingness to pay out-of-pocket supports investment in chairside digital systems. These services generate the steepest expansion trajectory as metropolitan disposable incomes rise.
- General Dentistry:Routine examinations, cleanings, and basic restorations constitute the highest patient volume across FONASA-subsidized and private channels alike. Valparaíso's expanding clinic base captures this demand through standardized service protocols.
- Emergency Services:Trauma and acute pain management operate across hospital dental departments and urgent-care clinic networks.
- Periodontics:Gum disease treatment and maintenance protocols serve an aging patient demographic in Santiago and Concepción.
Margin concentration favors Cosmetic Treatments; patient volume favors General Dentistry.
Technology:
Capital intensity and workflow integration requirements segment adoption by practice size and metropolitan location.
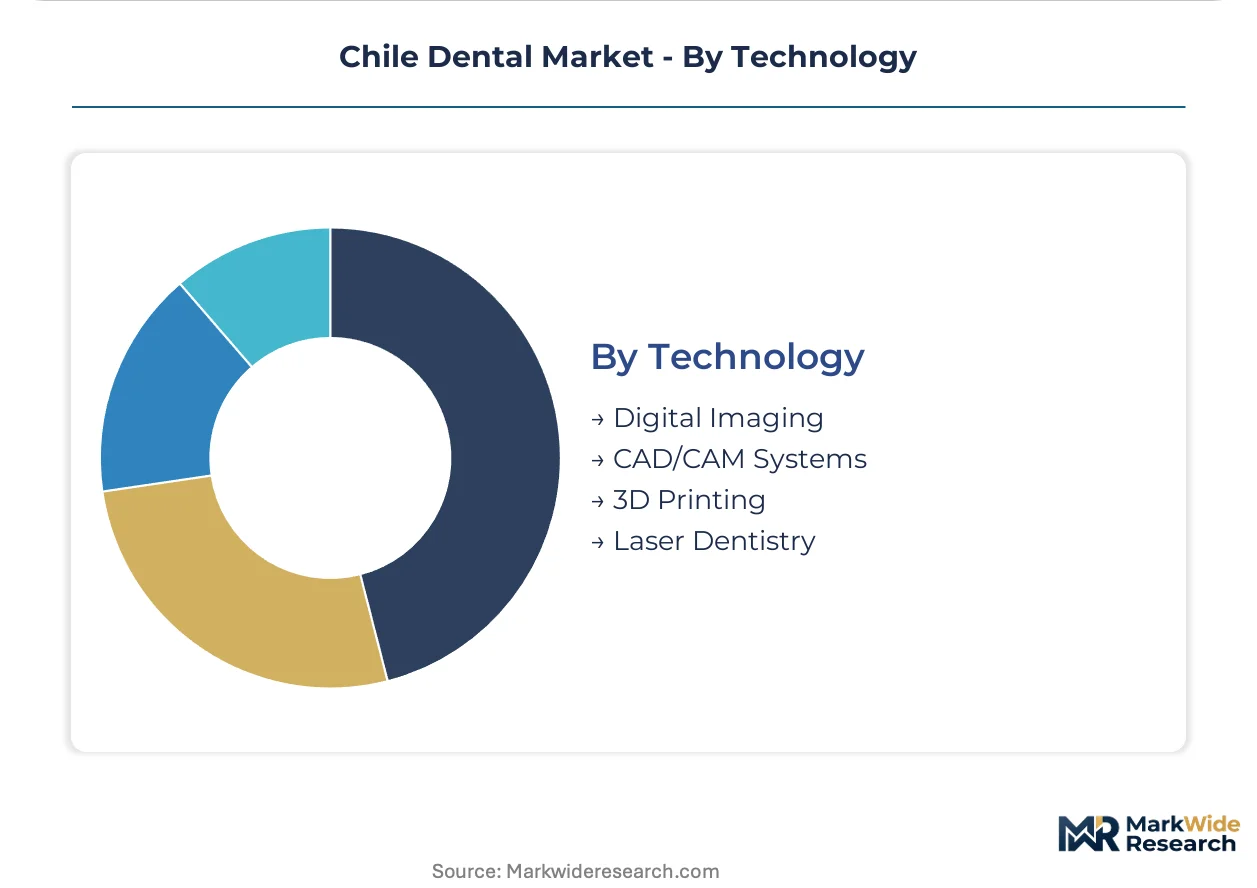
- CAD/CAM Systems:Chairside milling units and intraoral scanning platforms compress laboratory turnaround from weeks to hours, eliminating physical model shipping. Santiago's corporate clinic chains deploy these systems at accelerating replacement cycles as hardware costs decline and software interoperability improves.
- Digital Imaging:Intraoral sensors and panoramic units sustain stable replacement cycles tied to upgrade timelines across Chile's clinic network, with FONASA-affiliated facilities operating on extended depreciation schedules.
- 3D Printing:Resin-based surgical guides and dental models gain traction in specialist practices with laboratory integration.
- Laser Dentistry:Soft-tissue and hard-tissue laser systems remain concentrated in premium private channels due to capital requirements and specialist training needs.
Adoption velocity favors CAD/CAM Systems; replacement stability favors Digital Imaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Valparaíso-Santiago corridor's Pacific port infrastructure underwrites Chile's dental supply chain efficiency, anchoring import flows for precision equipment and biomaterials that serve the metropolitan clinic cluster.
Santiago Metropolitan Region
Cosmetic dentistry and implantology concentrate patient payment capacity in Santiago's premium clinic cluster. FONASA reimbursement ceilings shape product selection in public-affiliated facilities throughout the capital. Corporate dental chains expand multi-chair capacity across Las Condes and Providencia to capture rising metropolitan demand.
Valparaíso Region
Public-affiliated clinics in Valparaíso capture expanded FONASA benefit access for lower-income populations. The Ministry of Health's subsidized care expansion widens addressable patient volume across community health centers. Specialist practices cluster in Viña del Mar to serve coastal metropolitan demand for aesthetic procedures.
Biobío Region
Concepción presents underpenetrated demand for standardized multi-chair corporate dental chains. Regional workforce gaps in implantology and advanced prosthodontics limit service penetration beyond basic restorative care. The national pharmaceutical regulator's ISO 13485 enforcement filters supplier selection toward established multinationals with local technical documentation.
Araucanía Region
Temuco and surrounding municipalities operate on extended equipment depreciation cycles tied to FONASA-affiliated facility budgets. Geographic distance from specialist training centers constrains advanced procedure availability. Rural clinic networks prioritize preventive care consumables over capital-intensive digital imaging systems.
Coquimbo Region
La Serena's growing middle-income population supports private clinic expansion for cosmetic and general dentistry services. Regional dealer networks maintain equipment distribution reach into provincial markets lacking direct manufacturer presence. Cloud-based laboratory communication platforms enable remote case management for dispersed practices.
Chile Dental Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. Chile's dental market structures around three archetypes: multinational conglomerates with broad restorative and imaging portfolios, implant-focused specialists with premium biomaterial positioning, and integrated workflow system providers targeting high-throughput hospital departments. Competitive moves concentrate on manufacturer-direct service organizations displacing traditional regional dealers, and bundled equipment-and-service contracts capturing multi-location corporate operators.
Among the implant-focused specialists, Straumann Holding AG exemplifies premium positioning through concentrated biomaterial portfolios. Dentsply Sirona occupies a position among the multinational conglomerates with expansive restorative and imaging coverage. Danaher Corporation anchors the integrated workflow tier through KaVo's system offerings for hospital dental departments.
| Leading Market Players |
|---|
| Straumann Holding AG |
| A-dec Inc. |
| Planmeca Oy |
| Dentium Co. Ltd |
| Ivoclar Vivadent AG |
| Dentsply Sirona |
| Carestream Health Inc. |
| DEXIS |
| Danaher Corporation |
| Others |
Pricing and Supply Chain Analysis
German and Swiss milling spindle manufacturers anchor precision equipment supply for Chile's dental clinic network, concentrating margin capture upstream while Santiago's corporate chains extract procurement leverage through volume consolidation downstream.
Pricing Analysis
Volume-discount tiering structures dominate equipment procurement across Chile's multi-chair corporate operators, with Santiago's expanding clinic chains commanding steepest rebates through standardized bundled contracts. Pricing stratifies across premium CAD/CAM systems with full service integration, standard imaging packages with regional dealer support, and economy-tier consumables serving FONASA-affiliated facilities. Price erosion runs through the economy tier as Asian biomaterial suppliers expand ISP-registered product lines. Corporate dental chains exhibit lowest price sensitivity due to amortization across chair count, while independent practitioners in provincial markets face acute cost pressure.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts optical sensor sourcing for intraoral scanning systems, forcing Chilean distributors to maintain dual-country supplier relationships. Precision manufacturing concentrates in Germany, Switzerland, and Japan for milling spindles, CAD/CAM hardware, and digital imaging sensors. Raw material dependencies span zirconia blanks from Japan, titanium implants from Switzerland, and resin composites from US and European chemical producers. Single-source vulnerability persists for chairside milling unit controllers. Distribution runs through Valparaíso's Pacific port infrastructure, with regional dealer networks extending reach into Concepción and La Serena.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Chile dental market sits in a cyclical recovery phase as FONASA reimbursement expansion drives patient volume growth and clinic capital expenditure cycles turn upward.
For Market Incumbents: Insulate premium positioning by deepening backward integration into CAD/CAM software ecosystems and securing exclusive service contracts across Santiago's corporate clinic chains. Threat from Asian biomaterial suppliers with accelerated ISP registration timelines demands accelerated local technical documentation investment. Channel control through manufacturer-direct service organizations represents the critical defensive lever. For New Entrants and Emerging Players: Concepción and La Serena's underpenetrated corporate dental markets offer white-space expansion with lower competitive density than Santiago's saturated premium cluster. Target mid-tier clinic operators seeking standardized equipment procurement without multinational minimum volume commitments. Cloud-based laboratory integration platforms enable remote case management as a differentiated go-to-market angle for dispersed provincial practices. For Investors and Strategic Acquirers: Capital is best deployed toward integrated workflow system providers with established ISO 13485 infrastructure and FONASA reimbursement pathway expertise. Long-term viability hinges on regulatory compliance capacity rather than hardware innovation alone. Watch for ISP registration timeline compression as the signal indicating accelerated market entry for novel biomaterial categories.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | ISP enforcement creates competitive moat for manufacturers with superior quality documentation infrastructure. |
| Manufacturer-Direct Service Organization | Santiago's corporate chains favor bundled equipment-and-service contracts over traditional regional dealer relationships. |
| Cloud-Based Laboratory Integration | Remote case management platforms enable provincial clinic networks to access metropolitan laboratory capacity. |
| FONASA Reimbursement Pathway Investment | Public-affiliated clinic procurement depends on navigating Ministry of Health payment ceiling structures. |
| Provincial Clinic Network Expansion | Concepción and La Serena present underpenetrated demand for standardized multi-chair corporate operations. |
Research Methodology
Desk research of ISP registration databases, FONASA reimbursement schedules, and Chilean customs import records preceded structured interviews with dental clinic operators, biomedical equipment distributors, and Ministry of Health procurement officials. Primary fieldwork captured capital expenditure timelines and equipment replacement cycles across Santiago Metropolitan Region and Valparaíso clinic networks. Secondary validation drew from Instituto de Salud Pública adverse-event reporting systems, regional dealer sales data, and hospital dental department procurement records. Bottom-up clinic census data triangulated against top-down equipment import value estimates.
Forecast assumptions held FONASA reimbursement expansion rates and CAD/CAM hardware cost decline curves within observed historical patterns across the projection horizon. Segmentation modeling incorporated product type, end-user channel, service category, and technology adoption tier dimensions. CAGRs derived from equipment replacement cycle analysis, patient volume growth trajectories, and technology penetration curve fitting. Industry-specific inputs included ISP registration approval timelines, specialist workforce geographic distribution, and corporate clinic chain expansion plans.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by Asian biomaterial suppliers or accelerated FONASA benefit expansion would shift volume and value outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Implants and Dental Prosthetics Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
Prophylaxis Pastes Market
Dental Devices
Digital Facebow Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Australia Dental Devices Market
Dental Devices
Nano Dentistry Market
Dental Devices
US Dental Splint Market
Dental Devices
Dental Composite Filling Market
Dental Devices
Argentina Dental Devices Market
Dental Devices
Dental Whitening Lamps Market
Dental Devices
Dental Units Market
Dental Devices
Dental Fittings Market
Dental Devices
Global Restorative Dentistry Market
Dental Devices
Orthodontic Wax Market