
 Dental Dam Market | 2026-2036
Dental Dam Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Dam Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) is repositioning material sourcing strategies across the dental consumables supply chain. This mandate for greater transparency influences raw material selection and waste management protocols for manufacturers. COLTENE Group specializes in high-performance polymer formulations, particularly for its non-latex product lines. Dentsply Sirona leverages its extensive global distribution network to supply both traditional latex and alternative material dams to dental clinics worldwide.
A dental dam is a thin, flexible sheet, typically made of latex or nitrile, used to isolate specific teeth from the oral environment during procedures. Its primary function is to create an aseptic and dry operating field, improving visibility and preventing the patient from swallowing or aspirating foreign objects. The non-latex product segment is expanding rapidly to address practitioner and patient sensitivities. In terms of application, endodontics remains the dominant segment, where the use of a dam is considered the standard of care for root canal treatments.
Regulatory frameworks from bodies like the US Food and Drug Administration (FDA) and the European Union's Medical Device Regulation (MDR) govern material biocompatibility and manufacturing standards. In parallel, Japan's Pharmaceuticals and Medical Devices Agency (PMDA) enforces strict quality and labeling requirements for market access. Manufacturers must navigate these diverse international standards while balancing investments in innovative hypoallergenic materials against procurement cost pressures from large dental service organizations.
Market Dynamics
The dental dam market's trajectory is defined by the intersection of stringent clinical standards and advanced material science. Heightened requirements for aseptic operating fields in endodontics are pulling demand, while regulatory frameworks governing biocompatibility are pushing material innovation, particularly away from traditional latex.
Growth Catalysts
- Standard of Care Mandates:The elevation of dental dam use to a standard of care for endodontic procedures by professional bodies in the United States and Germany establishes a strong, non-discretionary demand floor in these key markets.
- Advanced Polymer Development:Innovations in non-latex materials like nitrile and polyisoprene are critical for addressing practitioner and patient allergies, thereby expanding the product's applicability and user base beyond traditional latex tolerance.
- Infection Control Focus:Global dental guidelines emphasizing aerosol reduction and cross-contamination prevention have reinforced the clinical necessity of isolating the operating field, directly benefiting dental dam utilization rates across various procedures.
Market Restraints
- Procurement Cost Pressure:Large Dental Service Organizations (DSOs) leverage their consolidated purchasing power to negotiate lower prices on consumables, which compresses profit margins for manufacturers of what is often viewed as a commodity item.
- Application Time Perception:Some general practitioners perceive the placement of a dental dam as time-consuming, creating a barrier to adoption for routine restorative procedures where speed and patient throughput are prioritized.
- Raw Material Volatility:The price and availability of key inputs, particularly nitrile and other specialized synthetic polymers, are subject to fluctuations driven by demand from the broader global healthcare sector, creating supply chain uncertainty.
Strategic Opportunities
- Pediatric Dentistry Applications:Designing products specifically for pediatric patients, featuring smaller sizes, appealing colors, or integrated comfort features, opens a significant and underserved market segment with unique clinical needs.
- Emerging Market Education:There is a substantial opportunity to drive adoption in fast-growing dental markets like Brazil and India by partnering with local dental associations and universities to promote the benefits of isolation.
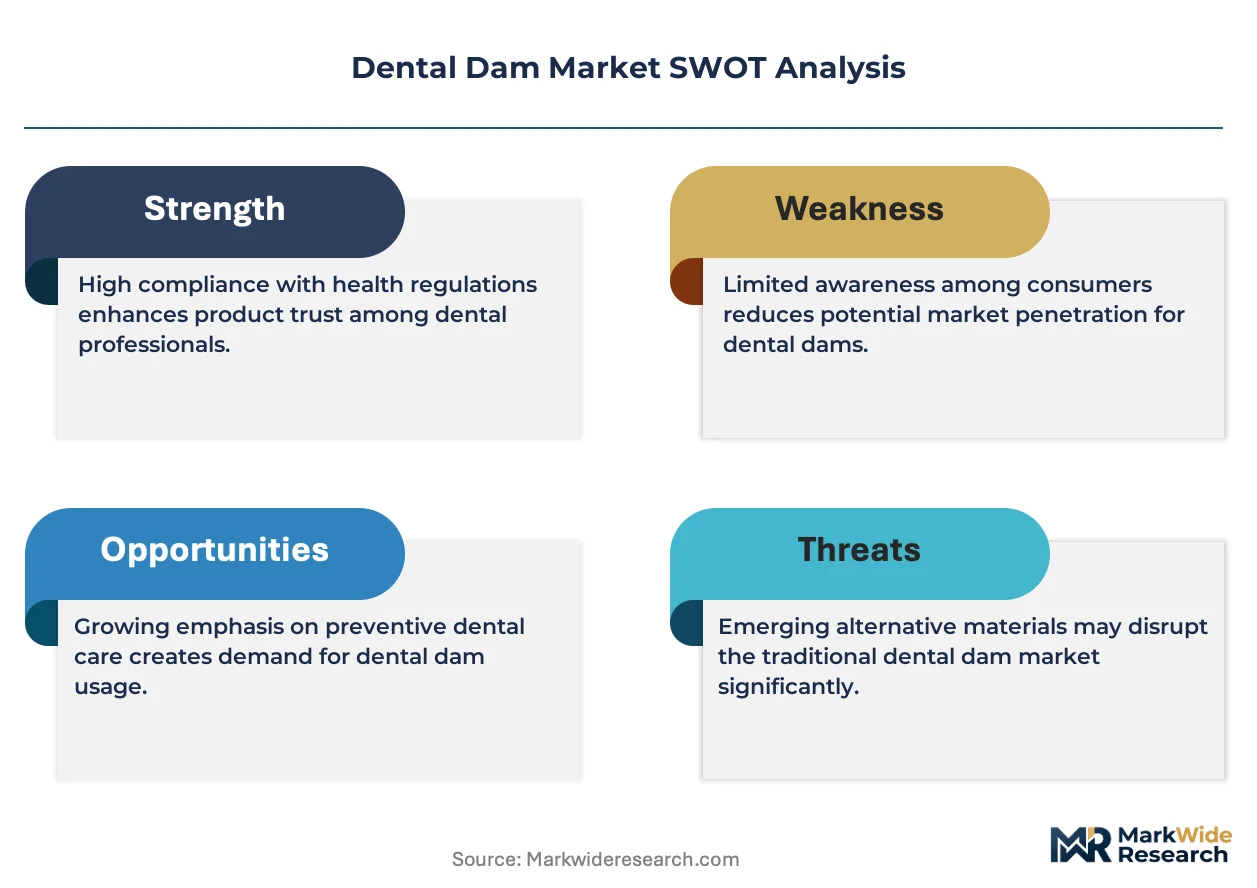
- Regulatory-Driven Differentiation:Stricter quality and biocompatibility mandates under frameworks like the EU's MDR allow manufacturers of high-compliance, premium products to differentiate themselves from lower-cost, less-regulated competitors.
Industry Challenges
- Variable Training Standards:Inconsistent emphasis on efficient dental dam placement techniques within dental school curricula globally results in a skills gap and variable adoption rates among newly qualified dentists.
- Complex Compliance Navigation:Manufacturers face significant administrative and testing overhead to secure and maintain market access across jurisdictions with distinct regulatory hurdles, such as the FDA, EU MDR, and Japan's PMDA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Dam Market |
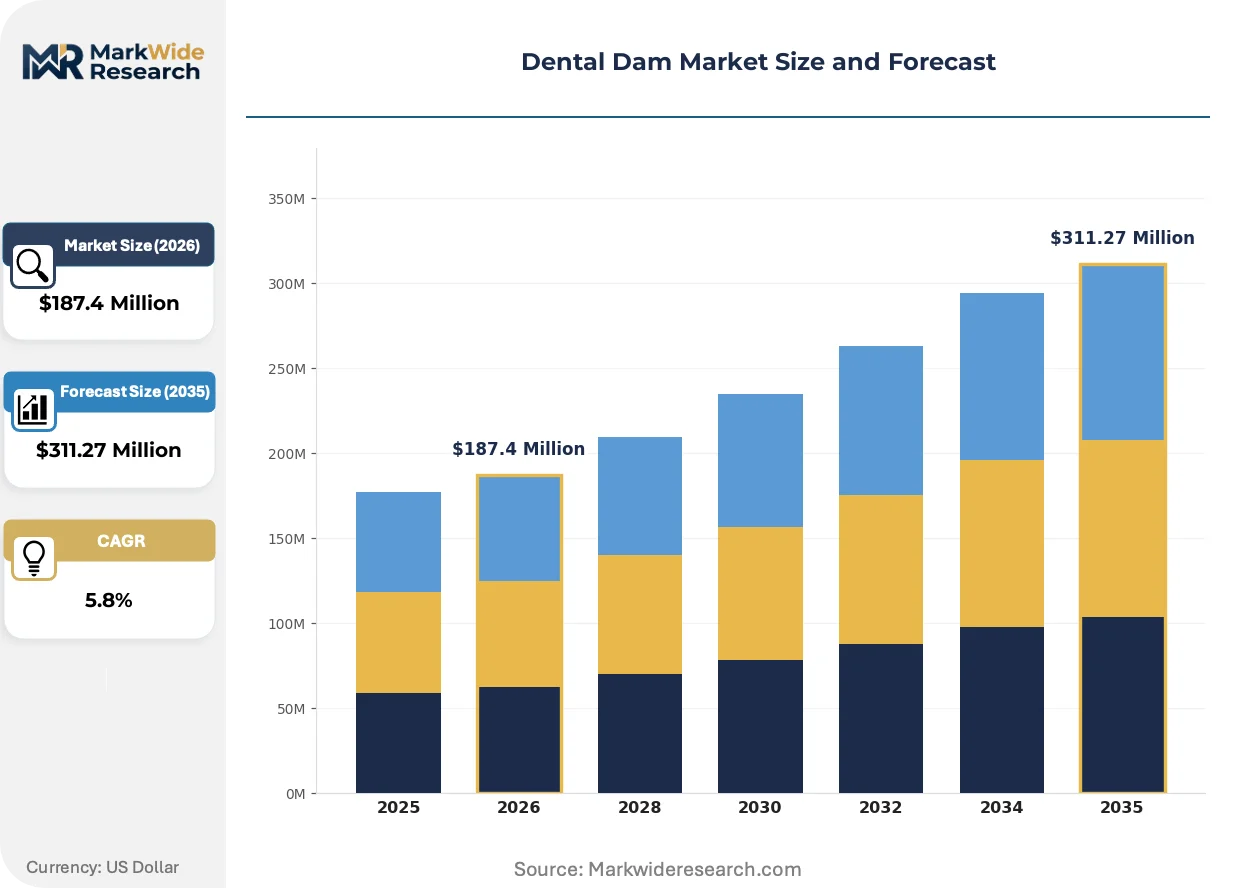
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Latex, Non-Latex, Colored, Printed End User: Dentists, Dental Clinics, Hospitals, Educational Institutions Application: Oral Surgery, Periodontology, Endodontics, Restorative Dentistry Distribution Channel: Online, Offline, Medical Supply Stores, Distributors |
| Companies Covered | Top Glove Corporation, Kulzer GmbH, COLTENE Group, Den-Mat Holdings, Hedy Canada, Dentsply Sirona, Zirc Dental Products, Sanctuary Dental Dam Systems, Hu-Friedy Mfg. Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Dam Market Strategic Shifts & Innovations
Innovation in the dental dam market is converging around material science and supply chain transparency. The drive for improved patient and practitioner safety, combined with new environmental reporting mandates, is fundamentally altering product development priorities and sourcing strategies for manufacturers.
Advanced non-latex polymers, including specific formulations of polyisoprene, offer elasticity and tear resistance comparable to latex without the associated allergenic proteins. Dental practices and large hospital systems are adopting these materials to mitigate the risk of allergic reactions in both patients and staff. This movement toward hypoallergenic options is overtaking traditional latex as the default material in markets with high allergy prevalence, such as North America and Western Europe.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a significant regulatory development impacting the supply chain. This directive compels manufacturers to disclose the environmental and social impacts of their material sourcing and waste management protocols. Dental consumable producers supplying the EU are most affected, as they must now provide extensive documentation on polymer provenance and end-of-life considerations, influencing material selection for next-generation products.
Consolidated procurement by large Dental Service Organizations (DSOs) is altering traditional sales channels. This shift disrupts the direct sales relationship manufacturers historically held with individual private practices, substituting it with a competitive bidding process for large, multi-clinic contracts. The trend is particularly evident in the United States, where the rapid growth of DSOs forces suppliers to adapt their pricing and distribution models to secure volume-based agreements.
Dental Dam Market Segmentation
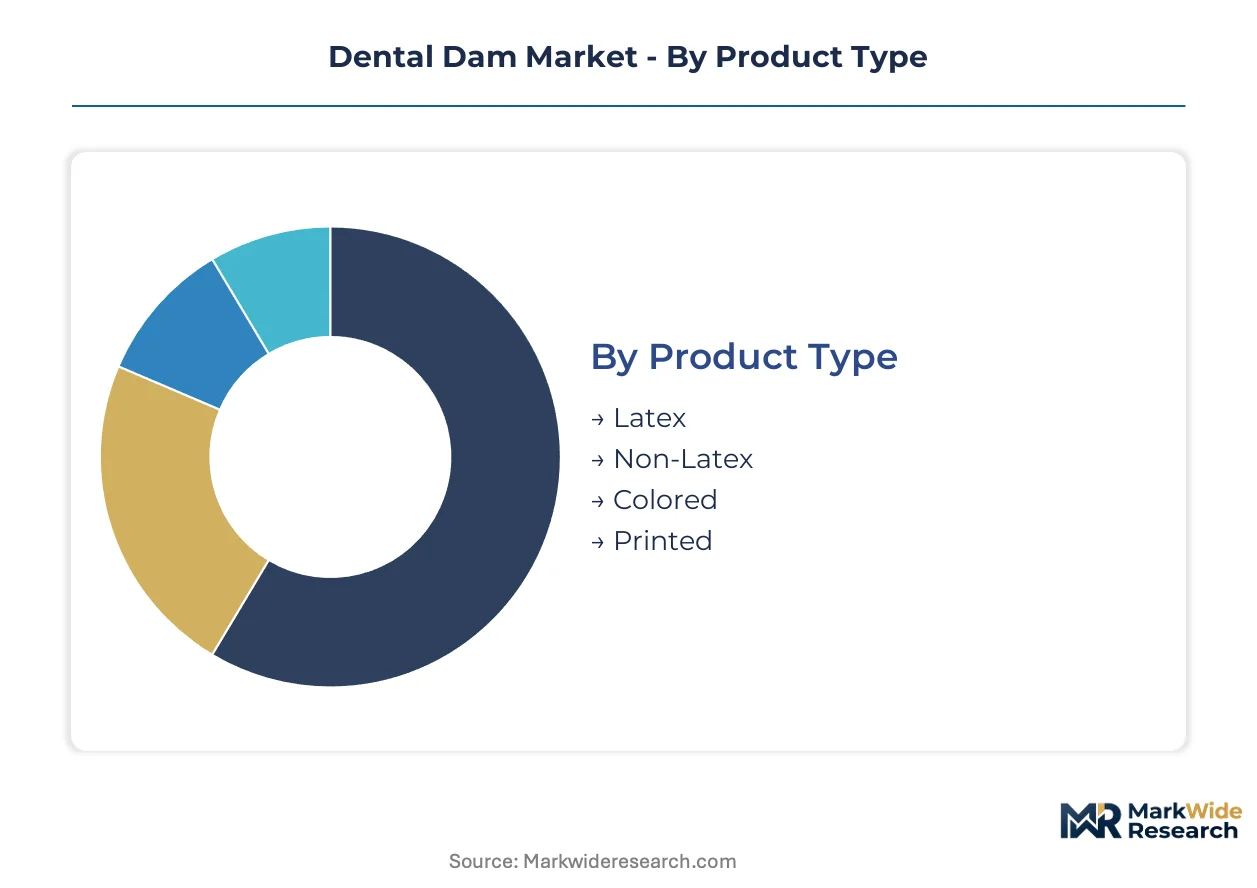
The dental dam market's segmentation provides a granular view of product evolution, end-user consumption patterns, and critical application areas. Understanding these distinctions helps manufacturers align product development with clinical needs and optimize distribution strategies. Each segment reflects unique demand drivers and competitive dynamics.
Product Type:
The dental dam market's product type segmentation reflects ongoing shifts in material science and clinical preferences, often driven by replacement cycles for traditional options.
- Non-Latex:These products are typically made from synthetic polymers like nitrile or polyisoprene, designed to mimic latex elasticity without allergenic proteins. Demand is concentrating in North America and Western Europe, driven by heightened awareness of latex allergies among practitioners and patients.
- Latex:Derived from natural rubber, these traditional dental dams offer high elasticity and tear resistance at a cost-effective price point. Volume demand remains strong in markets where allergy prevalence is lower or cost sensitivity is higher, particularly in some emerging economies.
- Colored:These dental dams come in various hues, primarily for aesthetic preference or to provide better contrast against tooth structures during specific procedures.
- Printed:Featuring patterns or designs, printed dental dams are often marketed towards pediatric dentistry to make the isolation process more engaging for younger patients.
Volume placements concentrate in Latex; the faster expansion belongs to Non-Latex.
End User:
End-user categories delineate where the highest volumes of dental dams are consumed, reflecting diverse clinical settings and patient demographics.
- Dental Clinics:These facilities represent the largest collective end-user segment, encompassing a wide range of general and specialized dental practices. Demand here is driven by routine restorative work and specialized endodontic procedures performed daily.
- Hospitals:Dental departments within hospitals utilize dental dams for more complex oral surgery cases, trauma, or treatments for medically compromised patients requiring stringent infection control. Demand is influenced by institutional purchasing protocols and specialized surgical needs.
- Dentists:Individual dental practitioners, particularly those in private practice, purchase dental dams directly or through smaller supply channels for their daily patient care.
- Educational Institutions:Dental schools and teaching hospitals procure dental dams for training purposes, ensuring future practitioners are proficient in isolation techniques.
Dental Clinics generate significant demand, while Hospitals demonstrate a climbing expansion trajectory.
Application:
The application segmentation highlights the specific clinical procedures where dental dams are essential, each with distinct isolation requirements.
- Endodontics:This segment includes root canal treatments and other procedures focused on the dental pulp, where a completely dry and aseptic field is paramount. The use of a dental dam is considered the standard of care for endodontic interventions, particularly in the United States and Germany.
- Restorative Dentistry:This application involves fillings, crowns, and other procedures to repair damaged teeth, benefiting from isolation to ensure optimal bonding and prevent moisture contamination. Adoption rates are increasing as general practitioners recognize efficiency gains and improved outcomes.
- Oral Surgery:Dental dams are used in certain minor oral surgical procedures to isolate the surgical site, prevent aspiration, and manage soft tissue.
- Periodontology:In periodontics, dental dams assist in isolating specific teeth or areas during gum treatments, improving visibility and controlling moisture.
Endodontics remains the primary application, but Restorative Dentistry is gaining share fastest as practitioners overcome adoption barriers.
Distribution Channel:
Distribution channels define the pathways through which dental dams reach end-users, with supply concentration varying across direct and indirect models.
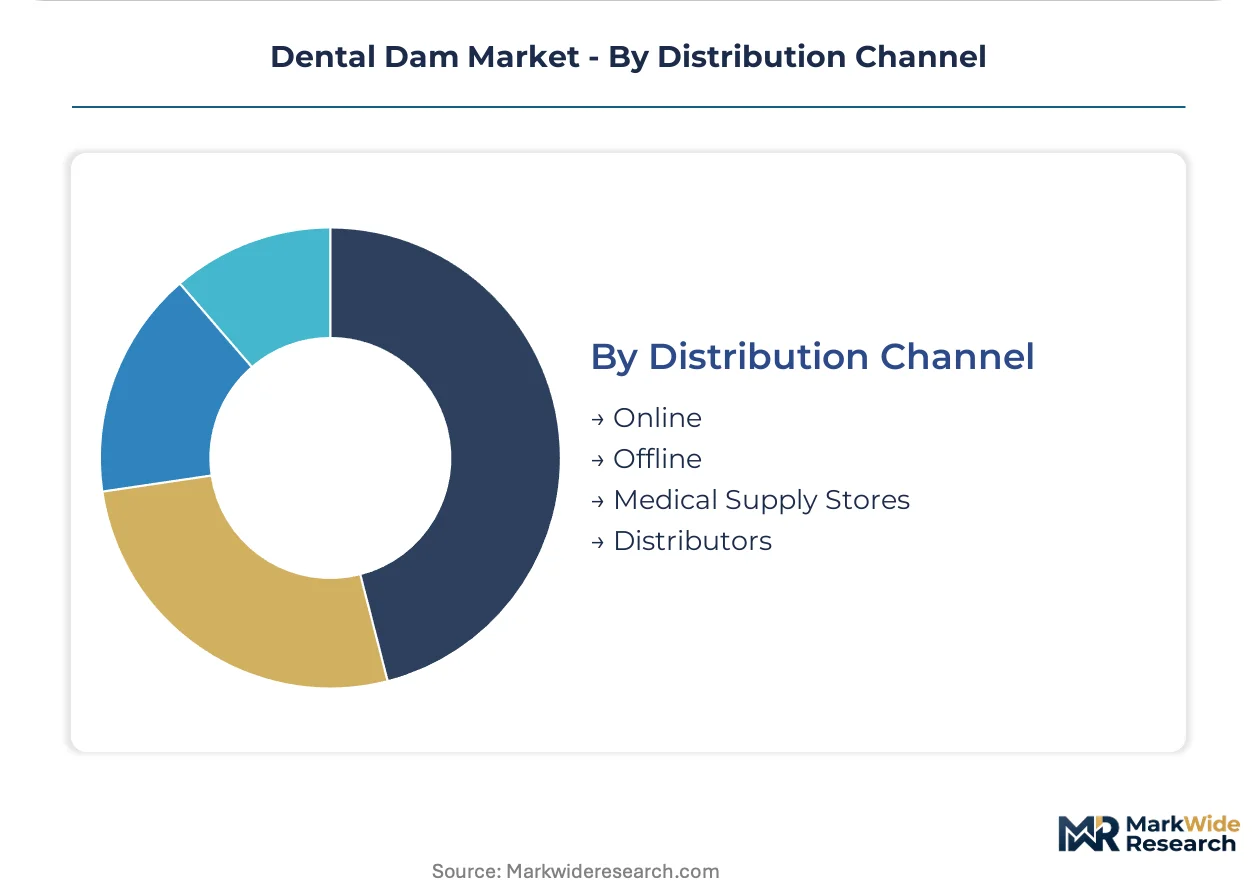
- Distributors:These entities serve as intermediaries, purchasing dental dams in bulk from manufacturers and then selling them to a wide network of dental clinics, hospitals, and individual practitioners. This channel relies on established logistics and sales forces to reach diverse markets.
- Online:E-commerce platforms and manufacturer websites facilitate direct sales to end-users, offering convenience, competitive pricing, and a broad product selection. This channel is experiencing significant growth, particularly among smaller practices and individual dentists.
- Offline:This traditional channel includes direct sales representatives from manufacturers or local dental supply stores where practitioners can physically purchase products.
- Medical Supply Stores:These retail outlets offer a range of medical and dental consumables, providing another avenue for dental professionals to acquire dental dams.
Traditional Distributors manage substantial volume, while Online channels are experiencing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The medical technology cluster around Tuttlingen, Germany, influences dental dam market dynamics by fostering material science advancements and precision manufacturing. This region, known for its high-quality medical device production, sets benchmarks for dental consumables. It drives demand for innovative solutions across European markets.
United States
Dental dam demand in the United States is primarily driven by the established standard of care for endodontic procedures. The US Food and Drug Administration (FDA) enforces stringent biocompatibility and manufacturing standards for dental devices. Major dental service organizations in metropolitan areas like New York and Los Angeles influence procurement patterns and product specifications.
Germany
Germany's dental dam market benefits from high clinical standards and robust healthcare infrastructure. The European Union's Medical Device Regulation (MDR) dictates strict quality and safety requirements for market access. Dental manufacturing hubs in areas such as North Rhine-Westphalia are at the forefront of non-latex polymer development.
Japan
Strict quality and labeling requirements from Japan's Pharmaceuticals and Medical Devices Agency (PMDA) shape product offerings in the Japanese market. Demand for advanced non-latex materials is growing due to practitioner and patient sensitivities. Tokyo and Osaka serve as key centers for dental technology adoption and distribution.
Brazil
Brazil's dental dam market is expanding, fueled by increasing access to dental care and professional education initiatives. The national health surveillance agency, ANVISA, regulates medical devices to ensure patient safety and product efficacy. Sao Paulo and Rio de Janeiro are significant metropolitan areas for dental clinic expansion and product consumption.
India
Growing awareness of infection control and evolving clinical protocols contribute to dental dam adoption in India. The Central Drugs Standard Control Organization (CDSCO) regulates medical device imports and manufacturing standards. Major cities like Mumbai and Bangalore are experiencing significant growth in specialized dental practices.
Dental Dam Market Key Industry Players
The competitive structure tilts toward a blend of specialized material science innovators and large, diversified global dental solutions providers. This market includes companies focused on advanced polymer formulations and others leveraging extensive distribution networks. Strategic archetypes include niche technology developers, comprehensive product portfolio providers, and high-volume commodity manufacturers. Competitive moves often involve strategic partnerships for market reach and continuous research into hypoallergenic materials.
Within the specialized material development segment, COLTENE Group, a Swiss-based entity, exemplifies innovation in high-performance polymer formulations for non-latex products. Dentsply Sirona, a global dental technology company, anchors the comprehensive solutions archetype, leveraging its extensive distribution network for both traditional and alternative material dams. Top Glove Corporation, a Malaysian manufacturer, represents the high-volume production scale, often supplying foundational latex and nitrile materials. These companies collectively illustrate the varied approaches to market penetration and product differentiation.
| Leading Market Players |
|---|
| Top Glove Corporation |
| Kulzer GmbH |
| COLTENE Group |
| Den-Mat Holdings |
| Hedy Canada |
| Dentsply Sirona |
| Zirc Dental Products |
| Sanctuary Dental Dam Systems |
| Hu-Friedy Mfg. Co. |
| Others |
Cost & Logistics Intelligence
Advanced non-latex polymer development simultaneously reshapes cost economics and supply concentration within the dental dam market. This material shift mandates investments in new manufacturing capabilities while diversifying raw material sourcing away from traditional latex, impacting overall market pricing.
Pricing Analysis
Value-based pricing anchors premium dental dam products, reflecting enhanced patient safety and improved clinical outcomes, particularly in endodontics. Pricing differentiation stems from material biocompatibility, with FDA and EU MDR compliant non-latex options commanding higher prices, and brand premium from established manufacturers like COLTENE Group. Procurement cost pressure from large Dental Service Organizations (DSOs) creates downward pressure on margins for high-volume, commodity-grade latex dams. Individual dental clinics prioritizing specialized procedures exhibit lower price sensitivity for advanced non-latex solutions.
Supply Chain Analysis
Dual-sourcing requirements for critical materials influence the dental dam supply chain, ensuring resilience against regional disruptions. Geographic supply concentration for raw materials includes Malaysia for natural rubber and parts of Asia for synthetic polymers like nitrile. Key inputs are natural rubber latex, nitrile, and polyisoprene. Commodity price volatility for specialized synthetic polymers, driven by broader healthcare sector demand, represents a structural supply chain risk. Downstream distribution runs through established dental distributors and increasingly, online e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental dam market presents a cost-of-compliance story, where stringent regulatory frameworks like the EU's Medical Device Regulation (MDR) create a barrier-to-entry moat for compliant manufacturers.
For Market Incumbents: Extend research and development into next-generation non-latex polymers, focusing on enhanced elasticity and tear resistance to counter raw material volatility. Deepen strategic partnerships with large Dental Service Organizations (DSOs) to secure long-term volume contracts, mitigating competitive threats from lower-cost alternatives. Invest in comprehensive certification processes, particularly for new product lines, to maintain a strong regulatory advantage in markets like Germany and the United States.
For New Entrants and Emerging Players: Dental distributors and specialized dental supply chains offer a viable entry point into underserved market segments. Target pediatric dentistry with innovative product designs, such as smaller, colored, or printed dental dams, which present a penetrable niche. A focused go-to-market strategy involves educational partnerships with local dental associations and universities in fast-growing markets like Brazil and India to promote isolation benefits.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized material science innovators given the increasing regulatory emphasis on biocompatibility and sustainability. The long-term viability of the dental dam market is sustained by non-discretionary demand from endodontic procedures and the accelerating shift towards non-latex options. A signal to watch is the increased regulatory enforcement on material provenance and waste management protocols in key markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop advanced non-latex polymer formulations | This initiative directly addresses patient allergy concerns and regulatory mandates for biocompatibility. |
| Expand regulatory compliance certifications (e.g., EU MDR, FDA) | Achieving these certifications strengthens market access and product differentiation in premium segments. |
| Form strategic partnerships with Dental Service Organizations | These partnerships secure high-volume procurement contracts and stabilize market share against competitors. |
| Invest in educational programs for emerging markets | This move drives product adoption rates and establishes brand loyalty in high-growth geographies. |
| Optimize online distribution channels and e-commerce platforms | Enhanced online presence improves market reach and caters to changing procurement patterns of dental clinics. |
Research Approach
Multi-period observation of material science advancements and regulatory shifts anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with endodontists, dental clinic managers, procurement specialists from Dental Service Organizations (DSOs), and material scientists. Secondary validation drew from FDA filings, EU MDR guidance documents, national dental association guidelines from the ADA and DGZMK, and polymer industry reports, triangulating insights through bottom-up and top-down approaches.
The segment-weighting approach informed the forecast framework, projecting market evolution across the analysis window. Segmentation dimensions modeled included product type (latex, non-latex), end-user (dental clinics, hospitals), application (endodontics, restorative dentistry), distribution channel (distributors, online), and material biocompatibility. Compound annual growth rates were derived from historical trends and future projections, with non-latex polymer availability and regulatory compliance costs serving as key forecast inputs.
Caveats apply where raw material price volatility or new regulatory mandates could materially shift the outlook, as forecasts reflect underlying assumptions. A model refresh is warranted upon material change in global polymer supply dynamics or major healthcare policy shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Asia-Pacific Dental Lab Market
Dental Devices
Global Dental Labs Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Dental Floss Market
Dental Devices
Dental Erbium Lasers Market
Dental Devices
North America Dental Implants and Prosthetics Market
Dental Devices
Toothbrush Sterilizer Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
Netherlands Dental Devices Market
Dental Devices
Dental Implant Motors Market
Dental Devices
Italy Dental Devices Market
Dental Devices
Dental Irrigation Devices Market
Dental Devices
Dental Handpieces Market
Dental Devices
Root Canal Market
Dental Devices
Chile Dental Market