
 Endodontic Supplies Market | 2026-2036
Endodontic Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Endodontic Supplies Market Analysis
Hospital outpatient departments is restructuring their procurement of endodontic supplies as dental clinics capture a larger share of complex root canal procedures. Dentsply Sirona leverages its integrated digital workflow platforms to anchor premium positioning across rotary file systems. Envista competes through specialized distribution networks that sustain channel control in North American dental schools. Danaher differentiates via R&D intensity in nickel-titanium alloy formulations for next-generation file designs.
Endodontic supplies encompass instruments, materials, and diagnostic devices used to treat diseased dental pulp and periapical tissues, with nickel-titanium rotary files typically featuring taper designs between 0.04 and 0.12 mm/mm and tip diameters ranging from 0.15 to 0.50 mm to navigate curved root canal anatomies. These products serve the primary purpose of enabling complete chemomechanical debridement, three-dimensional obturation, and periapical healing in teeth that would otherwise require extraction. Rotary endodontic files command the largest product category share, while digital apex locators represent the fastest-growing technology segment as practices replace radiographic methods with electronic working-length determination. Obturation materials concentrate margin pools through thermoplasticized gutta-percha systems that command premium pricing over cold lateral condensation techniques.
The FDA regulates endodontic files as Class II medical devices requiring 510(k) premarket notification, while the EU Medical Device Regulation mandates notified body conformity assessment for rotary instruments sold under CE marking. ISO 3630-1 standards govern dimensional specifications and mechanical testing protocols for endodontic instruments, directly shaping manufacturer R&D priorities and product qualification timelines. Stakeholders must monitor evolving reimbursement codes for cone-beam computed tomography-guided endodontics, as payer coverage decisions will determine whether digital workflow investments translate into sustainable procedure economics.
Market Dynamics
The central structural force reshaping endodontic supplies is the migration of complex root canal procedures from hospital outpatient departments to dental clinics, driven by patient preference for single-visit treatment protocols and the capital investments required for in-house digital imaging capabilities.
Growth Catalysts
- Germany's reimbursement reforms:The country's statutory health insurance framework now favors preventive endodontic intervention over extraction, redirecting procedure volume toward conservative pulp therapy.
- Heat-treated nickel-titanium alloys:Advanced metallurgical processes are improving cyclic fatigue resistance in rotary files, enabling safer instrumentation of severely curved canal anatomies.
- FDA 510(k) pathway modernization:Streamlined premarket notification procedures for nickel-titanium rotary instruments are compressing time-to-market for next-generation file designs in the United States.
Market Restraints
- Nickel price volatility:Raw material cost swings for nickel-titanium alloy feedstock compress margins on precision-manufactured rotary instruments.
- Supply concentration in file manufacturing:A limited number of specialized Swiss and German machining houses control high-precision grinding capacity for taper-controlled instruments.
- EU Medical Device Regulation compliance burden:Notified body conformity assessment timelines for rotary instruments under CE marking extend product qualification cycles by 12-18 months.
Strategic Opportunities
- Digital apex locator penetration in India:Electronic working-length determination devices remain underdeployed relative to radiographic methods in tier-2 and tier-3 cities.
- Thermoplasticized obturation systems:Warm vertical compaction technology commands premium pricing over cold lateral condensation in markets where reimbursement supports procedure differentiation.
- Cone-beam CT-guided endodontics:Three-dimensional imaging integration creates service bundling potential for clinics investing in chairside diagnostic workflows.
Industry Challenges
- ISO 3630-1 testing protocol complexity:Mechanical validation requirements for torsional resistance and cyclic fatigue consume substantial R&D engineering resources.
- Cross-contamination protocol adherence:Strict sterilization and single-use compliance for intracanal instruments demands rigorous staff training and inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endodontic Supplies Market |
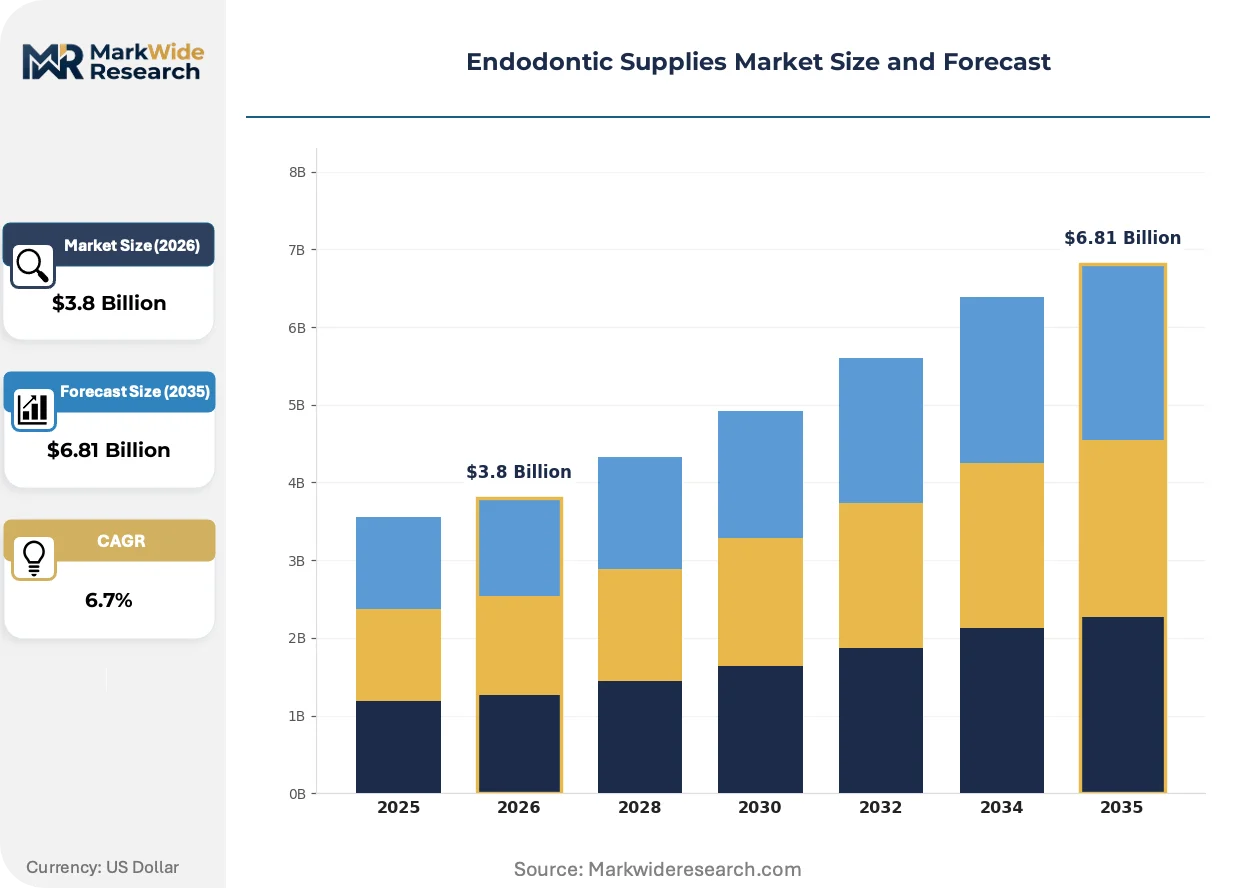
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endodontic Files, Irrigation Solutions, Obturation Materials, Apex Locators Application: Root Canal Treatment, Pulp Capping, Retreatment, Surgical Endodontics End User: Dentists, Dental Clinics, Hospitals, Academic Institutions Technology: Manual, Rotary, Disposable, Digital |
| Companies Covered | Dentsply Sirona, Envista, Danaher, Coltene Group, Septodont, FKG Dentaire, Ultradent Products, Ivoclar Vivadent, Brasseler USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endodontic Supplies Market Emerging Trajectories
Digital workflow integration is compressing treatment timelines and reshaping capital allocation decisions across dental practices. Three convergent developments are redefining competitive advantage in endodontic instrumentation.
Variable-taper rotary file systems are expanding into complex molar cases previously referred to endodontic specialists. General practitioners in the United States and Germany are adopting 0.06-0.08 taper designs for second molar instrumentation, compressing the referral pipeline and capturing margin previously lost to specialty practices. This adoption pattern is expanding into single-visit protocols that eliminate interappointment temporary restorations.
EU Medical Device Regulation enforcement is intensifying post-market surveillance obligations for rotary instrument manufacturers. Notified body audits now require systematic clinical follow-up data on file separation rates, compelling manufacturers to invest in traceability infrastructure. German and Swiss suppliers are responding by embedding laser-etched batch codes and establishing direct-to-practice feedback channels for adverse event reporting.
Consolidated purchasing through dental service organizations is displacing traditional dealer relationships in North America. Multi-location practice groups are negotiating direct supply contracts with instrument manufacturers, extracting volume discounts that independent practitioners cannot match. This concentration is most visible in Florida and Texas, where private equity-backed dental platforms control substantial procedure volume and standardize file system selection across affiliated clinics.
Endodontic Supplies Market Segmentation
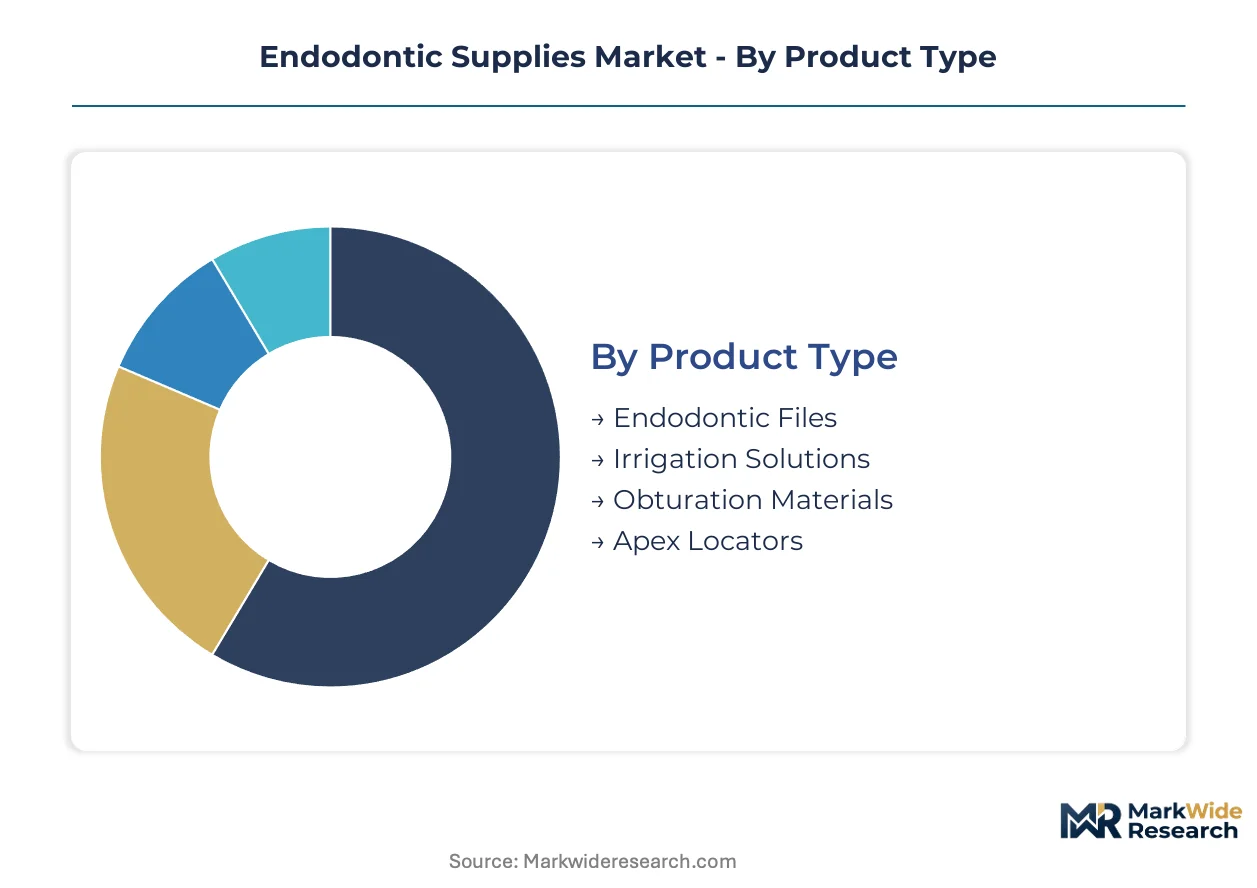
Endodontic supplies segmentation reveals how procedure economics, clinical workflow preferences, and capital investment cycles fragment demand across instrument categories and practice settings. Understanding these splits enables targeted positioning for premium rotary systems versus commodity irrigation products.
Product Type:
Volume concentrates in single-use instruments with rapid turnover, while premium pools form around capital equipment and specialized alloys.
- Endodontic Files:Nickel-titanium rotary instruments with 0.04-0.12 taper designs dominate complex canal anatomies. Heat-treated alloys from German and Swiss machining houses command pricing premiums in curved molar cases across US dental schools.
- Irrigation Solutions:Sodium hypochlorite and EDTA formulations enable chemomechanical debridement. Demand concentrates in high-throughput dental clinics in Florida and Texas where single-visit protocols require bulk procurement.
- Obturation Materials:Thermoplasticized gutta-percha systems for warm vertical compaction.
- Apex Locators:Electronic working-length determination devices replacing radiographic methods.
Mature deployment sits with Endodontic Files. Newer deployment is concentrated in Apex Locators.
Application:
Procedure complexity and reimbursement differentiation separate high-margin specialty work from commoditized general practice volume.
- Root Canal Treatment:Conventional non-surgical therapy comprising chemomechanical preparation and three-dimensional obturation. Volume concentrates in dental clinics across Germany where statutory insurance reforms favor conservative intervention over extraction.
- Pulp Capping:Direct and indirect capping procedures preserving vital pulp tissue. Demand is climbing fastest in pediatric and young adult demographics across Indian tier-2 cities where minimally invasive protocols reduce long-term restoration costs.
- Retreatment:Removal of existing root canal filling materials and re-instrumentation.
- Surgical Endodontics:Apicoectomy and retrograde filling procedures.
Established procedure volume rests with Root Canal Treatment. Steepest expansion trajectory belongs to Pulp Capping.
End User:
Capital intensity and purchasing scale separate institutional procurement from independent practice buying patterns.
- Dentists:Independent general practitioners and endodontic specialists selecting file systems based on handpiece compatibility. Demand clusters in German private practices where ISO 3630-1 compliance drives brand loyalty.
- Dental Clinics:Multi-chair facilities with in-house CBCT and apex locator capabilities. Procurement concentrates in US dental service organizations negotiating direct manufacturer contracts in Florida and Texas.
- Hospitals:Outpatient departments and emergency dental services.
- Academic Institutions:Dental schools and residency programs standardizing training curricula.
Traditional purchasing volume sits with Dentists. Consolidated procurement is accelerating in Dental Clinics.
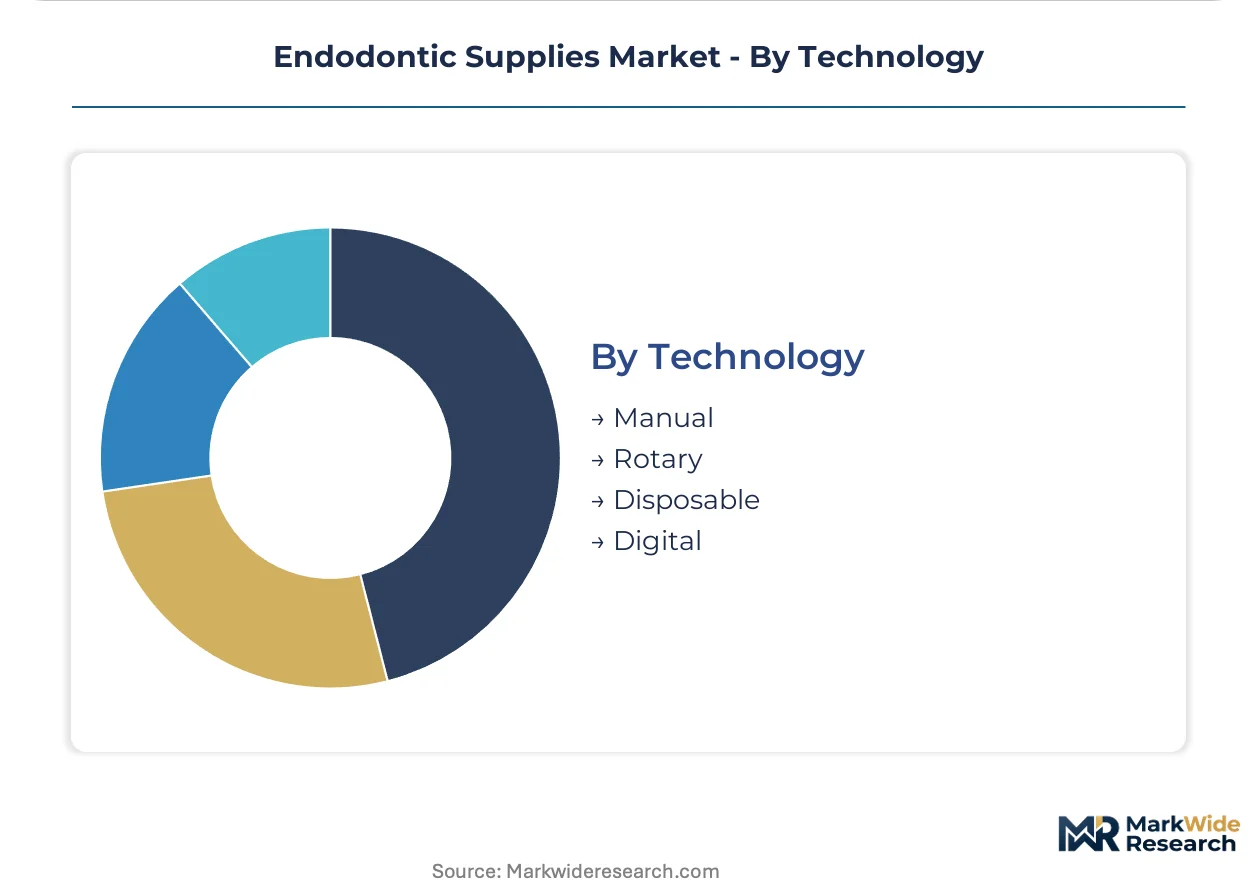
Technology:
Automation depth and disposability economics fragment manufacturing investment and margin capture.
- Manual:Stainless steel hand files and reamers for initial canal negotiation. Demand persists in emerging markets and academic training programs across India where cost sensitivity outweighs speed advantages.
- Rotary:Motor-driven nickel-titanium instruments with variable taper and tip diameter configurations. Adoption concentrates in US and German practices where FDA 510(k) cleared systems reduce operator fatigue in complex anatomies.
- Disposable:Single-use sterile packaged instruments eliminating cross-contamination protocols.
- Digital:Integrated electronic apex location, obturation control, and imaging workflows.
Conventional technology deployment sits with Manual instruments. Integrated workflow adoption is concentrating in Digital.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Telangana are accelerating dental manufacturing clusters that serve both domestic Indian demand and export markets across Southeast Asia and Africa.
United States
FDA 510(k) pathway modernization is compressing clearance timelines for nickel-titanium rotary instruments, enabling faster product launches. Dental service organizations in Florida and Texas negotiate direct manufacturer contracts, consolidating procurement power across multi-location practice groups. The Greater Boston corridor hosts academic research centers advancing heat-treated alloy formulations for next-generation file designs.
Germany
Statutory health insurance reimbursement reforms now favor preventive endodontic intervention over extraction, redirecting procedure volume toward conservative pulp therapy. EU Medical Device Regulation enforcement intensifies post-market surveillance obligations for rotary instrument manufacturers. The Baden-Württemberg machining cluster supplies high-precision grinding capacity for taper-controlled instruments serving European and North American markets.
India
Tier-2 and tier-3 cities present underdeployed digital apex locator penetration relative to radiographic methods, creating equipment upgrade cycles. The country's national pharmaceutical regulator oversees medical device quality standards for imported and domestically manufactured endodontic supplies. Dental schools in Maharashtra and Karnataka standardize training curricula around ISO 3630-1 compliant instrument specifications.
Japan
Minimally invasive endodontic protocols gain traction among aging demographics seeking tooth preservation over extraction. METI industrial policy supports precision manufacturing capabilities for nickel-titanium alloy processing. The Osaka-Kobe manufacturing belt concentrates suppliers of specialized endodontic handpieces and motor systems.
Brazil
Private dental insurance expansion drives demand for single-visit root canal protocols in urban centers. ANVISA regulates medical device registration for imported rotary instruments and obturation materials. São Paulo's dental district hosts distribution networks serving practices across Latin America's largest consumer market.
Endodontic Supplies Market Vendor Landscape
Top-tier vendors anchor premium positioning through integrated digital workflows, while mid-tier competitors compete on specialized distribution networks and alloy formulation R&D. The vendor base clusters around three strategic archetypes: diversified dental conglomerates with cross-category portfolios, specialized endodontic instrument manufacturers with machining expertise, and regional distributors with channel control in academic and institutional settings. M&A activity concentrates on digital workflow integration capabilities, while capacity expansion targets heat-treated nickel-titanium alloy production.
Within the diversified conglomerate tier, Dentsply Sirona and Danaher occupy positions defined by cross-product ecosystem integration. Envista exemplifies the specialized distribution archetype with focused channel strategies. Coltene Group and Septodont represent European precision manufacturing heritage. Brasseler USA anchors North American distribution capabilities for imported instrument systems.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Envista |
| Danaher |
| Coltene Group |
| Septodont |
| FKG Dentaire |
| Ultradent Products |
| Ivoclar Vivadent |
| Brasseler USA |
| Others |
Supply Flow & Price Mechanics
Swiss and German precision grinding specialists anchor the labor-cost differential that separates premium heat-treated nickel-titanium rotary files from economy-grade stainless steel alternatives. Their machining expertise commands wage premiums that propagate through three-tier pricing structures across premium, standard, and economy levels.
Pricing Analysis
Short lead-time premiums attach to heat-treated nickel-titanium rotary files sourced from Baden-Württemberg machining houses, while spot inventory of standard-grade instruments trades at discounts. Pricing stratifies across premium, standard, and economy tiers based on ISO 3630-1 certification grade and after-sales technical support bundling. Cost compression in economy stainless steel files is intensifying because Indian manufacturing scale is flooding tier-2 markets. Dental service organizations in Florida and Texas exhibit lowest price sensitivity due to direct manufacturer contracting, while independent German practitioners show highest sensitivity to handpiece compatibility switching costs.
Supply Chain Analysis
CE marking and FDA 510(k) qualification gates restrict supply chain entry for rotary instrument manufacturers, elongating product validation cycles. Manufacturing concentrates in Germany, Switzerland, and Japan for high-precision taper-controlled grinding. Raw material feeds draw from nickel-titanium alloy suppliers, precision grinding equipment, and sterilization packaging materials. Single-source vulnerability sits with specialized Swiss machining houses controlling sub-micron tolerance capacity. Distribution runs through dental service organization direct contracts in North America and dealer networks in European private practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained precision grinding capacity in Swiss and German machining clusters props pricing power for qualified manufacturers. This bottleneck sustains margin pools despite raw material volatility.
For Market Incumbents: Deepen backward integration into heat-treated nickel-titanium alloy production to insulate margins from feedstock volatility. Secure captive grinding capacity through long-term offtake agreements with Baden-Württemberg machining houses. Counter dental service organization procurement consolidation by embedding file systems into integrated digital workflow platforms that raise switching costs. For New Entrants and Emerging Players: Enter via digital apex locator penetration in Indian tier-2 and tier-3 cities where radiographic methods still dominate working-length determination. Target pulp capping procedure growth in pediatric demographics as the most penetrable application segment. Pursue dental school curriculum partnerships as a go-to-market angle to establish brand preference before practitioners enter independent practice. For Investors and Strategic Acquirers: The window for entry favors specialized endodontic instrument manufacturers with ISO 3630-1 compliant machining capabilities and established notified body relationships. Long-term viability hinges on digital workflow integration assets that capture recurring revenue streams beyond disposable instrument sales. Watch FDA 510(k) clearance velocity for nickel-titanium rotary instruments as the inflection signal indicating regulatory pathway efficiency and competitive launch cadence.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treated Alloy Capacity Expansion | Captive nickel-titanium metallurgy investment secures supply continuity for next-generation file designs. |
| Digital Apex Locator Platform Launch | Electronic working-length devices displace radiographic methods in underpenetrated Indian urban markets. |
| FDA 510(k) Pathway Optimization | Streamlined premarket notification accelerates time-to-market for rotary instrument innovations. |
| Dental Service Organization Partnership | Direct supply contracts with multi-location practice groups consolidate procurement volume in Florida and Texas. |
| Cone-Beam CT Workflow Integration | Three-dimensional imaging bundling creates service differentiation for clinic capital equipment investments. |
Methodological Framework
Independent corroboration across endodontic instrument manufacturers, dental clinic procurement directors, and GPO contracts managers underwrites the qualitative findings. Primary interviews with biomedical engineers, endodontic specialists, and dental school curriculum directors combined with secondary validation from FDA 510(k) filings, ISO 3630-1 standards documentation, and hospital procurement databases. Bottom-up procedure volume estimates triangulate against top-down manufacturer shipment data.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation across product type, application, end user, and technology deployment stage. CAGRs derive from procedure volume trajectories, reimbursement code evolution, and capital equipment replacement cycles. Forecast inputs incorporate nickel-titanium alloy cost curves and dental service organization penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU Medical Device Regulation enforcement intensity and nickel price volatility. Forecasts reflect assumptions about reimbursement stability and regulatory pathway efficiency. A model refresh is warranted upon material change in FDA 510(k) clearance timelines or statutory insurance reimbursement frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Supplies
Global Hotel Dental Kits Market
Dental Supplies
Fissure Sealants Market
Dental Supplies
Global Dental Suture Market
Dental Supplies
Dental Consumables Market
Dental Supplies
Dental Caries Treatment Market
Dental Supplies
Plaque Disclosing Market
Dental Supplies
Orthodontic Consumables Market
Dental Supplies
Orthodontic Supplies Market
Dental Supplies
Dental Preventive Supplies Market