
 Root Canal Market | 2026-2036
Root Canal Market Size, Share, and Industry Trends Forecast 2026-2036
Root Canal Market Outlook
Market Context with Strategic Players
The gap between conventional hand instrumentation and digitally guided rotary systems is narrowing as endodontic workflows integrate real-time 3D imaging feedback. Dentsply Sirona Inc. leverages its integrated CAD/CAM ecosystem to anchor premium positioning across dental clinic networks. Envista Holdings Corporation sustains manufacturing scale through multi-site production across North America and Europe. Ultradent Products Inc. differentiates via specialized bioceramic sealer formulations that command loyalty among endodontic specialists.
Technical Definition and Structural Segments
Root canal therapy encompasses the mechanical debridement, chemical disinfection, and three-dimensional obturation of the pulp canal system to eliminate infection and preserve natural dentition, typically requiring nickel-titanium rotary files with tapered geometries between 0.04 and 0.12 mm/mm and biocompatible gutta-percha or resin-based filling materials. Rotary Systems dominate procedural throughput in developed markets where capital equipment density supports throughput economics, while 3D Imaging represents the fastest-expanding technology layer as cone-beam computed tomography replaces periapical radiography for complex anatomy mapping. Filling Materials capture concentrated margin pools owing to recurring consumption per procedure and limited generic substitution for bioceramic sealers with superior sealing ability.
Regulatory Framework and Forward Outlook
The FDA's 510(k) clearance pathway and the EU Medical Device Regulation (MDR) impose distinct biocompatibility and sterility validation requirements that shape product development timelines and market access costs for instrument manufacturers. Japan's Pharmaceuticals and Medical Devices Agency (PMDA) maintains additional clinical evidence standards that filter entrants in the Japanese market. Stakeholders must monitor convergence between national digital health infrastructure investments and reimbursement coding reforms that will determine whether advanced imaging and single-visit protocols achieve sustainable procedure economics.
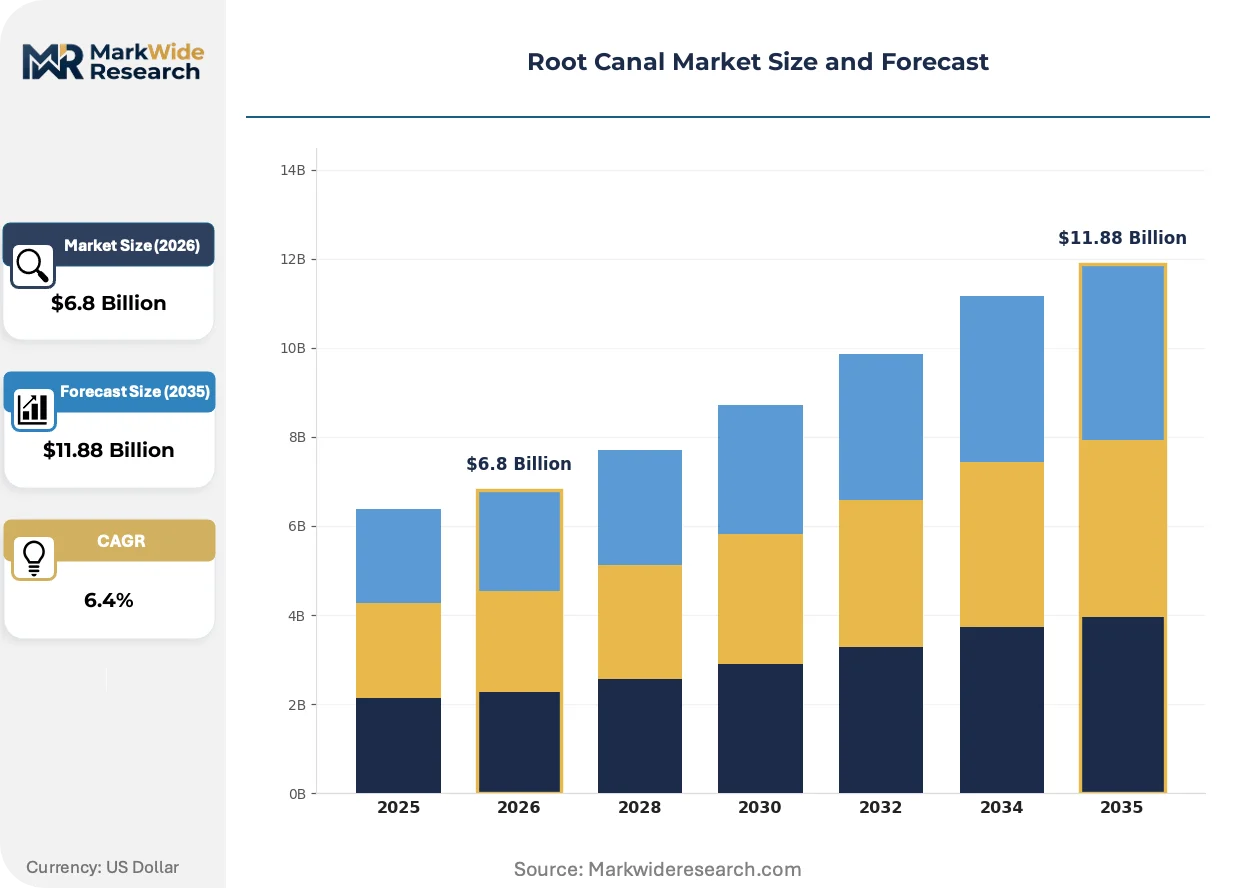
Market Dynamics
The convergence of cone-beam computed tomography with nickel-titanium rotary instrumentation is compressing treatment timelines from multi-visit protocols toward same-day completion, forcing capital allocation decisions across dental clinic networks.
Growth Catalysts
- Bioceramic Sealer Chemistry:Mineral trioxide aggregate and calcium silicate formulations eliminate moisture sensitivity during obturation, expanding single-visit case eligibility in high-throughput metropolitan practices.
- PMDA Streamlined Pathways:Japan's Pharmaceuticals and Medical Devices Agency introduced conditional early approval frameworks for digital endodontic navigation systems, accelerating commercialization timelines for 3D-guided instruments.
- Aging Cohorts:Germany's over-65 population exhibits elevated rates of necrotic pulp requiring intervention, sustaining procedural volume growth independent of elective dental spending cycles.
Market Restraints
- Nickel-Titanium Supply Concentration:Superelastic alloy feedstock for rotary files concentrates among specialty metallurgical suppliers in Western Europe, exposing manufacturers to price volatility and allocation risk.
- EU MDR Recertification Burden:The Medical Device Regulation's enhanced clinical evidence requirements for Class IIa instruments extend clearance timelines by 18-24 months for legacy file systems.
- Implant Substitution:Titanium dental implants achieve functional equivalence for non-restorable teeth, capturing cases that previously mandated endodontic salvage in price-sensitive patient segments.
Strategic Opportunities
- Rural Brazil Penetration:Underdeveloped endodontic service coverage in Brazil's interior states creates whitespace for mobile clinic models deploying portable rotary systems with telemedicine-supported diagnosis.
- AI-Powered Apex Locators:Machine learning integration with electronic length determination devices is digitizing canal measurement accuracy, reducing periprocedural radiograph exposure and operator variability.
- US Reimbursement Coding Reform:Proposed ADA code additions for cone-beam guided therapy would legitimize premium billing for advanced imaging, improving procedure economics for capital-intensive installations.
Industry Challenges
- Microscopic Dexterity Training:Operating microscope proficiency requirements for complex retreatment cases outpace graduating endodontist supply, creating regional service deserts.
- Cross-Infection Protocol Compliance:Heat-tolerant nickel-titanium file sterilization cycles accelerate instrument fatigue and fracture risk, forcing inventory depth increases or single-use cost absorption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Root Canal Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Filling Materials, Medicated Pastes, Retreatment Kits End User: Dentists, Dental Clinics, Hospitals, Research Institutions Technology: Rotary Systems, Hand Instruments, Endodontic Microsurgery, 3D Imaging Application: Single-Visit Treatment, Multi-Visit Treatment, Child Endodontics, Emergency Cases |
| Companies Covered | 3M Corporation, Ultradent Products Inc., Dentsply Sirona Inc., Brasseler USA, Ivoclar Vivadent Group, Envista Holdings Corporation, Septodont Inc., Mani Inc., Coltene Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Root Canal Market Strategic Shifts
Digital workflow integration is dissolving boundaries between diagnostic imaging, mechanical preparation, and restorative completion, collapsing traditional departmental silos within dental service organizations.
WaveOne Gold and similar reciprocating nickel-titanium systems employ reverse cutting geometry and heat-treated metallurgy to reduce cyclic fatigue during curved canal negotiation. Metropolitan dental clinics in the United States and Germany are replacing traditional crown-down sequences with single-file protocols to compress chair time. This instrumentation shift is digitizing throughput economics by enabling higher daily case volumes without proportional staffing increases.
The EU Medical Device Regulation's 2021 enforcement imposed unique device identification and post-market surveillance mandates on endodontic instrument manufacturers. Sterility validation documentation and biocompatibility testing under ISO 10993 now require substantial pre-submission investment. Small-to-mid instrument suppliers in Italy and Spain are consolidating or exiting rather than absorbing MDR compliance costs, concentrating supply among scaled multinational manufacturers.
Patient preference for same-visit completion is displacing traditional multi-appointment scheduling across Japanese and German dental networks. Clinics are unbundling endodontic diagnosis from general practice referrals, establishing in-house specialty capacity to capture full procedure revenue. This channel consolidation is most visible in Japan's Kanto region, where dental service organizations now employ direct-hire endodontists rather than relying on itinerant specialists.
Root Canal Market Segmentation
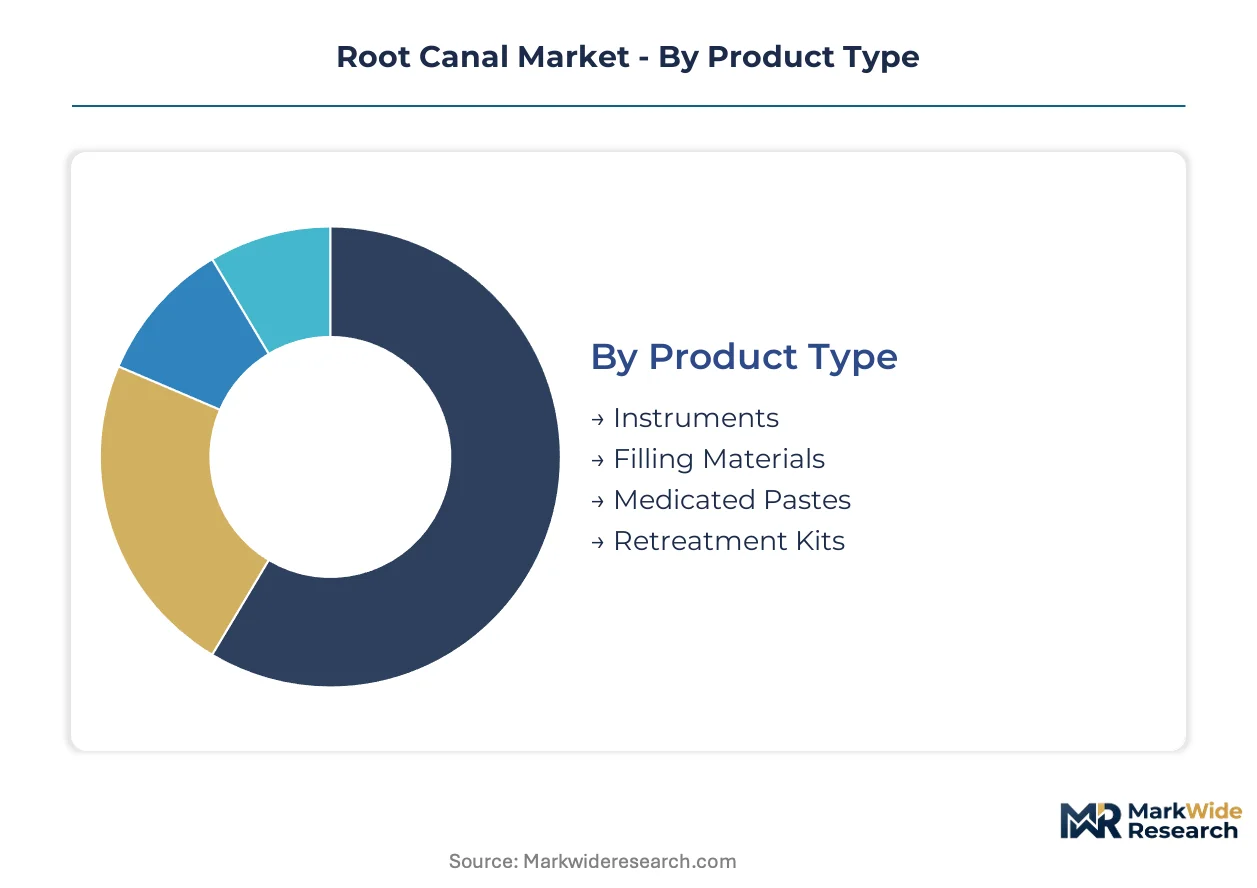
Root canal market segmentation reveals divergent investment cycles across product categories, with capital equipment vendors competing for clinic floor space against consumable suppliers seeking recurring revenue streams. Technology-layer segmentation exposes the tension between established hand instrumentation and digitally guided systems reshaping procedural economics.
Product Type:
Mature mechanical systems anchor installed base revenue while emerging bioceramic formulations capture margin expansion from single-visit protocol adoption.
- Instruments:Nickel-titanium rotary files with tapered geometries between 0.04 and 0.12 mm/mm dominate procedural throughput in United States metropolitan clinics where capital equipment density supports throughput economics. Heat-treated metallurgy variants reduce cyclic fatigue during curved canal negotiation, extending file longevity under high-volume scheduling.
- Filling Materials:Bioceramic sealers incorporating mineral trioxide aggregate and calcium silicate formulations command premium positioning in German specialist practices where moisture-insensitive obturation expands same-day case eligibility. Limited generic substitution for superior sealing ability sustains concentrated margin pools.
- Medicated Pastes:Calcium hydroxide and corticosteroid combinations serve interim disinfection protocols between multi-visit appointments.
- Retreatment Kits:Specialized solvent delivery systems and post removal instruments address growing retreatment volume from failed initial therapies.
Instruments retain volume leadership; Filling Materials holds the steepest expansion curve.
End User:
Customer-type segmentation tracks the unbundling of endodontic diagnosis from general practice referrals as service delivery consolidates.
- Dentists:General practitioners in Japan's Kanto region increasingly deploy portable rotary systems for straightforward anterior cases, retaining patients who previously required specialist referral.
- Dental Clinics:Metropolitan dental service organizations in the United States employ direct-hire endodontists rather than itinerant specialists, capturing full procedure revenue through in-house specialty capacity.
- Hospitals:Academic medical centers manage complex trauma cases requiring multidisciplinary coordination between endodontics and oral surgery.
- Research Institutions:University dental schools validate novel instrumentation through controlled clinical trials supporting regulatory submissions.
Dental Clinics command the highest per-site equipment spend; Dentists represent the broadest addressable base.
Technology:
Cost-tier segmentation separates premium digitally guided systems from economy hand instrumentation with divergent training and infrastructure requirements.
- Rotary Systems:Reciprocating nickel-titanium platforms with reverse cutting geometry compress chair time and enable higher daily case volumes without proportional staffing increases in high-throughput German practices.
- 3D Imaging:Cone-beam computed tomography replaces periapical radiography for complex anatomy mapping, with Japan's PMDA conditional early approval frameworks accelerating commercialization timelines for navigation-integrated instruments.
- Hand Instruments:Stainless steel files and reamers persist in price-sensitive segments and developing markets with limited capital equipment access.
- Endodontic Microsurgery:Operating microscope protocols for apical retreatment require specialized training that outpaces graduating endodontist supply.
Rotary Systems maintain installed base dominance; 3D Imaging climbs the fastest as reimbursement coding reforms advance.
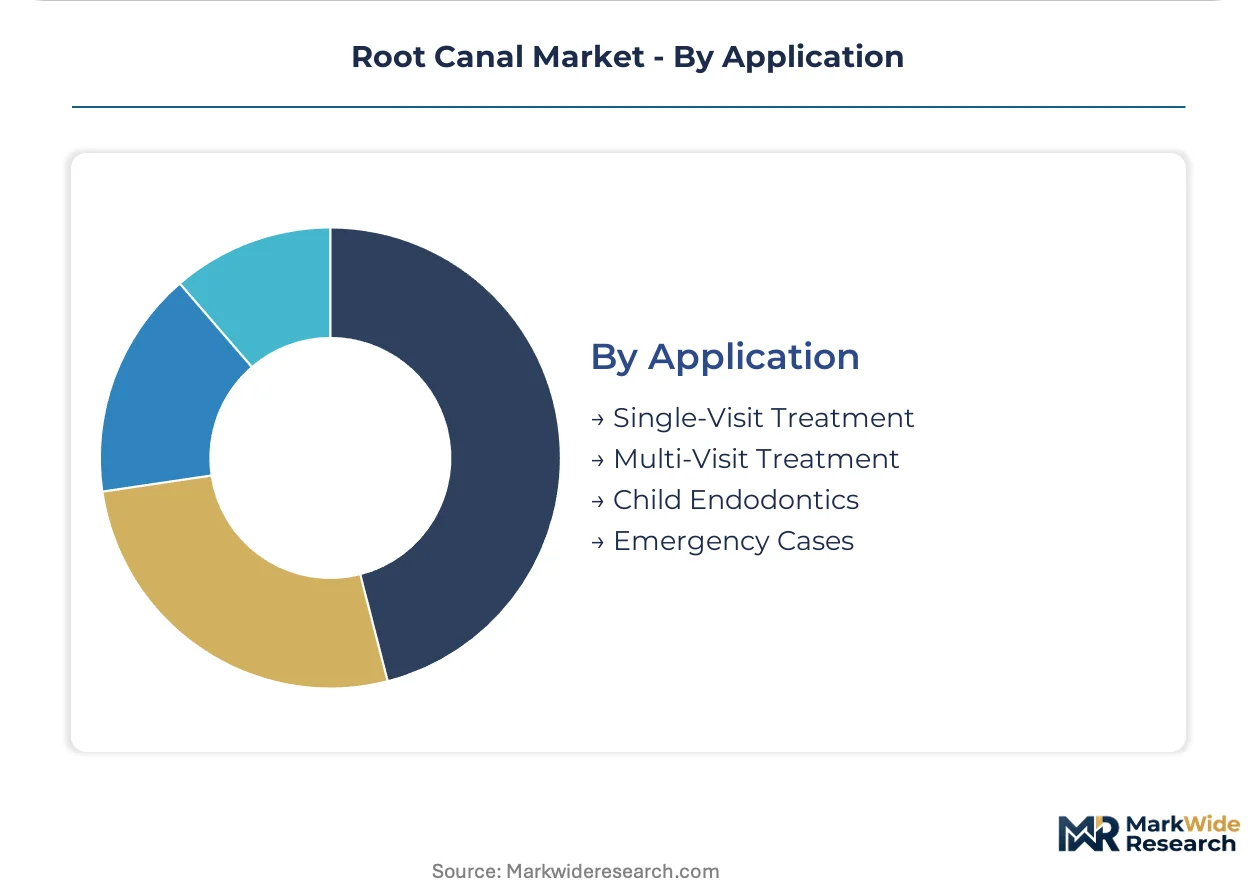
Application:
Volume segmentation distinguishes high-frequency routine procedures from complex cases requiring extended resource allocation.
- Single-Visit Treatment:Bioceramic sealer chemistry eliminates moisture sensitivity during obturation, expanding case eligibility in metropolitan practices where patient preference for same-day completion drives scheduling optimization.
- Multi-Visit Treatment:Traditional calcium hydroxide-based protocols persist for complex retreatment cases requiring extended disinfection cycles.
- Child Endodontics:Pulpotomy and apexification procedures for immature permanent teeth demand specialized file sizing and bioactive filling materials.
- Emergency Cases:Acute pain presentations requiring immediate debridement without definitive obturation completion.
Single-Visit Treatment captures the highest patient satisfaction metrics; Emergency Cases generate the most unpredictable scheduling disruption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for nickel-titanium alloy feedstock shapes regional manufacturing footprints, with Western European metallurgical suppliers commanding premium pricing and Asian fabricators securing cost-advantaged rotary file production. Export flows concentrate through specialized dental instrument trade corridors linking component manufacturers to clinic network distributors.
United States
Metropolitan dental service organizations in Texas and Florida drive capital equipment density for precision rotary systems, with clinic networks prioritizing same-visit completion protocols. The FDA's 510(k) clearance pathway structures product development timelines for instrument manufacturers seeking market access. Greater Boston anchors academic medical center adoption of cone-beam guided navigation systems for complex retreatment cases.
Germany
Bavaria's over-65 population sustains procedural volume growth for necrotic pulp interventions independent of elective dental spending cycles. The EU Medical Device Regulation's enhanced clinical evidence requirements for Class IIa instruments extend recertification timelines for legacy file systems. The Baden-Württemberg industrial corridor concentrates heat-treated nickel-titanium metallurgy suppliers serving rotary file manufacturers.
Japan
Kanto region dental clinics employ direct-hire endodontists rather than itinerant specialists, capturing full procedure revenue through in-house specialty capacity. The Pharmaceuticals and Medical Devices Agency introduced conditional early approval frameworks for digital endodontic navigation systems, accelerating commercialization timelines. Osaka-based manufacturers supply bioceramic sealer formulations to specialist practices prioritizing moisture-insensitive obturation.
Brazil
Underdeveloped endodontic service coverage in Minas Gerais and Paraná interior states creates whitespace for mobile clinic models deploying portable rotary systems. ANVISA maintains biocompatibility validation requirements for imported instruments that filter non-compliant suppliers. São Paulo's metropolitan dental networks are unbundling diagnosis from general practice referrals, establishing captive specialty capacity.
China
Yangtze River Delta fabricators produce stainless steel hand instruments for price-sensitive segments across developing Asian markets. The National Medical Products Administration's sterility validation standards shape import substitution dynamics for domestic rotary file manufacturers. Pearl River Delta dental equipment assemblers integrate cone-beam computed tomography modules from regional imaging component suppliers.
Root Canal Market Competitive Environment
On the supply side, the industry is consolidating around scaled multinational manufacturers capable of absorbing regulatory compliance burdens while mid-tier specialists retreat or seek acquisition. Three strategic archetypes dominate: integrated dental equipment conglomerates with CAD/CAM ecosystem leverage, pure-play endodontic consumable specialists commanding bioceramic formulation loyalty, and regional fabricators competing on nickel-titanium instrument cost structures. Competitive moves center on M&A absorption of MDR-burdened European suppliers and strategic partnerships linking imaging hardware to navigation software layers.
Among integrated equipment conglomerates, Dentsply Sirona Inc. and Envista Holdings Corporation exemplify the capital equipment-dominant archetype, leveraging multi-site manufacturing footprints across North America and Europe to sustain throughput scale. Ultradent Products Inc. occupies a position within the consumable-specialist tier, representing the bioceramic sealer chemistry segment where formulation differentiation commands specialist practice loyalty and resists generic substitution pressure.
| Leading Market Players |
|---|
| 3M Corporation |
| Ultradent Products Inc. |
| Dentsply Sirona Inc. |
| Brasseler USA |
| Ivoclar Vivadent Group |
| Envista Holdings Corporation |
| Septodont Inc. |
| Mani Inc. |
| Coltene Group |
| Others |
Value Chain & Pricing Dynamics
Nickel-titanium alloy feedstock concentration among Western European metallurgical suppliers determines both the premium spread for heat-treated rotary files and the geographic clustering of precision instrument manufacturing. This single-source dependency for superelastic alloys exposes endodontic instrument makers to allocation risk that compresses margins in economy-tier stainless steel segments while sustaining pricing power in premium rotary systems.
Pricing Analysis
The technology-generation pricing gap separates next-generation reciprocating nickel-titanium platforms from conventional crown-down sequences and legacy hand instrumentation. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and heat-treatment metallurgy sophistication. Pricing pressure stems from implant substitution capturing salvage cases in cost-sensitive patient segments. General practitioners exhibit highest price sensitivity for capital equipment, while specialist endodontists prioritize file longevity over per-unit cost.
Supply Chain Analysis
EU dual-use export controls on precision metallurgy equipment limit technology transfer to emerging rotary file fabricators in Asia. Manufacturing gravity centers on Germany's Baden-Württemberg corridor for nickel-titanium metallurgy, Japan's Osaka prefecture for bioceramic sealer chemistry, and China's Yangtze River Delta for stainless steel hand instruments. Feedstock draws from specialty alloy suppliers in Western Europe with limited second-source alternatives. Tariff exposure on precision-ground file blanks threatens margin structures for mid-tier suppliers. Distribution runs through dental service organization procurement consortia in metropolitan United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
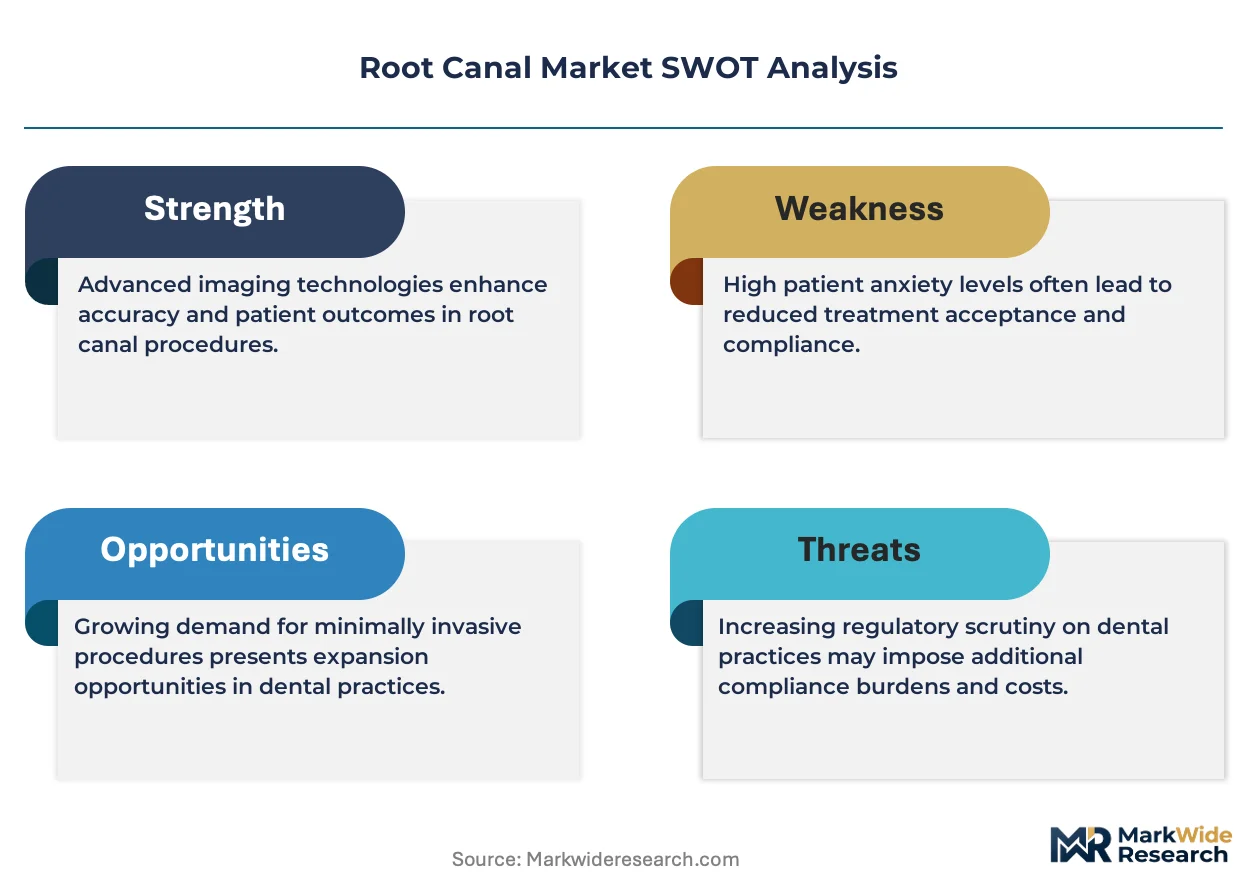
Analyst Recommendations
Dental service organization consolidation across Texas and Florida metropolitan markets has shifted procurement leverage toward buyers, forcing instrument suppliers to absorb compliance costs or cede shelf space.
For Market Incumbents:Entrench bioceramic sealer formulation loyalty through specialist practice certification programs that lock in recurring consumable revenue. Deepen backward integration into nickel-titanium alloy feedstock through captive supply agreements with Baden-Württemberg metallurgical suppliers, insulating against allocation risk from emerging Asian competitors. Prioritize EU MDR technical documentation investment to accelerate recertification timelines while smaller Italian and Spanish competitors exit.
For New Entrants and Emerging Players:Establish a beachhead in Brazil's Minas Gerais interior states where mobile clinic models deploying portable rotary systems face limited incumbent presence. Target general practitioner segments in Japan's secondary cities with simplified single-file protocols that reduce training barriers. Pursue telemedicine-supported diagnosis partnerships to bypass capital-intensive cone-beam imaging requirements.
For Investors and Strategic Acquirers:Pure-play bioceramic formulation specialists with ISO 10993 biocompatibility validation and specialist practice loyalty represent the most defensible acquisition archetype across a five-to-ten year window. Monitor PMDA conditional early approval framework utilization rates as signal for digital navigation system commercialization velocity. Track ANVISA import registration volumes for leading indicators of Brazilian market penetration timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioceramic Sealer Formulation Patent Extension | Extends mineral trioxide aggregate exclusivity against generic calcium silicate entrants in German specialist practices. |
| Heat-Treated Nickel-Titanium Metallurgy Scale-Up | Expands cyclic fatigue-resistant file production for high-volume United States dental service organizations. |
| PMDA Conditional Early Approval Navigation System | Accelerates 3D-guided instrument commercialization in Kanto region clinics ahead of reimbursement codification. |
| Mobile Clinic Partnership in Brazil Interior | Captures whitespace in Minas Gerais and Paraná through portable rotary system deployment with telemedicine support. |
| Cone-Beam Guided Therapy Reimbursement Strategy | Positions for proposed ADA code additions that would legitimize premium billing in Texas and Florida metropolitan markets. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with endodontic specialists, dental service organization procurement directors, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, PMDA approval databases, EU MDR technical documentation, hospital procurement databases, and customs trade records for nickel-titanium alloy imports. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue estimates across product categories.
Forecast inputs incorporated procedure frequency by age cohort, capital equipment replacement cycles, and reimbursement coding reform probability across the analysis window. Segmentation dimensions modeled include product type, end user archetype, technology tier, and application protocol. CAGRs derived from weighted average of historical procedural growth and technology penetration curves, with specific adjustment for bioceramic sealer substitution rates and cone-beam imaging adoption thresholds.
Sensitivities concentrate around PMDA approval timeline acceleration, EU MDR recertification bottlenecks, and nickel-titanium alloy price volatility. Forecasts reflect documented assumptions regarding single-visit protocol expansion and dental service organization consolidation velocity. Material shifts in implant substitution economics or major reimbursement coding reforms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Veneers Market
Dental Devices
Dental Hand Tools Market
Dental Devices
Saudi Arabia Dental Devices Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
Dental Microsurgery Market
Dental Devices
Single Tooth Implants and Dental Bridges Market
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
Dental Fittings Market
Dental Devices
Dental Articulators Market
Dental Devices
Dental Floss Market
Dental Devices
US Orthodontics Market
Dental Devices
North America Aligner Sheet Market
Dental Devices
Lights for Dental Healthcare Market
Dental Devices
Orthodontics Market
Dental Devices
US Dental Splint Market
Dental Devices
Dental Orthodontic Wax Market