
 Netherlands Dental Devices Market | 2026-2036
Netherlands Dental Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Dental Devices Market Foresight
Dental technician training pipelines in the Netherlands is collapsing, constraining laboratory throughput for crown, bridge, and implant abutment fabrication. Straumann Holding AG leverages its digital dentistry ecosystem to bypass traditional lab bottlenecks through chairside milling solutions. Dentsply Sirona sustains dominant channel control across Dutch dental clinics through integrated CAD/CAM sales and service networks. Henry Schein Inc competes aggressively on distribution reach, occupying the mid-market equipment and consumables tier with same-day logistics capabilities.
Dental devices encompass precision instruments, prosthetic materials, diagnostic imaging systems, and therapeutic equipment manufactured to ISO 13485 quality standards with biocompatibility requirements under ISO 10993, primarily serving oral healthcare delivery and dental laboratory production. Orthodontic appliances command mature, stable demand anchored by adolescent treatment protocols, while intraoral scanners represent the fastest-expanding product category as Dutch practices replace conventional impressions with digital workflows. CAD/CAM systems concentrate margin pools among integrated hardware-software vendors, whereas 3D printing in dental laboratories is displacing conventional casting for surgical guide and denture base production.
The Dutch Health and Youth Care Inspectorate (IGJ) enforces EU Medical Device Regulation (MDR) conformity assessments for all active implantable and Class IIb devices, elevating documentation burdens for manufacturers seeking Dutch market access. The Netherlands Standardization Institute (NEN) administers harmonized standards adoption, while the Medicines Evaluation Board (CBG-MEB) coordinates vigilance reporting for adverse incidents involving dental materials. Stakeholders must monitor evolving MDR transitional deadlines and IGJ inspection priorities to calibrate regulatory resource allocation and product portfolio certification timelines.
Market Dynamics
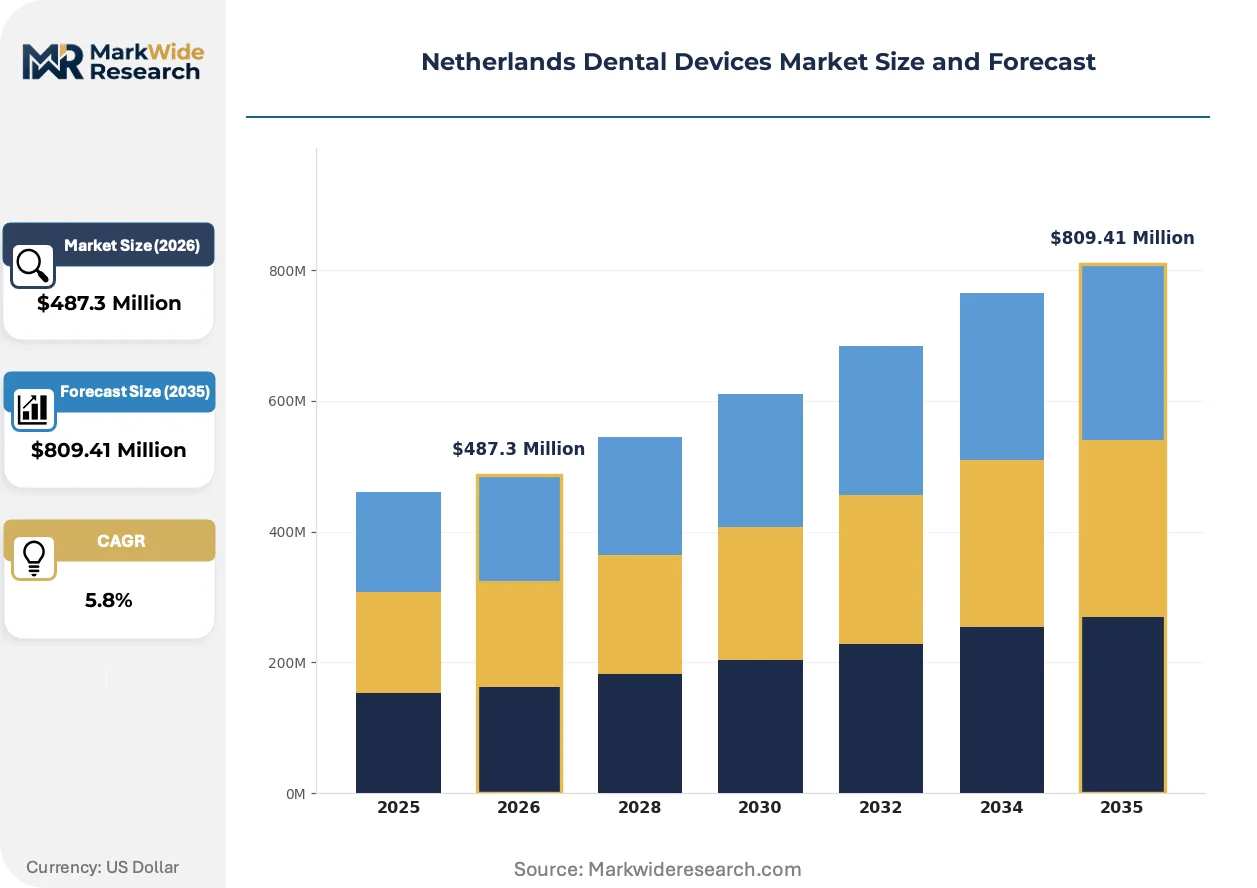
The Dutch dental devices sector is compressing through digital workflow consolidation, where chairside CAD/CAM adoption by Randstad specialist practices is collapsing the traditional dental laboratory intermediary layer and redistributing margin pools toward integrated hardware-software vendors.
Growth Catalysts
- EU Medical Device Regulation (MDR) compliance deadlines:The IGJ enforcement of Class IIb device conformity assessments is accelerating replacement cycles for legacy equipment across North Holland and Utrecht provinces.
- Intraoral scanner penetration:Amsterdam dental clusters are replacing conventional polyether impressions with digital capture systems, compressing appointment times and laboratory turnaround.
- 3D printing resin formulations:Photopolymer advances for surgical guide and denture base fabrication are enabling same-day production workflows in Dutch dental laboratories.
Market Restraints
- Biocompatible zirconia supply concentration:Sintering-grade powder sourcing depends on a limited supplier base in Germany and Japan, exposing Dutch manufacturers to input cost volatility.
- Wet op de medische hulpmiddelen vigilance reporting:The Dutch Ministry of Health's strict adverse incident documentation requirements create regulatory friction for implantable device market entry.
- Dental technician training pipeline collapse:Netherlands vocational education output for crown and bridge fabrication skills has contracted sharply, constraining laboratory throughput capacity.
Strategic Opportunities
- Zeeland and Limburg underpenetration:Rural provinces outside Randstad corridors maintain lower digital equipment density, creating whitespace for mobile CAD/CAM service models.
- AI-powered radiographic analysis:Machine learning integration with panoramic and CBCT systems is converging diagnostic imaging with treatment planning software.
- Direct-to-clinic consumables platforms:E-procurement channels are bypassing traditional dental distributor tiers for impression materials and burs in Rotterdam and The Hague clusters.
Industry Challenges
- ISO 13485 quality management recertification:Dutch manufacturers face compressed timelines for MDR-aligned documentation overhauls, straining quality assurance staffing.
- Legacy practice management system integration:Chairside milling units require API connectivity with existing patient record platforms, creating implementation friction for mid-market clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Dental Devices Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthodontic Appliances, Endodontic Devices, Dental Implants, Intraoral Scanners Application: Cosmetic Dentistry, Periodontology, Restorative Procedures, Oral Surgery End User: Dental Clinics, Hospitals, Research Institutions, Laboratories Technology: 3D Printing, CAD/CAM Systems, Digital Imaging, Laser Technology |
| Companies Covered | Ivoclar Vivadent AG, Zimmer Biomet, Dentsply Sirona, Ultradent Products Inc, Geistlich Pharma, Straumann Holding AG, Henry Schein Inc, Nakanishi Inc, 3M Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Dental Devices Market Shifts & Advancements
Digital capture and additive manufacturing technologies are restructuring the Dutch dental value chain, eliminating physical impression steps and enabling point-of-care production that bypasses conventional laboratory networks.
Photopolymer 3D printing for surgical guide and denture base production is displacing conventional lost-wax casting and vacuum-forming methods in Netherlands dental laboratories. Zeeland and North Brabant fabrication centers are adopting continuous liquid interface printing systems at accelerated pace. This transition is compressing production cycles from multi-day to same-day fulfillment while reducing precious metal consumption.
The EU Medical Device Regulation (MDR) transitional deadlines enforced by the IGJ are elevating technical documentation burdens for active implantable devices. Dutch manufacturers must submit updated clinical evaluation reports and post-market surveillance protocols. Implant abutment and endosseous fixture suppliers in the Amsterdam corridor face the steepest compliance resource reallocation.
Subscription-based equipment access models are disrupting capital-intensive CAD/CAM procurement patterns among Dutch dental practices. Specialist clinics in Utrecht and Rotterdam are replacing outright purchase with per-procedure fee structures bundled with maintenance and software updates. This shift is most visible in orthodontic and implantology verticals where utilization rates justify operational expenditure treatment.
Netherlands Dental Devices Market Segmentation
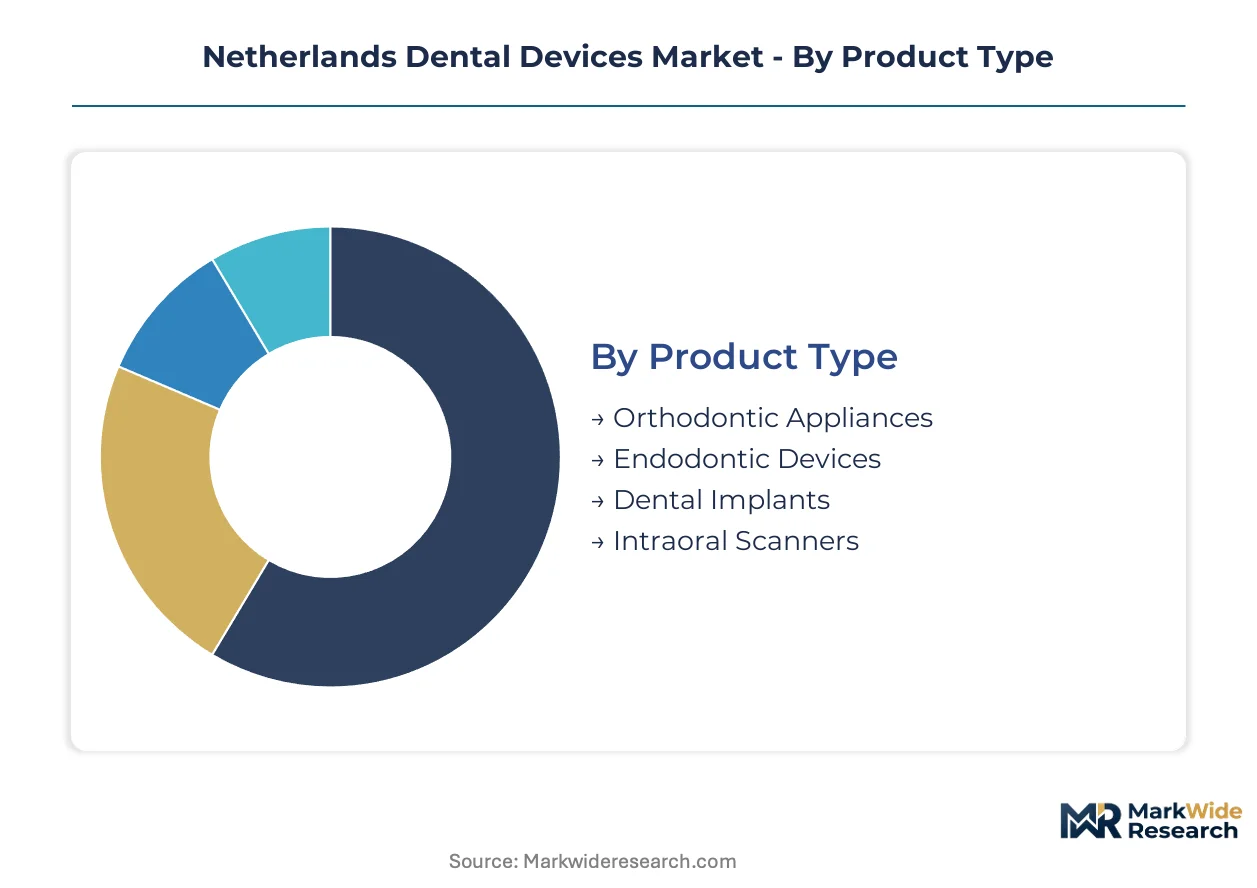
Segmentation in the Netherlands dental devices market reveals distinct procurement patterns across Randstad urban corridors versus peripheral provinces. Channel configuration varies sharply by product complexity, with premium equipment flowing through specialist distributors while consumables migrate toward direct e-procurement platforms.
Product Type:
Dutch dental practices source orthodontic appliances through orthodontic specialist networks, while implantology and digital equipment channels concentrate among integrated CAD/CAM vendors serving North Holland and Utrecht provinces.
- Orthodontic Appliances:Fixed brackets and clear aligners fabricated from biocompatible polymers serve adolescent treatment protocols across Dutch orthodontic practices. Demand concentrates in Amsterdam and Rotterdam specialist clinics where parental willingness-to-pay supports premium bracket systems and custom aligner workflows.
- Intraoral Scanners:Optical capture systems replacing conventional polyether impressions operate at 480-1200 frames per second with triangulation-based surface mapping. Randstad dental clusters in The Hague and Utrecht are replacing physical impression workflows fastest, compressing appointment times and eliminating laboratory shipping delays.
- Endodontic Devices:Nickel-titanium rotary instruments and apex locators with integrated impedance measurement serve root canal therapy across Dutch general practices.
- Dental Implants:Titanium endosseous fixtures and zirconia abutments for prosthetic rehabilitation flow through oral surgeon networks in Amsterdam and Eindhoven hospital clusters.
By volume, orthodontic appliances lead. By growth pace, intraoral scanners are expanding most quickly.
Application:
Cost tier stratification separates elective cosmetic procedures from reimbursed therapeutic interventions, with out-of-pocket payment concentration in North Holland aesthetic clinics versus insurance-covered periodontology in broader provincial networks.
- Restorative Procedures:Crown, bridge, and direct composite interventions constitute the procedural backbone of Dutch general dental practice. Volume concentrates across mid-market clinics in South Holland and North Brabant where aging dentitions drive recurrent intervention need.
- Cosmetic Dentistry:Veneer, whitening, and aesthetic alignment services command premium pricing in Amsterdam canal district practices serving affluent professional demographics. Patient self-pay dynamics isolate this segment from insurance reimbursement constraints affecting therapeutic categories.
- Periodontology:Scaling, root planing, and guided tissue regeneration address gum disease prevalence among Netherlands aging populations.
- Oral Surgery:Extraction, implant placement, and orthognathic procedures concentrate in university hospital settings across Leiden and Groningen.
Restorative procedures generate the highest absolute procedure volume. Cosmetic dentistry carries the steepest margin expansion trajectory.
End User:
Customer type determines procurement sophistication, with Randstad dental clinics adopting subscription-based CAD/CAM access while hospital systems negotiate capital equipment through centralized tender processes.
- Dental Clinics:Private practices across the Netherlands constitute the primary demand node for chairside equipment and consumables. Amsterdam and Rotterdam specialist clinics are consolidating toward digital workflow platforms with integrated practice management connectivity.
- Laboratories:Prosthetic fabrication centers in North Holland and Zeeland are transitioning from conventional casting to additive manufacturing for surgical guide production. Technician workforce constraints are compressing throughput capacity and accelerating automation investment.
- Hospitals:Academic medical centers in Utrecht and Leiden manage complex oral surgery and trauma cases requiring advanced imaging and implant systems.
- Research Institutions:University dental schools in Amsterdam and Nijmegen drive clinical validation for novel biomaterials and digital workflow protocols.
Dental clinics dominate unit volume. Laboratories are gaining share fastest as chairside production shifts workload from practice to centralized fabrication.
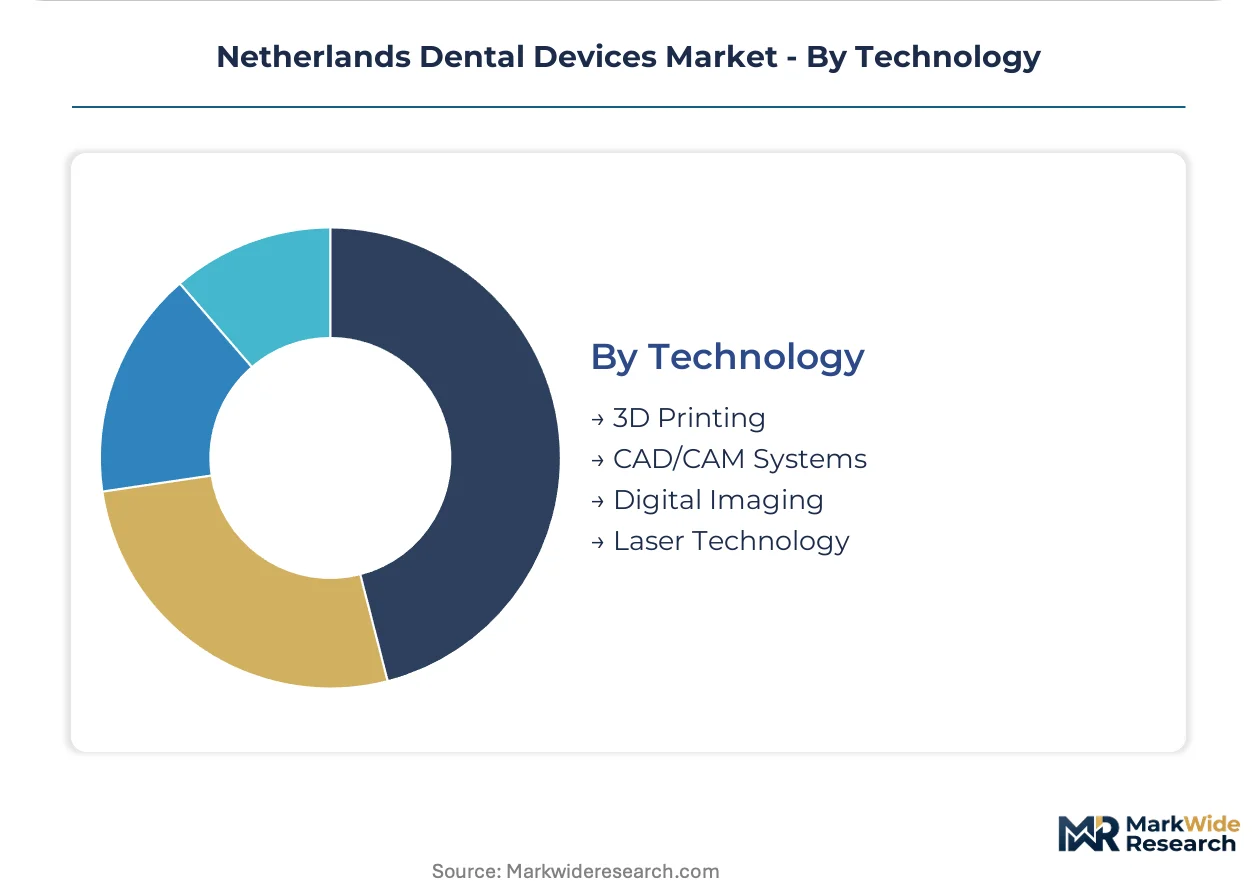
Technology:
Supply concentration in German and Japanese component sources shapes technology adoption timelines, with Dutch laboratories prioritizing resin formulations and milling burs available through established EU distribution channels.
- CAD/CAM Systems:Integrated computer-aided design and manufacturing platforms enable same-day crown production through chairside milling or central laboratory fabrication. North Holland specialist practices are adopting subscription access models over capital purchase, bundling software updates and maintenance into per-procedure fees.
- 3D Printing:Photopolymer stereolithography and digital light processing systems fabricate surgical guides, denture bases, and orthodontic models without conventional casting steps. Zeeland and Limburg laboratories lacking technician capacity are adopting continuous liquid interface printing fastest to compress production cycles.
- Digital Imaging:Panoramic radiography and cone-beam computed tomography systems serve diagnostic and treatment planning functions across Dutch oral surgery practices.
- Laser Technology:Erbium and diode laser systems address soft tissue procedures and caries removal in select Amsterdam and The Hague specialist clinics.
CAD/CAM systems anchor current installed base value. 3D printing represents the fastest-growing trajectory as laboratory automation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Randstad urban corridors consume dental devices through premium specialist channels, while peripheral provinces rely on general practice networks with slower digital adoption curves.
Randstad
Amsterdam, Rotterdam, The Hague and Utrecht concentrate three-quarters of Dutch dental device procurement through private specialist clinics and academic medical centers. The Dutch Health and Youth Care Inspectorate enforces EU MDR conformity assessments most intensively in this corridor, accelerating replacement cycles for legacy imaging and implant systems. Amsterdam's canal district aesthetic practices drive premium intraoral scanner and chairside milling unit demand.
North Brabant
Eindhoven's hospital clusters and Tilburg specialist networks anchor implantology and oral surgery device consumption in this southern province. The Wet op de medische hulpmiddelen mandates strict vigilance reporting for adverse incidents involving endosseous fixtures, elevating documentation burdens for suppliers serving this region. Eindhoven fabrication laboratories are transitioning fastest to photopolymer 3D printing for surgical guide production.
Zeeland
Rural dental practices in this southwestern province maintain lower digital equipment density than Randstad benchmarks, creating whitespace for mobile CAD/CAM service models and shared laboratory facilities. The Netherlands Standardization Institute administers harmonized standards adoption across provincial borders, ensuring uniform MDR compliance requirements. Middelburg and Vlissingen general practices rely on centralized Rotterdam laboratories for crown and bridge fabrication.
Limburg
Maastricht's university medical center anchors complex oral surgery and trauma reconstruction device demand in this southeastern province bordering Germany and Belgium. Cross-border patient flows from Aachen and Liège supplement domestic procedural volumes for advanced implant and regenerative material applications. Maastricht academic dental school drives clinical validation protocols for novel biomaterials deployed across Dutch and neighboring markets.
Northern Netherlands
Groningen and Leeuwarden hospital systems manage dispersed rural populations through general practice networks with concentrated oral surgery referrals to academic centers. The Medicines Evaluation Board coordinates post-market surveillance reporting for dental materials across this region's smaller laboratory base. Groningen University Medical Center maintains the northern Netherlands' only comprehensive maxillofacial surgery unit.
Netherlands Dental Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Dutch dental devices. The upper tier controls CAD/CAM hardware-software ecosystems and implant-abutment platforms that lock in recurring consumables revenue. Mid-tier distributors compete on logistics velocity and same-day fulfillment for chairside consumables. Fragmented laboratory equipment suppliers occupy the base with commodity milling burs and resin formulations. Dominant competitive moves include subscription-based equipment access models replacing capital purchase, and backward integration into zirconia powder sourcing to secure input cost stability.
Among Swiss-anchored implant and prosthetic specialists, Straumann Holding AG and Geistlich Pharma occupy positions exemplifying integrated digital dentistry ecosystems and regenerative biomaterial platforms respectively. Dentsply Sirona represents the consolidated dental equipment archetype with channel control across Dutch clinic networks through combined hardware-software-service offerings. These three entities anchor distinct competitive vectors: implant-prosthetic integration, biomaterial science, and full-workflow digitization.
| Leading Market Players |
|---|
| Ivoclar Vivadent AG |
| Zimmer Biomet |
| Dentsply Sirona |
| Ultradent Products Inc |
| Geistlich Pharma |
| Straumann Holding AG |
| Henry Schein Inc |
| Nakanishi Inc |
| 3M Company |
| Others |
Supply & Pricing Matrix
Per-procedure fee structures bundled with software updates and maintenance lock in supply access for Dutch dental practices while compressing upfront capital exposure into predictable operational expenditure. This contract pattern anchors price visibility across Randstad specialist clinics navigating EU MDR compliance cost absorption and technician workforce constraints.
Pricing Analysis
Subscription-based equipment access dominates Dutch CAD/CAM procurement, with per-procedure fee structures replacing capital purchase across North Holland and Utrecht specialist practices. Price differentiation separates premium integrated hardware-software ecosystems from mid-market distribution tiers competing on logistics velocity and same-day consumables fulfillment. Cost compression in mid-market equipment intensifies as Henry Schein and regional distributors compete for chairside consumables share. General practices in Zeeland and Limburg exhibit highest price sensitivity, while Amsterdam aesthetic clinics absorb premium positioning for intraoral scanners and chairside milling units.
Supply Chain Analysis
Germany and Japan anchor sintering-grade zirconia powder supply for Dutch dental laboratories, with photopolymer resin formulations increasingly sourced through established EU distribution channels. Dutch manufacturers draw from German milling bur suppliers and Japanese optical component producers for intraoral scanner assembly. Single-source vulnerability concentrates in biocompatible zirconia feedstock, exposing fabrication centers to input cost volatility. Distribution runs through integrated CAD/CAM vendors controlling premium equipment channels, while consumables migrate toward direct e-procurement platforms bypassing traditional dental distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
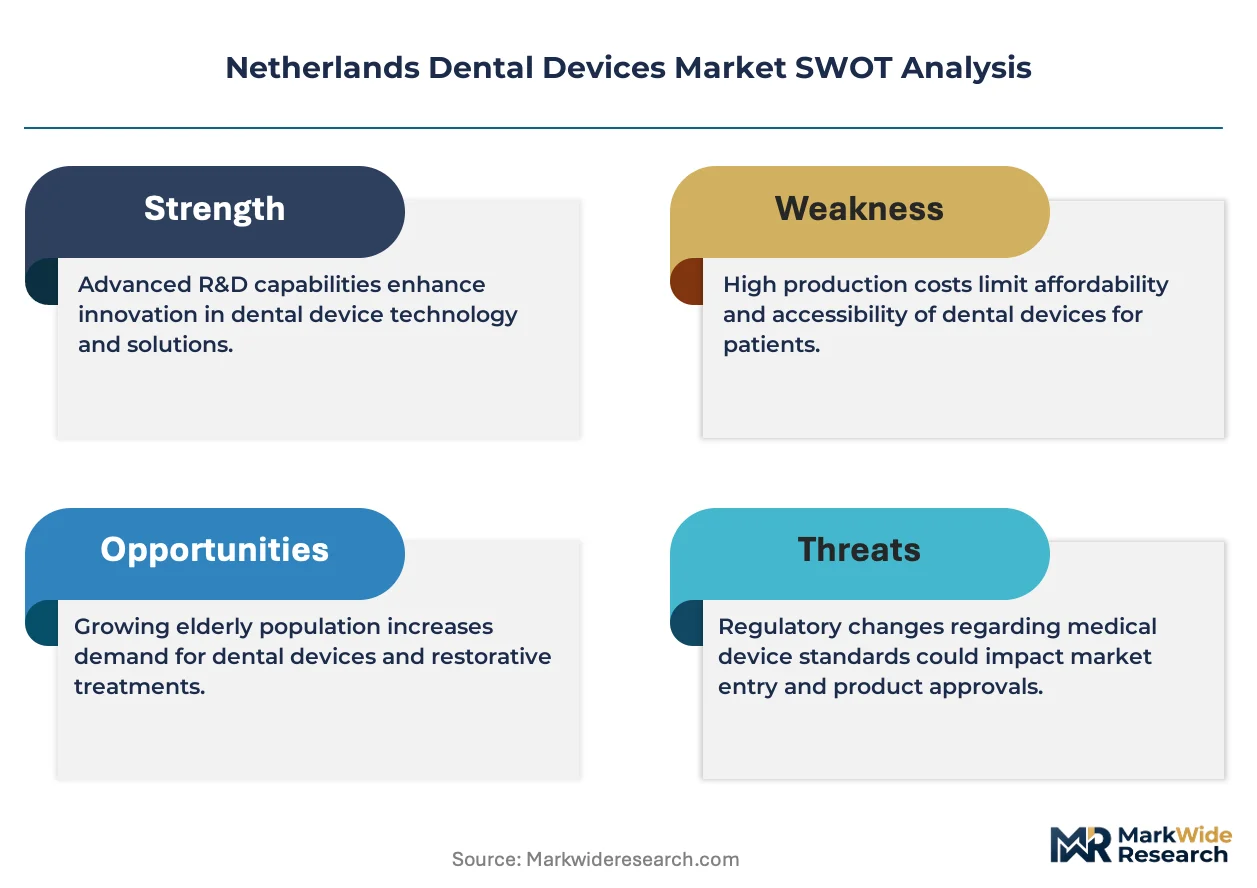
Digital workflow substitution threatens traditional dental laboratory intermediation, forcing incumbents to defend integrated ecosystem positions against chairside production displacement and technician workforce collapse.
For Market Incumbents: Secure backward integration into zirconia powder sourcing to stabilize input cost exposure against German and Japanese supply concentration. Lock in API connectivity with legacy practice management systems to reduce implementation friction for mid-market clinic CAD/CAM adoption. Defend against Straumann's chairside milling bypass by embedding consumables lock-in through proprietary abutment interfaces and subscription renewal structures.
For New Entrants and Emerging Players: Lead with mobile CAD/CAM service models targeting Zeeland and Limburg underpenetration, where rural practices lack capital for digital equipment acquisition. Capture whitespace in AI-powered radiographic analysis converging diagnostic imaging with treatment planning software. Position through direct-to-clinic consumables platforms bypassing traditional distributor tiers for impression materials and burs in Rotterdam and The Hague clusters.
For Investors and Strategic Acquirers: Specialized biomaterial developers with EU MDR certification traction represent priority acquisition targets as regulatory documentation burdens elevate barriers for novel implant surface technologies. Long-term viability hinges on MDR-aligned quality management infrastructure and post-market surveillance capability rather than pure product innovation. Monitor IGJ inspection priority shifts and MDR transitional deadline enforcement as inflection signals for compliance resource reallocation across Dutch market access.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | IGJ enforcement of EU MDR conformity assessments accelerates legacy equipment replacement cycles across North Holland. |
| Hospital System Partnership | Academic medical centers in Utrecht and Leiden anchor complex oral surgery device procurement through centralized tender processes. |
| Software Companion Development | API connectivity with patient record platforms reduces implementation friction for chairside milling unit adoption. |
| Reimbursement Strategy | Insurance coverage dynamics separate reimbursed periodontology from out-of-pocket cosmetic procedures in Amsterdam aesthetic clinics. |
| Backward Integration | In-house zirconia powder sourcing insulates Dutch manufacturers from German and Japanese supply concentration volatility. |
Research Methodology
A spread of perspectives from dental laboratory technicians, clinic practice managers, biomedical engineers at academic medical centers, and IGJ regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against EU MDR transitional deadline documentation, NEN harmonized standards adoption records, and CBG-MEB vigilance reporting databases. Customs records for zirconia powder imports and dental equipment trade flows anchored supply-side triangulation against bottom-up clinic procurement surveys across Randstad and peripheral provinces.
Segmentation dimensions modeled span product type, application, end user, and technology adoption intensity across the projection horizon. Analytical framework disaggregates orthodontic appliances, intraoral scanners, endodontic devices, and dental implants by restorative, cosmetic, periodontology, and oral surgery applications. CAGRs derive from procedure volume elasticity to aging dentition demographics, digital workflow penetration curves, and MDR-driven replacement cycle acceleration. Forecast inputs incorporate technician training pipeline contraction rates and photopolymer 3D printing adoption velocity in Zeeland and North Brabant laboratories.
Forecasts assume regulatory continuity in EU MDR enforcement timelines and Wet op de medische hulpmiddelen vigilance reporting requirements; material policy shifts would require re-modeling compliance cost absorption and certification timeline assumptions. Specific risks include IGJ inspection priority reallocation, zirconia supply disruption from German or Japanese sources, and accelerated chairside production substitution collapsing laboratory intermediary revenue pools. Recalibration cycles align with material shifts in MDR transitional deadlines, technician workforce output, and digital equipment penetration thresholds across Randstad versus peripheral provinces.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Healing Caps Market
Dental Devices
Global Endodontics Market
Dental Devices
Dental Hand Tools Market
Dental Devices
Global Dental Labs Market
Dental Devices
Subperiosteal Dental Implants Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
Global Dental Turbine Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Electric Dental Handpieces Market
Dental Devices
Dental Forceps Market
Dental Devices
Italy Dental Devices Market
Dental Devices
Europe Dental Lab Market
Dental Devices
Digital Dental Cameras Market
Dental Devices
Dental Air Polishers Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Dental Composite Filling Market