
 Global Adult and Pediatric Hemoconcentrators Market | 2026-2036
Global Adult and Pediatric Hemoconcentrators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adult and Pediatric Hemoconcentrators Market Foresight
Germany is reconfiguring its extracorporeal device manufacturing footprint through targeted capacity investments in Baden-Württemberg and Bavaria. Medtronic plc leverages integrated perfusion technology platforms to sustain leadership across cardiac surgery suites. LivaNova PLC anchors European supply through specialized hemoconcentrator production lines. Terumo Cardiovascular Systems Corporation competes on membrane filtration innovation in the Asia-Pacific theater.
Hemoconcentrators are blood processing devices that remove plasma water and low-molecular-weight solutes during cardiopulmonary bypass, typically employing hollow-fiber membrane technology with pore sizes between 0.2 and 0.6 microns to achieve hematocrit elevation without significant protein loss. The membrane filter segment dominates current procurement volumes due to established clinical validation and predictable performance parameters. Ultrafiltration devices are gaining procedural share in complex cardiac cases where precise volume management determines outcomes. Gravity filtration technology occupies the value-tier position while continuous flow systems command premium placement in high-throughput surgical centers.
The FDA maintains Class II device controls over hemoconcentrators through 510(k) premarket notification requirements, while the EU MDR imposes enhanced clinical evidence standards for blood-contacting perfusion components. ISO 10993 biocompatibility testing and IEC 60601 electrical safety protocols shape product development timelines and certification costs. Stakeholders must monitor evolving notified body capacity constraints in Europe and anticipate how updated FDA guidance on perfusion accessories will alter predicate device strategies.
Market Dynamics
Hollow-fiber membrane miniaturization is compressing device footprints while elevating filtration precision, forcing manufacturers to recalibrate production lines around sub-micron pore consistency.
Growth Catalysts
- EU MDR clinical evidence mandates:Enhanced documentation requirements for blood-contacting perfusion components are filtering out marginal suppliers and consolidating procurement toward validated device platforms.
- Pediatric cardiac surgery expansion:Specialized hemoconcentrator formats for low-prime-volume circuits are capturing procedural share in children's hospital networks across Japan and Germany.
- Continuous ultrafiltration protocols:Real-time hematocrit management during prolonged bypass procedures is virtualizing gravity-dependent filtration in complex aortic reconstructions.
Market Restraints
- Polyethersulfone membrane cost volatility:Specialized polymer feedstocks for hollow-fiber production face price instability tied to petrochemical supply chains.
- Notified body capacity constraints:EU MDR certification bottlenecks in Germany and the Netherlands are extending product launch timelines by 12-18 months.
- Zero-balanced ultrafiltration substitution:Modified dialysis-based volume control methods are displacing standalone hemoconcentrators in select renal-cardiac hybrid procedures.
Strategic Opportunities
- India tertiary cardiac center buildout:Greenfield hospital construction in Chennai and Hyderabad is creating first-mover advantage for perfusion technology suppliers.
- Integrated bypass circuit convergence:Hemoconcentrator-oxygenator module unification is reducing priming volume and disposable count in single-use cartridge formats.
- Japan PMDA fast-track pathway:Breakthrough device designation for pediatric-specific blood management tools accelerates regulatory access.
Industry Challenges
- Perfusionist workforce scarcity:Specialized cardiac surgery technologist training programs in the United States and Germany are failing to match retirement-driven attrition.
- Legacy circuit integration friction:Retrofitting continuous-flow hemoconcentrators into installed base oxygenator consoles requires proprietary connector adaptation.
- ISO 10993-4 hemocompatibility testing backlog:Thrombogenicity assay capacity constraints at contract laboratories are compressing development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adult and Pediatric Hemoconcentrators Market |
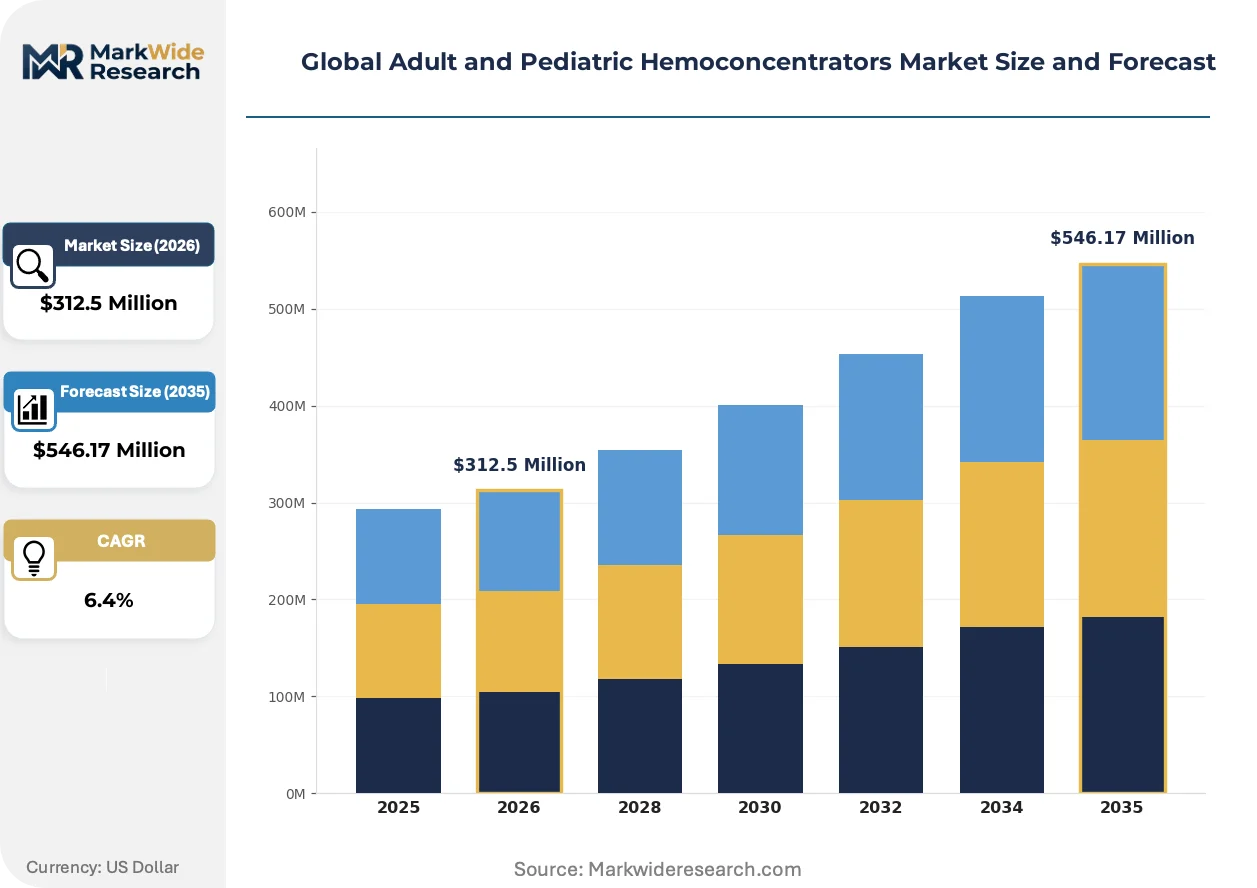
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filter, Centrifugal Separator, Ultrafiltration Device, Dialysis Concentrator Application: Cardiac Surgery, Liver Transplantation, Burn Treatment, Trauma Management, Blood Volume Management End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Emergency Care Units Technology: Gravity Filtration, Continuous Flow, Pulsatile Flow, Pressure Filtration |
| Companies Covered | Medtronic plc, LivaNova PLC, Terumo Cardiovascular Systems Corporation, Getinge AB, Nipro Corporation, Medivators Inc., Andocor NV, Medica S.p.A., MAQUET Holding B.V. & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adult and Pediatric Hemoconcentrators Market Shifts & Advancements
Membrane science convergence with digital perfusion monitoring is redefining real-time blood management during cardiac surgery, compressing the gap between filtration performance and clinical decision support.
Polysulfone-polyvinylpyrrolidone blend membranes with asymmetric pore architecture are achieving selective water removal while preserving albumin and coagulation factors. High-volume cardiac surgery centers in the United States are standardizing on these formats for complex valve replacements. This materials shift is virtualizing conventional cellulose-based filtration in premium procedure tiers.
EU MDR Article 10 technical documentation requirements now mandate clinical performance data for all Class IIa blood-contacting perfusion accessories. Manufacturers must submit post-market surveillance plans with defined safety endpoints. Pediatric device categories face the steepest compliance burden due to limited predicate device availability.
Hospital procurement committees are consolidating hemoconcentrator purchasing into multi-year oxygenator and arterial filter contracts. Integrated circuit suppliers capture bundled volume while standalone device vendors face margin compression. This concentration pattern is most visible in German and Japanese university hospital networks where perfusion standardization committees control formulary decisions.
Global Adult and Pediatric Hemoconcentrators Market Segmentation
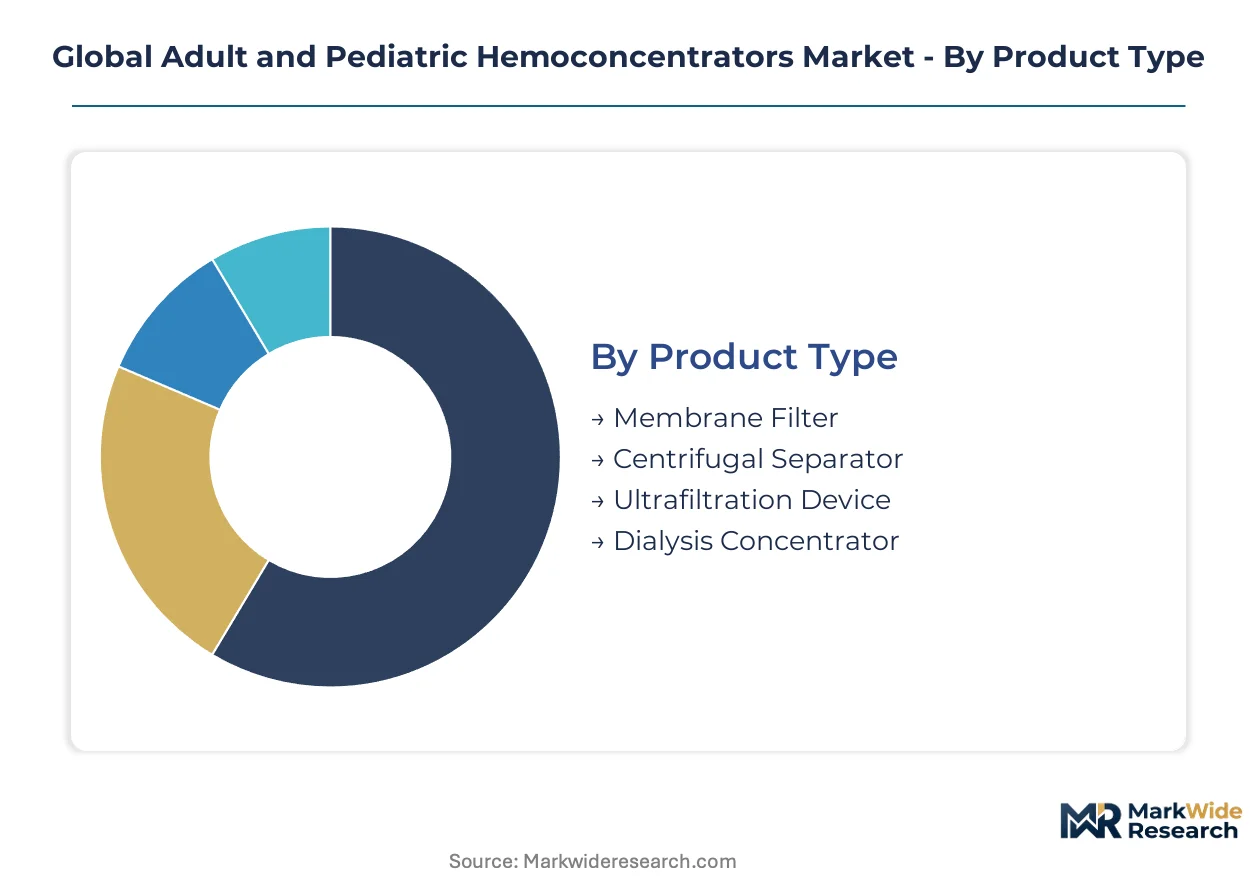
Hemoconcentrator procurement patterns diverge sharply across clinical settings, with membrane technology dominating cardiac suites while centrifugal formats serve specialized transplant programs. Understanding these segment boundaries illuminates where manufacturers must differentiate specifications versus compete on interchangeability.
Product Type:
Mature hollow-fiber platforms anchor current revenue, though emerging modalities are capturing complex-case volume through precision filtration capabilities.
- Membrane Filter:Hollow-fiber configurations with 0.2-0.6 micron polysulfone or polyethersulfone matrices deliver predictable hematocrit elevation without significant protein loss. German university hospital networks standardize procurement on these formats for routine coronary artery bypass procedures, driven by established clinical validation and streamlined perfusionist training protocols.
- Ultrafiltration Device:Continuous-flow systems enable real-time volume management during prolonged cardiopulmonary bypass through automated feedback loops. United States high-volume cardiac centers deploy these in complex aortic reconstructions where precise ultrafiltration rates determine patient outcomes, constrained by premium pricing and specialized console requirements.
- Centrifugal Separator:Rotational force separation technologies serve liver transplantation programs requiring rapid plasma water removal with minimal hemolysis.
- Dialysis Concentrator:Hybrid renal-cardiac platforms occupy niche positioning in hybrid procedure suites.
Membrane filters handle the majority of throughput; ultrafiltration devices are expanding most quickly on share.
Application:
Volume concentrates in cardiovascular intervention, though trauma and burn applications present untapped procedural expansion corridors.
- Cardiac Surgery:Coronary artery bypass grafting, valve replacement, and congenital defect correction constitute the core demand channel. Japanese and German surgical volumes sustain procurement of both adult and pediatric circuit formats, with pediatric-specific low-prime designs gaining traction in children's hospital networks.
- Blood Volume Management:Perioperative fluid control across non-cardiac major surgery represents an emerging indication. United States academic medical centers pilot hemoconcentrator integration in major orthopedic and oncology resections where aggressive fluid resuscitation complicates recovery, limited by reimbursement coding ambiguity.
- Liver Transplantation:Specialized centrifugal applications address massive transfusion protocols in hepatic surgery.
- Burn Treatment:Plasma water removal supports fluid management in extensive thermal injury cases.
- Trauma Management:Emergency deployment in hemorrhagic shock protocols remains experimental across most jurisdictions.
Cardiac surgery absorbs the dominant procedure share; blood volume management applications are climbing the fastest.
End User:
Customer concentration patterns reflect capital intensity and perfusionist workforce availability across care delivery models.
- Hospitals:Tertiary cardiac surgery centers with dedicated perfusion departments drive procurement of integrated circuit platforms. German and Japanese university hospitals bundle hemoconcentrator purchasing with oxygenator and arterial filter contracts, compressing standalone vendor margins through multi-year standardization agreements.
- Ambulatory Surgical Centers:Limited adoption due to procedure complexity constraints and capital equipment requirements.
- Specialty Clinics:Cardiovascular-focused outpatient facilities in the United States explore selective hemoconcentrator deployment for diagnostic cardiac catheterization with planned intervention.
- Emergency Care Units:Pre-hospital and emergency department applications remain confined to military and mass casualty preparedness programs.
Hospitals command the installed base; specialty clinics represent the steepest expansion trajectory among customer categories.
Technology:
Filtration mechanics separate premium automation from value-tier gravity dependence across price-sensitive procurement tiers.
- Continuous Flow:Automated pump-driven systems with integrated hematocrit sensors enable precise real-time adjustment. High-throughput United States surgical centers deploy these in complex multi-valve procedures, supported by favorable outcomes data and perfusionist preference for hands-off monitoring during prolonged bypass.
- Gravity Filtration:Passive hydrostatic pressure systems occupy the value tier through lower disposable costs and simplified training requirements. Indian and Southeast Asian hospital construction projects specify these formats for initial perfusion program establishment, constrained by slower filtration rates and less precise volume control.
- Pulsatile Flow:Cyclic pressure variation mimics physiological perfusion patterns in select research applications.
- Pressure Filtration:External pump-assisted gravity hybrid formats serve mid-tier positioning in European community hospitals.
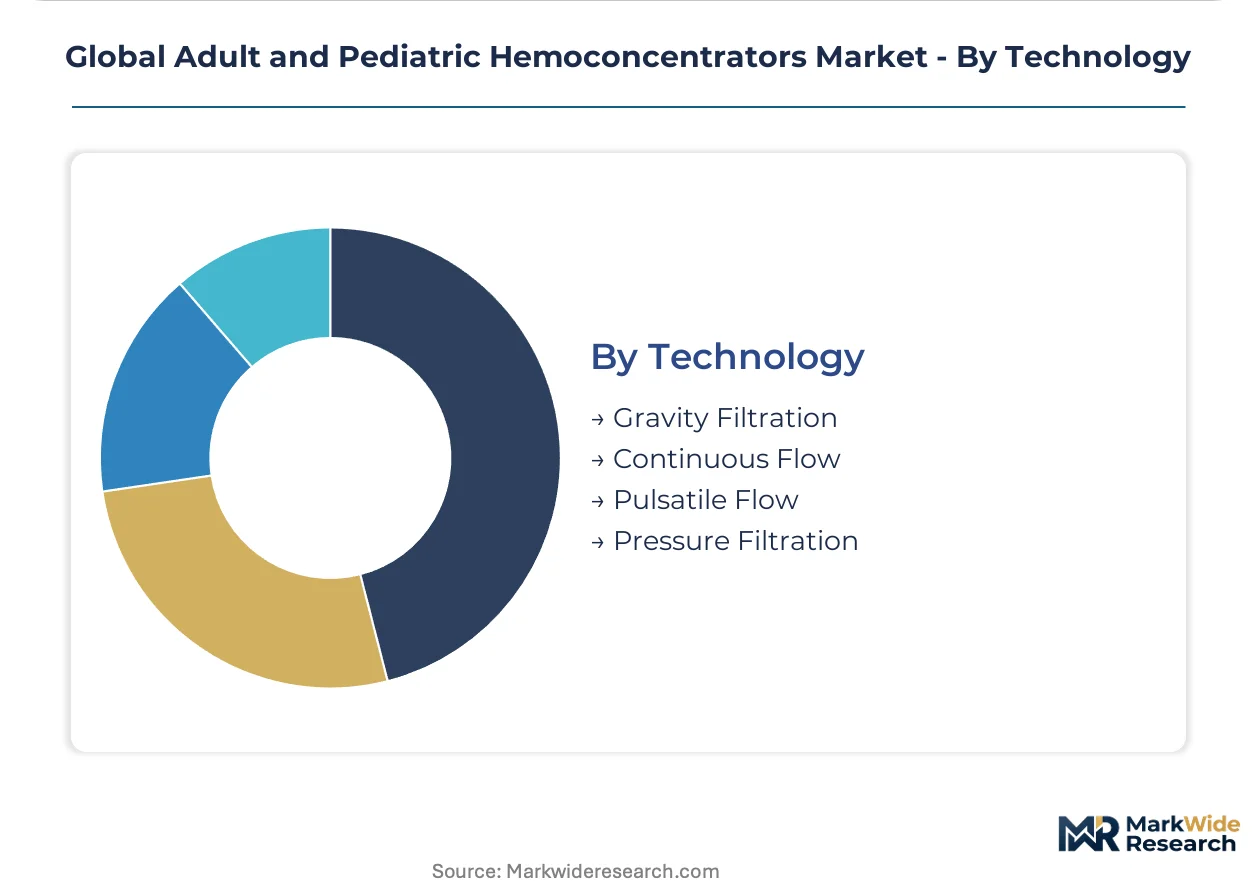
Continuous flow systems dominate premium procedure volume; gravity filtration maintains the broadest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys hemoconcentrators predominantly in high-complexity cardiac suites with continuous-flow automation, while Germany and Japan favor integrated circuit platforms bundled with oxygenator procurement; India and emerging Asian markets still rely on gravity-filtration value tiers for initial perfusion program establishment.
United States
High-volume cardiac surgery centers in Cleveland and Houston drive demand for real-time hematocrit management during complex aortic reconstructions. The FDA maintains Class II device controls through 510(k) premarket notification requirements, tightening predicate device strategies for blood-contacting perfusion accessories. Boston and New York Metro academic medical centers pilot hemoconcentrator integration in major orthopedic resections, expanding beyond traditional cardiac applications.
Germany
University hospital networks in Baden-Württemberg and Bavaria standardize procurement on hollow-fiber membrane formats for routine coronary artery bypass procedures. The EU MDR imposes enhanced clinical evidence standards for Class IIa blood-contacting components, filtering marginal suppliers toward validated platforms. Perfusionsstandardisierungsausschüsse in Heidelberg and Munich control multi-year bundled contracts compressing standalone vendor margins.
Japan
Children's hospital networks in Tokyo and Osaka capture specialized pediatric-specific low-prime circuit formats. The PMDA fast-track pathway accelerates breakthrough device designation for pediatric blood management tools, shortening regulatory access timelines. Nagoya and Kyoto surgical centers deploy continuous ultrafiltration protocols in complex multi-valve procedures.
India
Greenfield tertiary cardiac center construction in Chennai and Hyderabad creates first-mover advantage for perfusion technology suppliers entering previously unserved markets. The CDSCO regulates medical devices under the Medical Device Rules, with hemoconcentrators falling under notified device categories requiring import registration. Gravity filtration systems dominate initial procurement specifications due to capital constraints and simplified training requirements.
China
Provincial cardiovascular centers in Shanghai and Beijing expand extracorporeal membrane oxygenation capabilities, creating adjacent demand for integrated blood management components. The NMPA oversees Class II and Class III medical device registration through technical review and clinical trial requirements. Yangtze River Delta manufacturing clusters develop domestic hollow-fiber membrane capacity to reduce import dependence.
Global Adult and Pediatric Hemoconcentrators Market Competitive Landscape
Capability concentration sits with integrated perfusion technology platforms; scale advantage sits with diversified cardiovascular device conglomerates. The market structure bifurcates between premium-tier suppliers bundling hemoconcentrators with oxygenator-arial filter contracts and standalone device vendors facing procurement committee margin compression. Three archetypes dominate: integrated circuit platform owners, specialized membrane filtration specialists, and regional value-tier fabricators. Competitive moves center on M&A consolidation of notified body-certified manufacturing assets and strategic partnerships with university hospital standardization committees.
Within the integrated platform tier, Medtronic plc and LivaNova PLC exemplify the bundling archetype that captures multi-year hospital contracts through oxygenator-hemoconcentrator module unification. Terumo Cardiovascular Systems Corporation occupies a position among Asia-Pacific-focused membrane innovation specialists, while Getinge AB and Nipro Corporation represent diversified cardiovascular conglomerates leveraging cross-product scale economies. MAQUET Holding B.V. & Co. KG and Medivators Inc. sit within the European and North American mid-tier respectively, where regional regulatory proximity and perfusionist training relationships sustain positioning against consolidated procurement.
| Leading Market Players |
|---|
| Medtronic plc |
| LivaNova PLC |
| Terumo Cardiovascular Systems Corporation |
| Getinge AB |
| Nipro Corporation |
| Medivators Inc. |
| Andocor NV |
| Medica S.p.A. |
| MAQUET Holding B.V. & Co. KG |
| Others |
Supply & Pricing Matrix
German hollow-fiber membrane manufacturing clusters in Baden-Württemberg and Bavaria concentrate polysulfone and polyethersulfone feedstock processing, anchoring margin capture in the premium device tier while compressing value-tier suppliers dependent on Asian polymer sourcing.
Pricing Analysis
Long-term bundled contracts dominate procurement, with German and Japanese university hospitals locking oxygenator-hemoconcentrator-arterial filter combinations through multi-year standardization agreements. Price differentiation rests on FDA 510(k) clearance tier and ISO 10993-4 hemocompatibility certification depth, with premium continuous-flow systems commanding substantial markups over gravity filtration alternatives. Pricing pressure intensifies as hospital GPOs consolidate vendor panels and demand volume rebates. Standalone hemoconcentrator vendors face acute price sensitivity in Indian greenfield installations, while integrated platform owners retain leverage in Cleveland and Houston cardiac centers.
Supply Chain Analysis
Extended payment terms from German notified body-certified manufacturers to Southeast Asian polymer distributors characterize working capital dynamics in this sector. Raw material sourcing concentrates on Saudi and Qatari petrochemical feedstocks for polysulfone production, Japanese precision spinning equipment for hollow-fiber formation, and US membrane coating technologies. Single-source vulnerability in EU MDR-notified body capacity creates regulatory chokepoint risk. Distribution runs through cardiovascular device GPOs in the United States, university hospital standardization committees in Germany, and regional distributors serving Indian tertiary center buildouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
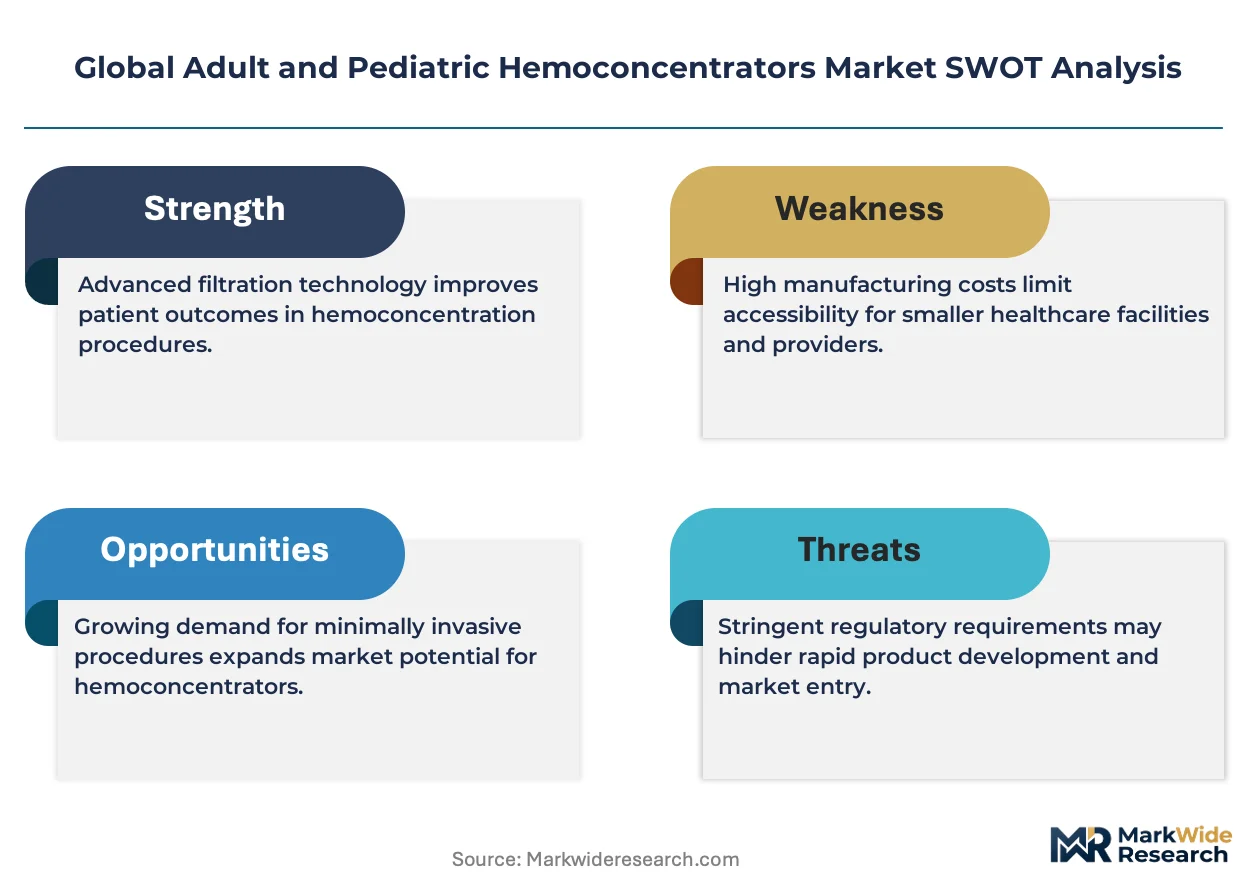
Zero-balanced ultrafiltration substitution and modified dialysis-based volume control methods threaten standalone hemoconcentrator positioning, forcing incumbents to demonstrate superior hematocrit precision in complex aortic reconstructions.
For Market Incumbents: Pre-empt substitution by integrating real-time hematocrit sensors with automated feedback loops in next-generation continuous-flow platforms. Deepen backward integration into hollow-fiber membrane production to insulate margin from polyethersulfone cost volatility. Secure exclusive multi-year contracts with German Perfusionsstandardisierungsausschüsse before EU MDR consolidation completes.
For New Entrants and Emerging Players: Indian tertiary cardiac center construction in Chennai and Hyderabad offers the most penetrable geographic entry point, with gravity filtration specifications dominating initial procurement and lower regulatory barriers than FDA or EU MDR pathways. Target pediatric-specific low-prime circuit formats where predicate device scarcity limits incumbent advantage. Pursue CDSCO import registration partnerships with established distributors rather than direct sales infrastructure.
For Investors and Strategic Acquirers: Capital is best deployed toward diversified cardiovascular conglomerates with integrated perfusion platforms and existing notified body-certified manufacturing footprints. Long-term viability hinges on bundling capability across oxygenator, hemoconcentrator, and arterial filter categories. Watch PMDA breakthrough device designations for pediatric blood management tools as signal of regulatory access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Enhanced clinical evidence requirements filter marginal suppliers toward validated device platforms. |
| Hospital System Partnership | Bundled procurement contracts with German university networks compress standalone vendor margins. |
| Backward Integration into Membrane Production | In-house polysulfone spinning capacity insulates margin from petrochemical feedstock volatility. |
| Pediatric-Specific Format Development | Low-prime circuit designs capture procedural share in Tokyo and Osaka children's hospital networks. |
| Software Companion Development | Digital perfusion monitoring integration compresses the gap between filtration performance and clinical decision support. |
Research Methodology
A standing panel of perfusionists, cardiovascular surgeons, hospital purchasing committee members, and biomedical engineers provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract disclosures. Bottom-up demand modeling across membrane filter, ultrafiltration device, centrifugal separator, and dialysis concentrator categories triangulated with top-down cardiovascular procedure volume estimates.
Scenario-bracketing around regulatory approval timelines, pediatric cardiac surgery expansion trajectories, and zero-balanced ultrafiltration substitution rates shaped the analytical framework across the projection horizon. Segmentation dimensions included product type, application, end user, and technology tier. CAGRs derived from procedure volume elasticity to device utilization rates and pricing trajectory assumptions for bundled versus standalone procurement.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified cardiovascular conglomerates into standalone hemoconcentrator categories would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Eccentric Tip Syringe Market
Medical Devices
Global Vein Finders Market
Medical Devices
Interventional Oncology Devices Market
Medical Devices
Injectable Drug Delivery Market
Medical Devices
Global Microkeratome Market
Medical Devices
Electroencephalography Devices Market
Medical Devices
Medical Pendant Market
Medical Devices
Medical Electronics Market
Medical Devices
US Anti-Blue Ray Myopia Lenses Market
Medical Devices
Kirschner Wires Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Neurovascular Catheters Market
Medical Devices
Medical Laser Cutting Device Market
Medical Devices
Bone Conduction Hearing Aids Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Uterine Fibroid Treatment Device Market