
 Dental Floss Market | 2026-2036
Dental Floss Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Floss Market Intelligence
The distinction between standard waxed nylon and advanced PTFE materials is collapsing as consumer preferences shift toward smoother, shred-resistant options. Procter & Gamble leverages its extensive retail presence to introduce premium floss variants into mass-market channels. Colgate-Palmolive sustains market share through strong brand loyalty and targeted campaigns for specific oral health needs. Sunstar Suisse specializes in the interdental cleaning segment, offering products for both professional dental offices and home use.
Dental floss is a cord of thin filaments used to remove food particles and dental plaque from between teeth. It is typically manufactured from materials like multifilament nylon or monofilament polytetrafluoroethylene (PTFE) and can be treated with agents like wax or flavorings. Its primary function is to clean interproximal surfaces where toothbrushes cannot effectively reach, preventing gingivitis and tooth decay. While unwaxed floss maintains a core user base, demand for expanded and flavored floss types is rising. Eco-friendly packaging is a key purchasing factor, influencing choices for both dispenser and refill pack formats.
Material safety and product claims are governed by bodies like the Food and Drug Administration (FDA) in the United States, which regulates consumer health products. In Europe, regulations such as REACH scrutinize the chemical substances used in manufacturing, including any coatings on PTFE floss. Future success for manufacturers depends on balancing the development of innovative, sustainable materials with the cost expectations of a mass-market consumer base.
Market Dynamics
The central force shaping the dental floss market is the collision between consumer demand for sustainable, biodegradable materials and the established cost structure of mass-market nylon and PTFE, forcing a re-evaluation of the entire value chain.
Growth Catalysts
- Orthodontic Patient Demand:A growing orthodontic patient base requires specialized interdental cleaners, boosting sales of shred-resistant floss and threaders.
- EU Plastic Reduction Mandates:EU directives on single-use plastics accelerate the shift to biodegradable materials and plastic-free packaging systems.
- Sustainable Material Innovation:Viable biodegradable materials like silk and PLA allow brands to meet strong consumer demand for eco-friendly options.
Market Restraints
- Input Cost Disparity:Biodegradable materials like silk command a price premium over nylon, limiting appeal in price-sensitive mass-market channels.
- Regulatory Compliance Costs:Adhering to chemical regulations like REACH for PTFE coatings adds complexity and cost to the manufacturing supply chain.
- Water Flosser Substitution:Electric water flossers present a direct substitution threat, capturing users who prioritize convenience over traditional floss.
Strategic Opportunities
- DTC Subscription Models:Direct-to-consumer subscriptions for eco-friendly refills bypass retail and build loyalty with targeted consumer segments.
- Untapped Geographic Markets:Rising oral health awareness in economies across Southeast Asia and Latin America presents a significant opportunity for expansion.
- Value-Added Formulations:Incorporating ingredients like charcoal into floss fibers allows product differentiation that targets specific consumer wellness trends.
Industry Challenges
- Supply Chain Transition:Shifting from petrochemical nylon supply chains to agricultural-based PLA or silk sources requires substantial capital investment and new logistics.
- Avoiding Greenwashing Allegations:Brands must substantiate environmental claims with credible certifications to avoid consumer backlash and regulatory action from bodies like the FTC.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Floss Market |
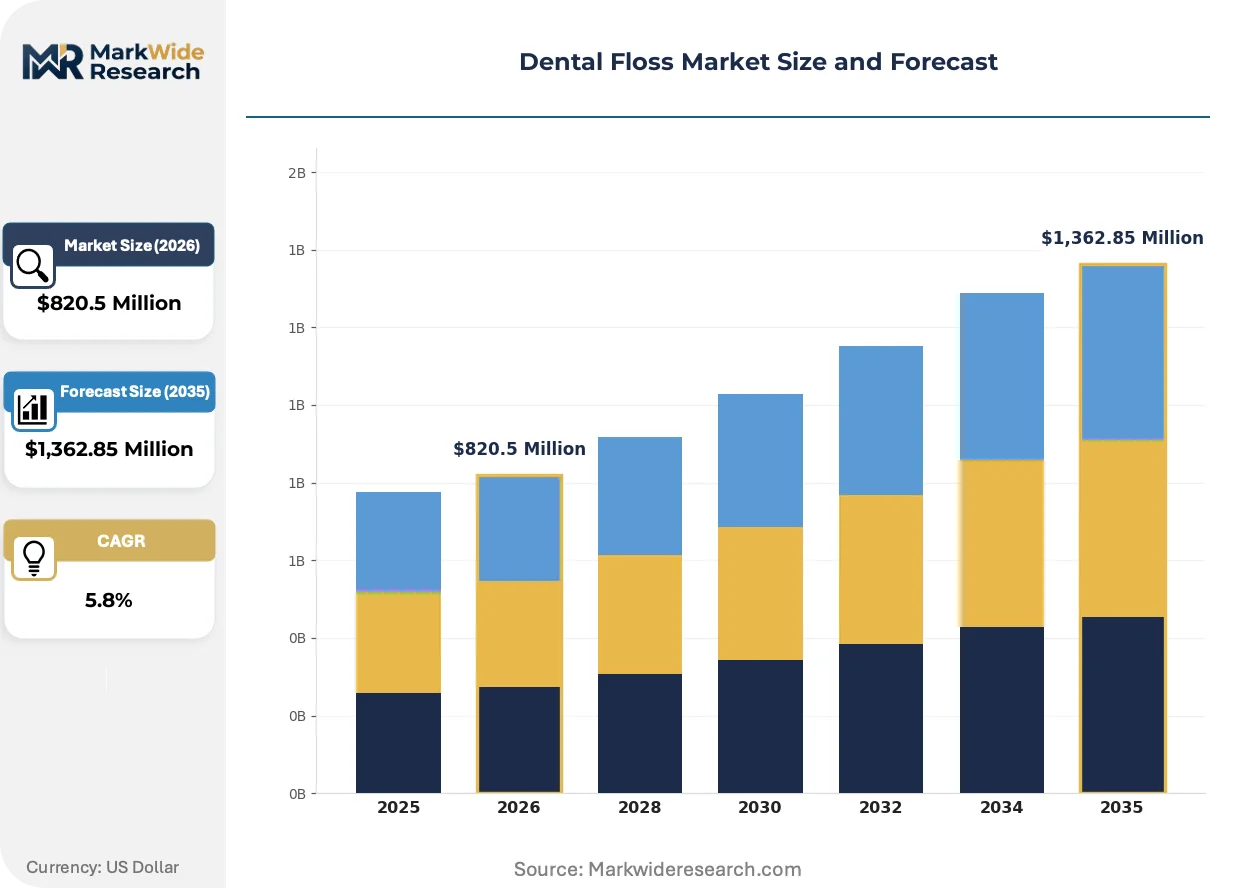
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,362.85 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waxed, Unwaxed, Flavored, Expanded Material: Nylon, PTFE, Silk, Polyester Packaging Type: Dispenser, Refill Pack, Travel Size, Eco-friendly Customer Type: Adults, Children, Orthodontic Patients, Seniors |
| Companies Covered | Church & Dwight, Prestige Consumer Healthcare, Procter & Gamble, Dr. Fresh, Lion Corporation, Johnson & Johnson, Sunstar Suisse, DenTek, Colgate-Palmolive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Floss Market Strategic Shifts & Innovations
Material science innovations are colliding with evolving consumer ethics around sustainability and wellness. This dynamic forces a re-evaluation of product composition, from the filament itself to its packaging and ultimate disposal.
Biodegradable polymers like polylactic acid (PLA), derived from renewable resources like corn starch, offer a sustainable alternative to traditional nylon. Eco-conscious consumers, particularly in European markets, are driving early adoption of these products. This material shift is decomposing the long-standing market structure built on the cost-efficiency of non-degradable, petroleum-based filaments.
The European Union's Single-Use Plastics Directive directly impacts product design beyond the floss filament itself. This regulation pressures manufacturers to eliminate plastic in dispensers and secondary packaging, accelerating the move toward glass, metal, or paperboard containers. Firms targeting Germany and France are at the forefront of this packaging innovation to maintain market access.
Subscription-based purchasing models are altering how consumers acquire oral care products, including floss. This direct-to-consumer (DTC) channel enables niche brands, especially those with a sustainable focus, to circumvent traditional retail gatekeepers and cultivate direct customer relationships. The trend is most prominent in North American and Western European urban markets where convenience and product curation are highly valued.
Dental Floss Market Segmentation
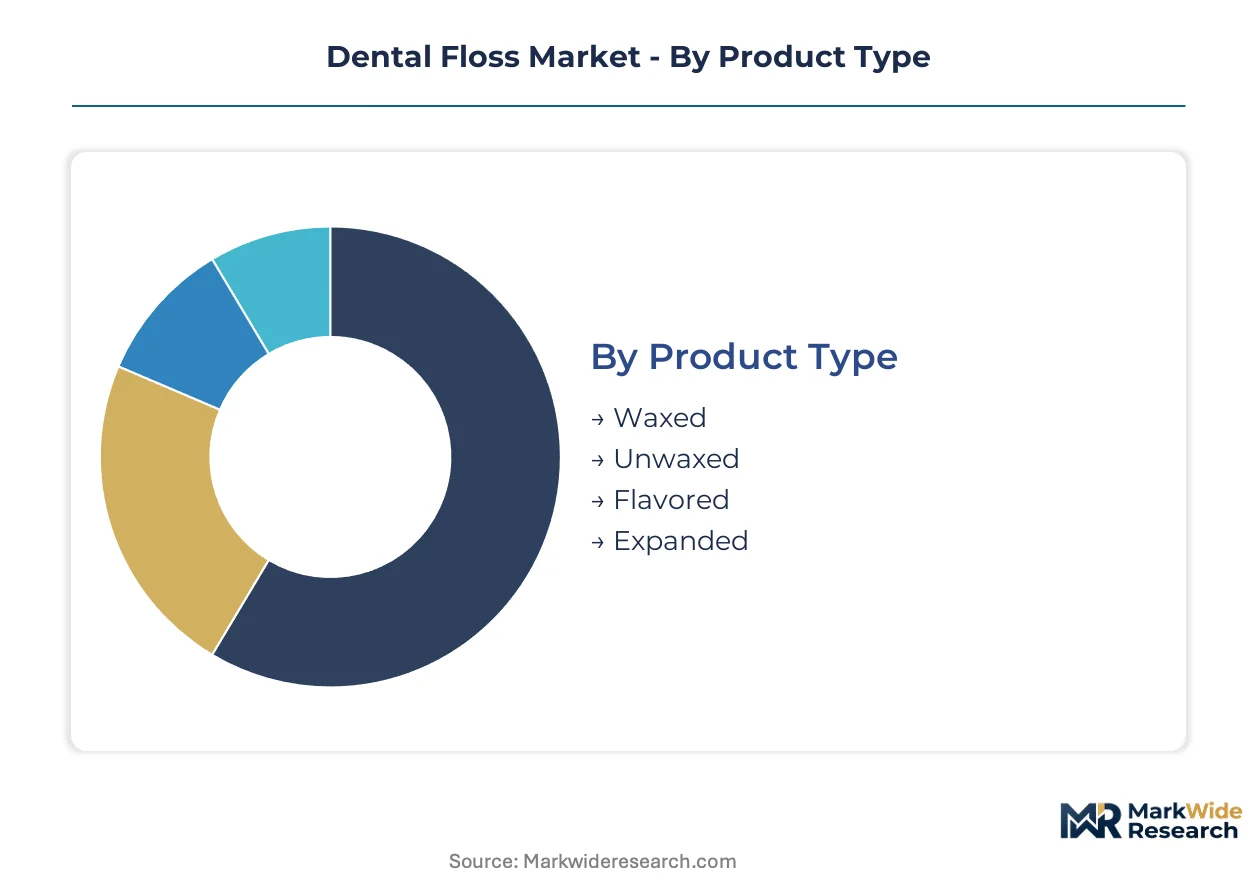
The dental floss market exhibits diverse segmentation, driven by evolving consumer needs and material innovations. Understanding these distinct segments allows manufacturers to tailor product development and marketing strategies effectively. This analysis breaks down the market across key dimensions, highlighting areas of concentration and growth.
Product Type:
Regulatory considerations significantly influence the development and marketing of dental floss product types.
- Waxed:This traditional floss variant features a polymer coating, typically wax, which eases its glide between teeth and reduces shredding. Demand remains robust among general consumers prioritizing ease of use and consistent performance in established markets like the United States.
- Unwaxed:Composed of multiple nylon filaments, unwaxed floss offers a squeaky clean feel and is favored by users seeking maximum plaque removal.
- Flavored:These floss types incorporate mint, cinnamon, or other flavorings to enhance the user experience and encourage consistent oral hygiene practices. Consumer preference for flavored options is particularly strong among younger demographics and in markets such as Germany, where oral care product innovation is valued.
- Expanded:This type of floss expands upon contact with saliva, increasing its surface area for more effective cleaning, often preferred by individuals with wider interdental spaces.
Established volume favors Waxed; emerging adoption favors Flavored.
Material:
Supply chain concentration heavily influences the material choices available for dental floss manufacturing.
- Nylon:A multi-filament, petroleum-based polymer, nylon is the most widely used material for dental floss due to its cost-effectiveness and tensile strength. Its widespread availability and established production infrastructure support mass-market products globally.
- PTFE:Polytetrafluoroethylene, a monofilament material, offers superior shred-resistance and glides smoothly, often preferred by users with tight teeth or specific orthodontic needs. Regulatory scrutiny, such as REACH in Europe, impacts the coatings and additives used with PTFE materials.
- Silk:A natural, biodegradable fiber, silk floss appeals to eco-conscious consumers seeking sustainable oral care alternatives, especially in markets like France.
- Polyester:This synthetic polymer offers a cost-effective alternative to nylon, providing good strength and flexibility for various floss formulations.
Demand for Nylon remains significant, while Silk is gaining traction due to sustainability drivers.
Packaging Type:
Consumer preference and convenience are primary factors shaping dental floss packaging types.
- Dispenser:The traditional format, featuring a plastic or increasingly eco-friendly container with an integrated cutting mechanism, offers convenience for daily use. Design innovation in dispensers, particularly for plastic reduction, is a focus for brands in the European Union.
- Refill Pack:Designed to replenish existing dispensers, refill packs reduce plastic waste and offer a cost-effective option for regular users.
- Travel Size:Compact and portable, travel-size floss is designed for on-the-go convenience, catering to consumers with active lifestyles.
- Eco-friendly:This segment includes packaging made from biodegradable, recycled, or reusable materials like glass, metal, or paperboard, often paired with plastic-free floss. Strong consumer demand for sustainable options in countries such as Germany drives rapid innovation in this category.
Traditional Dispenser formats maintain broad appeal, but Eco-friendly options are expanding most quickly.
Customer Type:
Specific oral health needs dictate the types of dental floss preferred by different customer segments.
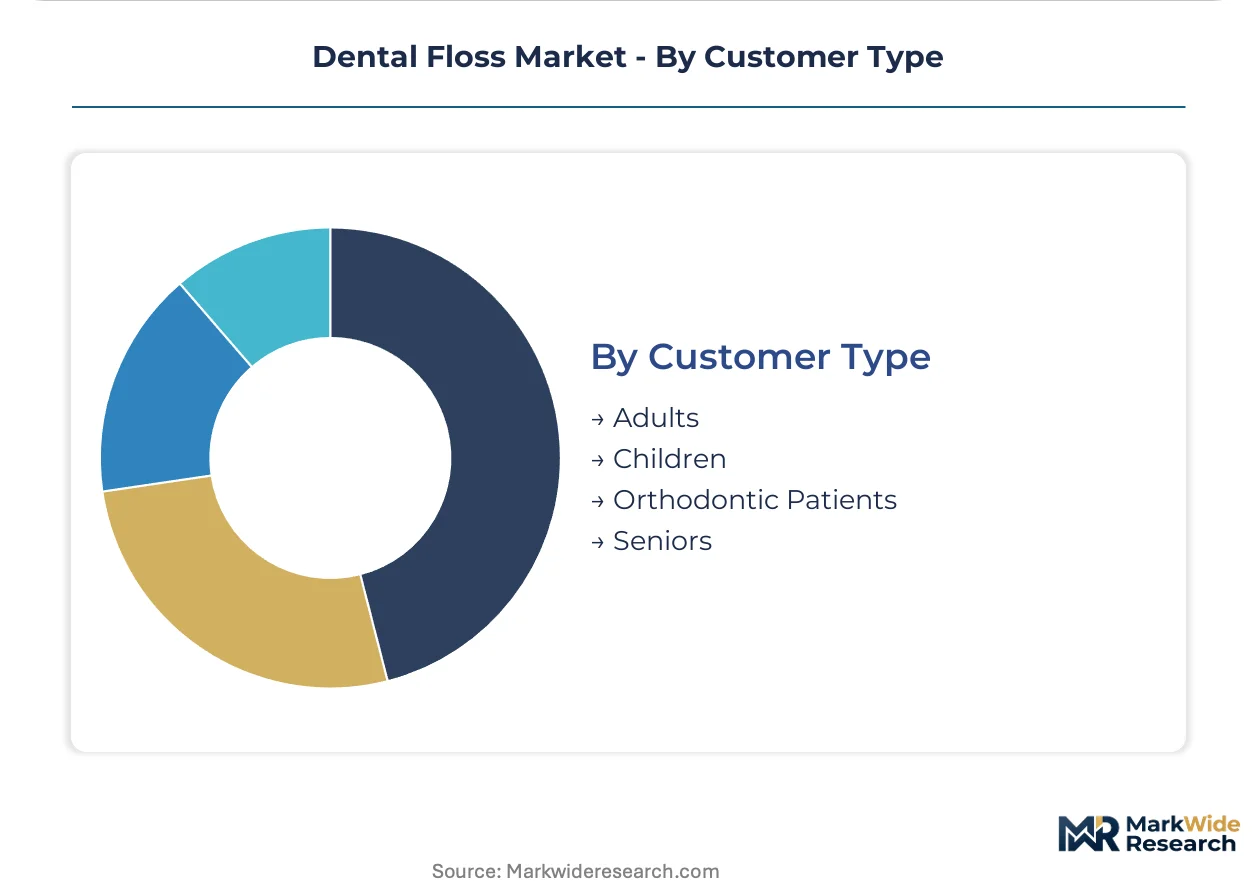
- Adults:This segment represents the largest user base for dental floss, employing it for routine plaque removal and gingivitis prevention. Product choices vary widely, encompassing waxed, unwaxed, and flavored options to meet diverse preferences.
- Children:Dental floss for children often features smaller sizes, fun flavors, and easy-to-grip designs to encourage early oral hygiene habits.
- Orthodontic Patients:Individuals undergoing orthodontic treatment require specialized floss, such as super floss or floss threaders, to navigate braces and wires effectively. Demand from this growing patient base is a significant growth driver for interdental cleaning products.
- Seniors:This demographic often requires floss designed for sensitive gums or larger interdental spaces, sometimes preferring softer or expanded floss types.
General oral hygiene drives Adults demand, while specialized needs increase focus on Orthodontic Patients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global dental floss production concentrates in regions with established chemical manufacturing infrastructure. The supply chain for traditional nylon and PTFE filaments is particularly centralized. However, new centers are emerging for sustainable materials like silk and PLA, driven by evolving consumer ethics and regulatory pressures.
United States
United States consumers drive demand for both traditional waxed floss and advanced PTFE variants, prioritizing ease of use. The Food and Drug Administration (FDA) strictly governs material safety and product claims for oral hygiene items. New Jersey's manufacturing hubs innovate on floss formulations and delivery systems.
Germany
Germany exhibits strong consumer preference for eco-friendly floss and innovative flavored options, reflecting a wellness-oriented market. European Union directives, including REACH, impose stringent chemical substance scrutiny on dental floss materials. Manufacturing clusters in Bavaria focus on developing biodegradable polymers and plastic-free packaging.
France
France shows a growing appetite for natural, biodegradable silk floss and sustainable oral care alternatives, particularly among eco-conscious consumers. The EU Single-Use Plastics Directive directly pressures manufacturers to eliminate plastic from dispensers and secondary packaging. Paris, as a consumer trend hub, sees early adoption of refillable systems and plastic-free floss options.
China
China's expanding middle class and rising oral health awareness fuel a growing demand for basic and advanced dental floss products. National health initiatives encourage consistent oral hygiene practices across diverse demographics. Guangdong province, a major manufacturing hub, produces vast quantities of cost-effective nylon floss for domestic and export markets.
Dental Floss Market Key Industry Players
Concentration sits with established consumer goods giants leveraging extensive distribution networks for mass-market reach. The dental floss market exhibits a tiered structure, from global brand leaders to niche specialists. Strategic archetypes include diversified oral care conglomerates, focused interdental cleaning solution providers, and emerging sustainable product innovators. Companies pursue portfolio diversification, geographic expansion into untapped markets, and strategic partnerships to capture evolving consumer preferences.
Within the diversified oral care conglomerate archetype, Procter & Gamble and Colgate-Palmolive leverage their global brand recognition and extensive retail presence. Procter & Gamble, a US-based corporation, exemplifies the strategy of introducing premium floss variants into mass-market channels, while Colgate-Palmolive, another prominent US-based company, sustains market share through strong brand loyalty and targeted campaigns for specific oral health needs. Sunstar Suisse S.A., a Swiss-based specialist, occupies a position as a dedicated interdental cleaning segment provider, catering to both professional dental offices and home use consumers.
| Leading Market Players |
|---|
| Church & Dwight |
| Prestige Consumer Healthcare |
| Procter & Gamble |
| Dr. Fresh |
| Lion Corporation |
| Johnson & Johnson |
| Sunstar Suisse |
| DenTek |
| Colgate-Palmolive |
| Others |
Cost & Logistics Intelligence
Scale economies in petrochemical processing underwrite the cost-effectiveness of traditional nylon and PTFE floss. This efficiency drives supply concentration in established manufacturing hubs and sets a low price floor for mass-market products.
Pricing Analysis
The Food and Drug Administration (FDA) dictates the pricing tier structure for dental floss, ensuring material safety claims are substantiated. Per-unit transactional models dominate, with premium-mid-economy pricing differentiation based on material innovation and brand recognition. Price differentiation also stems from certification levels for eco-friendly products. Pricing pressure intensifies on traditional nylon floss due to competition, while sustainable alternatives face upward pressure from higher input costs. Orthodontic patients and eco-conscious consumers exhibit lower price sensitivity compared to mass-market adults.
Supply Chain Analysis
Dependence on petrochemical derivatives for nylon and PTFE production concentrates supply in specific global regions. China dominates cost-effective nylon floss manufacturing, while the United States focuses on PTFE innovation. Key raw material dependencies include multifilament nylon, monofilament PTFE, and agricultural sources for polylactic acid (PLA). A structural supply chain risk involves commodity price volatility for petroleum-based inputs. Downstream distribution runs primarily through extensive retail networks, though direct-to-consumer (DTC) models are gaining traction for niche sustainable brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental floss market is experiencing high-growth disruption, driven by the EU Single-Use Plastics Directive. This regulatory inflection is forcing a profound shift towards sustainable materials and packaging solutions.
For Market Incumbents:Compound existing retail presence by introducing premium, sustainable floss variants into mass-market channels. Invest heavily in biodegradable material research and development to mitigate the threat of water flosser substitution. Acquire niche eco-friendly brands to integrate specialized capabilities and expand market share. Leverage established supply chain expertise to transition from petrochemical-based materials to agricultural-based alternatives, addressing greenwashing allegations proactively.
For New Entrants and Emerging Players:Lead with direct-to-consumer (DTC) subscription models for eco-friendly refill packs, bypassing traditional retail gatekeepers. Target eco-conscious consumers in urban Western European markets with transparent sustainability claims and credible certifications. Focus on value-added formulations, such as charcoal-infused floss, to differentiate products and tap into specific wellness trends. The most penetrable segment remains consumers actively seeking plastic-free and biodegradable oral care solutions.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among DTC subscription models, offering attractive long-term viability in the oral care sector. Oral health awareness and continuous product innovation ensure sustained market growth. Seek acquisition targets that are innovative material science startups or brands with strong eco-credentials and established intellectual property in biodegradable filaments. The signal to watch is the accelerated adoption rate of plastic-free packaging in regulated markets like Germany and France.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Material R&D | Develop next-generation biodegradable filaments, reducing reliance on petrochemicals and meeting EU mandates. |
| Direct-to-Consumer Channel Expansion | Build loyalty with eco-conscious consumers and bypass traditional retail gatekeepers for niche brands. |
| Geographic Expansion into Emerging Markets | Capture demand from rising oral health awareness in Southeast Asia and Latin America. |
| Eco-Friendly Packaging Innovation | Eliminate single-use plastics from dispensers and secondary packaging, particularly for Germany and France. |
| Value-Added Formulation Integration | Differentiate products with ingredients like charcoal, targeting specific consumer wellness trends. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during the primary research phase. Interviews included brand managers, procurement leads, R&D directors, and dental professionals. This primary data was validated against secondary sources such as FDA product registrations, EU REACH filings, trade association reports, and retail sales data. A rigorous bottom-up and top-down triangulation approach ensured comprehensive market sizing and validation.
Across the analysis window, the quantitative framework integrated various data points to project market growth. Segmentation dimensions modeled included product type, material, packaging type, customer type, and regional regulatory environments. Compound annual growth rates were derived from historical trend analysis and projected future growth drivers. Key industry-specific forecast inputs included orthodontic patient growth rates and plastic reduction mandate timelines.
Forecasts assume regulatory continuity in US and EU regimes; material policy shifts would require re-modeling. These projections reflect assumptions regarding material cost stability and consumer adoption rates for new products. Practitioners should keep alternative scenarios live as material science innovations and consumer preferences evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Self-Ligating Bracket Sales Market
Dental Devices
Global Dental Burs Market
Dental Devices
Global Dental Laboratory Welders Market
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
Dental Dam Market
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
Sleep Apnea Oral Appliances Market
Dental Devices
Global Dental Restorative Market
Dental Devices
Single Tooth Implants and Dental Bridges Market
Dental Devices
Dental Fittings Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Dental Needle Market
Dental Devices
Dental Piezoelectric Ultrasonic Unit Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Americas Acrylic Teeth Market
Dental Devices
RFID-Enabled Dental Printing Market