
 Allergy Tester Market | 2026-2036
Allergy Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Allergy Tester Market Analysis
Market Context with Strategic Players
A shortage of certified clinical laboratory scientists is redrawing competitive boundaries in allergy diagnostics. Thermo Fisher Scientific leverages its end-to-end reagent-instrument ecosystem to sustain installed-base loyalty across hospital networks. Siemens Healthineers anchors its position through automated immunoassay platforms that reduce manual specimen handling. Danaher Corporation competes via integrated workflow solutions that compress turnaround times for immunoglobulin E quantification.
Technical Definition and Structural Segments
An allergy tester comprises in vitro diagnostic devices and reagent systems that detect and quantify allergen-specific immunoglobulin E antibodies or cell-mediated hypersensitivity responses, typically operating with analytical sensitivity thresholds below 0.1 kU/L for serum-based assays. These systems serve clinical laboratories, hospitals, and point-of-care settings by enabling precise identification of environmental, food, drug, and insect allergens to guide therapeutic intervention and patient avoidance strategies. Blood test platforms dominate revenue generation due to their standardization and scalability within high-throughput laboratory environments, while molecular diagnostics segments capture accelerated expansion as multiplexed allergen profiling replaces single-parameter screening. Patch test applications for contact dermatitis occupy mature, stable demand channels, whereas home care end users represent an emerging growth vector as self-administered finger-prick devices gain regulatory clearances.
Regulatory Frame and Forward Outlook
The FDA governs allergy tester premarket pathways through Class II device designations, while the Clinical Laboratory Improvement Amendments impose proficiency testing standards that shape product development priorities. ISO 15189 accreditation requirements in European diagnostic networks and Japan's PMDA quality management standards further constrain market access for non-compliant manufacturers. Stakeholders must monitor evolving harmonization between FDA breakthrough device criteria and EU MDR performance benchmarks to anticipate competitive repositioning costs.
Market Dynamics
Laboratory automation is compressing turnaround times for immunoglobulin E quantification while simultaneously raising capital barriers for diagnostic manufacturers seeking CLIA high-complexity certification. This dual pressure is restructuring competitive entry pathways across the allergy testing value chain.
Growth Catalysts
- CLIA Proficiency Testing Mandates:United States clinical laboratories face escalating test volume requirements that favor automated immunoassay platforms capable of processing thousands of specimens daily with minimal manual intervention.
- Multiplexed Allergen Profiling:Molecular diagnostics laboratories are replacing single-parameter screening with comprehensive allergen panels that simultaneously detect environmental, food, and drug sensitivities from single serum samples.
- Self-Administered Finger-Prick Devices:Home care settings are capturing regulatory clearances for point-of-care immunoglobulin E testing, expanding addressable demand beyond traditional hospital and laboratory channels.
Market Restraints
- Reagent-Instrument Ecosystem Lock-In:Diagnostic manufacturers face structural switching costs when migrating from incumbent closed-system platforms to open-architecture alternatives, entrenching installed-base loyalty.
- Serum-Based Assay Input Volatility:Purified allergen extract supply concentrates among specialized biotechnology suppliers in Germany and the Netherlands, exposing reagent producers to raw material price instability.
- ISO 15189 Accreditation Burden:European diagnostic networks impose quality management documentation requirements that extend product development timelines by 18-24 months for non-accredited manufacturers.
Strategic Opportunities
- Pediatric Allergy Screening:Underpenetrated demand in India for early childhood food allergen detection presents whitespace for affordable multiplex platforms adapted to tropical climate storage conditions.
- AI-Assisted Pattern Recognition:Machine learning algorithms converging with flow cytometry data streams enable automated interpretation of basophil activation test results, reducing specialist pathologist review requirements.
- Direct-to-Consumer Subscription Models:Digital health platforms in the United States are piloting recurring allergen monitoring services that ship collection kits to seasonal allergy sufferers before peak pollen periods.
Industry Challenges
- Clinical Laboratory Scientist Shortage:United States hospital networks face critical staffing gaps for high-complexity testing personnel, forcing diagnostic manufacturers to engineer greater walkaway automation into instrument designs.
- FDA Breakthrough Device Validation:Accelerated premarket pathways demand rigorous analytical sensitivity documentation below 0.1 kU/L thresholds, compressing development resources for mid-cap entrants.
- Legacy LIS Integration Complexity:Hospital information system architectures vary substantially across integrated delivery networks, requiring customized middleware development for seamless test result transmission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allergy Tester Market |
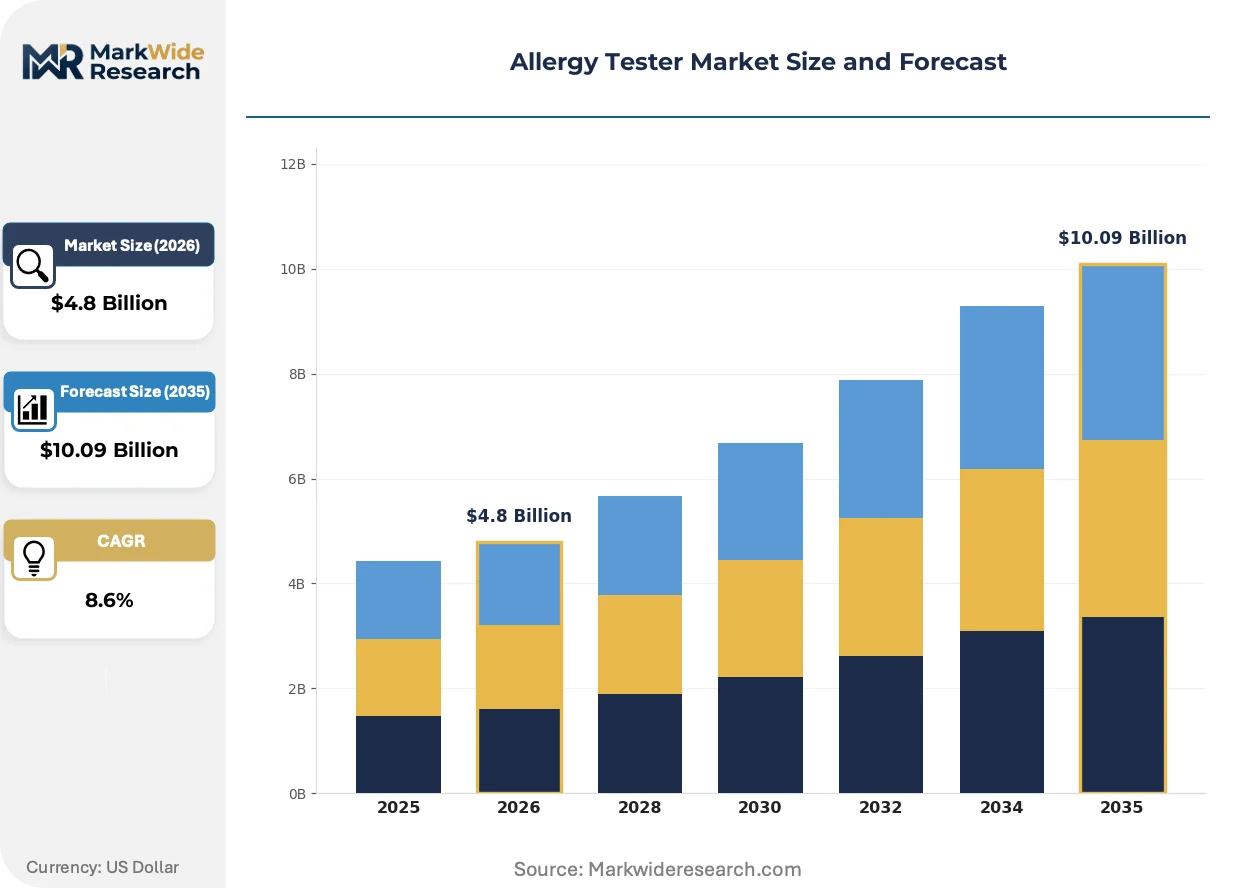
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Prick Tests, Blood Tests, Patch Tests, Intradermal Tests Technology: Immunoassays, Molecular Diagnostics, Microarrays, ELISA End User: Hospitals, Diagnostic Laboratories, Home Care, Research Institutions Application: Environmental Allergens, Food Allergens, Insect Allergens, Drug Allergens |
| Companies Covered | Thermo Fisher Scientific, Siemens Healthineers, Danaher Corporation, bioMérieux, EUROIMMUN, HollisterStier Allergy, Omega Diagnostics, HYCOR Biomedical, Eurofins Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allergy Tester Market Emerging Trajectories
Component miniaturization is enabling portable allergy testing platforms that challenge the historical dominance of centralized laboratory infrastructure. These developments are redrawing competitive boundaries between point-of-care and high-throughput diagnostic segments.
Microfluidic cartridge systems are fragmenting the traditional separation between sample preparation, allergen-antibody binding, and signal detection into discrete disposable modules. Community health clinics and urgent care chains in the United States are deploying these platforms to offer same-day immunoglobulin E results without courier transport to reference laboratories. This fragmentation is compressing revenue capture for centralized diagnostic networks while expanding accessible testing geography into rural and underserved urban corridors.
The FDA's evolving oversight of in vitro diagnostic devices is accelerating validation requirements for software-as-medical-device components embedded in automated immunoassay platforms. Manufacturers must now submit algorithmic performance data alongside traditional analytical sensitivity documentation, extending premarket notification timelines. Blood test platform developers with substantial regulatory affairs infrastructure are absorbing these compliance costs more readily than molecular diagnostics specialists.
Hospital procurement committees are unbundling after-sales service contracts from instrument purchase agreements, demanding à-la-carte preventive maintenance and reagent supply arrangements. This behavioral shift pressures diagnostic manufacturers to disclose true cost-per-test economics rather than obscuring operational expenses within bundled leasing structures. Integrated health networks in California and Texas are leading this transparency push, negotiating multi-year reagent commitments separate from capital equipment financing.
Allergy Tester Market Segmentation
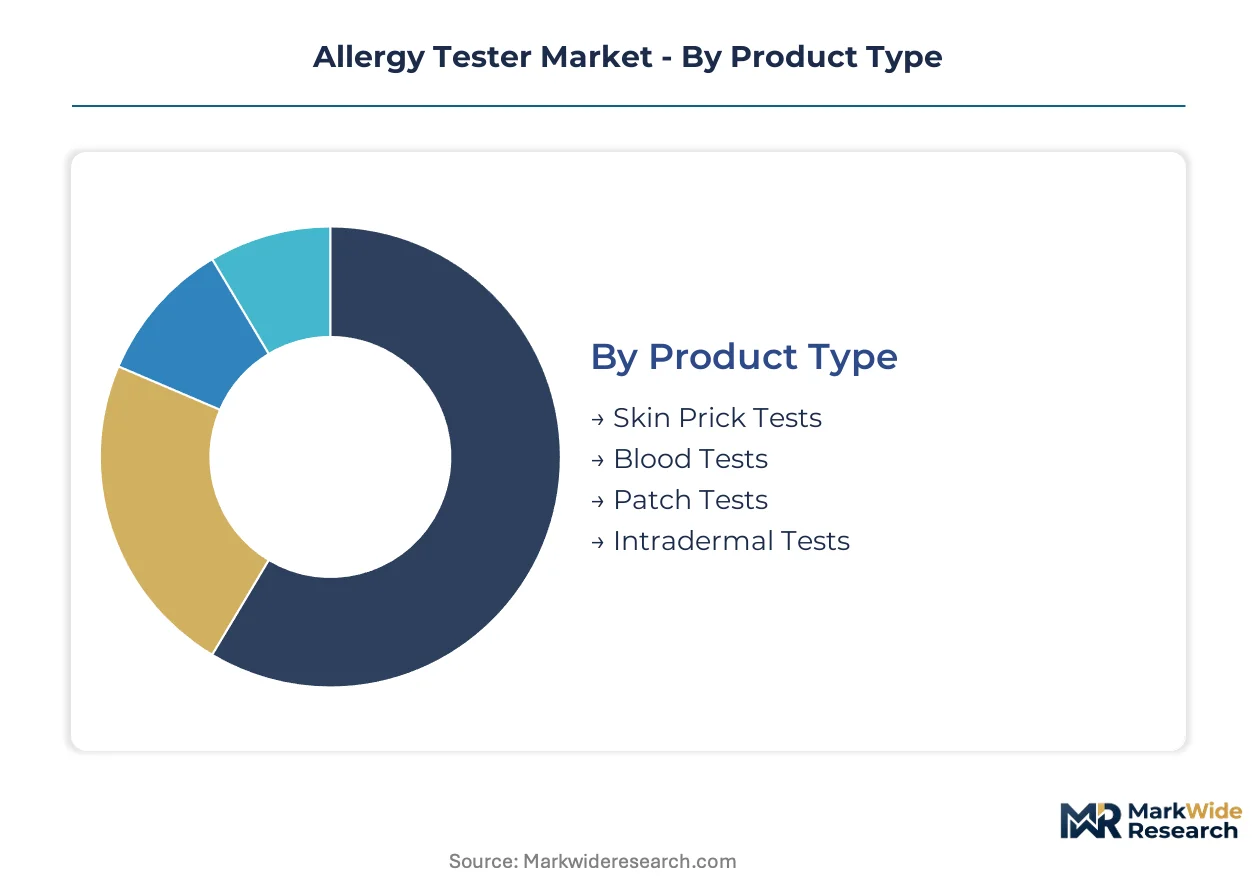
Segmentation in allergy diagnostics reveals divergent regulatory pathways and capital requirements across testing modalities. Manufacturers must align product development with specific CLIA complexity tiers, FDA device classifications, and end-user automation needs to secure market access.
Product Type:
FDA Class II designations vary substantially across testing modalities, with serum-based assays facing distinct premarket notification requirements versus percutaneous methods.
- Blood Tests:Serum immunoglobulin E quantification operates below 0.1 kU/L analytical sensitivity thresholds. Demand concentrates in United States hospital networks and centralized diagnostic laboratories processing high specimen volumes under CLIA high-complexity certification.
- Skin Prick Tests:Percutaneous allergen introduction with immediate hypersensitivity observation requires allergist supervision. Demand concentrates in United States allergy specialty clinics and European ambulatory care centers where physician reimbursement structures favor in-office procedures.
- Patch Tests:Epicutaneous allergen application for delayed contact dermatitis diagnosis.
- Intradermal Tests:Dermal allergen injection for enhanced sensitivity in venom and drug allergy assessment.
Established volume favors blood tests; emerging adoption favors skin prick tests.
Technology:
Cost tier differentiation separates capital-intensive automated platforms from lower-throughput manual methods.
- Immunoassays:Automated chemiluminescent and fluorescent enzyme systems dominate high-throughput laboratory environments. Demand concentrates in integrated health networks across California and Texas where walkaway automation addresses clinical laboratory scientist shortages.
- Molecular Diagnostics:Multiplexed nucleic acid amplification enables simultaneous allergen profiling from single specimens. Demand concentrates in academic medical centers and reference laboratories where comprehensive panels replace sequential single-parameter testing.
- Microarrays:Miniaturized solid-phase allergen chips for targeted IgE profiling.
- ELISA:Enzyme-linked immunosorbent assays for standardized quantitative measurement in resource-constrained settings.
Capital deployment favors immunoassays; panel complexity favors molecular diagnostics.
End User:
Customer type determines reimbursement pathway and regulatory scrutiny intensity.
- Diagnostic Laboratories:Centralized reference and hospital-affiliated labs process bulk specimens under stringent proficiency testing mandates. United States networks in Illinois and New York drive automated platform procurement for immunoglobulin E quantification.
- Hospitals:Inpatient and emergency departments require rapid turnaround for acute hypersensitivity events. Demand concentrates in tertiary care centers across Florida and Ohio where anaphylaxis protocols mandate immediate allergen identification.
- Home Care:Self-administered finger-prick collection with mail-in or connected device analysis.
- Research Institutions:Academic and pharmaceutical research applications for allergen characterization and therapeutic development.
Procurement scale favors diagnostic laboratories; regulatory clearance velocity favors home care.
Application:
Maturity gradients separate well-established environmental testing from emerging therapeutic monitoring domains.
- Environmental Allergens:Pollen, dust mite, mold, and pet dander sensitivity detection constitutes the foundational testing category. Demand concentrates in seasonal allergy management protocols across United States pulmonary and ENT specialty practices.
- Food Allergens:Peanut, tree nut, shellfish, and milk protein IgE quantification guides elimination diets and oral immunotherapy candidacy. Demand concentrates in pediatric allergy practices across Massachusetts and Pennsylvania where early childhood screening protocols expand.
- Insect Allergens:Hymenoptera venom sensitivity assessment for immunotherapy qualification.
- Drug Allergens:Beta-lactam and perioperative agent hypersensitivity evaluation for surgical clearance.
Test volume concentration favors environmental allergens; steepest expansion trajectory favors food allergens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States hospital networks while German diagnostic manufacturers capture premium reagent margins through specialized allergen extract supply. This asymmetry shapes regional investment allocation across the allergy testing value chain.
United States
Integrated health networks in California and Texas drive centralized laboratory procurement of automated immunoassay platforms. FDA Class II device designations and CLIA high-complexity certification requirements filter market access for non-compliant entrants. The Boston-Cambridge corridor anchors molecular diagnostics innovation where academic medical centers pilot multiplexed allergen profiling.
Germany
Specialized biotechnology suppliers in Bavaria and North Rhine-Westphalia dominate purified allergen extract production for global reagent manufacturers. EU MDR performance benchmarks and ISO 15189 accreditation standards extend product development timelines for international competitors. The Heidelberg-Mannheim region concentrates automated platform engineering for European diagnostic networks.
Japan
PMDA quality management standards constrain rapid market entry for foreign allergy testing device manufacturers. Tokyo and Osaka metropolitan areas host centralized reference laboratories processing high specimen volumes for aging populations with elevated atopic sensitization. METI industrial policy supports domestic production of miniaturized point-of-care platforms.
India
Pediatric allergy screening demand in Maharashtra and Karnataka presents whitespace for affordable multiplex platforms adapted to tropical climate storage conditions. CDSCO regulatory pathways and FSSAI quality standards shape import substitution strategies for domestic diagnostic manufacturers. The Delhi-NCR corridor anchors contract research operations serving European and North American reagent producers.
United Kingdom
NHS procurement frameworks favor consolidated reagent-instrument contracts that entrench incumbent supplier relationships. London and Southeast England concentrate private allergy specialty clinics where physician reimbursement structures support in-office percutaneous testing. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance pathways for device manufacturers.
Allergy Tester Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with consolidated reagent-instrument ecosystems dominating high-throughput laboratory segments while specialized molecular diagnostics firms capture premium panel complexity. The vendor base separates into three strategic archetypes: diversified life science conglomerates with end-to-end platform control, focused diagnostic specialists with automated workflow optimization, and emerging point-of-care innovators with miniaturized cartridge systems. M&A activity concentrates on reagent supply chain security and software-as-medical-device capabilities, while strategic partnerships address legacy LIS integration complexity.
Among diversified platform providers, Thermo Fisher Scientific, Siemens Healthineers, and Danaher Corporation exemplify the reagent-instrument ecosystem archetype that sustains installed-base loyalty through closed-system architectures. These entities occupy positions where regulatory affairs infrastructure and multi- geography compliance capabilities create defensive moats against mid-cap entrants facing compressed FDA breakthrough device validation timelines.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Danaher Corporation |
| bioMérieux |
| EUROIMMUN |
| HollisterStier Allergy |
| Omega Diagnostics |
| HYCOR Biomedical |
| Eurofins Scientific |
| Others |
Supply Flow & Price Mechanics
Ninety-day allergen extract inventory cycles in Bavarian biotechnology facilities directly tether pricing power to concentrated purification capacity. German suppliers command premium reagent margins while United States hospital networks leverage high-throughput volume commitments to compress per-test costs.
Pricing Analysis
The customization-premium spread separates configured-to-order immunoassay platforms from standard instrument configurations. Subscription-based reagent-instrument bundles dominate high-throughput laboratory segments, with price differentiation driven by CLIA certification tier and after-sales service bundling. Pricing pressure intensifies in the economy tier as Indian and Chinese manufacturers introduce affordable multiplex platforms. Diagnostic laboratories exhibit highest price sensitivity due to unbundled procurement demands, while academic medical centers absorb premium pricing for comprehensive allergen panels.
Supply Chain Analysis
Strait of Hormuz transit vulnerability exposes allergen extract shipments to Middle Eastern diagnostic manufacturers. Supply concentrates in Germany, the Netherlands, and Denmark for purified allergen extracts, while instrument manufacturing clusters in the United States, Germany, and Japan. The chain draws from specialized biotechnology suppliers for recombinant allergen components and microfluidic cartridge substrates. Single-source vulnerability in German extract purification creates structural risk. Distribution runs through authorized distributor networks serving hospital procurement committees and reference laboratory chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified clinical laboratory scientist scarcity constrains operational scaling for automated platform deployments. This talent gap favors manufacturers engineering walkaway automation and remote diagnostic capabilities.
For Market Incumbents: Consolidate reagent supply security through captive purification capacity or long-term extract offtake agreements with Bavarian biotechnology suppliers. Deepen installed-base loyalty by unbundling service contracts to match procurement committee transparency demands while embedding algorithmic interpretation software that reduces specialist pathologist dependency. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks market access for AI-assisted basophil activation test platforms with analytical sensitivity below 0.1 kU/L. Target underpenetrated pediatric allergy screening in Maharashtra and Karnataka with tropical-stabilized multiplex cartridges. Pursue direct-to-consumer subscription models shipping seasonal collection kits ahead of peak pollen periods. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core diagnostic assets with stranded regulatory affairs infrastructure. Long-term viability hinges on software-as-medical-device capabilities and EU MDR compliance readiness. Monitor FDA harmonization initiatives with international standards as inflection signal for competitive repositioning costs.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Supply Security Investment | Captive allergen extract purification insulates margins from German supplier concentration. |
| Software-as-Medical-Device Development | Algorithmic basophil activation interpretation reduces pathologist staffing requirements. |
| CLIA High-Complexity Certification | United States laboratory access requires proficiency testing compliance and automation validation. |
| Direct-to-Consumer Platform Launch | Self-administered finger-prick devices expand addressable demand beyond hospital channels. |
| EU MDR Compliance Pathway | ISO 15189 accreditation enables European diagnostic network procurement participation. |
Methodological Framework
A standing panel of clinical laboratory directors, biomedical engineers, hospital procurement managers, and regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) premarket notification databases, CLIA proficiency testing records, EU MDR technical documentation filings, and hospital GPO contract repositories. Bottom-up instrument shipment analysis triangulated against top-down reagent consumption estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, technology platform, end-user setting, and application category dimensions. CAGRs derived from logistic diffusion curves fitted to automated platform adoption patterns and molecular diagnostics penetration trajectories. Forecast inputs included clinical laboratory scientist staffing projections and FDA breakthrough device approval velocity.
The analysis sits within stated boundaries; outcomes outside sustained CLIA certification requirements and stable allergen extract supply would require recalibration. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and reimbursement stability for multiplex allergen profiling. Revision becomes warranted when FDA software-as-medical-device validation thresholds cross analytical sensitivity boundaries below 0.1 kU/L.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Fertility Testing Market
Testing Services
Fungal Testing Kits Market
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
Trichomonas Rapid Testing Market
Testing Services
Pregnancy Point of Care Testing Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
Anti-Asthma TDM Assay Kits Market
Testing Services
Global Urinalysis Test Market
Testing Services
Pharmaceutical Dissolution Testing Services Market
Testing Services
Platelet Function Testing Market
Testing Services
Fecal Occult Testing Market
Testing Services
Thyroid Test Market
Testing Services
Skin Perfusion Pressure Testing Devices Market
Testing Services
Aerospace and Life Science Testing Certification Market
Testing Services
Bimetallic Thermometer Market
Testing Services
Warfarin Sensitivity Testing Market