
 Dental Consumables Market | 2026-2036
Dental Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Consumables Market Intelligence
The unbundling of complete procedural kits into single-use, application-specific components is decoupling purchasing decisions from brand-loyal systems. This shift allows smaller clinics to manage inventory costs more effectively. Dentsply Sirona leverages its extensive portfolio of integrated equipment and consumables to encourage system loyalty. In contrast, 3M Company competes with a broad range of standalone material science innovations, particularly in adhesives and composites. Meanwhile, the Straumann Group specializes in the premium implant and prosthetics segment, commanding a strong position with its specialized offerings.
Dental consumables are single-use or limited-use products essential for clinical procedures. These items, often formulated with biocompatible polymers, ceramics, and metallic alloys, must meet strict sterility and performance standards. Their primary purpose is to facilitate restorative, preventive, and prosthetic dental treatments within professional settings. Restorative materials like composites constitute the largest product segment by volume for dental clinics. Advanced adhesives and cements, while a smaller category, command higher margins due to their specialized formulations and critical role in procedural success.
Regulatory oversight significantly influences product development and market access. In the United States, the FDA classifies and clears devices based on risk. The European Union’s MDR framework, enforced via CE marking, imposes stringent clinical evaluation and post-market surveillance requirements. Similarly, Japan's PMDA mandates rigorous approval processes for medical devices. Future success depends on developing materials that meet both stricter regulatory hurdles and clinical demands for faster, more durable patient outcomes.
Market Dynamics
The dental consumables market is being reshaped by a structural shift towards evidence-based material performance, driven by stricter global regulatory frameworks. This pressure for enhanced clinical data and material traceability, exemplified by the EU's MDR, is elevating standards for all manufacturers.
Growth Catalysts
- Aesthetic Treatments:A higher volume of cosmetic procedures, particularly in markets like Brazil, stimulates demand for specialized consumables such as whitening agents, veneers, and orthodontic materials.
- Digital Dentistry Integration:The adoption of CAD/CAM technology and 3D printing in dental labs and clinics creates new demand for compatible materials like millable ceramic blocks and photopolymer resins.
- Preventive Care Focus:Public health initiatives promoting oral hygiene and preventive treatments expand the use of consumables like fluorides, sealants, and professional cleaning pastes.
Market Restraints
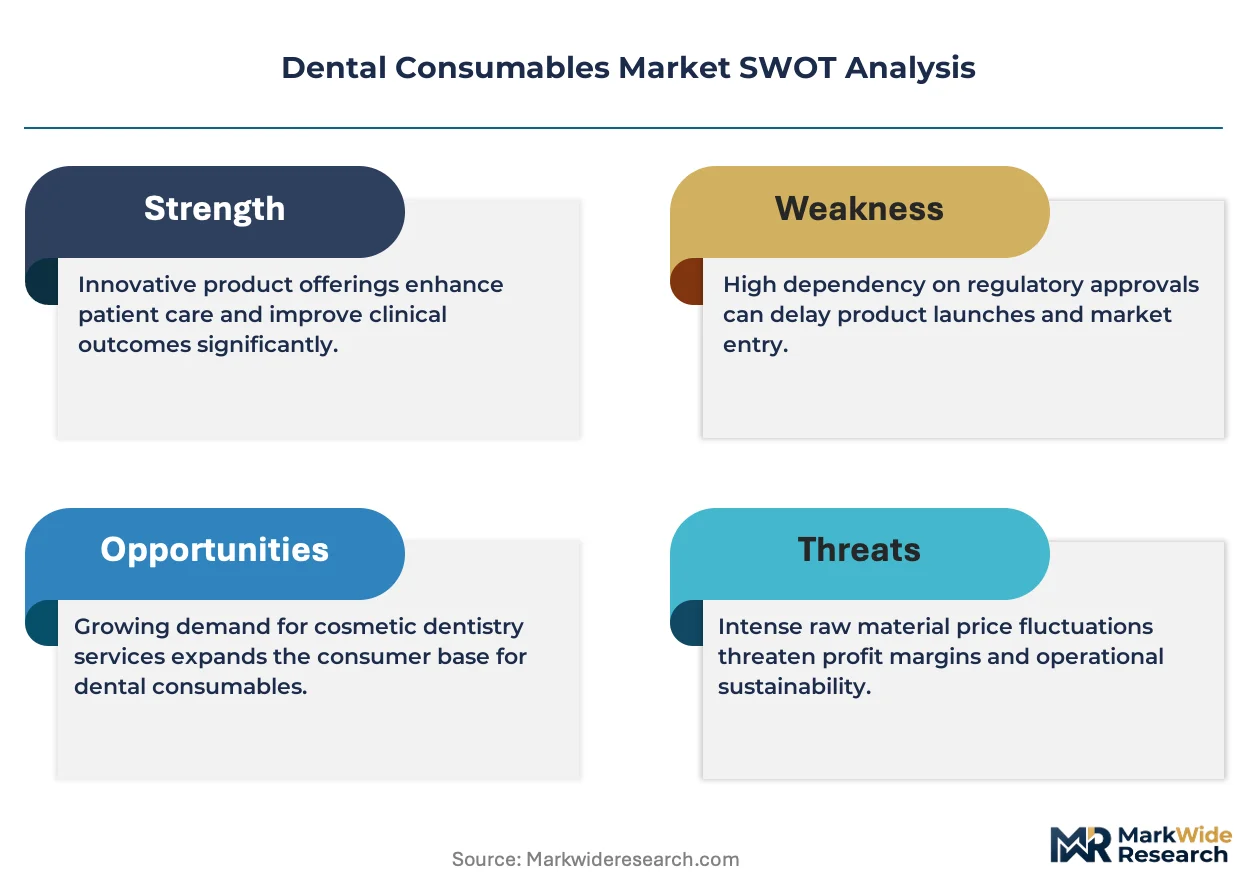
- Material Cost Volatility:Fluctuations in the price of key raw materials, including medical-grade polymers and specialized ceramic powders, create margin pressure for manufacturers.
- Regulatory Burden:The high cost and extended timelines associated with obtaining and maintaining regulatory clearances, such as CE marking under MDR, act as a barrier for smaller innovators.
- Consolidation of Dental Practices:The growth of large Dental Service Organizations (DSOs) increases buyer power, leading to pricing pressure on consumable suppliers.
Strategic Opportunities
- Bioactive Materials:Development of restorative materials with therapeutic properties, such as ion-releasing composites that can help prevent secondary caries, presents a significant growth avenue.
- Emerging Market Penetration:Expanding distribution networks in Southeast Asia and Latin America to provide access to advanced restorative and prosthetic consumables offers substantial upside.
- Subscription-Based Models:Offering inventory management and automated replenishment services for clinics via subscription can create recurring revenue and increase customer loyalty.
Industry Challenges
- Supply Chain Traceability:Implementing the rigorous lot-level tracking and post-market surveillance systems required by regulations like the EU MDR presents a significant operational and IT challenge.
- Digital Workflow Training:A deficit of technicians and clinicians proficient in digital design and milling software slows the adoption of associated advanced consumables.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Consumables Market |
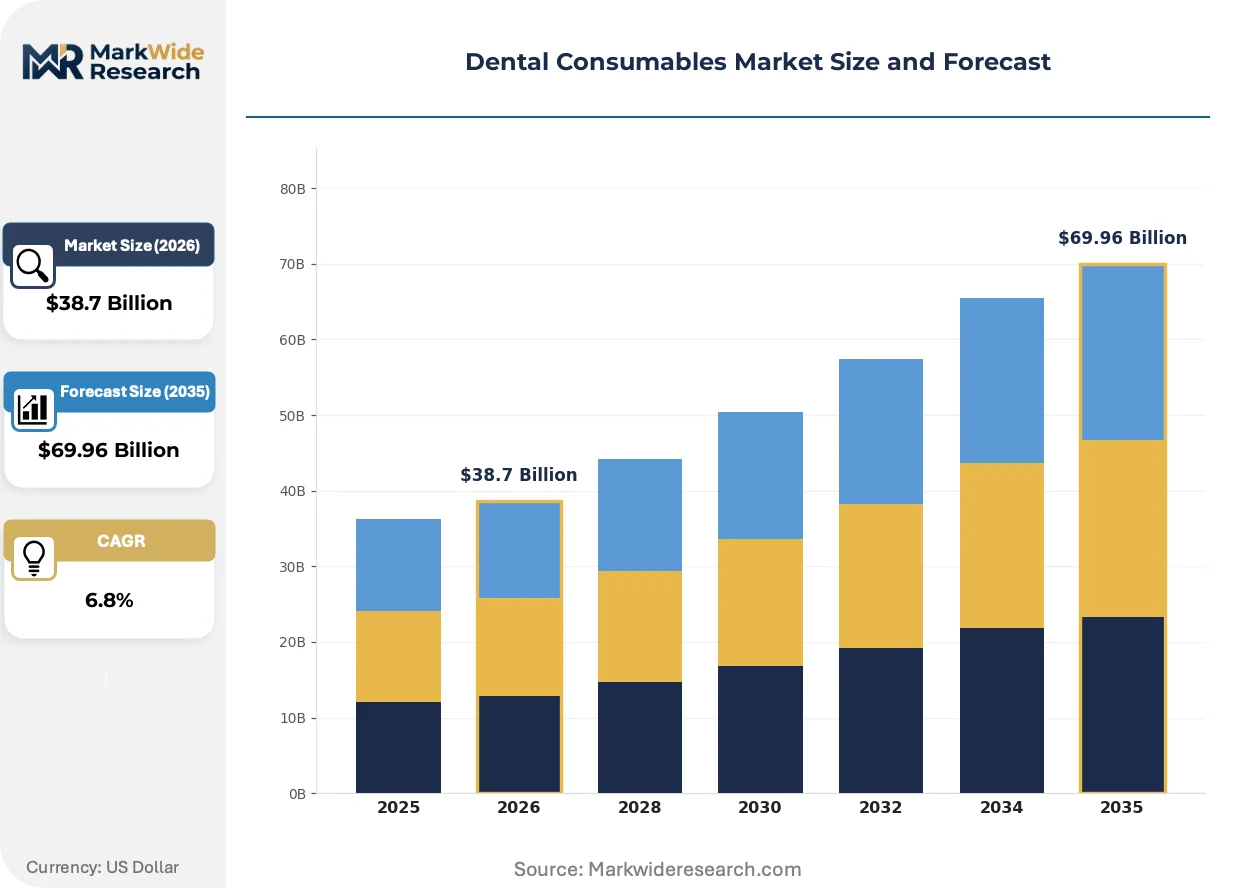
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Impression Materials, Restorative Materials, Cements, Polishing Agents End User: Dental Clinics, Orthodontic Labs, Dental Hospitals, Prosthodontic Centers Application: Restorative Procedures, Preventive Care, Orthodontic Treatments, Prosthetic Rehabilitation Packaging Type: Cartridges, Tubes, Bottles, Sachets, Blister Packs |
| Companies Covered | Dentsply Sirona, 3M Company, Henry Schein, Institut Straumann AG, Envista Holdings, Ivoclar Vivadent, Zimmer Biomet, Straumann Group, Patterson Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Consumables Market Strategic Shifts & Innovations
Material science innovation is intersecting with digital workflow integration, fundamentally altering how dental procedures are planned and executed. This evolution is occurring under the increasing influence of global regulatory bodies demanding higher standards for patient safety and product efficacy.
Biocompatible 3D-printable resins are enabling the rapid, in-house production of surgical guides, custom trays, and temporary restorations. Dental laboratories and large multi-practitioner clinics are the primary adopters, seeking to reduce turnaround times. This on-demand manufacturing capability is converging with intraoral scanning data, allowing for a fully chairside digital workflow.
Regulatory frameworks like the EU’s Medical Device Regulation (MDR) impose stringent requirements for clinical evidence and post-market surveillance. This forces manufacturers to generate robust data, increasing development costs. The implant and bone graft segments are most affected, needing to update technical files and clinical evaluation reports to maintain market access.
A shift toward unbundled purchasing of individual components is disrupting traditional, brand-loyal procedural kits. This allows clinics, especially smaller practices, to mix and match materials from various suppliers based on price or performance. The trend is most pronounced in North America for restorative materials like composites and adhesives.
Dental Consumables Market Segmentation
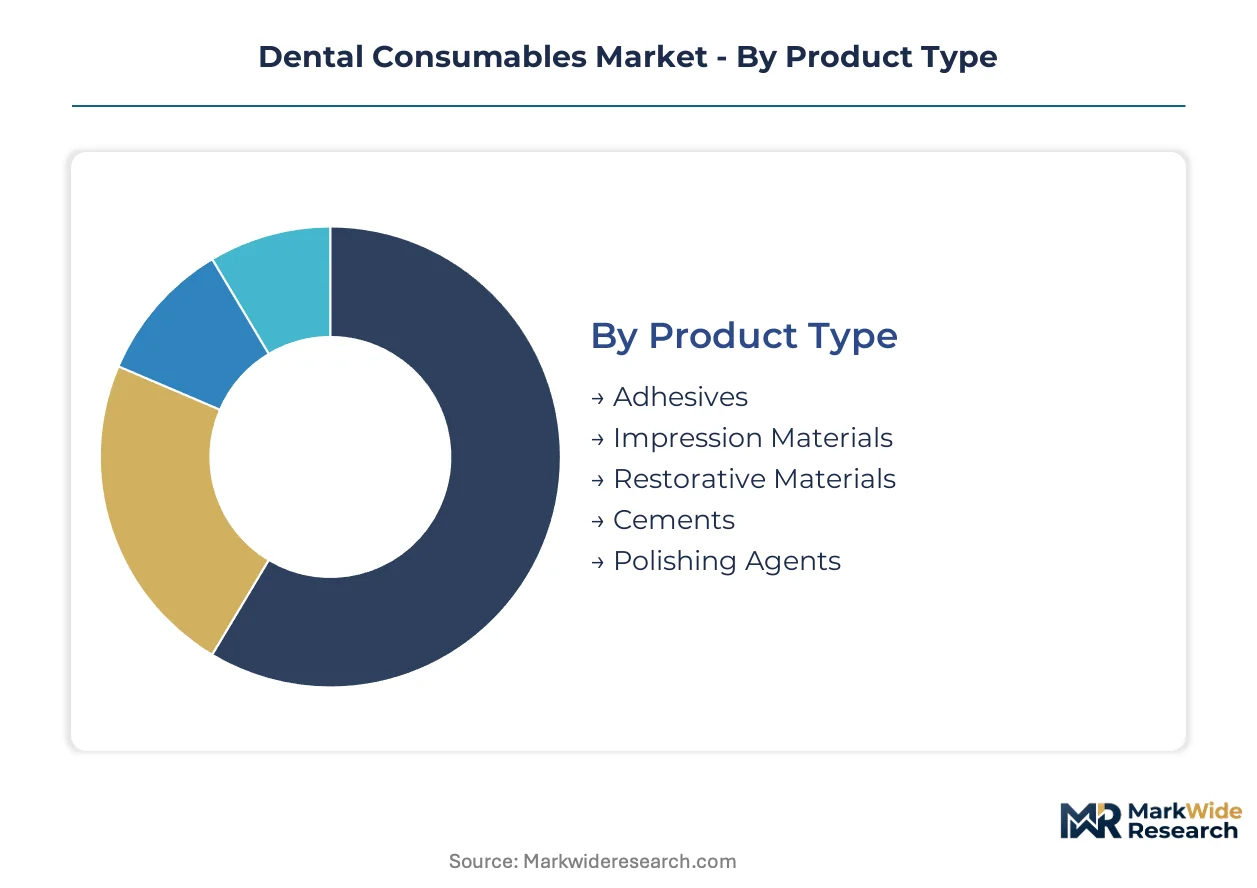
The dental consumables market segmentation offers a detailed view of product utilization and end-user demands, highlighting specific areas of material innovation and service delivery. Understanding these segments is critical for manufacturers to align product development with evolving clinical needs and regulatory standards. Each segment reflects distinct procurement patterns and application requirements across the dental care continuum.
Product Type:
Supply concentration in product type segmentation highlights material science specialization among manufacturers.
- Restorative Materials:Composites, amalgams, and glass ionomers form the core of dental repair, designed to rebuild tooth structure lost to decay or trauma. Demand concentrates in general dental clinics across Brazil, driven by widespread need for essential and cosmetic dental care.
- Adhesives:These specialized bonding agents, often resin-based, create a strong, durable link between restorative materials and tooth enamel or dentin. Higher margins are commanded by advanced formulations used in complex cosmetic procedures in European clinics.
- Impression Materials:Elastomeric or hydrocolloid compounds capture precise oral cavity details for prosthetic and orthodontic appliance fabrication.
- Cements:Luting agents and liners provide mechanical retention and thermal insulation for crowns, bridges, and other indirect restorations.
- Polishing Agents:Abrasive pastes and cups refine the surface of restorations and natural teeth, improving aesthetics and reducing plaque accumulation.
Restorative Materials absorb the bulk of installed capacity; Adhesives are expanding most quickly.
End User:
Customer type segmentation reflects the varied operational scales and service offerings within the dental care ecosystem.
- Dental Clinics:These general practices provide comprehensive oral care, procuring a broad spectrum of consumables for restorative, preventive, and diagnostic procedures. Demand is concentrated in urban centers globally, driven by direct patient interaction and diverse treatment needs.
- Orthodontic Labs:Specializing in the fabrication of custom orthodontic appliances like aligners, retainers, and braces, these labs require specific materials such as wires, brackets, and bonding agents. Growth is prominent in the European Union, fueled by a higher volume of aesthetic treatments.
- Dental Hospitals:Larger institutional settings offer specialized and complex dental surgeries, requiring a wider range of advanced consumables for intricate cases.
- Prosthodontic Centers:Focused on prosthetic rehabilitation, these centers utilize specialized materials for crowns, bridges, dentures, and dental implants.
Dental Clinics represent the largest consumer base; Orthodontic Labs are experiencing significant expansion.
Application:
Application scope delineates consumable usage based on the specific treatment modalities in dental practice.
- Restorative Procedures:These treatments involve repairing or replacing damaged tooth structures, primarily utilizing composites, amalgams, and bonding agents. Demand is consistently high across all geographies, driven by the prevalence of caries and trauma.
- Orthodontic Treatments:Focused on correcting malocclusion and aligning teeth, this application segment relies on specialized consumables like brackets, archwires, and clear aligner materials. The adoption of digital dentistry workflows is driving innovation in this area.
- Preventive Care:Procedures aimed at maintaining oral health and preventing disease, such as fluoride application, sealants, and professional cleaning.
- Prosthetic Rehabilitation:This involves restoring missing teeth or oral structures using materials for crowns, bridges, dentures, and implants.
Restorative Procedures command the highest volume; Orthodontic Treatments show a strong growth trajectory.
Packaging Type:
Delivery format segmentation reflects the diverse methods for dispensing and storing dental consumables in clinical settings.
- Cartridges:Pre-filled, single-use units ensure precise dosing and minimize cross-contamination for materials like impression pastes and cements. Their usage is increasing in practices prioritizing infection control and workflow efficiency in North America.
- Bottles:Bulk containers for liquids, powders, or gels, such as etchants, bonding agents, and some restorative materials, offer cost efficiency for high-volume usage. Procurement patterns in large dental clinics in Asia favor these formats due to economic considerations.
- Tubes:Collapsible containers are common for pastes, gels, and some impression materials, allowing for controlled dispensing.
- Sachets:Single-dose packets provide convenience and sterility for powders or small quantities of liquid, reducing material waste.
- Blister Packs:Individualized, sterile packaging protects single-use instruments or small material components from environmental exposure.
Bottles cater to significant volume requirements; Cartridges are gaining traction for their precision and hygiene benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market for dental consumables exhibits a clear production-consumption asymmetry, with manufacturing prowess concentrated in a few advanced economies while demand spreads globally. This dynamic shapes supply chain strategies and regulatory compliance efforts across diverse regions. Regulatory frameworks, such as the EU's MDR, are elevating material traceability and clinical evidence standards for all manufacturers.
United States
Demand for advanced restorative materials stems from a high prevalence of aesthetic dentistry and an aging population seeking comprehensive care. The FDA's 510(k) clearance process rigorously regulates new device market entry and post-market surveillance. California's MedTech cluster drives innovation in biocompatible polymers and digital dentistry solutions, supporting rapid prototyping and advanced material development.
Germany
European clinics prioritize high-margin specialized formulations for complex cosmetic procedures, particularly in implantology and advanced prosthetics. The EU's MDR mandates stringent clinical evaluation and post-market surveillance for all medical devices, elevating quality standards. The Bavaria region hosts several advanced dental material manufacturers and research institutes, fostering material science advancements.
Brazil
A large population seeking both essential and cosmetic dental care drives consistent demand for restorative materials and preventive products. ANVISA oversees medical device registration and ensures compliance with national health regulations, influencing market access. São Paulo serves as a major hub for dental equipment and consumables distribution, supporting a robust domestic market.
Japan
Rigorous approval processes by the PMDA influence product development for all medical devices, emphasizing clinical safety and efficacy. Digital dentistry adoption creates demand for compatible materials like millable ceramic blocks and photopolymer resins. Tokyo's research institutions and manufacturing centers contribute to material science innovations and precision manufacturing.
China
Expanding distribution networks in emerging markets increase access to advanced restorative and prosthetic consumables, particularly in urban centers. The NMPA regulates medical device production and import, increasingly aligning with international standards for quality and safety. The Yangtze River Delta region is a growing manufacturing base for dental products, serving both domestic and export markets.
Dental Consumables Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the dental consumables market. The competitive landscape features a blend of established global players offering extensive portfolios and agile niche innovators targeting specific segments. Strategic archetypes include integrated system providers, material science innovators specializing in adhesives and composites, and specialized implant and prosthetics manufacturers. Companies increasingly pursue portfolio diversification to address varied clinical needs and engage in strategic partnerships to expand their market reach.
On the integrated system vector, Dentsply Sirona exemplifies a comprehensive portfolio approach, spanning both dental equipment and a vast array of consumables. This strategy encourages system loyalty among clinics. 3M Company, a Minnesota-based diversified technology corporation, anchors the material science innovation segment, particularly with its broad range of standalone adhesives and composites. Its strength lies in specialized formulations. The Straumann Group, a Swiss-based medical device company, represents the premium implant and prosthetics segment, commanding a strong position with its specialized offerings and advanced biomaterials. These players leverage distinct strategic positions to secure and expand their market share.
| Leading Market Players |
|---|
| Dentsply Sirona |
| 3M Company |
| Henry Schein |
| Institut Straumann AG |
| Envista Holdings |
| Ivoclar Vivadent |
| Zimmer Biomet |
| Straumann Group |
| Patterson Companies |
| Others |
Cost & Logistics Intelligence
Digital workflow integration, enabling chairside manufacturing, simultaneously reshapes cost economics and supply concentration by localizing production. This shift impacts material procurement and pricing strategies across the dental consumables market.
Pricing Analysis
Margin tightening in the restorative materials segment reflects increasing competition from unbundled components. Per-unit transactional pricing dominates most consumable sales, with clinics purchasing based on immediate need. Price differentiation stems from material quality grade, such as advanced ceramic formulations, and brand premium associated with established manufacturers. Consolidation of Dental Service Organizations (DSOs) increases buyer power, leading to pricing pressure on suppliers. Smaller independent clinics often exhibit higher price sensitivity due to tighter budget constraints.
Supply Chain Analysis
Skilled workforce availability in Germany, Japan, and the United States underpins specialized material manufacturing. The supply chain draws from key raw material dependencies, including medical-grade polymers and specialized ceramic powders. Commodity price volatility for these inputs presents a significant structural supply chain risk for manufacturers. Distribution runs through a hybrid model, combining direct sales for large accounts and specialized dental distributors serving a fragmented base of smaller clinics and labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a vertical-integration race, with players pursuing upstream control over material science innovations to secure competitive advantages.
For Market Incumbents:Hedge against material cost volatility by securing long-term supply agreements for critical raw materials like biocompatible polymers. Diversify product portfolios to include both integrated system offerings and unbundled, application-specific consumables, mitigating the threat of shifting purchasing patterns. Invest in advanced manufacturing capabilities within key regional hubs to reduce lead times and enhance regulatory compliance. Reinforce channel partnerships with DSOs through value-added services, combating pricing pressure from consolidated buyer power.
For New Entrants and Emerging Players:Launch via subscription-based models targeting smaller clinics, offering inventory management and automated replenishment services. The restorative materials segment in emerging markets like Southeast Asia presents a penetrable white space due to increasing demand for essential dental care. Focus on developing innovative bioactive materials that offer therapeutic benefits, providing a strong differentiation point. Leverage digital platforms for direct-to-clinic sales, bypassing traditional distribution channels and reducing overhead costs.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized material science innovators and integrated digital dentistry solution providers over the next 5-10 years. Prioritize targets with strong intellectual property in biocompatible materials or advanced manufacturing processes, such as 3D printing resins. The signal to watch for inflection is widespread regulatory adoption of new material classifications, indicating market readiness for next-generation products. Consider mid-cap companies demonstrating robust clinical evidence for novel applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire specialized material science firms | Secures intellectual property in high-margin advanced formulations. |
| Invest in digital dentistry infrastructure | Enhances workflow integration and enables chairside manufacturing capabilities. |
| Expand into emerging markets | Taps into unmet demand for essential and cosmetic dental care. |
| Develop subscription-based service models | Creates recurring revenue streams and fosters customer loyalty. |
| Strengthen regulatory compliance teams | Ensures market access amidst stricter global medical device regulations. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary research involved interviews with dental clinicians, procurement managers at DSOs, R&D directors at material manufacturers, and regulatory affairs specialists. This approach allowed for bottom-up validation of market size estimates and top-down triangulation of growth projections.
Granularity of modeling focused on product type, end user, application, and packaging type across the analysis window. The analytical framework also integrated region-specific regulatory landscapes and technology adoption rates as key dimensions. Compound annual growth rates were derived from historical data trends and projected market drivers, including demographic shifts and healthcare spending patterns.
Regulatory changes, raw material price fluctuations, and shifts in digital dentistry adoption are the dominant revision risks for this market. Forecasts reflect assumptions documented through extensive primary and secondary research. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Supplies
Dental Preventive Supplies Market
Dental Supplies
Dental Caries Treatment Market
Dental Supplies
Global Hotel Dental Kits Market
Dental Supplies
Fissure Sealants Market
Dental Supplies
Global Dental Suture Market
Dental Supplies
Orthodontic Supplies Market
Dental Supplies
Orthodontic Consumables Market
Dental Supplies
Endodontic Supplies Market
Dental Supplies
Plaque Disclosing Market